Stock in Focus: Indivior

How can a company that’s only been listed for six months be the highest-ranked stock on Stockopedia, with a StockRank of 100?
It’s a question I’ve been asking myself as I’ve watched shares in Indivior climb by 57%.
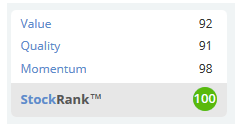
I know that there’s plenty of statistical evidence to suggest that spin-offs tend to outperform the market. I also know that Indivior appears to have the winning characteristics of a super stock, with high value, quality and momentum ranks.
Yet with such a limited track record, can investors have confidence in Indivior’s future?
The Indivior story
Indivior was the name given to the Reckitt Benckiser Pharmaceuticals business, which demerged from its FTSE 100 parent Reckitt Benckiser at the end of 2014.
Reckitt’s view was that the pharma business was no longer a good fit with its consumer goods focus and that “the potential risks and rewards of Indivior” would be better understood as a standalone business.
One of the risks Reckitt’s board might have been referring to is the possibility that Indivior is a business in decline. Indivior’s only significant product is Suboxone. This is a treatment based on the drug buprenorphine, which is used to treat opioid addiction, including for heroin addicts.
Although it’s sold in Europe, Suboxone's main market is the US, where it has a dominant share of the market. Reckitt’s decision to spinoff Indivior coincided with the approval of four generic competitors to Suboxone in the US.
This competition is eroding Indivior’s profits and its market share, which has fallen from 64% to 59% over the last year.
What it’s not doing, however, is reducing volumes. Indivior appears to be benefiting from President Obama’s flagship legislation, the Affordable Care Act. According to the firm, this has been a significant factor in driving demand growth in the US market. Despite Suboxone’ loss of market share, volumes rose by “low double digits” during the first quarter of this year.
A value play?
There’s no doubt that Indivior looked cheap at the time of its demerger. Even at today’s share price, Indivior trades on just 7.2 times trailing twelve month (TTM) earnings and only 6.3 times trailing free cash flow.
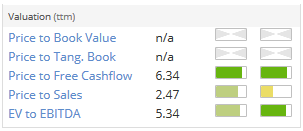
These impressive ratios are reflected in Indivior’s ValueRank of 92, which the firm scores despite a negative book value and no historical dividend yield.
But the ValueRank is backwards looking, using historical data while Indivior’s future value and earning power is harder to understand. Consensus forecasts show the firm’s P/E rising to 13.2 in 2015 and to 16.7 in 2016, as earnings fall.
Value investors usually value a company by its net asset value or the likely value of its future earnings. Indivior’s net asset value is negative, due to the firm having few assets and a moderate amount of debt.
A more appropriate measure, Indivior’s future earning power, is also uncertain. The firm expects the high level of generic competition to cause prices to fall by as much as 80% (see this graph). This has not yet happened and the timing of the fall is uncertain.
In the short term, this could enable Indivior to repeatedly beat earnings estimates, as it did last year. In the longer term, the firm expects Suboxone prices to fall severely, reducing its stunning 48% operating margin to more normal levels.
Quality concerns
Indivior’s QualityRank of 91 suggests a strong balance sheet, high profit margins and a defensive moat.
The firm’s profit margins are very high, and the balance sheet does appear to be healthy. Indivior’s Piotroski F-Score of 7 supports this view. The only slight weakness I could see was a current ratio of just 1.2. I’d prefer something closer to 2.
However, I do wonder whether Indivior’s asset-light balance sheet is exaggerating the firm’s qualities a little. For example, Stockopedia’s calculation of Indivior’s long-term average return on capital employed (ROCE) is given as 272% in the QualityRank (you can view these figures by clicking on the rank numbers on the sector page).
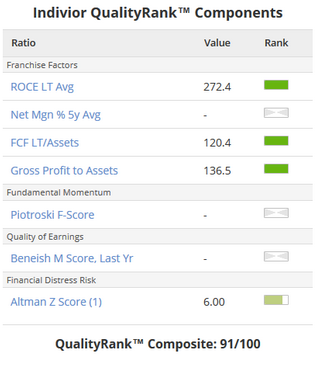
While Indivior is very profitable, ROCE also reflects a firm’s assets. Indivior has so few assets that it has a negative book value. This provides a big boost to ROCE.
Please note this isn’t intended as a criticism of the StockRank system. It’s just a factor resulting from Indivior’s slightly unusual balance sheet. Even with a more normal asset profile, Indivior would still have a high ROCE. Just not this high.
Ultimately, the biggest question mark over Indivior’s quality is how much pricing power it will retain for Suboxone in the US. The firm’s film delivery method (it’s placed on the tongue where it dissolves) distinguishes it from the tablet delivery of its competitors, but this might not be enough to protect Indivior’s profit margins.
Powerful momentum
Indivior shares have all the classic hallmarks of a momentum stock, with strong price and earnings momentum.
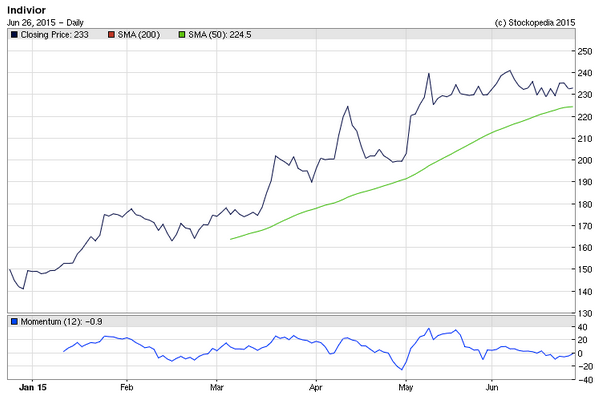
A MomentumRank of 98 reflects this broad strength. Indivior has qualified for the Josef Lakonishok Momentum Screen since February and the share price remains within 5% of its all-time high.
Indivior’s last reported earnings per share were 9.4% above consensus forecasts and current year eps estimates have been upgraded by 11% over the last three months.
However, momentum does seem to have tailed off following the last round of earnings upgrades, in May. At the time of writing, the shares have been fairly flat for around six weeks and the momentum reading is hovering around zero.
Outlook
My comments above may seem negative, but that’s not my intention. I think that Indivior deserves a high StockRank and may prove to be a company that under promises and over delivers.
If this is the case, the projected collapse in pricing power may not be as severe as expected. Similarly, a well-judged acquisition or successful new product could transform the firm’s outlook.
However, there are some real risks. Indivior is a single-product firm in a market that’s suddenly been exposed to aggressive competition. Profits could could rapidly evaporate if prices do start to fall.
Indivior’s high StockRanks are a good starting point, but I believe that even more than usual, Indivior is a DYOR stock.
As always, I’d welcome your views on this interesting company, so please leave a comment below.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

17 comments
I bought Indivior earlier this year and have done well - but top sliced a few weeks ago purely to manage portfolio risk as the position size had grown substantially. I was originally attracted as it was ranking highly in the StockRanks but also a spin-off. Joel Greenblatt showed in "How to be a Stock Market Genius" that spinoffs are very often a fertile hunting ground for stock picks.
Indivior is a complicated one. I did manage to get hold of some broker research on INDV and I've attached somecomments from a professional friend that I trust:
So - £1.50 or £4... weighted for probability £2.50 target... which is not far from where we are.
Regarding Indivior's StockRank '100' - don't read too much into it ... As many have pointed out the ValueRank is entirely based on historic numbers... but INDV's earnings and cashflow numbers need to be considered w.r.t. the worsening suboxone outlook. The historic numbers don't work for INDV on a pure value basis. So to me, the ValueRank is "overstated" in this specific case. There is of course an argument to weight the forecast earnings & cashflow into the ValueRank - there are certainly merits to that argument.
Our philosophy to date has been to allow the Momentum Rankto take the 'forward looking' side of the equation and the Value Rank the past. It has worked well so we're reluctant to 'fix it' - and certainly won't fix it just because Indivior has a very unusual forecast profile.
This linked article is vital reading for understanding how to use StockRanks - especially when using them to select individual stocks.
For full disclosure - I do continue to hold the shares, but I am likely to top-slice further in coming months.
Hi Ed - just wondering what you view is now given the release of INDV results on Tuesday. The share price continues to decline - but guidance has actually been raised. I am still holding.
The promise in the pipeline and the fact that directors have been buying in droves are the main factors that have been driving the share price in my opinion. The positive top-line results from their pivotal phase 3 trial of RBP-7000 in Schizophrenia is one key development not to be overlooked. These are far more important factors that the historical numbers or Stockopedia stock rank, the focus of this article..
Interesting and informative article - thank you Roland.
You have covered the key concerns for investing in Indivior:
1) By how much and how soon do the Suboxone profits drop? Current trading suggests that the anticipated reduction has not kicked in yet. When or if this happens then the company needs to plug the falling revenues and profits with some new successful drugs.
2) Can Indivior source new drugs of sufficient profitability and revenue? New successful drugs are not easy to find, the three drugs reported to be in development do not carry guarantees, just hopes of profitability. Even proven effectiveness of the drugs will be no guarantee of profitability in the market. The alternative to developing the drugs in-house is to acquire further pipeline drugs - and they have plenty cash in the bank at present to do this.
Too much of a gamble for myself to invest here - but it will be interesting to see where the company stands at year end and how it moves forward in the coming years.
This company surely represents a slight failing in StockRank's methodology.
The Value Rank gives it a high score based on historic numbers, the Momentum Rank gives a high ranking based on share price growth and upgrades to current projections, and slipping through a gap is the not insignificant fact that this year's profits are set to roughly halve from last year's.
Where do you think Value comes from? If profits were anticipated to double next year, do you think that it would be so deeply discounted?
I have lived through many an exclusivity (not the same as patent - but I digress) expiry, often times, but not always the market takes the most pessimistic view regarding future cashflow from the drug going generic. Therefore any surprise is to the upside - leading to a re-rating. If the drug discounts as expected, then all is not lost as it was already built into the price!
As far as I understand it, am sure Ed can explain it better than me, this fits with the two dominant theories about why the value premia exists and persists (on average and in the long term so far...). EMH says value stocks pay off because they are discounted due to higher risk, Behavioral finance says that we (humans) are hard wired to loss aversion - we oversell on bad news (drug patent expiry), and overpay for a potential theoretical win (lottery syndrome).
All IMHO DYOR etc..
I don't think any single company represents a 'failing in the StockRanks methodology' - possibly an anomaly - but the StockRank isn't a guarantee of predicting only winners but aims to predict stocks more likely to be winners.
The evidence to date suggests this methodology is effective for a basket composed of high StockRank shares.
Not sure about that, if Indivior (LON:INDV), rankings are based on last years figures then that maybe misleading. The EPS is estimated to fall by over 50%. I think the same may apply to M&A, these will not show until the next figures are produced. For example Gama Aviation (LON:GMAA) has a SR of 20, but estimated for 2015, revenue will be up x3, profits will be up x10, EPS up 67% if this is correct then the SR will rocket?
I agree that the SR can be misleading if the latest figures have not been assimilated.
This doesn't change the evidence that a basket composed of high SR shares tend to outperform baskets of shares with lower decile stock ranks.
My preferred interpretation of this is that even with some imperfect SR values, the system is still effective based on the evidence to date.
Yes I agree just pointing out there maybe a few anomalies with certain shares.
I think you should focus on what the product actually does! Financial ratios only tell you so much. Below is what I learned when I chatted to someone who used to do corporate PR for Indivior. Being a corporate PR, she could easily outdrink me - so this is my befuddled memory of the conversation.
It is an innovative solution for heroin and methodone addicts who receive opioid replacement therapy. But the problem is that the replacement can be traded for street heroin. The film Suboxone, which Indivior produces, can't be abused in the same way. Similarly the pills can't be dissolved in water and are hence more difficult to trade.
Hence it is an innovative way of treating addicts, by delivery the opioid replacement in a different way, rather than a "wonder drug".
As I say, I was several beers down when I spoke to the PR girl. But I really think the screens in stockopedia should not be a replacement for basic understanding of the product. Would you buy IG Group without understanding why it was so profitable? I wouldn't.
http://brucepackard.com/how-to-bet-on-casino-capitalism/
Hi Bruce,
It's a good point about the quality of Indivior's film delivery method versus tablets. The question is how much of a premium the doctors and insurance companies who prescribe Suboxone it can/will pay for this? Indivior seems to expect a significant loss of pricing power to the generics.
I wouldn't invest in a company without understanding what it does, but in my view the risk is that you move from understanding to trying to second guess the future. After all, Plus500 (LON:PLUS) was very profitable too, but how many investors successfully identified the differences between Plus500 and IG Group (LON:IGG) ?
Cheers, Roland
I've dipped my toe in without a great understanding of the sector TBH - just looking at the numbers and market - so this post is really useful.. I'll keep a close eye on the US market and these new drug releases and hover over the sell button ;). I'm actually testing high StockRanks in a small portfolio to see what happens - I couldn't leave Indivior out at 100!
Hi Warranstar,
That sounds about right, but what we don't know is how successful any of these new drugs will be. They have big boots to fill if they are to protect Indivior from the likely decline of Suboxone.
Statistically, I'd guess that not all of them will be major successes.
Roland
But we have a free option on them, plus they are developing low (development) risk products. DYOR etc...
@underscored,
I can see your point, but I'd argue that given Indivior (LON:INDV) falling profits, a certain amount of success from the pipeline is already priced into Indivior stock.
I don't think Suboxone alone will provide the 2015 forecast level of profit for 13 years (i.e. forecast P/E of 13). In my view, this is what would be required for the development pipeline to be a free option.
In reality, we can't tell how much of the firm's current valuation of £1.6bn is based on the earning power of Suboxone, and how much on the projected future earning power of the pipeline of new products.
What we do know is that earnings per share have fallen by 24% on a TTM basis and are expected to fall by more than 50% over the full year.
As I said in the article, I believe that Indivior could turn out to be a company that under promises and over delivers, but there's no guarantee of this.
Cheers, Roland
As with many pharmaceutical companies, the pipeline of new drugs, which the company is developing, is a very important factor. When I did my own research on this company on 01/04/2016 the company's plan was to launch one new drug every year between 2016 and 2020. As far as I am aware, that is still the case.