Stock in Focus: Is boardroom change the catalyst Debenhams needs?

Michael Sharp’s five years as the chief executive of Debenhams have not been an obvious success.
Mr Sharp’s spell at the helm included a string of profit warnings in 2013. His resignation came after reports that a number of major shareholders had been working with broker Cenkos to organise a boardroom shakeup.
A review of Debenhams’ financial performance suggests that City was right to campaign for change. Although Debenhams shares are worth 35% more than when Mr Sharp took charge in September 2011, profits are substantially lower. Net profit peaked at £125m in 2012 but was just £93.5m in 2015. That’s a 25% decline in just four years.
The big problem is that profit margins have fallen steadily. Debenhams’ operating margin was 8.9% in 2010. Today it’s just 5.8%:
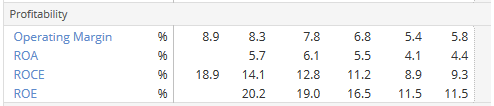
This has been blamed on causes including excessive discounting and poor store sales versus online. The good news is that things may be about to change.
Debenhams already has a new chairman, Sir Ian Cheshire. Later this year, Debenhams will also have a new CEO. Until last year, Sir Ian was the chief executive of B&Q owner Kingfisher Group. He’s a highly-rated retail executive.
I believe that the combination of a new chairman and CEO could prove to be a catalyst for change. Indeed, I’d be surprised if something didn’t change. Debenhams’ fundamentals appear solid and suggest to me that this stock could be an attractive contrarian opportunity.
Classic value credentials?
What I like most about Debenhams is that it generates plenty of free cash flow. The shares currently trade on just 10.5 times trailing free cash flow. Last year’s surplus cash of 6.8p per share covered the 3.4p dividend twice, giving a very safe 4.6% trailing yield.
Debenhams scores well on other value metrics, too. A price/sales ratio of just 0.4 is undemanding, as is the trailing P/E of 9.5. I criticised the firm’s falling operating margins above, but Debenhams’ profitability isn’t quite as bad as its operating margin might suggest. The stock’s earnings yield last year (EBIT/EV) was 11.1%. That’s not too bad.
Despite this, there are a couple of risks I’d like to flag up. As the majority of Debenhams’ stores are leased, lease liabilities are considerable. According to the 2015 annual report (p135) “minimum lease payments under non-cancellable operating leases” are £850.9m within five years.
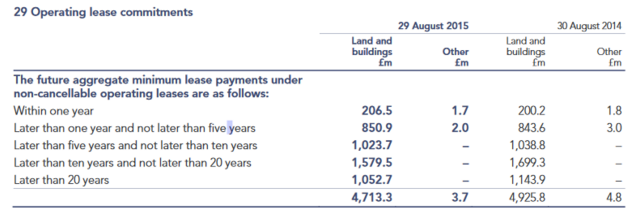
Source: Debenhams 2015 annual report
The firm’s lease commitments stretch more than 20 years into the future and total £4,713.3m. This is presumably the result of Debenhams being an anchor tenant in many major developments. The group may have signed up to long leases in return for more favourable rates.
These commitments effectively add to Debenhams’ net debt. If lease commitments for the next five years are included, then net debt rises from £319m to about £1.1bn. Although this is only likely to be a problem if store closures are planned, I think it’s worth considering.
We don’t know much about the profitability of stores compared with online profit margins. It’s possible that some stores aren’t really paying their way, so closures are not impossible.
Debenhams’ lack of freehold property also contributes to its negative tangible book value. This lack of asset backing means that liquidating or scaling back Debenhams’ business would be very costly for shareholders.
A perfect 9
I often talk about the Piotroski F-Score in this column. That’s because since I started to use Stockopedia, I’ve come to see the value of this indicator as a measure of financial quality. By including measures of profitability, cash generation, leverage and liquidity in one score, the F-Score provides a very useful instant snapshot.
Debenhams is one of only five companies in the FTSE 350 which have a Piotroski F-Score of 9/9. This is one of the main reasons for the stock’s QualityRank of 84. The other main contributors to this score are the strong free cash flow and respectable long-term profitability.
However, as I mentioned earlier, declining profit margins are a concern.
Another concern flagged up by the QualityRank is Debenhams’ lack of asset backing. The firm’s Altman Z-Score is just 0.68, indicating some statistical risk of financial distress. This is due to the lack of liquid assets, and to Debenhams’ market cap being less than the value of its total liabilities. Here’s a snapshot of how the score breaks down:
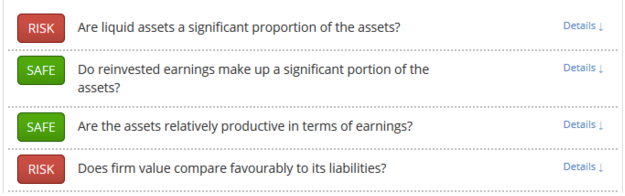
Obviously the Z-Score is only a statistical indicator. It’s not a company-specific analysis of financial risk.
However, Debenhams’ low Z-Score does correlate with my comments about lease liabilities above. In my view, this highlights the useful way in which Stockopedia data can flag up such risks in a systematic way.
Will the shares continue to fall?
Debenhams’ lack of momentum is no secret. It’s the main reason for CEO Michael Sharp’s departure.
The Stockopedia MomentumRank figures tend to back up the City’s view that something needs to change. Price momentum is poor, with the shares 25% below their 52-week high. The 50-day moving average is only 95% of the 200-day moving average, suggesting that a downwards trend may be in place.
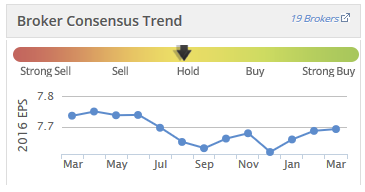
Earnings forecasts have also been downgraded slightly over the last month. Although the last set of results did beat expectations, analysts aren’t optimistic. Earnings per share are expected to rise by just 1% during the current year, and by only 4% in 2016/17. The forecast trend is uncertain:
My view
Debenhams has a StockRank of 96. The firm’s cash flow and quality metrics appeal to me. At the same time, I feel cautious about the wider retail sector at the moment.
Although the Christmas trading update was bullish, my concern is that when a new CEO takes over, we’ll find that store profitability is a bigger issue than expected. Wages are rising due to the National Living Wage, and sales are moving online. This problem may not be unique to Debenhams, but solving it could be a tough challenge.
We’ll find out more about trading conditions when Debenhams’ interim results are published in April. However, I don’t expect an update on strategy ahead of the appointment of a new chief executive.
What do you think? Does the retail sector face a tough few years, or could big retailers such as Debenhams bounce back with a vengeance?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

4 comments
There's no mention of Mike Ashley and his shareholding.
What's his intention?
He could de-rail any plans by the BOD?
Daveburke,
I think the Sports Direct stake in Debenhams (LON:DEB) is around 10%, so it's not enough to control events without the backing of other major shareholders.
That said, I do agree that Mike Ashley is a bit of a wildcard in this situation. The problem with Mr Ashley is that he always plays his cards close to his chest. We don't really know if he has any plans for Debenhams beyond the Sports Direct concessions which now exist. He may just have seen his stake in Debenhams as providing an attractive turnaround opportunity, with some leverage for good commercial terms.
Regards, Roland
Thanks Roland.
I like your articles and always reconsider my views after reading them
Regards
Dave
Thanks Dave, I'm glad the articles are useful. Although I should stress they are not tips and are only my view of the information that's available!
Regards, Roland