Stock in Focus: Is Northgate a value trap?

Shares in van rental firm Northgate lost a third of their value in 2015, as earnings growth came staggering to a halt. The firm didn’t issue a profit warning, but the cyclical and restructuring momentum which caused profits to double between 2011 and 2015 was clearly fading away.
The firm’s interim results, issued in December, confirmed this outlook. Pre-tax profits were down slightly, despite a 3% rise in revenue. The results also revealed that Northgate’s UK fleet contracted slightly during the period, mostly as a result of changes intended to maximise profitability:
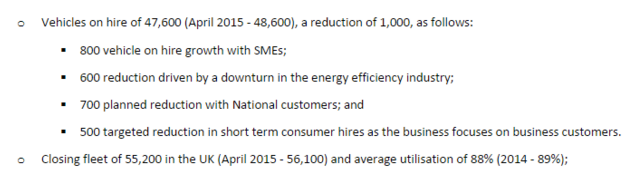
We can see that an increase of 800 vehicles on hire to SME customers was largely offset by a slump in the solar panel installation sector. This was triggered by the government’s drastic cuts to feed-in tariffs.
SME customers are the firm’s most profitable, and Northgate is targeting further growth in this area. The firm is pulling back from large corporate (National) customers and consumer customers, both of which are less profitable.
Although most of us think of vehicle hire as a short-term option, this isn’t the case in the commercial sector. A high proportion of Northgate’s business customers use the group’s long-term flexible hire product as an alternative to owning or leasing vans.
This approach has become increasingly popular since the financial crisis and has obvious appeal. Financially, using hired vans keeps the fleet off the balance sheet and avoids the need for financing. Operationally, unpredictable running costs are exchanged for a fixed monthly fee and vehicles can be added or removed from the fleet as needed, with no commitment.
Northgate also operates a very similar business in Spain, where its fleet size is around two-thirds that of the UK. This makes the potential for economic recovery in Spain very material to the outlook for Northgate.
Recovery, value or momentum?
One thing I’ve found interesting is how Northgate’s changing fortunes have been reflected in its StockRanks. Back in July 2015, when Stockopedia analyst Alex Naamani took a look at Northgate, the group’s StockRank profile was that of a high flying Quality-Momentum play:
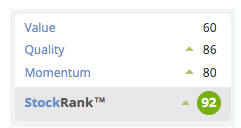
(July 2015)
Such shares tended to do well last year, but Northgate didn’t. The combination of solid trading but poor share price performance has changed the picture. Northgate is now positioned as a contrarian Value-Quality play, with a QV rank of 98 and rising momentum:
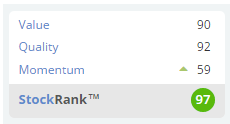
(January 2016)
Value investing performed poorly last year, as Paul Scott noted in his penultimate small-cap report of 2015. Will this underperformance continue in 2016, or will mean reversion provide a boost to cheap, good quality stocks?
Good value?
Northgate is a cyclical business, so its ValueRank of 90 should be seen in this context. Net profit is now nearly three times that reported in 2010. This suggests that as with housebuilders, a low P/E rating is not necessarily a sign of absolute cheapness.
However, I’d argue that Northgate’s value credentials are too strong to be the result of cyclical factors alone. Here’s a shot of the components behind the stock’s ValueRank:
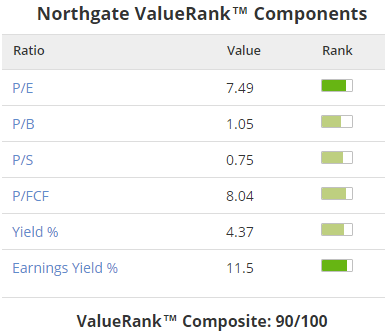
The P/E is very low but is almost matched by the price/free cash flow ratio. This demonstrates that the firm’s earnings are real cash profits, not just accounting gains.
I’m also encouraged by the fact that Northgate is trading at little more than its book value. Given an earnings yield of 11.5% and dividend yield of 4.4%, I reckon the shares are cheap enough to offer some upside potential.
Cyclical quality?
The risk here, of course, is that Northgate’s business is cyclical. Profitability is controlled by the resale value of vans when they are defleeted, and the profit margins they earn while on fleet. Both of these change constantly, and small percentage changes can have a big impact.
For example, new van registrations collapsed after the financial crisis, as business owners put off replacing vans for as long as possible. In many cases they bought used or switched to renting in order to benefit from more flexibility and fewer liabilities. Secondhand demand rocketed but the supply of good quality used vans was limited. Used van prices rose to record levels.
This was all good news for Northgate, but in the UK this exceptionally favourable environment is starting to unwind. New van registrations hit an all-time record in 2015 and used values are softening. However, in Spain, the economic recovery is at a far earlier stage. Rising profits here could offset the more mature market conditions in the UK.
If at some point Northgate ends up facing falling demand and weaker residual values in both countries, then the firm’s profits will be decimated. That’s the bear case.
The bullish argument is that Northgate manages fleet size, resale and pricing very carefully. At this point in the cycle, this stock ought to be able to deliver solid returns for some time yet -- before the inevitable cyclical downturn.
Certainly the firm’s quality metrics aren’t yet showing any serious causes for concern. A QualityRank of 92 is built around an excellent Piotroski F-Score of 8. I’m also happy with the 15% profit margin, although my gut instinct is that this must be close to its cyclical peak.
Net gearing of also 76% seems high for a QV stock, but debt is normal for hire companies. I’m fairly comfortable with Northgate’s gearing as the firm’s net debt only represents around 50% of net fixed assets. Northgate also completed a refinancing deal last year that reduced its overall interest rate, and extended the maturity on its bank facility.
Overall, I’m reasonably happy with the quality of Northgate’s financials, despite the cyclical risk.
Is poor momentum a risk?
Northgate’s relentless slide lower suggests that negative momentum may be a problem here. One of the more painful lessons I learned last year was the danger of investing into a headwind. It’s true that Northgate’s momentum has been poor, but this might be changing.
Northgate’s MomentumRank has risen by 14 to 59 over the last 30 days. Earnings per share forecasts have been tweaked higher. According to Stockopedia, December’s interim results were 9.6% above consensus forecasts.
The fall in Northgate’s share price hasn’t been reflected by earnings forecasts, which are slightly higher than they were a year ago. This has led to a de-rating of the firm’s shares, which now trade on a forecast P/E of just 7.3. A year ago, the shares had a P/E of around 13.
If Northgate can meet current forecasts and maintain a stable outlook, then in my view the shares should probably trade somewhere north of 400p, rather than significantly below this level.
I don’t currently own shares in Northgate but the stock is on my watch list and I’m tempted. As always, I’d welcome your views in the comments below.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

7 comments
Good morning and thank you for asking.
I am a newcomer to Stockopedia of just two weeks and I am still familiarising myself. The article is excellent in demonstrating how QVM thinking is applied. However I find i have used an intuituive traditional SWOT approach differentiaiting between historic and current perspectives of what is in their control and what is not..
On balance I will stay out as I sense a fading beacon and would wish to hear how the key executives express their strategy and hopes for the future.
Regards
Roger
The stock has been on my 'value' radar for some time. What worries me the most is the fact that, as the company also recognise in their report, they operate in highly competitive market. I dont know how long they can maintain high ROE before new competition erodes the margins away (as you recognised in the article - some sectors are already too difficult). Nevertheles, the valuation is so compelling that I went for a small position but I am not overweighting as a high conviction call.
Lucas,
You're right that it's a competitive sector, but Northgate does have some scale and a significant reputation in the long-term flexible hire market. This may help the group maintain market share. (If you look carefully, you'll see a lot of Northgate vans when you're out and about. They are usually unmarked but have a small green logo in the bottom corner of one of the rear doors.)
On balance the risk of weakening demand/slumping residual values worries me more than competitive factors, although I freely admit this is just guesswork. Without being on the inside of a business like this, there's little way to really know which risk is the bigger threat, IMHO.
Regards,
Roland
Useful article. Thank-you. Confirmation bias of course because I started buying recently. My analysis included comparaison with the equipment hire firms, LVD, HSS and SDY. Slightly different business model I admit but closer than what the 'Compare to Peers' tool suggests. That comes from actuarial stock market categories but I would argue that NTG is not comparable to Stobart and Clipper.
Furthermore in a downturn DCash Flow is important and NTG scores well at the moment. Hope clients keep paying.
Northgate looks quite exposed to any slow down in the economy. It also has quite high debt, I can see why the share has fallen.
herbie47,
I've commented on the debt which I believe is reasonable for a hire company -- it's normal to fund hire fleets with debt. In this case net debt is only half the value of the firm's fixed assets (i.e. mainly its rental fleet) so I don't think it's too risky.
Northgate (LON:NTG) would certainly be exposed to a slowdown, I guess the question is when/if that is likely to happen. It's worth remembering that Spain is at a different point in the economic recovery to the UK, as well.
Cheers,
Roland
Well I think it is looking fairly likely now. Its seems Spain is even more exposed to a global slowdown than we are.