Stock in Focus: Is Pure Wafer a special situation worth pursuing?

They say every cloud has a silver lining. For shareholders of Pure Wafer, a small-cap electronics firm which lost a factory in a major fire last December, that’s certainly true.
Pure operates in a fairly competitive sector, recycling silicon wafers for semiconductor manufacturers in order to reduce costly waste. Despite a successful turnaround and refinancing, the shares were on a downward trend last year. That was, until 22 December, when a fire destroyed the firm’s Swansea plant.
Since then, Pure Wafer stock has almost four-bagged, rising in value by 285%. The reason for this dramatic turnaround is simple. Rather than using the $90m insurance payout received after the fire to build a new factory, Pure Wafer has decided to return most of this money to shareholders.
Trading below net cash
At the end of June, Pure had net cash of $85m and no debt. This equates to about 190p per share, which is slightly more than the current share price of 180p.

The firm plans to return 140-145p to shareholders in the not-too-distant future, which should leave cash of perhaps 45p per share.
Pure Wafer also has another factor in its favour. It has a second business, in Prescott, Arizona. This remains in operation and is profitable.
In summary, Pure Wafer shares currently trade slightly below net cash, with a profitable business thrown in for free.
Rather impressively, Stockopedia’s algorithms appear to have picked up on this opportunity. The company is the biggest StockRank riser of the last month. Pure Wafer’s StockRank of 99 is 44 places higher than it was 30 days ago. It has the high quality and momentum profile of a turnaround stock.
The question for shareholders and potential investors is whether there might be more gains to come, or whether it is time to take some profits.
Pure value play
Pure Wafer only qualifies for one Stockopedia Guru Screen, the Negative Enterprise Value Screen. However, this is a deep value screen and is worth a closer look.
Enterprise value is a valuation metric calculated as market cap minus net cash. As I write, Pure Wafer’s EV is -£2.4m.

In theory at least, this presents an arbitrage opportunity. An investor could potentially buy the firm’s equity and debt and still be left with some spare cash to return to investors.
In practice, it doesn’t always work out that way. Company boards often need or choose to spend the cash, and any hint of such buying would send the share price soaring and destroy the arbitrage. There’s also a risk that such high cash balances are not always genuine.
In Pure Wafer’s case I think we can be certain that the cash is genuine and that the board does intend to return the majority of it to shareholders. On this basis, these shares are worth a closer look.
Pure Wafer’s ValueRank is 71. This isn’t an especially outstanding score, but there’s only really one ratio that matters: the price/book ratio. The current price/book ratio is around 0.85, which corresponds to a total book value per share of about 210p, around 16% more than the current share price of 180p.
Of the 210p per share net asset value, approximately 190p per share is cash. This leaves 20p per share for the firm’s continuing business. Is this good value?
I’d always recommend checking the accounts directly in a special situation like this. However, in this case Stockopedia’s data provider has picked up the figures we need from Pure Wafer’s 2015 accounts.
The three key numbers from the StockReport are 2015 revenue, operating profit and reported EPS:
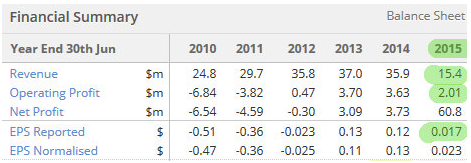
These numbers correspond to the figures provided for turnover from continuing operations, operating profit before exceptional items and earnings per share from continuing operations in Pure Wafer’s 2015 results.
Pure Wafer’s earnings from continuing operations were 1.1p per share last year. Given that I’ve identified 20p per share of book value excluding cash, this suggests that the market is currently valuing Pure Wafer’s continuing business with a P/E of 18.
Does this business justify such a strong valuation?
Genuine quality
Pure Wafer reported an operating profit from continuing operations of $2.3m last year, after excluding $300,000 of exceptional items. These appear to relate mainly to costs resulting from the Swansea fire, so I think it’s reasonable to ignore them.
Given the firm’s turnover of $15.4m, this suggests Pure Wafer’s continuing business has an operating margin of 14.9%. That’s pretty healthy and provides a solid backing for Pure’s QualityRank of 92.
Other strong points are a Piotroski F-Score of 7 and a Beneish M Score of -6.85. Collectively, these highlight the firm’s strong balance sheet, profitable operations, good cash generation and reliable accounting practices. I’d suggest that there’s no cause for concern on any fundamental issues.
That only leaves one question. What will happen next?
Powerful momentum could surprise
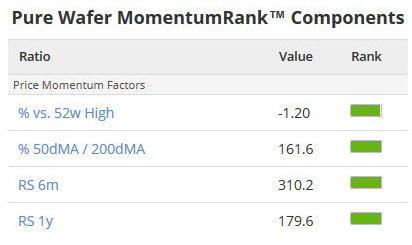
Pure Wafer’s strongest Rank is its MomentumRank of 100. This isn’t a surprise. The stock’s price momentum is outstanding on all counts:
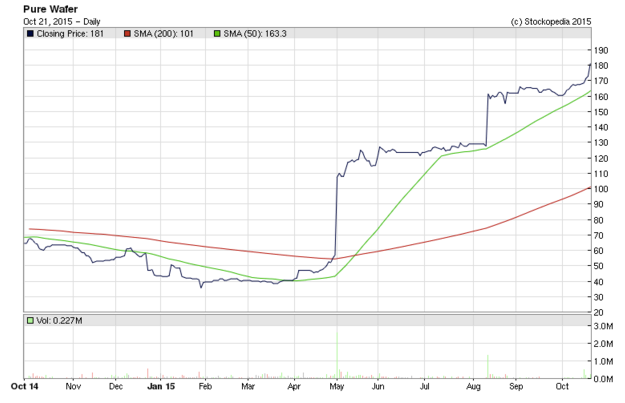
It’s impossible to say whether the shares will rise further without a specific catalyst, but it’s worth thinking what might happen to this business over the next year.
The directors own enough shares to enjoy a six-figure windfall from the proposed cash return, perhaps more in some cases. Directors and other employees with stock options have been exercising them at a steady rate recently, in obvious preparation for the big payout.
It seems likely to me that once the board has returned the majority of the cash to shareholders, the directors and some senior management may lose interest in running the company. After all, they will be considerably richer and the company itself will be half its previous size, with operations located entirely in the USA.
I wouldn’t be surprised if Pure’s board attempts to sell the firm’s US operations, after which all remaining cash could be returned to shareholders and the business wound down. It’s what I’d do.
The Arizona operation appears to offer attractive profit margins and good cash generation. Selling it to one of Pure Wafer’s competitors might not be too difficult.
One risk to watch out for, however, is that the board finds a way to award itself a large number of dilutive new options that can be exercised before any cash return takes place. This would be poor corporate governance and perhaps unlikely, as this firm seems well run. It’s still worth watching for though, as it would reduce the per share value of any future cash returns.
My view
I’d suggest that Pure Wafer does have the potential to deliver more gains at its current share price.
If the directors sell the remaining part of the business, at least another 20p per share seems realistic. Should Pure’s board choose to continue, then the current discount to book value and planned cash return should provide downside protection.
DYOR of course -- this is a special situation and there’s little doubt that the majority of gains have already happened. Understanding and assessing the figures before buying or selling is even more important than usual.
If you think I’ve missed something, then as always please leave a comment below.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

5 comments
As I suggested above back in October, Pure's management have no interest in running a US-only business. They have agreed a deal to sell Pure Wafer Inc (the US business) for $16m. Following this, the shares will be de-listed from AIM and the Pure Wafer (LON:PUR) will be wound up.
http://www.investegate.co.uk/pure-wafer-plc--pur-/rns/proposed-disposal-of-pure-wafer-inc-/201511240700116963G/
This is subject to shareholder approval. Based on a quick look at the figures and assuming that the majority of inventories and working capital is transferred to the new owner, my *rough* calculations suggest Pure may end up with around 200p per share (c.$90m) of cash to distribute to shareholders. This includes the mooted 140-145p from the Swansea insurance payout mentioned in last year's results. There was no mention of this today, suggesting it will not go ahead before the shares are delisted.
These distributions will be issued in stages by the liquidators after Pure shares have been delisted. Shareholders wanting to receive the full distribution will need to holding onto their unlisted shares in Pure, without knowing how much they will receive.
The other choice, as today's RNS points out, is to sell into the market ahead of the delisting and take the cash. Naturally this is likely to be at a discount to the eventual total distribution (in my opinion), but it is a sure thing.
What will be interesting will be to see whether directors with large shareholdings (who will have a more accurate idea of the likely return) sell out ahead of the delisting or hold onto their shares.
DYOR as always, this remains a special situation.
Roland
There are still some outstanding warrants which will dilute all your numbers somewhat (in the region of 5% from memory)
eezymunny,
Good point, I wasn't exactly sure how many remain but this sounds about right. Dilution is a risk when you're trying to squeeze the most from an opportunity like this.
Regards, Roland
I previously held Pure Wafer (LON:PUR) for over a year but sold out for a small profit after lack of liquidity, wide spread and lacklustre growth potential. This was before the fire. It was interesting to see the outcome from the insurance claim and there decision not to rebuild. Great news for people that bought at the lows but I'm not sure how much of a viable business will be left. Is it large enough to maintain a listing with the associated costs? There were also some legal issues in the States about their factory there. I don't know if this was resolved and could be worth looking into.
Seems a good opportunity. Simon Thompson (IC) also thinks so.
I bought a small number yesterday. The spread shows at 5p, but you could buy and sell well within that yesterday