Stock in Focus: Is Spirent Communications a true High Flyer?

Almost all of us use smartphones and mobile data these days. Data volumes on mobile networks are rising rapidly across the world and speeds are on the up.
All of this requires a lot of engineering, so why have profits slumped at data communications testing specialist Spirent Communications since 2012?
One reason may be that investment in new testing systems tends to happen ahead of consumers starting to use the technology. A second problem is that Spirent’s customers haven’t spent as much as they were expected to. The market has been consolidating, reducing the number of independent operators. In the meantime, technical requirements have changed and Spirent has had to adapt its product range.
The impact of the changes is clear: while revenues have continued to rise, operating profit has collapsed from £108m in 2012 to just £10.1m last year. The firm’s operating margin has fallen from 23% to just 2.1%. But the tide may be turning. Spirent’s net profit is expected to rise from £13.3m in 2015 to £35.1m in 2016.
Spirent shares have bounced back from the market sell-off at the end of last year. Forecasts have been upgraded and Spirent is the second biggest StockRank mover of the last 30 days, up 37 places to a StockRank of 91.
With strong quality and momentum scores, Spirent looks well positioned to become the high flyer many investors thought it could become three years ago. Is this really possible?
Should we question the price tag?
As a value investor, Spirent is not the kind of share I would normally buy. But the group’s apparently demanding valuation is backed by a solid balance sheet, decent cash flow and a progressive dividend.
This isn’t a reckless punt on a blue sky tech growth story. Spirent is a real business. Although the shares don’t look cheap, all the key value ratios make sense and are consistent with each other:
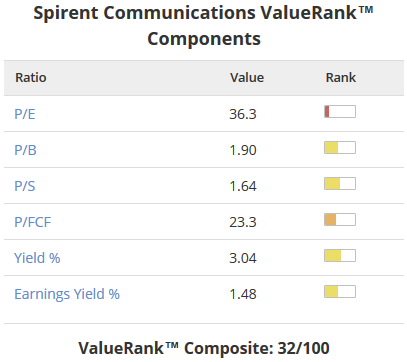
A dividend yield of 3% is reasonably attractive for a company of this type. It’s also worth noting that free cash flow exceeded earnings last year. This seems to be because while Spirent recorded $32m of exceptional costs last year, most of these were non-cash impairments. The underlying business delivered a 30% rise in operating cash flow and $35m of free cash flow. Spirent ended the year with net cash of $102m.
In my view, the only glaring problem is the earnings yield of 1.48%. This is pretty dire and clearly needs to be addressed. However, the other metrics look acceptable if you view them on the basis that earnings are bottoming out after a downturn.
If things don’t improve for any reason, then it’s hard to see where the bottom might be. Spirent has a book value of about 48p per share, but tangible assets are just 26p per share.
In any case, it’s very hard to put an accurate value on intellectual property. I’d imagine that some of Spirent’s technology could date quite quickly. I suspect that the market value of the group’s assets would be limited, if commercial results were poor.
A near-perfect score
One area where Spirent doesn’t lack is quality. The stock has a QualityRank of 98 and is very hard to fault in this department -- with one exception.
Stockopedia’s QualityRank is calculated based on a mixture of trailing and five-year average metrics, such as five-year net margin. Averages of this kind can be a double-edged sword. While they are useful for smoothing out short-term fluctuations, they can also mask steady declines.
To some extent, that’s what is happening here. Spirent has a long-term return on capital employed of 14.7% and a five-year average net margin of 12.4%. Yet both of these figures mask serious declines. ROCE has fallen from 27% in 2010 to 2.2% in 2015.
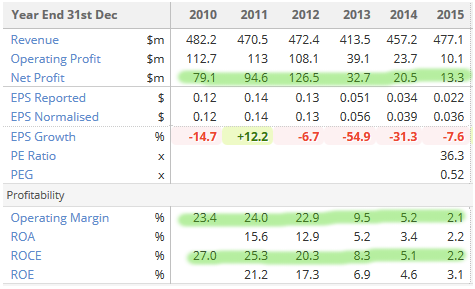
Spirent’s declining profitability is a real concern that’s masked by the use of average margins
Having said that, Spirent does have a number of other impressive quality metrics that aren’t flattered by averaging.. The stock’s Piotroski F-score of 8 out of a possible 9 is reassuring, as are the Beneish M Score and Altman Z Score. Collectively, these show that Spirent is profitable, cash generative and unlikely to be overstating its profits.
It’s also worth remembering that Spirent has maintained a net cash balance and a stable share count over the last two years, despite making more than $80m of acquisitions in 2014. For me, this provides further evidence that this is a decent business which generates cash and which has a strong balance sheet.
Apart from the need to improve profit margins, I’ve no real concerns about Spirent’s quality.
Is the tide really turning?
Spirent’s MomentumRank has risen 55 places to 93 over the last 30 days. So what’s changed?
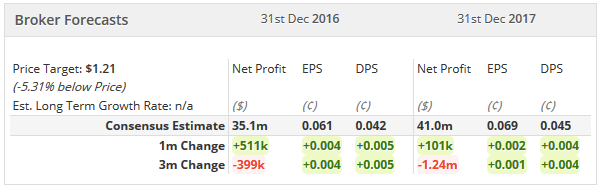
One factor is that after a long series of downgrades, analysts have turned positive on the stock. Broker forecasts for Spirent’s earnings rose last month for the first time in a year:
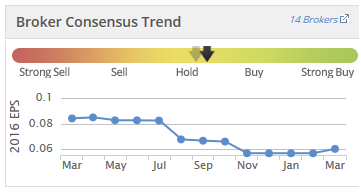
The change in sentiment seems to have been triggered by the firm’s full-year results on 25 February. According to Stockopedia’s figures, earnings per share were 6.9% ahead of expectations.
Spirent also confirmed that the board’s expectations for 2016 are unchanged. Having crunched the numbers, analysts appear to have taken a slightly more optimistic view. This has triggered a modest round of earnings upgrades:
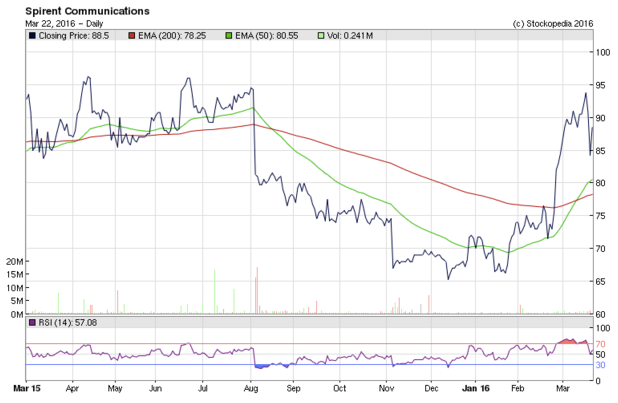
The shares have responded well to this stimulus and to the wider market rebound. Spirent is up by 26% so far this year. This has helped to improve the stock’s price momentum and the technical picture:
Worth a closer look?
The narrative in Spirent’s latest results was broadly positive, in my view. After a period of investing in new products and acquisitions, I think that Spirent should start to reap the rewards of this investment in 2016.
Although any further disappointments are likely to be severely punished by the market, I am cautiously optimistic.
However, I could be wrong! As always, please let me know what you think in the comments below.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

No comments yet
No one has commented here yet! Why not be the first one?