Stock in Focus: Should you play with Character Group?

Toy and giftware manufacturer Character Group has climbed 80% so far this year. It’s the second-best performer in Ed Croft’s NAPS portfolio and helped drive the NAPS’ impressive 32% gain during the first nine months of 2015.
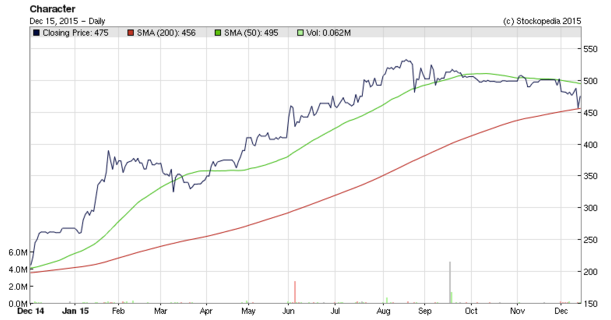
Character continues to rank highly with a StockRank of 99, but the firm’s recent final results were given a lukewarm reception by the market and are down 5% so far in December. I suspect this is simply because the firm didn’t announce upgraded guidance for the year ahead, not because of any overt problems.
However, after such a strong run it seems worth taking a closer look. How far can toy ranges such as Peppa Pig, Fireman Sam, Scooby Doo and Doctor Who take this £102m manufacturer?
Inside ownership
 As we’ll see in a moment, Character Group has a number of attractions. However, it’s clear to me that this is very much a small business, in the sense that it is closely managed by its three founders and a small number of other directors.
Given this, I think it’s useful to consider whether the directors’ interests are aligned with those of shareholders. One encouraging sign is that the group’s directors all have significant shareholdings in Character:
| Director | Shareholding |
| Richard King (Exec. chairman) | 1.56% |
| Kiran Shah (Group FD & Joint MD) | 10.58% |
| Jon Diver (Group Mktg Director & Joint MD) | 6.28% |
| Joe Kissane (MD - Character Options) | 2.31% |
| Michael Hyde (MD - Far East Operations) | 0.97% |
Messrs Shar, King and Kissane founded Character Group in 1991. Jon Diver joined the group shortly after and these four remain in charge today. This explains their substantial shareholdings, but what about executive pay?
Michael Hyde is a more recent hire (2005) and is not as well paid as the four other executive directors. They enjoyed a base salary of between £200,000 and £250,000 for the year ending 31 August 2014, the most recent year for which figures are available. In addition, each enjoyed a cash performance bonus of between 100% and 225% of salary.
Total director remuneration was £2.7m in 2013/14. To put this in context, pre-tax profit was £7.1m during the same year, while the 7.25p per share dividend payout cost around £1.7m. On this basis, I’d argue that Character’s directors are quite generously paid.
However, there seems to be little doubt that Character Group is a well-run company where shareholders have also been well rewarded. Character’s share price has risen by 281% over the last three years, while its dividend has increased by 67%.
Given this, I suspect investors will overlook generous boardroom pay packages for as long as Character’s share price and dividend continue to rise. Indeed, if Character Group is a genuine high flyer, such generous rewards may be justifiable.
Too late for value investors?
What I find interesting about Character’s current valuation is that it looks quite cheap. Earnings have grown so fast that they have kept pace with the share price.
Character’s ValueRank of 71 is rising. It reflects the firm’s trailing P/E of 10.4 and price-to-free cash flow ratio of 6.7, which both seem quite cheap to me. A dividend yield of 2.3% isn’t anything to write home about, but the payout has grown by an average of 22% per year since 2010 so this yield is likely to improve.
One metric I am keen on is the earnings yield of 12.7%, which along with the price/sales ratio of 1.04 suggest to me that Character’s earnings are being quite modestly valued by the market.
The only weak point from a traditional value perspective is that Character’s book value is low, at just 73p per share. As I understand it, the firm designs and distributes toys under licensing and partnership agreements. Character’s own assets are very limited and would probably be worth even less if the business ever ran into problems.
As a result, the value appeal of this stock is not asset based. Instead, investors are buying affordable earnings, generated by a proven and well-executed model with significant scale.
Quality is essential
Given the nature of the firm’s business model, high-quality execution and financials are essential. Here, Character scores highly, with a QualityRank of 98.
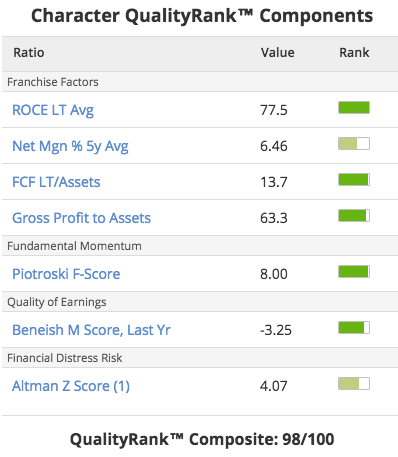
As you’d expect, there are no real weak points here. Character’s Piotroski F-Score of 8/9 confirms that the firm is profitable, cash generative and has a strong balance sheet. The F-Score is heavily weighted in the calculation of QualityRank.
Character operates in a competitive marketplace where item values are often quite low. On this basis, the firm’s 6-year average operating margin of 8.3% seems good to me. However, Character’s biggest appeal, in my view, is its ability to generate cash.
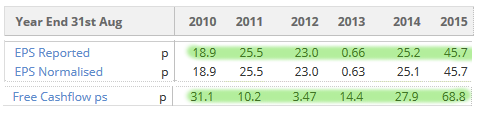
Based on Stockopedia figures, Character’s has generated free cash flow in excess of its earnings per share over the last six years. That’s a rare achievement in any industry:
Does this financial performance mean that Character has a defensive moat of some kind? Perhaps. The firm’s management is obviously trusted to execute well and deliver successful toys. I wonder how much of this is down to the reputation and leadership of the key directors.
Three of the five executive board members are over 60. In my view, there is a degree of key person risk with Character. This could be something to watch for over the next few years.
Ride the momentum
Character appears to be on a roll. The group’s MomentumRank of 99 highlights a sweet combination of strong price and earnings momentum. This could easily drive further gains, in my view.
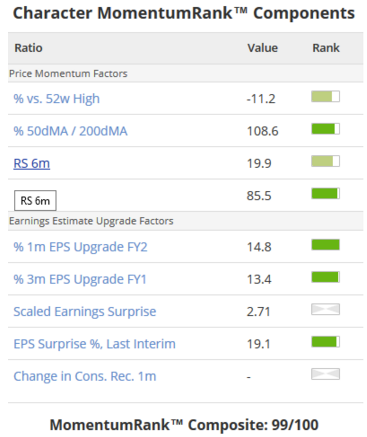
Despite this, the firm’s recent final results did not include upgraded guidance for the current year. However, that hasn’t stopped the two brokers covering the firm from increasing their forecast earnings for the next two years:
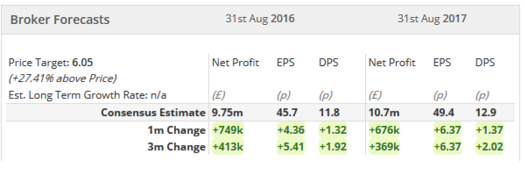
The rise in profits seen in 2015 is expected to stick, leaving the shares on a forecast P/E of 10.4, falling to 9.6 in 2016/17. I’d hazard a guess that the shares could deliver further gains if these forecasts are met.
Coupled with a forecast yield of 2.5% for the current year, I believe Character could have further to go. If I was a shareholder, I certainly wouldn’t sell just yet.
However, the downside of a business of this kind is that a bad run of luck, an unsuccessful range or the loss of a few key contracts can hit profits hard.
This makes it important to DYOR before making any decisions -- and as always please share your views in the comments.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

20 comments
Results showed good year on year growth when forex movements rightly stripped out. I think the outlook is promising given Teletubbies is selling well and being launched into overseas territories. New products to come out later in year & they seem to be gaining traction in the USA.
Rock solid balance sheet & full year expectations look very achievable. Sales in the Jan trading update for current year were up 6%, then a little over a month later up to end of Feb they were up 12%.
Bullish management interview released today: Http://brrmedia.co.uk/event/141860/
Hi Roland - would be interested in your update following today's half year results.
FWIW, I get the impression that the fizz is going out of this share. On a HY-HY comparison, although revenues were up 12%, both the net profit and adjusted eps are lower than HY15.
Broker forecast eps is also flat at 45.8, compared to 45.7 at FY15 (according to the StockReport). I may be mistaken but I haven't seen anything in the results which suggests a better performance.
I sold out early this morning when the sp was still some 2% up. Can deploy the cash to better effect elsewhere.
All IMO.
Regards, Ram
Hi Ram
I thought the results read quite well.
On a HY-HY comparison revenues were up 12% and adj EPS was up 13.6%, when you strip the forex gains last year. Interim divi was increased by40% compared to a forecast divi rise of 8%. Cash generation was also impressive and they've moved from £4.5m in cash as at the end of August to £14.5m at the end of Feb 16.
That's just my take on the results, and I guess that's what makes a market.
Best wishes,
Imran.
Maybe the directors will start buying some? After the massive sales last year that would be an indication for me. The figures are not bad but nothing like the previous 2 years.
Hi Imran -
OK as they say, beauty is in the eye of the beholder. Having said that, let me just focus on one aspect.
The report heading states an increase in net cash of 237.2%, which they calculate as £14.5m end Feb '16 vs. £4.3m end Feb '15. Fair enough.
But if you ask the more relevant question, how much net cash was generated during each half year and compared the two, you get a more modest figure of 14.6%. If you scroll all the way down to the cash flow statements, cash increase this half was £10.2m, and cash increase during the corresponding HY15 was £8.9m.
CFO and FCF, HY to HY are also lower this time.
Anyway, good luck with your holding.
Regards, Ram
Ram,
Surely the OCF & FCF H1 on H1 only declined due to unusually large reduction in trade receivables in 15H1?
And you are talking about a company with a EV of £95m generating what looks to be a fairly sustainable annual £15+m OCF. The market is arguably pricing in a large reduction in OCF going forward. The management are talking about growth. One of them will be proved wrong and I'm not convinced it's the management in this case.
Mark
Hi Mark -
Yes, if the management is talking growth then they certainly have the firepower at their disposal. The business is throwing up generous cash and the balance sheet is debt free.
I'll keep a watchful eye from the sidelines for the time being.
Simon T of IC gives this share a thumbs up today. A further buy rating with a target price of 600p. I think he is right and have increased my holding.
Character (LON:CCT) Very positive comments issued today
http://brrmedia.co.uk/event/141262/jon-diver-group-marketing-director-and-joint-managing-director--kiran-shah-group-finance-director-and-joint-managing-director
Ivolpe/Lucien.
The Dreamworks deal is an Entertainment One story but it does not affect or concern Peppa Pig at all,
as far as I know, that is unless Spielberg is thinking of some movie project for some jurassic
or poltergeist version of the little porker dancing or rolling about in some celestial mud puddle!
So, no impact on Character, imo, that is from this particular bit of news, although I do know that ETO does intend to make a Peppa Pig film as part of its normal film programme.
The deal is great news for Entertainment One, though!
Might be of relevance:
"Peppa Pig owner Entertainment One has teamed up with Steven Spielberg to create a new film company in a bid to boost its revenues, writes Peter Campbell. Mr Spielberg will use the new company – called Amblin Partners – to distribute DreamWorks films across the world. The deal will see the Peppa Pig owner expand its film distribution division into new countries, as well as working on new shows and films."
and
"This long term partnership builds on the successful output relationship between eOne and DreamWorks, whilst extending the relationship through additional territories, licensing and merchandising and television production and distribution."
Source https://next.ft.com/content/134a83f9-2b7e-3bf2-95d4-25498c7852af
So I guess this could be good or bad depending on whether CCT retains the franchise.
Wouldn't this be an indicator that they would want the licence back or the next contract would be on significantly worse terms?
Hi Roland & Jane,
I have a vested interest in CCT so decided to have a long hard look at the numbers.
Jane is of course right. Comparing 2H2015 to 2H2014, revenues show a drop of around 20%. This impact ripples all the way down to the income figures and is more pronounced when you compare the Cash Flow figures. Operating Cash Flow(CFO) drops by 37% and Free Cash Flow (FCF) drops by 66%.
On the positive side, the company is cash rich around 17% of their market value is cash. The balance sheet is rock solid with no debt to speak of.
So either this is just a blip and we are reading too much into half year data fluctuations, or this is a first sign of an underlying longer term slowdown. Personally I will ride it out and hope that any slack is taken up by the teletubbies franchise next year. This stock is only 1% of my portfolio.
One thing I am sure of which is that this share is definitely not a pig in a poke. (sorry couldn't resist it)
Regards, Ram
Roland, I'd expect that Peppa Pig contributes about a third of total revenues.
On page 4 of the later Allenby report, they state that no one brand accounts for more than 20% of sales. Domestic sales are 70%-75% of total revenues. I'd expect Peppa to be their leading brand so those domestic Peppa sales would be about 15% of total revenues.
Allenby then say that two-thirds of international sales are of Peppa articles, so that would amount to somewhere between a further 17% and 20% of total company revenues.
So, adding those together, one can deduce that about a third of total sales are related to Peppa Pig.
so they are certainly highly or perhaps entirely dependent on this little porker for all their profits, at least until the Teletubbies range gets going next year, hence the importance (and the vulnerability) of retaining that particular franchise.
You are right that there seem to be no figures in respect of their other ranges.
Jane, Mayn,
Thanks for both of your comments. To address the various points you make, I agree that Character's earnings and sales are likely to fluctuate depending on the success of individual ranges and other timing/commercial issues which won't always be apparent to outsiders (i.e. private investors) until after the event.
I'd imagine that the risk of losing a contract renewal to a competitor is an ever-present risk, especially after holding it for a long time. It's perhaps similar to the situation with ad agencies, where large clients occasionally shift their accounts to see if they can get something fresher/better/cheaper elsewhere. I did hint at these risks within the article.
Similarly, while you might expect Character's growth to result in a more resilient and diverse portfolio of sales, we've no way of knowing whether this is the case, as Character doesn't appear to provide any breakdown of sales. Profits/revenues could be heavily weighted to one or two key ranges.
Cheers, Roland
Disclosure: I have no financial interest in Character Group.
The directors did sell a lot of shares in September, so that is another minus point.
Hi Roland,
"However, there seems to be little doubt that Character Group is a well-run company where shareholders have also been well rewarded."
Well, that is the case for the last five years or so. But the track record since the mid-90s flotation has been quite mixed to say the least, and all with the same management in charge. I wrote a potted history of the dividend here: http://www.stockopedia.com/content/character-group-93598/?comment=3#3
I suppose the best time to buy this share is, for example, when Jane did in 2010 -- i.e. after the company has suffered various problems, rather than after a long streak of success...which historically at least the firm has found hard to sustain. Perhaps the group's ups and downs longer term have been due to the fickle nature of toys.
Mayn
Roland, I have cut down my holding in Character.
I have several points of caution.
Firstly, the sharp (20%) downturn in revenues for the six months to August 31, 2015, compared to the corresponding period in the previous year. I covered this in two previous posts:
December 2:
"Yesterday evening, when I had a little more time, I went back over Character's revenues figures, half-year by half-year: These are as follows (in millions of pounds):
2012/2013 H1 30.6
H2 36.5
2013/2014 H1 46.9
H2 51.0
2014/2015 H1 58.2
H2 40.8
Although, as I wrote yesterday, the profit for the year and the cash generation seem good and the Teletubbies relaunch likely to generate substantial business, I am very puzzled by the REVENUE figures for H2 2014/2015, deduced from yesterday's RNS. They show a 20% reduction on the H2 revenue figures for H2 of the previous year. Also, the H1 2014/2015 revenue figures were 24% higher than those for H1 of the previous year. So revenues figures seem to have gone from a 24% increase over the previous year for H1 to a 20% decrease over the previous year for H2, something I found rather startling.
I can't find anything in the RNS to explain this satisfactorily. There is a mention of currency headwinds and general economic conditions but for myself, I can't see that as explaining an apparent change of this scale. Neither do product launches nor the Christmas factor seem to help.
I have written to the CFO about this and will pass on his answer. - See more at: http://www.stockopedia.com/content/small-cap-value-report-1-dec-2015-bry-isg-113589/?comment=34#34
Then on December 8:
"Ref. my post no. 34 above, I have had a response from the CFO which, in essence, seems to simply repeat what was said in the RNS relating to currency headwinds and general economic conditions, as well as the perhaps different and earlier timing of Christmas toy sales to overseas markets. I have also read through two quite lengthy reports from Allenby Capital which can be found here:
http://allenbycapital.com/research/research-char.html
Looking at these figures for revenues in another way and supposing the year-end had been February instead of August, revenues figures for those twelve-month periods would have been (in millions of pounds):
12 months to 28.02.2014 36.5 + 46.9 = 83.4
12 months to 28.02.2015 51.0 + 58.2 = 109.2
12 months to 28.02.2016 40.8 + ??
So, looking at the revenues figures this way, to match the revenues figures for the previous twelve-months period, Character would need revenues of 68.4 million pounds in the present half-year, that would be an increase of more than 17% ( 68.4 / 58.2 ) over those of the corresponding six months in the previous twelve-months period. Note, however, that the last declared figures for the six months to 31.08.2015 show a 20% reduction ( 40.8 / 51.0 ) over the corresponding previous period.
Note that I am referring only to revenues and not profits and that Character have declared higher margins for the last six months reported, an increase (stripping out the mark-to-market adjustments) from 32% to 35%, this being essentially the factor that enabled profit performance to be as reported. This increase in margins also puzzles me since, assuming they buy in US dollars from their Chinese suppliers, their buying prices ought logically to have been impacted negatively by the strengthening of the US dollar against sterling. However, perhaps they have been able to screw down Chinese suppliers' prices by even greater amounts to more than compensate for the currency factor. Or, perhaps, they were protected in that period by their currency hedging. For me, this remains an unknown, rather puzzling, how this combination of sterling weakness against the US dollar but strength against the euro has reportedly produced, at the same time, both higher margins and weaknesses (presumably in export markets) in revenues. Would there, for instance, not have been scope within those higher margins to be able to remain competitive in export markets?
Another factor that concerns me is the thought that Character may be going through a relatively weak patch in their product range, at least until the introduction of the new Teletubbies ranges in 2016, that is after this year's Christmas toy buying season. I'd explain my thinking this way. Reportedly, Peppa Pig accounts for about a quarter of Character's turnover and some 70% of export sales. I know that this little creature is still trotting along very nicely ( I'll avoid the "bringing home the bacon" comment that has been done to death!) wherever she sees a mud puddle to roll about in and she ought to produce bedrock revenues for years to come, in UK but also overseas, where the series is now being launched. That's why I find the apparent fall in reported revenues even more puzzling since Peppa seems to be doing at least as well ( I mean in terms of audience figures) in every country, not just in the euro countries where the strength of sterling may well have held back sales.
I wonder, in this market where novelty is everything, whether Character are simply weaker in their product range, at least until the Teletubbies reappear. Allenby actually do, in their latest report, hint at product fatigue in export markets. If they are right, then perhaps this is something that might be affecting sales in UK as well. On the basis of what I know at present, I can't see Character reaching the 68.4 million pounds of revenues needed to keep them on a growth track in the present twelve-months period (the period I refer to above) while I also wonder whether the present margins are sustainable long-term.
All of this is simply my own thinking but I have now trimmed my position in Character, which has to date been one of my best investments. - See more at: http://www.stockopedia.com/content/small-cap-value-report-1-dec-2015-bry-isg-113589/?comment=48#48
Besides these points, there does seem to be anecdotal evidence of sluggish toy sales this Christmas, posted December 11:
"From "Toy World", perhaps a further alert for Home Retail, perhaps also for Character:
"Elsewhere this week, Argos has launched what can only be described as a clearance flyer in-store, featuring some fairly hefty price reductions. The timing seems a little unusual – it looks more like the kind of flyer you’d see after Christmas, not three weeks beforehand – but it dovetails with rumours I’ve been hearing that retailers are asking suppliers to increase their consumer marketing activity to help shift stock which they’re currently sitting on. I’m not sure how much capacity the TV broadcasters have to be able to respond to this request, or if indeed suppliers believe it’s the right thing to do. However, it does suggest that predictions of a significant rise in sales for the toy market in 2015 may perhaps have been a little premature. I guess we’ll all find out in a few weeks’ time."
http://toyworldmag.co.uk/blog/egg-not-pie-on-their-faces-its-the-friday-blog/ - See more at: http://www.stockopedia.com/content/home-is-mr-market-being-too-pessimistic-113031/?comment=12#12
And this, that I posted on the iii bulletin board today:
"DHX, the developer and owner of the Teletubbies brand and which has licensed Character as master toy franchisee for the Teletubbies relaunch, seems to be getting very close to Mattel, the US group which is the world's number 2 in the toy market.
http://www.toysnplaythings.co.uk/news/latest_news/mattel_and_dhx_sign_content_partnership.aspx?dm_i=GSU
,3X2HZ,IYGR07,E4H1B,1
Note this sentence:
". Importantly, this relationship also creates the potential for future content, licensing and franchise development collaborations between Mattel and DHX.”
Although this agreement does not include Teletubbies, I wonder whether there would be the danger for Character of it being extended to cover that franchise as well in the future.
http://www.dhxmedia.com/newsreleases/dhx-media-signs-global-toy-partner-for-new-teletu"
There is one other nagging doubt, the thought of which was kicked off by reading of the DHX/Mattel deal and that relates to the normal duration of the licensing agreements in the toy industry. This appears to be of three years and this perhaps implies an inherent short-term visibility to Character's earnings. Specifically, I wonder whether Entertainment One, now under pressure itself to ramp up profits after having taken its stake in Peppa Pig up to 85%, would be thinking of either changing toys franchisee (CCT has held it for about 10 or 11 years, I believe) or extracting a tougher deal. Also, whether Mattel would push DHX to take the Teletubbies franchise from Character when it expires, presumably at the end of 2018 or perhaps earlier.
My approach to investing is quite different to yours, being very much aimed at getting behind the figures and the ratios and understanding the business itself from a forward-looking perspective. All this may complement or may conflict with your own analysis.
All IMHO, DYOR.
wow. fantastic analysis, Jane! many thanks. Having done very well on character when it showed up on the stockrank screen a year ago, I sold the lot after the latest announcement as it seemed unnecessarily confusing and opaque and deliberately misleading. made me wonder why they couldnt just be straightforward (compare, say, the results from Zytronic). if in doubt, get out.
Roland / Jane
Just to say thank you for your detailed analysis. I guess one of the problems with CCT is that it is effectively a fashion business. Will this year's toys catch the public eye. As such a few good years are no guarantee of long continued success. A (three year?) licensing deal might guarantee exclusivity with Peppa Pig merchandise but who is to say whether the kids will want that this year. Maybe they are all keen on the latest Star Wars Droid.
Will handle with care
Julian