Taylor Wimpey nudges profit guidance lower on weak volumes, but value may be emerging

Analyst’s view:
The company has nudged full-year profit guidance towards the lower end of the range of analyst forecasts, but my number crunching suggests that consensus estimates were pretty much at that level already. While the valuation looks fair to me on a near-term view, I'd be inclined to turn positive on any sign of a market recovery.
Down 3% to 80p (£2.8bn) - Trading Statement
When a company downgrades its guidance without seeing a corresponding share price drop, it's often a sign that the bad news may already be priced in. I think that could be true here.
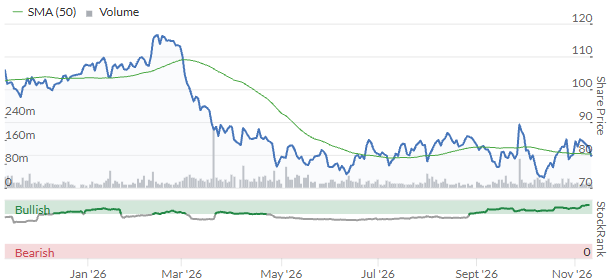
While today's update from FTSE 250 housebuilder Taylor Wimpey is disappointing, it's not really surprising. Analysts with access to industry and peer data are likely to have factored in the "subdued" market conditions to their forecasts already. As I'll explain, I don't expect any significant change to forecasts following this update.
Key points: Autumn sales "subdued"
Like most housebuilders, Taylor Wimpey has been using bulk sales to rental landlords to offset weaker sales to private buyers. Volume is the lifeblood of housebuilders, so this strategy makes sense. The main problem is that bulk sales tend to be made at lower prices than equivalent sales to homebuyers, adding further pressure to the group's margins.
Sales metrics provided today demonstrate the increased contribution of bulk sales so far this year:
Net private sales rate per outlet per week, including bulk deals: 0.69 (2025: 0.72)
Net private sales rate excluding bulk deals: 0.62 (2025: 0.68)
The order book has also shrunk:
Order book excluding joint ventures at 8 Nov 26: 6,839 homes (2025: 7,253 homes)
Order book value at 8 Nov 26: c.£1,984m (2025: c.£2,116m)
There are a couple of (relatively) positive bits of news too:
Currently operating from 225 outlets, +9% year-on-year - the company says "early action to capture the opportunities arising from planning reform continues to support this growth" Land buying has remained "highly selective" but the company is seeing an increased rate of conversion from its strategic pipeline.
Expected build cost inflation remains unchanged at 3% to 4% for 2026.
Crucially, the balance sheet continues to look healthy, with full-year guidance unchanged today:
The company expects to end the year with c.£250m of net cash, after the return of c.£240m to shareholders in 2026 through dividends and buybacks.
Outlook & Earnings Estimates
CEO Jennie Daly summarises the situation:
The Autumn selling season has been more subdued, as higher mortgage rates and living costs continue to reduce customer affordability. We now expect 2026 UK completions excluding joint ventures to be around 10,500 homes and Group adjusted operating profit* to be around the bottom end of the consensus range.
Previous guidance in July was for 2026 sales of 10,600 to 10,800, which itself was at the lower end of the company's original guidance in March 2026.
In terms of profit, Taylor Wimpey helpfully provides a consensus forecast adjusted operating profit range of £262m to £299m, prior to today.
Updated earnings estimates: Earnings estimates have declined steadily over the last year or so, but my number-crunching suggests that any downgrade will be minimal.
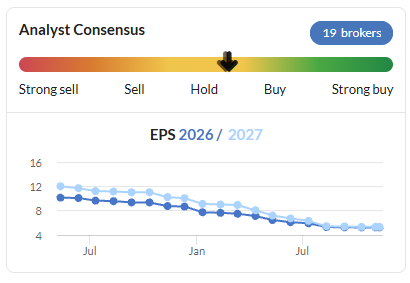
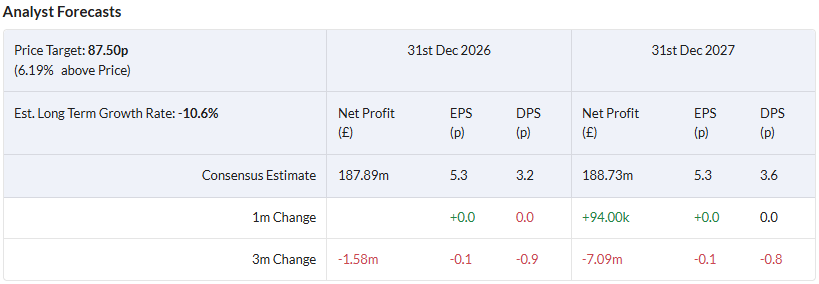
Assuming a 2026 adjusted operating profit of £265m, with tax and finance costs in line with H1, I estimate 2026 net profit of £184m. That's equivalent to adjusted EPS of 5.3p.
This estimate isn't markedly different to the consensus shown on the StockReport:
Roland's view
Assuming 2026 forecasts are largely unchanged, Taylor Wimpey shares currently trade on a forecast P/E of around 15, with a 3.2% dividend yield.
That may not seem cheap, but cyclical stocks often have relatively high P/E ratings during low periods for earnings.
For me, the price-to-book ratio is a more useful metric of value. We aren't given a revised net asset value figure today, but the half-year results showed NAV of 118p per share at the end of June. With the stock trading at around 80p, that's equivalent to a discount of over 30%:
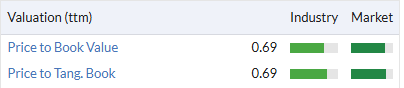
All else being equal, I'd expect buying a solvent housebuilder at a discount to book value to generate an attractive return on a medium-term view. The two main risks to this thesis are the time that may be required to realise this value, and the risk that land and property values could fall in the meantime.
On a near-term view, I think Taylor Wimpey's discounted valuation is probably fair.
Forecast earnings of 5.3p imply a return on equity of just 4.5%, well below the company's likely cost of capital.
Comparing forecast earnings to Taylor Wimpey's share price improves this return figure to 6.6%. Better, but still low.
Housebuilders like Taylor Wimpey need to be able to raise prices and increase volumes to repair their compressed profit margins. I'm sure this will happen at some point, but I don't know when that might be.
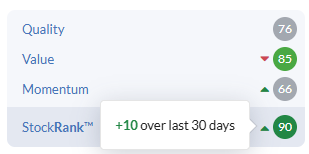
Given that today's update is technically a mild downgrade, if not a profit warning, I'm going to leave my previous neutral view on this business unchanged. However, I'm interested to see that the StockRanks have turned more positive recently:
I would also be inclined to turn positive on any sign that housing market conditions were improving.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Taylor Wimpey (1)
Comments here are also visible in the Daily Stock Market Report
Taylor Wimpey (LON:TW.) itching to call the low….