The secrets of investing success: changing your mind
In a 2019 interview, when asked what made him one of the most successful investors ever, the late great Charlie Munger replied:
Part of the reason I’ve been a little more successful than most people is I’m good at destroying my own best-loved ideas. I knew early in life that that would a useful knack and I’ve honed it all these years, so I’m pleased when I can destroy an idea that I’ve worked hard on over a long period of time. And most people aren’t.
Financial markets are always in a state of flux. The results and outlook for a business can change rapidly, and share prices even more so. An investor unable to adapt to the changing fortunes of the businesses they invest in is unlikely to generate market-beating returns, let alone be the next Charlie Munger.
Why do investors struggle to change their minds?
The problem is that it is very hard to change our minds. Indeed, in his later years, Munger appears to have made two of the biggest errors he cautions investors against. He strayed out of his circle of competence into the sphere of architecture. His proposal to the University of California Santa Barbara was to build student accommodation where 90% of residents would have rooms without windows or natural light. He even offered to fund it with a substantial donation. Understandably, this faced considerable opposition from students and architecture experts, but there was little sign that Munger was willing to take these critiques on board.
Fortunately, Munger’s failings in this area didn’t affect his investments, but it shows how hard it is to give up an idea when one is passionate about it. There are a few psychological reasons why changing your mind about an investment idea is very difficult:
Ownership Bias - the tendency to overvalue items owned compared with equivalent items that are not owned.
I discussed ownership bias a couple of weeks ago when I explained how tipsters may not always be unbiased in their stock selections. Overvaluing what they own can undoubtedly impact investors when it comes to changing their minds, too. But an even stronger effect is often at play: confirmation bias.
Confirmation Bias - the tendency to only seek information that confirms our prior beliefs and ignore or downplay information that contradicts them.
Confirmation bias means that investors often completely ignore the information they would need to change their minds about an investment. It’s why further stock research doesn’t always lead to better decision-making. Having decided that an investment is undervalued, many investors only look for information that shows how undervalued the stock is. This effect can be even worse when a stock features heavily on discussion boards. Humans are tribal animals, and investors can often group around a particular investment idea. Changing their minds involves leaving the safety of the tribe, and many are simply unwilling to do this.
Loss Aversion – the tendency to prefer gambling on an uncertain future outcome rather than take a definite loss now.
In addition to ownership and confirmation biases, loss aversion adds an extra challenge to jettisoning losing investments. When faced with a loss, investors are more likely to find ways to justify hanging on in the hope of avoiding the loss rather than changing their minds about an investment.
How can investors be better at changing their minds?
Encourage contrary opinions
Some investors become annoyed or even angry when someone disagrees with them over their favourite investment idea. It can feel like someone has run over their pet or called their baby ugly! If an investor finds they have this type of emotional response, that is a crucial sign that they have lost their objectivity.
As investors, we should take the opposite tack; we should encourage contrary opinions as long as they are based on facts or a reasonable interpretation of them. It can be a balancing act. As a value investor, I am a natural contrarian. I like to hunt for investment ideas amongst the most hated companies because I believe this is where the greatest undervaluation will likely be found. When I do this, the market constantly screams at me that I’m wrong and that a company has poor management, products, or prospects. This is often true, but not central to my investing thesis. However, these contrary opinions should make me check that any valuation includes these factors and a sufficient margin of safety.
Although discussion boards can be prone to groupthink, the Stockopedia boards are full of experienced and knowledgeable investors. Whenever I have written a Stock Pitch, I have received thoughtful and informed feedback. No one wants to do the work for another investor, but anyone who puts forward a detailed investment case here is likely to receive useful pushback, especially if they encourage others to take a contrary view rather than try to shout them down.
The most challenging time to accept a contrary opinion is when I genuinely know more about a business than someone else. However, I have to remind myself that these are precisely the types of companies where I am the least calibrated investor. Although someone putting a contrary opinion may be less informed, in general, this doesn’t mean their points are invalid. I should judge each pushback on merit.
Write down what would change your mind.
I was recently challenged by one of the commenters to my articles if I would consider changing my mind about a potential investment. The answer, of course, has to be yes. In this case, I had been critical of a company for being on a high rating for such a capital-intensive business. It seemed to me that, if the pattern of the past continued, the company would continue to grow but at the cost of requiring significant capital investment. Hence, the company wasn’t likely to generate high enough returns on capital to justify the current rating. But I must recognise that this past situation may not reflect the future. If this business requires much lower capital to grow in the future (or derates to a much lower multiple), then I would certainly consider investing.
The process of being challenged caused me to check my assumptions, the recent economics of this business, and, more importantly, what would cause me to change my mind. For companies that an investor hasn’t bought yet, a watchlist can do this, and I wrote about some ways to create an effective one last week.
For companies that an investor already owns, some form of investment diary may be useful. When buying a stock, an investment diary would record:
- Why the purchase is being made;
- What is expected to happen to cause a positive investment outcome; and
- What factors would mean the investment has gone wrong and should be sold.
As with an investment watchlist, this will prevent style creep. This happens when an investor purchases a stock for one reason, then the story changes, but they convince themselves that they should hang on (usually at a loss) for other reasons. This can be avoided by reviewing an investment against current results and what an investor recorded in their diary as the reason for owning.
Use the StockRanks
The Stockopedia StockRanks can be a valuable tool to enable investors to change their minds. The Value Rank falling (hopefully due to a share price rise rather than a drop in profitability) will indicate when a value stock may be fully priced. A falling Quality Rank may indicate that a company’s competitive advantage is being eroded by competitors.
The StockRanks are particularly useful for momentum investors. It is clear that momentum investors should sell when the trend reverses. However, this can be hard to do since it almost always involves selling after the share price has peaked. The Momentum Rank clearly indicates when the trend is moving against the investor. When I analysed when to sell stocks with falling momentum, I concluded:
…investors should be long gone by the time the Momentum Rank drops below 50. However, the examples of Reach (LON:RCH) and Iqe (LON:IQE) show that an even more aggressive selling strategy is probably ideal. Once the momentum Rank for these stocks started falling below 90, it kept falling rapidly. Any investor who waited for the Momentum Rank to fall below 50 would have given up a significant amount of the peak gains.
This wasn’t an exhaustive analysis of all such stocks, but I think that investors should be more sensitive to selling when the Momentum Rank starts to fade than the Value or Quality Ranks. For the Momentum Rank, the change in Rank may be more important than the absolute value, the Momentum Momentum, as it were.
The StockRanks can also help an investor respond to an unexpected drop in share price, such as caused by a profits warning. To help with this, Stockopedia have created a Profits Warning Survival Guide. It is worth reading in full to understand the nuances, but the simple version is that, on average, QM investors will do better by selling immediately, and QV investors should hang on.
Skate where the puck will be
There is one problem with relying on the StockRanks to show when investors should change their minds: they may not always reflect the latest market knowledge. Sometimes, changes in forecasts cannot be reflected in the StockReport. For example, on 10 November last year, Argentex (LON:AGFX) said:
…following a review of its financial forecasts, the Board of Argentex expects to report revenue and operating profit for the year ending 31 December 2023 at approximately the same levels as for the twelve months ended 31 December 2022, which are below current market forecasts.
In response, their sole broker, Singer, said:
Until the new strategy is announced and new executive team is settled, we withdraw our forecasts…
Until better data is available, the former forecasts remain in the StockReport:
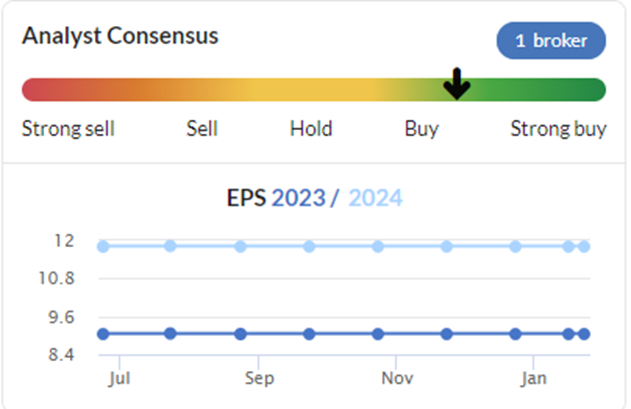
When up-to-date forecasts are issued or FY23 Results are available, then it is likely that the StockRank will be materially below the current 52:
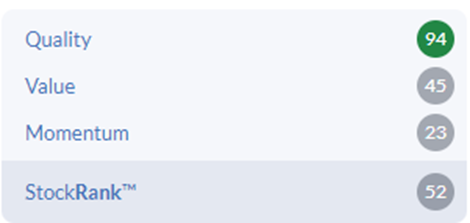
The Value Rank will be lower due to the lower profits, the Quality Rank will be lower due to the Piotroski F-Score reflecting the trend in earnings, as will be the Momentum Rank. If the downgrade is severe enough, this could easily emerge as a Sucker Stock.
When asked about how he was so successful, Canadian ice hockey legend Wayne Gretzky famously said:
I skate to where the puck is going to be, not where it has been.
Investors need to take the same approach. While they may not be able to calculate exactly what the new StockRank will be. When forecasts are withdrawn or a profits warning hits but has not yet been reflected in forecasts, investors should consider where the StockRank is likely to be rather than where it is now. Thankfully, these cases are relatively rare, but it is always worth checking the latest trading statements or results for any current or potential investments.
Despite best efforts, it is still very hard for investors to change their minds about an investment idea. However, using the Stockopedia Tools and making a conscious effort to encourage contrary opinions will go a long way to becoming a better investor. Although I've still got a way to go to reach Munger levels of changing my mind!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
17 comments
Selling decisions are not as hard as suggested in posts here. There’s a simple rule that works well far more often than not. It’s simply run our winners and sell our losers as soon as there is a poor update. Taking profits on big winners ahead after a 20% or whatever gain is ok if running the rest unless bad news. But why sell a 20% winner if the last update was a “better than expected” one UNLESS that good news looks well and truly priced in with the share on a high rating.
Obvious times to sell include disappointing updates and sudden unexpected bad news, and when a share we hold is falling while others in the sector are going up. That’s often a big warning sign that the market is aware of bad news that we aren’t….YET!!
If the whole sector is falling then the fall is the share price for the share we hold in that sector is probably not sinister and might even be a buy opportunity.
Finally if investing in shares doesn’t work for us then consider Investment Trusts. There are Investment Trust bargains galore available at present, some on huge discounts to NAV to such an extent that some can be bought for just 60p when NAV is £1! And Investment Trusts are far less risky than single shares
There’s an excellent Investment Trust thread on Stockopedia!
Hi ken, I also follow the IT thread so I thought I'd put in a link to it here. Looking forward to it going monthly. Keep up your great posts.
Thanks a lot mark for yet another insightful article. I’m keen to read the profit warning survival guide and I can’t access it through the link. Can you help?
Links to the Stocko e-books don't seem to work for some reason. You can browse there from Learn/Books
Excellent, thanks Mark. I recognise these biases. And I was interested to read this just after having sold out of my largest position (McBride (LON:MCB)) after a short battle with myself because I had done well. 5 days down in a row with fair volumes and mediocre fundamentals. I'd ridden a nice wave. Mind you, the Momentum score is still 97 so we will see!
Is it true that very short term momentum is usually "given back" and that you should look over three months or more? I think I read that in one of Ed's articles.
Academic studies show that share prices are "short-term negatively serially autocorrelated", i.e. over 1-3 months, what goes up tends to come back down and vice versa. Medium-term, 6-12 months positively autocorrelated, i.e. winners keep on winning, this is typically what people call momentum. Long-term negatively autocorrelated again. 3-5 years see mean reversion. This is capitalism, the value effect, whatever you want to call it.
Momentum strategies look for the best performers from one month ago to 12 months ago to try to avoid the short-term mean reversion you get when something spikes up (or down).
Thanks Mark. McBride (LON:MCB) heading to 120p then haha
I'm finding it tricky to know when to sell. As Mark says usually, a spike does fall back down, but some I was expecting to pullback have spiked up again, such as Good Energy (LON:GOOD) went from 160p to 340 then back to 320p then up to 410p before falling back to around 300p then back up to 400p then down to 324p. MPAC (LON:MPAC) another one that spiked up, then spike up more. Ashtead Technology Holdings (LON:AT.) spike up then level for a bit, now going up again. System1 (LON:SYS1) similar chart.
A few have pulled back around 10-15% then gone up again, B.P. Marsh & Partners (LON:BPM) and Cerillion (LON:CER).
I don't find the Momentum scores to be much use on these type of shares. There is quite a lag before the Momentum score falls.
Generally I'm selling out too early. But some have dropped due to profit warnings, such as Watches of Switzerland (LON:WOSG) and JD Sports Fashion (LON:JD., fortunately I had sold most of my JD Sports Fashion (LON:JD.) before that.
A solution Rusty2 (unless you are a trader rather than longer term investor) is to buy and sell for INVESTMENT reasons, and ignore short term share price moves. e.g sell on a poor trading update or profits warning and continue to hold or even add on better than expected updates.
I’m holding Good Energy (LON:GOOD) as a potential long term hold in the hope that the profits to double each year for next 3 years forecast is borne out by subsequent updates, but just one update suggesting that’s unlikely and I’ll likely sell.
Good Energy (LON:GOOD) is unusually volatile. So on the rare occasions a share I hold bounces around as much as GOOD does I also have a trading stake to buy the dips and sell the bounces. So far that’s worked well.
Knowing when to sell has to be the hardest thing in investing. Knowing when to buy so much easier in comparison, oddly.
Once I show a 20% gain I then aim to sell that £ amount and leave the rest to run. Doing this has worked well for the past 18 months. Once a share drops below the 30 week ma I then consider to sell.
Mark
Thank you this is really interesting.
I have a bit of a similar investment philosophy to you - I have a bias for invest in “cheap” stocks “with hair on”. There are many problems doing this but one of the advantages is that there is no way I can fool myself these companies don’t have significant problems. More the problem is finding if there are any positives that might turn market sentiment/ or even the company’s financial performance.
Superb article Mark. I used to subscribe to a site where the confirmation bias and loss aversion section of your post applied in spades. So much so that those promoting the shares they loved (e.g Bnn Technology (LON:BNN^B18) (went bust and scored zero on Stockopedia) Reabold Resources (LON:RBD) (now down 99% and shares in issue went from 655 million to about 9 BIllion) and Bluejay Mining (LON:JAY) another down 99% and many similar disasters, were still genuinely believing in them all the way to bankruptcy numerous times.AND they claimed to be surprised and shocked when reallty at last hit. Was the lesson learnt? No!! They just went on to find and promote new disaster shares.
It’s the same on other bulletin boards like ADVFN where the lower the quality of that share so hundreds a day sometimes of rubbish posts promoting them, and that intolerance of any negative comments.
BUT this is not something that happens much on Stockopedia imo. And if you posted it, including the paste below of the section of your great article I’m referring to on sites and bulletin boards like that, your article would either be dismissed or considered rubbish comment!
Here’s the section I was referring to:-
Confirmation Bias - the tendency to only seek information that confirms our prior beliefs and ignore or downplay information that contradicts them.
Confirmation bias means that investors often completely ignore the information they would need to change their minds about an investment. It’s why further stock research doesn’t always lead to better decision-making. Having decided that an investment is undervalued, many investors only look for information that shows how undervalued the stock is. This effect can be even worse when a stock features heavily on discussion boards. Humans are tribal animals, and investors can often group around a particular investment idea. Changing their minds involves leaving the safety of the tribe, and many are simply unwilling to do this.
Loss Aversion – the tendency to prefer gambling on an uncertain future outcome rather than take a definite loss now.
In addition to ownership and confirmation biases, loss aversion adds an extra challenge to jettisoning losing investments. When faced with a loss, investors are more likely to find ways to justify hanging on in the hope of avoiding the loss rather than changing their minds about an investment.
How can investors be better at changing their minds?
Encourage contrary opinions
Some investors become annoyed or even angry when someone disagrees with them over their favourite investment idea. It can feel like someone has run over their pet or called their baby ugly! If an investor finds they have this type of emotional response, that is a crucial sign that they have lost their objectivity.
Very interesting article Mark, many thanks . I am actually quite good at changing my mind about a particular equity, in fact my problem is that I often change it too soon!!! There is actually another quote from , I think, Charlie in which is mentions that patience is the most important attribute in investing, and most non professionals don’t have enough of it.
‘I have lost count of the number of times I have sold far too early !!
Great article - must apply all of this knowledge more. David
Great article Mark.
It is yet another reminder for me to use the SR's more - and to keep an eye on trends.
Interesting piece Mark, thank you. So much of investing is between the ears, I find it endlessly fascinating.