The Week Ahead (13-17 January): GAW, FDEV

Good afternoon and welcome back to the Week Ahead.
After a quiet start to the week, company newsflow has stepped up a gear in the last couple of days. We’ve had a good scattering of trading updates from retailers and another surge of takeovers (three to talk about this morning).
On Tuesday Keelan wrote about why the outlook for takeovers is worth taking note of. And Mark has compiled a very comprehensive guide for private investors who hold companies which receive a takeover bid. You can read that here.
The week in review
Outside of companies' news, the biggest story of the week has been the movement in bond markets.
Earlier in the week, the UK government sold new 30year bonds at a 5.2% interest rate, which sent the yield on 30year gilts to their highest level since 1998. The yield on 10year bonds has also risen to highs not seen since 2008. On Thursday the yield hit 4.93% while the pound dropped to its lowest level against the dollar for more than a year.

The sell-off in the price of bonds (which is what sends yields higher) reflects concerns about the fiscal prospects in the UK. Investors are worried about a rising threat of stagflation (when inflation is high, but the economy is shrinking) in combination with the government’s ongoing heavy borrowing needs.
And this is all before the proposed national insurance changes kick in in April, which could stimulate further price inflation. This week, Next clearly laid out the impact that NI hikes will have on the company’s cost base and said it was likely to push some of those higher costs onto customers. Greggs (which employs over 30,000 staff) also said it would ‘mitigate the NI costs’, while trying to maintain its decent value offering.

The UK is not alone in suffering falling bond prices. In the US, the yield on 10year bonds rose to 4.7% this week. While in Europe, French, German and Italian bonds yields all crept higher.
The equity markets have been mixed, although the FTSE All Share looks like it’s on track to end the week moderately higher:
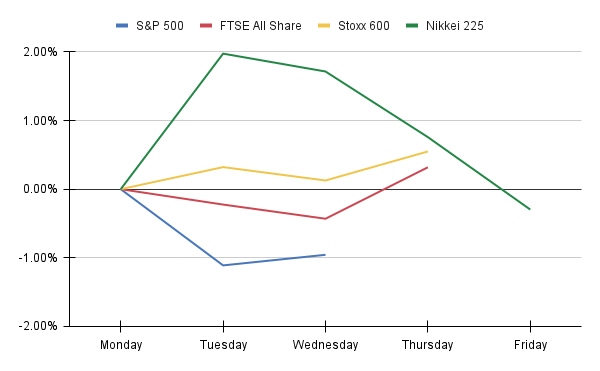
In the US, the S&P 500 was dragged down on Tuesday by a fall in the share price of Nvidia (which makes up 7% of the index) after the chief executive’s keynote speech at the Consumer Electronics Show. We talked about the dominance of the Magnificent 7, which now make up 40% of the total S&P 500 in our webinar on Wednesday. Those who missed it can catch up here.
The Week Ahead: 13-17 January
Onto next week, starting with the economic calendar.
Economic Calendar
Wednesday 15th | ||
07:00 | United KIngdom | Inflation Rate |
10:00 | Europe | Industrial Production |
Thursday 16th | ||
07:00 | United Kingdom | GDP |
07:00 | Germany | Inflation |
13:30 | United States | Retail Sales |
Friday 17th | ||
07:00 | United Kingdom | Retail Sales |
14:15 | United States | Industrial Production |
Companies Reporting
It’s still quite quiet for pre-announced earnings releases or even trading statements, but we expect more newsflow during the week.
UK | US | |
Monday 13 Jan | Quarterly results including: UnitedHealth Blackrock | |
Tuesday 14 Jan | Interim Results including: Games workshop (GAW) and Duke Capital (DUKE) Final results from Ramsdens (RFX) Trading updates including: Grafton (GFTU) Knights Group (KGH) Ocado (OCDO) Robert Walters (RWA) | |
Wednesday 15 Jan | Interim results from Frontier Developments (FDEV) Trading updates including: Currys (CURY) Fuller Smith & Turner (FSTA) Hays (HAS) Vistry (VTY) | Quarterly results including: Wells Fargo JP Morgan Goldman Sachs Citigroup |
Thursday 16 Jan | Trading updates including: Bakkavor (BAKK) Dunelm (DNLM) Harbour Energy (HBR) Rathbones Group (RAT) Taylor Wimpey (TW.) Whitbread (WTB) | Quarterly results including: Bank of America Morgan Stanley |
A tale of two gamers: GAW and FDEV
Not that long ago, Games Workshop (LON:GAW) and Frontier Developments (LON:FDEV) could be held up as peers. They both sell products to similar end markets. Games Workshop makes fantasy worlds full of miniature figurines for a relatively niche division of the gaming community, Frontier Developments makes video games.
In 2021, both had enjoyed strong share price rises driven by rising demand for their products and supported by a robust financial position.
But as Games Workshop has continued the march upwards and recently entered the FTSE 100, with a market capitalisation of £4.4bn, Frontier Developments has collapsed. From highs of over 3300p, the share price is now just 189p.
Now I am not saying that the two companies followed the same operating model. While Games Workshop focused on its core IP, building on its loyal core audience and expanding the universes it creates, Frontier Developments has spent a lot of time building video games for other people. A reliance on inflows of IP from others meant profits were always lumpy. In years that the company was building the games, costs would be very high and profits relatively low, while profits would soar in the period immediately after a game launch.
In recent years that strategy has haunted Frontier Development, with 2024 being described by the chairman as “the most challenging in the company’s 30 year history.” In both of the last two financial years, the company has been loss-making at the operating level largely because of whopping depreciation costs and impairment charges made on underperforming games.
And so, in 2024 management made the decision to refocus on its core expertise in building so-called creative management simulation games (those in which the players build or operate a virtual world). As part of the strategic ‘reset’ the company sold the publishing rights to Roller Coaster Tycoon for £4.9m which helped bolster the cash-based operating performance in the second part of the year. Still it took heavy adjustments to report a tiny positive EBITDA number in the second half of the year.
In first half results due next week, it will be interesting to see whether the turnaround is delivering anything more meaningful.
Megan’s view:
Games Workshop is a truly fabulous company and despite its slightly toppy forward price to earnings ratio of 27x, I remain positive about the investment case. Next week we might get more detail on the company’s IP tie up with Amazon, which could see television series made out of the Warhammer worlds. The Amazon deal could be a boon for the IP section of the company, as well as fantastic marketing. GREEN.
As for Frontier Developments, this has been a real disappointment and because it’s such an asset light business (something which should lead to higher margins), there isn’t even much of a value argument to be made at current levels. I’ll delve into the results next week, but for now I am sticking with the principle: ‘don’t try to catch a falling knife’. RED
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

12 comments
Warpaint London (LON:W7L) will be reporting early in the week. I would hope that the update will be positive, judging by the number of share options that the directors took up in December.
It would be interesting to read how Games Workshop's tie up with Amazon may help GAW's share price, which has recently fallen from well above 1350pps when the news of their listing on the FTSE 100 was first announced. With their having over 500 stores selling the Warhammer products to a niche customer base, in addition to a flourishing on-line sales business of their own. Although Amazon will provide opportunities for brand licensing in films and similar streaming outlets, They are certain to demand far smaller profit margins in exchange for potential increased volume sales their marketing platform is likely to bring. From the news announcement on provided it appears that the film and Warhammer story franchise rights are seen as long term and no difference has been suggested to the IPO value before June 2025.
My understanding, from some recent reading, is that GAW (I hold) might expect to receive around $1mn per episode of a Warhammer TV series made under the auspices of Amazon Prime (I suppose). Inconsequential for the revenues, really, which are above £500mn. The writer suggested that the real 'payback' might come in the enhanced publicity around the Warhammer world/brand and the likelihood that even more players would become interested.
I can't really see any similarity whatsoever between GAW and Frontier except they are both UK listed companies. There apears to me to be a huge 'moat' around GAW, allied to a unique yet pragmatic ethos. If of interest the most recent GAW annual report, though long, is a real eye opener. None of the excess verbiage of most recent UK annual reports but a straightforward explanation of how the company sees itself and its customers.
My Mr Head (Roland) Buffett Screen has highlighted Energy as a play.
We know it's 'cold' so 'current' but these things play out over a longer timeframe.
There is no point in writing an article about next week BUT missing main economic events and getting the dates wrong.
1. US CPI 15th January.
2. Taiwan Semiconductor Manufacturing Co (NYQ:TSM) Results 16th January before open. This is over 1T company!
3. Blackrock (NYQ:BLK) Results out 15th January before open (NOT on Monday 13th January).
All the best
Hope Blackrock (NYQ:BLK) is good. Did they fund the Democrats?
As Megan covers, bonds driving the action reflected in the FTSE 250 losing -4.5 % on the week with 105 of the names losing 5% or more : Plot below shows relative performance across the indices for the close today , Friday 10 Jan
Commodities defied the stronger dollar with a slew of green in the base and precious metals while Brent rallied almost 5% touching the $80 level today - this put even more pressure on the mid caps especially the travel sector but boosted the FTSE100 and support AIM via the resource names
The below plot shows relative strength over the past week and month for several sectors in the LSE (MCAPs>£30m to remove micro cap skew, sized by MCAP, coloured by Bearish to Bullish - a composite score- , plots are medians of price ) . This highlights those sectors getting punished the most by the macro with Retailers, REITs, Utilities, Travel, Homebuilder, Construction all sitting in the lower left Quad (Dogs: declining in both timescales)
Oil and Gas boosted by commodity price improvements in the top right quad (Stars) as is Renewables which has seen a real resurgence in the past month : counterintuitive given the orange Don has been quixotically railing at windmills over the past few weeks . Defensives like Pharm , Tobacco A&D as well as Banks, Miners and Consumer Service names also sitting above the median lines in both timescales
Plot below shows a drill down into the relative price plot of the Renewables Sector names (except Active Energy LON:AEG which is up 260% on the month )
And on the subject of falling knife , LON:GRG Greggs put in the worst week in its quoted history dropping 25.5% on the week - sums up some of the price action in the mid cap massacre we saw in this first full week of 2025 .
Earnings calendar below - interactive version here which can can be sliced by Index, Sector and viewed by date :( particularly mobile friendly dates need to be selected for the week from the top right chiclets)
Here's to a better next week !
click on image to open full screen
Wishing I could throw up graphs like yours Harry.
Kind regards
Hi Megan - It's the US inflation figures on Wednesday 15th as well as the UK inflation figures.
Hi Megan - Card Factory (LON:CARD) due to provide a TU next week as well :)
A physical piece of printed paper with actual hand writing is perhaps more personal and valuable than an email with some clown attachment. Anyway another discussion. I'm interested in Small Modular Reactors, defence, keeping the lights on and making Britain Great Again. Greggs at least is sustaining the beast.