The Week Ahead (14-18 July): TACO, US banks, UK inflation, Burberry, Brickability

NVIDIA (NSQ:NVDA) became the first company to achieve a $4 trillion market cap this week, having gained around 20% so far this year. Investors appear to be comfortable that breakneck growth in demand for the company’s chips will render insignificant any possible negative impact from tariffs and other macro factors.
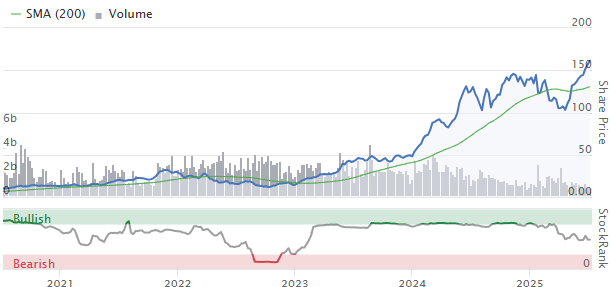
This confidence is reflected in the US S&P 500 index, which also hit new highs during the week. At the time of writing, more than eight in 10 of the index’s constituent companies have delivered share price gains over the last three months.
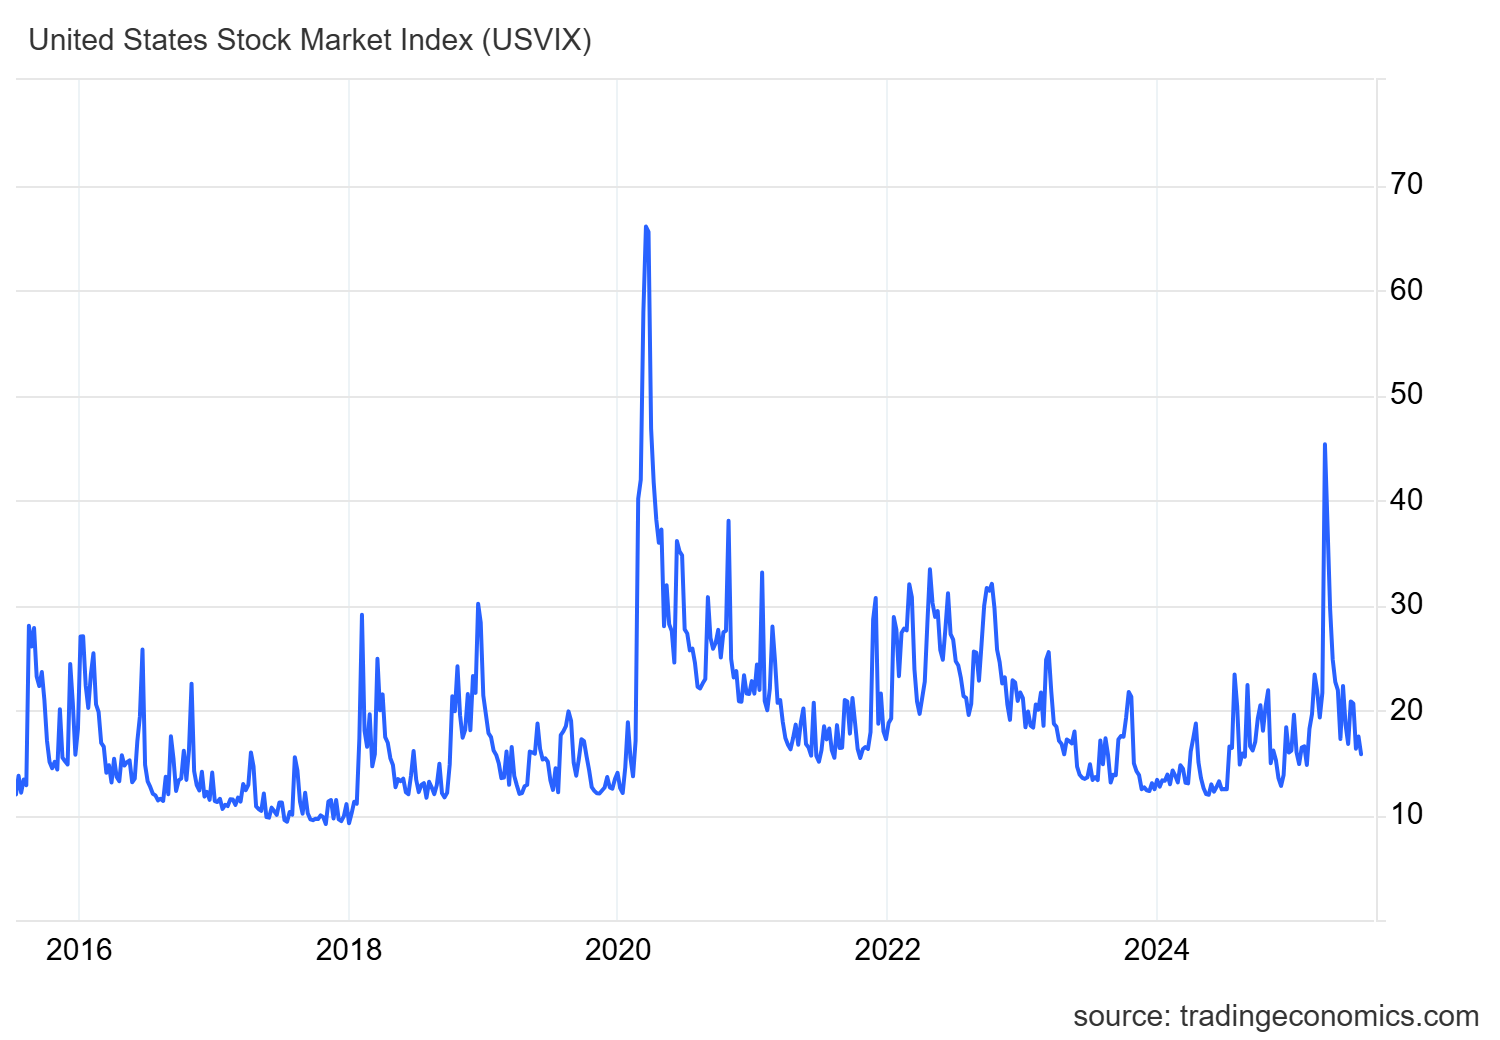
Rightly or wrongly, US equity investors just don’t seem nervous. This seems to be down to the so-called TACO trade – Trump will Always Chicken Out – a view that’s evolved as numerous tariff threats and deadlines have been rolled back at the last minute since April.
As a result, the stock market’s ‘fear gauge’ – the VIX volatility index – is trading at levels that have historically corresponded to fairly benign conditions for investors:
It’s always possible that this confidence is misguided, of course. Some commentators are pointing out that record US equity prices are at odds with the more cautious view being taken by bond markets, where investors seem to be pricing in a more downbeat outlook for the world's largest economy.
Bond investors are traditionally seen as the smart money, but given the broader uncertainties of this situation, I’m not sure there is a conclusive right answer just yet.
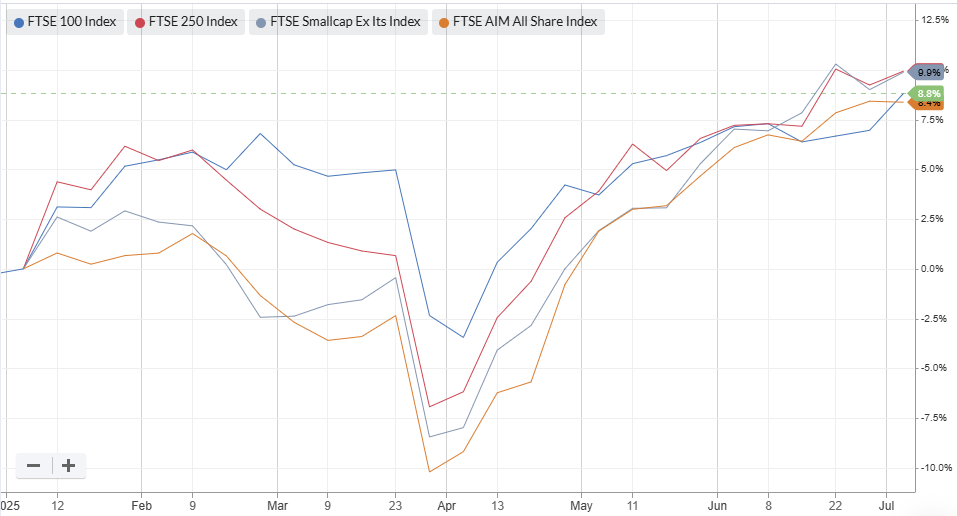
The good news for UK equity investors is that the animal spirits on show in US equity markets have been starting to appear in the UK market, too.
Small and mid-cap indices enjoyed a strong Q2. All the UK’s main indices are now in positive territory for the year:
We don’t yet know how durable this rally will be. While I’m fairly positive about the opportunities in British shares, the UK economy doesn’t necessarily seem in a strong position to drive growth.
We learned on Friday that GDP fell by 0.1% in May. There seems to be a plausible case to believe that further tax rises might yet become necessary.
Looking at the UK equity market specifically, there’s also still one important ingredient missing that will probably be needed to deliver a sustained rally – fund inflows.
As Graham discussed recently, most UK-focused fund managers are still seeing net outflows, despite increasingly positive market performance.
This chart from fund network Calastone shows that the persistent trend of outflows eased in Q2, but has not yet started to reverse:

Source: Calastone July ‘25
Personally, I think there’s only so far we can go when it comes to worrying about the bigger picture. Focusing on company fundamentals and proven investing factors such as quality, value and momentum is always my main focus.
Turning to UK company news, it looks like a quiet start to the week in the UK next week, with an interesting range of small and mid-caps updating later in the week.
Across the pond, it’s US bank earnings season. A roll call of the biggest names in global finance are all lined up to report their second-quarter earnings, so it may be worth looking out for any key underlying trends from their commentary.
Economic Calendar
Date | Time (BST) | Country | Event |
14 July | 04:00 | China | Exports & Balance of Trade |
15 July | 03:00 | China | Q2 GDP |
15 July | 10:00 | Germany | Economic Sentiment index |
15 July | 13:30 | US | CPI Inflation |
16 July | 07:00 | UK | CPI Inflation |
16 July | 13:30 | US | Purchasing Price Index inflation |
16 July | 15:30 | US | EIA Crude oil inventories |
17 July | 07:00 | UK | Unemployment |
17 July | 13:30 | US | Initial jobless claims |
17 July | 13:30 | US | Retail Sales |
18 July | 07:00 | Germany | Purchasing Price Index inflation |
Companies Reporting
Date | UK Trading Updates and AGMS | UK Financial Results | International Financial Results |
Monday 14 July | Eco Animal Health (EAH) | Fastenal ($FAST) | |
Tuesday 15 July | Experian (EXPN) Integrafin Holdings (IHP) Robert Walters (RWA) Barratt Redrow (BTRW) | Brickability Group (BRCK) Gateley Holdings (GTLY Northern Bear (NTBR) RM (RM) Sosander (SOS) | JPMorgan ($JPM) BlackRock ($BLK) Citigroup ($C) Wells Fargo ($WFC) Bank of New York Mellon ($BK) |
Wednesday 16 July | Bloomsbury Publishing (BMY) Caledonia Investments (CLDN) Vianet (VNET) Intermedia Capital Group (ICG) Wynnstay Properties (WSP) Harbourvest Global Private Equity (HVPE) | Cohort (CHRT) Creightons (CRL) Ocado (OCDO) | J&J ($JNJ) Bank of America ($BAC) Morgan Stanley ($MS) Goldman Sachs ($GS) |
Thursday 17 July | B.P. Marsh & Partners (BPM) RS Group (RS1) Johnson Matthey (JMAT) QinetiQ (QQ.) SSE (SSE) Premier Foods (PFD) Kefi Gold and Copper (KEFI) Helical (HLCL) Big Yellow Group (BYG) Wise (WISE) | Ilika (IKA) Frasers (FRAS) | Netflix ($NFLX) Abbott ($ABT) General Electric ($GE) PepsiCo ($PEP) |
Friday 18 July | Burberry Group (BRBY) United Utilities (UU.) Jangada Mines (JAN) | Bridgepoint Group (BPT) | American Express ($AXP) Charles Schwab ($SCHW) 3M ($MMM) Schlumberger ($SLB) |
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

5 comments
Well Trump announced 30% tariffs for EU and Mexico from 1st Aug. Ive been fully invested and so gained alot from this strong market but can't help but think one should have a good cash reserve handy in case the market falls (again) . Sadly I might not take my own advice as I tend just to hold through choppy times . Need to have a word with myself!
I am though pretty sure America will go into a recession within the coming 12 months or so. There just been so much uncertainly it will have subdued investment and activity. At some point that will show itself.
But take the point we are here for specfic investment in certain companies and maybe we leave the market to do its thing and in the long term its - Time not Timing.
Hi Roland, useful report as always, thanks.
Is there any reason Burberry and Brickability are mentioned in the headline? Brickability (LON:BRCK) is one I have owned, so if it’s significant I’d be interested in your thoughts.
NVIDIA (NSQ:NVDA) is up about 70% in under 3 months.
The UK, is mixed, plenty of profit warnings, some already from the budget changes in April.
Roland - where did you get NCC (Tues 15th) from? Interims were June 19th and I am not expecting anything until the pre-close for the year ending 30/9 (12/9/24).
Hi sharw,
Thanks for flagging this up. You are correct about NCC (LON:NCC) - nothing is scheduled for this week.
In the spirit of full disclosure, I have to confess that the interim date I listed is for a different NCC (Ncc AB (STO:NCC A)) , not the London listed IT group. I should have spotted this!
I'll amend the table!
Apologies for any confusion,
Roland