The Week Ahead (15-19 Dec): BoE interest rate decision + NKE, CURY & SMWH

Welcome to the final Week Ahead of 2025. This weekly update will take a break over the festive period and return on 2 January 2026.
Company news is expected to be fairly thin next week, but the economic calendar is relatively busy. One key focus for UK investors will be the Bank of England interest rate decision on Thursday.
In theory, at least, November’s Budget is expected to result in a reduction in inflation of up to 0.5% by the middle of next year. This naturally supports the case for a rate cut.
City projections suggest the Monetary Policy Committee (MPC) will vote to cut the Bank Rate by 0.25% to 3.75%, after having held rates unchanged since August. A cut to interest rates is generally seen as positive for equity markets. It reduces the cost of borrowing and puts downward pressure on yield expectations, potentially supporting higher asset prices.
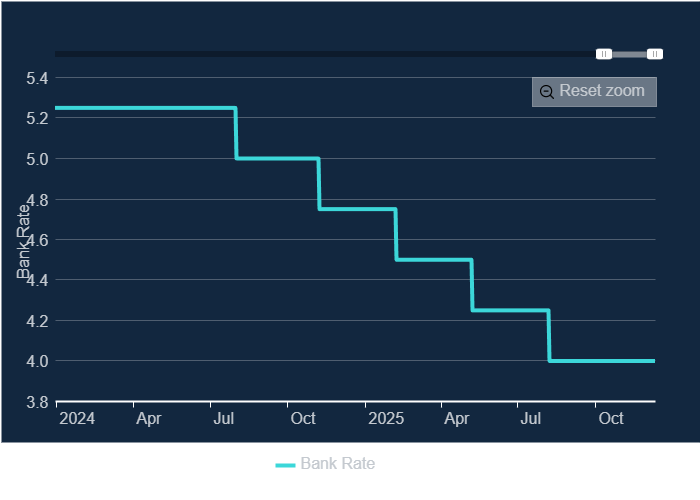
Source: Bank of England
Despite this consensus view, next week’s MPC vote is expected to be quite tight. There’s a still view among some MPC members – including BoE Deputy Governor Clare Lombardelli – that inflation remains a concern.
Ms Lombardelli was quoted in the FT (£) this week suggesting it might be wise to “slow down a bit” [on rate cuts], saying she worries “more about the upside risks to inflation”.
One factor that may prove relevant is the latest UK unemployment data, which is due on Tuesday. Higher unemployment could potentially ease the path to another interest rate cut, as it might suggest greater slack in the economy than is desirable.
Company news preview
UK and US company results are likely to be thin on the ground next week, if my usual data sources can be trusted. In the remainder of this piece I’ve selected three stocks (one US, two UK) for a closer look.
As usual, scroll straight to the bottom of this piece to see our Economic and Company Reporting calendars for the next week.
Nike (NYQ:NKE)
Shares in the sportswear giant have fallen by around 60% from their 2021 highs.
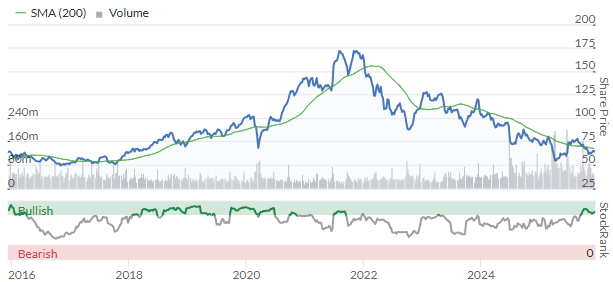
When I first saw this chart, I thought it might suggest a buying opportunity for the stock. But I’m not sure it’s quite as simple as that.
One of the reasons for the stock’s de-rating is that Nike’s sales have gone into decline since peaking in the 2023/24 financial year (Nike has a 31 May year end).
Nike’s revenue fell by nearly 10% last year. That’s a problem, especially against a backdrop of inflation. It’s very difficult for any business to deliver real earnings growth if its sales are in decline.
The impact on profits has been fairly brutal – operating profit fell by 41% last year, while margins fell to a level last seen seen during the first year of the pandemic:
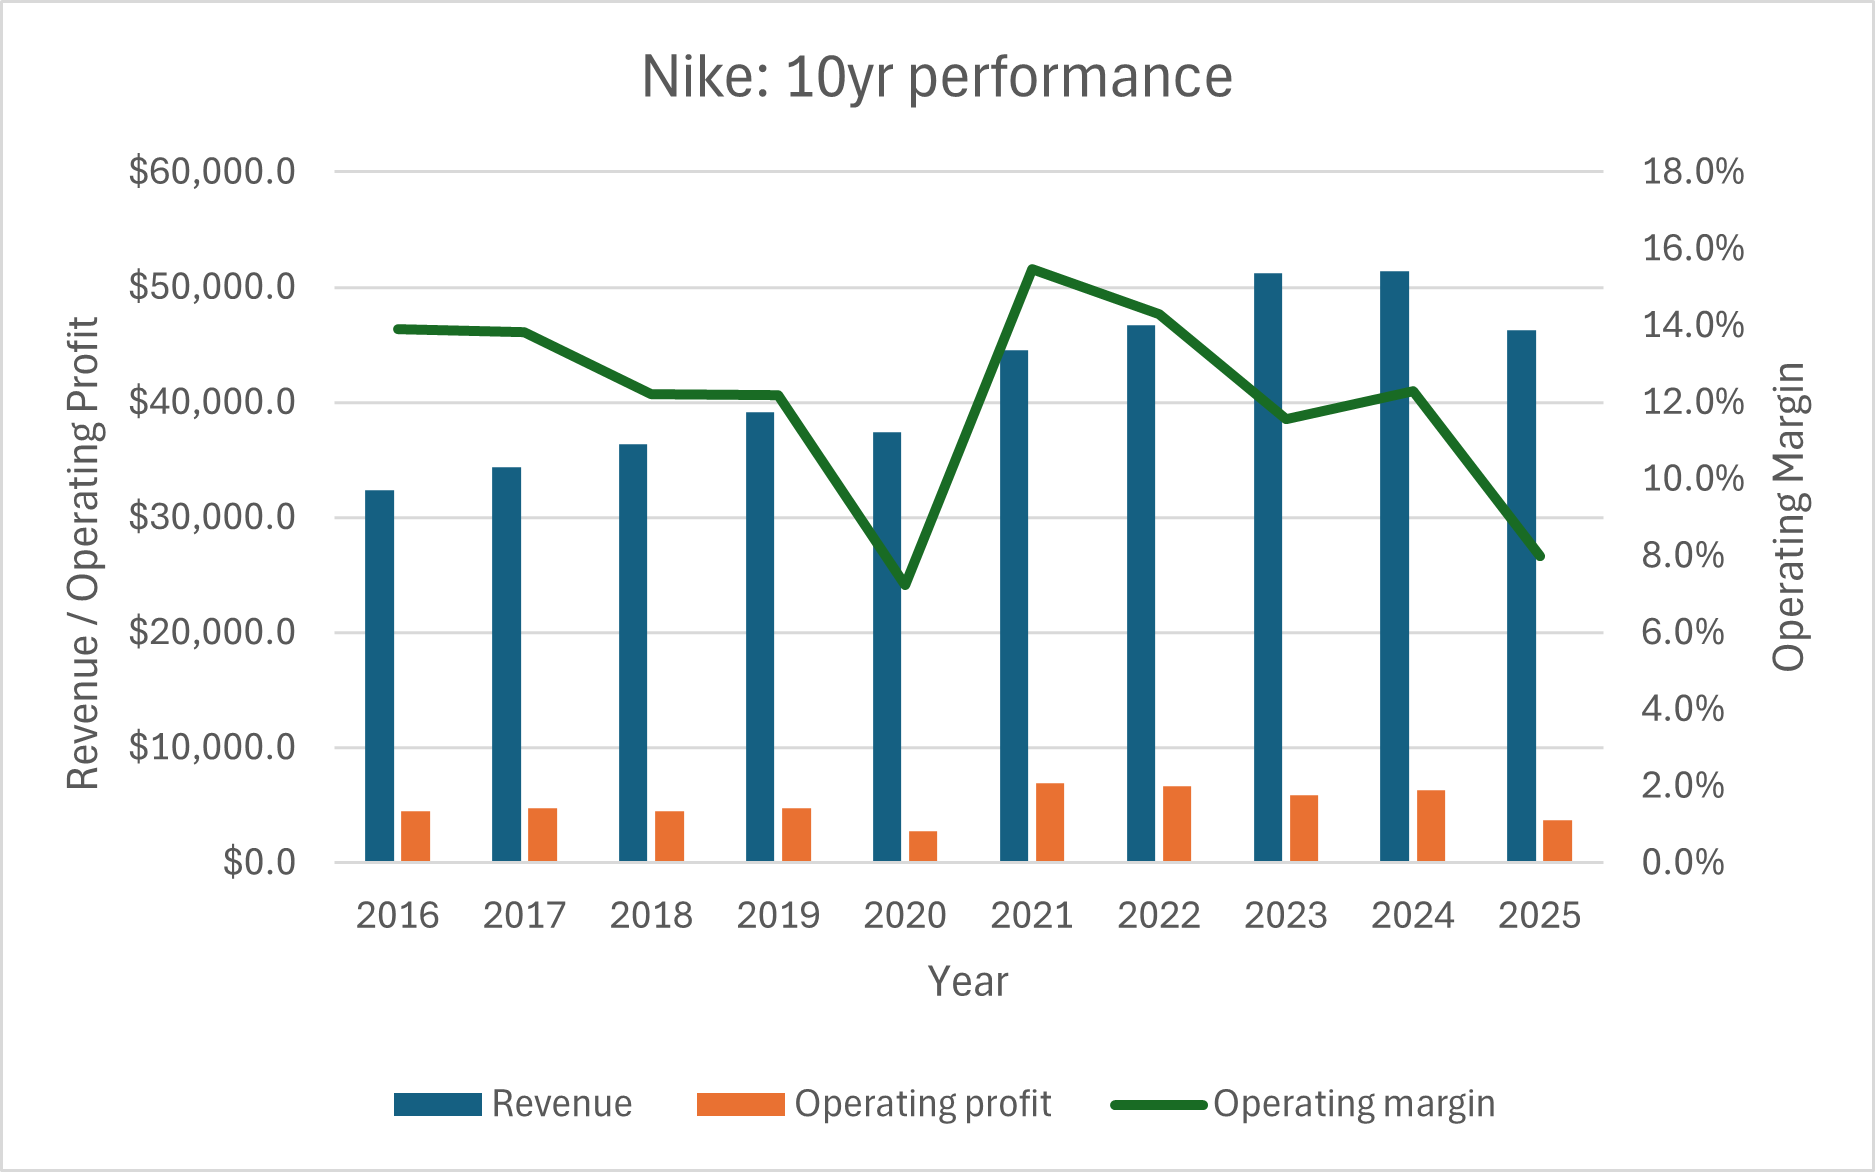
Forecasts suggest Nike’s sales will make a modest return to growth during the current financial year. My guess is that investors will be closely focused on sales commentary from CEO Elliott Hill next week, in addition to the usual focus on earnings.
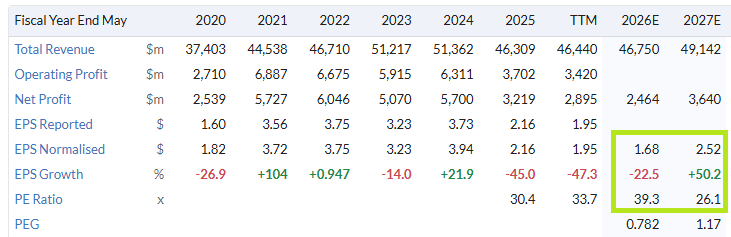
The slump in Nike’s profits means its shares are still trading on a forward P/E of more than 30.
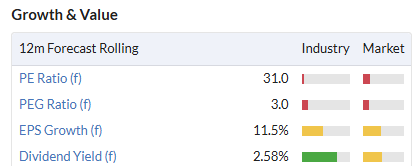
Splitting this down shows analysts are predicting a 50% rise in earnings for FY27, potentially supporting a more reasonable valuation:
However, the stock’s High Flyer styling supports my view that a fair chunk of any recovery may already be baked in the price. Certainly I’d expect harsh treatment if results disappoint.
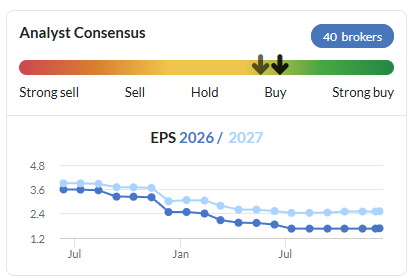
Fortunately for shareholders, the broker consensus view appears to have stabilised over the last six months.
I don’t have much insight into this business, but I recognise that Nike has had to adapt to growing competition from more nimble brands and a shift to greater levels of online and direct-to-consumer selling.
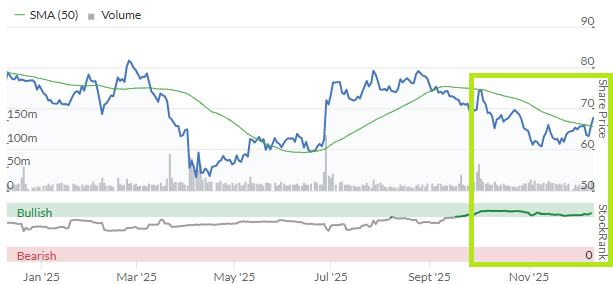
Despite these challenges, I think this remains a world-class global brand. I suspect we’ll see a recovery at some point and am encouraged to see the StockRank has trended higher in recent months. Is a bowl forming on the 1-year chart?
Currys (LON:CURY)
It’s easy to be sceptical about Currys as an investment (or even as a customer), but the UK’s bricks-and-mortar electrical retailer is performing well and has been a double-bagger for UK investors over the last two years.
CEO Alex Baldock has improved operational performance in the core business, while also modernising the group’s mobile offering and delivering strong growth in the group’s credit offer. Supplying goods on finance provides incremental profit, but also aids customer stickiness.
With the benefit of hindsight, following the StockRank provided a good lead into this opportunity.
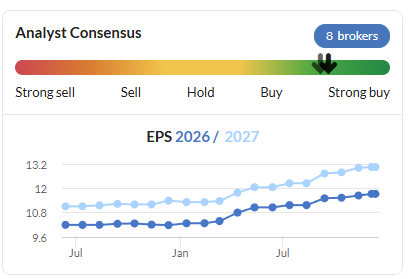
While the easy gains may now be in the bag, Currys retains Super Stock styling. I think it could still be an interesting choice if management can maintain this year’s impressive run of earnings upgrades:
This week’s half-year results from the company cover the six months to 31 October.
The numbers themselves may not be too significant, given the significant H2 weighting to the festive period (H1 is often loss-making).
However, management commentary on sales trends and the full-year outlook will be closely watched by the market and could give rise to a further upgrade (or perhaps a downgrade…).
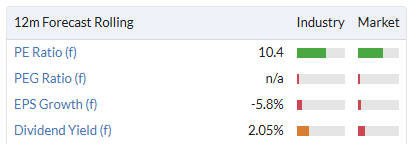
Turning to the stock, the valuation still looks reasonable to me at face value:
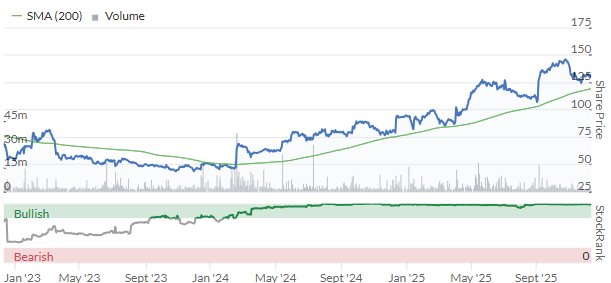
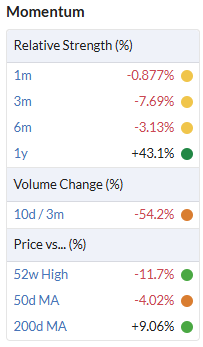
However, I’d also note the recent drop-off in technical momentum. If this continues, I’d guess we might see some pressure on the share price:
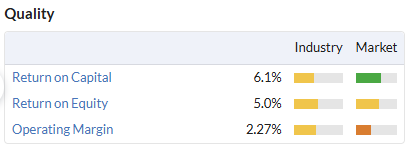
More broadly, I would argue that this business is always likely to deserve a fairly modest valuation. It’s low margin, cyclical and faces intense competition on price from Amazon and other online retailers.
Personally, I’m on the fence. But I can certainly see a continued bull case for the stock, which remains very highly ranked:
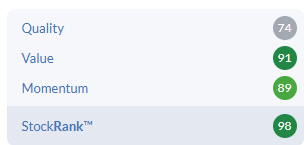
Currys’ interim results are expected on Thursday – keep an eye on the DSMR for our thoughts.
WH Smith (LON:SMWH)
Checking the RNS feed on Friday morning before finalising this article, I noticed that the travel retailer has delayed the publication of its final results for the second time since October. Results for the year ended 31 August will now be published on Friday 19 Dec, rather than Tuesday 16 as previously expected.
It’s not hard to see why the company might need extra time to finalise its figures. Accounting errors in its US travel business mean FY25 profit guidance for this division has been cut from £55m to just £5-15m.
An update from the company in November warned investors to expect a litany of changes relating to supplier income in its FY25 results, with significant restatements expected for FY24 and FY23 as well.
Supplier income represents rebates based on hitting sales volumes, promotions and other such criteria. Correctly timing the recognition of such items in a company’s accounts isn’t always straightforward. It’s also an area where aggressive accounting can be used to inflate profits – although I’m not suggesting any kind of wrongdoing in this case.
Alongside the supplier income issues, a year-end review by the company has also identified around £20m of “additional one-off costs” relating to inventory in North America. These are said to be “primarily in respect of inventory shrinkage [theft/loss] and aged inventory provisioning”. Management says that handling of these inventory issues has not been consistent with the group’s accounting policies.
Even the accounting review that’s been necessary to unravel all of these issues has come at a cost – WH Smith expects to incur fees of “up to £10m”.
The curse of big acquisitions? The group’s US business was largely created through the acquisition of InMotion (2018, $198m) and Marshall Retail Group (2019, $400m). Soon after the latter deal, of course, the world plunged into the pandemic travel shutdown. I’d speculate that these operations may never have been properly integrated and brought up to the operating standards of the group’s core UK travel operations.
When I looked at WH Smith in more detail in 2024, my impression was that the group had paid a fairly full price for its US acquisitions and would need to deliver decent organic growth to generate returns in line with its historic profitability.
Unfortunately, strong sales growth wasn’t immediately apparent despite resurgent levels of transatlantic travel. North America revenue rose by just 6% in FY24, compared to a 12% rise in the UK. A 6% increase in sales isn’t much, given that US inflation was running at over 3% for most of that year.
Fast-forward to today and WH Smith shares have fallen further and faster than I’d ever have expected:
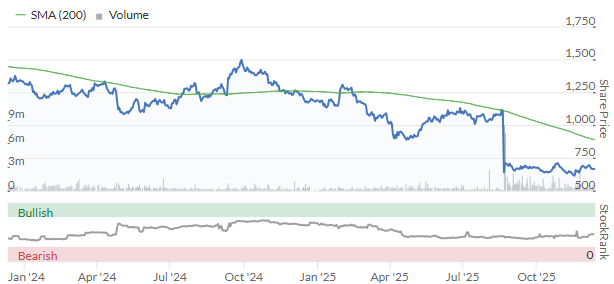
Maintaining a watching brief: I am not inclined to try and catch the bottom just yet. But I do think that the core appeal of this business remains. Adjusted pre-tax profit for FY25 is still expected to be within a range of £100-110m, suggesting the valuation could be quite modest at the current £844m market cap.
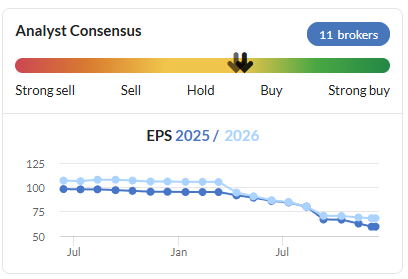
Although net debt is expected to be above 2x EBITDA at the end of this year, this business has historically been very cash generative. Once these issues are ironed out, I would hope that WH Smith can repay debt and return its focus to shareholder returns.
It’s worth remembering that the UK and Rest of World operations aren’t affected by the issues that have derailed the group’s share price – as far as we know, problems are limited to North America.
While these big acquisitions may now seem misjudged, or at least mismanaged, I think they may still eventually deliver the hoped-for benefits. My (limited) personal experience suggests that WH Smith’s US airport travel stores are generally well located and often busy. I don’t see any obvious reason why they should not be profitable.
While the company has yet to recruit a new CEO, investors will be hoping this week’s results provide confidence that these issues have been addressed and reliable guidance for FY26.
Of course, details of actual trading will also be important. Having exited the high street and become a pure-play travel retailer, can WH Smith return to consistent revenue growth?
Friday’s results from this FTSE 250 business promise to be an interesting read, livening up what is otherwise likely to be a very quiet day for UK company news.
Here’s a summary of what’s expected next week.
Economic Calendar
Date / Time (BST) | Country | Event |
15 December | ||
00:01 | UK | Rightmove House Price Index |
02:00 | China | Industrial Production |
10:00 | EU | Industrial Production (Oct) |
13:30 | US | NY Empire State Manufacturing Index |
16 December | ||
07:00 | UK | Unemployment Rate |
09:30 | UK | Manufacturing PMI |
09:30 | UK | Services PMI |
13:30 | US | Retail Sales |
13:30 | US | Non-Farm Payrolls |
13:30 | US | Building Permits |
13:30 | US | Unemployment Rate |
17 December | ||
07:00 | UK | Inflation (Nov) |
10:00 | EU | Inflation (Nov) |
18 December | ||
12:00 | UK | Bank of England Interest Rate Decision |
13:15 | EU | ECB Interest Rate Decision |
13:30 | US | Inflation Rate |
13:30 | US | Initial Jobless Claims |
19 December | ||
07:00 | UK | Retail Sales (Nov) |
13:30 | US | Personal Income |
13:30 | US | Personal Spending |
15:00 | US | Existing Home Sales |
Companies Reporting
Date | UK Trading Updates and AGMS | UK Financial Results | International Financial Results |
Monday 15 Dec | Helium One Global (LON:HE1) | Gore Street Energy Storage Fund (LON:GSF) | |
Tuesday 16 Dec | SThree (LON:STEM) Shearwater (LON:SWG) Time Finance (LON:TIME) | Hollywood Bowl (LON:BOWL) Jersey Electricity (LON:JEL) Oxford Biodynamics (LON:OBD) | Lennar (NYQ:LEN) |
Wednesday 17 Dec | Beeks Financial Cloud (LON:BKS) Guardian Metal Resources (LON:GMET) Netcall (LON:NET) | Integrafin Holdings (LON:IHP) Victoria (LON:VCP) | General Mills (NYQ:GIS) Jabil (NYQ:JBL) Micron Technology (NSQ:MU) |
Thursday 18 Dec | Chesterfield Special Cylinders Holdings (LON:CSC) Currys (LON:CURY) Frp Advisory (LON:FRP) | Accenture (NYQ:ACN) Cintas (NSQ:CTAS) Darden Restaurants (NYQ:DRI) FedEx (NYQ:FDX) Nike (NYQ:NKE) | |
Friday 19 Dec | Proservice Building Services Marketplace (LON:PRO) (formerly HSS Hire) WH Smith (LON:SMWH) | CAG AB (STO:CAG) Carnival (LON:CCL) Paychex (NSQ:PAYX) Winnebago Industries (NYQ:WGO) |
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

4 comments
Excellent. An insightful and thoughtful assessment of three pretty important companies. I personally have not owned any of them but visited Currys Guildford last week and was very impressed. I am not so sure that Amazon or other purely online companies are a threat. For amateurs like myself I like to see an expensive product, visualise its usage and possibly its location, and if necessary speak to a sales assistant. This store may be exceptional - it has moved and been updated - but I came away satisfied and will return.
Spendi it while you've got ir is my thinking on Currys (LON:CURY) . Fallen inflation next June to me means less spending being done.
Currys (LON:CURY) exactly the kind of dull low-margin company that fits Ed's paradoxical earnings-beating chart. I went in early based significantly on the stock ranks and it's worked out very well. So far!
FYI, I am expecting Goodwin (LON:GDWN) interims next week.