The Week Ahead (21-25 July): FTSE 100, Alphabet, Tesla, Lloyds, ME Group

The FTSE 100 touched an all-time record intraday high of 9,016 on Tuesday, although it didn’t manage to stay above 9,000 and looks likely to end the week broadly unchanged. The UK’s big cap index is now up by nearly 10% so far this year:
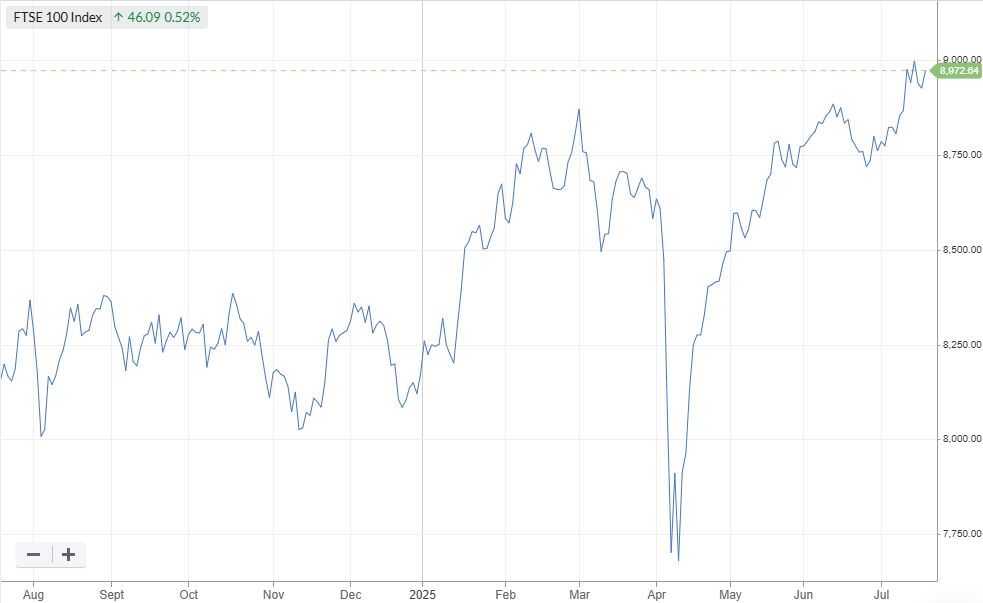
This strength suggests that the animal spirits I highlighted in the last Week Ahead may still be at work in some parts of the market. Unfortunately, evidence from the real-world economy to support this seems a little more mixed, especially in the UK.
This week’s UK economic data has included a rise in both inflation (to 3.6%) and unemployment (to 4.7%), in addition to commentary from housebuilder Barratt Redrow (LON:BTRW) suggesting market conditions remain sluggish.
A big profit warning from small cap Churchill China (LON:CHH) also highlighted the despondent state of affairs in the hospitality industry, which is particularly struggling under the weight of higher employment costs.
The picture looks a little more benign in the US. Initial jobless claims were slightly lower than forecast on Thursday, while retail sales rose by 0.6%, beating forecasts for an increase of 0.1%.
All of this said, perhaps it’s worth remembering that bull markets are said to climb a wall of worry. The real economy and the stock market don’t necessarily move hand in hand. Good businesses adapt to changing circumstances and at any time, there are usually some sectors of the market doing well.
What’s in store next week?
US earnings season continues next week. Following this week’s deluge of bank results, the week ahead will see numbers from Google owner Alphabet, Tesla, ExxonMobil, Coca-Cola, McDonald’s and Mastercard, among others.
Here in the UK, FTSE 100 names including Lloyds Banking Group, quality favourite Relx and consumer goods firm Reckitt Benckiser are due to report. We should also have updates from a raft of smaller companies.
Reporting from many of these companies is likely to highlight macroeconomic conditions in the UK and further afield. Updated Purchasing Manager Indices (PMI) in the UK, EU and US are also likely to shed light on the health of the manufacturing and service sectors in western markets and perhaps some initial impact from US tariffs.
We also have an interest rate decision due next week from the European Central Bank, whose key rate has already fallen from 3.15% to 2.15% this year. That’s a sharp contrast to the Bank of England and US Fed, whose main rates remain at 4.25%.
Finally, there should be a statement from embattled Fed Chairman Jerome Powell, ahead of an auction for long-dated US government debt. Watch out for any volatility in bond yields if investor appetite disappoints – or if President Trump attempts to follow through on his threats to remove Powell.
That’s all to come – but first, I hope you have a great weekend!
Economic Calendar
Date | Time (BST) | Country | Event |
21 July | 00:01 | UK | Rightmove House Price Index |
22 July | 07:00 | UK | Public Sector Net Borrowing |
22 July | 14:30 | US | Fed Chair Jerome Powell speaks |
22 July | 21:30 | US | API Weekly Crude Oil Stock |
23 July | 12:00 | US | Mortgage data |
23 July | 15:00 | US | Existing Home Sales |
23 July | 15:00 | EU | Consumer Confidence flash data |
23 July | 18:00 | US | 20-year Treasury Bond auction |
24 July | 07:00 | Germany | Consumer Confidence |
24 July | 08:30 | Germany | Manufacturing & Services PMI |
24 July | 09:30 | UK | Manufacturing & Services PMI |
24 July | 13:15 | EU | ECB Interest Rate decision |
24 July | 13:30 | US | Initial jobless claims |
24 July | 14:45 | US | Manufacturing & Services PMI |
24 July | 15:00 | US | New Home Sales |
25 July | 07:00 | UK | Retail Sales |
25 July | 13:30 | US | Durable Goods Orders |
Companies Reporting
Date | UK Trading Updates and AGMS | UK Financial Results | International Financial Results |
Monday 21 July | Spiritus Mundi (SPMU) | MONY Group (MONY) | Verizon ($VZ) Dominos Pizza ($DPZ) |
Tuesday 22 July | B&M European Value Retail (BME) Compass Group (CPG) Evoke (EVOK) GB Group (GBG) Kier Group (KIE) Luceco (LUCE) Mitie Group (MTO) Surface Transforms (SCE) | Arbuthnot Banking (ARBB) ME Group International (MEGP) TheWorks.co.uk (WRKS) | Coca-Cola ($KO) Philip Morris International ($PMI) Raytheon Technologies ($RTX) Texas Instruments ($TXN) Lockheed Martin ($LMT) General Motors ($GM) |
Wednesday 23 July | HICL Infrastructure (HICL) JD Wetherspoon (JDW) Norcros (NXR) Record (REC) Symphony Environment (SYM) Tissue Regenix (TRX) VP (VP.) | Aptitude Software (APTD) Breedon Group (BREE) FRP Advisory (FRP) Informa (INF) PensionBee Group (PBEE) Van Elle Holdings (VANL) | Alphabet ($GOOG) Tesla ($TSLA) IBM ($IBM) McDonalds ($MCD) |
Thursday 24 July | Airtel Africa (AAF) AJ Bell (AJB) Aminex (AEX) BT Group (BT.A) Challenger Energy (CEG) CMC Markets (CMCX) DiscoverIE Group (DSCV) DP Poland (DPP) Emmerson (EML) Halma (HLMA) Inspiration Healthcare Group (IHC) Pennon Group (PNN) Tate & Lyle (TATE) Tatton Asset Management (TAM) Vodafone Group (VOD) Wizz Air (WIZZ) | Centrica (CNA) Howden Joinery (HWDN) IG Group Holdings (IGG) Lloyds Banking Group (LLOY) Quartix Technologies (QTX) Reach (RCH) Reckitt Benckiser (RKT) Relx (REL) Severfield (SFR) SysGroup (SYS) | Mastercard ($MA) Blackstone ($BX) Union Pacific ($UNP) TotalEnergies SE (€TTP) Royal Caribbean Cruises ($RCI) |
Friday 25 July | Atome (ATOM) Bezant Resources (BZT) Cordiant Digital Infrastructure (CORD) Steppe Cement (STCM) Taylor Maritime (TMIP) | Jupiter Fund Management (JUP) Rightmove (RMV) | ExxonMobil ($XOM) Chevron ($CVX) Phillips 66 ($PSX) |
Disclosure: at the time of publication, Roland owned shares in Churchill China.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

5 comments
Thursday is also the Fourth Quarter FuM Announcement & Pre-Close Trading Update for City of London Investment (LON:CLIG) . Source: https://clig.com/financial-cal...
Maybe too much on X but there are serious issues in this country with the users and the growers. If the social contract with government breaks down then this is not a nice environment for investment.
Costs of energy, water, local government is growing and now wealth taxes are on the table. Ok I don't have 10m in assets so 'safe' but the bar will be lowered slowly or overnight as they need the money for socialism. No incentive here to build wealth. pension or anything if going to be taken down the line - and the direction of travel is clear.
Maybe the big institutions can stay above the streets so still provide the worlds financial hub but they must be worried.
I missed Serco (LON:SRP) rise - silly me.
Ok America is a time bomb - but keeps the impossible money train running - x trillion pension funds now being pushed into crypto "The Genius Act" - when this explodes will make Tulips look like Martian daisies. Opening mines for the minerals previously got from China (they have abundance, whilst the UK imports oil/gas - good Lord in Heaven).
Sorry about Churchill China (LON:CHH) the Stage 4 started in 2022 - Chart tells the story.
I hold Filtronic (LON:FTC) and BAE Systems (LON:BA.) ETF's and miners but otherwise trying to liquidate everything else from the UK as soon as they break even.
They say Korea will be nice in 2026 but a land far away.
B&M European Value Retail SA (LON:BME)
Roland, we have already had the trading up date. Released on 15 July.
Hi jonno,
The date next week is for the AGM at B&M European Value Retail SA (LON:BME).
Companies often issue AGM trading updates, so this can be useful to monitor. Although in this case I don't expect another update, given how recent B&M's last update was.
Roland
Hi Roland, would it be possible to differentiate between Trading updates and AGMs? Maybe an asterisk, for AGM?
Trading updates are far more relevant to me.