The Week Ahead (23-27 Feb): UK earnings season kicks off + Iran, NVDA, MONY, DGE, RR

Welcome back to The Week Ahead. We’re gearing up for a mammoth week of earnings in the UK next week as the floodgates open on Wednesday and results season gets underway.
Given the impending flow of company news, perhaps it’s just as well that the economic news scheduled for next week is relatively limited.
There may be more focus on geopolitical events as President Trump said on Thursday that Iran needs to reach a deal in the next 15 days “or bad things will happen”. The US has already staged a substantial military build-up in the Middle East which is said to be similar to that seen before the 2003 Iraq war – enough to sustain a significant air campaign.
Opinions vary on the impact attacks could have on oil markets and broader stability in the region. Last June’s Iran-Israel conflict – which ended with the US bombing Iran – only caused a short-lived blip in oil prices, but there’s always the risk of a more severe reaction.
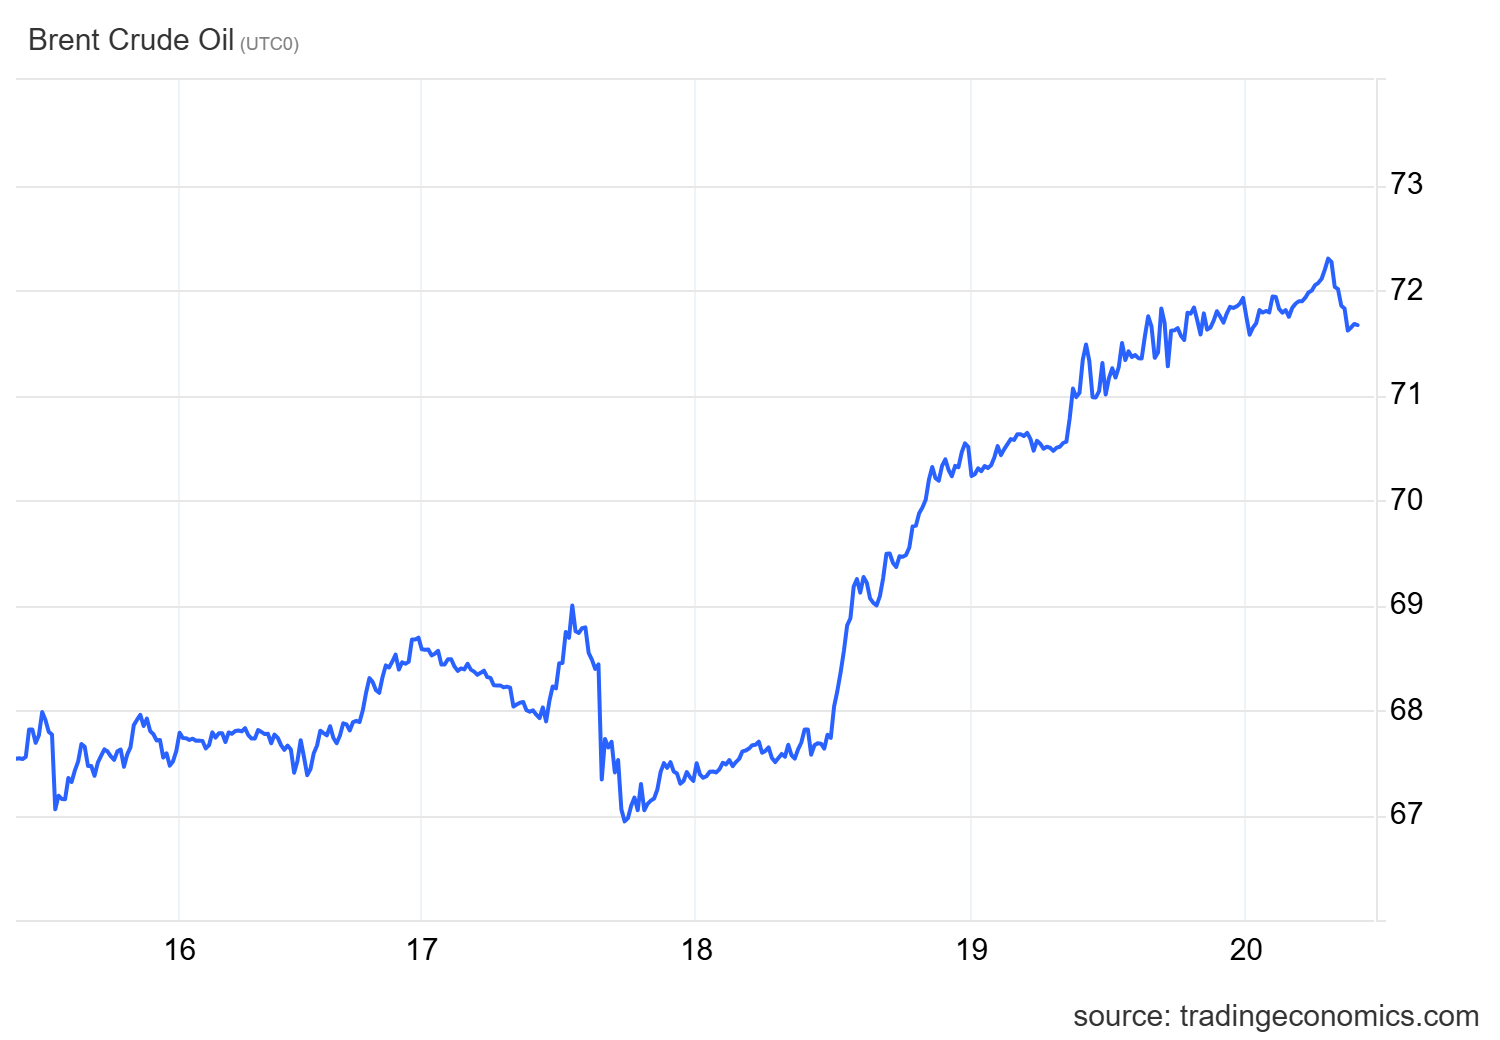
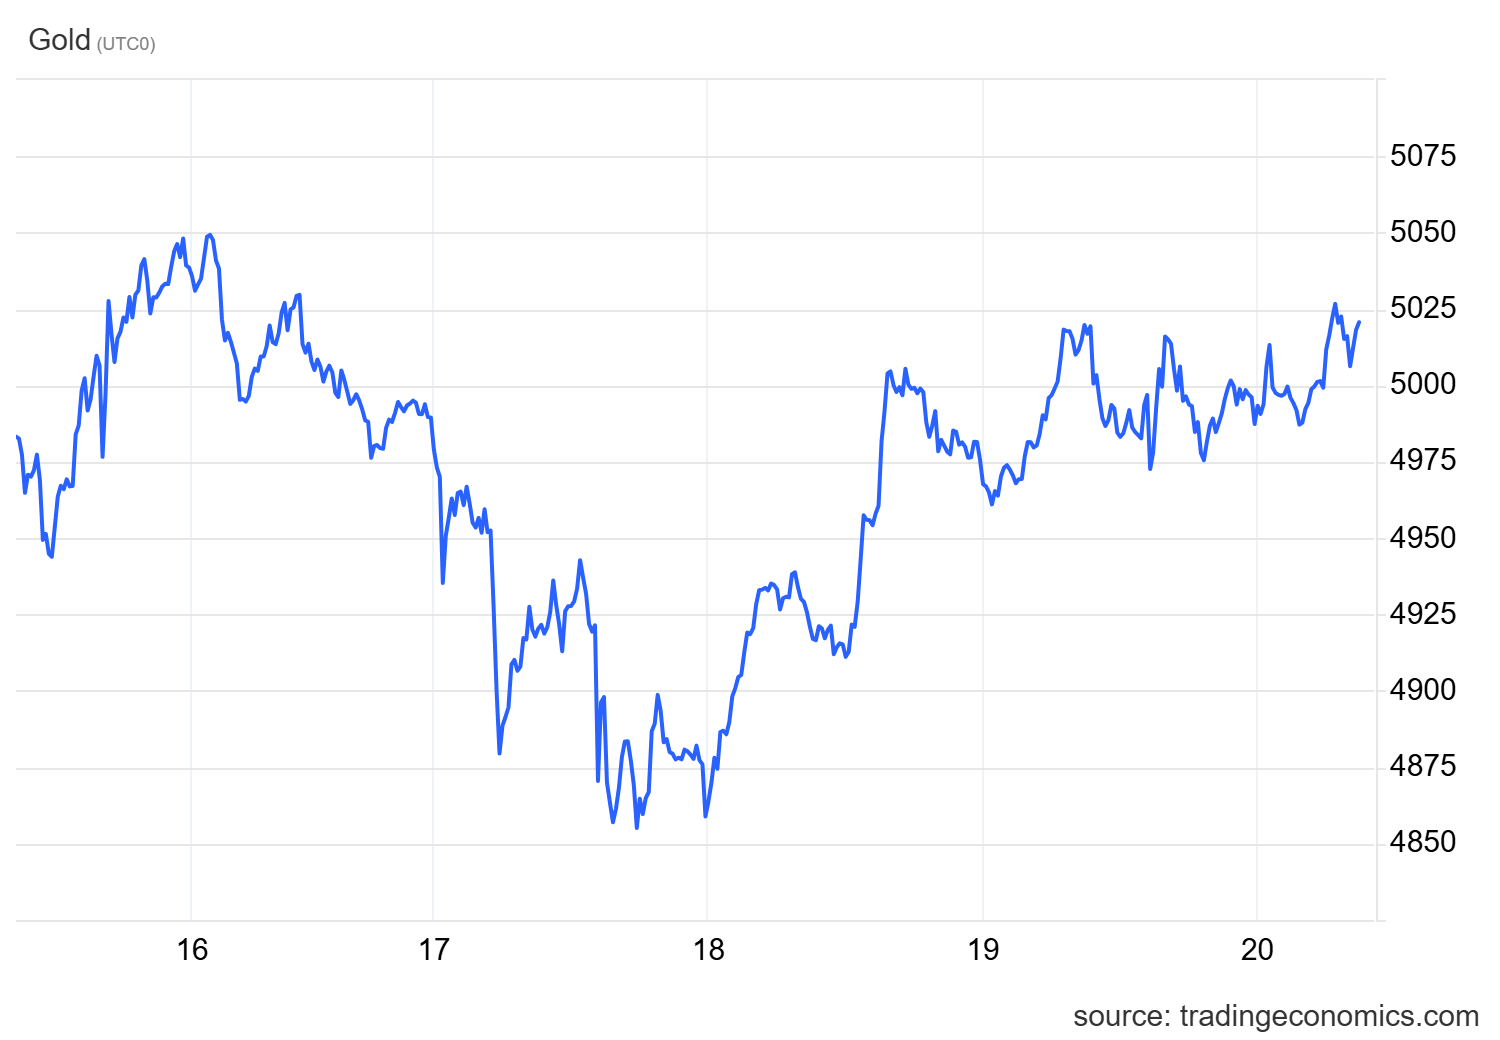
As uncertainty has risen, oil and gold have both risen this week, although only quite modestly:
UK Housing: one other area of interest for UK investors could be the housing market. Land Registry data showed prices for flats and detached properties fell across London and the South East in December. I would guess this suggests problems with demand and affordability, respectively.
Prices elsewhere rose though, so it may be interesting to see what this Friday’s Nationwide House Price index update shows. The UK’s largest lender uses mortgage approval data for its survey rather than completed sales, so is a little more timely than the Land Registry.
Company news
NVIDIA (NSQ:NVDA) is set to report its fourth quarter and full-year earnings on Wednesday week. The world’s largest company by market cap at c.$4.5tn will no doubt make many headlines, but I’m not sure there is much I can contribute to the debate.
However, there are a number of UK companies reporting next week whose prospects we do often consider in the Daily Report, including a FTSE 250 stock that’s a potential casualty of the rapid growth in AI services.
MONY (LON:MONY)
The owner of MoneySuperMarket.com is due to report its 2025 full-year results on Monday.
Shares in this leading price comparison business have suffered badly in the recent AI sell off and are down by 25% in six months:
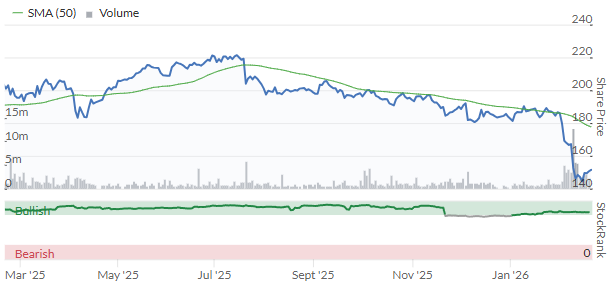
Investors appear to be pricing in a difficult future rather than any immediate new problems. December’s trading update was in line with expectations, so these results shouldn’t contain any serious surprises.
Although earnings expectations have edged lower over the last year, they don’t reflect the market’s gloomy view:
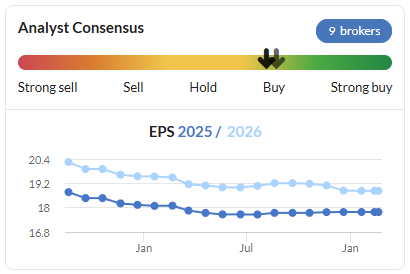
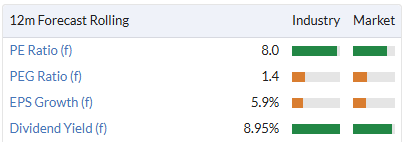
Stable earnings and a sharp fall in the share price has left MONY trading at what might prove to be a bargain valuation:
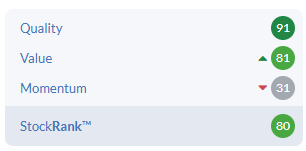
I’m not surprised to see this highly-profitable business classified as a Contrarian stock by our algorithms, with high quality and value ranks:
Comment: I’ve generally been positive on this high-margin, cash-generative business and have considered buying the stock in more recent times. However, I’ve held back over concerns that its best days are past and that future growth potential could be limited.
Although I think it’s too soon to write this business off, I do think it looks like the type of service whose market share could easily be eroded by AI. While MONY has some membership-related revenue and a valuable data bank it can use for B2B services, the majority of its revenue comes from standalone price comparison searches.
I don’t think this is a particularly sticky model. These services aren’t embedded into business workflows or people’s personal finances.
Indeed, companies in this sector have always struggled to differentiate themselves with consumers. This is one reason for the never-ending series of wacky adverts television viewers have endured over the years.
I can’t see this situation improving with AI, but I will be interested to see what kind of story management tells next as they try to assuage investor concerns.
Diageo (LON:DGE)
This week’s interim results will include the first statement from Diageo’s new chief executive Sir Dave Lewis on his plans for the business. Unless the former Tesco CEO uses the occasion to push through another profit warning, I’d imagine Lewis’s comments will be of more interest than the short-term numbers.
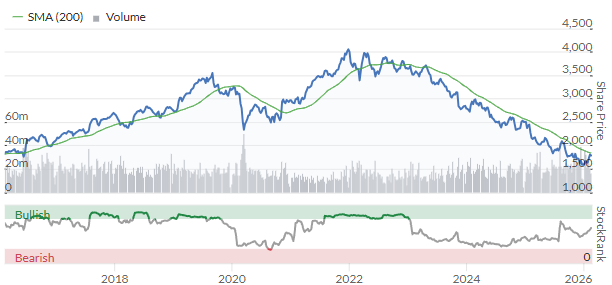
The FTSE 100 drinks giant is currently historically cheap, following a slump in profits and fears that changing fashions and weight-loss drugs will lead to a lasting decline in alcohol consumption.
An FT article (£) this week cites insiders who suggest Lewis is planning “a major shake-up” of the top team at Diageo, suggesting the business may have become “fat and happy”...
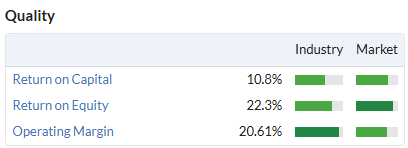
Diageo’s quality metrics are still respectable:
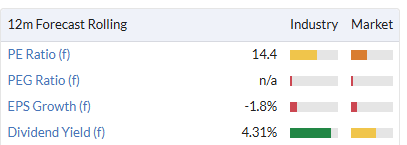
… and I think the valuation could be tempting, if you believe that alcohol is likely to retain its deep-rooted presence in many global cultures:
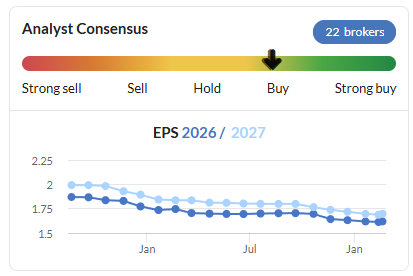
Earnings have trended lower over the last year as previous profit warnings have filtered through:
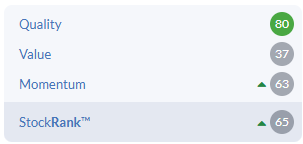
… but the StockRank has risen recently, as share price momentum has improved. This could be a sign of improving value, but might also reflect the investors’ optimism about Lewis’s ability to repeat his Tesco turnaround success:
Lewis has reportedly spent the first six weeks of his tenure criss-crossing the globe and getting to know Diageo’s people and businesses.
Comment: I’m on the fence about alcohol, but my guess is that booze is probably here to stay, even if consumption patterns do evolve. I will be very interested to hear what he has to say this week.
Rolls-Royce Holdings (LON:RR.)
From Diageo we move to another FTSE 100 company with an acclaimed CEO who has already seemingly pulled off a remarkable turnaround.
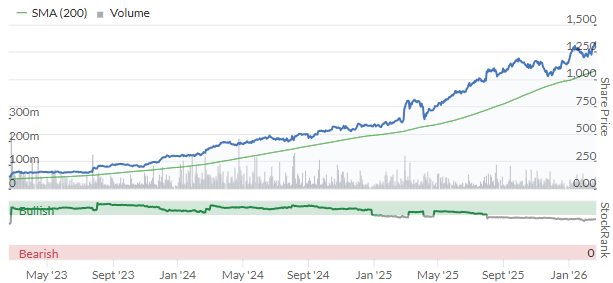
Rolls-Royce shares have risen by more than 1,000% over the last three years under the leadership of Tufan Erginbilgic:
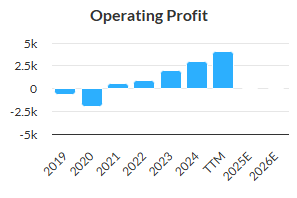
While the recovery in profits has also been impressive, operating profit has only risen fourfold over the same period:
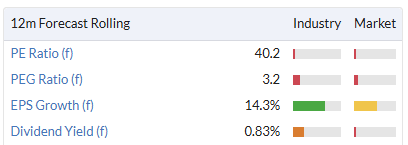
As a result, Rolls-Royce shares now trade on a truly high flying multiple of 40x forecast earnings:
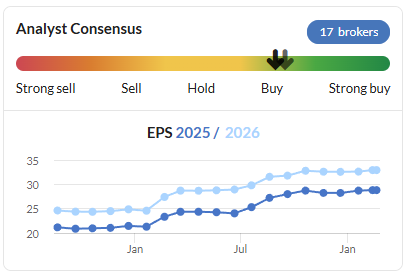
One reason for this has been the engineer’s stunning momentum. Earnings upgrades have been both frequent and substantial over the last 18 months.
2026 earnings forecasts are now 33% higher than they were a year ago:
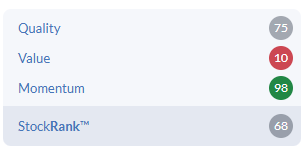
While Rolls-Royce’s High Flyer status is probably well deserved, the company’s low ValueRank is perhaps a warning that any slowdown in momentum could see the shares pause for breath or pull back:
This may not happen for a little longer yet, though.
Comment: Rolls-Royce’s core Civil Aerospace business is enjoying strong demand for large engines. Flying hours reached 109% of 2019 levels during the first 10 months of last year and the company is now moving beyond long-running technical issues with the Trent 1000 engine.
The group’s Defence and Power Systems divisions are also in good shape. Defence demand is described as “robust” and last year’s deal to sell 20 Typhoon jets to Turkey (which I discussed here) will also benefit Rolls-Royce, which supplies the engines.
In Power Systems, data centres have helped to drive strong order intake as the AI construction boom helps drive demand for backup power generators and – in some cases – primary power to allow completion despite long delays on grid connections.
Current guidance from the firm is for free cash flow of £3.1-3.2bn in 2025. That gives the stock a free cash flow yield of just under 3% at current levels, which looks quite full to me.
Although consensus forecasts suggest free cash flow could rise towards £4bn in 2027, that’s still only a FCF yield of around 3.6%. I can’t see much value here without further upgrades. We will have to see what the market’s view is – and if Mr Erginbilgic does upgrade guidance again – when Rolls reports on Thursday.
I hope you enjoy the weekend!
Here’s a summary of what’s expected next week.
Economic Calendar
Date / Time (BST) | Country | Event |
23 February | ||
- | China | Chinese New Year holiday |
09:00 | Germany | IFO Business Climate |
15:00 | US | Factory Orders monthly |
24 February | ||
05:00 | EU | New Car Registrations |
13:15 | US | ADP Employment Change weekly |
14:00 | US | S&P/Case-Shiller Home Price index |
15:00 | US | CB Consumer Confidence |
21:30 | US | API Crude Oil Stocks |
25 February | ||
07:00 | Germany | GDP |
10:00 | EU | Inflation |
15:00 | US | New Home Sales |
15:30 | US | EIA Crude Oil & Gasoline Stocks change |
26 February | ||
13:30 | US | Initial Jobless Claims |
13:30 | US | Durable Goods Orders |
27 February | ||
00:01 | UK | GfK Consumer Confidence |
07:00 | UK | Nationwide House Price Index |
13:00 | Germany | Inflation |
13:30 | US | Producers Price Index (PPI) |
18:00 | US | Baker Hughes Rig Count |
Companies Reporting
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

2 comments
Is there some sense in LSEG having a stock split to enhance liquidity? They could conduct their very own experiment!
The link for this report is not showing on the Today page.