The Week Ahead (28 Sept - 2 Oct): big picture bond yields, Likewise, JD Wetherspoon & Nike

Welcome back to The Week Ahead.
In the years after the 2008 financial crisis, UK bank stocks often looked temptingly cheap, but their results (and share price performance) kept on disappointing.
At the time, I remember reading commentary from an experienced investor who noted that the banking crisis had taken a decade to build and would probably take a decade to unwind.
This turned out to be broadly correct and was a useful lesson for me on the importance of a long-term perspective:
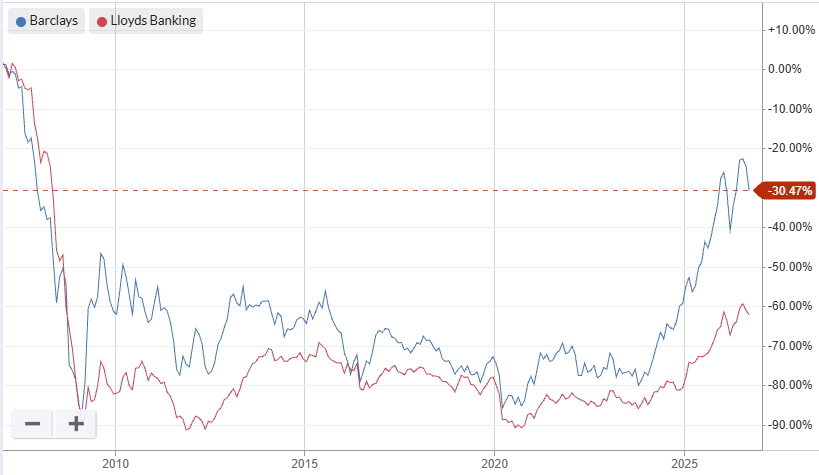
Of course, one factor behind the banks’ eventual recovery was the return to more normal interest rates, after a decade of near-zero rates.
Interest rates – and their close cousins, government bond yields – have been the topic of many newspaper column inches recently. The suggestion often seems to be that bond yields are soaring to historically high levels:
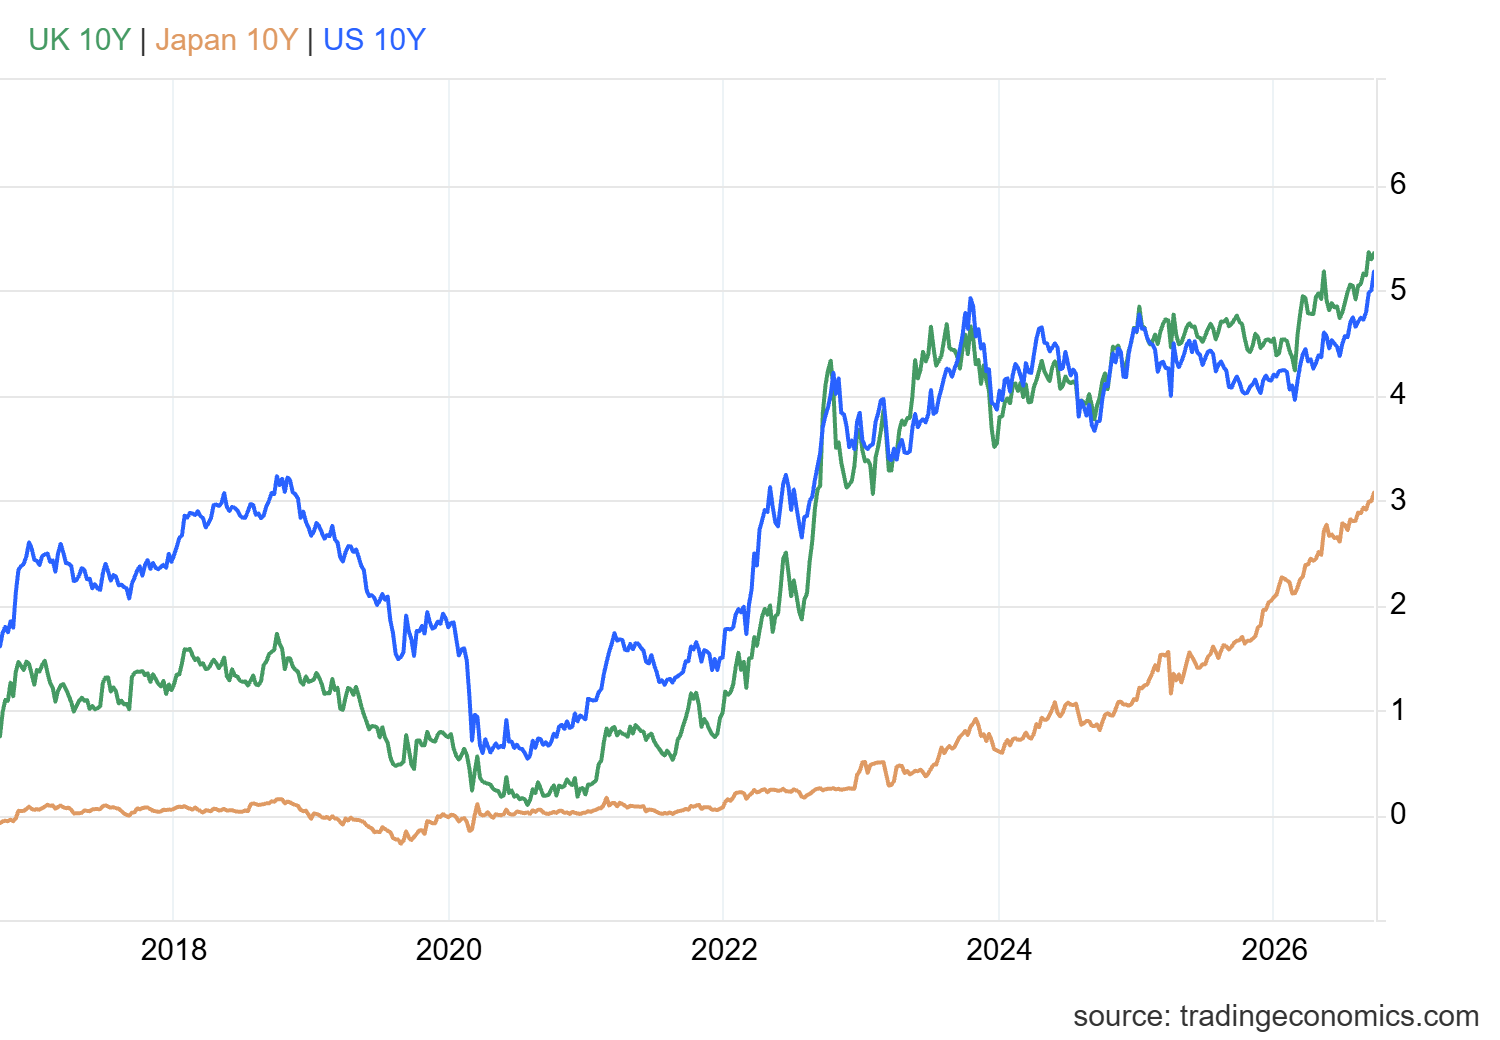
That’s true on a 10-year horizon, but taking a broader view suggests that rates are well within historical norms. While government borrowing levels in the UK and elsewhere may indeed be a concern, I wonder if what we’re seeing in yields is simply the final stage of post-2008 normalisation.
Using the Bank of England base rate as an approximate proxy for long-term bond yields suggests that the current situation is in line with pre-2008 norms:
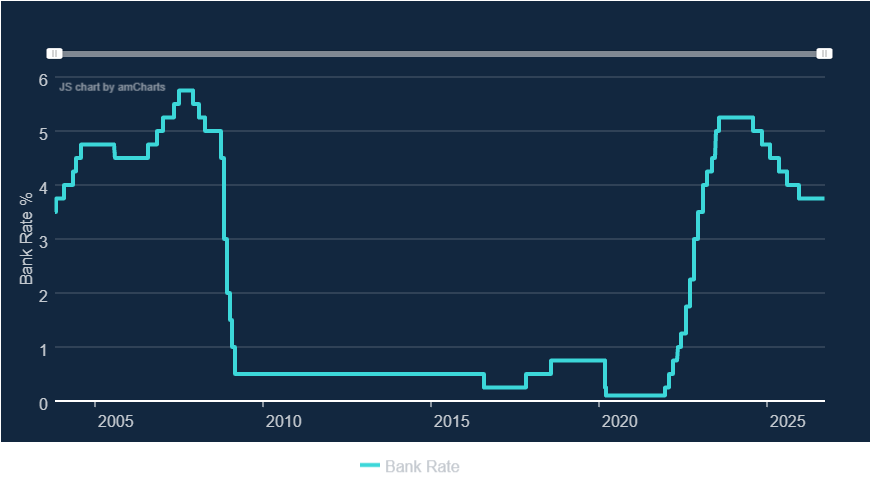
Source: Bank of England
Indeed, official BoE bank rate data stretching back to 1694 suggests that borrowing costs have been at similar levels for most of the last three hundred years:
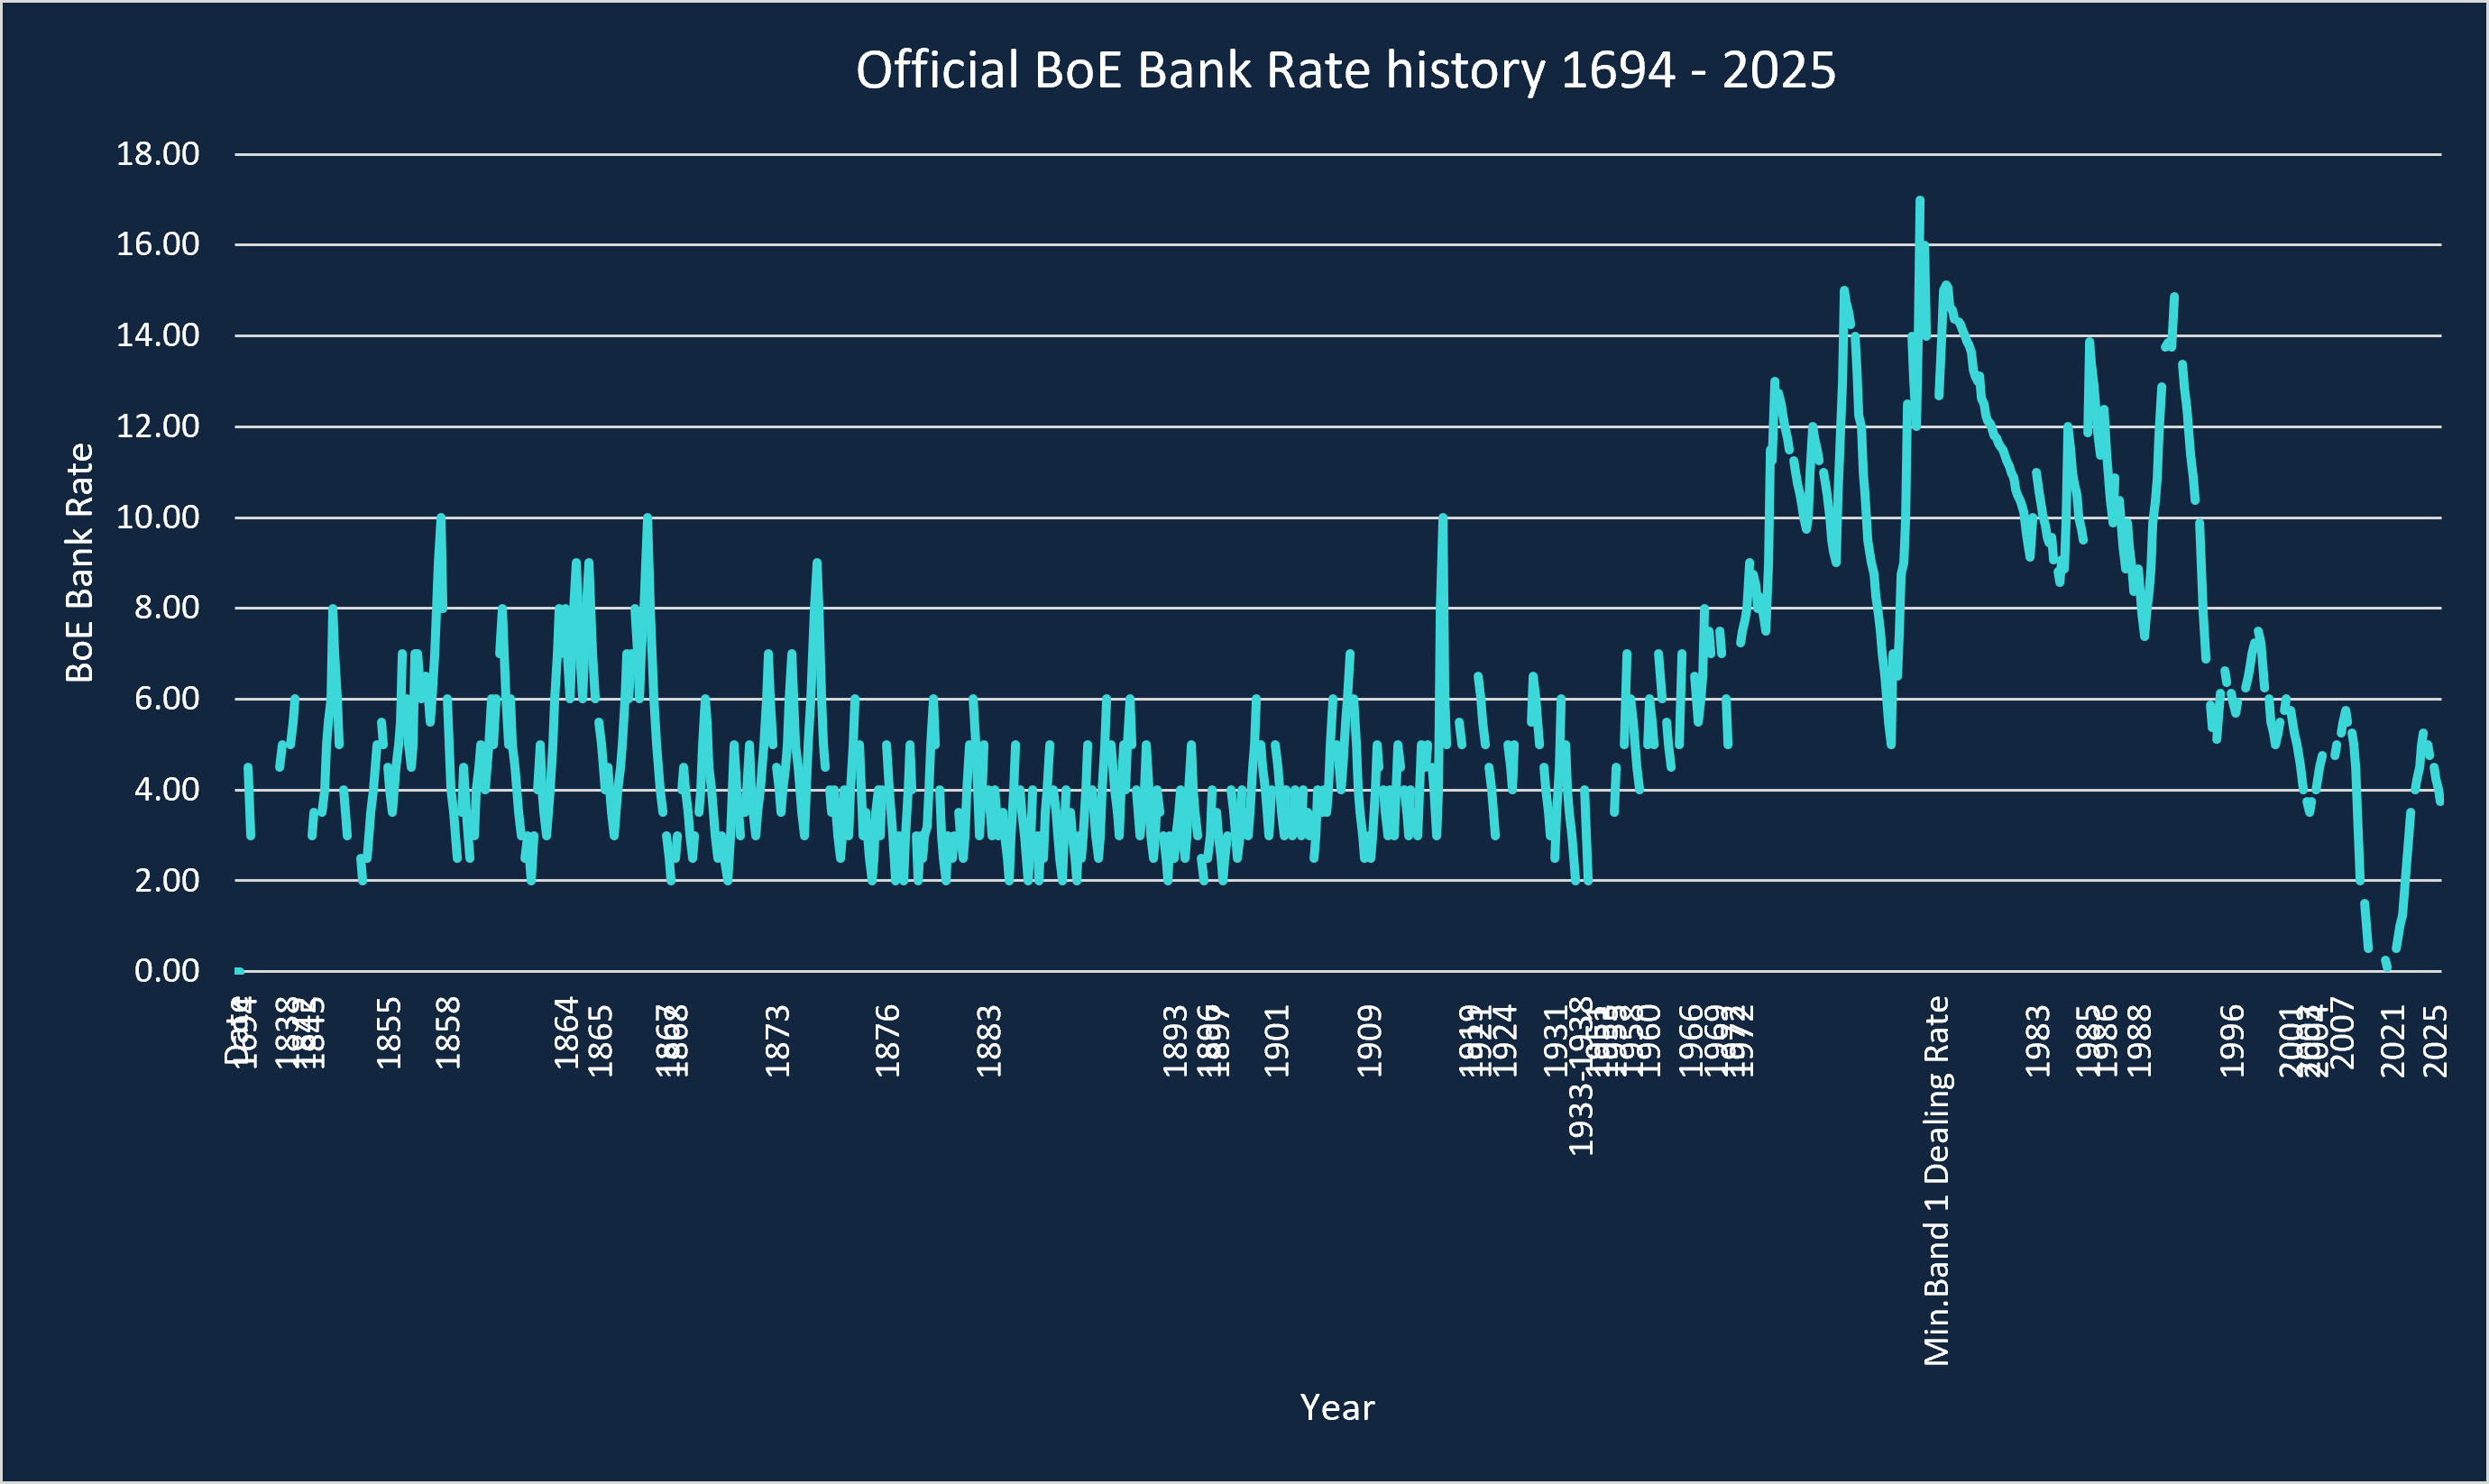
Source: Bank of England
In my view, it’s probably a sensible working assumption to assume that governments, businesses and consumers need to adapt to current borrowing costs.
The process of adjustment may prove to be painful, which is one reason why I am more keen than ever on owning shares in companies with net cash. I have to confess to a certain geekish pleasure in seeing some of my companies report pre-tax profit that’s higher than operating profit, due to the benefit of interest income!
Economic news
Higher bond yields are pushing up fixed mortgage rates for UK homeowners seeking new deals. Next week we’ll see if this is having any early impact on house prices or transaction volumes. The Bank of England publishes the latest mortgage data on Tuesday, while Nationwide updates its House Price Index on Wednesday.
Across the Atlantic, US homeowners do things differently and often secure 30-year fixed rate mortgages. The headline 30-year rate is now hovering around 7%, so next week’s update could grab headlines, as it’s done this week.
US job numbers may also be of interest, but the data points that are most likely to be of interest are the price of oil, gasoline and especially diesel. The latter is currently at long-term highs in the US, causing pain for the influential farming lobby (and others).
Rumours are swirling about the possibility of a US export ban on diesel, but the way refineries work suggests to me that this could have some undesirable knock-on effects. There’s no schedule for this, but any news on Hormuz shipping or US refinery exports could move markets.
Company news
It’s the end of the third quarter next week, which means there will be a rush of small and mid-sized companies publishing results on Tuesday and Wednesday (the final day of the month).
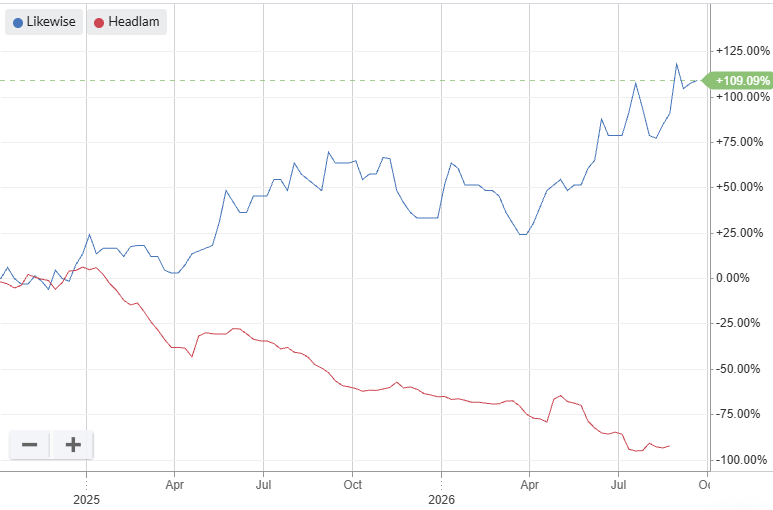
Of likely interest for UK private investors will be the latest numbers from highly-rated flooring distributor, Likewise (LON:LIKE). This business is led by CEO Tony Brewer. He was previously very successful at Headlam (LON:HEAD), but his current venture now appears to be profiting from Headlam’s failure:
Flooring sales are suffering from weaker housing market activity, but Likewise’s success makes it clear that there is still some demand out there. For a different take on flooring, leading vinyl flooring manufacturer James Halstead (LON:JHD) will report its full-year results on Thursday.
Housing is a headwind for another of next week’s reportees: building supplies firm Lords Trading (LON:LORD) will share its half-year results on Wednesday.
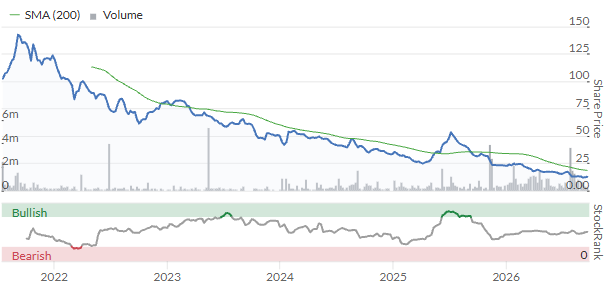
Lord’s share price has fallen by nearly 90% since its 2021 IPO as its profits have withered. The last 12 months have seen a series of profit warnings, leading Mark cut our view to RED in July due to debt concerns.
Other results of interest during the first half of the week are likely to include Card Factory (LON:CARD), specialist lender S&U (LON:SUS) and soft drinks firm A.G. Barr (LON:BAG). All of these may provide some insight into the health of the UK consumer.
Although the latter part of the week is expected to be much quieter, one honourable exception will be pub group J D Wetherspoon (LON:JDW), which is due to report full-year results on Friday 2 October. Founder Tim Martin’s comments on the health of the UK consumer and the wisdom (or not) of government policy may make interesting reading on Friday.
Finally, JD Sports Fashion (LON:JD.) shareholders may want to check out the latest results from NIKE (NYQ:NKE) on Thursday. 40% of JD’s sales come from this leading US sportswear brand, which is going through a protracted turnaround.
Have a good weekend!
Here’s a summary of what’s expected next week.
Economic Calendar
Date / Time (BST) | Country | Event |
28 Sept | ||
Nothing of note. | ||
29 Sept | ||
09:30 | UK | Mortgage Approvals |
15:00 | US | Job Opening and Labor Turnover Survey (JOLTS) job openings |
21:30 | US | API Crude Oil Stocks |
30 Sept | ||
02:30 | China | NBS Manufacturing PMI |
07:00 | UK | Nationwide House Price Index |
08:55 | Germany | Unemployment |
12:00 | US | MBA 30-Year Mortgage Rate |
13:30 | US | GDP Growth |
13:30 | US | Personal Income |
15:30 | US | EIA Crude Oil Stocks |
1 Oct | ||
09:30 | UK | Manufacturing PMI |
10:00 | EU | Unemployment |
13:30 | US | Initial Jobless Claims |
15:00 | US | ISM Manufacturing PMI |
2 Oct | ||
10:00 | EU | Inflation |
13:30 | US | Non Farm Payrolls |
13:30 | US | Unemployment |
15:00 | US | Factory Orders |
18:00 | US | Baker Hughes Oil Rig Count |
Companies Reporting
Date | UK Trading Updates and AGMS | UK Financial Results | International Financial Results |
Monday 28 Sept | Edx Medical (LON:EDX) Renalytix (LON:RENX) | Christie (LON:CTG) Likewise (LON:LIKE) Redcentric (LON:RCN) Tullow Oil (LON:TLW) | Vail Resorts (NYQ:MTN) |
Tuesday 29 Sept | Eden Research (LON:EDEN) Knights group (LON:KGH) Patrizia SE (ETR:PAT) Thalia Therapeutics (LON:THAT) Tungsten West (LON:TUN) XP Factory (LON:XPF) ZIGUP (LON:ZIG) Zoo Digital (LON:ZOO) | Airea (LON:AIEA) A.G. Barr (LON:BAG) Card Factory (LON:CARD) Ebiquity (LON:EBQ) Made Tech (LON:MTEC) S&U (LON:SUS) Venture Life (LON:VLG) | Clean Air Metals (CVE:AIR) Carnival (NYQ:CCL) Carmax (NYQ:KMX) |
Wednesday 30 Sept | Activeops (LON:AOM) Aminex (LON:AEX) DSW Capital (LON:DSW) Great Southern Copper (LON:GSCU) Greggs (LON:GRG) Proservice Building Services Marketplace (LON:PRO) Windar Photonics (LON:WPHO) | Aoti (LON:AOTI) Avation (LON:AVAP) Lords Trading (LON:LORD) NAHL (LON:NAH) Northcoders (LON:CODE) Novacyt SA (LON:NCYT) Pinewood Technologies (LON:PINE) Real Estate Investors (LON:RLE) Saga (LON:SAGA) Skillcast (LON:SKL) | Conagra Brands (NYQ:CAG) FactSet Research Systems (NYQ:FDS) Jabil (NYQ:JBL) Jefferies Financial (NYQ:JEF) Micron Technology (NSQ:MU) |
Thursday 1 Oct | PZ Cussons (LON:PZC) | James Halstead (LON:JHD) | NIKE (NYQ:NKE) Constellation Brands (NYQ:STZ) McCormick & Company, Incorporated (NYQ:MKC) Acuity (NYQ:AYI) |
Friday 2 Oct | Capital Metals (LON:CMET) | J D Wetherspoon (LON:JDW) | Nothing of note. |
Disclosure: at the time of publication, Roland owned shares in James Halstead.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

26 comments
Hi Roland, nice summary as always.
Would add Avingtrans (LON:AVG) to your list. Prelims due on Wednesday
James Halstead (LON:JHD) results delayed due to the auditors needing more time.
Great overview and shares much of my own thinking. I get frustrated when many commentators today say `Interest rates are high`. Its fundamentally untrue against history and the judgement is made only against `recent` history where interests rates were near zero. I suspect many who write these comments are 40 or younger who, sadly, have no recount of the interest highs pre 2000 and when I got crushed owning a first house. That time period set the whole picture for my future saving and investing, to ensure I could stand on my own two feet financially and be self-dependent, and in hind sight was what allowed me to build the assets and way of life I have today. High interest rates I would argue encourage all of us to stay prudent, appreciate what we have and realise we need to build for the future. Having free money means we appreciate nothing and think every day is a free lunch!
Card Factory (LON:CARD) hoping for decent results this week , in my view this looks too cheap. Decent divi, decent profit , low debt (excluding leases and recently acquiring on line business from WHSmiths
Hi Roland
Thanks for the update. I expected a quarter point rise in BOE base rate this month but was wrong. Hard to see given all that is coming to the rate of inflation etc did not provoke this. Not many will predict an unchanged rate at the next announcement. Being a cycnic one could argue that Mr Burnham's new help to buy scheme needed to not be unveiled against a too obvious background of rising mortgage rates. Interested to note the reaction of housebuilders etc on Monday. I note also the new building safety levy applies from 1st October so a further cost implication for housebuilders and particularly those in the London area where it is steepest....
I see Vistry (LON:VTY) and Crest Nicholson Holdings (LON:CRST) are amongst the most shorted stocks on LSE with materials providers Ibstock (LON:IBST) and Breedon (LON:BREE) also featuring
Much appreciated Roland.
I totally agree with what you are saying about the current rising interest rate environment and markets always find ways to adjust.
However, the problem is far deeper this time. By the time Trump leaves office, approximately 42 cents of every dollar collected by the US government will go straight to the bondholders. These are personal but accurate calculations.
We are only a couple of years away from a major financial crisis and a long and deep recession. The markets will adjust much earlier, probably after the midterms or sometime in the first half of next year.
US markets are flooded every week with all these new bond issues and it is crystal clear that prime bond dealers (that have to buy these bonds) are bidding lower and lower and will continue to do so.
All the best
Hello Yiannos,
Interesting point, and I tend to agree. Maybe it's just the fear element of my brain, but I am fearing a lost decade of such in American markets, perhaps in the next 2/3 years. And one is due,looking at history.
So as investors, what do we do? Carry-on as normal, or look to be a bit more proactive, as bond/ISA rates are currently very appealing to take some risk off.
Following a great four year run in the US market, I have begun shifting funds back home into the UK market.
My two big clients have sold everything over the pond and will started investing some of their money in the UK stock market. Most of it has already gone into university students rental properties.
My personal portfolio will be divided evenly.
Finding good stock picks in the U.S. market feels a lot harder now than it did a few years ago. My US portfolio is currently 2/3 cash and will reassess the situation after midterms/early new year.
Remember that in early 2027 a new US debt has to be discussed and raised. With the House and probably the Senate back to democrats, this will lead us to another long government shutdown. By that I mean longer than ever before!
Some very good UK stock market opportunities at the moment.
Obviously DYOR.
All the best
Thank you Yiannos1; your wise words/ observations are always much appreciated. KB.
Hi Yiannos
I posted a similar comment a little while back in that I see the yawning budget deficit in US finally becoming of more concern that the latest issues with AI invasion. I see Anthropic float being a possible ' top of the market event' OK maybe this is too specific but the way Trump spends money on fights he should avoid just carries a ' cows coming home' analogy
I pity the next President of what ever colour as the economic mess left by Trump's ignorant profligacy will surely be a major headache
Been 100% equities last decade, but now approaching 50, i am having thoughts to reduce risk...retirement is possible at 53/57
Hi But what would you do with your time if you retired at 53?
Anything I liked, that's the beauty of it
Agreed I almost think the democrats would be best trying not to win the next election i truly think if Trump is left to his current devices the Republicans won't get in again for a generation, but agree with you whoever comes next is going to be handed a massive poison chalice.
I have Topps Tiles (LON:TPT) down as trading update on Thur 1 Oct
Currently yielding >8.5% with potential for budget boost
Topps Tiles (LON:TPT)
Currently yielding >8.5% with potential for budget boost
yes but how sustainable is that level of dividend - its this possibly a value trap?
by my calcs that yield is higher trhan net profit expected this year - thats against backdrop of eanings expectations being decimated the last 18 months or so with no sign of trend down tuning upwards.
The only oddity to me is how they current expect the year starting 1st October will be so much better than the yeasr just about to finish bearing in mind they expect sales to go up by less than the rate of inflation.
last year they had 6p eps factored in for 2027 - year about to finish they wiooll be lucky if they hit 2.5p.
They wont have done much wrong either - those decreases will likley be due to rates increases and staff NI increases and other costs going up above inflation.
are they really in a strong position to control costs so they rise slowerr than sales ? or are they stuck with their lot that shareholdsers get 2p in the pound of sales - if they are lucky.
If i was a betting man i wouldnt be betting that at best they will be on track ref 2027 - with material chance dividend may need chopped - or their expectation that eps will magically grown 44% from next month compared to this is taken away before the year starts or soon after.
Note i havent really dug into the business details - i kinda like the company so perhaps their recent acquisition will help deliver recovery next year - so perhaps they have already put steps in place to make things better - anwway we wil find out soon if 2027 expectations per stocky will last the week out.
Thanks Roland, I find these summaries very useful.
One addition - I believe Avingtrans (LON:AVG) report on Wednesday (30th).
Water Intelligence (LON:WATR) also report HY earnings on Monday next week. Hoping to see a reduction in amortisation so some of their FCF ends up on the bottom line. I hold.
This is a friendly response so please do not take this the wrong way.
Most companies report on adjusted basis and Water Intelligence (LON:WATR) is one of them.
Water Intelligence (LON:WATR) even reports on statutory basis.
What you have posted is wrong and this is not the way financial statements interact (connect) with each other.
Amortisation is a non cash expense and remember that net income is the beginning of the FCF statement (already subtracted and added back).
Net income might look higher but FCF will look exactly the same as a smaller amortisation amount will be added back.
Happy to explain it in more detail if needed by dropping me a DM on X @OptionsFlowBoss.
All the best
Thank you for the explanation. You are correct.
What I should have said was that the high acquisition-related amortisation depresses reported profit but is reversed for cash flow, so atm FCF > profit. If the amortisation decreases (no new franchise purchases) then the difference between the 2 will reduce.
You have my utmost respect!
This place can be so much better and beneficial to subscribers if we ALL acknowledge that we are not always correct. The big problem is that investors/commentators get angry, defensive, even aggressive when you criticise their views/holdings, even if the numbers prove it.
Four decades in this fascinating world of investing, I am the first one to admit that mistakes will always be made. The biggest mistake is to believe and insist that your original mistake is correct, even if the market says otherwise.
The only mistake that the stock market does not forgive is the money management one. Learn to manage the portfolio first and the successful stock picking process will come along……..
All the best
Why is the "Thumbs Up" at the top rather than where it used to be, below the text? Isn't below more logical? Maybe that's why there are currently only 10 thumbs from 218 reads.
Thanks for pointing this out. I thought it was a glitch. Don't think anyone finding it ATM.
I'm going back up just to make that tick, I'd been wondering wher that box was as this such a good post of Roland's.
On Monday, I'm also expecting to see interims from Spectra Systems (LON:SPSY) they were published on the last Monday in September 2025 so unless there has been a hitch it should be the same this year. Profit and dividend for the year are forecast significantly lower after an exceptional 2025 so it will be interesting to see if those forecasts are confirmed at the interim stage. I am slightly wishing I had sold earlier in the year... but it remains a well-run company with interesting capabilities, in my view (I hold).
Anecdote - I am not long back from the Netherlands where I paid Euro 2.58 per litre to fill up with diesel, so about £2.22. That must be hurting the hauliers and farmers there.
I also hold Spectra Systems (LON:SPSY) any forward looking statement will be more important than backward looking figures. Currently priced for the big drop in revenue so any improvement could get a positive reaction.