TPXimpact sees H1 revenue up 60%, but guidance suggests a weaker H2, we moderate our view

Analyst’s view:
Today's half-year results are clearly very strong, but broker forecasts have been trimmed slightly today and today's unchanged management guidance suggests profits will be significantly lower in H2. I don't see any serious problems here, but I think it makes sense to moderate our view slightly after such a strong run this year.
Down 6% to 101p (£96m) - Interim Results
By any standards, today's half-year numbers from public sector digitalisation specialist TPXimpact look pretty strong:
Revenue up 60% to £57.9m
New business wins of £86m (H1 26: £31m)
Adjusted EBITDA margin increased to 13.9% (H1 26: 8.8%)
Reported operating profit of £3.5m (H1 26: loss of £1.1m)
Adj Earnings per Share of 5.6p (H1 26: 1.7p)
Net cash of £1.0m, with all debt fully repaid
This improved financial performance is reflected in the scale of recent wins and underlying business growth:
UK central government wins including Ministry of Justice (£1m), Land Registry (£19m) and the Prison & Probation Service (£25m)
Total headcount including associates up 15% to 806
Permanent headcount up 22% to 508
Employee retention improved to 86% (FY26: 83%)
This all sounds pretty rosy - so why has the company's share price fallen this morning?
As ever, I think the main reason for this lies in the outlook - broker forecasts have been trimmed today and guidance suggests profits will be significantly lower in H2.
Outlook & Broker Estimates
Management has reiterated its previous guidance from 15 October 26:
FY27 revenue of at least £105m
FY27 adj EBITDA of at least £14m
TPXimpact has upgraded guidance repeatedly over the last six months. Investors may have been expecting another such increase (even though it's frankly unlikely, coming less than a month after the previous upgrade):
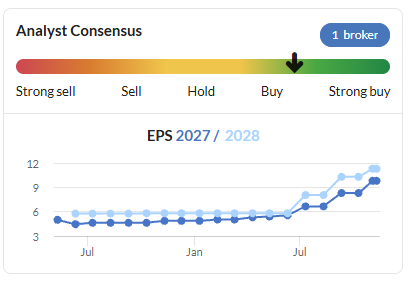
With thanks to the company's broker, Cavendish, we have updated forecasts today. Unfortunately, it appears that this may be a slight profit warning:
FY27E adj EPS: 9.5p (-3.1% versus 9.8p previously)
FY28E adj EPS: 10.9p (-3.5% versus 11.3p previously)
Cavendish says the reduction to FY27 forecasts reflects "increased dilution". My reading of this is that it's a consequence of the increase in share-based payments, which rose from £813k to £1.4m in H1 and will presumably rise further for the full year.
Higher variable remuneration is presumably a reflection of the group's increased size and profitability. The fact that TPXimpact is making these payments with shares mean cash flow is unaffected. Instead, shareholders are diluted - there's no such thing as a free lunch.
Roland's view
Despite today's slight downgrade, the forward valuation continues to look fairly modest, with a P/E of around 10x forward earnings.
However, today's forecasts suggest that earnings will be lower in H2, with a c.60/40 split implied by current consensus forecasts.
The shares have four-bagged this year and we've previously been GREEN on this stock, which Mark also covered in a Stock Pitch last month.
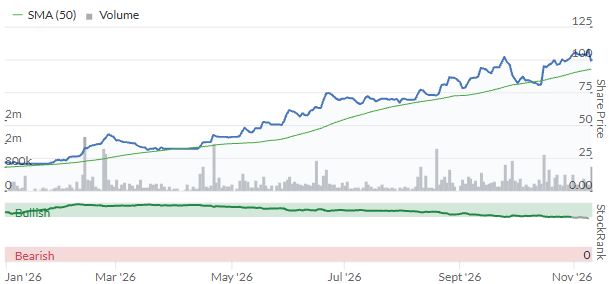
However, I think the prospect of lower H2 earnings and today's slight downgrade to forecasts could put pressure on the company's High Flyer styling.
I'd also point out that the StockRanks have already been pricing in a more measured outlook, drifting steadily lower in recent weeks (see chart above).
On balance, I think it makes sense to moderate our view slightly, while remaining positive. AMBER/GREEN.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Tpximpact Holdings (7)
Comments here are also visible in the Daily Stock Market Report
Today’s H1 results from Tpximpact Holdings (LON:TPX) slightly beat last month’s trading update, the fourth EBITDA beat or upgrade this year. Together with repeated contract wins, that has more than quadrupled the shares. Yet the market still can’t quite believe it: TPX trades on about 11x this year’s forecast earnings and under 10x next year’s.
Given that record, unchanged FY27 guidance looks conservative. It implies H2 revenue nearly a fifth below H1, and doubling H1’s 5.6p adjusted EPS already beats this year’s consensus. Cavendish suggests TPX is “well-placed for further upgrades”. I hold.
iwright7 thank you! I bought Tpximpact Holdings (LON:TPX) following your comments in mid February 2026. I should have bought more but have done very well. Your input is greatly appreciated
Sandstone – good that you were able to take advantage. Tpximpact Holdings (LON:TPX) has been my best-performing share this year.
I first bought in early January, after a whopping +42% jump on its H1 results in December 2025. It just goes to show it’s best not to be afraid of buying after a big rise if you think the shares are still too cheap.
Well I've added Tpximpact Holdings (LON:TPX) this morning.
Big riser but numbers still justify to my eye
And down it goes 5%!!!
Yep 8% at one point. Still struggling now, unfathomable
Dialight (LON:DIA) . Sorry Ed and for the sake of consistency I had to pick you up on this.