Trifast: a Smart Money turnaround

Source: Trifast
Last week, Alex took a look at How Smart Money Targets Turnarounds through the lens of stocks held by the Rockwood Strategic (LON:RKW) investment trust. I’d recommend taking a look if you haven’t already, as it’s full of interesting data-driven insights.
In this week’s Stock Pitch I’m going to follow up on this with a look at one of Rockwood’s larger holdings, Trifast (LON:TRI). The industrial fastenings group was a top 10 holding for Rockwood at the end of 2025, accounting for 4.4% of the trust’s net asset value.
Harwood Capital (Rockwood Strategic’s investment manager) is currently Trifast’s largest shareholder, at over 16%:
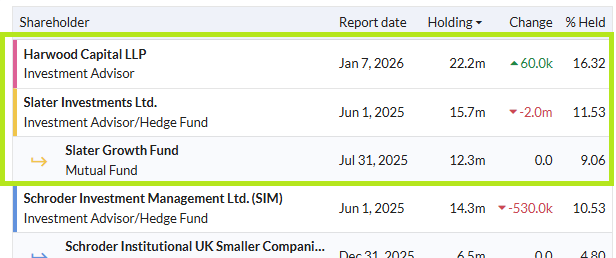
Coincidentally, Trifast’s second-largest shareholder is Slater Investments – another well-regarded UK active fund manager. I’ll be covering Slater Investments in more detail next week, so look out for that piece.
The Pitch
Trifast’s product portfolio contains more than 50,000 items, mostly small fastenings such as screws and bolts that are needed by the company’s industrial customers. It’s undeniably a cyclical business, but ultimately I think this is where the opportunity lies.
The company is currently in the middle of a transformation plan aimed at delivering improved profitability and shaping the business for future growth. Management has put in place medium-term targets for a 10% operating margin and 12%+ return on capital employed.
Hitting these targets could see profits double, even with minimal sales growth. In such a scenario, I believe Trifast shares would justify a significantly higher valuation, as it has done during past growth cycles.
The Big Picture
Trifast’s niche focus and global reach means it’s a key supplier to many much larger customers. The group’s focus on improvement and consistency is already delivering results, with value starting to emerge:
Margin progression: the group’s adjusted operating margin rose from 5.1% in FY24 to 6.7% in FY25. Broker forecasts for FY26 were reiterated this week and suggest this figure could rise to 7.5% for the year ending 31 March.
Global growth exposure: Trifast’s operations stretch across the UK, Europe, Asia and North America. In total the group is active in c.65 countries. It operates as a full-service provider to OEMs and Tier 1 manufacturers in sectors such as Automotive, Smart Infrastructure (including data centres) and Medical Equipment.
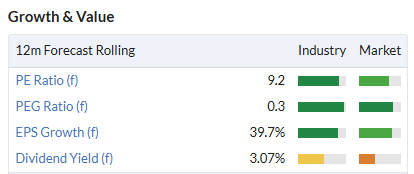
Value opportunity: the shares currently trade on a FY27 forecast P/E of 9 and at a 15% discount to book value. Fans of GARP (growth at a reasonable price) investing may also be interested to note the stock’s PEG ratio of 0.3 – well below the 1.0x threshold commonly seen as good value.
What The Brokers Say
Consensus earnings forecasts have been stable since last summer’s profit warning:
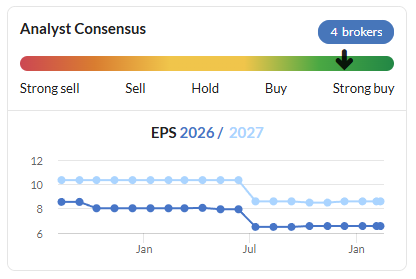
Four brokers covering Trifast have an average target price of 126.7p, 56% above the current share price;
The current financial year ends on 31 March, so I would hope that forecasts for FY26 are reasonably secure at this point;
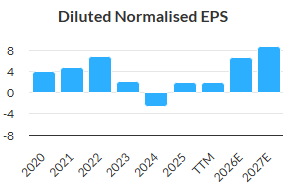
FY27 estimates suggest earnings could climb by 30% to 8.6p per share. This potentially leaves Trifast trading on just nine times next year’s forecast earnings.
The Bear Case
As with all turnarounds, there’s a risk that Trifast simply won’t turn. In my view, the key risks lie in the following areas:
Automotive exposure: the group’s UK division is its largest, but also the lowest margin. Management commentary has suggested this is mainly due to weak conditions in the UK automotive sector. While a recovery in demand could drive a rapid improvement in margins, there’s also a risk that geopolitical conditions and the technological shift to EVs (many from China) will mean that the UK automotive sector remains a drag on the group’s profitability.
Lack of pricing power? Trifast is a key supplier to many of its customers, but it’s not without competitors and its products are often individually of low value. Key customers may be able to drive a hard bargain to secure big contracts, potentially limiting Trifast’s pricing power and margins.
Capital-intensive & Cyclical: even at past peaks, returns on capital have only reached mid-double digits. Ultimately, this is a capital-intensive manufacturer with a fairly large fixed cost base. Shareholder returns may be limited by this reality and it seems likely to me that good timing will be required when buying and selling the stock.
The Bottom Line
Trifast is a niche manufacturer with significant capabilities in its core industrial fastenings market. It operates in sectors and geographic markets which I believe have considerable long-term growth potential, albeit they also tend to have strong cyclical characteristics.
Recent weakness – particularly in the automotive sector – has contributed to a major downturn in profit. A transformation programme is underway to improve efficiency and position the business for future growth. The impact of this is already feeding through to the bottom line, with significant further progress expected over the coming year:
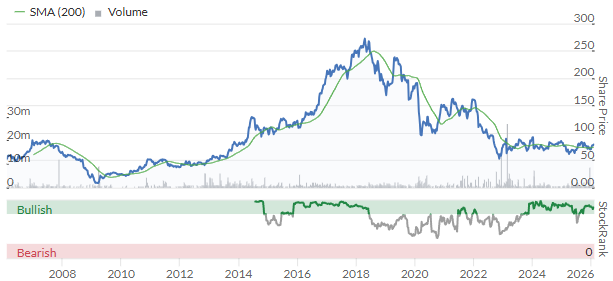
Despite these early signs of progress, the shares remain at a 12-year low. I believe this highlights the potential for significant gains if improving profitability can be paired with modest revenue growth:
In conclusion, Trifast is a modestly valued, specialist manufacturer with attractive scale and a 50-year track record.
While it’s always likely to remain a relatively low-margin, cyclical business, I think the shares may currently offer investors the opportunity to benefit from a cyclical upturn and material re-rating.
Disclosure: At the time of publication, Roland does not have a position in Trifast.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

7 comments
Christopher Mills' Harwood have a significant stake in Trifast, and watching a Youtube podcast with them it is one of their to picks for 26.
they seem to think TRI have been unduly punished following the US tariffs
Being rather naïve and fairly new to investing, can I ask why the chart shows a very spikey share price movement - for a company that makes fastenings? Happy to have it explained like I am a small child, really.
I’ve not looked into this but I would have thought that China is holding an oversupply of steel nuts and bolts looking for markets outside of their old USA customers.
I think whilst investors remain focussed on AI this type of opportunity will remain mute. But as investors we all know focus changes and it will be timing that which will get the returns along with the company delivering on its promises. So for me not quite there yet but definately a future opportunity.
Be interested to see your take on ' well regarded' Slater - Yes, they were well regarded, but the Fund performance has been dire in recent years as Ive commented here before.
Did it not have a huge stake in HUTCHMED (China) (LON:HCM) ?
Indeed it did