Why quality and value can be a magic formula for bargain hunters

Joel Greenblatt, the prominent US fund manager, once wrote that “buying cheap stocks at bargain prices is the secret to making lots of money”. Part of the challenge however, as Greenblatt noted, is that value investing doesn’t work all the time. Indeed, over the past two years, some of the value strategies tracked by Stockopedia have had a rough ride. But we’ve seen some changes in that trend in 2016, with Greenblatt’s Magic Formula strategy putting in a strong performance in the UK, Europe and the US.
To understand this performance, it’s worth exploring some of the factors that drive value strategies - and why hardened value hunters are prepared to ride out periods of underperformance in the expectation of stellar returns.
What really makes a value stock?
Value strategies come in a variety flavours, but they all share a focus on stocks that are priced cheaply against either what they earn or what they own.
Take for example, the classic value investing style of the late Ben Graham and modern day hedge fund guru, Seth Klarman. Their focus digs deep for stocks that trade at prices well below their intrinsic value. These are the companies hated most by the investing herd. They’re potentially broken or at the bottom of the business cycle, and very few can stomach buying them. But they are also the stocks that value investors believe are mispriced and will rebound in time.
A similar approach is used by Nick Kirrage, who runs the Schroder Recovery Fund. As he puts it: “Value outperforms over time, and when it doesn’t I think a lot of the skill in the job is psychological. It’s about learning not to drive yourself crazy or fall apart on bad performance. Over time you have a strategy that outperforms, but you also know that you’ll struggle with it.”
Another challenge of hunting down ‘absolute’ value is that the pool of potential targets dries up quickly in bullish conditions (when a rising tide floats the valuations of many stocks). At times like these, growth strategies often dominate, leaving value investors on the sidelines. Back in the late 1990s there was a value drought that lasted five years and cost the jobs of many value-oriented fund managers.
Despite these challenges, value strategies can still work well even in strong markets, and it’s here that the Greenblatt model has proved effective in the second half of 2016.
Buying good companies at cheap prices
In The Little Book That Beats the Market, Greenblatt set out a ‘Magic Formula’ for buying good companies at cheap prices. To do it, he used versions of just two ratios: the earnings yield as a measure of ‘cheapness’ and return on capital as a measure of ‘quality’. In Stockopedia’s parlance, it’s a classic contrarian Quality + Value strategy.
Broadly speaking, the earnings yield tells you how much profit a company is making in relation to its underlying value. To take account of varying levels of cash and debt in companies, one way of working it out is to divide what the company earns in operating profit by its total valuation (known as the enterprise value). You can then apply this to every company in the market to see which are offering the best value – the higher the yield, the cheaper the stock.
The return on capital focuses on the how good a company is at generating high returns from the investment it makes in itself. Good quality companies are very efficient at delivering high percentage returns from the cash they reinvest to grow.
Greenblatt’s strategy ranks every company on each ratio and then adds the ranks together to get a Magic Formula rank for each one. The appeal of this ‘ranking’ approach is that it looks for relative performance. So, in any market conditions it will always point to those stocks that are the best blend of ‘good’ and ‘cheap’ - so the pool never runs dry. For sure, it may go through periods of not working well, but there is never a shortage of candidate stocks to investigate.
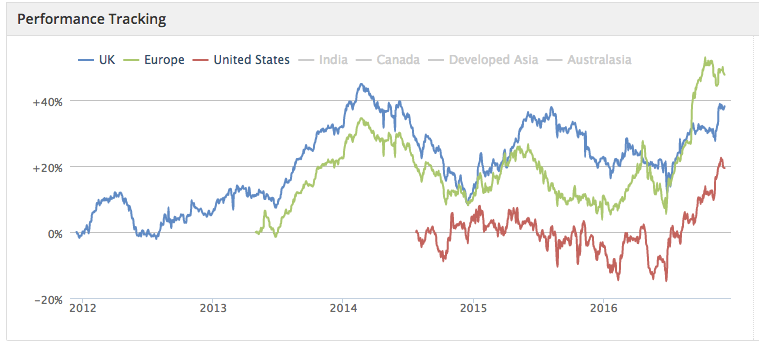
After a quiet two years, there has been a noticeable uptick in the Magic Formula strategy over the past six months. In the UK, it is up by 13.5% versus 8.7% from the FTSE 100. And in both Europe and the US the strategy has soared by just over 30%.
In the UK, the current model portfolio, which was refreshed at the end of September, has seen some strong gains in stocks like Somero Enterprises, Constellation Healthcare, Utilitywise and CPP Group. CPP in particular was a company some believed to be on its knees. But it recently uprated its earnings guidance for this year, and the shares leapt in price - and that’s precisely what value investors are looking for.
Interestingly, when you map the Magic Formula against Stockopedia’s own QV composite rankings in recent months, particularly in the UK and Europe, the performances have been similar. It points to some positive signs from the combination of quality and value in recent months, and perhaps to a rotation out of more expensive stocks towards value.
Waiting for the magic to happen
In the years since Greenblatt introduced the Magic Formula, there has been a great deal analysis about how (and when) it actually works. He always acknowledged that it was a difficult strategy for investors to follow consistently because, he said, it lacks excitement and it requires patience. That’s an observation that can be applied to many value-focused investing strategies. But in recent months, the Magic Formula has shown that it can perform very well.
You can find Stockopedia tracking of the Magic Formula strategy here, and our broader look at contrarian QV strategies here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

6 comments
Value and quality might help one steer clear of seemingly undervalued companies that are doomed. But the criteria do not address the problem of timing - will the stock just sit there year after year? Value + quality + momentum might address the timing problem.
Nick de Peyster
http://undervaluedstocks.info/
Not a great time to post this article given that Greenblatt's Magic Formula screen is only working for UK and Europe. Returns no companies when the "focus" is on Developed Asia, Australasia, Canada, India, or United States.
Also, while I'm complaining ... Stockopedia classifies Greenblatt's Magic Formula as a "Quality" screen. That is fair enough; but it's inconsistent to then classify Richard Beddard's Nifty Thrifty screen as a "Value" screen, since this screen is simply Greenblatt's Magic Formula combined with Piotroski's F-Score (a quality criterion). If Greenblatt's screen is a "Quality" screen, then, a fortiori, so is Beddard's.
(Moan over. I do actually really like Stockopedia.)
It shows value strategies can work but it also shows that other strategies work better as you can see in other screens, the problem with value shares is you often have to wait quite a long time for it to be realised. 6.7% return is not very impressive, many others are returning 20% or more. I think you need to mix value with momentum.
I do not believe in magic, and I know that no formula will transform a losing system into a winning one.
Joel Greenblatt's Magic Formula is somewhat controversial and I have never understood the approbation afforded to it. Independent studies have never produced the returns Greenblatt claimed (apparently the "Magic" bit of the formula is Greenblatt's own, additional input). Most studies have found Magic Formula returns to be somewhat mediocre, and certainly nothing like those claimed by Greenblatt.
Any screen will outperform occasionally by chance, but unless one can predict those periods when a particular screen will outperform (and I, for one, certainly cannot), then it is long term performance that is important. On that basis, Stockopedia's Magic Formula screen appears to agree with previous, independent studies: namely that the Magic Formula produces only mediocre returns. Since inception, Stockopedia's version of the Magic Formula produces an annualised return of 6.7% compared with the FT All Share Index over the same period producing a marginally inferior 6.03%.
Over the longer term, Stockopedia's own figures suggest there are many superior screens.
I think the opening quote should be "buying good businesses at bargain prices is the secret to making lots of money” - otherwise it doesn't quite work!