Babcock International: shares climb on solid H1 and unchanged outlook

Analyst’s view:
Today's results are in line and do not report any further cost overruns on the loss-making Type 31 frigate contract. However, commentary from the new CEO makes it clear - in my view - that further losses remain a risk. On a P/E of c.15, I think the shares look up with events so I'm leaving my neutral view unchanged.
Up 7% to 1,041p (£5.1bn) - Half-Year Results
I suspect the share price rally that's followed today's half-year results from engineering group Babcock is at least partly a measure of the market's relief. The shares fell sharply earlier this year when the company admitted to an expected £140m cost overrun on its high profile Type 31 frigate contract.
Today's results are resolutely in line and do not reveal any fresh problems with the Type 31s. New CEO Harry Holt has shared some additional detail on the Type 31 contract problems, though, which I'll look at below.
Half-year results: key points
Today's results are broadly positive, but do highlight the lumpy nature of contract wins in this business:
Revenue up 6% to £2,697.7m
Underlying operating profit up 13% to £227.3m
Reported operating profit down 6% to £220.7m
Underlying EPS up 15% to 32.7p
Interim dividend up 12% to 2.8p
Contract backlog down 10% to £8.9bn
Reassuringly, cash generation remained strong with net profit of £160.5m converting into free cash flow of around £185m - a strong performance. This supported a half-year net cash position of £34.7m, excluding leases. I don't see any serious concerns around the group's balance sheet - a risk that's always worth watching in this sector.
Trading commentary: Babcock's main focus is defence, although the company is also active in the growing nuclear power market. Although the value of the group's contract backlog fell during the first half of the year, the company sounds confident about its pipeline and highlights a number of new wins today - including a large win expected in November:
Six-year Canadian submarine support extension contract (CAD 1.2bn)
Aviation training contract with French Armed Forces
Secured "key role" in UK SMR nuclear rollout
Expects to sign Future Maritime Sustainment Programme nuclear submarine and naval base successor contract in November - this is to support the UK's nuclear submarine fleet, and would be a renewal of existing Babcock contracts. Not winning this work would be a major setback.
Type 31 Frigates: In 2019, Babcock won a contract to build five Type 31 frigates for the Royal Navy, based on an existing design which it also hopes to sell overseas.
I've mentioned this again today because it's an example of how large engineering contract can go wrong for big companies, especially if they are not structured to provide protection against changing macroeconomic conditions. My emphasis:
Although the contract contained certain escalation clauses, it provided limited protection from the macroeconomic changes of recent years relating to Brexit, Covid, raw material prices and UK labour shortages, which have significantly increased our costs. This has resulted in the contract being loss-making, together with increases in estimated costs due to the maturing of the design and the forecast cost of labour.
In May the company said that the cost of completing this contract would be around £140m higher than completed. Today's results explore the cost overrun in much more specific detail, which is worth reading if you're interested. The upshot is that a further £700m of costs are expected on the project.
Although the company still has £71m remaining of the original provision booked last year, any further cost overruns would add to this, putting pressure on both reported profits and the balance sheet (as all further cost overruns will be real cash outflows).
At this stage I don't think there's any way to know how likely this is. While I think Babcock could afford a further 10% (say) cost overrun, this is a good reason why I think contracting businesses such as this need to maintain net cash positions (and very disciplined bidding practices).
Roland's view
Defence contractors are meant to be enjoying a bull market at the moment, for obvious (if regrettable) reasons. That's true, to some extent, but it's becoming clear that delivering real, profitable growth in a lumpy, government-led market isn't always as easy as it might sound.
Babcock's share price has de-rated sharply since defence stocks hit a general peak early this year:
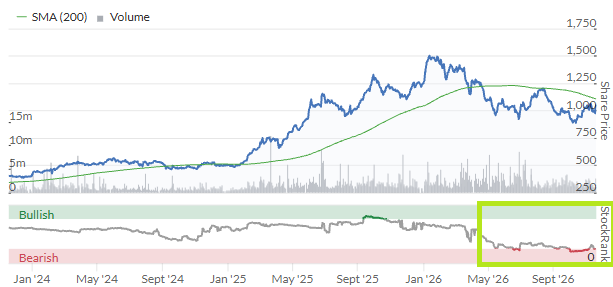
The StockRank has seen a corresponding decline and our algorithms now view this as a Falling Star, a style that often underperforms for an extended period of time.
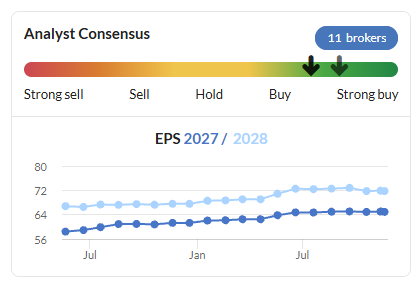
However, broker estimates have remained relatively resilient this year, so it's possible that today's in line results may result in an improvement in the StockRank:
In my view, the valuation of the stock is reasonable, but not especially cheap.
A forward P/E of 15 seems about right to me and the 1.3% dividend yield is not especially appealing. While cash generation remains good, the outlook (under a newly-arrived CEO) makes it clear that there's still some risk of further cost overruns on the Type 31s. Problems could occur elsewhere, too: this is a perennial risk in this sector and has affected Babcock before.
In May I moved our view down by one notch to neutral. Based on today's results, I think this remains a fair choice.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Babcock International (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?