Daily Stock Market Report (Wed 13th May 2026) - TCAP, VTY, GAMA, ITRK, VTU, AVON, BAB

Good morning!
Prime Minister Starmer is still in Number 10 despite the resignation of four ministers yesterday. He has said he won’t stand down unless someone launches a formal leadership challenge. The yield on 10-year UK gilts has now topped 5%, while 30-year gilts are at almost 5.8% – the highest level since 1998.
Across the Atlantic, US inflation rose to 3.8% in April, from just 2.4% in February, prior to the start of the Iran conflict. The increase has been driven by a c.25% increase in petrol prices. This squeeze on consumer spending will add to pressure on President Trump ahead of this year’s mid-term elections. Inflation is expected to spill over into higher prices for food and other goods and services in the coming months.
Trump will shortly arrive in China where he’s expected to discuss China’s support for Iran, in addition to a range of trade issues. More controversially, US arms sales to Taiwan are said to be on the agenda; China would like these to cease. He will be joined by Nvidia boss Jensen Huang in China, suggesting AI will also be on the agenda.
Also on AI, Claude maker Anthropic is reported to be in discussions to raise $30bn at a valuation of $900bn, according to Bloomberg.
Here in the UK we don’t have any $900bn companies, but we do have some more affordable ways to play the AI theme, as Gareth discussed in his latest article on Friday.
FTSE 100 expected to open up 0.6%
S&P 500 expected to open up 0.2%
Brent Crude is trading at $104 a barrel
Gold at $4,703/oz
Update 10:18: added Intertek's response to the latest offer from EQT to the table.
Today's report is now complete. See you in the morning!
Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
| Intertek (LON:ITRK) (£8.2bn | SR59) | Statement re final proposal from EQT | “… the Board of Intertek considers that the financial terms of the Final Proposal [£60 per share + dividend] deliver value in cash to Intertek shareholders at a level which it would be minded to recommend to Intertek shareholders” | PINK (Roland - I hold) [no section below] It looks like Intertek is now likely to accept private equity group EQT’s offer, assuming it is made firm. As a shareholder I’m not unhappy. While I think the long-term value of the business could be greater, £60 seems fair to me and offers certainty versus the execution risk of the company’s own plan to spin-off or sell its lower-margin energy-focused business. |
Spirax (LON:SPX) (£5.29bn | SR73) | Delivering organic growth ahead of industrial production, with margin progression. Full-year guidance unchanged for mid-single digit organic revenue growth. | ||
Babcock International (LON:BAB) (£4.94bn | SR34) | FY26 revenue up 9%, with underlying earnings down 21% to 39.6p due to a £140m charge relating to rework costs for the Type 31 frigate contract. FY27 expectations are unchanged. | AMBER ↓ (Roland) Today’s update reveals a surprise £140m cost overrun on a large project to build five Type 31 frigates for the Royal Navy. Babcock has booked the accounting charge in FY26 but expects cash outflows over the remainder of the contract. While this doesn’t necessarily detract from the positive macro environment for defence businesses, it is a useful reminder of the kind of pitfalls large contractors like Babcock can face. While FY27 guidance is unchanged today, Babcock’s order book fell last year and consensus figures suggest earnings growth will slow this year. The valuation looks up with events to me and I note the StockRank has been falling steadily for months. I’m downgrading our view by one notch to neutral. | |
TP Icap (LON:TCAP) (£2.3bn | SR96) | Record Q1, with revenue up 13% led by Global Broking (+15%) and Energy & Commodities (+13%). Remains comfortable with the outlook for the remainder of the year. | GREEN = (Roland - I hold) It’s no surprise to see that this broking group had a strong Q1 – by design, it’s built to benefit from volatility and heightened market activity. Full-year guidance is unchanged today which is perhaps slightly disappointing, but current forecasts look undemanding to me and I think the risk is probably to the upside. One possible joker in the pack is the group’s high cost base, which I discuss below. However, with a single-digit P/E and near-6% dividend yield, I think the valuation and outlook are attractive and am happy to maintain our positive view. | |
Resolute Mining (LON:RSG) (£1.57bn | SR67) | Study confirms ABC’s “strong economic potential” and “pathway” to become Resolute’s second gold mine in Côte d'Ivoire, with expected gold production of c.141 koz/yr over a 12-year mine life at an AISC of $1,614/oz. NPV (5%) of $1.2bn, capital cost estimate of $648m. | ||
| Savills (LON:SVS) (£1.22bn | SR89) | AGM Statement | Trading for the year to date has been “marginally ahead of the Board’s expectations”, despite the impact of geopolitical volatility. 2026 expectations remain unchanged. | |
Vistry (LON:VTY) (£1.04bn | SR78) | Year-to-date sales rate is 32% higher than last year as Vistry takes action to generate cash, but increased use of discounting and incentives means H1 profit will now be lower than expected and “significantly lower” than last year. H2 profit is expected to be in line with the prior year. Vistry remains committed to the Partnerships model. The new CEO is leading a review of the business and will report by 24 Sept 26. | BLACK/AMBER/RED ↓ (Mark- I hold) While the company says that Adj. PBT will be in line with the middle of the range of analysts expectations, there is a huge variation in these. It is clear that "significantly lower” in H1 and similar H2 performance to last year add up to lower figures overall. There are some signs that the company is being put under financial strain by delays in completions, and the need to offer increased incentives. Average net debt is higher in H1, but expected to be significantly lower in H2. I have reduced our view today to reflect these near-term risks. However, this is a rather unique situation, where a significant proportion of the equity has been sold short into this update. If the company doesn’t report any further bad news in the next few months, and net debt does start to reduce, then there may be significant buying pressure from those shorts closing. After all, the discount to TBV would remain even with a large haircut to land values. | |
Gamma Communications (LON:GAMA) (£810m | SR55) | Good start to FY26, with full-year expectations unchanged. Strategic review: Gamma says it is in discussions with various parties and confirms press speculation that it is in talks with Providence Equity Partners about a possible offer. | PINK (AMBER/GREEN ↑) (Roland) Gamma’s trading faces various near-term headwinds, but these have previously been flagged and guidance for this year is unchanged. Management reports positive progress in the core UK and German markets and confirms that preliminary talks with possible bidders are ongoing. With a trailing free cash flow yield of 7% and single-digit P/E, I think Gamma is likely to offer medium-term value, so I’m upgrading my view by one notch today. | |
Conduit Holdings (LON:CRE) (£693m | SR87) | “Solid start to 2026”, with gross written premiums +4.9% and reinsurance revenue +12.8%. However, overall portfolio risk-adjusted rate change was -5% in Q1, net of claims inflation. Approved new $50m buyback. | ||
Thor Explorations (LON:THX) (£500m | SR100) | First set of drilling results from Douta following completion of PFS earlier this year “confirm expanding gold footprint” at Douta. | ||
Avon Technologies (LON:AVON) (£486m | SR30) | Revenue up 6.8%, but closing order book down 11.4% due to a 31.6% fall in order intake. This is said to be due to timing of US DoW orders and weakness in US commercial helmet demand. H1 adj pre-tax profit up 47% to $21.8m. Firmly on track to meet or exceed FY26 guidance. | AMBER/RED ↓ (Mark) | |
Guardian Metal Resources (LON:GMET) (£393m | SR26) | Guardian Metal is evaluating the potential of recovering tungsten and other metals from the historic tailings at Tempiute, with a view to provide an opportunity for near-term, domestically sourced tungsten in the U.S. These tailings cover c.550 acres and GMET has expanded its mineral rights position to cover the full tailings footprint. Drilling planned for June 2026. | ||
Marshalls (LON:MSLH) (£318m | SR75) | Trading was in line for the four months to 30 April, with revenue down 1% at £205m. Full-year expectations are unchanged. | ||
Public Policy Holding (LON:PPHC) (£286m | SR22) | Revenue up 27.5%, with +5.1% organic growth. Adj net income up 100% to $7.4m, with adj EPS up 74.5% to $0.25. Net debt reduced to $1.8m following January capital raise and US IPO. 2026 guidance: revenue $205-209m, adj EBITDA $46-48m. | ||
Vertu Motors (LON:VTU) (£205m | SR92) | Revenue -1.5% to £4.83bn, Adj. PBT -16% to £24.5m, Adj. EPS -13% to 5.71p, Net debt £61.3m (FY25: £66.6m), FY dividend flat at 2.05p. Outlook: Strong start to FY27, trading profit for March and April 2026 was ahead of the prior year. | AMBER ↓ (Mark) There is nothing wrong with these results, indeed they are slightly higher than forecast (if you accept the ongoing adjustments). However, the share price is now higher than when we reviewed this last, meaning that a forward P/E of 11 doesn’t look particularly great value for a company exposed to worrying consumer confidence trends. Hence I am moderating our view. There is still a discount to TBV, which is mainly supported by freehold property. However, with little sign that these assets can be made productive any time soon, and alternative uses such as property land sales looking shaky, this type of play is only for the very patient. | |
| Afentra (LON:AET) (£170m | SR97) | FY25 Annual Results and Corporate Update | Strategic review: continuing as an independent company. Results: 2025 WI production 6,324 bopd, Revenue -37% to $114.4m, EBITDAX -43% to $51.7m, LBT $3.2m (2024: PBT £52.4m). Refinancing: secured a refinancing of its debt facilities through the entry into a $125 million Pre-Payment Facility at SOFR +6%. | |
Inspecs (LON:SPEC) (£84.9m | SR79) | Revenue -1% to £191.7m, Adj. EBITDA -9% to £17.7m, Op. Profit -3% to £5.7m, Net debt excl. Leases £32.3m (FY24: £22.9m). “….the Group is on track to deliver Board expectations for 2026.” | PINK | |
Orosur Mining (LON:OMI) (£79m | SR12) | Ongoing drilling at Pepas West continues to show positive results, including 23m at 2.98 g/t. | ||
Arrow Exploration (LON:AXL) (£62.5m | SR62) | The Icaco 1 exploration well reached target depth on May 9, and encountered multiple hydrocarbon-bearing intervals. Plans to production test over the coming weeks. | ||
Enwell Energy (LON:ENW) (£44.1m | SR86) | Aggregate average daily production of 1,865 boepd (2024: 2,288 boepd) when in production. Aggregate production volumes of 49 kboe (2024: 722 kboe). Revenue -92% to $3.3m due to license suspensions. Net Loss $4.5m (2024: $23.7m profit). Cash $97.1m (2024: $99.4m). “...continuing to pursue legal proceedings to challenge the suspension orders and protect its business and assets…” | ||
Getbusy (LON:GETB) (£35.7m | SR27) | April ARR +11% to £23.4m. “...the Board reconfirms its expectations for 2026 with a high degree of confidence.” | ||
KRM22 (LON:KRM) (£18.7m | SR8) | ARR +15% to £7.6m. Revenue +10% to £7.4m. Adj. EBITDA -20% to £0.8m. LBT £2.1m (FY24: £1.4m LBT). Net Cash £5.2m (FY24: Net debt £3.5m) following £9.2m fundraise in period. | BLACK | |
Kelso group (LON:KLSO) (£13.7m | SR38) | Intention to raise new funds equal to 5% of its issued share capital at a placing price of 3.0 pence per share, equivalent to c.£650,000. 3% discount to last night’s close. | ||
Panther Metals (LON:PALM) (£10.7m | SR21) | Sixth and final batch of Vibracore sample assay results for the Winston Tailings Project continue to show good grade consistency across the vertical depth-profile and laterally between Vibracore hole collar locations, and support or exceed the previous batches. |
Roland's Section
TP Icap (LON:TCAP)
Up 0.5% at 316p (£2.3bn) - Trading Statement - Roland - GREEN =
(At the time of writing, Roland has a long position in TCAP.)
This interdealer broker group sits as the middle man between buyers and sellers in many key markets globally, notably interest rates, FX and energy commodities. As Gareth highlighted in this recent article, this business gets paid based on activity rather than the outcome of the underlying investments – so it’s designed to benefit from volatility and heightened market activity.
TP ICAP’s management provides evidence of this in this morning’s AGM Update:
Q1 revenue rose by 13% to £689m, a new record
Global Broking revenue: +15%
Energy & Commodities revenue: +13%
Liquidnet (an off-exchange trading venue) revenue: +9%
The company also provides an update on its proprietary OTC data analytics business, Parameta Solutions:
At Parameta Solutions, recently added sales reps are beginning to contribute and the business remains focused on buy-side engagement, new logos, upsell and retention, with Q1 revenue +4 per cent.
Parameta is a high margin (c.40%), recurring revenue business that’s seen as undervalued within TP ICAP’s portfolio. It was previously being prepared for a US IPO, but that seems to be on hold currently. The company says this delay is due to market conditions, but I can’t help wondering if sluggish revenue growth (+5% in 2025) may have contributed to this decision – perhaps investors were deterred by the apparent lack of momentum.
I’m pleased to see TP ICAP is now taking Parameta’s growth more seriously and investing in the business.
Outlook
Management is confident:
As market leaders we are well-positioned to continue to support our clients with highly trusted, reliable execution, and insight as they manage their risk during the continuing macroeconomic and geopolitical uncertainty.
But there’s no change to guidance at this relatively early point in the year:
The Board remains comfortable with the outlook for the remainder of the year at current FX rates.
Forecasts from Cavendish are unchanged today, but the broker says it will review its forecasts on the back of this morning’s announcement.
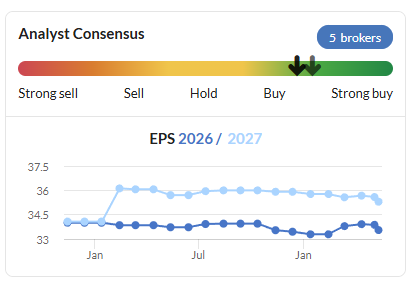
The StockReport shows a slightly negative trend to consensus estimates in recent weeks, but I would not expect any further downgrade following today’s update:
Roland’s view
Broker consensus prior to today was for revenue growth of just 2.3% in 2026. While there’s still more than half the year remaining, it seems hard to imagine that TP ICAP will underperform this target after such a strong start to the year. After all, I would imagine that strong trading has continued into Q2, which is now 50% complete.
Likewise, consensus earnings forecasts for 33.6p per share would represent a flat performance on last year’s adjusted EPS of 33.5p. Against the macro backdrop, I’d consider this a disappointing result for 2026.
The joker in the pack of course is that costs could rise, both in terms of remuneration and broader overheads. This is, by its nature, a high remuneration business.
Brokers are paid a profit share and broker compensation rose by 6% to £1,068m in 2025. This contributed to total employee compensation and benefit costs of £1,485m last year – 63% of revenue.
Today’s update mentions “strict cost discipline”, but the company has also previously reported recruitment challenges in Energy & Commodities. I imagine that overcoming these challenges to implement “a successful hiring programme” in H2 2025 may have involved providing improved compensation packages.
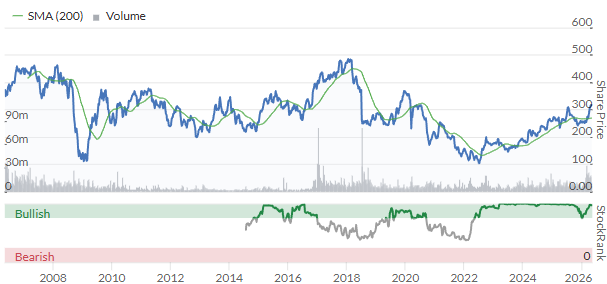
TP ICAP has not been a great long-term compounder, but the stock has performed very well since the start of the war in Ukraine:
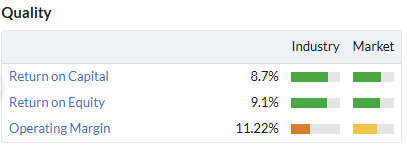
Profitability has also started to improve, with (unadjusted) operating margins returning to double digits. Return on equity remains underwhelming, though:
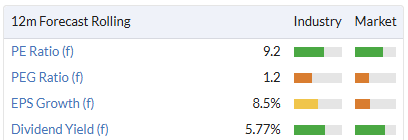
The good news is that – in my view – all of this is already in the price. The shares trade on a single-digit P/E with a 5.7% dividend yield:
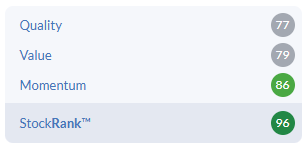
The StockRanks view this as a Super Stock and I agree that the valuation and investment case look appealing at current levels.
TP ICAP is currently a member of my SIF portfolio. Personally, I’m happy to hold the shares, which I see as a hedge against volatility and the uncertain macro outlook.
I’m going to leave Graham’s previous positive view unchanged today.
Gamma Communications (LON:GAMA)
Up 5.5% at 943p (£853m) - AGM Trading Update & Response to Speculation - Roland - PINK (AMBER/GREEN ↑)
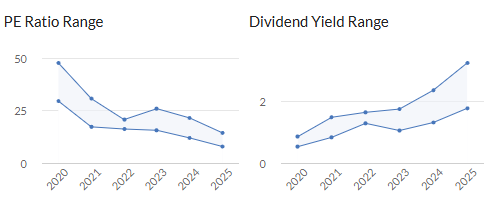
This business communications technology provider has de-rated sharply over the last five years:
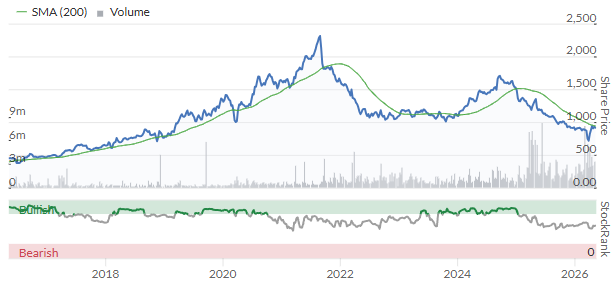
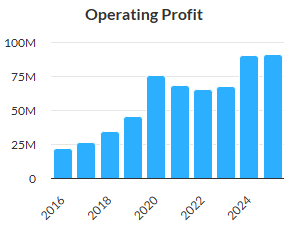
The shares are now trading at seven-year lows, even though operating profit has doubled over the same period:
As far as I can see, this stock is now trading more cheaply (on a P/E basis) than at any time since Gamma’s 2014 IPO.
While the valuation may have overheated at times in the past, I’m not convinced the current single-digit P/E is a fair reflection of the value of this business, despite ongoing headwinds in the UK due to the switch from copper telephone lines to (lower margin) digital services.
Management appears to agree and has perhaps run out of patience for convincing public markets of the group’s value. In March, Gamma confirmed reports that it was in preliminary sale discussions with “a number of interested counterparties”.
Sales talks ongoing: Today, the company has confirmed that preliminary discussions are ongoing and identified one possible bidder as Providence Equity Partners, a US private equity firm with a specialist focus on media and communications.
AGM Trading Update
We also get a trading update to mark today’s AGM, confirming that full-year guidance is unchanged.
Here are the main points:
“The Group has made a good start to FY 2026, with trading in line with expectations.”
Germany: continued strong adoption of cloud solutions, with ongoing momentum from new customer wins and upselling to existing customers.
UK SME: ongoing headwinds from the switch-off in early 2027 of the UK’s legacy phone network (PSTN), as previously guided. However, cloud volumes continue to grow, driven by sustained uptake of Webex for Gamma and PhoneLine+. “Customer engagement and the partner pipeline remain healthy with opportunities for larger migration deals.”
Service Provider: early traction of international strategy in Europe and APAC, has signed first contracts with customers in Germany, Australia and Singapore.
Enterprise: continued momentum from contract renewals and new business wins, including “an AI-led Customer Experience deployment at JD Sports” and further public sector wins.
Balance sheet: net debt was £1.6m at 30 April following expected cash outflows on buybacks (£12.1m) and deferred consideration for past acquisitions (£3.8m).
While I’m not always a fan of share buybacks, following the approach used by Next suggests buying back Gamma shares could create value for shareholders at current levels. Based on last year’s statutory profits, I estimate a pre-tax return on capital of 10.3% at today’s share price. That’s comfortably above the 8% minimum required by Next, whose use of buybacks is generally considered best-in-class.
Outlook
The Board expects financial performance for FY 2026 to be in line with market expectations, with Adjusted EBITDA and Adjusted EPS (fully diluted) in line with the consensus range (FY 2026 Adjusted EBITDA £138.1m - £142.8m and Adjusted EPS (fully diluted) 90.9p - 94.4p respectively, as at 12 May 2026).
Checking the March note from paid research house Progressive shows forecasts that are bang in the middle of the ranges cited above, so I don’t think there’s any change to expectations today.
That leaves Gamma still trading on a single-digit P/E, despite hopes of a bid:
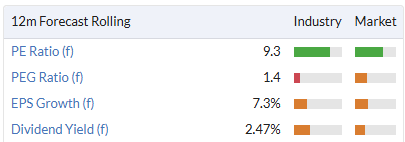
Roland’s view
Gamma’s Quality metrics remain strong, as does the balance sheet:
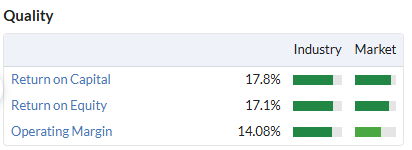
The valuation also looks very tempting to me. By my sums, last year’s results give the stock a free cash flow yield of 7% and trailing EBIT/EV yield of 10.7%.
These are both levels I’d associate with value unless a business is in decline.
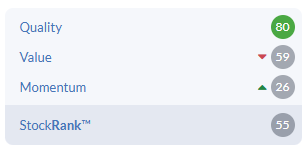
The missing element is momentum. This is highlighted by the StockRank and Contrarian styling:
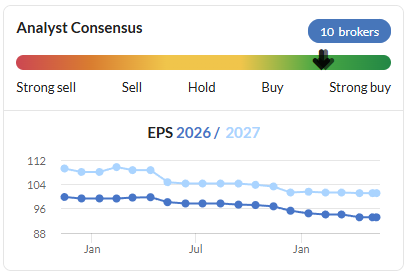
Earnings forecasts have also drifted lower over the last year, although estimates for 2027 still show a useful return to growth:
When I reviewed Gamma’s trading update in January I took a neutral view, commenting that “it feels to me like management may be digging in for a difficult period”. I noted the decision to freeze the dividend and direct up to £85m of cash into buybacks instead.
The share price is largely unmoved since then despite the emergence of possible bidders.
The only explanation I can see for this is that investors are pricing in structural weakness in margins (following the UK PSTN switch off) or slower growth due to subdued economies in Gamma’s core UK and German markets.
There’s evidently some risk of near-term weakness, but I’m reassured by today’s in line statement and my view is that the sell off has probably gone too far.
Although consensus forecasts do indicate flat earnings this year, I think technology and demand will continue to evolve and should support the medium-term growth of this business. I share the StockRanks view that this could be a contrarian opportunity and am moving my view back up one notch to AMBER/GREEN today.
Babcock International (LON:BAB)
Unch at 1,009p (£5.0bn) - FY26 post close Trading Update - Roland - AMBER ↓
Engineering contractor Babcock is one of the main outsourcing partners for the UK defence sector. This is a hot place to be at the moment, as Graham commented in January.
Despite this, Babcock’s share price has fallen by 30% since our last view on 23 Jan:
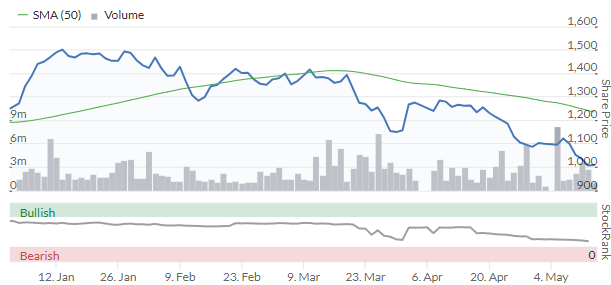
One reason for this may simply be that Babcock’s share price had run ahead of events. After all, the stock was trading on a P/E of 24 in January with a dividend yield of under 1%.
However, today’s update has revealed another reason why investors may want to be cautious about overpaying for companies such as Babcock – cost overruns on big projects.. While this particular news has only been released today, as far as I know, it’s a type of risk we’ve seen many times before with outsourcing groups, including Babcock (my emphasis):
The Group's strong underlying financial results were partly offset by a non-recurring charge on the Type 31 contract, estimated to be £140 million, fully recognised in FY26.
The Type 31 contract is a deal to build five frigates for the Royal Navy that was awarded to Babcock in 2019. Two ships were floated off last year and are now being outfitted, while a further two are now under construction. Unfortunately, problems have emerged:
During the outfitting stage we have experienced higher than expected levels of rework as a result of changes to the design and the long-term impacts of out-of-sequence build activity earlier in the programme. Whilst the number of such rework events is not entirely unexpected, the work is being performed in the later stages of completion and therefore is more complex and more costly.
Following an engineering review, Babcock has concluded that the cost of completing the contract is now expected to be £140m higher than previously expected. This will be a cost the company has to absorb:
This is reflected in an expected charge on the contract (subject to audit) of £140 million for the revised costs to complete delivery of the Type 31 design and build contract, which is fully recognised in FY26, but the cash costs of which will be incurred over the remainder of the programme.
The market appears to have shrugged off this news today, perhaps because Babcock has left its FY27 guidance unchanged (the group’s year end is 31 March).
However, The Type 31 problems will have a significant impact on the group’s FY26 results:
Contract backlog down 7.7% to £9.6bn
Revenue up 9.1% to £5,273m
Underlying operating profit down 19.3% to £293m
Underlying operating profit excluding Type 31 charge up 19.3% to £433m
Depending on whether you’re willing to exclude the costs of Babcock’s engineering miscalculations, FY26 underlying earnings per share are either slightly ahead of consensus at 60.5p, or significantly below expectations at 39.6p (Stockpedia consensus: 56.3p).
Personally, I am not inclined to ignore these costs. Building ships is a core part of Babcock’s business. If the company miscalculates the likely cost to do so, then ultimately shareholder returns will suffer. This has happened in the past – when departing CEO David Lockwood joined in 2020, the company was struggling with another such mishap (albeit larger):
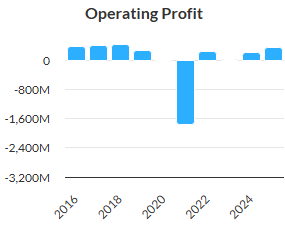
In this case, the impact appears to be both limited and manageable. Even so, the impact on free cash flow could be material – the company has reported FY26 underlying free cash flow of £262m today. Assuming the cash costs of the Type 31 problems will be similar to the £140m accounting charge reported today, then cash outflows over the next few years could erode the group’s cash generation.
FY27 outlook: incoming CEO Harry Holt (previously in charge of Babcock’s nuclear business) will have to hope that there are no further problems with the Type 31 build.
The company has left its FY27 guidance unchanged today and says it has secured around 70% of revenue for the current year, “a similar percentage to the prior year”.
The consensus page on Babcock’s website gives me the following figures, suggesting sales and (underlying) profit growth are expected to slow this year:
FY27 Revenue: £5,376m (+2% vs FY26)
FY27 Underlying operating profit: £449.3m (+3.8% vs FY26, excluding Type 31)
FY27 Underlying EPS: 63.1p (+4.3% vs FY26, excluding Type 31)
These figures are broadly in line with the consensus estimates on the StockReport. To me, the valuation looks up with events:
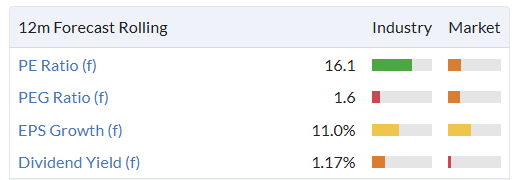
Roland’s view
Graham was AMBER/GREEN on Babcock in January, but I am not sure I see sufficient evidence of value or momentum to maintain that view today.
In addition, I’m a little disappointed at the scale of the cost overruns on the Type 31 contract and the decline in Babcock’s order book last year.
As Mark pointed out with Avon, it’s difficult for us to guess how much the intention to increase Western defence spending will translate into additional revenue and profit for individual companies. While Babcock’s position as a key partner for the UK Ministry of Defence looks very secure, that won’t necessarily translate into automatic growth.
The StockRanks have been taking an increasingly cautious view on Babcock and I am inclined to mirror this:
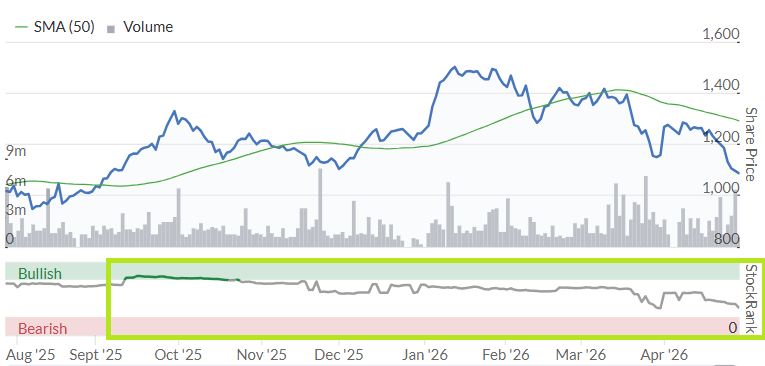
I’m going to downgrade our view by one notch to neutral (AMBER) today.
Mark's Section
Vistry (LON:VTY)
Down 10% at 292p (£1.04bn) - AGM Trading update - Mark - BLACK/AMBER/RED ↓
(At the time of writing, Mark has a long position in VTY.)
This is a fascinating situation. There is no doubt that today’s warning was expected. Here is the short position going into this update:
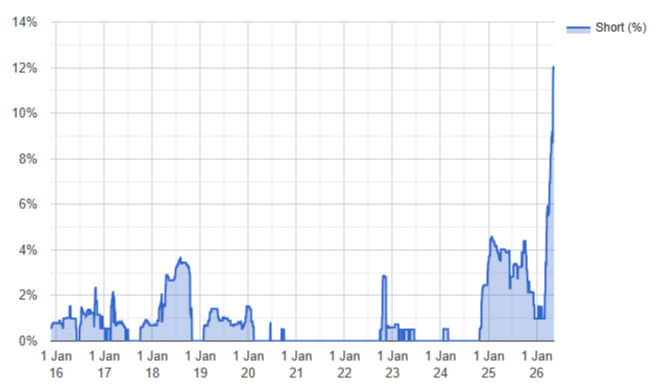
[Source: shortracker.co.uk]
These aren’t just quant funds, either, but look like largely discretionary positions, who have all been increasing their short positions into this update:
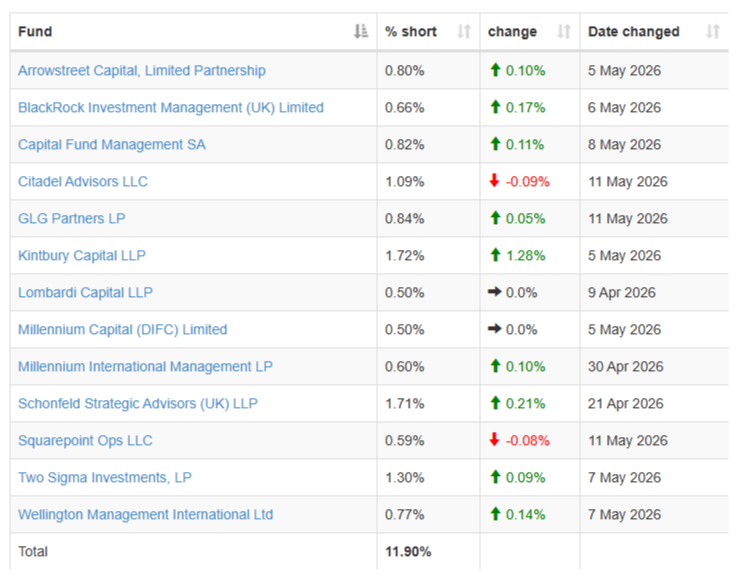
[Source: shortracker.co.uk]
However, looking at the annual report, it was hard to see what exactly is wrong with the company. It was clear from their comments on average daily net debt versus year end position that the financial situation is not as strong as some simple year end metrics may suggest:
Net debt reduced to £144.2m as at 31 December 2025 (31 December 2024: £180.7m) with average daily debt of £733.7m.
However, the obvious signs of financial distress were not there. Trade payables looked a little elevated, but not necessarily out of the ordinary:
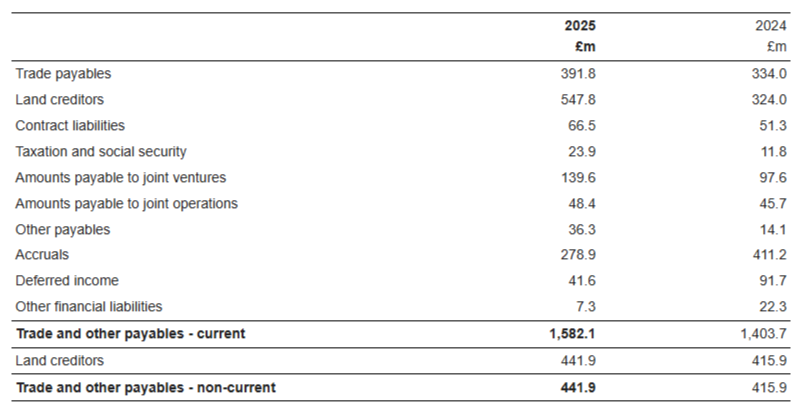
The current land creditors being so large is perhaps the only thing that looks out of the ordinary. It seems the company has viewed the weak market for building land as an opportunity, and been buying. This perhaps looks a little unwise as companies such as Crest Nicholson have had to pause their planned land sales due to lack of demand.
And it is undoubtedly cheap on many metrics, not least that P/TBV:
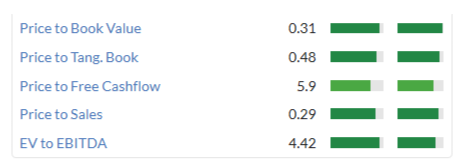
Given what is happening in the sector, the land on the balance sheet may be overvalued, but it would take a huge haircut to wipe out that discount to book value. Perhaps the most damning critique is that it goes against their stated strategy of moving to an asset-light, partnership model.
Both Roland & I kept our neutral view, when we reviewed it at a significantly higher price. The big question is does today’s update change these dynamics?
First up, it may not be an explicit profits warning, but it is a sort of pre-warning:
Primarily due to the up-front profit impact of the actions to accelerate cash generation, as described above, we expect H1 profit to be significantly lower than the prior year. However, with the benefits of an improved margin mix on active sites and a step up in demand from our affordable housing partners we expect H2 2026 profit to be in line with H2 2025 profit. The Board expects adjusted profit before tax for FY 2026 to be towards the middle of the range of analysts' forecasts.
H1 significantly below, H2 in line with last year, clearly makes the FY below the previous year. There’s a huge range of analysts forecasts:
The range of analysts' forecasts (excluding those who have not updated forecasts since the start of March) for 2026 APBT is £168m to £283m.
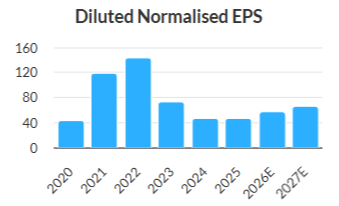
Mid-point is £226m, but we rarely see such variation in analysts' views. Adjusted PBT for FY25 was £269m, so realistically, FY26 is likely to be below FY25 on earnings. I suspect the numbers in the Stock Report from Refinitiv include stale forecasts, something the company say they have filtered out for their numbers manually:
There are modest signs that the company may be having some liquidity challenges. They talk about their cash generation focus. They are prioritising sites where they can make near-term sale or require lower capex, and being stricter with the economics of land purchases. There are signs that the sales strategy is delivering:
The year-to-date Open Market sales rate remains around 30% higher than the prior year, despite some moderation in recent weeks reflecting uncertainty arising from the Middle East conflict. The use of increased incentives and discounts has been more significant on low margin sites and developments that are nearing completion, resulting in an earlier recognition of profit impacts and a higher weighting of the overall profit impact in the first half than previously anticipated. We expect the level of discounting and its effect on profit to reduce in the second half of the year.
So homes are selling but they’ve been having to offer much bigger incentives, and this is impacting margins.
Perhaps the most disappointing part is that they are pausing their share buyback. This suggests that their liquidity headroom isn’t entirely comfortable. However, there is no mention of issues with banking covenants (unlike at Crest Nicholson, for example). And their facilities will not need renewing for some time:
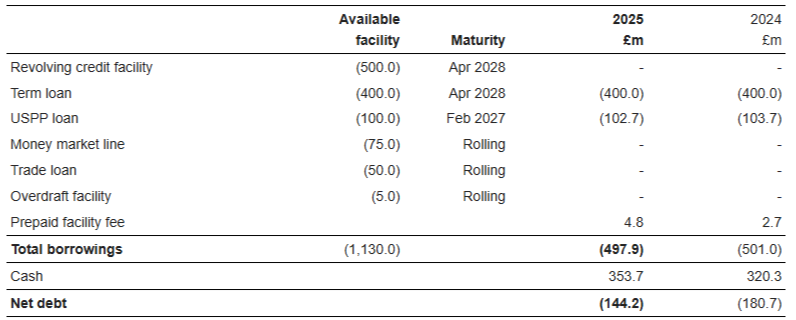
There are no signs of the usual language indicating that an equity raise is on its way. So while I don’t think they are entirely comfortable, I also don’t see an immediate liquidity crisis, which looks like what the short positions may be pricing:
….the combined effect of the above actions is expected to deliver significantly lower average net debt levels in the second half and we are now expecting a net cash position in excess of £100m at 31 December 2026.
Mark’s view
It would be a push to describe today’s update as good news, but it isn’t truly terrible news, which is what a 12% short position (of only declared positions that we know about) suggested was about to arrive. The financial situation clearly isn’t comfortable, and hence I’m downgrading our view to AMBER/RED to reflect the risks as an investment. However, the eagle-eyed will spot that I have a position here and this updated view looks incongruous with that. For clarity, this is a small controlled-risk position initiated today, on the basis that a significant proportion of the equity is sold short, presumably expecting a liquidity squeeze soon. However, given that today’s update didn't bring things to a head, this now looks like a crowded trade. If further bad news doesn’t arrive in the next few months, and the company does see significantly lower debt levels in H2, then the squeeze is likely to be the other way. I accept that this position is high risk and I’m trading against market actors that are usually smarter than me!
Vertu Motors (LON:VTU)
Flat at 65p (£205m) - Final results - Mark - AMBER ↓
Vertu don’t calculate percentages for us, but it is clear that these results aren’t anything to write home about:
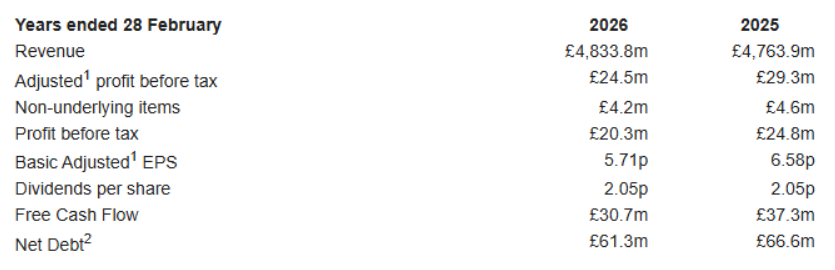
Revenue is flat and adjusted EPS is down 13%. However, these are slightly above consensus which was for Adj. PBT of £24.0m. Forecasts had been declining for some time, though, so I wouldn’t place much emphasis on this:
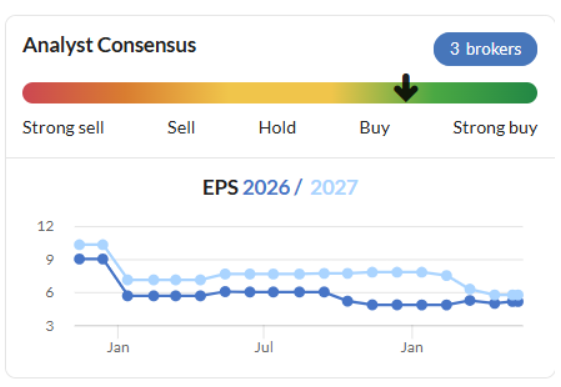
Much of the challenges have been market driven, with motability criteria tightening, and commercial sales weak:
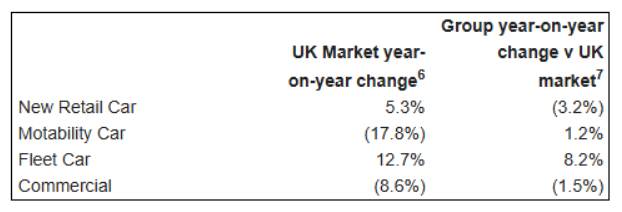
The big underperformance has been in New Car Retail, where historically Vertu have been under-represented in Agency sales. This has been the fastest growing part of the market with Chinese electric car brands, which are much cheaper for an equivalent vehicle. Despite seeing almost 40% LFL growth in Agency volumes, this still lags the market:
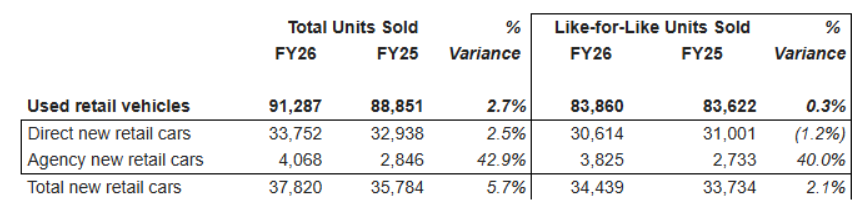
Vertu are under-represented here, but are looking to fix that imbalance:
Programme to enhance portfolio with new Chinese entrant brands implemented and set to continue: Jaecoo, Omoda, Lepas, Chery and Leapmotor to be added to portfolio.
Adjustments:
These are pretty standard. However, it is worth noting that few of these appear to be one-offs:
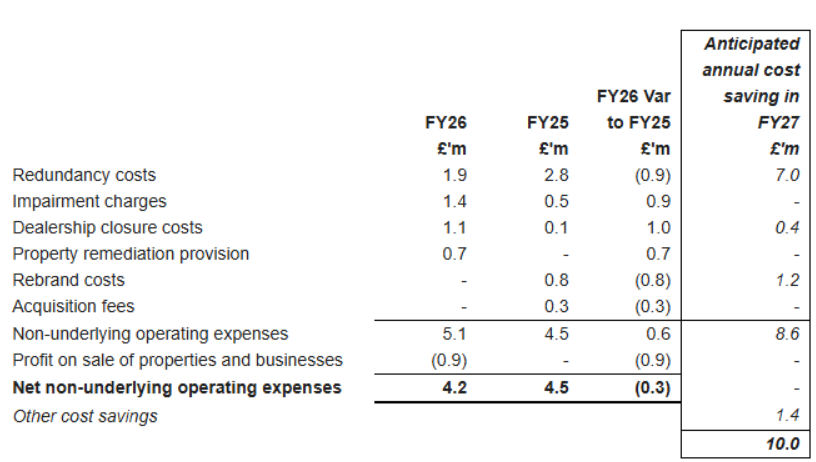
The group is likely to continue to optimise its workforce and dealership network, and future bolt-on acquisitions aren’t out of the question. So while these make sense from a business perspective, we can be sure they won’t be adjusting out the gains from these programs in FY27!
Balance sheet:
Net debt is roughly flat at around £61m, which is relatively modest. They do have negative working capital, with payables exceeding inventories and receivables. This is normal for this sort of business, but is worth bearing in mind that they could see cash outflows from working capital if trading dipped.
They are backed by significant freehold property, though:
The Group has a balance sheet with shareholders' funds of £357.5m (2025: £357.6m) underpinned by a freehold and long leasehold portfolio of £327.1m (2025: £330.9m) and net debt (excluding lease liabilities) of £61.3m as at 28 February 2026. The Group's conservative financing and capital structure resulted in a strong tangible net assets position of £235.1m as at 28 February 2026, representing 75.9p per share.
It is worth noting that if they had to pay rent instead of owning most of their sites they would probably be loss-making. The reality is that these assets are currently producing a sub-optimal return on capital.
Outlook:
Current trading looks good, with them saying “strong start to FY27, trading profit for March and April 2026 was ahead of the prior year.” However, there is a possible sting in the tail. While they have yet to see any impact from events in the Middle East, they flag the very weak consumer confidence in the UK.
Forecasts:
Shore doesn't appear to make any significant changes to forecasts, and usually provides estimates out to FY29. However, they aren’t particularly inspiring. A forward P/E of 11, falling to 10 for FY28, and 9x for FY29.
These still suggest that the assets are not particularly productive, and it may require a step change in consumer conditions or industry dynamics for these forecasts to be beaten and the stock to look good value on earnings rather than just assets.
Mark’s view
Although these results come in slightly ahead of expectations, these have been gradually reduced over the last year or so, meaning we should read little into this. There is a positive outlook, with no impact from the Middle East so far. However, it may be hard for the company to escape the impact of weakening consumer confidence in the UK. Assuming they hit forecasts, a P/E of 11 doesn’t look particularly inspiring, so the investment thesis here is largely a very long-term one assuming that their freehold assets can be made proactive, or sold off to someone who can make them productive. We’ve tended to be moderately positive here in the recent past. However, the price is now higher than when we first gave that rating, and with the risks perhaps now to the downside rather than the upside, I think a more neutral view of AMBER probably makes sense. There is still a reasonable discount to TBV, but with no sign that these assets will be particularly productive, even out to 2029, this sort of play is only for the very patient.
Avon Technologies (LON:AVON)
Down 6% at 1500p - Interim Results - Mark - AMBER/RED ↓
Some impressive numbers for H1:
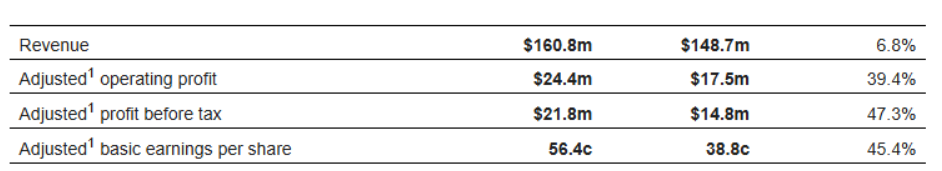
Adjustments:
Excluding amortisation of intangibles is fairly standard. However, this is another company that wants to us give them all the credit for making cost-savings in the business, but exclude all the costs of doing so:
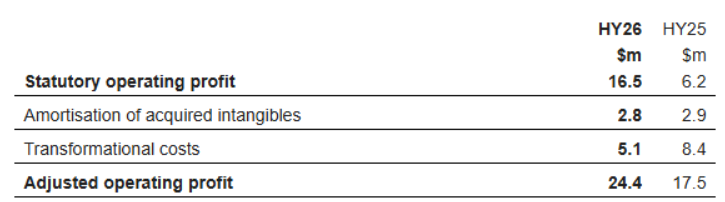
These costs are about 20% of operating profit so are not negligible. However, they are reducing and don’t change the fundamental picture of a company becoming significantly more profitable.
Outlook:
This confirms that they expect these trends to continue in the near term:
Firmly on track to meet or exceed FY26 guidance with exciting long-term growth prospects
· Increasingly confident in H2 delivery with strong commercial and international pipelines
· Still see significant operational improvement opportunities in both businesses
· Clear pipeline of opportunities to outperform core markets and deliver sustainable growth
However, there is some scary looking moves in the future order intake:
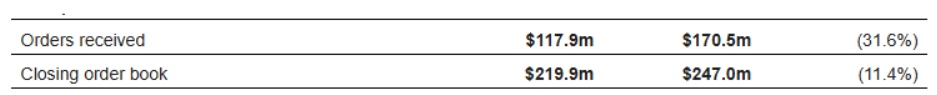
The issue is at Team Wendy where there are government procurement delays in the US:
Team Wendy's order book declined by 30% vs HY25. This reflects strong delivery on our DoW NG IHPS and ACH Gen II programs and improved commercial lead times which reduced the backlog of orders. Commercial orders have also been held back due to delays in government funding although there are signs that this is starting to ease.
Valuation:
The multiples here already price in some significant future growth:
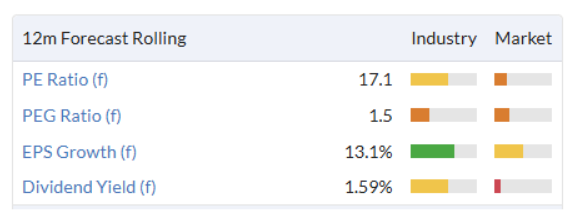
With no asset backing to fall back on, the investment case here lives or dies on them delivering that earnings growth. The defence backdrop should be supportive of this in the near-term, but as recent issues with governmental budgets in the US show, a desire to invest in defence doesn’t always lead to actual spending.
Mark’s view
Given the rating and drop in order book, I can see why the market has taken fright today. Significant future growth is already priced in, and while today’s results and outlook back that up, there is little room for error at the current earnings multiple.
I’m not sure I’m smart enough to judge how much of the current desire for increased defence spending by governments around the world will lead to actual increased spending. Nor judge whether that money will be spent on Avon’s products, or, for example, used to replace missile stockpiles that were expended defending against Iranian drones. So in the absence of any great defence industry insight, I am going to rely on the Stock Ranks:
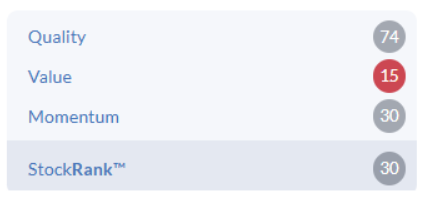
With the Momentum Rank of 30, and likely to drop further once the reaction to today’s results is processed by the algos, this is rated as a Falling Star. Since the shares peaked in the middle of last year, the Stock Rank has been declining:
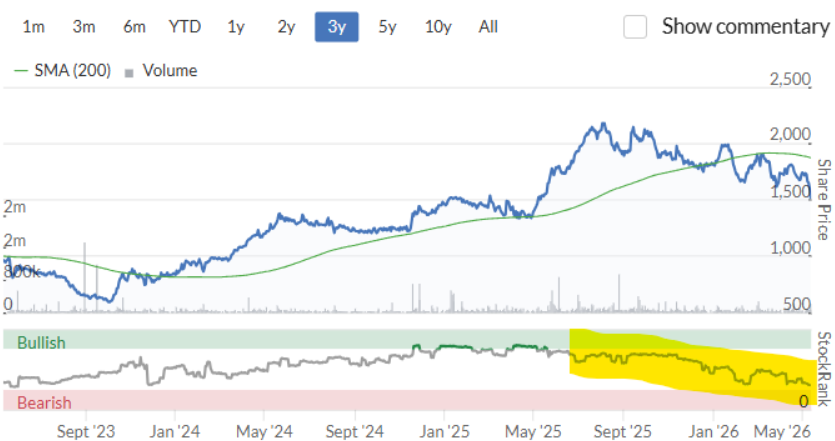
With a long way down before that Value Rank of 15 starts to provide share price support, I feel we should be broadly negative here. AMBER/RED.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

70 comments
TP Icap (LON:TCAP) have Stocko ratings:-
Quality 77
Value. 79
Momentum 86
StockRank 96????? How come?
There may be other weightings as the average isn't an exact ranking, but it is pretty close. The rank (if I understand correctly) is to split the population into 100 'bins' so if the average score (or whatever weighting that Stocko apply) falls into that bin, it gets that ranking.
So for the first 200 companies (from the download *.csv file)
Cheers!
Presumably because it scores highly across all 3 metrics (very few stocks manage this), which must put it in the top few per cent of stocks overall. It is not a simple average of the 3 metrics.
Ok I am intrigued what the back the truck price in Wise (LON:WISE) is? A random guess would be 20x but that's only because I have no idea how to value this longer term. Price to book and returns look way too high to me and I really don't believe in PEG or anything like that. I guess we won't see 800p but as its started life in the US so badly its anyones guess - happy to be guided higher.
Airtel Africa (LON:AAF) This is the result of today's Bharti party https://www.stockopedia.com/ne...
Future (LON:FUTR) interims tomorrow. Unless they hit the market with another profit warning, you have to say that the valuation is starting to get ridiculous. P/e of 2.7 and generating large free cash flow with good margins. 10% buyback and 6% yield. Priced like it’s going bust! It may be a value trap but even so a valuation of double where it’s at would be more appropriate!
Just as a general point - another "in line" engineer Spirax (LON:SPX) doing perfectly fine and a decent quality statement but shares off 2%. I don't own but it's on my industrial watchlist - rating probably a little high although I try not to let that put me off too much. I thought they seem to be doing quite well but with room to turn more negative...should the straight remain closed.
Re Vistry, I note that a lot of the comments reference profitability but none the quality of the accounting. From memory, due to the long term nature of their projects, Vistry use a form of contract accounting i.e. it makes subjective assumptions, whereas most housebuilders use accounting that is more cash based. The issue for Vistry is that it assumed a healthy housing market and reasonably benign costs, both of which have proven to be flawed, so the balance sheet position has deteriorated even more significantly than the headline figures might suggest.
Vistry (LON:VTY)
Re Vistry, I note that a lot of the comments reference profitability but none the quality of the accounting. From memory, due to the long term nature of their projects, Vistry use a form of contract accounting i.e. it makes subjective assumptions, whereas most housebuilders use accounting that is more cash based.
Great point Wilted sage and this point isnt highlighted enough on. I suspect vistry is very much then opposite of anice conservative company like Henry Boot (LON:BOOT) who hold alot of stuff at cost value - so balance sheet is understaing how well they are doing. any company where you can make subjective decisions its always potentially ahouse of cards that may come falling down. One thing you can be certain of is they are much more likely to over egg the situation than under egg it - it shouldnt be like that in a proper acounting world - but unfortunately the reality is it probably is. Thats without mentioning counterparty risk too ! - to be fair to them if there are bottlenecks in planning and the like but things are improving (if KS and RR do their job) - its plausible that it may simply be genuine timing rather than house of cards.
What's brought about the meteoric gain in AEP Plantations (LON:AEP) Up another 10% today ?
See that man Robert post?
Its the hedge against oil as well
Use of palm oil for biofuel?
The build target of 1.5 million homes over five years (effectively 300,000 per year) has shifted from a bold campaign pledge to what Angela Rayner now describes as a "stretching and momentous" challenge. As of May 2026, the progress report is a mix of aggressive policy overhauls and harsh delivery realities.
Current Status & Targets
Key Delivery Mechanisms
Primary Obstacles
Obstacle
Impact
Labour Shortage
Post-Brexit lack of skilled tradespeople (bricklayers, electricians) is the #1 physical bottleneck.
Mortgage Environment
High rates have dampened private sector "pre-sales," which developers rely on to fund new phases.
Nutrient Neutrality
Environmental regulations regarding water runoff continue to stall thousands of homes in the planning stage.
Local Opposition
Despite mandatory targets, many local authorities (including Labour-controlled ones) have labeled the new quotas as "absolutely impossible."
Market Sentiment
Confidence is "modestly growing" as of mid-2025, with a slight uptick in housing registrations in the North and South West. However, London activity remains depressed (down nearly 60% in some quarters) due to the complexities of the new building safety regime for high-rise blocks.
The consensus among analysts is that while the policy reforms (NPPF overhaul) are the most significant in decades, the 1.5 million figure is currently viewed more as a "north star" than a guaranteed outcome.
Mortgage sustainability has not been considered .Reported on a couple of names recently
Was this ChatGPT? Has it gone through a validation prompt / model council for accuracy?
I'd like to understand the indigestion of the Wise (LON:WISE) Wise (NSQ:WSE) move from a primary listing in London to New York. Shares are down 8% since. I think this business is one of the best growth opportunities on the market currently but surprised at the impact of the market move - AI puts it down to : Market analysts attribute this initial cooling-off period to a combination of transition costs related to the dual listing and conservative near-term operating margins forecasted for the 2026/2027 fiscal periods.
Wise (LON:WISE)
is it not buy on the rumour sell on the fact.
It often seems to be stated that simply moving listing to US will work wanders - often i think the reality is that some may have bought in on hopes of quickm gains - and if they are momentum traders they aint going to hang around.
Note i would say 5% variance on moving listing if its only a few days is surely to be expected - shares are most down this weak anyway are they not ? so could it not simply be market weakness.
Not sure why you expect quick gains lie aint like that - perhaps judge in 12 months time?
Not sure why you expect quick gains lie aint like that - perhaps judge in 12 months time?
I don't expect quick gains, just pointing out that the share price had been strong going into the listing change and since it is down quite a bit. I am not trading the share, so don't care!
Im also interested and can't add much - although I love this business as a customer Im less convinced as a shareholder. Obviously quite a lot going on - especially in the US with potential coins being issued which I think Western Union is tied into. Watching with interest...
"the share price had been strong going into the listing change and since it is down quite a bit".
That's quite normal.
Agreed bsharman I was surprised also. I've not listented to the 2.5hr presentation from yesterday but perhaps there was something in there which put investors off. I'd assume any buying and selling would cancel out? But perhaps there are some rules in place for people to drop any shares with a primary listing elsewhere, leading to shares being sold off.
Any reason for AEP Plantations (AEP) shooting up this morning 10%? I can't see any news
Just finished watching the Avon Technologies (LON:AVON) analysts meeting. Management as ever presented very well. Clearly the way Trump is manipulating US purse strings and tussling with Congress is giving hccoughs in order flow, but they are very confident in underlying demand. NPD is relentless, and they inceasingly confident in having developed product moats. They noted in passing that the US astonauts were wearing Avon's Team Wendy bump helmets after their rescue from the briny. The only explanation I can think of for the unwarranted negative SP reaction is that they are talking about building a platform for M&A - not just in adjacent or identical product areas, but "we believe we can improve any industrial business". Which might have spooked some. Looks like a buying opportunity to me.
Re: Vistry
The April S&P Global UK Construction Purchasing Managers' Index (PMI) was released last week and is reported upon in the BMN - link below...
https://www.buildersmerchantsn...
The BMN reports that the macro trend is downwards.
"The headline seasonally adjusted S&P Global UK Construction Purchasing Managers' Index (PMI) – an index tracking changes in total industry activity – registered 39.7 in April, down from 45.6 in March and indicative of a sharp fall in overall business activity."
If you have been following the index for the past 6 months or so it has been giving clear signals of an industry with headwinds, even before the inflationary effects of the Iran conflict.
Specific to Vistry, there have been press reports from a few months ago that it was discounting stock to achieve sales. There were also reports in the House that questions were being raised about the level of subsidies given to Vistry.
I am monitoring the housebuilding sector for a possible recovery. I don't think its likely to happen for some time and if it does I wouldn't be considering Vistry as a potential investment.
I take Intuitive's point and have my eye on buying into the sector for a trading opportunity.... it is a moot point how much lower share prices need to be. I have always been aloof to Vistry since to me it is accident prone ( you never have to wait long for yet another one....) and it is not hard to see a pretty poor macro outlook ( hence the type of margin squeeze which we are seeing) for housebuilders in the next few months on the back of inflationary costs for materials and further issues with affordability from higher mortgage rates. There are still plenty of people who will need to re-mortgage off fixed rates maturing this year and into 2027 and the impact of potentially higher interest rates from Middle East situation. Further pressure on affordability....
There are also higher building costs to come from the need for builders to upgrade specs for Solar Panels etc and whatever the new PM decides is right for one of Labour's flagship policies. I take Roland's point that a small position in the hope that Vistry news has ' bottomed out' provided it is run with a close eye on stop loss could be profitable. Not a recommendation I may add from me. Not my style
I suggest a new PM maybe more interested in ensuring affordable homes are the key driver of growth in housing supply and we all know housebuilders do not like these given the lower margins and impact on the value of land banks
Late RNS from Intertek (LON:ITRK):
https://www.londonstockexchang...
However, having carefully evaluated the Final Proposal, together with its advisers, and following significant engagement with its shareholders, the Board of Intertek considers that the financial terms of the Final Proposal deliver value in cash to Intertek shareholders at a level which it would be minded to recommend to Intertek shareholders
£60 a share, could have bought at £35 when they were on sale six weeks ago.
timarr
Vistry (LON:VTY) is yet another example of wasteful buybacks. When the buyback programme started the share price was around £7, and they’ve bought back regularly all the way down to current £3.25p.
It’s nonsense to describe wasteful buybacks like this as a reward to shareholders, or as returning money to shareholders.
Today they’ve announced they are pausing buybacks! If they wanted to buyback it would have been far better to start the programme now instead of wasting so much money on them (bearing in mind profits warnings and inevitable share price falls as a result) while they were buying back at inflated prices.
Are company boards expected to have a crystal ball of where their share price is going in the next X months, to inform buyback decisions?
Vistry (LON:VTY) did have a crystal ball as while they were buying back they issued a series of profits warnings. Yet even then they bought back regardless. Have a look at Next (LON:NXT) to see how buybacks SHOULD be done…..only at what they think are low enough prices.
Also Roland wrote this in one of his updates last September when the share price was over £6. After the update today it’s now down to just £2.95p.
“I’m also a little discouraged by Vistry’s decision to focus on buybacks rather than deleveraging. A strong balance sheet is never wasted and while I don’t think the company is in distress, there are still a number of calls on its cash flow that could lead to further pressure if volumes disappoint next year.”
Hope doesn't carry much weight in the financial world sorry to say. Some Directors hold a list of current directorships as long as you arm, how can they be expected to actually care about where the share price is going in any one of their companies?
Vistry (LON:VTY)
todays update is just rambling nonsense - really pathetic.
Its not a great combo though company with ever increasingly poor and tougher trading conditions thinking buy back is great. perhaps though we need to judge the buybacks 3-5 years down the line.
Most blasting buybacks pick frnanly ridiculously biased examples with then benfit if hindsight.
the simple golden rule is
if you pick company that has had buybacks and subsequently releases profits warnings or has poor trading - well buy backs are gonna look poor.
if you pick company that had buybacks and trading is picking up and they are upgrade expectations buybacks will look poor.
these silly examples of selective picking are blaming buybacks - when its simply a company delivering crapola news - it aint the buybacks that the problem here - trust me you have picked a company that has failed to deliver so buybacks will obviopusly not look good now
If future trading looks sketchy thats your clue that the investment may not be good - the buybacks are a complete red herring. I would agree its adding ton the problem if they are buying back then releasing later bad news - crystal ball they have not though.
Vistry has obviosuly gone through lots of woes last 18 months
birarrely after their rambling nonsense speech that our PM could have written the last line thankfully adds some clarity.
The Board expects adjusted profit before tax for FY 2026 to be towards the middle of the range of analysts' forecasts1.
Note it looks like profits are super back loaded and this company gives me zero confidence they are on the ball - is the market worried they are just delaying the profit warning and excuse for later - hell ya!!!
For my sins i bought in here as company is still projected to make decent profits and has great discount to NTAV - its not going well up till now though - serves me right for not waiting till there is "updward trend in future forecasts" and ignoring the red flags about managemnet being frankly hopeless - Life lesson at present beware the company that advises things are "broadly on track for now".
I've heard some scary stories about Vistry (LON:VTY) of late. Most recently, a payment of circa 2 billion for gov housing, promised by the government, being delayed until the end of the year. Vistry have been told to get their supply chain in line including paying them on time. Once they've addressed that they can come back at the end of the year with evidence and apply again.
Vistry (LON:VTY)
I've heard some scary stories about Vistry (LON:VTY) of late. Most recently, a payment of circa 2 billion for gov housing, promised by the government, being delayed until the end of the year. Vistry have been told to get their supply chain in line including paying them on time. Once they've addressed that they can come back at the end of the year with evidence and apply again.
thanks for that Dodds98
Vistry have already within last couple of years had to fess up for acountinmg issues internally - i was very unimpressed with managemnt blaming rogue regional unit - its their job as bosses to not let acounting fraud go on under thise noses and thats exactly what happened - being frank i am surprised any of the main team were allowed to remain in their job - we wernt talking about minor money.
Yep i hold small stake as a gamble and would have zero confidence that they are doing the basics right. Your comments tally in with the fact they have had to stop buybacks to conserve cash - from memory gearing here was pretty low when i bought - this one has as many red flags as your normal china day celebration unfortunately.
As a long suffering shareholder, I have previously expressed here my dissatisfaction with Vistry (LON:VTY) continuing to buy large amounts of share as the price kept rising, only to scale the purchases back when the price fell.
It's about time more companies followed the example recently set by Next (LON:NXT) , where their buybacks are subject to the constraint that the buybacks are typically executed with a minimum 8% Equivalent Rate of Return (ERR) requirement. If the share price exceeds the set limit for buying back shares in the market, Next has indicated it may return the remaining surplus cash via special dividends.
Apologies for your loss but the buyback isn't the fall guy here Im afraid. Blaming a buyback is like blaming a dividend for negative investment returns....yet the dividend has indeed softened the blow. All the companies in the sector are struggling - some more than others - yet the news flow is consistent across the batch. I know it isn't popular here to say this but what the shares actually do after a buyback really should not determine the decision. Returning money to shareholders is always accretive whatever happens to the stock afterwards. The issue with house builders is waiting for a recovery that has failed to materialise. I have no view on the Vistry (LON:VTY) balance sheet but that would be a fairer criticism if valid....not the direction of the stock.
As for assuming I hold and have lost money on Vistry (LON:VTY) . I don’t hold and never have,but if I had held I would have sold ages ago on the first iffy update or profits warning,
So “ Returning money to shareholders is always accretive whatever happens to the stock afterwards.”
Really?
As an investor who buys quality big dividend paying shares and Investment Trusts when they look to be at bargain prices and then holds long term as long as newsflow is good, I now hold shares that are paying as much as 35% a year in dividends. Lord John Lee adopted that approach for multiple years and now holds shares yielding him as much as 100% a year or more in annual dividends. That’s what I call “returning money to shareholders”. it’s REAL money unlike with buybacks where far too often there’s no reward for shareholders.
I luckily bought TP Icap (LON:TCAP) at just over £1.The current yield is a useful 6%, but for me the yield is 18%.
As others have posted, see how Next (LON:NXT) approach buybacks. They do it correctly and in their case shareholders have been genuinely rewarded. But for every NEXT there are dozens of Companies wasting money on buybacks.
Is it better to look at actual examples like these instead of just swallowing the convincing sounding case for them?
Well the accounting for the buyback is to credit cash and debit shares with are either cancelled or held in treasury. They are not an investment by the company - with a reduced share count the earnings improve. Of course, with share prices as low as possible enables more shares to be cancelled but as others have pointed out no-one has a crystal ball. The advantage of a buyback over a dividend is firstly, it's much easier to walk back from should trading deteriorate and secondly tax, for holders this is better. You can chose to take part or not, by selling some stock but the eps impact is mathematical and not affected by future direction of shares nor your decision to participate. The problem with Vistry (LON:VTY) is trading is poor.... and I am not disputing your investment strategy just defending buybacks since I think they get unfair bad press in popular media and here. It is always in shareholders interest for there to be as few shares in issue as possible...I don't think that is the debate. And to answer the question - yes really! the maths of the buyback is always accretive. It's just maths.
Vistry (LON:VTY)
As for assuming I hold and have lost money on Vistry (LON:VTY) . I don’t hold and never have,but if I had held I would have sold ages ago on the first iffy update or profits warning,
This was company projected to make £200 mil profit with great discount to NTAV - imho there was plenty of room for trading to be "poor" and the value still to out later on in theory - its pretty clear to me their is a will for them to be providing their necessary services. well thats how it looked when i purchased. I only had a small punt though - the clues were their ref their inability to add the numbers up previously. all they needed to do was have no nasties concentrate on making something close to projected profits - are they still on track - perhaps but i have little confidence in the board now - more the fool for buying in here due to the numerous red flags.
"I now hold shares that are paying as much as 35% a year in dividends. Lord John Lee adopted that approach for multiple years and now holds shares yielding him as much as 100% a year or more in annual dividends."
Ken, whilst I very much appreciate your contribution to Stockopedia boards and I read all posts, I do not think it is right to repeatedly talk of yield on cost. Holding period, inflation, currency debasement and opportunity cost are just some of the factors that need to be factored in. For most of us, I would think yield on capital tied up (current value) was a much more relevant consideration (when considering yield).
If you had bought Venezuelan shares 25 years ago the yield on cost would be astronomical (and would eclipse Lord Lee's figures of over 100% many times over). Although this might be of some interest/emotional satisfaction, I would suggest it is misleading and that your original cost is a historical fact and capital allocation decisions/reviews should depend upon the current value of the asset and the available alternatives.
This is a good point Willinvest. I also appreciate Ken's contributions but he does have a somewhat irrational dislike of buybacks despite seemingly not able to grasp that over the *long term* these are a good way of increasing shareholder returns, especially if a company is trading below its NAV. Future EPS increase even if profits remain the same as they are spread over fewer shares. Like I said before dividends offer immediate gratification but buy backs can take a much longer period to impact the valuation - this is where examples of companies buying back now but their shares are lower than the buyback are missing the point. It is where the shares will be in the future that matter - 1-3 years after the buybacks. Using the yield on cost - I have traded something like TP Icap (LON:TCAP) over the years and my "average price" is 15p, They pay a 17p dividend, so my yield on cost is 113%!
While I prefer dividends to buybacks I do not dislike all buybacks. My posts make it clear I’m not against all of them. e.g Next (LON:NXT) .
Replies from posters disagreeing re buybacks like those from Vistry (LON:VTY) never try and explain why I’m wrong with that example but just trot out the convincing theory that is convincing. I prefer to look at what actually happens rather than just using the theory to make the general case for them.
Ken RE Vistry (LON:VTY) - buybacks are accretive because they are trading at a massive discount to their NAV.
1. The Mathematical Case for NAV Buybacks - When a company buys back its own shares at a steep discount to NAV, it effectively purchases assets for pennies on the pound, which mathematically boosts the value of every remaining share.
Also, you are only considering very short timescales, rather than looking to see the positive impact of share buybacks over the longer term. When the housing market finally recovers, EPS will rise at a faster rate due to the buybacks. So what you see as a waste of money now may be a great move in 18 months time?
I agree that a buyback only rewards shareholders *if and when* the market eventually recognises the underlying value. If the market chooses to permanently derate the sector, that cash spent on buybacks is gone forever. A dividend is a bird in the hand. But are you saying that Vistry (LON:VTY) will never recover?
Having investigated a bit I came across this:
The S&P 500 Buyback Index: Long-term historical data from S&P Dow Jones Indices demonstrates that the S&P 500 Buyback Index (which tracks the top 100 firms with the highest buyback ratios) consistently beats the broader S&P 500 and outpaces high-dividend-yield indices over 10- and 20-year trailing periods.
Vistry (LON:VTY) needs to get the balance right between making sure the balance sheet is strong enough to trade through this difficult period and buying back its shares for the reasons above. Hope this addresses your comment about not explaining why you are wrong on Vistry (LON:VTY)
Hi Ben
Re Vistry (LON:VTY) I think the recent buybacks have been incredibly irresponsible when taken in conjunction with the deeply uncomfortable levels of average indebtedness at a time when their end markets are under pressure from cost inflation & deteriorating affordability/consumer confidence in the non partnership sector. In the partnership division they are effectively offering fixed price transactions in an environment where lead times are long and cost inflation is a real pressure …the departure of the architect of this business model amidst the aftermath of an accounting scandal doesn’t fill me with confidence either.
I believe there is a major risk of a material covenant breach as these chickens come home to roost and only a lifeboat heavily discounted equity raise will avoid insolvency in those circumstances.
The discount to NAV is a moving feast as land/housing market conditions vary over time and won’t necessarily help solve a liquidity crunch in a tough housing market.
Best of luck with your shareholding irrespective of my jaundiced view of the investment case.
Thanks for trying! Unfortunately I don’t accept that theory as there are so many examples of Companies seeing huge share price gains without any need to waste money on buybacks at inflated prices that start at £7 and end at £3.
Just one such example is Games Workshop (LON:GAW) which I bought a few years ago at £4.60 and then sold far far too early. It’s now £194, and nearly 50 times higher. Also GAW has paid £8 in dividends since the start of 2025. That getting on for a 200% dividend yield at the £4.60 buy price.
Here’s their take on buybacks:-
“Based on available financial reports and news up to May 2026, Games Workshop has not engaged in a share buyback program. [1, 2]Instead, the company focuses on returning cash to investors through high dividend payments. [1, 2]
The company's shares have been performing exceptionally well, hitting record highs in 2026 and being promoted to the FTSE 100 in December 2024. [1, 2]”
I don't really agree with these cherry picked examples. Of course you're correct that some buybacks in hindsight prove to be wasting shareholder value. But no one has a crystal ball and you also need to allow way more time to see if there judgement proves correct. Unsurprisingly no one is able to predict short term moves. Buybacks have been very successful for many companies, especially in the US where the worlds largest companies have usually gone with buybacks over dividends, and are proof that it does work when a company performs well over a long period. The example of Games Workshop is a poor one imo. What would the share price be had they done buybacks instead of dividends. The share count would have come down and the shareholders relative value (EPS) would have been compounded at a much higher rate. Sure you can re invest divs, but many people don't, and buybacks capture that value for those that don't re invest divs. I feel like your comment assumes that the share price would be the same today had they done buybacks not dividends, but obviously it would be materially higher. Nb. Its also easier in regards to taxes. Just my opinion. I very much like reading your contributions but feel you are too selective/ bias with your examples when it comes to buybacks.
I agree. I think Ken has a fundamental dislike of share buybacks and no arguement will persuade him that they can be positive (except Next). He seems to think in the majority of cases they are a waste of capital and uses a handful of examples to prove his point. In the case of Games Workshop - Like you say, how does he know where the share price would be if the company had bought back shares rather than pay dividends!? The maths works if a company is trading below its assets if it has a strong balance sheet. I don't think anyone will be able to change his mind!
Ken is simply pointing out the flip side ref share buybacks - to provide soem rebuttal to those dissing sharebuyacks - evidencing how they do work in practice makes sense to me - key is always investing in a good business though not a shit one.
I do think that some people simply think "sharebuybacks almost never work" - its kinda annoying when the chirp up - pick a biased example and ignore the fact that when its done in a good company they are great (sometimes tehy need to be given time to work their magic - hopefully thats the case with spoons at present)
I have to agree with Ken. My investment style is very different, but IMO his views on share buybacks are solid. Timmar did a very balanced post on share buybacks a while ago - this is one of the best posts I have read in a while. Aswath Damodaran has done a few youtubes on dividends vs. buybacks which are also excellent.
My tuppence worth...
I dont think that there is any argument on the objective equivalence of share buybacks vs dividends, just the increased opportunity for management misuse of shareholder money. Any DCF valuation has to make the assumption that someday the management has the intention to return capital to shareholders, even if this is unforeseen at the present. Any deviation from this becomes what I like to think of as 'financial casuistry'.
You have to believe that the company is better at investing YOUR cash than you would be able to in order to accept that buybacks are a better choice.
If there was a true 'valuation' argument in share buybacks then the amount bought would be proportional to the value below a nominal 'fair price' - which I have not seen done - just companies jumping aboard a fashionable trend.
Wasn't there a scrip dividend available in the past ? Where investors could opt to receive more shares rather than their dividend - this would get around the tax advantage (which to me is used as a lever for management to pursue their preferred option of buybacks).
If we are talking about examples, the most prominent for me is Michael Burry's post about nVidia share buybacks (Nov 2025)
$205bn net income & $188bn of FCF
'But it bought back $112.5bn worth of stock and there are 47million MORE shares outstanding'
I dont think that there is any argument on the objective equivalence of share buybacks vs dividends, just the increased opportunity for management misuse of shareholder money. Any DCF valuation has to make the assumption that someday the management has the intention to return capital to shareholders, even if this is unforeseen at the present. Any deviation from this becomes what I like to think of as 'financial casuistry'.
can one not argue that with dividend tax increases sharebuybacks probably trump dividends
i just dont get the argument against - if an onwer thinks the share is expensive and buybacks arent good value - the easy solution is to sell and move on. if share is good value then why wouldnt you want to have a bigger slice of the pie
'But it bought back $112.5bn worth of stock and there are 47million MORE shares outstanding'
well american tech companies that remunerate via issuing shares are a compeltely different beast - zero relevance to your average uk listed company - t- hey spoons hand out some shares to staff eaach year but thats fine by m
When you say there are 47 million more shares os - my google check suggests there has been slight decline each year for last 4 years - not materiaL
https://www.macrotrends.net/st...
Hi Ken and all other interested investors - Buybacks
The depth of feeling here sounds like Ed C ought to put one of his team on preparing a "learning" presentation on Buybacks !
Perhaps there ought to be twice as long put aside for questions as the presentation itself
The Naked Trader Radio Show is live today from 9am - 10.30am
Lots of today's companies covered .. trading ideas.. plus your trading songs. Text or whattap 07950028120 with your favourite share and why or email robbiethetrader@aol.com
If you miss it it will repeat 24/7 afterwards
To hear the show use your PC, laptop or phone and click here:
https://fast.citrus3.com:2020/...
Remember to press the play arrow symbol.
great news - I'm in need of cheering up
Hi Robbie Good to see you here as your book was my first quideing influence and know how base when I was still green so I must express my thanks here and now.I cannot remember which edition it was but I am sure that the hardback version now has a considerable additional value to collectors as well.May I ask if you have since dived into it for a bigger splash? Rob
Restore (LON:RST) didn't get much attention yesterday as "only" inline but rhetoric pretty robust actually. Think recent acquisition Synertec is going quite well and at the recent results presentation they were pretty upbeat for this to positively move growth forward and their ability to acquire more. Net net (I own) I think Restore (LON:RST) is sitting a little better than inline and hopefully can beat expectations later in the year. I don't expect much impact from Middle East so this little business is attractive enough and cheap enough to do ok for me.
Yep, I concur fwiw. Easy business to understand too, ex div soon also
Sir Starmer making the Liz Trust Government look like a picnic.
I would have expected more trouble if Process Man had been ousted to be replaced by the Vape Dragon or the Little Weasel! Gilts it was then....thanks!!
Oh get off the anti Starmer bandwagon. The guy has served 2 years and was elected to serve for at least 4 years. Judge him then and vote for whoever, but all this griping is getting us nowhere.
if his actions are pushing up the rate of interest we need to pay on our national debt are you happy to give him two more years if that creates £50 billion a year black hole on top **- before someone who can sort out finances takes over? Liz Truss was rightly removed when it was clear she couldnt sort the finances out
. We need leaders who can command respect of the debt markets imho. I would agree that temporary spikes can perhaps be ignored - but i doubt the majority of his own party supporrt him now ?
if his own party dont trust him why should we trust the guy. I wanted the last lot our but its clear Starmer and his team have been an abject failure up till now on every level - they seem to be utterly clueless.
** the worst thing about labour is they tried to lay full blame on the conservatives party ref debt projections when they first took power - its ridiculous double standards if they start blaming stuff beyond their control now when they shouted from the rooftops that similar situation was the fault of prior leaders.
I dont want to jump on the bandwagon - but it seems 100% clear cut hes toast medium term - bookies confirm its more likely than not he will be gone before october - never mind getting to next election !
Yes he will be gone with so many people out to get him, he hasn't got a hope of staying in office. There isn't much space in politics for decent people like Keir Starmer. I hope he does stay and fight though and doesn't make it easy for all these bullies and turncoats.
I was looking for the Dead Man Walking whispers as he passed through the malarkey of today on TV. On a market view he has to stay strong
Babcock International (LON:BAB) read ok to me - possibly better than BAE Systems (LON:BA.) but shares are -30% from the peak and making relative lows. Not cheap by traditional measures but looks healthy to me, and no longer fashionable. Seems worthy but needs to exit the positioning reset following optimistic view of Iran and Ukraine settling.
Whilst the possibility of some kind of settlement in these wars will take some froth of defence co. share prices, we're seeing the realisation that governments that talked big on defence spending haven't yet shown the money to deliver. Also, there is the growing realisation that much (not all) future defence will rely more on drones, satellites, optics etc. The traditional defence cos are not much into this, and it will be a while before BAE, for example, has a big enough presence there to move the bottom line.
The big money with these guys was made in 24 and early 25. In 26, the decline has been relentless, and not just in the UK. High flyers like Rheinmetall, Saab etc have lost 20/40 % since January.
This is probably part of the reason for Seraphim Space's success. They're about future defence at least as much as space itself. There is also the much overlooked ETF, "VanEck Space Innovators", which has doubled in 12 months.
Ignore.
What did I miss yesterday that resulted in my portfolio taking a 3.5% nosedive?
Probably Starmer and gilt yields rising.
It was a sea of red yesterday. US indices were also down slightly - presumably with the cost of oil remaining high.
What did I miss yesterday
6 profit warnings - pm being sacked - trumps peace deal lookier dodgier than our next pm - oh and the relavation that Greggs is a basket case investment due to some new sketchy slimming product. Must admit i check out at 12.29 pm what happened in ten afternoon people did i miss anything ?
I think the higher than expected US inflation was the biggest factor - led to a sell off in US markets although they later recovered somewhat by the close