Daily Stock Market Report (Fri 19th September 2025) - FUM, SPI, IGG, CNC

Good morning and welcome to Friday's report!
The agenda is now complete.
Update: 10.15: it's a quiet news day today so I am wrapping up the report there. Graham will be back with you next week.
Spreadsheet accompanying this report: link (last updated to: 5th September).
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Vodafone (LON:VOD) (£20.3bn) | Vodafone and Digi Romania have entered into an agreement to purchase assets worth €30 million from Telekom Romania. | ||
Investec (LON:INVP) (£5.3bn) | H1 2026 trading shows earnings are broadly in line with last year, with headline earnings per share expected to come in around 35.2-38p. Share buyback programme ongoing and steady progress in both the South African and UK markets, despite macroeconomic challenges. | ||
IG group (LON:IGG) (£3.8bn) | Acquisition of Independent Reserve / Update on Revised Customer Metrics | IG acquires Australia’s Independent Reserve for A$178m, or £86.8m to accelerate Asia-Pacific crypto expansion. / IG Group revises customer metrics from Q12026 onwards, introducing funded customers and aligning active and first trade definitions across products. Trading update confirmed for release on 25th Sept. | GREEN (Roland - I hold) Today’s acquisition looks expensive upfront at 5x trailing sales and 18x EBITDA. However, Independent Reserve does seem to have some attractive characteristics, in particular a very high revenue per customer figure. If recent growth can be maintained this could prove to be a value-additive deal, but I don’t have any way to judge how likely this is. Fortunately this purchase is comfortably affordable for IG and we know from recent results that the group has had good momentum this year. I am going to leave our positive view unchanged today ahead of a trading update later this month. |
Kainos (LON:KNOS) (£1.06bn) | Kainos acquires Canadian consultancy Davis Pierrynowski, expanding Digital Services in Canada. Adds 120 staff to support digital transformation across healthcare, government and community organisations. | ||
Spire Healthcare (LON:SPI) (£872m) | Confirms has engaged Rothschild & Co as adviser and has begun a process to hold preliminary discussions “with a number of parties” relating to a range of possible options, including a sale of the company. | PINK (AMBER) (Roland) [no section below] In today’s statement, Spire’s management complains that the operational progress being made by the company and the value of its “freehold property and well invested asset base” are “not yet reflected by the market in full”. In other words, they think the share price is too low. Checking the latest accounts shows freehold property with a book value of c.£640m, which management says is valued at “<£1.4bn” – quite possible if the property is held at cost on the balance sheet. This looks significant relative to the market cap of c.£850m. However, as a business Spire seems to have very average profitability, with return on capital employed of just 6.4% on a trailing 12-month basis. Return on assets is c.1% according to the StockReport. I’d suggest this low profitability may be one reason why the share price isn’t higher. Operating margins are under 10% and it doesn’t seem like Spire is generating much value from its properties. The other potential concern for me is debt. Net bank debt was £357m (2.2x EBITDA) at the end of June and the group also had £915m of lease liabilities. The debt was agreed in Feb 22 and is currently being refinanced (so presumably interest rates will rise). The balance sheet also shows a net lease liability of c.£270m, perhaps suggesting that some of Spire’s properties are loss making. Given that finance costs accounted for 68% of operating profit in H1, I think group’s overall debt and lease obligations could continue to limit profitability and cash generation unless margins improve. Spire’s earnings are forecast to rise sharply in 2026, so perhaps management is right to hope for a re-rating. However, until there’s more evidence of this, my feeling is that the business looks quite fairly valued. We’ll have to see what the market thinks, but I’m going to echo the StockRanks and take a neutral view today. | |
Close Brothers (LON:CBG) (£748m) | FY25 results delayed by 7 days to 30 Sept due to request for additional audit time. | ||
Henry Boot (LON:BOOT) (£264m) | Developing Duxford AvTech site to develop low and zero carbon aircraft technology at IWM Duxford | ||
Concurrent Technologies (LON:CNC) (£192m) | Provision of design services to major US contractor over 2025/26. First time selling design services. | AMBER/GREEN (Keelan) Concurrent Technologies has secured a $5.25m US defence design contract, marking its first move into outsourced design services and strengthening ties with a major US prime. This comes on the back of a record £4m UK contract and the launch of Bragi, its first AI-focused GPU, earlier this month. Broker Cavendish sees further upside, but keeps its price target at 256p. While the shares look a bit pricey at around 30x earnings, execution has been impressive, and the pipeline suggests there could be more to come, which is why I’m giving it an AMBER/GREEN rating. | |
Life Science Reit (LON:LABS) (£139m) | Following review and sale process is planning a managed wind-down over 12-18 months. | ||
Skillcast (LON:SKL) (£51m) | Rev +43% to £529k, Q1 26 rev +143%. Op loss reduced to £6.1m. £328k cash at 31 March. | ||
Insig Ai (LON:INSG) (£29m) | Rev +43% to £529k, Q1 26 rev +143%. Op loss reduced to £6.1m. £328k cash at 31 March. | ||
Futura Medical (LON:FUM) (£27m) | FY25 rev to be materially below exps, at £1.3-1.4m. Eroxon sales below exps, $2.5m payment from Haleon delayed as patent claim not yet approved. £2.7m cash expected to provide working capital to Jan 26. Exploring funding options and carrying out “significant restructuring”. | RED (Roland) [no section below] The company is warning that it only has sufficient cash until January 2026 – and even this is “subject to a number of variables”. It's also trying to raise funds. It’s an automatic RED from me, as it looks like there’s a significant risk to equity here. | |
Predator Oil & Gas Holdings (LON:PRD) (£23m) | Report and Interim Financial Statements for the 6 months to 30 June 2025 | First oil revenue of £66k in Trinidad. H1 net loss £1.6m, cash balance £2.6m. | |
GEO Exploration (LON:GEO) (£20m) | Drill hole JUD001 complete at 810m. Expect assay results in Q4 2025. JUD002 now underway. |
Roland's Section
IG group (LON:IGG)
Down 1% at 1.094p (£3.8bn) - Acquisition of Independent Reserve - Roland - GREEN
(At the time of publication, Roland had a long position in IGG.)
IG is acquiring Independent Reserve, “a leading cryptocurrency exchange based in Australia”.
The total consideration for the deal is A$178m (£86.8m).
In fairness, I don’t know that much about crypto and I have never heard of Independent Reserve. But my first impression is that this is a relatively expensive purchase, priced on the hope that Independent Reserve’s recent rapid growth can continue.
Here are some key metrics we are given about the company being acquired:
Independent Reserve has strong growth momentum, with revenue in the 12-months ending 30 June 2025 of A$35.3m (£17.7m), increasing 88% on the previous fiscal year and representing a CAGR of 70% over the prior two years. Approximately 76% of revenue was generated in Australia and 24% in Singapore. EBITDA in the 12-months ending 30 June 2025 was A$9.9m (£5.0m).
Based on this, today’s purchase price represents 5x FY25 revenue and 18x FY25 EBITDA.
Naturally, these figures could rise if revenue growth continues at a CAGR of 70%, but how likely is this? I cannot say.
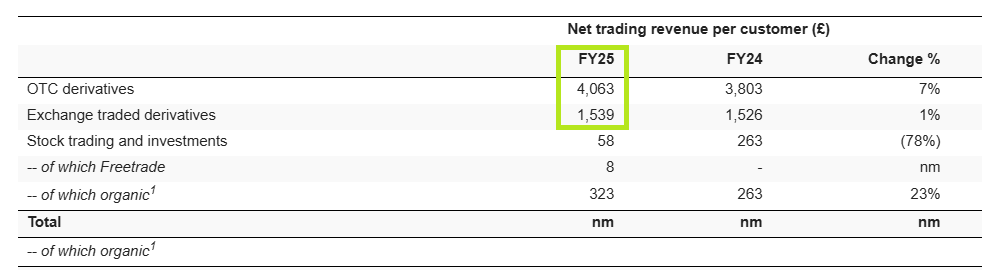
We’re told that Independent Reserve had c,11,600 active monthly customers during the 12 months to 30 June. This implies each contributed just over $3,000 of revenue during the year – that’s potentially attractive and is comparable with the revenue per customer generated from the group’s core OTC derivatives (spread bet/CFD) and options trading (exchange-traded derivative) customers:
Purchase terms:
Fortunately, IG does seem to have engineered some caution into the payment structure for this acquisition.
Initial acquisition of 70% of Independent Reserve for £53.4m
Additional payment of £7.3m is contingent on FY26 performance
Call option to buy remaining 30% stake with a valuation based on performance in FY27 and FY28
In the meantime, the current leadership team and employees will remain, owning the the outstanding 30% stake and presumably motivating them to continue growing the business:
The leadership team and employees will remain with Independent Reserve, and retain a collective 30% shareholding at completion, bringing strong crypto-native expertise to lead future propositions at IG.
Crypto progress:
IG says this acquisition complements the progress it has made with its crypto offering in the UK and US under CEO Breon Corcoran.
UK:
In the UK, the Group launched spot crypto trading in May 2025, becoming the first UK-listed company to provide the product to retail investors. Launched in partnership with Uphold, the offering includes 35 coins and is fully integrated across the IG platform and IG Invest app.
US:
In the US, tastytrade has expanded its product range to 23 coins and enabled stablecoin account funding for investors across multiple blockchain networks. This innovative funding method allows tastytrade customers around the world to fund their brokerage accounts with stablecoins, 24/7/365, powered by Zero Hash, the leading on-chain infrastructure provider.
Roland’s view
I think IG can easily afford this purchase and it could be a logical addition to its offering. Crypto appears to have become a mainstream asset class, especially for speculative traders.
I take some reassurance from the high revenue per customer and existing profitability of Independent Reserve.
However, there’s no doubt this deal could turn out to be quite expensive, if Independent Reserve’s growth slows for any reason – or if market conditions change.
Graham was GREEN on IG Group when he reviewed its full-year results in July and covered the company in more depth in a Stock Pitch article last week.
Obviously I am biased as a long-term shareholder, but I am also a fan of this business, which is currently benefiting from strong market conditions thanks to the elevated volatility that’s been seen this year.
I don’t see any reason to change Graham’s positive view today – with a trading update due on 25 September, I think it makes more sense to wait until then to consider refreshing our view.
Keelan's Section
Concurrent Technologies (LON:CNC)
Up 1.68% at 225.7p - $5.25m US defence contract secured - Keelan - AMBER/GREEN
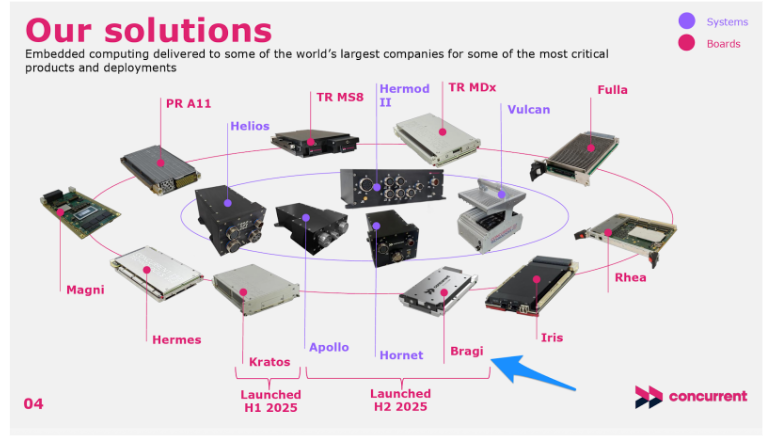
Concurrent Technologies is a UK-based designer and manufacturer of embedded computer systems, supplying mission-critical computing platforms to defence, aerospace, and industrial clients. Whether it’s powering sensor systems, drones or complex communications gear, its systems are designed to work flawlessly in critical conditions.
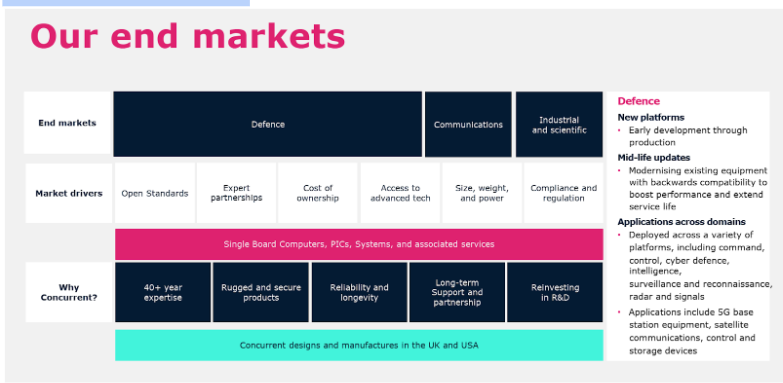
Source: Concurrent Technologies H1 2025 Results presentation
The company announced this morning that it has just secured a $5.25 million design services contract with a major US defence customer. This is a significant win for the business. It’s the first time the customer has outsourced the design of one of its own computing products, and the first time Concurrent will be delivering a fully external design service. The contract runs through 2025 and 2026, and it's a clear sign that the relationship with this US prime contractor has deepened.
This deal reflects trust and also a strategic shift. More and more defence primes are outsourcing hardware development to focus on their core systems and software. Concurrent is now well placed to benefit from that emerging trend, especially as a principal member of the SOSA (Sensor Open Systems Architecture) consortium, which is helping standardise these types of platforms.
CEO, Miles Adcock, commented on the update: "We are well positioned to benefit from the growing trend of outsourced hardware development, and this contract provides a valuable opportunity to assess the potential of design services as a future line of business."
The announcement comes after a busy month for Concurrent, having delivered strong H1 results earlier this month.
Broker Cavendish, which acts as house broker, described the contract as a “substantial new area of business”, but kept its price target at 256p, implying a further 13.2% upside from current levels. The broker does expect the company to now beat current market forecasts, though, and says forecast risk is now very much to the upside.
Moving beyond product sales
This latest contract suggests Concurrent is moving up the value chain. Rather than just selling its rugged computing hardware, it is now designing core products for major customers. That opens up potentially higher-margin work, deeper customer integration, and longer-term stickiness.
This contract could pave the way for broader revenue streams, especially as defence primes shift toward open standards and start outsourcing more of their hardware development. Concurrent has spent four years building credibility with this US customer, and this deal shows that work is starting to pay off.
This move into design services won’t replace the core products business, but it could significantly boost the company's long-term addressable market.
A strong operational year
Financially, things are already trending in the right direction. Revenue is forecast to grow from £40.3 million in 2024 to £66 million by 2028, with earnings per share climbing steadily from 6.8p to 10.2p over the same period.
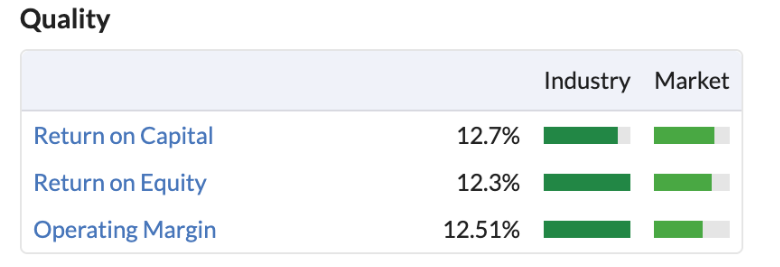
Profitability is robust, with returns on capital now at 12.7% and rising. The business remains cash generative, although free cash flow has been a little volatile due to working capital changes and investment in growth. Free cash flow is forecast to rise steadily over the next three years, reaching £6.6 million by 2028.
Momentum is firmly on the company’s side, with the company’s share price rise having outperformed the FTSE All-Share by 72.3% over the past year, and trading near 52w highs.
Valuation: pricing in growth
At around 226p, the shares trade on a forward P/E of 29.5 and an EV/EBITDA multiple of 21.7. That’s not cheap, even when compared to other UK industrial or defence names.
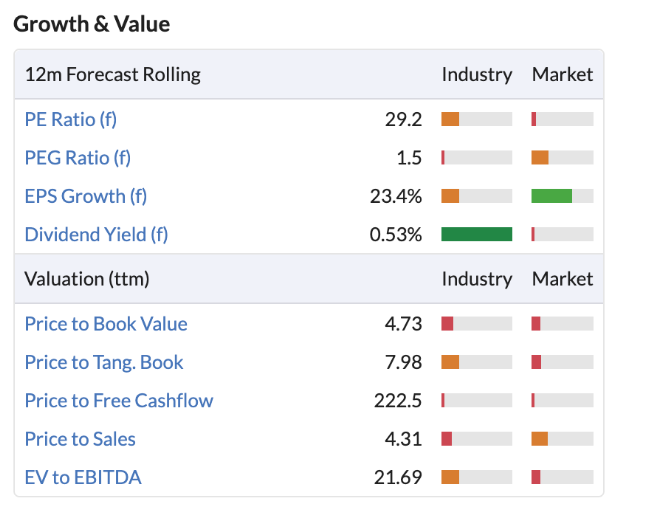
The current valuation is being supported by the business delivering on growth and maintaining margin progress. Should that continue, investors may be willing to look past near-term multiples, but there is a degree of execution risk here.
Recent catalysts
On top of the US contract, Concurrent has had a busy few weeks. It recently launched Bragi, its first general-purpose graphics card powered by NVIDIA’s latest Blackwell architecture (which is one of the most advanced GPU chips to date). Developed in partnership with EIZO Rugged Solutions, Bragi is designed for high-end AI and edge processing applications, plugging in directly into Concurrent’s modular systems.
Source: Concurrent Technologies H1 2025 Results presentation
At the start of September, the company also landed a £4 million UK defence contract, the largest in its domestic history.
Cavendish summed up these contract wins well in their note this morning: “This new contract follows a record 1H25 order intake of £22.3m, up 25% on 1H24 and 2H25 despite slower orders from the US market. 2H25 has already seen the group’s largest UK design win (£4m) announced on 4 September and the US market is expected to see orders accelerate throughout 2H25 following the passing of the One Big Beautiful Bill Act in July”
Keelan’s View
Concurrent seems to be firing on all cylinders. In the past month alone, it has delivered two major contract wins, a new AI-ready product, and record interim results.
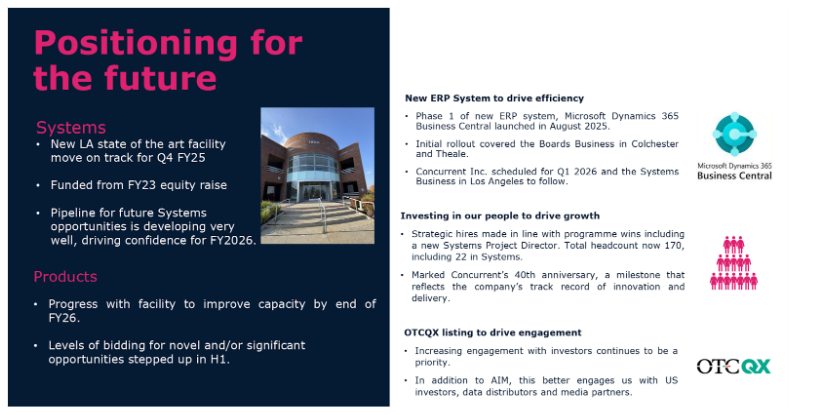
The balance sheet remains solid, with no debt and healthy cash reserves. Investment in capacity continues, including an expanded UK facility at Colchester to help scale manufacturing, while the move to a larger site in California should support US growth, particularly for systems integration.
Source: Concurrent Technologies H1 2025 Results presentation
The only real hesitation I have is around valuation. At around 30 times earnings, the shares are not obviously cheap, though, for a comparable business listed in the US, I probably wouldn’t think twice. That’s the disconnect. If Concurrent keeps up this pace of innovation and contract wins, brokers may need to lift their forecasts quite soon, especially seeing as Cavendish’s 256p target already looks within reach.
There are definite echoes of Journeo (LON:JNEO) and Filtronic (LON:FTC) here, UK-based small-caps that are executing smartly in a specialist niche and steadily growing their global base and revenues with notable contract wins. For now, I’m rating this AMBER/GREEN.
The delivery from management has been excellent so far. If execution continues, and the design services side starts to show repeatable traction, this could tip into green territory.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

41 comments
Over time there are many observations on here that put a finger on what a government that was concerned about growing UK business should know and understand. This and (not too many ) others should be part of the government’s knowledge base regarding the public companies of the UK.
So here is a challenge: if you, the reader, are in an executive position in the relevant government departments that say they are concerned about our economy, then let us know by replying to this comment. Better still if you are Jonathan Reynolds (since 5th September the responsible Minister - keep up everybody!).
Somero Enterprises (LON:SOM)
Regent up to 10% now……….
I do not hold but Somero Enterprises (LON:SOM) will be acquired by them.
All the best
Gulf Keystone Petroleum (LON:GKP) - for those awaiting news on the re-opening of the Turkish pipeline this was issued an hour or so ago BAGHDAD, Sept 19 (Reuters) - Iraq, OPEC's second-largest producer, has given preliminary approval to a plan to resume pipeline oil exports from its semi-autonomous Kurdistan region through Turkey following delays to a hoped-for restart, sources familiar with the talks told Reuters.
Gulf Keystone Petroleum (LON:GKP)
One of my favourite cash cow stocks.
Too much personal interests from the two corrupt governments involved that I can never see this pipeline reopening. Iraqis make no effort for the Kurdish people to get paid on a regular basis. Shame.
Similar announcements on a daily basis…….
All the best
Focusrite (LON:TUNE) is now up around 25% this week after reassuring update. Surprised this has had so little coverage or comment on here. I bought a few weeks after the good update from Gear4music (HOLDINGS) (LON:G4M) I took this as a positive sign that the sector was finally turning a corner after the post Covid hangover. If TUNE gets anywhere close to its earlier valuation then could have a long way to run
I commented on Focusrite (LON:TUNE) when they issued their update, but no follow ups were forthcoming!
Like you, the good news from Gear4music (HOLDINGS) (LON:G4M) I thought was a signpost to improving fortunes for Focusrite (LON:TUNE).
However, I sold out, along with most of my other non income UK stocks yesterday. I'm going away for a week or so and didn't want to get caught out by any government inspired bad news, which never seems far away.
But I will re-assess upon my return.
Hi
A Friday type post, to offer food for thought and provide some insights into the changing landscape in the UK.
The theme is UK as an AI superpower and some aspects of the important inward investments the imitative might bring.
This 6:21min vid from Bloomberg with GM for International from CoreWeave (NSQ:CRWV) surfaces multiple points of interest.
CoreWeave (NSQ:CRWV) already have two data centres (DCs) operating in the UK.
This vid explains a new build out they are doing in Scotland. In order to tap into sensible locally provided energy to power the DC.
It is an example of private investment working in conjunction with local UK resources plus UK gov. to elevate the UK's capability on several fronts. Elevating better energy supply, private capital uplifting UK Plc, laying foundations to support the UK to keep pace with global AI, bringing the vey latest AI tech. into Britain.
As Jensen CEO of NVIDIA (NSQ:NVDA) stated at the Trump state visit, this drive to build AI leadership in the UK will not only support the UK to remain a player in AI (we are third most capable behind US and China) but it will offer many jobs for years to come. IT professionals, but also electricians, carpenters, construction works, energy professionals, tech, equipment providers, etc ...
If you are interested here is the 6 min vid.
(I hold CoreWeave (NSQ:CRWV) and several other AI related stocks).
Regards
Howard
I also hold CRWV. The idea that the UK could be a 'superpower' against those 2 seems optimistic to me. We can get jobs and crumbs but no leadership. The UK companies would have to identify niche areas where they might identify comparative advantage? Not the bits the others have discarded (carbon capture?). Trouble is the substack debate on this always seem to see Iqe (LON:IQE) as an advantage!
Hi snowdrop
Indeed the UK will and is getting crumbs as you put it. But in my view our economy's malaise is great and likely to get worse. So I am glad of, not the crumbs, but rather some flour and water, as ingredients to join together and hopefully evolve into something with a bit more substance and appeal.
I believe in the UK we have much to offer the global AI industrial revolution - world class engineering, IT, research skills to list but three. But some key ingredients we lack are - substantial risk investment capital, visionary leadership, depth of entrepreneurial courageous business cultures and a shortage of the move fast and break things spirits. There are others I know.
I have a hope that some of the promised investments made this week and the initiatives which will (hopefully) flow from them. Might pour in some motivating energy, enthusiasm, risk taking and courage, to enliven our 'failing selves' and economy.
So many outside of the UK see our untapped potential, our world class resources, our world class intellectual prowess. But shake their heads at why we fail to see it ourselves and worse, do nothing about it.
Why do I say this? Listen to Trump praising Rolls-Royce Holdings (LON:RR.) and our defence and aerospace industry.
NVIDIA CEO Jensen Huang praised the UK as being in a “Goldilocks position, where world-class talent, research and industry converge,” while committing to support the development of the UK's largest AI supercomputer.
Prologis regional head Paul Weston emphasized the UK's strengths in two of its most critical sectors—life sciences and logistics—while announcing a £3.9 billion investment in the Cambridge Biomedical Campus and Daventry upgrades.
Blackstone's long-term £100 billion pledge, including £10 billion in data centers, underscores the UK's robust infrastructure and investment environment as a hub for tech and asset growth.
Amentum's £150 million commitment to nuclear engineering, planning to increase its UK workforce by over 50% and create 3,000 jobs, highlights the country's skilled workforce and advanced capabilities in energy and infrastructure.
That over 20% of Palantir Technologies (NSQ:PLTR) resources are in the UK (and they only recruit the very best engineers in the world) and it is to become the central hub of defence innovation across Europe.
So for myself, I tilt strongly toward optimism and just hope the UK can grasp the hands the US tech giants are offering us.
Regards
Howard
Well, buried on p23 of the DT, Ambrose Evans-Pritchard appears to agree with you. No doubt he is being horse whipped by the Ed.!
Hi snowdrop
I have not seen that.
Thanks for the comment
Regards
Howard
'life sciences and logistics'
The drug companies are doing their best to divest from the UK at the moment.
As for AI, I fail to see how we can ever compete seriously with the US while our electricity is three times as expensive as theirs.
Hi John2
Your points are accurate and I do not disagree with them.
'The drug companies are doing their best to divest from the UK at the moment.'
I suspect not all drug companies. As far as I understand it's Merk. I know AI by its very nature will assist remaining UK drug companies to evolve and hopefully help us to improve as a country.
'As for AI, I fail to see how we can ever compete seriously with the US while our electricity is three times as expensive as theirs.'
I do not expect US to compete with US in the AI space. But it is a very large and growing space and our capabilities will fit well into a very big pie, thus better for us all. Yes our net stupid zero energy policies are ruining us. I hope the pull factor of going towards AI might just get Starmer to see the light and side line Red ED.
Regards
Howard
AstraZeneca (LON:AZN) have paused a £200m investment in the UK also.
Hi john2
Also agree with your point but that is related to the policies being perused by the current government.
Regards
Howard
Well it's the only government we're going to have for the next few years. Reeves and Streeting seem to be doing their best to cripple British industry.
Hi john2
I agree completely.
Regards
Howard
In my opinion, a safe AI-related bet is uranium - look at the recent performance of Global X Uranium UCITS ETF USD Acc (LON:URNG)
The energy alternatives sector is flying in ETFs - (WisdomTree Renewable Energy UCITS ETF USD Acc (LON:WREN) , Global X Hydrogen UCITS ETF USD Acc (LON:HYGG) , WisdomTree Ur and Nuclear Energy UCITS ETF USD Acc (LON:NCLP) to name a few...
edit: add Global X Solar UCITS ETF USD Acc (LON:RAYG)
John
Wise words there!
A look at Verona Pharma (NMQ:VRNA) and what these great British people achieved by going and listing over in the US.
As for the AI it was nothing else but a show from Starmer/Trump. I think electricity costs for commercial use is something like between X5-X10 more here. CEO’s of these magnificent companies cannot pass this not in a million years. They will be crucified by their shareholders.
All the best
And regardless of energy price, the UK has no spare grid capacity to power heaps of new data centers. It's not uncommon in the winter for the grid to be running at 99% capacity (which is why they pay you not to use electricity at certain times).
This is why China will win out in AI - they always have 100% spare grid capacity, and deploy double the growth needed every year to their grid.
I believe the US has between 10-15% spare grid capacity, but they're not doing a lot to grow it.
All great points
Straight to the point.
Thanks.
US have realised this (exactly what you are saying) and taking steps to solve their problem but it will take between 5-10 years to achieve that.
That’s why the AI play will be here for many years and grow gradually.
All the best
Great post thanks.
And Farage of course a former commodities trader and businessman understands this, as opposed to the socialist rubbish pulled out of Cambridge University - Cameron May Millibund Johnson etc.
You can say this is not X but it is so so important - being an ostrich is not an option.
They want pensioners savings and property next - ok “news” but food for thought. As well as ID cards and government controls your life.
I won’t necessarily vote Reform, not if he plugs the ranks with former liberals (known as the Conservative Party but anything but). Emigration the only option but I love Britain, born here.
Look at private landlords now - some tenant grows a bit of mould on their walls from their breath and cooking is “your problem”. RIP poor little Awaab but a true socialist would help not just legislate the hell out of the investment market.
Millibund giving 11bn to foreign countries when we are bankrupt?
We are a divided country. This affects investments and futures yours and your grandkids.
Cameron, May, Miliband and Johnson all went to Oxford not Cambridge. Do I detect a smidgeon of anti-elitism? Three of them are Conservatives as well - not traditionally the party of socialists.
Farage described as a (successful) commodities trader is a joke………..
The least…..
All the best
I recently bought back into IG group (LON:IGG) as I think if offers an attractive combination of value, quality and growth - as summarised by the 97 StockRank and Super Stock rating.
I'm also a long-term customer with a small spread-bet account on the sidelines of my main portfolio. Funnily enough the vast majority of my spread-bet gains came through cryptocurrencies in 2020-21 (BTC,ETH,SOL), before the FCA banned retail access to crypto derivatives and Exchange Traded Notes (ETNs), forcing my positions to be sold.
I was pleased to take advantage of IG's new Crypto account with Uphold earlier this year, as I found the fees to be lower than Coinbase, who I was forced to use from 2021 onwards.
However, the FCA has lifted the ban on retail access to crypto ETNs from 8 October 2025. I'm eagerly awaiting that day, in the hope that I'll shortly be able to access securities such as the WisdomTree Physical Bitcoin fund through standard platforms like HL and IBKR, potentially within ISA and SIPP accounts.
The WisdomTree Bitcoin fund has a small annual charge of only 0.15%, whereas it cost me around 2.0% - 2.5% to purchase Bitcoin through IG. As someone who likes to trade in and out to avoid the largest drawdowns, that's quite prohibitive to me and I'll be using the fund instead, in the future. It will be interesting to see how IG react to the change.
Chris
I’m waiting for the 21Shares Bytetree BOLD ETP (BOLD) to become available. You can find the details at https://www.bytetree.com/bold/. It invests in Bitcoin and Gold on a weighted basis and is rebalanced monthly. Part of the rationale is to smooth out drawdowns.
Will these ETN’s be available for UK customers? I ask as there a lot of US ETF’s that are not accessible to UK customers as they don’t disclose additional documents (KIID)
With Life Science Reit (LON:LABS) announcement that they have decided to wind the trust up over the next 12 - 18 months, they have finally done what seemed obvious several months ago when a fund manager interview earlier this year (one of Paul Hill's guests on VOX?) was quite damming about the location of the Bicester property and rental prospects. (I hold)
Has anyone done an analysis on what the expected realisation NAV ps might be?
Futura Medical (LON:FUM)
Wife - I knew that stock was a lousy investment in more ways than one. Go back to the little blue tablets
Morning All!
If you're not too busy I'd appreciate your thoughts on Insig Ai (LON:INSG). Not a holder but saw Richard's enthusiastic presentation at the last Mello and I popped in on the watchlist.
There seems to be somewhat confusing messaging going on - it seems to be considering becomming a digital assets investor, "this could result in the Company's listing being cancelled and re-listed as an AIM investing company". A digital assets investor - is that a new euphamism for multi coin "treasury"? Uh-oh! That seems quite a big shift, and it comes following an admission that it is proving impossible to scale due to lack of "incomming" in the context of a land-grab going on elsewhere.
Either way the market doesn't seem to like todays update.
Insig Ai (LON:INSG)
That have tried all different stories!
Regular announcements but no Revenues given.
Clever money behind this and would not be surprised to see this go higher in the future. Needs to go lower though! so clever money can take big positions again.
Held in the past and made good money but not getting involved again.
I find it amusing how some of the UK listed companies try to copy US ones in a 2-3 year delay mode!
All the best
Henry Boot (LON:BOOT) - Interesting new project but what value/profit will it bring to the company?
Henry Boot (LON:BOOT)
not often a share bores me into selling - but Boot probably could get the boot for that very reason. these announcements mean didly squat to me , they are about as useful as the weekly Journeo contract updates (just kiding Journeo fans i do like the company and hold some shares) - the only thing that matters is does this contract move the dial and the answer is alomost certainly no.
I should probably look at Boot as emergency cash for a rain day that one never spends - it probaably does as well as putting funds in a decent savings acount.
They are doinf fine - the main thing that attracted me here was teh very conservative balance sheet (many projects held at cost price - so hidden profits simply waiting to be rubber stamped in the future) - plus the fact it was trading about book value when i bought - its even cheaper now as the book value have risen from 230p per share to 300p per share without the company rerating - with profits not exca tly going up i understand why the market is saying its not worth much more than the dividend it pays !
Hey ho back to sleep in the hope that this company will have a purple patch before it has a crisis and the share might get close to tnav and they might up the profits - in that regard i suspect upping the volumes on the housebuilding side of things would be the obviopus way to go - they make noises in that direction without much tangible progress yet.
Skillcast (LON:SKL) showing operational gearing kicking in and worth a look, esp their FCF statement. I've held since their lows so DYOR:
P.S: Roland I believe you have the wrong figures.
Power Metal Resources (LON:POW) setting itself up to possibly start share buybacks and dividends. Currently market cap is covered by cash holding which means you get all their exploration for £0. (and it’s a good portfolio).
Hi
Concurrent Technologies (LON:CNC)
Headline ... (I hold start position).
Concurrent Technologies Plc (AIM: CNC), a designer and manufacturer of leading-edge computer products, systems, and mission-critical solutions used in high-performance markets by some of the world's major OEMs, is pleased to announce that it has been awarded a $5.25m contract for the provision of design services to a US-based major defence prime contractor.
RNS ... https://www.stockopedia.com/sh...
Regards
Howard
Hi Howard,
A nice contract win from Concurrent Technologies (LON:CNC) this morning, building further on the record domestic win earlier this month.
There are some wider (positive) implications of this morning's announcement, so I'm currently working on a section for this.
Best,
Keelan
Hi Keelan
Great we will look forward to your thoughts.
I have not done much research into Concurrent Technologies (LON:CNC) so I welcome your views.
I do suspect however, that the increased investments into many aspects of defence in US, UK and across Europe may well be a factor.
In addition it might be that the growth of the space industry, particularly communications between space orbiting satellites and earth based communication systems and mobiles might also be a tail wind.
Regards
Howard
My one concern about this company - the directors hold so little and in fact have been selling this year - despite the seemingly successful news coming through
If you are a Zytronic (LON:ZYT^E25) shareholder, make sure you vote at the upcoming AGM and GM on 1 October (29 September deadline for proxy votes). Henry Spain wants to retain some of the company's assets to seed a fund (or some other investment alternative). To prevent this from happening and receive all proceeds from the liquidation VOTE AGAINST all the Requisitioned Resolutions at the General Meeting. If you hold your shares with a private broker contact them immediately to request to vote. I hold my shares with Halifax and had to call them up in order to vote.
https://www.zytronic.co.uk/wp-...