Daily Stock Market Report (Fri 23 May 2025) - EPWN, TLY, GAW, AJB, AGR/PHP, BEG, TEK, SEA

Good morning!
The agenda is now complete.
Update 11.50: today's report is now complete. I hope you're able to enjoy the long weekend! The Daily Report will be back on Tuesday.
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
Games Workshop (LON:GAW) (£5.2bn) | Expect FY25 rev of c.£610m, PBT at least £255m. Record licensing revenue, exp lower in FY26. | GREEN (Roland) Today’s update is ahead of previous expectations, as far as I can see. These are certainly exceptional figures from the Warhammer maker, only tempered slightly by a warning that licensing revenue is expected to be lower this year. Given the group’s exceptional quality and track record of outperformance, I’m going to maintain our positive view. | |
AJ Bell (LON:AJB) (£1.9bn) | Rev +17%, PBT up 12% to £68.8m. Customers +9%, AUA +5% to £90.4bn, £3.3bn net inflows. FY results to be ahead of previous expectations. | GREEN (Roland) I am staying positive on this well-run investment platform after today’s strong half-year results. Upgraded guidance for the full year highlights strong trading momentum and customer acquisition. Profitability remains excellent despite price cuts and the business is investing in its brand and offering to support continued market share gains. On a P/E of 20, I think the shares remain fairly priced on a longer-term view. | |
Assura (LON:AGR) (£1.6bn) | Due diligence underway on improved Primary Health Properties (LON:PHP) offer. A planned General Meeting to vote on the KKR offer has been adjourned. | PINK (Roland) [no section below] With two firm offers on the table for this healthcare REIT, a deal of some kind seems very likely to me. For shareholders, the weakness of the PHP offer is that it’s a cash/shares offer, whereas KKR’s 49.4p offer is all cash. At current prices, I estimate both offers are almost identical in terms of value (49.4p vs 49.6p). With AGR stock trading at book value (49.5p) and in line with the current value of both offers, investors may want to consider whether to lock in some gains or hold out in hope of a slightly better outcome. | |
Begbies Traynor (LON:BEG) (£157m) | Revenue, EBITDA, net cash ahead of exps. Rev +12%, adj PBT +7% to £23.5m. | AMBER (Roland) Today’s update is (slightly) ahead of expectations, but I don’t see much to change my view that this business is not really profitable enough to deliver the kind of rewards shareholders might hope for. However, the business seems fine and I can’t fault these numbers in themselves. The valuation also remains modest at under 10x earnings. On balance, I’m happy to stay neutral here. | |
Epwin (LON:EPWN) (£125m) | YTD trading in line with exps. Revenue +8% ahead of prior year. FY op profit exp to be in line. | GREEN (Roland - I hold) [no section below] This building materials group continues to look attractively valued and in good health to me. While housing market conditions remain mixed, I think Epwin is well positioned to benefit in an upturn. In the meantime, the 6% dividend yield and ongoing share buyback look affordable. The buyback is likely to generate value for shareholders at current levels, in my view. | |
Seascape Energy Asia (LON:SEA) | Year end cash £2.8m, op loss £5.7m. Since received c.$11m cash. Progress with SE Asia portfolio. | (Roland) - this oil and gas stock was previously known as Longboat Energy. The company has sold its Norwegian/North Sea assets and pivoted to Southeast Asia. | |
Tekcapital (LON:TEK) (£17m) | Net assets +46% to $70.1m, NAVps +22% to $0.33. After-tax profit $19.2m. | AMBER (Roland) [no section below] This investment group targets IPOs for its portfolio companies. When successful this can generate significant gains, as highlighted by last year’s net profit of $19m. Last year’s UK listings included MicroSalt and GenIP, both on AIM. The discount to book value is over 60%, but similar peers in the UK (e.g. Molten Ventures, IP Group) also trade at large discounts, presumably reflecting the difficulty and uncertainty involved in realising gains. There could be value here for an investor willing to research the investee businesses, but it’s too speculative for me. | |
Totally (LON:TLY) (£2.8m) | Offers have been received for subsidiaries. Board has concluded disposals are only option to fund liabilities. Sale of business expected before further funding required, but potential proceeds are unlikely to meet all future liabilities - “there could be no value in the ordinary shares” | RED (Roland) [no section below] Completely uninvestable, in my view. I think the only sensible choice is to assume that shareholders will face a total loss. |
Roland's Section:
Games Workshop (LON:GAW)
Down 3% to 15,390p (£5.1bn) - Full Year Trading Update - Roland - GREEN
The Group's profit before taxation ("PBT") is estimated to be not less than £255 million (2023/24: £203.0 million).
Games Workshop’s share price is down slightly this morning, but today’s full-year update appears to be ahead of broker forecasts.
When the maker of Warhammer last issued a trading update in March, paid research provider Edison issued a FY25 forecast for pre-tax profit of £242m. Today’s figure of £255m is comfortably ahead of this.
The total FY25 revenue figure provided today of c.£610m is also higher than the £590m consensus estimate shown on Stockopedia.
I think it’s reasonable to view today’s trading statement as another ahead of expectations update from this impressive company.
FY25 trading update: here’s a quick summary of the numbers provided today for the 52 weeks ended 1 June 2025.
The company divides this reporting into core (the wargaming business) and licensing:
Core revenue “not less than” £560m (FY24: £494.7m)
Licensing revenue of c.£50m (FY24: £31m)
Core operating profit “not less than” £210m (FY24: £174.8m)
Licensing operating profit of c.£45m (FY24: £27m)
Core trading: these figures tell us that core sales rose by 13.2% last year, driving a 20% increase in operating profit. When profits rise faster than sales it means margins are expanding – in this case the numbers imply a core operating margin of 37.5% (FY24: 35.3%).
Licensing: licensing revenue is generated from deals for Games Workshop intellectual property to be used in other media - TV, games and films. It’s almost 100% margin and rose by around 60% to a new record high last year. However, the company does sound a note of caution on licensing prospects for the current year:
Licensing revenue in the period is at a record level and we are not expecting this to be repeated in 2025/26. Licensing remains a significant area of focus.
This is perhaps one area where the company could be more transparent – the statement above leaves a lot to interpretation. It doesn’t, for example, make any mention of progress with the company’s Amazon deal.
Staff profit share: Games Workshop’s employees have received profit share payments of c.£20m during the year, paid on an equal basis to each member of staff. Last year’s annual report indicates the company has c.3,500 staff, so they may each have received a payment of around £5,700.
The company consistently reports high staff retention and its employees clearly make a big contribution to its success.
For contrast, shareholders received dividends during the same period of £171.4m, so there’s clearly no clash between treating employees fairly and rewarding investors. Perhaps a lesson other companies could take on board.
Outlook & Estimates: apart from the comment on licensing, there’s no forward guidance in today’s update. This is in line with Games Workshop’s normal practice of largely restricting its reporting to facts.
However, the last broker note I can find (from 6 March) suggests revenue and earnings could fall during the 25/26 financial year. This is also reflected in our consensus forecasts:
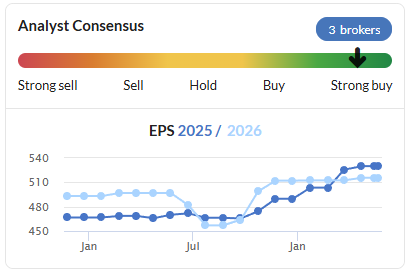
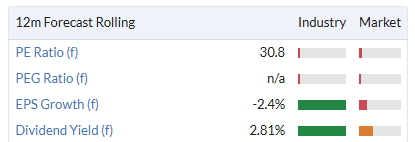
Based on past performance, there’s a reasonable chance these estimates may be upgraded over the coming year. As things stand, these numbers leave the shares on a forward P/E of 30.
Roland’s view
Ed recently highlighted Games Workshop as one of only two multibaggers from his NAPS portfolio that would have been worth holding over the whole 10-year history of the portfolio. It’s tempting to think that normal rules don’t apply to this business, but of course they do.
The shares have not looked cheap for a long time, but a combination of exceptional quality metrics and continued growth has meant that they’ve offered value regardless, truly living up to their High Flyer styling.
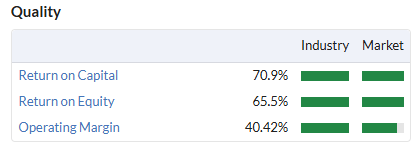
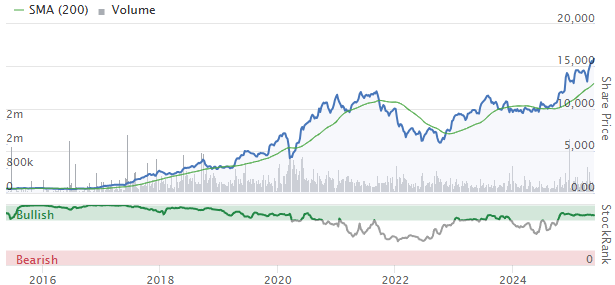
I don’t know when this long run of success might end, but for now I’m inclined to give the firm the benefit of the doubt despite the forecast drop in earnings this year. Games Workshop’s strong performance and exceptional quality means I’m going to maintain our GREEN rating for now.
AJ Bell (LON:AJB)
Up 7% to 490p (£2.0bn) - Interim Results - Roland - GREEN
AJ Bell plc ('AJ Bell' or the 'Company'), one of the UK's largest investment platforms, today announces its interim results for the six-month period ended 31 March 2025.
We’ve written favourably about this investment platform previously. Today’s results highlight many of the things we like so much about this business and put the company on track to deliver full-year results ahead of previous expectations (my emphasis):
In the first half of the year we have delivered strong financial results. We expect this momentum to continue with full-year revenue and PBT anticipated to be higher than that previously guided at the start of the financial year.
H1 results summary: AJ Bell’s revenue for the half year rose by 17% to £153.2m, supporting a 12% rise in pre-tax profit to £68.8m. Shareholders will be rewarded by a blended mix of dividend growth and a further buyback:
In accordance with our capital allocation framework, we are pleased to declare an interim dividend of 4.50 pence per share, up 6% versus prior year, alongside the initiation of a second share buyback programme of up to £25 million, reflecting our ongoing commitment to return surplus capital to shareholders.
While conventional fund managers are struggling to attract new customers, this doesn’t seem to be a problem for the leading retail investment platforms.
AJ Bell saw customer numbers rise by 9% to 593,000 during the period, while total assets under administration (AUA) rose by 5% to £90.4bn. The majority of this increase came from net inflows of £3.3bn, topped up with a £0.6bn gain due to market movements.
Today’s profits show the group’s pre-tax profit margin falling from 46.8% to 44.9% (still an outstanding figure). However, the company says this reflects planned investment in the company’s brand and customer proposition to drive long-term growth.
Fortunately, the underlying profitability of the group’s asset management operation remained stable, despite a £20m package of price cuts in April. AJ Bell’s revenue margin for the half year was 32.4bps (i.e. 0.324%), compared to 32.3bps for the same period last year.
Revenue margin represents revenue as a percentage of AUA. Management says this stable result was driven by the benefit of higher transaction volumes and AUA-related fees offsetting lower prices.
Outlook: CEO Michael Summersgill says the growth momentum seen during the company’s first half has continued into the second half (i.e. April onwards), “despite significant market volatility”.
He says DIY investors (vs advised investors) were particularly active, investing over £300m in just 10 trading days at the start of April, mostly in equities and bonds.
Full-year revenue and pre-tax profit are now expected to be ahead of previous guidance, which appears to be for revenue of £296m and a pre-tax profit of £124m (source: Hannam & Partners Dec 24).
We aren’t given details of upgraded guidance today and I don’t have access to any updated broker notes. However, assuming H2 pre-tax profit is level with H1, full-year PBT could be c.£137m – roughly 10% above previous estimates. This is consistent with the c.10% share price gain seen this morning.
Roland’s view
I think this is an excellent and well-run business. I like AJ Bell’s dual approach of providing a platform for financial advisers and DIY investors. This addresses two areas of strong growth, without requiring the company to commit to a single segment.
AJ Bell is continuing to invest to broaden its offering and maintain high service quality, taking advantage of strong trading to support this spend without impacting overall margins.
A P/E of 20 doesn’t seem excessive to me for a business with a strong growth record, good market share and outstanding quality metrics:
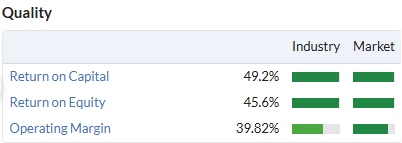
Graham went GREEN on AJ Bell in January, when the shares were trading at around 440p. The share price is nearly 15% higher now, but given the group’s strong progress and today’s upgrade, I am inclined to maintain our positive view.
Begbies Traynor (LON:BEG)
Up 2% to 100p (£159m) - Year-End Trading Update - Roland - AMBER
Begbies Traynor Group plc (the 'company' or the 'group'), the professional services consultancy, announces an update on trading for its financial year ended 30 April 2025.
The market seems underwhelmed by today’s trading update, despite insolvency specialist Begbies Traynor proudly flagging these figures as “ahead of consensus expectations”.
The headline figures show solid revenue growth, but with profits rising more slowly than revenue, it seems that overall margins weakened last year (even at an adjusted level):
Revenue expected to rise by 12% to c.£153m (including 10% organic growth)
Adjusted EBITDA to be up by c.10% to c.£31.3m
Adjusted pre-tax profit to rise by c.7% to c.23.5m
Net cash of £0.9m at 30 April 2025
In its insolvency business, Begbies says it saw an increase in insolvency activity over the last year, especially in higher value cases. Revenue in this division rose by 11%, without any acquisitions.
Begbies claims a market-leading position in this sector by number of appointments and says it has expanded its team to support growth, with a strong pipeline for FY26.
Property-related legal services: the company’s other division is focused on property. Organic revenue growth of 7% was doubled by acquisitions last year, to give a total increase of 15%.
Management says that strong growth in property auctions and increased geographic coverage contributed to last year’s gains. Again, extra senior staff have been hired to support further expansion.
Outlook & Estimates: There’s no comment on the outlook for the year in today’s update – that’s likely to be provided with the full-year results in July.
However, broker Shore Capital has released an updated note today slightly upgrading its earnings estimates for FY25 and FY26:
FY25E EPS: 10.5p (previously 10.4p)
FY26E EPS: 10.5p (previously 10.3p)
The very small size of these upgrades probably tells us why the share price hasn’t moved much today. However, this fresh update is useful and confirms the shares should be trading on less than 10 times forecast earnings, with a useful 4%+ dividend yield.
Roland’s view
My main concern with this business is that its profitability is consistently low, at least a reported level:
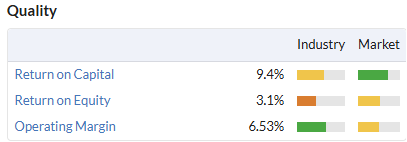
This low profitability may explain why the share price is unchanged from five years ago, even though revenue and profits have doubled over the same period:
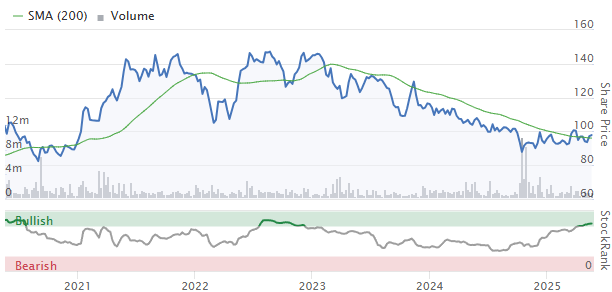
This business doesn’t seem to be profitable enough to expand and create value for its shareholders.
Regular acquisitions have often been part-funded with new equity. As a result, the share count has risen by 50% since 2019, but book value per share has actually fallen slightly:
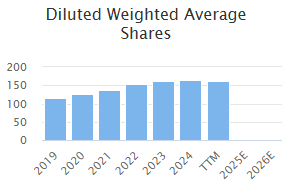
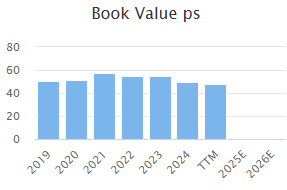
I can’t help wondering if this professional services group is run more for the benefit of its partners and senior fee-earners than for its shareholders.
We’ve previously been neutral on Begbies Traynor, a view that’s also reflected by the StockRanks:
I don’t see anything in today’s announcement to suggest that I should change that view. (AMBER)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

22 comments
Lightbridge (NAQ:LTBR) Thanks to Yiannios for his pre tariff day US checklist. up 45% today.Im radiating warmth!
It’s Yiannos
You are too excited I guess!
Good morning. Any chance you could give Biogen a glance and share your thoughts ? My track record with American shares is awful but I still persevere thus thinking of buying into Biogen.
Thanks
Porch Inc (NAS:PRCH)
All the best
Hi yiannos1
Porch (NAQ:PRCH) will take a look, thanks have a good weekend.
Regards
Howard
As ever, it remains very challenging to try and ascertain what is, and what isn't, priced in to a share price.
Bloomsbury Publishing (LON:BMY)
Yes, many valid discussions yesterday & previously about organic vs. acquired growth, over-reliance on a single author, whether valuation is appropriate etc etc.
But none of this is new. If you look at the H2Radnor note (H2Radnor BMY 20/3/25) from back in March the gap between forecast "reported" & "adjusted" PBT of £41.5m vs £30.3m is very clear to see - the big step up in the amortisation of intangibles is broken out explicitly. The published results were indeed ahead of these forecasts, coming out at £42.1m and £32.5m.
If markets are remotely efficient (and I'm not sure they always are) then I would surmise that the share price drop must be a question of the outlook disappointing, but the share price move is quite large for a "broadly in line with current consensus" statement, especially given they had the helpful footnote.
So what to make of it? Do they need a better broker to get their earnings guidance into the market? Were investors hoping for 10 new SJ Maas titles to be launched next month? Or are we moving to a more American style of earnings season where the absence of an upgrade to expectations is in effect a downgrade? Or maybe it is just one of those things - the marginal buyers & sellers having an oversized impact in thin UK liquidity?
BT (LON:BT.A)
So to follow on from the above, BT supposedly missed expectations yesterday, and the shares were duly down on the day. Or were.
As I write this the shares are now trading 9.5% higher than yesterday's low point.
Go figure. I think it just reinforces how traders can still lose money even if they know what tomorrow's headlines are going to be.
My personal conclusion is not to trade around results, although I do read them. Those who sold out after the recent Qinetiq (LON:QQ.) profit warning must now be wondering whether following simplistic rules is really the way forward. Differentiating between a temporary blip and turning point is so, so difficult in real time, and so obvious in hindsight.
Bloomsbury Publishing (LON:BMY)
Yes, the discussion as to why such a large reaction to "broadly in line" continues.
There was a discussion on this yesterday by the 2 Pauls that you can view here.
I have re-viewed the Q&A from yesterday's presentation at https://sparklive.lseg.com/Blo...
There was a reminder that the bumper profit from SJM last year and (41m 54s in) the CEO reminds us that a good deal of this was the 15 previous books from her bought by people who read the latest and wanted more. I am no expert in 'social media' but am told that most of the first time purchasers resulted from discussion on her books "going viral". What that implies is that although the next SJM book will be a big hit there may not be so many buying previous books because they already have them and BMY revenue may disappoint investors as a result.
There are also comments on the state of the US academic market. 28m 41s in the CFO talks of budget pressures previously reported on small/midsize institutions now also seen on the large ones. 37m 47s in there is a question on the same theme and the reply is that it's tough out there.
Then there is the matter of acquisitions. In reply to the very last question (50m 11s) there is a weary 'we need some sleep' reply from the CFO saying that immediately after the last one she and Nigel received an email from the head of M&A detailing the next 10 targets.
Of course, buying these usually brings goodwill onto the balance sheet. When this is written off it is conveniently swept into the 'highlighted items' which are excluded from the headline figures. In the excluded items this year there was an increase in amortisation of intangibles for the non-consumer section from £4.5m last year to £8m this.
Finally I have seen no comment on an item buried in the report (between Dividend and Outlook) that is usually subject to a separate RNS - the resignation of the CFO. It is all very harmonious and she will stay on to hand over to the new one but is "to pursue a portfolio career" the main reason? Is it to get someone else in before the big change? (Nigel Newton will be 70 next month although he may go on much further like Buffett!).
Yes, I was surprised about the lack of reaction to a changed CFO. This is rarely a positive development and especially when they haven't been in the job that long and are moving to pursue a "portfolio career" - whatever that may be?
Good morning Roland and thank you for a very decent write up on Games Workshop (LON:GAW) which is my largest individual holding. I have held shares in this company since 2017 and in that time broker forecasts have always been behind the curve, largely due to the company’s habit of under promising and over delivering which we have seen in action again today. I’ve lost count of the number of times a positive update is tempered by a cautionary note from the company.
You just have to look at the company’s financial growth to see the reality of the situation. What is perhaps more remarkable is that this growth is entirely organic. They don’t make acquisitions. The accounts are the cleanest you will ever see. They don’t make adjustments. Surplus cash is regularly returned to shareholders via dividends. They don’t engage in share buybacks.
In short, it is the best company I have ever owned and the best I am ever likely to own. The time will come when the current CEO moves on and at that point I will reassess my conviction.
Enjoy your weekend folks,
Simon
Morning Simon,
I agree with you re. CEO Kevin Rountree at Games Workshop (LON:GAW) - when he leaves, I suspect a lot of people may reassess their conviction! He has been an outstanding leader, from what I can tell.
Roland
Epwin (LON:EPWN)
Very very dependable plodder of a share here - mangement always seem to do decent job of delivering on promises (ie not over promising !!) - they may not have a huge moat ref what they sell (there may be too many players in their market?) - but i think there stuff is specialised enough that effectively they seem to own their space ref delivering reasonable outurn on sales.
organic growth is probably pretty non existent - there wil be busy and quiet time s- now is obviously semi quiet but ticking over - its good that they can still churn out profits when time sare quiet.
minor acquisitions share buybacks and new outlets and p/e of 8 and decent cashflow - should enable the company to hopefully grow its eps over the cycle - with 6% dividend yield while you wait.
Perhaps takeoever or merger candidate (eurocell to improve efficiencies would be very obvious choice?) at 25% premum might come along while we wait
Looks like Harwood have purchased another chunk of PAYP.L
Harwood are clearly reinvesting their profits from Argentex (LON:AGFX) !
Or PayPoint (LON:PAY)
US President Donald Trump plans to sign orders to revitalize the nuclear energy sector, aiming to streamline regulatory processes and bolster the fuel supply chain. This initiative will invoke the Defence Production Act and promote the construction of new nuclear facilities with federal support.
https://www.livemint.com/news/...
Yellow Cake (LON:YCA) in demand this morning. ASX uranium stocks also taking off
Avingtrans (LON:AVG) that has a US presence may also be a beneficiary.
Also demand today for £NUCG (VanEck Uranium and Nuclear Technologies ETF) which has had strong momentums since Trump's "Liberation Day". Its an ETF mainly exposed to Uranium Miners and Nuclear Infrastucture.
...NUCG ETF provides exposure to the global uranium and nuclear energy industry, including mining, engineering, reactor technology, and physical uranium assets. It is designed for investors seeking to benefit from the growth and development of nuclear energy as a key component of the global clean energy transition.
Good news that at least it's not an attempt to drill for yet more gas and oil, nuclear is the generally seen as the most sensible mid-term option by both sides of the climate argument.
I have a small holding of Yellow Cake (LON:YCA), so that's also useful, and I think other countries will be following suit for various reasons.
Hopefully the attempt to grab Greenland isn't related to the push to nuclear, there's already a nuclear waste dump there courtesy of Project Iceworm. Given the partial truths of that administration they might think it's a great idea to dump more under the ice, spoiler alert it's most certainly not.
Luke Johnson adds ~2.1m shares in Inspecs (LON:SPEC) to up his stake to 5.86%
Stocko Fcst p/e 6.6 and peg 0.1
Inspecs (LON:SPEC) Yes watching this one closely, now the new Vietnam factory is completed I want to see how they allocate their capital, ideally they reduce their debt pile in a meaningful manner, obviously also there is the matter of tariffs and how that plays out but I agree eParo this could have legs especially from these levels....
Didn’t they report that they breached their bank facility covenants in March?
Not a great place to be so recently after agreeing them!
Inspecs (LON:SPEC) - A German competitor has filed for insolvency:
https://www.ewintelligence.com...