Daily Stock Market Report (Fri 27 June 2025) - IGG, NFG, LIKE, AEWU, BBSN, DEVO, BAB

Good morning and welcome to Friday's report.
It's almost the end of the half year and news flow today is limited to a handful of small companies with very late accounts. We may take a look at some backlog items from this week - please feel free to drop any suggestions in the comments.
Spreadsheet accompanying this report: link.
12.15: today's report is now complete, thanks for all your comments.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
IG group (LON:IGG) (£3.7bn) | Capital has been reduced by the cancellation of £300m worth of shares, a £126m reduction in the premium account and £3,501 reduction in the capital redemption reserve. | GREEN (Roland - I hold) [no section below] These changes are an accounting exercise with no real-world cash effects. Their purpose is to allow IG to return more of its surplus cash to shareholders, if it should choose to do so. Graham explained this issue in more detail here. | |
Aew UK Reit (LON:AEWU) (£167m) | NAV up 7% to £174m and NAV total return up substantially to 15.3%. Cash of £28m at the year end, management comments that it is “an excellent time to deploy capital”.
Rental income -5% to £18.85m | AMBER/GREEN (Roland) [no section below] | |
Seeing Machines (LON:SEE) (£132m) | Six week pilot trial for its AI-powered transport safety monitoring system. This is the first trial to come out of the pipeline of opportunities from the agreement with MEAA signed in February. | ||
Devolver Digital (LON:DEVO) (£98m) | Trading in line with current expectations. Consensus exps are for the company to move back into profitability in FY25. | AMBER/GREEN (Roland) [no section below] I think this could be an interesting contrarian situation. With net cash covering c.30% of the market cap, I estimate that the shares trade on a cash-adjusted forward P/E of c.12. That could be too cheap if the business can deliver a multi-year run of growth, in line with forecasts. | |
DP Poland (LON:DPP) (£87m) | Rev +20% to £54m (18% lfl growth). Average weekly order count +13%. Group losses reduced to £0.5m. Trading in first few months of the new financial year is ahead of the same period in FY24. | (MB) Results to Dec 2024 being published in late June are a red flag. | |
Likewise (LON:LIKE) (£54m) | Rev +10%. Continued investment in logistics network to support “significantly higher sales activity”. Group is “well on course” to achieving current forecasts.
Broker Zeus leaves forecasts unchanged today, but notes they look “increasingly achievable”. | AMBER/GREEN (Roland) [no section below] Revenue growth of 10% is ahead of consensus forecast revenue growth of 6.7% for this year. Likewise says it is continuing to gain market share. Assuming this level of performance can be maintained, I think there could be some scope for an upgrade to forecasts in H2. While minimum wage and NI increases are expected to be a headwind, positive operating leverage from higher volumes may help to offset this. I have tentatively upgraded our view today to reflect strong momentum. | |
Brave Bison (LON:BBSN) (£41m) | 2025 YTD trading in line with exps, “strong progress”. Four acquisitions so far this year. | AMBER/GREEN (Roland) [no section below] Today’s in-line statement provides useful reassurance and does not alter forecasts or our moderately positive view. Mark covered the MiniMBA acquisition and related issues in depth on Wednesday. | |
Hercules (LON:HERC) (£35m) | An electrical transmission line specialist. Consideration up to £15.7m (9x PBT). | ||
EMV Capital (LON:EMVC) (£13m) | Closed £350k of £1m fundraising for Q-Bot and converted £865k of convertible loans. Equity in Q-Bot will be 30% (£1.4m) | ||
Switch Metals (LON:SWT) (£9m) | Non-trading in 2024. Acquired miner Switch CDI and joined AIM in April 2025, raising £2m. | (RH) Results to Dec 2024 being published in late June are a red flag. | |
Jarvis Securities (LON:JIM) (£7m) | Second Interim Results & Change of accounting reference date | Rev +8.4%, PBT +71% to £2.4m for 6mo to 31/12/24. Warns certain conditions of sale to ii not satisfied. | (RH) Results to Dec 2024 being published in late June are a red flag. |
Mindflair (LON:MFAI) (£5m) | NAV +85% to £10.8m for y/e 31/12/24 due to Infinite Reality investment. PBT of £3.2m, NAVps 205p. | (RH) Results to Dec 2024 being published in late June are a red flag. |
Roland's Section
Next 15 (LON:NFG)
Down 28% to 208p yesterday (£210m) - Statement re. Mach49 LLC & Trading Statement - Roland - RED
Shares in this tech and data-driven growth consultancy group fell by 28% yesterday after the company disclosed legal problems at a subsidiary and issued a profit warning.

Here’s a summary of the timeline:
Wed 25 at 4.20pm: Statement RE: Mach49 LLC - “become aware of potential serious misconduct concerning the Mach49 business”
Thu 26 at 7am: Trading Statement - “the Group now believes that profit for FY26 will be materially below current year expectations”
Thu 26 at 7am: Directorate Change: long-time CEO Tim Dyson will retire after a transitional period to hand over to his replacement, Sam Knights (currently CEO of a Next 15 subsidiary, Shopper Media)
Let’s take a look at what’s happened.
Mach49 legal issues
For some background, Next 15 acquired Mach49 in 2020, when the business was described as a “Silicon Valley-based growth incubator for global businesses”. The price of the deal wasn’t disclosed at the time.
In this week’s statement, the company says it was working on calculating the final earnout payment for the sellers of Mach49 when it became aware of “potential serious misconduct”.
As a result, three senior managers at Mach49 have been fired and the former co-CEO has been appointed as sole CEO.
The potential misconduct appears to be serious:
Next 15, on behalf of Mach49, is in the process of reporting the matters to relevant law enforcement agencies. It is too early to know the outcome, but Next 15 will ensure that full co-operation is provided to those agencies.
Next 15 has paused any further payouts to Mach49's selling shareholder until these issues are resolved.
Profit warning
The Mach49 RNS crept out just before markets closed on Wednesday. There wasn’t much time for traders to react. On Thursday morning we got a conventional 7am Trading Statement with more bad news, triggering yesterday’s share price slump.
Here’s a summary of the main points:
Revenue for FY26 (y/e 31 May 26) is expected to be broadly in line with market expectations, given as £491.7m
However FY26 profit is expected to be materially below current year expectations due to a range of factors:
Mach49: management expects to see a “lower conversion of opportunities within this brand’s pipeline”. This is said to be the most significant impact on expected profit;
Growth investment: additional spending on staff, products and AI;
FX effects: adverse movements in the USD/GBP exchange rate, with over 50% of revenue in USD.
Updated estimate: advisory h2Radnor has provided updated estimates for FY26 - many thanks.
FY26E revenue: £486.1m (prev. £494.1m)
FY26E adj PBT: £63.0m (prev. £82.3m)
FY26E adj EPS: 43.5p (prev. 57.6p)
These forecasts suggest a cut to profit expectations of c.24% for the current year. Some recovery is forecast for FY27, but I’m not sure I would place much weighting on the outlook for next year, given the potential legal issues here.
Roland’s view
When Mark looked at Next 15 in January, he reminded us that Next 15 suffered a mishap in 2024 when it lost a major contract for its growth consultancy division. January’s trading statement was also quite downbeat, warning that profits would be at the lower end of expectations.
Even before this week’s bad news, there seems to have been a backdrop of disappointing performance – reflected in the consensus trend chart:

The risk here is that bad news and additional costs could continue for some time before positive momentum is restored. Even before this week’s news, the StockRanks were flagging up very low momentum, which can be a risk factor:

A further concern for me is the timing of the departure of the CEO. Tim Dyson has been in this role since 1992 and joined the firm straight from university. The company says succession planning has been in progress for some time, but I would speculate that the timing of the news may suggest that the board has decided to accelerate the process of leadership change.
It’s possible that Next 15 shares are cheap at current levels and may recover. This week’s updated forecasts from h2Radnor suggest the shares may now be trading at just four times FY26 earnings:

However, there are too many factors that are simply unknown at this time for me to consider this as a possible investment. In this case, I’m particularly concerned by the risk of exceptional costs and reputational issues that might affect Next 15’s ability to win new contracts.
Until we have some clarity from the new CEO on both the Mach49 situation and trading performance, I am inclined to view Next 15 shares as uninvestable. RED
Babcock International (LON:BAB)
Up 11% to 1,144p on Wed 23/6 (£5.9bn) - Preliminary Results - Roland - AMBER/GREEN
I’m circling back to look at FTSE 100 defence contractor Babcock International, which released its full-year results on Wednesday this week.
It's no secret that defence stocks are enjoying structural headwinds at the moment. Babcock has also been benefiting from a successful turnaround under CEO David Lockwood, previously of Cobham (which was controversially sold to private equity!).
As a result, the Babcock share price has tripled over the last three years:

I don’t think Babcock is ever likely to become a takeover target, due to its national security significance as a key contractor looking after the Royal Navy’s nuclear submarines. But there seems little doubt that the company is in a strong position at the moment.
FY25 results summary (y/e 31 March)
Babcock’s revenue rose by 10% to £4,831.3m last year, supporting a 51% increase in operating profit to £363.9m, giving a margin of 7.5%. This is a reported profit figure – refreshingly, the adjusted operating profit figures were almost identical.
Adjusted earnings for the year rose by 63% to 50.3p while the dividend was lifted 30% to 6.5p. That seems a surprisingly small payout for a business with this level of profitability, giving a total payout of c.£33m – equivalent to a yield of just 0.6%.
The explanation seems to be that Babcock has decided to follow the fashion for prioritising share buybacks over dividends. This week’s results included details of a £200m buyback (39.5p per share) to be carried out over the coming year. That’s equivalent to a yield of 3.4% that shareholders could have enjoyed in cash.
Personally, I’m not a fan of this approach - especially when a company’s shares are trading on a relatively high valuation and the planned buyback is not covered by free cash flow. Both of these are true here, based on last year's results.
Trading: Babcock’s trading performance for the year was supported by strong growth in the Nuclear and Marine divisions, according to the company. The contract backlog remained stable at £10.4bn, reflecting new business wins offset by the ongoing delivery of some long-term contracts.
Some of the highlights flagged by the company include the hull completion of the first Type 31 Frigate for the Royal Navy and the docking of the first Astute Class nuclear submarine in upgraded facilities at Devonport.
Elsewhere, the firm secured a five-year, £1bn support contract with the Army and a 15-year deal to provide military air training solutions for the French Air Force and Navy.
Balance sheet/cash flow: looking over Babcock’s accounts in more detail doesn’t suggest any obvious concerns to me.
Debt levels are now comfortable at 0.3x EBITDA (net debt of £101m exc leases). Free cash flow of £153m (my calculation) represented 61% of net profit for the year. This level of cash conversion looks fine to me against a backdrop of elevated investment to support future growth.
Outlook
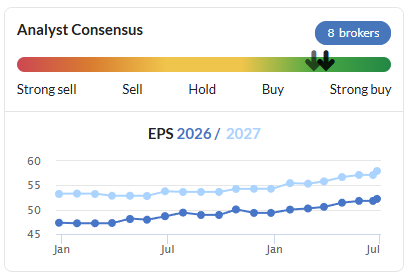
Babcock now expects to achieve its previous medium-term operating margin target of 8% in FY26, one year earlier than previously planned. Brokers have tweaked forecasts slightly higher this week, according to the consensus data on Stockopedia:
FY26E EPS +0.8% to 52.2p
FY27E EPS +1.2% to 57.9p

This valuation and growth outlook is reflected in High Flyer styling and a StockRank that’s weighted to quality and momentum:

Average mid-single digit revenue growth;
Underlying operating margin of at least 9%;
Average underlying operating cash conversion of at least 80%.
Roland’s view
Earnings forecasts have trended steadily higher over the last 18 months, supporting the strong momentum we've seen:
I’m relieved to see that I upgraded Babcock to AMBER/GREEN in April when the company issued a positive trading statement, confirming full-year guidance and emphasising an improvement in margins.
Based on valuation and current year forecasts alone, I might be tempted to revert to a neutral view. But I can't ignore the stock's strong momentum and the broader expectation of a structural increase in defence spending, highlighted by CEO Lockwood:
This is a new era for defence. There is increasing recognition of the need to invest in defence capability and energy security, both to safeguard populations and to drive economic growth. Our specialist capabilities are increasingly relevant …
The main risk I can see is that we could now see an awkward pause in growth while the market waits to see how pledges for higher defence spending will translate into concrete commitments and contracted projects.
Even so, I think the direction of travel remains clear and believe that Babcock should be well positioned to benefit. I’m going to leave our view unchanged at AMBER/GREEN.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

25 comments
3i (LON:III) l do find the directors share awards very excessive. I don't hold anymore.
Zotefoams (LON:ZTF) good rise onto theback of Nike (NYQ:NKE).
Works co uk (LON:WRKS)
Re The Works WRKS
Anyone aware of any news/announcements? I can't find anything but share price is taking a bit of a walloping this morning - down 10% on 3x higher than average trading.....
Works co uk (LON:WRKS) - I suspect it's a combination of profit taking coupled with the fact that at just £38m Mkt cap - any sells will have a major effect on SP. FWIW their local shop is always having a sale - but then thats business these days and like all busineses also suffering addl costs
Ok that's fair enough - thanks for the reply, I was just concerned in case there had been any company specific news or financial updates that I may have missed.
NEXT 15 Plc ....
Just catching up on the story. Share price horror story after peaking at £13 two years ago they have destroyed mot of that value and we now stand at £2.15 (MCap £209)
I'm not a share holder but for those that either have been or are currently you must be livid.
Clearly the current management were not up to the job, they lost business, they buy Mach49 in 2020 and find everyone inside the business has been having them over, to be fair many running Mach49 were the prior owners of the business focused clearly on their multi year earnout payments rather than N15. Doing alittle research I noted the Mach49 owners, after accepting 2m inital consideration were willinhg to cap the consideration in 2022 at 300m dollars. In the last Annual Return they were still talking about deferred contingent consideration for Mach49 of 219m dollar
Its eye watering how much they have been paying out as deferred considation, not just Mach49 of course. 60m GBP last year and 42m GBP the prior year.
No wonder the CFO left this year and now the CEO.
Tandem
Results the other day reinforced what we are seeing .
Bike market has turned the corner now .
Leaving
- less compeition
- distressed stock has cleared the system
With the demise of some quite major players in past few years if ever there was an open goal tandem have it now .
They have a very good range of Chris Hou bikes that i think will give Frog a real run .
Less competiition
Reduced buy pruces usd weakness
Lean stock
Big warehoude can now sweat
New motivated major shareholder
Oldguard dinisaurs gone
Shareoruce hardly mived
interstingly a smaller distributor just went pop and slots straight into tandem, 3 million turnover - they could pick that up very cheaply and bolt on
Normally illiquid but seems to be a big seller jim shears maybe one of the old guard
i just cant see ANY downside ar all
Anx plenty of upside if only they tap the ball into the open goal .
Historicslly have to say not the best scorers in the industry
Im very long on this now if it stays in the 170s will have to RNS soon .
NFG I treat a Stocko momentum score of 7 as a severe red flag. It seems the market sensed trouble miles in advance. The analyst consensus EPS plot paints a picture that explains it all. This announcement blows even those worsening expectations out of the water.
Shares are up 4% today. Go figure.
It seems the market sensed trouble miles in advance
is that not like saying every company at the bottom of 5 year price range is going down the pan. Ok poor momentum doesnt help - but clearly the 7 score relates to the events over the last 5 years and current expectations and not much more. - in that regard the number simply reflects the fact the company makes materially less than it did back in 2012 and 2022
Most established companies have poor runs with shareprice and momentum and bounce back latyer - its nonsense to over extrapolate from past events and say that such companies will always be a busted flush - momentum will likley turn at some stage and that is then opposite of what memoentum tells you will happen now !!
ignoring the tea leaves there has been constant donwgrade in expectations here ref company financials - while company continues too perform poorly its nmo surprise share price is going nowhere - signs of flattening or raising of expectations imho is likley to align with improving sharrpice - whatever the chart may say !
in summary chart is whatn it is does to poor results compared to peak years - not beacuse a chart predicted that would happen.
I've noticed that Rio Tinto (LON:RIO) is trading towards the bottom of its 5 year chart. I might look into it. Before I do so, I was wondering if anyone had any particular comments about the pros/cons of the company or any particular articles that are useful for me to read? I literally know nothing about them beyond they mine iron!!! I know that everyone says large caps are well covered but I find a lot of the commentary accessible to the hoi polloi tends to be quite high level.
I noticed it reports in US dollars so I'm assuming dollar weakness versus £ is not helping right now along with a lower iron ore price?
Rio Tinto (LON:RIO) transitioning from iron ore to copper and lithium which sucks up capital. Copper is trending up. Don’t know if Ferrexpo (LON:FXPO) has been stockpiling its high grade ore awaiting war end. Aluminium subject to high energy cost and move to cleaner processes and Chinese supply. Good value, profitable but not a growth story at the moment. Hold small position as well as Glencore (LON:GLEN). Don’t hold BHP (NYQ:BHP).
Tortoise Investor
You (and anyone interested in the Mining sector including Rio Tinto (LON:RIO) of course) might find this post I wrote in 2023 useful. Though it’s out of date now, many of the key points in it still apply and will continue to apply.
Also readers will see that it was forecasting a big Mining Sector bull market in 2024, with reasons why that will continue to apply.
Good news for anyone starting to look at the Mining sector now is that far from a bull market in 2024, it was a poor year with further falls for the share prices of the big Mining Companies (excluding gold miners).
Key reason the Mining sector is still in the doldrums in mid 2025 is the continuing problems in China, including their huge property debt. And as the post explains China demand is key for big commodity prices.
As for Rio Tinto (LON:RIO) it’s a high quality share that’s now right at a multi year low. I’ve held it for many years, originally buying towards the end of the big Mining bear market that ended in 2015. It pays huge dividends in the good years (e.g 20% yield in 2022) but far less in less profitable times like now.
More good news is that Rio Tinto (LON:RIO) is almost right at a multi year low around £41. I topped up recently at £42.
I also hold Anglo American (LON:AAL) , BHP (LON:BHP) , Glencore (LON:GLEN) (now recovering from a big fall) , and Investment Trusts BlackRock World Mining Trust (LON:BRWM), Blackrock Energy and Resources Income Trust (LON:BERI) and CQS Natural Resources Growth and Income (LON:CYN. I bought all of them either at the end of the 2015 Mining bear market or on the big covid dip.
For any looking for the Trust that holds many of the big Mining Companies look no further than BlackRock World Mining Trust (LON:BRWM) . This Trust gets covered quite often on the very good Investment Trust threads here.
https://www.stockopedia.com/co..
And here’s the link to that post and the follow on comments:-
https://www.stockopedia.com/co...
Chinese govt looking to gain an upper hand vs iron ore miners.
They established a new trading company last year, and gave it lots of backing, to be the principal buyer/importer of iron ore in China. Then distributing to all the steel mills, end users, etc.
Thinking is to have such a strong buying power and eventually the only buying power in China, that they can dictate the price they want. Rather than the other way round atm, where there are only a few large scale iron ore producers, especially in the high grade quality that Rio Tinto (LON:RIO) does.
So there is a big tussle over pricing power to come maybe...
JD Sports Fashion (LON:JD.) reacting to positive overnight news from largest partner Nike (NYQ:NKE). JD having a good week. Is it the start of a sustainable recovery?
MS International (LON:MSI) continue to behave like a sulky teenager, enigmatically ignoring their shareholders. Whilst they continue to perform, this gnomically insular behaviour can be looked upon as simply the quirky behaviour of an old fashioned, family / founder led business that is far too focused on the day to day endeavours, to be bothered with the niceties of keeping outside investors abreast of performance.
I would argue however that it's a fine line between quirkiness and arrogance. It's one thing to eschew analyst coverage, interim updates (or indeed any form of investor communication) but quite another to simply not release FY accounts or any financial calendar or any explanation as to why FY accounts haven't been released.
Last year's accounts were out on Jun 26, 2024 and Stocko had been showing FY25 accounts as due today. If they're not released today, surely it wouldn't be unreasonable to expect at the very least that their advisor (Shore Capital) might venture a date.
I 100% agree. But perhaps the perceived delay is a consequence of more than just results to be announced?
MS International (LON:MSI) with respect I disagree. Just because last year's results were out on 26/6 does not mean they will be this year. Stockopedia's estimate of this year release date is a guess based on last year and nothing else. Results have been as late as July in the past. Personally I would much rather the board focus on the business and feel lucky that I am able to invest in it.
Helvellyn, I do agree regarding MS International (LON:MSI) that the board should focus on the business and I'm happy to be invested here too. My point is only that it wouldn't be that big of a distraction for the board / Shore Capital / the company secretary to publish a financial calendar.
As to the usual date of the results - Stocko, and by extension Refinitiv, have the results due today which is coincident with pretty much all previous years. Indeed, since 2013, they have only once been later than June and that was 2020 when they came out on July 1st.
I've no doubt they'll arrive early next week, but it perhaps demonstrates a certain mindset to not want to keep investors informed of that date.
Frustrating definitely. But difficult to be too upset when the share price is hitting new highs. As alluded to above, it does beg the question as to whether something else is going on. From recollection, the founders are at a "mature" age...
My issue is that I am sitting on a 50% gain. It's tempting to bank some profit, but then, what might I miss out on. I hate this dilemma, however nice it is to have!
Dave
(edit MS International (LON:MSI) )
I think the point you are making johnsmith68 is valid, but in my calculations Management is part of the stock selection process. This management team have been totally consistent for a long time. They are unlikely to change now, that said they are in their 70s change is coming one way or the other.
MS International (LON:MSI) Stocko had 24/6 the other day. Their dates are often incorrect. But companies should publish the dates in advance. I'm sure in the US they more scheduled dates.
Re MS International (LON:MSI) I hold.
I actually quite like the idea of a Board focussing as much of their time as possible on making the business better rather than continually updating and reporting. As long as there is a long track record of improvement.
As others have said, you pays your money , you takes your choice, its not as if this behaviour is unknown.
What offends me,however, is the lack of their respect they show to fellow owners, such as small shareholders. Its like walking into an empty bar and the landlord blanks you. It costs nothing to be nice to your supporters and own kind !
Hopefully the delay is part of the strategic review, would be nice to announce a,sale of part or all of the business!!
IG group (LON:IGG) Roland, thank you very much for saving the rest of us from having to even read the capital reorg rns! Your simple explanation is very much appreciated! An even happier holder.
Good news related to Revenge taxes and Remittance taxes-
Bessent has asked Congress to remove the Revenge taxes (section 899) from Trump's tax bill.
https://www.ft.com/content/5d9...; (subscription)
https://thehill.com/business/5...
Additionally, remittance tax clarifications indicate that personal transfers from a US brokerage or bank account to a personal non-US bank account won't incur a 3.5% excise tax. (N.B. this source may not be reliable): https://www.pstein.com/blog/se...
Thankfully Bessent seems to be one of the few in the cabinet who is competent Laurie.