Daily Stock Market Report (Mon 13 Jan 2025) - POLR, FTC, PLUS, EYE, SOS, MACF

Good morning! I hope you had a restful weekend.
11.45am: we are all done for now! Cheers.
Spreadsheet accompanying this report (updated to 3/1/2025).
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Entain (LON:ENT) (£4.0bn) | Reiteration of FY24 guidance. | Group EBITDA at the top of the £1,040-1090m guidance range (previously: “towards the top”). | |
Plus500 (LON:PLUS) (£1.95bn) | Year End TU | Rev $768m, meaningfully ahead of market expectations. EBITDA $342m. Confident outlook. | GREEN (Graham) |
Oxford Nanopore Technologies (LON:ONT) (£1.27bn) | Full Year TU | In line. H1 revenue grows 1% (to $100m+), adj. EBITDA c. $30.3m. | |
Pagegroup (LON:PAGE) (£1.0bn) | Q4 2024 TU | 2024 operating profit towards lower end of range (£49-58.5m). Ongoing challenging conditions. | |
Craneware (LON:CRW) (£728m) | H1 FY25 TU | H1 revenue growth >10% to exceed $100m. Full year in line with exps, confident outlook. | |
Polar Capital Holdings (LON:POLR) (£488m) | AuM Update | Net inflows & positive market perf. AuM up 9% to £23.8bn at 31 Dec. | GREEN (Graham) |
Science (LON:SAG) (£203m) | FY24 TU & 2025 Buyback | 2024 record adj op profit “in line or slightly ahead” of exps. | |
Filtronic (LON:FTC) (£198m) | Trading ahead of expectations | Ahead of expectations. Order intake for the current year is higher than anticipated. | AMBER (Roland) |
| Macfarlane (LON:MACF) (£170m) | Acquisition of the Pitreavie Group | £18m price including £4m earn-out, all-cash. Funded by MACF’s existing bank facility. | GREEN (Graham) |
Eagle Eye Solutions (LON:EYE) (£139m) | H1 FY25 TU & Multi-Year Global OEM Agreement | Revenue warning. FY25 and FY26 revenue to be 15% and 18% below exps. Higher EBITDA margins mitigate impact. | AMBER (Roland) |
Quartix Technologies (LON:QTX) (£76m) | TU | FY24 rev £32.4m, PBT £6.0m. FY25 slightly ahead of expectations. | |
Hercules Site Services (LON:HERC) (£35m) | Final Results | “Ahead of expectations”, continuing rev +28%, adj PBT +43%. Positive outlook. | |
Sosandar (LON:SOS) (£16m) | TU & New Store Agreements | In line with expectations of £40.5m revenue and £1m PBT. Two new leases for its own stores. | AMBER/GREEN (Roland) |
Huddled (LON:HUD) (£10m) | TU | FY2024 loss in line with expectations. Revenue >£14m, “exceeding exps”. Cash £1.6m. |
Summaries
Polar Capital Holdings (LON:POLR) - unch. at 486p (£496m) - AuM Update - Graham - GREEN
This fund manager suffers a net outflow of £260m in Q3 (£360m if you include the planned closure of a fund). Assets under management rose anyway, thanks to the tailwind of positive market movements, and are up by 9% in the financial year to date. I continue to rate this highly as a pick within the fund manager space. Net flows are still positive overall for the current financial year.
Plus500 (LON:PLUS) - down 3% to £25.60 (£1.92bn) - Year End Trading Update - Graham - GREEN
Today’s full-year update requires some interpretation; the company has “meaningfully” beaten full-year revenue expectations, but this has not been converted into a meaningful increase in the EBITDA result. The company argues that its higher marketing spend will convert into medium- and long-term success but as I’ve argued before, the trading life of a PLUS customer is not typically all that long. Either way, I’m happy to stay positive on this as I’ve learned not to doubt the company’s ability to generate cash and with $900m of its own cash already on the balance sheet, I don’t view this stock as expensive at this level.
Eagle Eye Solutions (LON:EYE) - down 22% to 366p (£109m) - H1 FY25 TU & Multi-year global OEM agreement - Roland - AMBER
Today’s half-year update from this loyalty scheme software specialist reveals a double-digit cut to revenue guidance for FY25 and FY26, with a similar cut to broker earnings forecasts. Eagle Eye is operating in a growing market and benefits from net cash. However, slower sales cycles are a potential concern. I’d like more clarity before considering whether to catch this falling knife, so I’ve downgraded our view to neutral ahead of March’s interim results.
Macfarlane (LON:MACF) - down 1% to 106p (£169m) - Acquisition of the Pitreavie Group - Graham - GREEN
I’m giving the acquisition the thumbs up: the price is a little high but MACF can afford it and the rationale is sound. MACF is cheaply rated and worthy of further investigation in my view.
Short Sections
Filtronic (LON:FTC)
Up 7.5% to 97p (£214m) - Trading ahead of expectations - Roland - AMBER
The supplier of electronics to Space X (and others) has issued another upgrade to guidance, less than a month after its previous upgrade. Management says that “order intake for the current financial year is at a higher rate than anticipated”. Full year results are now expected to be ahead of recently-upgraded market expectations.
Helpfully there’s an update from broker Cavendish on Research Tree this morning. FY25 revenue forecasts have been increased by 11.5% to £48.4m, with adjusted EBITDA up by 22.3% to £13.7m. FY26 forecasts are unchanged. It’s worth pointing out that the company’s brief RNS this morning gives no idea of the substantial scale of today’s upgrade, leaving investors without access to broker notes at a disadvantage.
Filtronic clearly has strong momentum at the moment, but I can see a couple of potential concerns. One is customer concentration – how much of Filtronic’s business is now dependent on SpaceX? Secondly, in December, management said customer orders were being pulled forward (i.e. not additional orders). That comment has not been repeated today, but Cavendish’s decision to leave FY26 forecasts unchanged means that revenue is now expected to fall by 15% next year. Operating leverage means FY26 EBITDA is expected to fall by 31%.
Roland’s view: I remain broadly positive about Filtronic as a business. But the shares are now trading at 32 times FY26 forecast earnings, and there appears to be a risk that profits could fall sharply next year. I’d prefer to stay neutral, at least until the company’s interim results (six months to 30 Nov) are published in February. AMBER.
Sosandar (LON:SOS)
Up 7.2% to 6.7p (£16.6m) - Trading Update & new Store Agreements - Roland - AMBER/GREEN
This women’s fashion retailer has seen its share price fall by more than 75% over the last three years. Today’s update shows sales of £12.2m during the three months to 31 December (Q3 FY25), down from £14.3m in the prior year. The company says this reflects a transition away from promotional activity to full price sales.
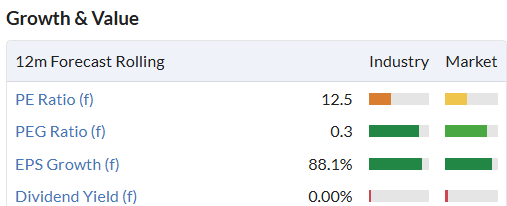
Gross margins were improved at 64.7% (Q3 FY24: 58.3%) and the company says trading remains in line with market expectations for a pre-tax profit of £1m for the year ending 31 March 2025. Stockpedia’s consensus forecasts suggest a rolling P/E of 12.5 with a potentially attractive PEG ratio of 0.3:
Sosander has switched strategy from being online only to pursuing an omnichannel model. It’s opening stores, and today confirms new locations in Bath and Harrogate “where Sosander customers over-index” and says it’s also a top-selling brand on the NEXT and M&S marketplaces.
My main concern here is that you can’t shrink your way to growth – I would want to see revenue starting to rise fairly quickly to justify a more positive stance. But I think this business could be worth a closer look for micro cap investors, at current levels. AMBER/GREEN (Roland).
Graham adds: I am very sceptical of the change in strategy at SOS. The whole point of this company was to provide a pure-play online women’s fashion brand, not just another fashion chain with physical stores. As it is now just another clothing chain, I don’t see any attraction here except for the cash balance (£8m), much of which is likely to be spent on the store roll out. Personally, I’d stay AMBER for now while they try to prove their new business model.
Graham's Section
Polar Capital Holdings (LON:POLR)
Unch. at 486p (£496m) - AuM Update - Graham - GREEN
This is a Q3 update, as Polar’s year end is in March.
In November, we reported on how Polar was one of the vanishingly few fund managers in the UK experiencing net inflows (net flows of £472m for H1, April-Sep 2024).
Unfortunately, this is no longer the case as net flows for the 9-month period (April-Dec 2024) are now only £212m, implying outflows of £260m in Q3. While the Emerging Markets funds continued to enjoy inflows, there were outflows from the European Opportunities Fund, the Global Technology Fund and the UK Value Fund.
CEO Gavin Rochussen points out that flows during this Q3 period are still much better than they were during the corresponding Q3 period last year. Last year, clients withdrew a net £1.1bn in Q3.
He also notes that the broader funds industry, and Polar itself, was particularly weak during the Budget period:
"Net outflows during the quarter were primarily concentrated in October, mirroring the broader UK funds industry, which experienced its third worst month on record ahead of the Chancellor's Autumn Budget. Including the impact of a fund closure, net outflows for the month of October totalled £301m. Net outflows in December were £76m. November saw net inflows of £17m.
Looking on the bright side, market movements have been very positive and have boosted AuM by almost £1.5 billion in Q3, having a far larger impact than the outflows during the quarter. AuM has risen to £23.8 billion.
Performance fees: good news here with £8.3m of performance fees earned in the financial year to date, not far off last year’s £9.6m. Most of these fees relate to one fund.
Graham’s view
I’m slightly disappointed that Polar couldn’t pull another rabbit out of the hat and give us another quarterly inflow. However, there are many consolation prizes: the improved year-on-year performance, the stabilisation in Nov/Dec, the fact that the entire industry funds industry suffered in Oct, and the positive market movements helping to sweep Polar’s AuM up to fresh highs.
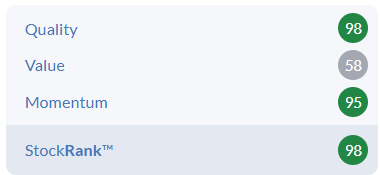
I continue to view this as a quality business trading at an attractive price. The StockRanks are in agreement: the QualityRank is 99, while the overall StockRank is 94.
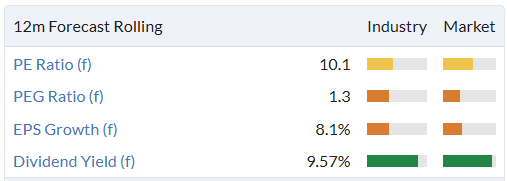
Plus500 (LON:PLUS)
Down 3% to £25.60 (£1.19bn) - Year End Trading Update - Graham - GREEN
At its Q3 update, CFD trading platform PLUS said that its market expectations were:
Revenue $724.5m
EBITDA $338.3m
It also said that it was trading in line with expectations.
Today we learn that the full-year outcome is going to be:
Revenue $768m
EBITDA $342m
The question that immediately springs to mind is why EBITDA hasn’t come in much higher, given that that revenue is “meaningfully” ahead of expectations.
The answer is that they’ve been spending heavily on new customer acquisition:
The Group's sophisticated and proprietary marketing technologies drove a significant increase in New Customer acquisition during the year, including more than 36,000 New Customers in Q4 2024 alone, which equates to an increase of c.45% versus Q3 2024. As the Group has consistently demonstrated historically, current customer acquisition lays the foundation for future performance, making it an investment in Plus500's medium to long-term growth.
However, as I’ve argued before, customer churn is a big issue at PLUS. In the first nine months of 2024, the company recruited 82,000 new customers (15% higher, year-on-year), but its total number of active customers nudged up only very slightly to 211,000. Is it possible that customer churn is getting worse?
Today we learn that the company just recruited 45,000 new customers in a single quarter, helping to boost revenues by $40m+ vs. expectations, but the EBITDA result didn’t budge. All of that customer recruitment must have been very expensive - as these new customers continue to trade in H1 2025, perhaps we will see the investment feeding through to a better EBITDA result in the new year?
A falling EBITDA margin is not a new issue at PLUS. In October we were told that falling margins were due to “the ongoing investment which the Group has made and will continue to make to enter new markets, develop new products”.
It’s fortunate that the company has such enormous profit margins to begin with (over 40%), so that it can afford to go heavy on investment. The full-year result is now headed for an EBITDA margin of 44%.
Cash falls from $950m in September to $900m in December.
Strategic progress: PLUS has gained a clearing membership with ICE Clear US (part of the Intercontinental Exchange, one of the biggest exchange groups in the world), and a new license in the United Arab Emirates.
2025 outlook: confident. PLUS is “well positioned to continue executing against its strategic roadmap of expanding into new markets, developing new products and deepening engagement with customers…”
Graham’s view
I’ve always been a little bit critical and a little bit sceptical about this one. However, I’ve also learned to stop doubting its ability to generate cash, and I’ve been fully GREEN on this for a year, during which time it has generated a total return of over 50%.
If I was to put my sceptical hat on, I would argue that customer churn seems to be getting worse, raising the ever-present risk that the company’s marketing machine runs out of prospective customers to target. EBITDA margin is falling and cash is falling as the company has to spend ever larger sums in order to find new recruits.
But that would be overly negative, I think. An EBITDA margin of 44% is still excellent, no matter which way you look at it. It’s the sort of margin that most companies in most industries would envy.
Furthermore, the cash balance is still (probably) large enough to manage any risk associated with customers’ unhedged trades, even after all the investment activity in recent months, and after $360m was returned to shareholders in 2024 in the form of buybacks and dividends.
Finally, the company's new licenses point to an increasingly diverse and sophisticated product set.
I’m going to stay GREEN on this, while reiterating that I consider CMCX and IGG to be lower-risk investments (I’m long IGG).
Macfarlane (LON:MACF)
Down 1% to 106p (£169m) - Acquisition of the Pitreavie Group - Graham - GREEN
This Glasgow-based packaging group announces a meaningful acquisition, costing c. 10% of its market cap.
Pitreavie (external link) “designs, manufactures and distributes protective packaging, supplying to customers in the food & drink, energy, electronics and industrial sectors, primarily in Scotland.” It has 159 employees at four locations across Scotland.
Rationale: “The blend of businesses Pitreavie operates complement both the Distribution and Manufacturing operations of Macfarlane.”
Financials: Pitreavie generated sales of £24.8m in 2024, adj. EBITDA of £2.5m and adj. PBT of £1.3m.
The price: £18m, including an earn-out of up to £4m over two years.
Macfarlane will inherit debt of £4m but will get paid a “completion adjustment” to reflect this, effectively a refund on the purchase price..
How to fund it: using MACF’s £40m bank facility. Checking the most recent trading update in November, I see that MACF’s net bank debt was only £5m, so it sounds like they have plenty of headroom available to fund this.
CEO comment:
"Pitreavie is a fast-growing, well-invested company with an experienced management team that is fully committed to the business. The acquisition represents a unique and exciting opportunity to grow our business in Scotland and provide in-house supply to our businesses in the North of England."
Graham’s view
I do like small, debt-funded acquisitions that are still large enough to make a useful contribution to overall profits.
The price paid for Pitreavie is arguably a little punchy. The trailing price to sales ratio for the deal is 0.72x, which is higher than MACF’s own trailing price to sales ratio.
Similarly, the adjusted P/E ratio for the deal is 18x, much higher than MACF’s own P/E ratio.
At least the risk has been mitigated by the earn-outs: if Pitreavie doesn’t meet targets over the next two years, then the P/E ratio would reduce to 14x.
And as part of a larger group with shared buying power and expertise, we can of course hope that Pitreavie’s profitability will be reinforced in the years ahead.
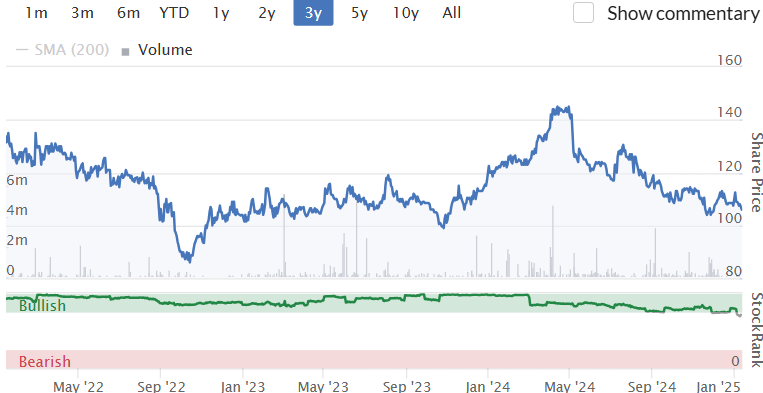
Overall, I’m going to give this deal the thumbs up. The price does seem a little high to me, but MACF can afford it. MACF itself remains an interesting proposition at this valuation:
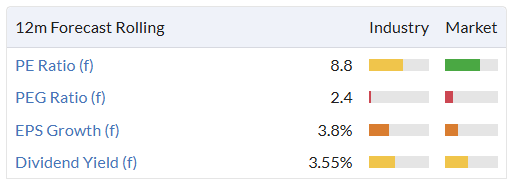
Both its share price and its profits have treaded water in recent years:
Roland's Section
Eagle Eye Solutions (LON:EYE)
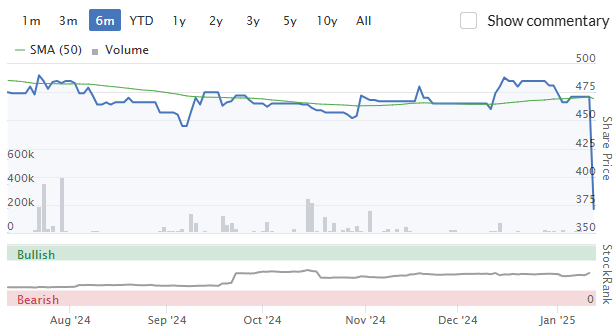
Down 22% to 366p (£109m) - H1 FY25 Trading Update & Multi-year global OEM agreement - Roland - AMBER
Eagle Eye specialises in providing software that creates tailored customer discounts for retail loyalty scheme members. Unfortunately today’s update appears to be a profit warning.
FY25 & FY26 Revenue is now expected to be c. 15% and 18% below current market expectations, respectively
The company has also issued a second RNS today about a new partnership agreement. No numbers are provided but the deal has been hailed as a “game changing opportunity” by management.
However, investors seem more focused on the numbers today. The shares are down by 22% as I write:
Checking back in the archives, we’ve covered Eagle Eye regularly in the past, most recently here.
Let’s unpack today’s updates in a little more detail – and try to estimate the impact of today’s downgrade on expected earnings.
H1 trading update: new wins secured during the first half of the year have included “a leading UK retailer”, plus Waterstones, Côte, RONA (in Canada) and Transa Backpacking (Switzerland). The company’s previous last TU in November also mentioned work with Asda and “increased engagement” with Morrisons.
However, this work does not appear to have translated into an improved financial performance. The H1 financial summary today shows flat revenue and EBITDA profits for the half year:
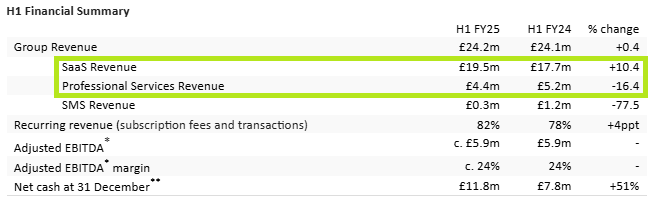
Like many software companies, Eagle Eye is trying to shift its business away from one-off fees and towards recurring subscription revenues. This does sometimes result in weaker near-term revenue, but stronger long-term performance.
We can see this in today’s update – highlighted above – with SaaS (subscription) revenue up and professional services revenue down. SMS services are largely being phased out, from what I understand, so I’d ignore these.
The proportion of recurring revenue has risen to 82% from 78% in H1 last year. I see this as positive, as it should help to support predictable cash flows.
Adjusted EBITDA isn’t my favourite measure of profit but has remained stable, with an EBITDA margin of 24%. This suggests the shift from professional services to SaaS is not affecting profitability.
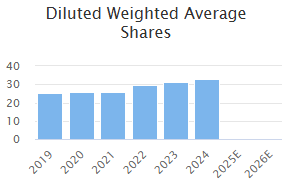
Net cash was £11.8m at the end of December, an increase of £1.4m from the end of June 2024. This represents 10% of the market cap after today’s fall – a useful buffer to support continued growth and protect equity holders. Hopefully this means no further dilution will be required:
Outlook: this is the bad bit.
Eagle Eye says that SaaS revenue is expected to continue growing at double-digit levels in FY25 (y/e 30 June) and FY26, but group revenue is expected to be c.15% and 18% below current market expectations, respectively.
The company says this is due to “lengthening sales cycles due to the macroeconomic climate” and a continuing decline in professional services revenues.
Consensus revenue forecasts on Stockopedia were previously £56.4m (FY25) and £64m (FY26). My sums suggest the updated figures based on today’s guidance should be £48m and £52.5m, which is supported by updated estimates from broker Shore Capital today.
The company says the impact on profit will be mitigated by (implied) higher EBITDA margins of between 24% and 25%.
I say implied, because Eagle Eye reported a 24% EBITDA margin in both FY24 and in today’s H1 numbers. So this only seems to be a very modest improvement in profitability.
However, Shore Capital was apparently expecting margins to fall to 22%/23%, so today’s guidance does represent an improvement on prior expectations.
Dropping down to the bottom line, Shore has made the following changes to its earnings estimates today:
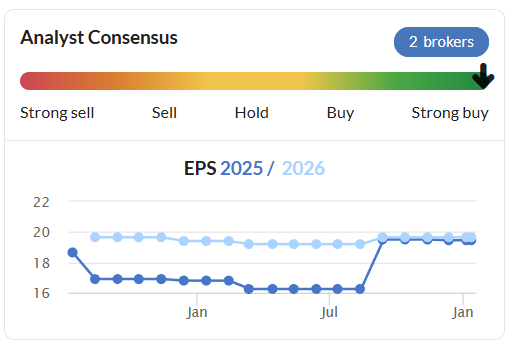
FY25 adj EPS down 11% to 20.1p (previously 22.5p)
FY26 adj EPS down 17% to 17.6p (previously 21.3p)
Previous consensus estimates shown in Stockopedia were just under 20p for both years. This means that today’s update represents a significant downgrade to the outlook for FY26, in particular, which is now expected to see a material drop in profits versus FY25.
“Game-changing” OEM agreement: in a separate RNS today, Eagle Eye has reported (limited) details on a new five-year partnership with “one of the world’s largest enterprise software vendors”. The company isn’t named.
Eagle Eye’s software will now be integrated into the vendor’s own “new cloud-based loyalty solution”. This is due for launch in 2025 with first customers live in early 2026.
The new loyalty solution will apparently have key elements of Eagle Eye’s platform embedded into it:
including its highly flexible and scalable Omnichannel Promotions, Real-Time Loyalty and Cloud-based Basket Adjudication services
No figures are provided, but this partnership is said to provide Eagle Eye with the opportunity to expand into new global markets and sectors:
Once the product is live, the agreement provides the opportunity for significant contribution to Eagle Eye's Annual Recurring Revenue over time, with a minimum three-year commitment commencing in the current year.
Roland’s view
Today’s partnership news sounds positive, but at this stage I think it’s impossible to know how much value we might attach to it in terms of future earnings.
Today’s cut to FY26 revenue guidance suggests to me that management and the company’s brokers are not factoring more than a minimal contribution in FY26 at this stage.
Using Shore Capital’s updated earnings estimates, Eagle Eye shares are now trading on a FY25 P/E of 18, rising to a FY26 of c.21.
That’s actually cheaper than the stock’s rating at last night’s close:
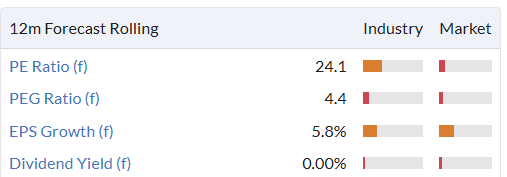
I think the caution implied by the market’s de-rating of the stock is sensible.
Although today’s update does not suggest any fundamental problems with the business to me, I am concerned by the apparent low profitability of this business. Slowing growth suggests to me that improvements in margins could take longer to come through:
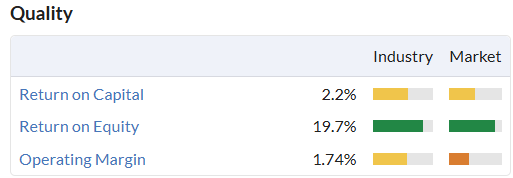
I am not tempted to rush in and buy after today’s profit warning. However, Eagle Eye does appear to have positive cash flow and benefits from a substantial net cash balance, so there doesn’t seem to be any near-term risk of financial distress.
I’m going to reduce our view to AMBER for now, pending a review of the half-year results when they’re published in March.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

56 comments
UK 10 year gilt yields hit 4.9%.
Small caps as usual bear the brunt. Unfortunately my portfolio is no exception Volex (LON:VLX) Kitwave (LON:KITW) Bloomsbury Publishing (LON:BMY) Eurocell (LON:ECEL) and others. All good companies that in normal markets would be trading at much higher prices.
Government borrowing cost continue to increase. Something has to give, as to what remains to be seen. Perhaps someone wiser to me has an insight?
The only facts that are known about the current gilt yield is that on the 26th March the OBR meets to report on the financial situation. If the gilt yields remain at current levels then the cost of Government borrowing will almost certainly exceed the 9 billion headroom that Rachel Reeves allowed for in the Budget.
It is assumed that the OBR will then call for another Budget to address the deficit - something that Rachel Reeves is loathe to do. Yes - clearly someone will have to back down.
What investors do about this situation is probably dependent on their age and style of investing. I have been investing nearly 50 years making steady gains from a relatively boring style of investing. I don't think that I want to ride out another downturn so my current style is defensive/cash.
If people want to hold through a downturn then they will probably have to consider how the Government might react to bad news on the 26th March. There are 3 Government options
Change fiscal rules
Increase taxation
Reduce Government spending
The disappointment for me is that Rachel Reeves has needlessly boxed herself into a corner. She has rejected the first two options with the third option being a potential war with the Unions. Ouch.
Off course - gilt yields might come down of their own accord and Rachel Reeves might pull of an improbable escape. Nobody knows for sure.
Why have City of London Investment (LON:CLIG) fallen off a cliff today???
Property shares are at bargain levels
I am watching the shares of the real estate and other property stocks dropping like a stone. Bond's yields are to blame. The drop is not limited to big or small property shares but also the reasonably save healthcare groups like PHP and AGR with secured rental income.
Surely, sooner than later there will be great values here for the astute investors. Taylor Wimpey ar £1 and Persimmon at £10 , arbitrary though it maybe, has proved a good entry point for me in the past.
REITS looks like a good sector right now.
My favourites are Supermarket Income REIT (LON:SUPR) and Assura (LON:AGR) as they have safer tenants, are in sectors with long-term structural growth prospects, they both have massive divis of c.9.5%, decent discounts to (depressed) book values albeit those might get rated down further given current rates and - importantly - most of their current debt is not due for renewal anytime soon so hopefully they will end up renewing on much more favourable terms then they can access today.
But you can also play the REIT game through a ETF called iShares UK Property UCITS ETF GBP (Dist) (LON:IUKP) which also has a divi, albeit smaller.
Brighton Pier (LON:PIER) is a bellweather of discretionary spending. It has fallen off a cliff this week. An ominous sign.
PIER probably need to raise some cash- gearing is very high.
Why is an American micro cap covered here?
Good luck anyone going long atm. Or is that just the fear taking over?
Have 15-20 quality companies on a watchlist, every time I consider buying prices drop some more.
A number of errors on the 'tickers' attached to companies reporting . seems to be a recurring theme??
Morning guys, HERC should be this one....Hercules Site Services (LON:HERC) rather than the US micro-cap traded...cheers!
Similarly - Should SOS be linked to Sosandar (LON:SOS), which is up 7% today. NOT the NYQ listed version - a different company which is DOWN 2.4%
Yes, the tickers sometimes default to the wrong ones, I then manually go in and fix them. They are fixed now!
Morning Graham, the ticker entered for SOS is for the NYSE entry…
I would welcome your comments on the announcement from Sulnox (OFEX:SNOX) this morning. I invested first in 2022 after seeing the company present at Mello and although the progress was not as fast as originally hoped, there now appears to be good traction. The company is addressing a large market in shipping, which is now having to comply with much more stringent emissions standards. I have not seen the share mentioned here on Stockopedia and wondered if that is because it is listed on Aquis.
Yes the most interesting RNS of the day with aspects I’ve never seen before . A buyer tasked with marketing in its sector ( shipping) and able to acquire shares at 2 pence to compensate . Plus commits to providing real operational data. It has trebled from the recommendation last year by the Times so a shame not followed by Stocko . Punchy price now but huge potential .
Get an extra 10% off all our companies use code UK10 at checkout”
Thats a headline we would have sent in a newsletter at plsnet x , would probably give a 50% uplift in sales .
(We once did a 25% off one on Christmas day and had a 10 times uplift )
, freight , energy , oil , GBP - cumulative negativves,
US acquisition frenzy coming ?
Going to be a tough year for any company with these issues
Freight - container prices from far east heading north
Energy - prices on the rise
GBP - importers stuffed by GBP to USD reversal
So
- inflation has to go up .
But
Values of companies are really cheap already , with USD to GBP the american buyers have just been give a “get an extra 10% off” discount code .
“Get an extra 10% off all our companies use code UK10 at checkout”
I notice a news report on Stocko this morning that "St James's Place hands 5.2 bln pounds fund to Schroders in blow to Impax - FT" Did I miss this previously or is this hot off the press?
Morning Peter T,
Impax Asset Management (LON:IPX) announced in December that it had lost the £5.2bn St James's Place (LON:STJ) mandate (see here), so this isn't news.
What is new today is that we now know Schroders (LON:SDR) will be taking over these assets.
Roland
Thanks Roland, I was aware of Impax losing it (being a sad holder at the time) but not that it has gone to Schroders, but as you confirm, this is news. I thought this may have a positive affect on Schroders (LON:SDR) SP but no. Thoughts anyone?
Edit: looks like it might be starting to move up a little now. Maybe the news filtering out? I see that Schroders have now confirmed it also but have not RNS'd it.
Not looked at Schroders (LON:SDR) for a while but surprised how far it's fallen. As a much bigger group, I guess the SJP mandate doesn't really move the dial for Schroders, especially given that it's a low margin mandate.
For their sakes - I hope Schroders (LON:SDR) do better for St James clients than they did for Woodford's Patient Capital
Still no idea why Schroders got involved with the Woodford patient capital trust - it was always going to turn out badly given the junk in there and would only end up tarnishing their reputation.
Filtronic
Quite annoying, though of course a good annoying, that the continual “ahead of previous” all lack any actual numbers .
I just counted i think four cumulative ahead of since August results .
Still my biggest holding by far despite top slicing three to four times think just have to let this run now .
I cannot see how Space X unless they are feeling very generous to Amazon will let Amazon use a key supplier makes no sense to allow this.
So Space X look likely to be forced to bid to protect their production, stay ahead and block a competitor .
And I would imagine they will not make a low offer
Plus of course USD to GBP strength thanks to car crash lack of confidence in UK means its salready at a 15% off price
Filtronic (LON:FTC) fully agree Planet X. Price will rise not just due to the detail-less "ahead of" updates but also in anticipation of a protective bid from Elon.
Hi PlanetX. Just to point out, Amazon have PARTNERED with SpaceX on their satellite business. So, any Amazon demand will be filtered through that collaboration... I don't think SpaceX will want to buy FTC
As I understand it, Amazon are using Space X's launch services and Falcon 9's in sending their own satellites into space. The actual satellite business (Starlink and Project Kuiper) remain totally independent of each other.
Good point. So actually Amazon will probably be a new customer for FTC (ie in addition to SpaceX). But you would expect some basic undertakings in the Amazon-SpaceX partnership agreement about restrictive actions (ie not buying a key supplier like FTC, withholding key components and being anti-competitive)?
Yes, I believe that Amazon will want to setup their own LEO satellite constellation and have stated they want to start with 3000. They will need Filtronic (LON:FTC) technology on board to be able to match Starlink.
Whether Bezos and Musk even if they have an anti-competitive agreement in place could be trusted is one thing. I suspect that the UK government, and/or US mergers and acquisitions would have something to say which would carry more weight.
I am less worried about Filtronic (LON:FTC) being used by one company as I was last year. Plenty of companies use (for example NVIDIA chips), without worrying about their competitors. Car parts are another example Dowlais (LON:DWL) I seem to recall that 50% of all cars use parts manufactured by them (or on license), which is where I can see this heading.
Re Filtronic (LON:FTC) and LEO links.
My understanding is that Filtronic is supplying E-Band technology (extremely high frequency band 60-90GHz) to Space-X/Starlink.
These are power amplifiers for the E-Band backhaul/gateway earthstations -not the satellite payloads?
E-band has not previously been used operationally in orbit. These links are much higher bandwith and hence throughput. As they are effectively experimental I expect that they will initially operate in addition to the existing Ku (12-20GHz) band gateway links.
Filtronic's special sauce has always been in coherent power combining at the highest frequencies. Very few suppliers of such high power at E-band frequencies. I expect that Filtronic currently has the highest power on offer for these earth stations.
As far as I can see Project Kuiper uses Ka Band links (20-30GHz) not E-band. Still high but not crazy high. There are more potential suppliers at these frequecies.
I would not assume that Filtronic (LON:FTC) automatically becomes the Kuiper gateway earthstation power amplifier supplier?
These are just my thoughts as an interested bystander I've not looked at this in great detail and I'm a little out of date with my LEO network and constellation design these days,
cheers
Mark
I'm just a lay person so I defer to your knowledge on this, although the reason that Filtronic (LON:FTC) does well is the amplification of E-band works and works well for LEO, especially when it comes to consistency.
The weather affects how the operational effectiveness of the satellites and whilst Kuiper is and will deploy Ka-Band, it's not as cutting edge as what the guys at Filtronic (LON:FTC) do.
I think the key is, using as much frequency as possible and combining them together which Starlink have set out using V-Band. Project Kuiper has been around some years now, so it may well have set out on a stall that leverages existing tech, but doesn't have much experience when it comes to practical use and providing coverage to actual customers.
My view is why would you not want to use better tech when it has been demonstrated it works en mass? Or at least have a part of it in your arsenal - unless Bezos genuinely feels that he can offer a product without the additional capacity that using other bands will provide?, in which case, no Filtronic (LON:FTC) might not be your number 1 go to. But I think you'd still give them a call...
I still find it amazing that Inmarsat which got taken private from its uk listing a few years ago didn’t have the vision to see this white space that the two billionaires are going after, despite being one of the de facto satcoms players for a long time….Polaroid, Kodak, etc…
Yup. And Nike aren’t going to buy Zotefoams (LON:ZTF) .
Good to see the BBC getting stuck into Shein at last, utter disgrace of a company
To be fair and balanced .
BBC reporting on chinese companies is notoriously piss poor .
We buy all our goods from china and whether its JD Sports, Sports direct, ANY big company with mass production is going to using what we call sweatshop labour.
I once had a really really good supplier, they made bags as well as toys .
THey supplied Disney and Disney did a WEEKLY check on all factories production which was a benchmark in maintaining factory .
The factory was clean, audited and checked by Disney , world class
Strangely they made teletubbies for the BBC licensee
Then bless them front cover daily mail
Child labour scandal”
A reporter posing as a buyer had been in the factory and taken lots of photos of very snall chinese workers who all looked about 12 .
The owner was devastated
”Why would I use child labour the national wage is 200 usd per month “
Ps - i mean “we” as a nation .
When is the gov going to cancel or significantly reduce the VAT exemption for 'small' parcels sent direct from China - which at the moment stands at £135 and is a major factor in these coys undercutting retail businesses in the UK
Perhaps this is what our Rachel really went to China to talk about, and if not should have.
Goods worth £135 or less in total
If you bought the goods yourself and they are not excise goods, the seller will have included VAT in the total you paid.
You will need to pay VAT to the delivery company if the goods are:
From gov.uk https://www.gov.uk/goods-sent-...
It's certainly the case when you buy from Aliexpress, they charge VAT.
Hi Dragon, re VAT on foreign goods, can you clarify please. It sounds like you pay vat to the seller and again vat to the delivery company. if so, VAT charged by seller, presumably is collected by the foreign government and charged by the courier presumably to UK revenue. Am I right?
If I buy from Aliexpress they will add 20% VAT at checkout, they then pay that VAT to the respective country the item is sent to. This was an EU policy, which came in just before the UK left the EU, and the UK adopted it. When the item arrives in the EU/UK, it should be marked duty paid, so you don't pay anything to customs or courier.
Thanks Dragon, good to hear first hand. I was recently looking at Aliexpress wondering about that.
That's a helpful clarification Dragon - thank you! But it looks like customs duty isn't applied below £135 - although I am less sure of whether that leaves UK companies at a competitive disadvantage. Do companies importing goods manufactured elsewhere have to pay customs duty even if they are shipping it to themselves?
Only for the brave. Conygar Investment Co (LON:CIC) Market cap of £25m. Debt of £56m. Write down on net asset value. Absolute terrible stock rank! But it is at a 60% discount to NAV and the bod keep buying with the latest bod rns today for £50k. Revenues tend to be sporadic due to being in the property business. I wouldn't buy atm with the chart in a continual down trend, but worth watching for it to bottom and show signs of recovery.
Conygar Investment Co (LON:CIC) - gmtrader, I was a shareholder in this at one point when it was doing well. I wouldn't buy back in at any price. The reason I sold was due to the directors taking highly excessive remuneration for part-time work . It was a lifestyle property company!
Good to know topvest. Just watching it. Bod buys I watch regularly.
Prime Minister sets out blueprint to turbocharge AI
Artificial intelligence will deliver a decade of national renewal, as part of a new plan announced today (13 January 2025).
https://www.gov.uk/government/...
Any UK listed companies worth investigating as potential beneficiaries?
Cordel (LON:CRDL) could benefit from more investor attention. Looks like a quality commercial application of AI IMO....I hold
if they can survey the road network as well as rail that could enhance their potential significantly
Strange no one talks about the dangers of AI anymore.
Anyone seen the Terminator film?
Looks like all foreign companies. The UK lead the world in AI, which planet is Starmer on?
Capita (LON:CPI) looks interesting - the CEO and other senior management have joined from Amazon Web Services, with the aim of integrating AI into the business, partnering with Microsoft and others to do this. And with the shares at 13p there must be considerable upside if they can win new contracts using AI. (I hold)
Another ‘trading ahead of expectations’ from Filtronic (LON:FTC)
Great little uk business, well done to those who spotted this last year, feel I’m a bit late to the party to buy now though
Filtronic (LON:FTC) late, yes, but party still going on! Bezos Musk clash could ignite further in testosterone mist.
Filtronic (LON:FTC) (I hold) interesting announcement with more orders awarded from the SpaceX program than expected which has given rise to further increases in revenue over and above an ahead of expectations forecast.
Is there a way to determine if Filtronic (LON:FTC) are charging SpaceX in USD or GBP? The USD has climbed against GBP in the last 3 months. This could have a material impact on the bottom line. I wouldn’t get too carried away just yet until more details are released.
You could have thought that you were late to the party 12 months ago when the Filtronic (LON:FTC) price jumped to 21p and the PE was 45x. But you would not have been!