Daily Stock Market Report (Mon 14th September 2026) - KEYS, CER, TRB, KMK, DATA, MPE

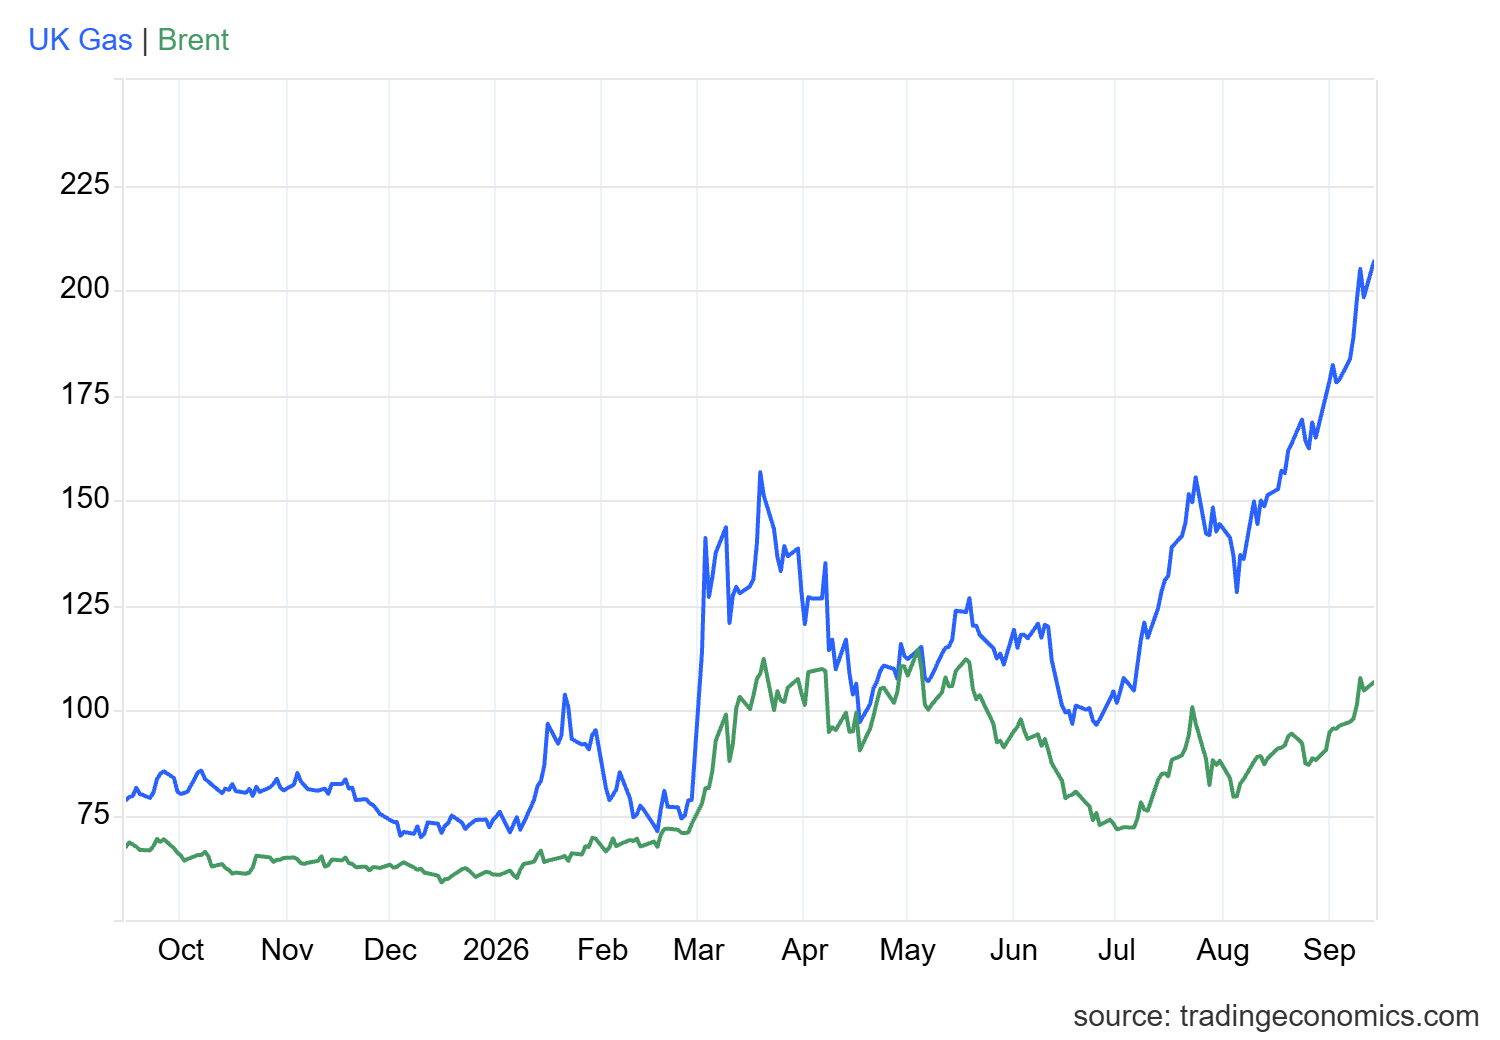
Good morning. Oil and gas prices rose sharply over the weekend, as planned talks among Gulf states to reopen the Strait of Hormuz were postponed.
Energy prices were already higher following last week’s attack on Saudi Arabia’s east-west pipeline, which forced it to close. The route had previously allowed some exports to bypass the Strait of Hormuz to reach the Red Sea.
In AI, the FT reports that Anthropic claims to have been profitable for the second straight quarter, ahead of a planned IPO later this year.
Politics continues to intrude into the AI sector, though. Anthropic founder Dario Amodei published an essay on Saturday outlining the case for AI development to be slowed in order to allow developers to better understand the risks involved. His conclusions were backed by SpaceX CEO Elon Musk and OpenAI founder Sam Altman.
According to Bloomberg, even China’s “top intelligence official” has warned that the pace of AI development “could threaten political stability”.
However, the market view seems to be that President Trump will apply pressure on the sector to ensure US leadership isn’t threatened, while Wall Street will be keen to maintain the frenetic level of financing activity.
Reflecting investors’ fear of a potential slowdown in spending, shares in AI investor SoftBank (TYO:9984) fell by 12% this morning on the Tokyo market, while chipmakers Samsung Electronics (KRX:005930) and SK hynix (KRX:000660) were also down sharply.
Let’s take a look at the company news closer to home.
Overnight market movements:
The FTSE is up 0.2% at 10,665
S&P 500 is down 0.5% at 7,617
Brent crude (November) is up 2.1% at $106.77/bbl
Gold is up 0.1% at $4,338/oz
Bitcoin is up 1.0% at $77,583
Ed Sheldon joins me (Roland) today.
Today's report is now complete.
Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
AstraZeneca (LON:AZN) (£182bn | SR44) | SERENA-4 trial did not meet primary objective of statistically significant improvement in progression-free survival, however a numerical improvement was observed. | ||
GSK (LON:GSK) (£72bn | SR81) | Jideytro positive data for ROS1-positive NSCLC & Ris-Rez Positive Ph 3 OS Lung Cancer Data in China | Jideytro: Results support potential to address key efficacy and tolerability needs in ROS1-positive NSCLC with US regulatory submission planned in 2026. | |
Beazley (LON:BEZ) (£7.9bn | SR60) | All regulatory conditions are now satisfied. Court hearing scheduled for 22 September 2026, with completion data expected to be 1 October 2026. | ||
Metlen Energy & Metals (LON:MTLN) (£5.8bn | SR63) | Petronas will deliver 6 LNG cargoes per year to Greece from its Atlantic portfolio, amounting to approximately 0.6 billion cubic meters per annum (bcma) over a period of five years commencing in 2027. | ||
M P Evans (LON:MPE) (£983m | SR96) | H1: total crop processed +8%, with gross profit +25% to $78.9m and earnings per share +21% to 86.5p per share. El Niño may have an impact on rainfall and production levels in H2 26 or 2027. | AMBER = (Roland) These are a good set of results and broker forecasts have been nudged higher once again, albeit while suggesting a reduction in earnings from 2027. This outlook reflects the fact that recent gains and super profits are being driven by high commodity prices, more than by any fundamental improvement in the business. I’d argue that further upside is largely dependent on continued commodity price strength, so from our point of view as fundamental investors, I think it’s sensible to maintain a neutral view. | |
GlobalData (LON:DATA) (£506m | SR44) | H1 revenue +4% to £162.9m with pre-tax profit -6% to £23.2m and adj EPS +8% to 2.7p. Volume and value renewal rates have “been consistent”. Outlook: FY26 revenue to be at lower end of expectations, with adj EBITDA below market expectations. | PROFIT WARNING (AMBER/RED ↓) (Roland) I can’t help feeling that there’s a lack of detail in today’s results about the headwinds facing the business. Having read today's outlook guidance, I was surprised by the scale of the broker cuts today: joint broker Panmure Liberum has cut its 2027 and 2028 EPS forecasts by over 30%. I think there could be an interesting business here that might be cheap if trading improves. But I’d like to see some evidence of this before returning to our previous neutral view. I also note that founder-CEO Michael Danson collected £17m in a well-timed share sale a month ago, since when the stock has fallen by c.30%. I’m moving down one notch to AMBER/RED today. | |
Guardian Metal Resources (LON:GMET) (£328m | SR9) | Positive tungsten drilling results from the newly discovered Tremor Zone and the previously untested Good Hope Zone, both of which form part of the Pilot Mountain project in Nevada. | ||
Central Asia Metals (LON:CAML) £301m | SR91) | The planned Court date of 18 September 2026 for the acquisition of Cygnus may have to be delayed as Kazakhstan regulatory approval has not yet been received. The company is not aware of any reason why this approval shouldn’t be received in due course. | ||
Big Technologies (LON:BIG) (£291m | SR41) | Litigation Update & Interim Results for the 6 months to 30 June 2026 | H1 revenue +6% to £26.9m at constant currency, with adj operating profit up 20% to £11.4m and adj free cash flow of £9.6m. £33m of Buddi settlement payments were made during H1, leaving cash at £65m. FY26 Outlook: confident that full-year performance will be marginally ahead of expectations. | |
Cerillion (LON:CER) (£261m | SR35) | H2 results will be ahead of the first half, but the full-year result is now expected to be behind consensus market forecasts due to delayed customer orders. FY26 revenue is now expected to be £46m to £48m, with adj EBITDA margin of 43% to 45%. (Previous consensus: £52.8m and 45.2%). Panmure Liberum broker forecasts cut by c.17% - FY26E adj EPS: 48.4p (prev. 58.4p). - FY27E adj EPS: 53.3p (prev. 64.1p) | PROFIT WARNING (AMBER/RED ↓) (Roland) Cerillion has left it to less than three weeks before the end of the year before cutting guidance, suggesting a certain amount of finger-crossing has been taking place. I admire the quality metrics of this business and I think the valuation could be coming down to a level where it might be interesting. However, I’m wary about the possibility that further downgrades could follow and would like greater clarity on the outlook for FY27 before taking a more positive view. At this stage, I think it’s prudent to be cautious. | |
Keystone Law (LON:KEYS) (£195m | SR76) | H1 revenue +22.5% to £66.3m with adj pre-tax profit +31.3% to £9.6m. The Board now expects to report FY 2027 revenue comfortably ahead and profits materially ahead of current market expectations (previous consensus for revenue was £123m with adj PBT of £15.8m). | GREEN = (Ed S) | |
Pantheon Resources (LON:PANR) (£156m | SR34) | Interim results remain in line with expectations, with available cash guidance until approximately year end. H1 operating loss of $6.1 million (H1 2025: $7.9 million). Outlook: continues to progress farm-out discussions and development planning. | ||
Tribal (LON:TRB) (£144m | SR91) | Proposed Acquisition by Main Capital Partners (Friday pm) | Agreed sale of the Tribal Group businesses to Main Capital for c.£189.3m, capital return to shareholders to be confirmed in due course. | TAKEOVER (Roland) [no section below] News of this transaction was snuck out at 5.54pm on Friday night. The offer seems to be at a c.30% premium to Friday’s closing price, or around 88p. However, I think the main point worth emphasising is that the buyers are buying all of Tribal’s operating subsidiaries, not the holding company itself. This means Tribal will remain listed following the transaction as a shell with a large amount of cash. This will be returned to shareholders “in the most tax efficient manner”, following which the company will be wound up. I am not sure why this approach has been chosen instead of a more normal takeover, but with Tribal directors controlling 44% of the stock and backing this bid, my guess is that it is a done deal. Our last view on Tribal was on 3 September, when Graham was AMBER/GREEN following the company’s half-year results. |
Strategic Minerals (LON:SML) (£141m | SR44) | CRL has confirmed further high-grade tungsten-tin-copper mineralisation within the Redmoor Sheeted Vein System, with multiple drillholes returning intervals in excess of 1.00% WO₃ over 1m and tungsten-equivalent grades ("WO3. Eq*1") exceeding 6.00% WO₃ Eq over 1m in certain intervals - among the highest-grade tungsten intercepts reported at Redmoor to date. | ||
Iofina (LON:IOF) (£98m | SR78) | These two plants will be built concurrently, and groundwork is anticipated to start soon, with the IOsorb® plants preliminarily scheduled to be operational before the end of H1 2027. The group is confidently tracking to its production targets over the next couple of years and towards its objective of reaching 2000MT of production per annum. | ||
Jubilee Metals (LON:JLP) (£76m | SR27) | Combined FY26 copper production prior to refining from the Roan operations and Molefe Mine totalled 3 739t of copper, an increase of 225.0% vs FY25. Molefe remains in planned ramp-up towards target production of 7,000-7,500tpm. | ||
Hardide (LON:HDD) (£69m | SR53) | The company’s North American energy sector customer has placed its first production order for these new components. This initial order is valued at c.$1.9m and scheduled for delivery early in the FY27 financial year. No change to Cavendish broker forecasts. | ||
Alternative Income REIT (LON:AIRE) (£55m | SR45) | AIRE has received a reservation of rights letter from HSBC UK relating to its £41m facility. This results from the change of control due to the Glenstone offer. It prevents the company from further utilisation of the facility and allows the bank to demand repayment. | TAKEOVER | |
Kromek (LON:KMK) (£47m | SR82) | Revenue +2% to £27.1m with adj pre-tax profit down 19% to £2.5m. FY27 outlook: expect to deliver results in line with market expectations, with significant revenue growth in both divisions. | AMBER = (Ed S) | |
Power Probe (LON:PWR) (£44m | SR49) | H1 revenue -17% to $17.7m reflecting the timing of product launches, with adj EBITDA -31% to $3.8m, including c.$0.6m of additional plc costs. Outlook: expect H2 weighting to revenue, consistent with previous guidance. | ||
ATC Music (LON:ATC) (£44m | SR29) | Group revenue increased by 39% to £30.6m, loss after tax reduced to £2.1m (H1 2025: loss of £2.3m), EPS of -7.29p versus -10.74p in H1 2025, cash and cash equivalents of £20.3m. Trading momentum in the second half of the year has continued to grow. | ||
System1 (LON:SYS1) (£43m | SR64) | Brave Bison (LON:BBSN) has increased its offer to 135p in cash and 2.394p new BBSN shares for each SYS1 share. This offer is said to be valued at 360p per SYS1 share, based on a BBSN share price of 94p. | TAKEOVER | |
Ariana Resources (LON:AAU) (£43m | SR28) | Michael Atkins, the current Non-Executive Chairman, has been appointed Executive Chairman with immediate effect. | ||
Blencowe Resources (LON:BRES) (£41m | SR11) | CEO Mike Ralston has resigned with immediate effect. The company has already commenced the search for a replacement. COO Iain Wearing will lead operations in the interim. The company has also been notified by Mr. Ralston of historical PDMR share transactions. | ||
Touchstone Exploration (LON:TXP) (£38m | SR43) | Operational activities during August and early September have focused on advancing the company's development, workover and production optimization programs across the WD-4, Ortoire, and Central blocks. Net sales production averaged 4,402 boe/d in July, while field-estimated net production averaged 4,392 boe/d in August. | ||
Sealand Capital Galaxy (LON:SCGL) (£33m | SR13) | Has entered into a conditional Share Purchase Agreement for the acquisition of a 60% controlling interest in Finely Technology Holdings Limited, a Cayman Islands-incorporated technology company with core operations in Hong Kong focused on enterprise software, cloud-native platforms, IoT technologies and digital infrastructure solutions, for total consideration of £12m. | ||
Prospex Energy (LON:PXEN) (£30m | SR42) | Tarba Energía S.L. has successfully installed the new electrical transformer at the Romeral gas-to-power plant in Andalucía, Spain, replacing the rental transformer, and reducing monthly operating costs by c.€14,000. Consistent production at Tarba, coupled with continued high electricity pricing, has delivered strong revenue performance during the peak summer months with Tarba self-sufficient on a cash basis for July and August. | ||
Europa Oil & Gas (Holdings) (LON:EOG) (£24m | SR25) | Revenue flat year on year at £1.5 million, pre-tax loss of £0.8 million versus £0.9 for H1 2025, cash at 30 June 2026 of £2.8 million. The Board looks forward to an active and potentially transformational second half of 2026. | ||
Panther Metals (LON:PALM) (£17m | SR23) | Preliminary findings from the Phase 1 Diamond Drilling programme at the Wishbone volcanogenic hosted massive sulphide prospect have strengthened the company's confidence in the scale and potential of this VMS system. Consequently, Panther has agreed a further extension of the Obonga sale and purchase agreement to facilitate drill permit renewals. | ||
Insig Ai (LON:INSG) (£15m | SR1) | Insig AI is to be allocated an equity interest in a new special purpose vehicle being established by Insig AI investee company ImpactScope OÜ. Provides exposure to Kibiva Energy, which manages a 350 MW portfolio of geothermal energy assets in Kenya, where sites are being developed to facilitate bitcoin mining and AI data centre clients. | ||
Eco Buildings (LON:ECOB) (£15m | SR3) | The company is now completing the fourth and final floor structure of the first apartment block. Expected to be completed next month. | ||
Lexington Gold (LON:LEX) (£13m | SR7) | Number of primary drillholes increased from 12 to 64, with 73 drillhole deflections catalogued, Kimberley Reef sampling data identified in 22 primary drillholes and 55 deflections, data acquisition, verification and geological correlation advancing ahead of 3D modelling, JORC (2012) Exploration Target estimation work planned for Q4 2026. | ||
Alien Metals (LON:UFO) (£11m | SR24) | Diamond drilling at the Ayshia deposit within the Whundo Project has returned high-grade copper-gold-silver: 4.76m @ 7.13% Cu, 1.20% Zn, 0.88 g/t Au and 29.6 g/t Ag from 367m, incl, 3.44m @ 9.43% Cu, 1.59% Zn, 1.20 g/t Au and 39.7 g/t Ag from 367.62m (26GTDD016). | ||
Arcontech (LON:ARC) (£11m | SR63) | Revenue decreased 11.5% to £2.8m, adjusted EBITDA decreased 19.2% to £706k, profit before taxation was £881,170 (2025: £987,390), net cash of £7.5m. | ||
Arkle Resources (LON:ARK) (£10m | SR12) | Trench assays define a 1.5 km uranium footprint in stacked leucogranite sheets, confirmed by drilling to at least 188m, at the Erongo Uranium Project, Namibia. Assay results expected during September 2026. |
Roland's Section
Cerillion (LON:CER)
Down 11% at 790p (£219m) - Full Year Trading Update - Roland - PROFIT WARNING (AMBER/RED ↓)
This telecoms CRM software business has issued a material profit warning this morning – commiserations to holders.
In our last view on this AIM-listed stock in April, I commented on the “very unusual 74% H2 weighting” to profit guidance and took a neutral view. I also expressed concern around the lack of disclosure on the value of the order book and on the timing of expected cash flows from the Omantel deal.
June’s interim results left full-year expectations unchanged and reiterated expectations for “material software licence revenue” to be recognised in H2.
Investors who were reassured by June’s guidance may feel a little frustrated today. The company has warned on profits with less than three weeks to go until the end of the financial year on 30 September.
My impression is that Cerillion has failed to convert its pipeline to orders as successfully as expected, and has been holding on to the last minute before deciding to cut guidance:
Here are the key points from today’s full-year update:
“While the second-half results will be significantly ahead of the first-half, it is now apparent to the Board that the year's outturn will be behind consensus market forecasts”
“The main reason for the shortfall is that some anticipated new and existing customer orders have been delayed or deferred. This included software licence expansions and upgrades.”
Major implementations are progressing, with software installation completed at Omantel and the UCom transformation project in Armenia is “nearing completion”.
Updated guidance:
The company has provided updated guidance this morning, so shareholders aren’t entirely reliant on broker updates:
FY26 revenue now expected to be £46 to £48m (previous consensus: £52.8m)
FY26 adj EBITDA margin now expected to be 43% to 45% (previous consensus 45.2%)
Taking the mid-point of these two metrics implies FY26 adj EBITDA of c.£20.7m, compared to previous forecasts I can see of around £24m.
Broker estimates: with thanks to Panmure Liberum and Cavendish this morning, we have access to revised forecasts through Research Tree. Analysts at both brokers have reached similar conclusions and have cut earnings forecasts by c.17% for FY26 and FY27:
Panmure Liberum / Cavendish
FY26E adj EPS: 48.7p / 50.4p (prev. consensus: 58.4p)
FY27E adj EPS: 53.3p / 55.8p (prev. Consensus 64.7p)
Roland’s view
Cerillion’s share price peaked at almost 2,000p in 2024, since when it’s fallen by around 60%:
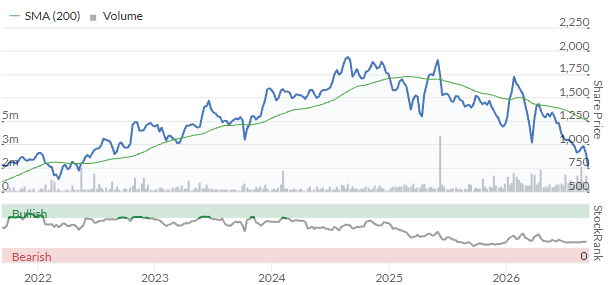
From a peak P/E of c.50x earnings, the shares now trade on around 15x today’s revised forecasts.
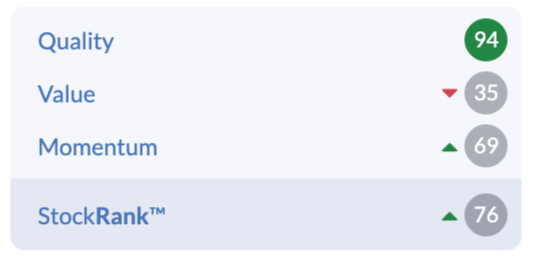
There could be an argument to suggest that the shares have fallen far enough. After all, quality metrics remain outstanding:
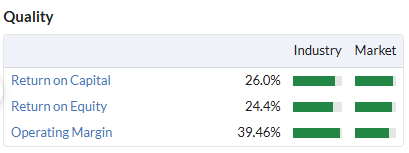
Today’s share price drop of c.10% (at the time of writing) is also smaller than the scale of the EPS downgrade, suggesting markets may already have priced in some of the bad news.
Another potential positive is that founder-CEO Louis Hall remains the company’s largest shareholder, at 20%, so is also well-motivated to return the business to former glories.
Despite these potential positives, I do have a couple of concerns.
One is simply that our long-term experience is that when a company warns on profits, this is often followed by a longer period of underperformance. While a recovery may be likely at some point, there’s an opportunity cost to holding a stock through a downgrade cycle.
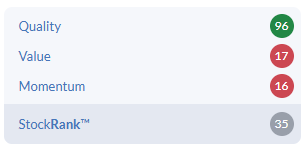
This view is reflected in the StockRanks, with a Falling Star styling and very low value and momentum ranks:
Another concern is that there’s no update on the value of the order book today.
The half-year results showed an order book at 31 March 26 of £82.1m (H1 25: £50.2m). While that looks like impressive growth, my impression is that much of it related to the Omantel deal and was expected to unwind in H2.
Although I do think Cerillion’s valuation is coming down to a level where it could become interesting, I’d like to have a little more clarity on the outlook for trading before forming a stronger view. I’m going to move down one notch from AMBER to AMBER/RED today.
GlobalData (LON:DATA)
Down 22% at 56p (£396m) - Half Year Results - Roland - PROFIT WARNING (AMBER/RED ↓)
This business describes itself as “the leading data, insight, and technology company”. It’s active in sectors including Healthcare.
We haven’t looked at it properly since March 2025, when Graham noted results in line with expectations, complex accounts and a fairly demanding valuation. He took a neutral view while commenting that this could be a good quality business.
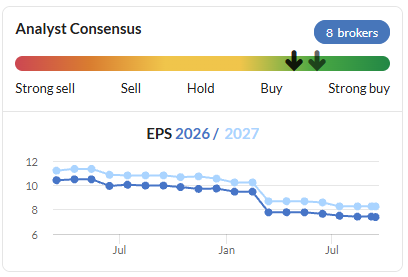
However, more recently in July 2026 we noted that the company was guiding for profits to be at the low end of consensus. Today’s profit warning appears to be a follow-on from this and has prompted a further downgrade to expectations, extending an already-negative trend:
Half-year results summary
The headline figures from today’s results do not seem overly encouraging:
Revenue up 4% to £162.9m (+1% underlying)
Adj EBITDA up5% to £54.8m (flat underlying)
Pre-tax profit down 6% to £23.2m, reflecting higher finance costs
Adj EPS up 8% to 2.7p
This is an acquisitive business and I think the underlying figures reflect performance excluding the impact of recent disposals.
To illustrate this, the company has made seven acquisitions since launching its “Growth Transformation Plan” in January 2024, spending over £132m, to “strengthen our proprietary data and competitive intelligence capabilities”.
Renewal rates appear to have remained reasonable in H1, although GlobalData’s customers aren’t the stickiest I have seen:
Renewal by value: 91%
Renewal by volume: 83%
The company notes “a significant opportunity” to improve organic growth it it can reduce churn and improve volume renewal rates.
Balance sheet & Profitability: net bank debt rose to £133m at the end of June, from £114m at the end of 2025 and just £17m in June 2025.
This represents leverage of 1.2x trailing 12-month EBITDA. That’s not a level that would concern me for a business such as this one, which appears to be quite profitable and cash generative:
H1 operating margin: 19%
Trailing 12-month return on capital employed: 16%
H1 free cash flow excl. acquisitions: £31.8m (versus net profit of £14.1m)
Outlook & Broker Estimates
GlobalData’s outlook statement is a clear profit warning:
FY26 underlying revenue growth is expected to be “more muted than expected, still in line with expectations, albeit towards the lower end of the range”.
FY26 adj EBITDA “to be below market expectations” reflecting slower revenue growth and the impact of “targeted investments” during the second half of this year.
However, I’m not sure these comments reflect the scale of the multi-year broker downgrade issued today by GlobalData’s joint broker, Panmure Liberum:
FY26E adj EPS: 5.7p (-24.6% vs 7.6p previously)
FY27E adj EPS: 6.2p (-31.5% vs 9.0p previously)
FY28E adj EPS: 7.0p (-31.6% vs 10.2p previously)
Looking at the broker note in more detail, it looks like the majority of the cuts apply to GlobalData’s non-healthcare business, where revenue forecasts have been cut significantly and margins are (already) much lower than in the Healthcare business.
The revenue split between the two divisions is approximately 60:40 (Non-Healthcare/Healthcare), but Healthcare has much higher margins and is expected to generate more than 60% of operating profit this year.
Roland’s view
GlobalData’s share price has been trending lower for two years and was already weak before today’s c.20% drop.
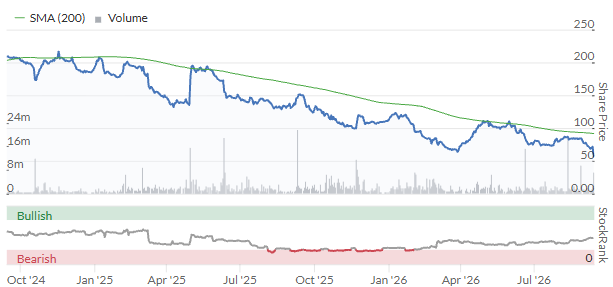
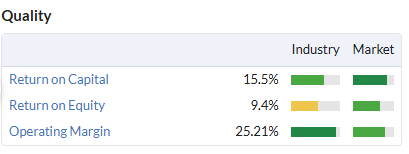
Today’s revised forecasts leave the company trading on c.10x FY26E EPS, which may not be expensive for a company with these quality metrics.
It could also be worth noting that GlobalData is led by founder-CEO Michael Danson, who has a controlling shareholding and a track record as an investor and entrepreneur in the market intelligence sector:
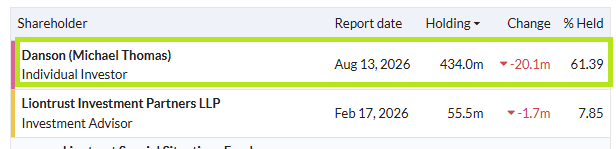
Mr Danson benefited from a well-timed sale of 20m shares at 85p last month. This sale netted him £17m, but would only have generated c.£11.5m at today’s much-reduced share price.
Danson previously founded Datamonitor (sold to Informa (LON:INF) in 2007) and has invested in a number of other privately-held companies in this sector. My understanding is that the acquisitions made by GlobalData over the last decade have included some of his private investments.
Graham was neutral on GlobalData in March 2025 and I can see why. There’s lots to like here, potentially, plus an owner-CEO with plenty of skin in the game.
On the other hand, there’s a certain level of opacity about the performance of the business, in my view. Why are volume renewals relatively weak? Is AI eroding some lower-value business?
Today’s broker cuts are also larger than I would have expected from reading the company's revised guidance.
Mr Danson is keen to emphasise that investments being made at the moment are expected to support long-term growth and profitability:
Longer term, the investments that we are making now should lead to a positive impact on revenue quality and client renewal rates giving us a stronger foundation for accelerating growth, as well as delivering operational and margin benefits.
I can see this argument and would not necessarily bet against a strong recovery over time.
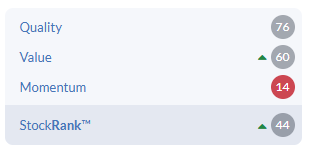
However, given the persistent trend of broker downgrades and today’s large cuts to EPS forecasts out to 2028, I think it’s sensible to be cautious. There seems to be an uncomfortable lack of momentum here at the moment, something highlighted by the StockRanks:
I’m going to move our view down by one notch to AMBER/RED today, in keeping with our normal practice for profit warnings. At the current valuation I would be quick to return to a neutral view on signs that trading is improving and I think there could be decent upside here if the growth case pans out.
M P Evans (LON:MPE)
Up 5.7% at 1,994p (£1.0bn) - Interim Results - Roland - AMBER =
There’s not too much to dislike in today’s half-year results from this palm oil producer:
Revenue up 9% to $196.3m
Pre-tax profit up 25% to $61.1m
Adjusted earnings up 21% to 86.5p per share
Net cash of $113.5m
Interim dividend up 39% to 25p per share
Of course, this is a commodity producer: profit growth was supported by continued “strong pricing for both CPO and PK” (Crude Palm Oil and Palm Kernel).
Volumes also improved during the half year:
Total crop processed up 8% to 798,200 tonnes
Total CPO production up 11% to 192,300 tonnes
Certified sustainable production up 16% to 151,800 tonnes
As reported on Thursday last week, MP Evans has also continued to acquire new land close to its main sites.
Outlook & Broker Estimates
It all adds up to a fairly positive picture.
The only possible note of caution that stands out from today’s management commentary is a warning that this year’s El Niño effect may have an impact on rainfall and thus production in either late 2026 or 2027. However, in this scenario, other producers would also be affected. The company notes that any shortfall in production might be offset by higher commodity prices.
The increase in the company’s productive base is certainly encouraging and supports a positive view on medium-term growth.
Broker forecasts have been upgraded today (with thanks to Cavendish):
FY26E adj EPS: 230p (+12.5% vs 204.5p previously)
FY27E adj EPS: 192.2p (+8.2% vs 177.6p previously)
FY28E adj EPS: 190.8p (8.8% vs 175.4p previously)
Roland’s view
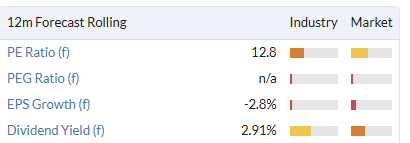
MP Evans’ shares don’t look wildly expensive against these forecast earnings:
However, I think it’s important to remember that this is a commodity producer and that profits are subject to commodity price movements. These could be peak earnings.
While the outlook remains strong at the moment, this won’t necessarily continue. I see that Cavendish forecasts continue to price in a return to more normal Palm Kernel pricing from 2027 onwards.
There could be further upside here, but I would argue that this is mostly dependent on commodity market conditions, not MP Evans’ growth.
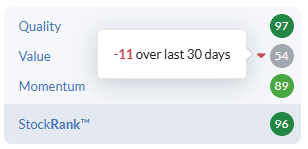
As we’ve commented before, I’d argue that the stock’s current valuation reflects high commodity prices and doesn’t suggest all that much fundamental value is on offer:
As we generally take an agnostic view on commodity prices, I’m going to maintain our previous neutral view today.
Ed S's Section
Keystone Law (LON:KEYS)
Up 7% at 658p (£195m) - Half-year report - Ed S - GREEN =
Tech-enabled platform law firm Keystone Law has posted its interim results for the six months ended 31 July 2026.
Financial highlights:
Revenue of £66.3m, up 22.5% year on year.
Revenue per Principal up 14.5% to £133.8k.
Adjusted profit before tax (PBT) up 31.3% to £9.6m.
Adjusted PBT margin of 14.5% (H1 2026: 13.6%).
Adjusted basic EPS of 23.1p (H1 2026: 17.8p)
Cash generated from operations up 19.2% to £8.1m with operating cash conversion of 95.6% (H1 2026: 104.2%).
Strong balance sheet with net cash of £10.5m (H1 2026: £6.5m)
Interim ordinary dividend of 9.6p per share and a special dividend of 15p (H1 2026: interim ordinary dividend 7.5p).
Current trading and outlook:
The group has made a positive start to H2 2027.
The Board now expects that Keystone will deliver FY2027 revenue comfortably ahead and profits materially ahead of current market expectations:
FY2027 market expectations prior to the announcement: revenue £123m, adjusted PBIT £13.8m, and adjusted PBT £15.8m.
Operational highlights:
23 high-calibre new Principals added bringing total Principals to 501 (31 January 2026: 491).
Principals continue to grow their Pods with net growth of 18 other fee earners in the period bringing total fee earners to 682 (31 January 2026: 654).
Extended AI capabilities with rollout of CoCounsel Legal, a professional-grade generative AI tool specifically designed for the legal industry, complementing additional AI tools deployed in FY2026.
Completed brand refresh, launching new website alongside the production of extensive marketing collateral.
“We continue to invest in our technology, brand and community, including the rollout of further market-leading AI tools, to ensure our lawyers have the infrastructure and support they need to grow and sustain successful practices. With a strong first half and an encouraging start to H2, we remain confident in Keystone's ability to deliver sustainable long-term growth."
Ed S’s view:
This is a stock I’ve owned in the past. I owned it for the scalability of the company’s platform (Keystone provides lawyers with full infrastructure and support via its central office team yet its lawyers ultimately have freedom, flexibility, and autonomy) and the company’s quality.
Looking at today’s results and the financials, I still like the quality-growth angle here. In terms of growth, we have a 22.5% year-on-year increase in revenue and a 31.1% increase in adjusted PBT (the only adjustments were share-based payments – these amounted to £392k).
We also get a boost to full-year guidance. Going into today’s print, analysts were expecting £123m in revenue for the financial year ended 31 January, however, the company says that it’s now expecting its top line to be ‘comfortably ahead’ of this.
Note that between FY2021 and FY2026, revenue climbed from £55m to £115m. That represents a CAGR of 16%.
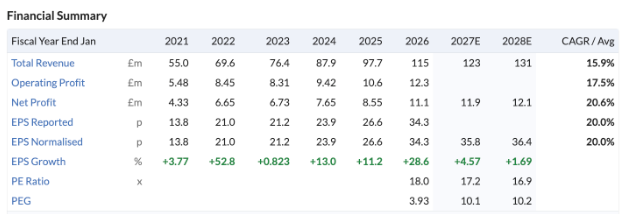
As for quality, it remains high. Over the last five years, return on capital employed (ROCE) has averaged 47%, which is phenomenal.
Meanwhile, the balance sheet remains strong. At the end of July, the company had net cash of £10.5m.
Dividends have been rising and there’s a yield of around 4% on offer today. Note that the company has a history of paying out special dividends – today it has announced a 15p per share special divi.
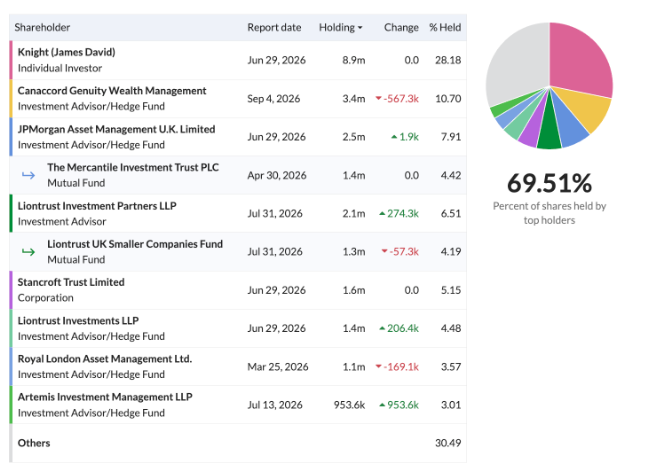
The company is also founder led. And founder James Knight owns around 28% of the shares, so his interests are aligned with those of investors.
In terms of the valuation, it seems reasonable to me, given the growth and quality. Before today’s print, analysts were expecting earnings per share of 35.8p for the year, putting the forward-looking P/E ratio at about 18.
However, the company now expects profits to be ‘materially ahead’ of expectations. So, higher earnings should bring the P/E ratio down meaningfully.
In terms of risks, two big ones for me are AI disruption and a major economic slowdown. Today’s results don’t seem to show any challenges from AI, but I keep hearing that people are turning to Claude and other AI models to draft legal documents, eliminating the need for lawyers (if anyone has any experience here feel free to drop comments in the comments section).
It’s worth noting that Keystone is embracing AI itself. In today’s update, it says:
Having successfully deployed a secure enterprise grade version of ChatGPT and Claude as well as the Netdocuments generative AI tool during FY2026, we have continued to extend the suite of AI tools available to our lawyers, successfully rolling out CoCounsel Legal during the Period. As a leading generative AI tool specifically designed to work for the legal industry, CoCounsel's major differentiating factor is its ability to access not only open-source data but, more importantly, it accesses the extensive, market leading, legal knowledge databases owned by Thomson Reuters. This roll out builds on the successes of last year and we have seen an increasing level of uptake and utilisation of these AI solutions.
Back in April, Graham gave Keystone Law a GREEN rating. However, at the time, he said that if the stock hit 600p by the date of his next coverage, and there haven’t been any further upgrades, he would return to a more conservative stance.
Given that we have strong results today and an increase to guidance, I’m happy to leave the stock on a GREEN rating. I do have some concerns over AI disruption in the long run, however, for now, we appear to have growth at a reasonable price.
Kromek (LON:KMK)
Down 2% at 6.94p (£47m) - Final Results - Ed S - AMBER =
Radiation detection and advanced imaging specialist Kromek has posted its final results for the year ended 30 April 2026.
Financial highlights:
Revenue increased to £27.1m (2025: £26.5m).
Advanced Imaging revenue was £19.9m (2025: £20.3m)
On an underlying basis* Advanced Imaging revenue rose 76% to £6.7m (2025: £3.8m).
CBRN Detection revenue increased by 17% to £7.3m (2025: £6.2m).
Gross margin was 62.8% (2025: 80.9%) due to revenue mix, including high-margin licensing revenue accounting for a higher proportion of revenue in 2025.
Adjusted EBITDA of £8.1m (2025: £10.3m)*.
Profit before tax was slightly ahead of expectations at £2.5m (2025: £3.1m).
Cash and cash equivalents at 30 April 2026 were £4.2m (30 April 2025: £1.7m), having secured a three-year revolving credit facility of £6.0m during the year.
Net debt (excluding lease liabilities) of £1.5m at 30 April 2026 (30 April 2025: £1.2m net cash (excluding lease liabilities)).
* Adjusted to exclude the licensing revenue contribution to both years from the Enablement Agreement signed with Siemens Medical Solutions USA, Inc. in FY2025 and a non-recurring major new sale to an existing customer delivered in H2 2026.
Outlook:
The new financial year is progressing well, with a healthy commercial pipeline and order book.
The Board expects to deliver further growth in FY2027.
The Group continues to trade in line with market expectations.
We enter FY2027 with positive momentum, supported by a healthy order book, an encouraging commercial pipeline and strong engagement with customers across both divisions. As demand develops for our Advanced Imaging technologies and government and security customers continue to invest in CBRN detection capabilities, we expect to deliver results in line with market expectations, including significant revenue growth in both divisions, while maintaining disciplined cost control and investment in key growth opportunities. Accordingly, the Board continues to look forward to the year ahead with confidence.
Ed S’s view:
Kromek operates across two divisions – Advanced Imaging and CBRN (Chemical, Biological, Radiological & Nuclear) Detection. So, it’s essentially exposed to two growth markets – healthcare and security/defence.
Note that in FY2025, revenues in the company's Advanced Imaging division received a major boost from a large deal with Siemens Healthineers (the Enablement Agreement). This deal was for the provision of Cadmium Zinc Telluride (CZT) detectors for SPECT (single-photon emission computed tomography) imaging.
In FY2026, headline revenue in Advance Imaging was down slightly. However, underlying revenue increased by 76% to £6.7m (2025: £3.8m), driven by renewed engagement with customers following the completion of the deal with Siemens Healthineers.
Total profit before tax within Advanced Imaging was £1.7m (2025: £6.9m). The company notes that FY2025 captured the higher margin of licensing revenue under the Enablement Agreement.
In the CBRN Detection division, revenue increased by 17% to £7.3m. Profit before tax was £0.8m for the year compared with a loss before tax of £3.8m for the previous year.
During the year, the company secured its first order under the UK Government's Radiological Nuclear Detection Framework, which was for the supply of the D3S-ID wearable detector, alongside training and maintenance. The majority of the £1.7m of revenue under this order was delivered during the year and the remainder will be received as service revenue over the coming years.
In CBRN Detection, the ever-greater global focus on national security resulted in increased demand for Kromek's market-leading technologies for mission-critical applications.
Overall, I like the growth story here. However, the financials are a bit messy with adjustments boosting earnings per share significantly:
Earnings per share for the year on a basic and diluted basis: 0.1p per share.
Adjusted earnings per share excluding a non-cash deferred tax charge: 0.4p.
Taking those EPS figures, we get a P/E ratio of about 17.4 using the adjusted figure of 0.4 and a P/E ratio of 69 using the non-adjusted EPS figure.
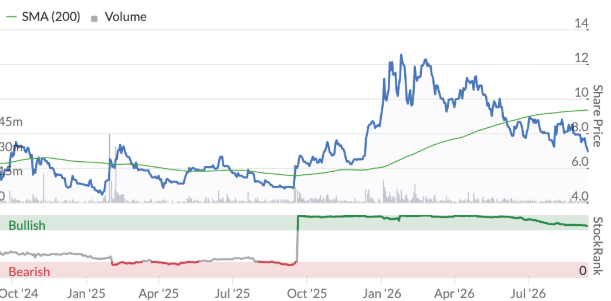
Turning to the technicals, the stock enjoyed a sharp rise late in 2025 and early in 2026 amid a surge in interest in defence stocks. For a while there, it was trading above 12p.
However, in recent months the hype has faded and the stock has lost its momentum. Right now, the trend is pretty ugly.
Given the current set-up, I’m going to leave Kromek on AMBER. There’s definitely potential here, but the stock has little momentum at the moment.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

20 comments
Question, don't know if this is where I should ask but here goes: Just wondering if I am able to build a screen of newer entries to the UK stock market, I haven't come across any rule that gives the date of when a share floated/how long they've been on the stock market. Thanks
Very useful write ups on both Kromek and Globaldata chaps. I hold both. Thanks
Keystone Law (LON:KEYS) Excellent 1H27 beating market expectations - interim div increased 28% and a special as well - not an infrequent occurrence with KEYS. With a positive outlook as well we should see this re-rate - and can expect upgrades.
If there are any negative impacts from AI - I can't see any in these results: The teams ('Pods') of lawyers (additional fee earners -i.e. billed time) supporting the Principals have been increased. Which is generating more revenue per Principal and profit margins have also increased. It might suggest that AI is perhaps making them more efficient without impacting pricing?
My own view is that AI will make professional services firms more efficient. I am sure you will get people that will try to use a solely AI drafted document but they probably aren’t the target clients of larger firms. Having reviewed a few legal and financial documents others have drafted using AI and trialling AI myself, my own view is that the technology is some way off replacing a trained professional, but it would be useful to get a first draft
I agree with this - first drafts via AI I completely get, but not close to being ready to handle final legal agreements without a trained lawyer. Also noticeable that Keystone Law (LON:KEYS) passes 6 long screens and now appears on Phil Hoffer's screen for anyone that follows that approach requiring 25 rules to be passed! Looks interesting.
Fourth offer from Brave Bison (LON:BBSN) for System1 (LON:SYS1) .....
Yet again, Brave Bison is making up fantasy valuations for the value of its own share price. Claims their shares are worth 94p each, when it hasn't been that price for almost 3 months since end-June! And today it is under 80p.
Looks like another dead offer in the water, albeit they do now have SYS1 shareholders representing 11% giving Letters of Intent (not as strong as irrevocables?) for this new deal.
Given BBSN share price is now 80p as of 9am this morning, total value on offer is still only 326p for SYS1 shareholders. Whereas the shares are trading c340p.
Lord Ashcroft, largest shareholder in BBSN, has been buying SYS1 shares in the open market at around 328p. That's an interesting signal there.
(I hold in the Boon Fund).
Cerillion (LON:CER) has a profit warning. The low end of the new revenue range is 12.9% below market estimates and the EBITDA margin 43% - 45% cf market estimates 45.2%.
Cavendish have reduced estimated adj. eps for this year from 60.2 to 50.4 and next year from 66.9 to 55.8p.
At 08 45 the sp is down 14.6%
The main reason given is delayed/deferred orders but the interesting bit is that the Omantel software installation has been completed. This pours doubt on the claims made about the Omantel contract from an anonymous interviewee who could be an employee with a grudge that were quoted by Norbury Capital as part of their reason for pulling out of CER. Other reasons were that no contracts coming from the pipeline had been announced since the interims and "Many software companies have become cheaper in recent months. This has created more attractive opportunities elsewhere".
This was published during the day on Friday 11th and could have affected the market this morning. You can read the article (in Dutch - in Firefox I just pressed the 'translate page' button) here: https://www.deaandeelhouder.nl...
Cerillion (LON:CER)
thats a pretty poor update here i have looked at the 01/06 update from the interims and to me that seemed fine and dandy ref the outlook.
per company 01/06 - note that update was after 8 full months - so only 4 months of year left !!
Looking at the remainder of the financial year, we believe that the Company continues to be well-positioned to deliver consensus market forecasts for the current financial year. Delivery is based largely on the continuing execution of projects already under way, supplemented by anticipated new orders from existing customers. Our new business pipeline, which stands at a record level even after our contract win with Omantel, also sets us up well for continuing progress.
and todaywe get
The main reason for the shortfall is that some anticipated new and existing customer orders have been delayed or deferred.
imho its very poor forecasting here - or the tone of the 01/06 update was too bullish for where they were.
Pet hate of mine when companies are doing well ane growing profits - there isnt any need to be over bullish ref forecasts - please dont inflate stuff though for it all to vanish right at the last minute.
Oh and to top it off they only care about sales and EBITDA .
looking at the shareprice well it seems that the money that mattered very well knew that this late profit warning was about to arrive - shame managemnt couldnt have let shareholders know till now.
MelloMonday returns tonight! https://www.melloevents.com/mm140926
Richard Penny joins us for a keynote presentation. #GROW & #DFCH present. #GTLY to be covered on our BASH (Buy, Avoid, Sell, Hold) panel. I will be sharing some insights on how investors can gain an edge in company meetings.
You can claim a half price ticket with code MMSTOCKO50 or a free ticket with code SHMM26 if you are a #GROW or #DFCH shareholder.
See you later
David
Brilliant results this morning from M P Evans. No negatives whatsoever that I can see. 25% uplift in share price is deserved? !
M P Evans (LON:MPE) I think the cooling was a little harsh. Whilst accepting commodity price is impacted by the cost of substitutes stuck as crude oil and complementary goods such as soya oil (grown in Ukraine). Their pattern of planting means that they have built in volume growth for several years to come.
Column
Tribal (LON:TRB) RNS out yesterday of a takeover
Morning Felix,
Thanks for flagging the Tribal (LON:TRB) offer from Friday night, I'm just adding that now.
Roland
Everplay (LON:EVPL) reports its H1 numbers on Tuesday and should guide regarding its new 100 player Warzone style game “Wardogs”.
On Friday a Everplay (LON:EVPL) RNS trumpeted sales; “…exceeded one million copies sold in day one after launching into Steam Early Access, also reaching over 340,000 concurrent players on Steam. The share price responded with a +20% Jump by the close.
I am not a game player but the sales numbers sound impressive, so I asked Claude AI to review them. AI reports that Day 1 sales are the least reliable future sales signal because they are inflated by wishlist-holders cashing in launch-day hype. It suggests that the real tell for how good a game is sales over the 1st weekend: Does the player count grow, or collapse?
So I ran a AI request earlier this morning which reports strong weekend player growth and that game reviews have been positive:
Wardogs players climbed from a 340k peak on Day 1 to a Sunday peak of 428k with reviews holding “Mostly Positive” @ 78% — a genuine hit, not just hype.... Wardogs will likely add £5M+ to Everplay's FY26/H2 economic contribution, via its publishing fee and 20% Bulkhead stake.
At the moment Wardogs is PC download only with consul versions not kicking in until 2028. More information tomorrow. I hold.
It is a hugely popular game, working best when you build a team (which increases the stickiness of the game) and it's just the beginning for the development of the game.
In the past Bulkhead, the studio that developed Wardogs, dropped by the ball with the previous crowdfunded project 1994. That's why the have been particularly transparent with this latest release, even releasing a video along the lines of "10 reasons why you shoudn't buy Wardogs" and offering people the opportunity to try the game and get a refund if they don't like it.
There were quite a few challenges on launch date:
What I like is that Bulkhead have communicated these issues clearly. The game is attempting to find the sweet spot between Military Simulator (think Arma Reforger - slow, requiring team planning) and more arcade style games like Battlefield 6 (think fast gun fights)
There is lots more to come on the PC side and given the overwhelmingly positive support from streamers when other franchises have become tired I think it will continue.
One thing to bare in mind from Bulkhead's past is that when they previously released the crowdfunded game 1944 on PC, the console version that was promised repeatedly slipped and was eventually cancelled. It might not be plain sailing.
The other obvious distraction ahead will be the release of GTA 6 in Nov '26
Phil: Interesting to hear from someone who has actually played the Wardogs game. I spotted that they had server problems and had to throttle entry to the login queue to batches of 10,000.
What do you make of the gameplay, and do you have any way to assess its likely impact on forward Everplay financials?
Like i said in the previous post the gameplay is trying to find the sweetspot between a MilSim (think individuals who prefer to work as a team, many of whom are former veterans, particularly in the US) and the Gen Z players who are used to everything fast.
I know their plan is not have have micro-transactions which for example often favour financially solvent players over skill based players, e.g. buy a better gun with £'s rather than earning it via skill based progression.
A quick AI query ...
Bulkhead has explicitly stated that Wardogs will feature zero microtransactions, paid weapon camos, battle passes, or purchasable in-game currency throughout its Early Access period. [1, 2, 3]To fund the game's long-term live service, server costs, and telemetry tracking, the studio is relying on a staggered pricing model and unique post-launch strategies rather than predatory monetization. [1, 2]
[ Early Access Launch ] -> $39.99 (Current Price)
│
▼
[ Mid-Development Updates ] -> Price steps up to $49.99
│
▼
[ Version 1.0 Release ] -> Full retail price $59.99 + Console Launches
│
▼
[ Long-Term Sustainability ] -> Meta optimizations & Service subscriptions
If the studio requires further revenue years down the line, they have stated they prefer the old-school approach of paid expansion packs over microtransactions. These would introduce new distinct map zones or alternative gameplay mechanics without splitting the baseline player base or making the game pay-to-win
Make of that what you will!
I have build a quick model to evaluate the impact of Wardogs on Everplay (LON:EVPL) financials in 2026/7. Based on 3M sales over the next 18 months (conservative given they are >1M already), EPS in both years should increase by over 30% vs. consensus to ~35-40p. Assuming Everplay (LON:EVPL) returns to its 14-15x PER from earlier this year, then a SP of 500-550p should be on the horizon.
According to Playtracker - whose figures I have found tend to be corroborated by companies I follow - we're at around 2.4 million sales so far and it's only day 4. With the UK price at £37 and Everplay (LON:EVPL)'s stake around 20% then gross revenue could end up being a lot more than £5m.
On another computer game note, tinyBuild (LON:TBLD) have an online showcase this afternoon where we might hear more news on their games including Kingmakers - which is at #8 on Steam wishlists.