Daily Stock Market Report (Mon 25 Nov 2024) - KGF, BMK, ITV, SNX, JNEO, MTL

Good morning!
Before we get started today, I wanted to point out a fascinating article written by our colleague Alex Naamani - When Dividends Turn Dangerous. Something to read over your morning coffee.
I'd also like to point you towards our new spreadsheet with records of the stocks we've covered since 5/11/24. It's a work in progress and does need to be improved but for a quick snapshot of the companies we've covered and the stances we've taken, it should do the job.
Now let's see what the RNS has in store!
Wrapping this up just before 1pm. Special thanks to Keelan for his section on MTL. Have a good day!
Explanatory notes
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day. We usually avoid the smallest, and most speculative companies, although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We have a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Add your own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing. Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023
Companies Reporting
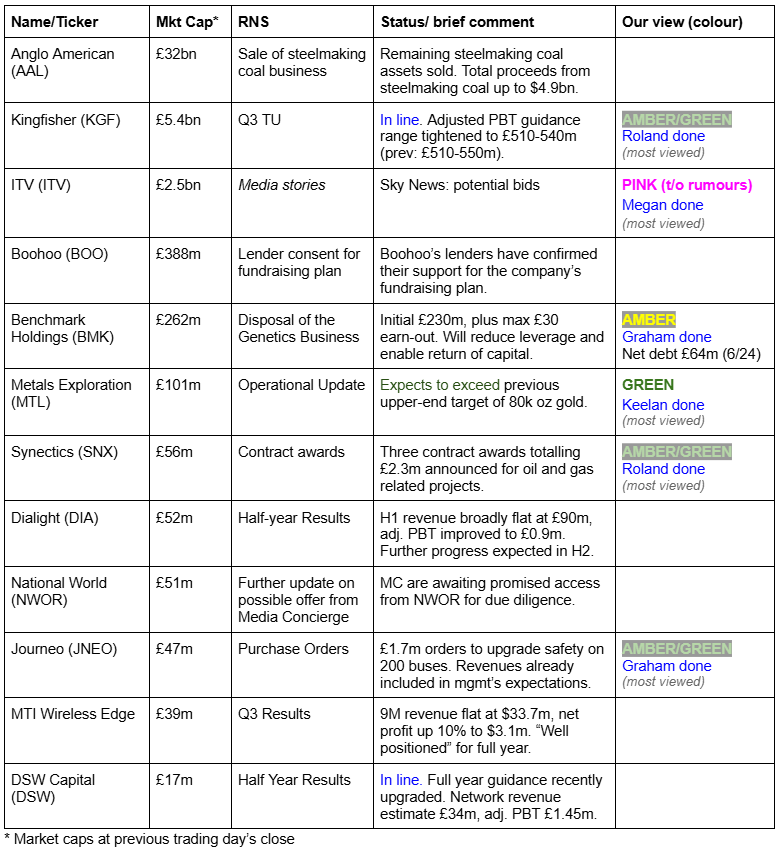
Summaries
Kingfisher (LON:KGF) - down 13% to 256p (£4.7bn) - Q3 Trading Update - Roland - AMBER/GREEN
The DIY retailer has trimmed the top end of profit guidance for 24/25 and warned of a potential £45m hit to profits next year due to tax rises in the UK and France. Cyclical headwinds remain a problem, but today’s guidance suggests a free cash flow yield of c.9%. This should provide ample support for the 4.7% dividend yield and suggests some value may be on offer.
Benchmark Holdings (LON:BMK) - up 11% to 39.4p (£291m) - Disposal of the Genetics Business - Graham - AMBER
It’s an enormous £260m disposal, although if you read the small print it will be c. £200m now plus the earnout of up to £30m. A debt-ridden, loss-making business is transformed into a cash-rich, probably loss-making business. I upgrade to AMBER as cash is now 45% of the market cap.
Synectics (LON:SNX) - up 0.6% to 315p (£56m) - Contract awards - Roland - AMBER/GREEN
Today’s contract awards show further progress at this business but appear to be included within existing earnings forecasts, which are unchanged today. I remain positive on this business but I think it’s worth considering the greater risk of disappointment, following significant recent share price gains.
Journeo (LON:JNEO) - up 3% to 290p (£48m) - Purchase Orders - Graham - AMBER/GREEN
Journeo announces some purchase orders that help to boost visibility, but their revenues were already included in management expectations so I don’t rate this news as material. I’m happy to leave our mildly positive stance unchanged due to a moderate valuation, healthy cash position and overall good performance.
Metals Exploration (LON:MTL) - up 1% to 5.8p (£101m) - Operational Update - Keelan - GREEN
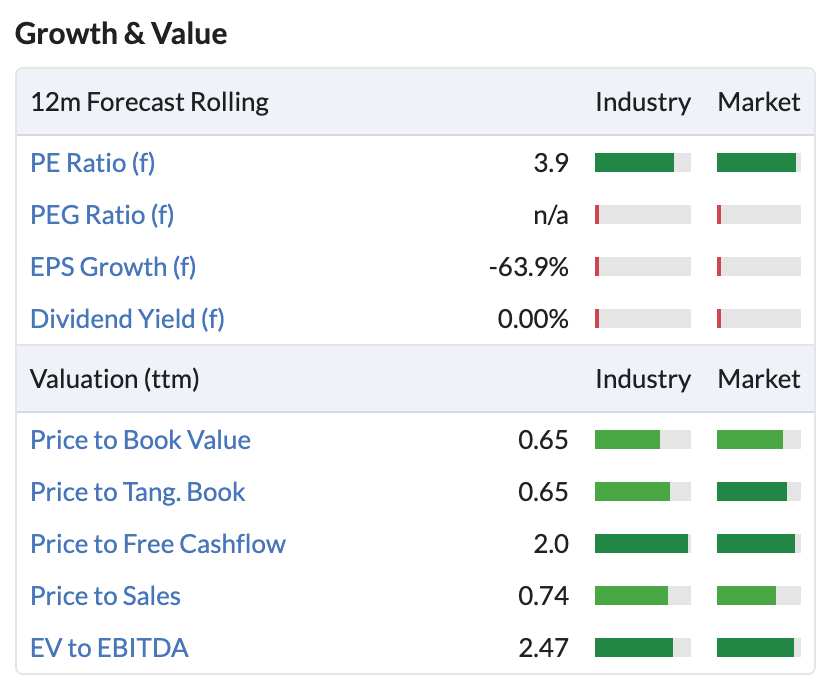
Metals Exploration has seen its share price more than double in 2024, with the company's operations update this morning leading to further share price gains. Gold production is now expected to top previous guidance, reaching 82,500 ounces of gold, whilst the all-in sustaining cost per ounce has also beaten guidance. The stock trades at a P/E of 3.9x and a P/FCF of 2x.
Short Sections
ITV (LON:ITV) - up 7% to 69p (£2.5bn) - Media: Suitors screen potential bids - Megan - PINK (takeover rumours)
Last week’s market rumours that ITV (LON:ITV) might be being sized up for a potential takeover gained more weight over the weekend after a report from Sky News. Private equity group CVC Capital Partners (the group behind the current takeover of Hargreaves Lansdown) and a major European broadcaster (thought to be French media conglomerate Groupe TF1) are reported to be among the suitors for the UK broadcaster, whose share price has languished for the last few years.
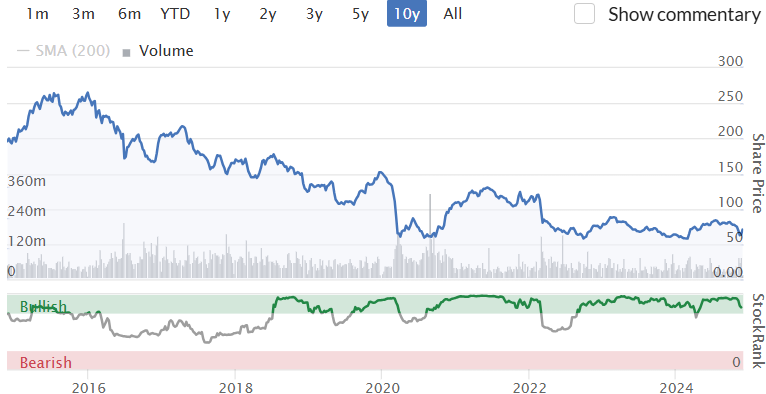
ITV’s share price peaked around 270p back in 2015 before the onslaught of competition from international streaming giants. Under current chief executive Carolyn McCall (who has been the boss since 2018) the company has done a decent job at diversifying away from its reliance on broadcasting. Studios revenue, where the company makes money from creating and producing films and programmes for other broadcasters and media companies, now contributes about half of group revenues and is expected to generate annual revenue growth of 5% over the next 4 years. Operating margins for the division are expected to be between 13% and 15%.
The Studios business alone is reported to be worth more than the whole of ITV’s market capitalisation. That is believable given the calibre of productions coming out of the studio and the type of valuations being placed on original content producers elsewhere in the world. In 2019, Hasbro acquired the London-listed film producer Entertainment One for $3.8bn, equivalent to three times the revenue generated by the business (it wasn’t an especially successful acquisition for Hasbro, which recently sold eOne on again for just $500m after sales tanked). The Roald Dahl Story Company fared better when Netflix paid 14 times company revenue in 2021. And Disney is never one to shortchange the various creative businesses it has brought into its own fold over the years.
Companies including RedBird Capital-owned All3Media and Mediawan, which is backed by the private equity giant KKR, are reportedly weighing up acquisition offers for the Studios business. If the Studios division was put up for sale on its own, it wouldn’t be crazy to suggest it could fetch a value of over £2.5bn, which is a little less than 1.5 times the revenue the division is forecast to generate in 2024.
Megan’s view
There is a lot of value in content producers at the moment and with ITV Studios hidden under the cloak of the challenged broadcasting arm, shareholders are not currently enjoying its full value. Splitting the company into its two components makes sense.
But for private equity suitors and retail investors alike, it’s the Studios business that holds the most appeal. Sure, there would be a cash boost to the business if its creative arm was sold off, but then all that would be left would be a broadcaster with an increasingly desperate reliance on aging shows like I’m a Celebrity and Love Island.
The good news for private investors is that there seem to be multiple potential acquirers and a bidding war would provide some welcome buoyancy to the share price. It has happened before. When 21st Century Fox first came calling for Sky, the offer was £10.75 per share. When Comcast finally won the bidding war, shareholders received £17.26.
Graham's Section
Benchmark Holdings (LON:BMK)
Up 11% to 39.4p (£291m) - Disposal of the Genetics Business - Graham - AMBER
Astonishing news here as a company with a c. £260m market cap (as of last Friday) announces a disposal with a headline price of £260m!
The valuation at Benchmark Holdings has been perplexing us for some time - see Paul’s most recent coverage in August when he noted that revenues were falling, losses were widening and net debt was at £64m.
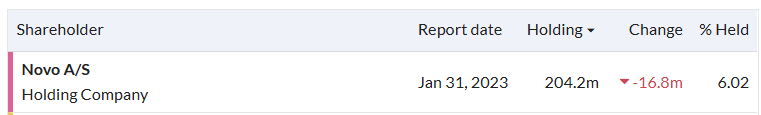
Management have delivered for their shareholders today in the form of a £260m disposal to Novo Holdings A/S, the largest and controlling shareholder of Novo Nordisk (NOVO). NOVO was covered by Megan in this report earlier this month.
Here are Novo Holdings on the NOVO shareholder register, with a stake worth £22 billion (!):
There are a number of companies included in the sale to Novo Holdings but the primary one is Benchmark Genetics Limited, “a leader in aquaculture genetics, present in every major aquaculture market and for a wide range of species”.
Valuation: 17.9x adj. EBITDA - generally I’d want to be a seller at this valuation, not a buyer!
Price: £230m initially (to be adjusted for debt and working capital), plus up to £30m based on trading performance to Sep 2027.
Use of proceeds:
Net proceeds from the Disposal will be used to return capital to shareholders and to reduce the Company's leverage, by repaying the Group's unsecured floating rate listed green bond and drawn amounts under the Group's revolving credit facility provided by DNB Bank ASA in full…
Checking BMK’s balance sheet for March 2024, I see that the value of BMK’s outstanding green bond was 750m Norwegian krone, or £54m, and it was set to mature in September 2025. There is also £16m drawn from an RCF. So that’s about £70m of debt for BMK to repay.
One of BMK’s Genetics subsidiaries had some other debts, and these reduce the amount paid to BMK by Novo, unless there is cash to offset them. As of March 2024, I calculate £16m of other debts at the Genetics subsidiary.
The announcement tells us that initial gross proceeds are expected to be £200m, payable in cash and anticipated during the first quarter of 2025. So I’m guessing that the debt/working capital position at Genetics may have deteriorated further during 2024.
Shareholders need to approve the transaction at a general meeting, as it represents a fundamental change.
Strategic Review: BMK’s Strategic Review is now complete. BMK will now focus on its Advanced Nutrition and Health businesses.
Graham’s view
Looking forward, let’s calculate what BMK shareholders now own.
Cash/Debt: £200m minus £70m of Group debts to repay, leaving net cash of £130m.
The potential for another £30m payout based on performance of Genetics out to 2027.
Advanced Nutrition division: in H1, this division generated revenues of £40m (down 11% at constant FX) and adj. EBITDA of £9.9m (down 5% at constant FX).
Health: H1 saw £11.5m of revenues (down 37% at constant FX) and £2.2m of adj. EBITDA (down 65% at constant FX).
In aggregate, therefore, the two divisions saw £51.5m of revenues and £12.1m of adj. EBITDA.
At a group level, positive adj. EBITDA turned into negative operating profits and I can only assume that the same is true for these two divisions.
My conclusion is that BMK shareholders are going to have c. £130m of cash, the potential for another £30m, plus two divisions generating revenues over six months of c. £50m, that are probably unprofitable.
The genetics business is being sold for 4.5x sales, so if any multiple like that was possible for the other divisions, then BMK shares would currently be undervalued. Although maybe the other divisions would have already been sold, if that was possible?
As I don’t know what the remaining divisions might fetch in a disposal, I feel obliged to take a neutral stance here. The group will now be swimming in cash (nearly half of the current market cap, until they return some of it to shareholders), and so continuing the mildly negative AMBER/RED stance would seem to be asking for trouble at this stage.
Journeo (LON:JNEO)
Up 3% to 290p (£48m) - Purchase Orders - Graham - AMBER/GREEN
I noticed this one on the “Most Viewed” list today, a sign of strong interest, even though the RNS didn’t seem terribly important to me:
Journeo plc (AIM: JNEO), a leading provider of information systems and technical services to transport operators and local authorities is pleased to announce that, further to its announcements on 11 March and 26 March it has received further purchase orders to supply and install the first tranche of safety systems on RATP buses within the Transport for London (TfL) fleet.
Key points:
£1.7m award to be paid in 9 tranches.
Installations on 200 buses, to be completed during Q1 2025.
External wing-mirrors will be replaced by the Journeo Camera Monitoring System, a digital wing mirror system for buses.
Key information is that “the revenues are included in management’s expectations of performance”, i.e. the orders do not change management’s revenue expectations.
CEO comment:
"I am delighted that RATP have selected our high-performance bus safety systems. This award is a further validation of Journeo's CMS which is increasingly being adopted by safety conscious public transport authorities and fleet operators throughout the UK where we have installed around 4,000 systems, including approximately 1,500 in London."
Estimates
I don’t see any fresh broker notes this morning, although I would not expect any change to forecasts even if there were. The most recent estimates I can find - published in September by Cavendish - suggested revenues this year of £50m, converting to adj. PBT of £4.8m, with modest growth anticipated in 2025.
Forecasts also suggest a healthy cash position with net cash of £13m by Dec 2024, more than a quarter of the current market cap.
Graham’s view
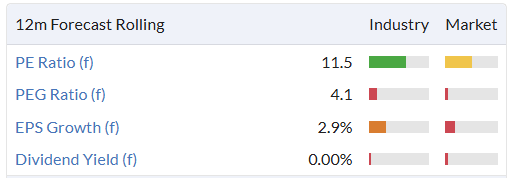
I’m happy to leave the AMBER/GREEN stance unchanged as the stock trades on a moderate earnings multiple and seems to be performing well. The share price has changed little since we covered it last, and I do not view today's update as material, even if it does help to boost visibility.
Given limited growth expectations and potentially lumpy revenues I don’t know if I’d pay a much higher multiple than the current level, but it could be worth a closer look:
Roland's Section
Kingfisher (LON:KGF)
Down 13% to 256p (£4.7bn) - Q3 Trading Update - Roland - AMBER/GREEN
Sales in line or ahead of the market across all our banners; full year profit guidance range tightened
The headline to today’s third-quarter update from DIY chain owner Kingfisher sounds confident, but unfortunately the numbers are less impressive.
Indeed, news that the owner of B&Q and Screwfix has trimmed the top end of its profit guidance for the current financial year appears to have triggered a nasty sell off:
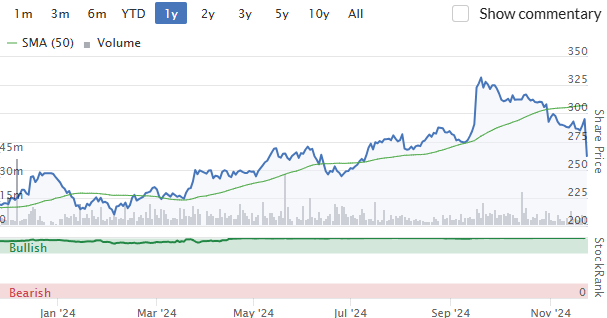
Let’s take a look.
Q3 highlights: today’s update from Kingfisher covers the three months to 31 October 2024.
Revenue down 0.6% to £3.2bn (-1.1% like-for-like)
UK up 1.2% to £1.6bn
France -6.4% to £967m
Other regions up 4.7% to £637m
The majority (69%) of Kingfisher’s revenue is essentially made up of many smaller and relatively low priced items used for home repair, maintenance and improvement (RMI). Sales in this core business fell by 0.4% LFL in Q3.
However, the group’s exposure to consumer confidence and housing was highlighted by a 4% LFL fall in big ticket sales (e.g. kitchens and bathrooms). These account for 16% of sales.
The remainder of sales are classed as seasonal. This category fell by 0.9% LFL in Q3, which the company blames on mild, wet weather in October.
Outlook: Q4 trading to date is said to show an improved trend, with LFL sales -0.4% versus -1.1% in Q3.
The company believes trading is tracking in line with previous guidance for its largest markets:
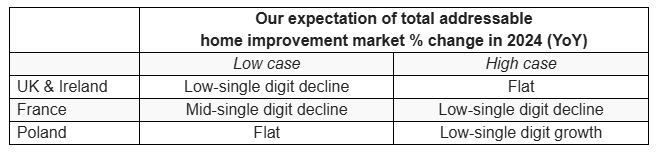
Consistent with what we set out in September, we believe the UK & Ireland and Polish markets are currently tracking within the higher end of our scenarios. We believe the French market is continuing to track at the low end.
Cost cutting has continued to help support profits this year, with £120m of structural cost savings expected by the end of January 2025.
Reflecting these various factors, the company has tightened its full-year profit guidance by lowering the top end of expectations:
Adjusted pre-tax profit of c.£510m to £540m (previously £510m to £550m)
Free cash flow expectations unchanged at £410m to £460m
Consensus forecasts on Stockopedia ahead of today’s update suggest adjusted earnings of 20.9p per share for the year ending 31st Jan 25. That would put Kingfisher on a P/E of around 12 after today’s drop, but I suspect we’ll see some modest downgrades to analyst estimates, so this multiple may increase somewhat.
Forecasts for 25/26 may also come under pressure after today’s update. Kingfisher says that tax increases in the UK and France are likely to have a £45m impact on profit next year. Some, but not all, of this is expected to be offset by further cost savings.
I don’t have access to any updated broker notes for Kingfisher, so we’ll have to wait to see what changes filter through to Stockopedia’s consensus estimates over the coming days.
Roland’s view
Kingfisher shareholders have seen a nice recovery over the last year, but much of this has now unwound.
However, while the macro environment is clearly quite weak, I do not think there’s any cause for serious concern. Kingfisher’s cash generation appears to remain strong and today’s guidance suggests the stock could be trading with a free cash flow yield of more than 9%.
On this basis, this year’s forecast dividend of 12.4p per share should be covered c. two times by surplus cash, so I don’t see any obvious reason to expect a dividend cut at this time. With the dividend yield now up to 4.7%, this could be of interest from an income perspective.
On a related note, it’s worth noting that while the StockReport shows Kingfisher’s net debt at c. £2bn, this is all lease debt (e.g. stores). The interim accounts showed a net cash position excluding leases, something that has been typical for this business in recent years.
On balance, I think CEO Thierry Garnier is doing the right things to strengthen the business while awaiting an improvement in external conditions.
The question is how long Kingfisher may have to wait. This issue is made more complicated by the group’s exposure to multiple markets.
Historically, the group’s growth has often been restricted by the tendency for strong performance in the UK to be offset by weaker performance in France, or vice versa. This seems to remain a problem.
A 10-year snapshot of operating profits suggests this business may be better suited to cyclical trading than long-term holding:
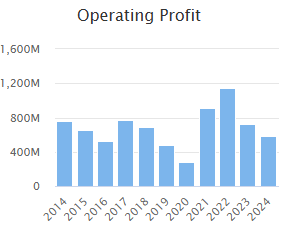
I can’t ignore the risk of further downgrades. But on balance, I think some caution is already reflected in the stock’s reduced valuation. I can see some value here, so I’m comfortable taking a view of AMBER/GREEN.
Synectics (LON:SNX)
Up 0.6% to 315p (£56m) - Contract awards - Roland - AMBER/GREEN
This small-cap surveillance technology specialist has issued another contract award RNS today, disclosing details of two new business wins for the company totalling £2.3m in value. Both are in the offshore energy sector, highlighting the company’s strong credentials in this market.
Qatar: a £1.8m contract with North Oil Company (NOC) to provide Synectic’s security camera station technology as part of the Ruya Project to expand the Al-Shaheen field, Qatar’s largest oil field. Delivery in two phases, expected in 2025 and 2026. This is a repeat customer for Synectics.
Brazil: a £0.5m contract to provide “specialist security and surveillance solutions” for a floating production, storage and offloading vessel. The solution provided by Synectics will help to ensure “compliance with rigorous offshore safety and performance requirements”.
These wins continue a strong recent run for the firm:
4 November 2024: a £2.2m contract with National Grid, following on from previous contracts awarded under the same framework agreement.
9 September 2024: $3.2m contract award at a gaming resort in Asia (casinos are another key market for Synectics products). This extended a $10m contract announced in June 2024.
Outlook: for a company with annual revenue of c.£55m, contract wins of this size are clearly material. However, today’s wins appear to be within existing broker forecasts for the firm.
With thanks to Synectics’ house broker Shore Capital, I can see that earnings forecasts for FY24, FY25 and FY26 have remained unchanged after today’s news.
Shore’s estimates match those shown in the StockReport for 2024 and 2025:
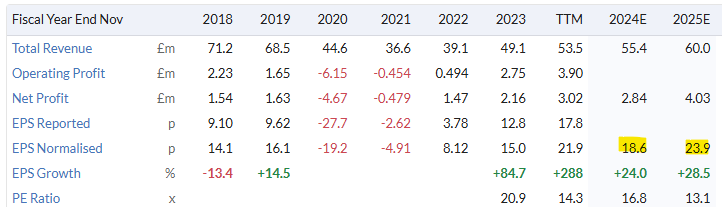
Roland’s view
If the strong profit growth seen over the last couple of years can be maintained, then I think the stock’s forward P/E of 17 could still reflect attractive value.
Graham highlighted a potential opportunity here back in February, suggesting further upside was possible. The shares have since doubled, providing a nice return for investors who did their research and decided to buy in:
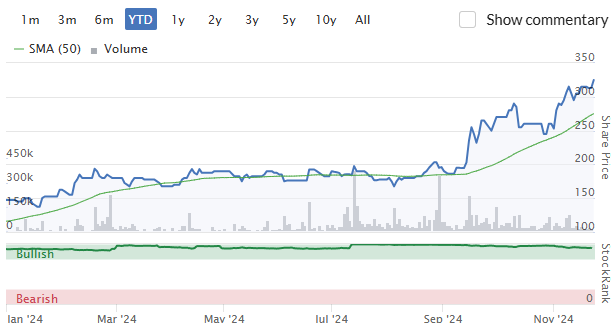
While the value may not be as obvious as it was at the start of this year, I’m encouraged by the operating leverage on display as Synectics continues to scale.
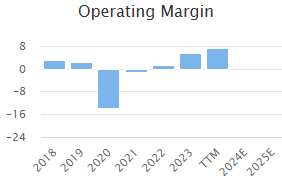
The company’s operating margin has improved steadily with sales growth, suggesting it’s been able to deliver higher sales without a corresponding increase in costs. In situations like this, profits can grow significantly faster than sales, potentially supporting a much higher share price rating.
However, while progress so far is encouraging, I think it’s worth remembering the downside risk here too.
The 7% operating margin achieved by Synectics over the last 12 months is unspectacular, in my view.
Meanwhile, unchanged forecasts after today’s news are a reminder that a fairly strong rate of growth is already baked into the share price. This is also reflected in Stockopedia’s High Flyer style rating, providing a useful reminder of the potential for a share price slump if Synectics’ results should disappoint the market:
Checking back in the archives, we last viewed Synectics as GREEN in September, when the shares were at 225p and the company upgraded its guidance for the current year.
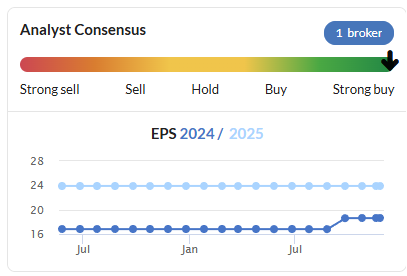
Given the 40% share price increase since then and the lack of any further upgrades to guidance, I’m going to step back a notch to AMBER/GREEN following today’s update.
Keelan's Section
Metals Exploration (LON:MTL)
Up 1% to 5.8p (£101m) - Operational Update - Keelan - GREEN
Philippines-based gold producer, Metals Exploration, has been one of the standout performers in this year’s NAPS portfolio. The share price has more than doubled year-to-date and shows no signs of slowing down after this morning’s operations update.
The company has announced that it now expects to exceed its previous upper-end target of 80,000 ounces of gold for the year. The total figure is now forecast to come in at around 82,500 ounces. The additional cherry on top is that the AISC, or All-In Sustaining Cost per ounce, is expected to fall to $1,125 per ounce, nicely below the lower guidance target of $1,175. At the current gold price of $2,670 per ounce, the company is making a profit of $1,545 per ounce…
This level of profitability is what led me to cover Metals Exploration in a recent article, which also explores what gold and silver miners may have in store for 2025. What strikes me most about Metals Exploration is its incredibly low valuation, despite its share price strength over the past year.
The company trades on a forward price-to-earnings ratio of 3.9 and, more impressively, a price-to-free cash flow ratio of just 2. This means that the company’s current free cash flow generation could pay back the equivalent of its market capitalisation within just 2 years. If you look at the most recent quarterly cash flow figures and extrapolate these it gets even better. Metals Exploration is well on track to generate around $100 million in free cash flows this year. An impressive feat for a company currently worth $126 million.
Now, when companies trade at these valuations, there’s likely to be a catch. Of course, miners will typically receive lower valuation multiples due to their cyclical nature. However, in this case, the market’s hesitation stems from concerns about Metals Exploration’s reliance on its single-producing asset, the Runruno mine. Current estimates are that only a few years of production remain, and the mine’s limited life significantly impacts long-term earnings visibility.
Therefore, the management team has actively been looking at ways to extend the mine life, whilst also securing other assets nearby. The acquisition of Yamang Mineral Corporation (YMC) this year will allow it to apply its technical expertise and hopefully secure the company’s future growth prospects in the Philippines. I’ve provided more details of these activities in my recent article.
Keelan’s view
Even with limited mine life left, the current gold price environment has transformed Metals Exploration into a cash cow and one of the cheapest companies listed on the London markets. Moving into a net cash position with substantial free cash flow generation gives the company much greater flexibility. It can now invest money into its new Abra tenements from the YMC acquisition, acquire further complementary assets, commence dividend payments or buy back shares, all of which could justify a higher valuation in the future.
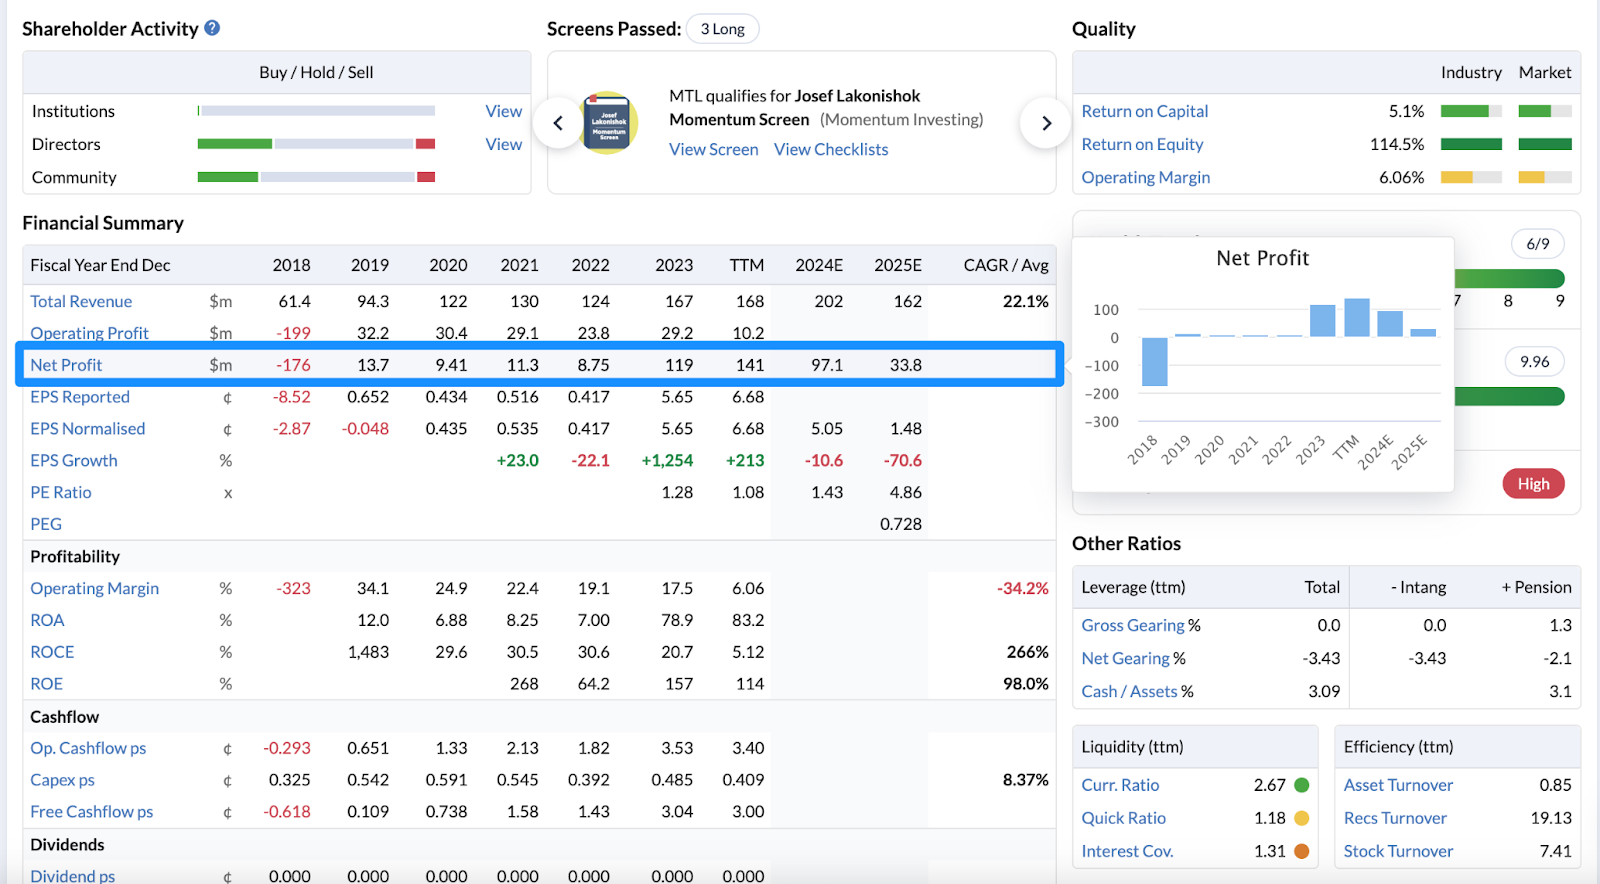
After the full-year results are published, brokers will likely start revising their projections as well. A forecasted net profit of $33.8 million for FY2025 is currently too conservative, given the company’s production rates and the current gold price.
As long as the gold price doesn’t fall off a cliff in 2025, and there aren’t any operational issues (the Philippines is unfortunately very natural disaster-prone), the company is well positioned for a strong 2025.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

95 comments
Any miners in jurisdictions which need cash to support their economy are at risk of ever increasing tax/bungs/etc. Killing the "golden goose". South Africa er anywhere outside of North America is a risk trade.
Cheers Roland for the review on Synectics (LON:SNX) . I agree it does look expensive atm. I wouldn’t buy now, but that’s because it’s not my style of investing. As long as they keep winning contracts it should slowly increase in sp but who knows what will happen tomorrow. I am happy to continue to hold though, until bad news comes out. As they say, run your winners.
ITV (LON:ITV) Short Interest has moved from 4.54% on the previous trading day to 5.11% today.
Definitely makes you wonder if people know something we don't. Seems mightily odd for shorting interest to increase off the back of a bid offer rumour. But short interest has been increasing rapidly over the last month or so. I'm not a cynic, but it does make me wonder whether those doing the shorting know something we don't, and have released the takeover rumour to try to lock in further profit when whatever has persuaded them to short the company, comes out.
I bought recently on the low, very tempted to now immediately get back out simply based on the rising short interest, as strong short interest nearly always seems to precede a sharp drop.
Hi Dragon
Where did you get your information for today’s increase in short interest in ITV (LON:ITV) ?
Research tree show an increase in short interest to 5.1% over the last month.
Research Tree or shorttracker.co.uk
EDIT:
My original post came from an email from Research Tree today, worded:
"The level of disclosed Short Interest in ITV has changed materially.
Short Interest has moved from 4.54% on the previous trading day to 5.11% today. That is a movement of 0.57 percentage points."
But looking on Research Tree it occurred on Friday 22nd.
Morning Dragon
Thank you for your reply, if the short interest increased on Friday, prior to Sky News breaking the story about a potential bid, this suggest that those who shorted ITV (LON:ITV) may well have got burnt. No sympathy from me if they did.
Small dip in Brickability (LON:BRCK) towards the end of the day - can anyone shed any light on why?
Brickability (LON:BRCK) down 7.5%. Either leaking bad news or MM tree shake ? Results out tomorrow ............
Brickability (LON:BRCK) buying and selling through the day above 60p then two trades shown at the end of the day totalling under £9k at 56p (one an uncrossing trade) and the share price is shown down over 7% at 56p but is it really? We'll see what tomorrow brings.
Brickability (LON:BRCK) If one believes the recent in line trading update and there is no reason not to the shares are very cheap. The update cites positive momentum in order intake, particularly for bricks indicating improving sentiment around recovery in the current financial year. Also the share price drop today occurred on very low volume. We shall see what tomorrow brings.
ITV (LON:ITV) an increase in short interest is unusual on bid rumours. However it is fantasy in my view for ‘shorters’ to fabricate rumours in order to improve their trade. Are Sky News that gullible? I would be very surprised.
More likely the rise in the share price has created an opportunity to profit further should the rumour turn out to be just that. Again speculation. I know that I have no idea!
Roland,
Thank you for your review of Synectics. It's one of my favourite shares - up almost
300% since I started buying a year ago. By the way, after SNX's year end in a few
days the P/E will fall back to 13.1. Thank you for your excellent reports - a - perfect
blend of intelligence and common-sense - a true Yorkshireman! (like me).
Philip Hayton
Stelrad (LON:SRAD) is down 8% today and has lost C15% recently, it had an RNS'd TU and a CMD on Novenmer 14th that read OK, anyone have any ideas why it has fallen so much ?
Not sure if it has been mentioned already but there was a little bit of insider buying at JD Sports Fashion (LON:JD.) last week with the Chairman and a director buying at 96p...
Keelan, about Metals Exploration (LON:MTL), I am not sure that your comments about mine life are right. My understanding from what management have been saying is that Runruno will be running out of mineable ore by 2028, and that the probability of any significant extension to that is close to zero. The valuation, although cheap, is not unreasonably so for a mine with only a few years life left. The interest in the stock now lies with Abra, which management have been aware of for some time, and they have been to some trouble and expense to acquire this property. Most of their cash flow will go into Abra, possibly none at all into dividends. If Abra is successful, Metals Exploration (LON:MTL) stands to be worth rather more than £100 million. I hold.
Hi SundayTrader,
Thank you for your comment.
It does look like the exploration programmes that were undertaken to identify new gold resources around Runruno have not been fruitful to date.
However, that still gives the company over three years of (albeit declining) production, which would see its balance sheet significantly strengthened from the free cash flow generation.
These robust cash flows will provide the company with the resources needed to execute the extensive drilling programme at Abra, while also opening the door to pursuing other ventures. It's worth noting that the company has just earned the "Government Industry Award" for the third consecutive year, highlighting the management team's strong reputation in the local industry. This puts the company in solid standing if it does decide to acquire further projects.
I believe that drilling is now officially underway at Abra on the Menikbel prospect. Hopefully, shareholders will have plenty to look forward to with upcoming drilling news. The initial resource estimate is expected to be ready around Q3 2025, so this will be a key period for Metal Exploration's future.
As you say, positive developments at Abra would likely lead to a substantial re-rating by the market.
Best,
Keelan
Agreed. I hold a large amount here, so far up around 80 percent, but would like to see 10p early 25 on the back of strong results and positive results at abra. Our balance sheet will look spectacular with the rising gold prices. Even if we do get bad news regarding abra I still see a lot of positives here.
It should be noted there’s been some heavy buys from the evans family and some at 6.75p, so I’m confident if they are happy to pay that, I’ll keep hoovering up shares in the 5s for now :)
Benchmark Holdings (LON:BMK) - Disposal of Genetics operation for £260m - latest note available here: https://www.equitydevelopment....
Benchmark Holdings has announced the disposal of its Genetics operation to Starfish Bidco AS for an enterprise value (EV) of £260m, comprising an initial consideration of £230m in cash plus an additional contingent consideration of up to £30m. The disposal indicates an EV/EBITDA multiple of 17.9x (£14.5m E). The contingent consideration is based on the performance of the core salmon sub-segment (salmon eggs production) of the Genetics Business from 1st October 2024 to 30th September 2027. Conclusion of the disposal is expected in Q1 25, subject to shareholder approval and regulatory clearance.
The disposal enables the reduction of debt and operational streamlining, and the transaction concludes the formal strategic review Group announced on 22nd January 2024.
We will review our outlook for the redefined Group and Fair Value with the publication of Group Q4 and full year FY24 earnings which is expected in early December.
Volex (LON:VLX) down and TT electronics (LON:TTG) up again today - maybe we should ask SKYNEWS for their take on potential takeover
Following on from the gripes about subscription rates for new members as opposed to existing subscribers, is it just me that has noticed the dramatic fall off in the numbers of posts in this SCVR (or whatever you call it now) board since Paul left and set up on his own? This myriad of comments by the learned members of the community was for me, as well as PS insights, a major plus point in the subscription
BTW how do you cancel the automatic renewal?
Just click on your profile and go to subscriptions and billings
Threepeat
“ is it just me that has noticed the dramatic fall off in the numbers of posts in this SCVR (or whatever you call it now) board since Paul left and set up on his own? This myriad of comments by the learned members of the community was for me, as well as PS insights, a major plus point in the subscription”
I’ve obviously noticed the drop off but it doesn’t necessarily jump out to me as a bad thing. To be fair I learned a lot from some of Paul’s and some departed member’s musings. I am still learning a lot more from DSMR (new name) and current contributers plus the various other threads on Summer Stage 2s (1389 posts since May 20th), Investment Trusts and of course Ed’s seminars and the Stocko Academy.
I do hold Small Caps (‘elephants don’t gallop’ and all that) but they are only about 30% of my holdings in my Stocko portfolios (and are dwarfed by my other non-Stock investments). I now can keep up to date without ploughing through dozens of other posts.
Good point about the plough
Paul could plough through the RNS's like none other, he certainly was/is the early bird. Members posts, speaking for myself, were for later consumption and still are.
is it just me that has noticed the dramatic fall off in the numbers of posts in this SCVR (or whatever you call it now) board since Paul left and set up on his own?
Out of sheer boredom at the dreariness of the comments section I recently counted the number of SCVR comments that included some level of stock analysis on a couple of days. One day there were 7 out of 113, another 9 out of 104. And when I say "analysis" I'm being off the scale generous. "Mentioned" might have been more honest.
Last Thursday there were 66 direct stock related comments out of 116, plus an interesting discussion on AI that got me thinking.
There may be good reasons for following Paul, but the quality of comments since he left isn't one of them.
timarr
The Phoenix Joined 2013 1,078 posts Fri, Nov 22, 2024
Stocko's answer to Phil and Grant of Eastenders fame
Charles Mitchell Joined 2021 1,052 posts Yesterday 7:21 pm
Phoenix- I went to a restaurant on Kefalonia 16 months ago to be greeted by "Eastenders" -Ken was not with me! I never watched the show- though had to wean my wife off it when we first met- restaurants and wine bars in the 80's did the trick !
The Phoenix Joined 2013 1,078 posts Yesterday 7:53 pm
Brilliant Charles and thanks again for the heavy lifting yourself and Ken both do on the monthly investment trust threads.
Charles Mitchell Joined 2021 1,052 posts Yesterday 7:58 pm
It is hopefully of interest- Trusts are a much maligned sector. Saw that in the 1980's when I sold them to institutions! Though we did quite well at it- the WoodMac team-I was a part of. Lucky to work with Robin Angus and Hamish Buchan- the experts. The late Robin Angus was a mentor to me in my early days and recognised as a true expert on the sector, miss his annual review. Never invested in Personal Assets Trust (LON:PNL) but he was involved in the formation of that to create a vehicle that did not rip off private investors.
ridavies Joined 2014 801 posts Yesterday 6:16 pm
Thanks to both timarr and Rusty2, and I think you both came up with the same comprehensive 'go to' links.
Unfortunately, I was referring to a contributor here who outlined his investments in ITs and outlined the impressive divis, then followed up some months later with an updated version of the original. Frustratingly, I can visualize the pages on this site but cant remember the name and didn't take a copy of the lists.
Jog anyone else's memory please? All I can remember in addition was that it was most impressive and helpful.
Note to self - always copy and file at the time!
I ask the readers' forbearance in repeating this request this morning.
. I posted this request late Friday and kindly Rusty2 and timarr responded. Unfortunately, although useful, it was not exactly what I was looking for. Any other takers please who do remember what is in my mind?
It was a specific reader who outlined his holdings of ITs, then some months later updated, It was a ready made list for someone who wanted to move in the direction of ITs out of equities. Thank you all.
ridavies Joined 2014 801 posts Fri, Nov 22, 2024
A general query. Does anyone remember the poster here who on several occasions has provided a really good analysis of his Investment Trust holdings, and ed specially a review of their outstanding dividends. I am considering at least a partial change of strategy as a result of a change in my family priorities.
I would love to have an update, as well as a pointer so that I can re-read his earlier postings.
Thank you.
Rusty2 Joined 2014 8,636 posts Fri, Nov 22, 2024
You probably mean this: https://www.stockopedia.com/co...
timarr Joined 2009 2,408 posts Fri, Nov 22, 2024
Does anyone remember the poster here who on several occasions has provided a really good analysis of his Investment Trust holdings
Ken and Charles do their stuff here:
https://www.stockopedia.com/co...
Follow the links at the head of the article for previous months.
timarr
Possibly
Investment trust thoughts november
?
Shoeshineboy or Brucie spring to mind
RIdavies, The list may have changed- depends how long ago it was posted. Some of the High div payers have cut dividends etc. The AIC have a dividend hero page- Trusts that increase dividends every year. Might be a starting place. https://www.theaic.co.uk/incom...
I would think Henderson Far East Income (LON:HFEL) would of been on it, high yield and chance of some div growth. Many of the infrastucture trusts have good yields- but caution is advised as some could be vulnerable. Here are all Trusts sorted by highest yield first https://www.theaic.co.uk/inves...
Ridavies.
It could be my posts you’re referring to, and hence the links to the relevant threads and links to them helpful posters here have already posted for you.
The difficulty is in me finding the specific post you want to read again as I’ve posted a lot of different ones both on threads I’ve started here and on the excellent Investment Trust threads on Stockopedia set up and run by my namesake Charles Mitchell.
I’ll do my best to help you but it’s SO difficult finding past posts here.
National world
What a weird company and management
The top table reward themselves with huge picket filling incentives which we must presume must because they are so very good at their jobs .
Then up pops a cheeky bid
And the defence is “oops dont trust them they seem to owe us 4.4 million that we only recently figured out .
I can think of any single company rhat “discovered” 4.4 million of. Invoices under declared where the FD would be able to show his face .
What sort of show are they running .
my guess is as David Montgomery and team are trying to turn Nwor into an online platform they dont have a clue as most octogenarians I know will be blussfully unaware of the fast moving internet .
On the very positive side od this I asked my FD on friday to do a check and hes found 4.5 million too tucked away that a customer hadnt self billed ?
What are these "incentives" you are referring to ? National World (LON:NWOR) is at least the third group of newspapers he has set up and at least the fourth that that he has been boss of. Montgomery has set up a good business in an unpopular industry as shown by this derisory offer.
Just read the RNS history
For example may 24 montgomery gets over 600,000. Ltip at 0.01p
Why does someone who already owns over 7% of the comoany need these ?
and why at 0.01p.
Montgomery is a dinosaur and a pocket filling clown who does not loo after his shareholders
There is now very likely to be an EGM called by a shareholder over 5% bringing hom to account .
Only just seen this. Ok so he has been given £65,000 worth of shares , but he has resurrected another newspaper group.
I suspect shareholders have more important things o think about.
He got over 4m shares last year, for nothing.
hVIVO (LON:HVO) (I hold) continues its decline. Whilst looking online for the purported link between Kennedy as new Health Secretary and HVO, I came across the below article. If he only initiates half of the policies mentioned, it is bound to impinge very significantly on HVO, which counts US big pharma amongst its major clients. I do not know whether Kennedy is a done deal or whether his appointment has to be approved.
https://nymag.com/intelligence...
If Kennedy is the reason for the hVIVO (LON:HVO) sell off then I suspect it is over done. I've been caught out but I'm not selling. Charts indicating price is oversold and sitting just above gap up and volume shelf, which can act as support.
Revs8 - hVIVO (LON:HVO) I'm in the same boat. I was too eager and added at the £26 level which brought it up into my Top5, but wish I'd added today at£20 ! Can't see anything on their pages about an update, last year there was one around Dec13th, any views on a date ?
In my view that should settle things a bit as all indications were good at the last TU - but hey.... Anyway, I'm sitting it out despite the fall.
hVIVO (LON:HVO) - Now down circa 30% over last few days - Oversold who knows - ? Doubt this is all down to Kennedy - Maybe time for a buyback programme
In the past two or three years hVIVO (LON:HVO) hasn't been backward in coming forward to tell us about positive deals and 'ahead of' trading. It's been a while since we've had that now.
At the interims some H2 profits were brought forward to H1 and they spoke about new field study services. It's not clear to me if demand in their traditional target market was starting to wane and needed support from the field study service to meet forecasts...all this before Trump.
In summary, whilst great contract visibility might give confidence about FY 31 December 2024, its unclear if the prospects are as good for FY25.
Why do you think that Rogerh?
Kennedy has publicly said he is not against vaccines per se but he is pro choice and pro transparency.
What that means in my view is the likelihood is that phase 3 trials will become more expensive. That in turn should mean it is likely that pharma will turn increasingly to challenge studies since they are far cheaper to run and more or less tell you the same thing BEFORE you spend any phase 3 money. Ie avoids wasting money on failed phase 3
Secondly hVIVO (LON:HVO) are focused on growing Asia ~ the last two large contracts came from there. So the US whilst important is by no means the only thing hVIVO (LON:HVO) is reliant on. Then you have the fact that this is a UK and European company that operates solely out of those regulated environments so faces none of the US rhetoric, aside from some of its clients demand or spend from the region.
Then we have the 35% net cash position.
The company would be wise in my view to issue some sort of trading statement though given the decline in share price. Either someone knows something the rest of us dont - which would be very bad form - or this is a classic case of the current small cap environment where any potential read across is taken as a sell signal until proven otherwise with a hefty dose of poor liquidity thrown in.
Anyway let’s see.
By way of a follow up to my post on Friday in respect of Games Workshop (LON:GAW) and potential future growth prospects, I thought it might be instructive to take a deeper dive into the sales mix by channel (retail, trade, online) and geography.
Retail are sales through their own stores (548 global stores in total, mostly one person operations).
Trade sales are through third party retail outlets which presumably are higher margin and less hassle. This trade channel is where the growth has been coming from and appears to be the strategic target for growth particularly in North America as I discussed on Friday.
Worth noting that trade sales include those third party retailers' own web stores as well as physical stores. Online sales figures do not therefore include online trade sale.
I created the following spreadsheet from the annual reports since 2017.
Takeaways as I see them are:
Finally, this website https://spikeybits.com/warhamm... gives a sense of the excitement around the forthcoming TV collaboration with Amazon Prime. That Henry Cavill is such a passionate exponent of the hobby will certainly do no harm to the prospects for the show's success. “It is the greatest privilege of my professional career to have this opportunity.” Apparently he will both produce and star in it.
Good post,
Trade sales are lower GM as the product is sold to trade at 55-60% of RRP. It's also worth noting that trade volumes are therefore a higher % than the financials suggest due to this. GAW always sell the product at RRP. The fact that GAW online is more expensive than trade online probably accounts for the lower growth at GAW online although site hits are currently running around 20% ahead in Sept & Oct (SM2 effect).
One plus side for Kingfisher (LON:KGF) is the recent demise of Homebase. Although some of the stores are likely to re-emerge under other names, they'll likely be less of a competitor. In the UK there is really only B&Q and Wickes left as large retail DIY chains.
There are other stores now doing DIY, such as B&M European Value Retail SA (LON:BME, Dunelm (LON:DNLM) and The Range. I use Screwfix and Toolstation. Screwfix is owned by Kingfisher (LON:KGF). For paint you can good deals online from the Paint Shed, which is owned by Brewers. I had a Homebase but never used it, prices were too high. B&Q closed our branch, down years ago. There is a Wickes but l rarely use it.
Rumours of potential bids for ITV (LON:ITV), either in whole or part, are being reported and the share price is up at the time of writing.
ITV (LON:ITV) - Yes but not the rise you would expect if an offer is coming - be interested to hear thoughts from others......
Hasn’t there been rumours of a take over for the last 10 years?
Agreed it isn't a huge rise on the day but it was also up on Friday perhaps when rumours were heard in the City.
It is a very different business to what it was 10 years ago. Reports are questioning if the streaming side alone is worth more than the current market cap. Interested in the views of the team and glad to see it has been added to the list of companies reporting and that Megan will be taking a look at this.
Agree - and Megan has done well with her analysis - Thanks Megan
Apparently short interest is up slightly today in ITV (LON:ITV) see comments here. Definitely some food for thought to get a balanced view of this.
Graham, is there any chance for your new spreadsheet you could highlight where a share has beaten expectations. I assume this will be slightly different to your green, amber/green ratings as beating expectations should indicate an improving situation.
Good question, DLTTWTG. I'll have to consider how this might be possible. G
Athelney Trust (LON:ATY) - "Yield attractions with small caps out of favour" (new research note here: https://www.equitydevelopment....)
ATY should be of interest to investors tracking the relative undervaluation of UK small caps vs their international equivalents, and indeed the segment’s underperformance generally. Over the longer term a small cap weighting would be regarded as a core component of a diversified portfolio. It has, however, materially lagged mid and large caps in recent years.
Those who see this differential as cyclical and temporary, rather than structural, will see potential for resumption of long-term outperformance. ATY should be of interest to investors tracking the relative undervaluation of UK small caps vs their international equivalents, and indeed the segment’s underperformance generally.
ATY holds a diversified portfolio of established, cash generative businesses, with proven management and competitive advantages in their specific industry niches. The core investment focus is listed UK smaller (£50-230m market cap) companies, all at a stage of their lifecycle where they pay regular dividends. This support ATY’s own distributions and core commitment to maintain progressive distributions.
At today’s share price ATY is underpinned by its 5.5% yield (historic), backed by a 21-year history of distribution growth and commitment to maintaining membership of a small group of ‘dividend heroes’. The mid-price is also at a 9% discount to end October NAV/share.
Can any of the knowledgeable contributors here clarify what will happen when Nexxen International (LON:NEXN) delist from AIM and relist on Nasdaq. I have read the information on their website but it has somewhat gone over my head. As a shareholder what will happen if I wait until they actually delist, will I get he cash value at the close of trading, will I be left with unlisted shares, or should I just sell at some point before the last day of dealing on AIM (14 Feb 2025)? Any advice/clarification regarding what happens in these situations will be appreciated. There is also a 2 for 1 reverse split planned if I have understood correctly. Apologies for posting here but not sure where else would be seen and I imagine others here may have a similar query.
We may know more after the AGM being held on Friday 20th December. Nexxen International (LON:NEXN) may perform better without its London listing, I don't know, it's one of my aging dogs that I hold.
KGF - the comment '... Looking towards next year, recent political and macroeconomic developments have layered incremental uncertainty onto the near-term outlook in our markets' looks like a clear pointer for a downgrade to next years forecasts, which were for around a 15% increase in EPS
Another 2 contract awards for Synectics (LON:SNX) totalling £2.3m. Earlier in the month they has a £2.2m contract award. Good to see so many contracts, making the company diversified and not relying on one big contract.
Thanks gmtrader, we added that announcement to the summary table. G
Your welcome. The two contracts are £1.8m and £0.5m, so total is £2.3m.
Thanks for highlighting this gmtrader, I double counted one of them but will update the table to show £2.3m.