Daily Stock Market Report (Mon 28th Sep 2026) - KLR, LIKE, CCT, TRB, CKT

Good morning!
Iran: The proposal from Iran to immediately reopen the Strait of Hormuz has been rejected by President Trump. Their proposal is said to be similar to the MoU that the two countries signed back in June. Trump expects new concessions, but the Iranian Foreign Minister has said “we have no reason to come back to diplomacy and engage with this administration once again”. The price of oil has risen overnight.
Flawed housebuilding: there was negative publicity for the housebuilding industry over the weekend as the BBC reported on first-time buyers in Leicestershire who found 150 defects in their new home. The home in question had been built by Countryside, which is owned by Vistry (LON:VTY). The article does acknowledge that all of the issues were covered by warranty and were fixed. Edit: Vistry shares are doing well today (up 10%) thanks to...
First-time buyer boost: Andy Burnham's new "Your First Home Scheme" has sent the shares of consctruction firms flying this morning. Here's the official announcement.
Key points:
- An equity loan scheme "to get more people into homeownership"
- Only a 2.5% deposit required.
- Initial interest free period.
- Will include a household income cap and local property price caps.
- Further details to be announced at the Budget next month.
The announcement has predictably been welcomed by the Home Builders Federation and slammed by the Conservatives.
MJ GLEESON (LON:GLE) is up 18%, Persimmon (LON:PSN) is up 14%, and Taylor Wimpey (LON:TW.), Crest Nicholson Holdings (LON:CRST) and Bellway (LON:BWY) are all up 12%.
Overnight market movements:
The FTSE is up 0.3% at 10,720
S&P 500 is down 0.4% at 7,715
Brent crude (December) is up 1.8% at $99.10/bbl
Gold is down 2.4% at $4,180/oz
Bitcoin is down 1.6% at $83,200
Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Land Securities (LON:LAND) (£4.6bn | SR39) | This 245 sq ft property has been sold to Seven Capital plc for a total consideration of £211m, equivalent to a five-year net rental yield of 6%. LandSec has now sold £550m of offices since early 2025 and remains on track with its plan to release £2bn of capital by 2030. | ||
HICL Infrastructure (LON:HICL) (£2.5bn | SR91) | HICL has invested c.£68m for a 42% stake in Hector Rail, the largest private sector rail freight operator in Scandinavia. The acquisition is expected to support HICL’s medium-term total return target of over 10% per year. | ||
Entain (LON:ENT) (£2.9bn | SR26) | An executive measure in Brazil currently withdraws all operators’ ability to operate online sports betting and gaming. This is initially for a 120-day period and requires Congressional approval to become permanent, so the eventual outcome is currently uncertain. Brazil was only expected to make a modest contribution to group EBITDA this year. FY26 group underlying EBITDA guidance of £910m to £960m remains unchanged, albeit the company expects to be at the lower end of this range. | ||
Keller (LON:KLR) (£2.27bn | SR95) | Keller has been granted a further $650m contract relating to the I-40 in the US. This increased the order book to c.£2.4bn and improves longer-term revenue visibility. There is no change to 2026 expectations. | AMBER/GREEN = (Roland - I hold) This contract extension adds around 20% to Keller’s June ‘26 order book and improves revenue visibility. The company has now won c.$1bn of work on the I-40 project, making it the company’s largest ever. I estimate this work accounts for c.28% of the remaining order book, creating some concentration risk. However, the US isn’t sure of major infrastructure projects and Keller is a recognised market leader in specialist geotechnical work. I’m inclined to maintain a broadly positive view given recent earnings upgrades and evidently strong momentum. | |
Bodycote (LON:BOY) (£1.61bn | SR70) | CVC has decided not to make a firm offer. The firm offer from Veritas at 940p remains unchanged. | TAKEOVER | |
Serica Energy (LON:SQZ) (£1.05bn | SR86) | Serica is applying for admission to the Main Market and expects this move to occur before the end of October 2026. | ||
Firstgroup (LON:FGP) (£957m | SR67) | Completion of Group pension buy-in and return of £17.5m escrow funds | Completed buy-in of c.£90m of Group Section Pension liabilities. Escrow of c.£22m was used to complete the transaction, of which c.£17.5m has been returned and £2.1m was used towards the buy-in premium. The balance has been retained in escrow to cover costs. The group retains c.£44m in escrow relating to the Bus Section [pension] that will be reviewed as part of the 2030 triennial valuation. | |
Burford Capital (LON:BUR) (£603m | SR12) | The jury in a patent case involving Apple in which Burford has a financial entitlement has awarded $5.7 billion in damages to the plaintiff, of which Burford's entitlement would be $1.4 billion. The company stresses this amount is likely to be altered in post-trial and appellate proceedings that are likely to “unfold over a considerable period of time”. | ||
James Halstead (LON:JHD) (£546m | SR79) | Results due on 1 Oct 26 will be delayed to 14 Oct 26 to allow the company’s auditor more time to finish its audit procedures for FY26. The company has not been informed of any material audit issues affecting the financial statements. | ||
Metals Exploration (LON:MTL) (£514m | SR76) | First gold production at La India remains on track for December 2026. Post draw down of an equipment loan, the company’s cash position is £25.8m. The maiden drilling programme at La Grecia has returned “high-grade gold intercepts including 1.30m at 36.5 grammes per tonne gold”. | ||
Chrysalis Investments (LON:CHRY) (£331m | SR43) | Chrysalis has completed the sale of its remaining shareholding in Klarna for £34m. The company will now begin a compulsory capital redemption of c.£25m at 127p per share. The balance of c.£9m will be retained by the company. | ||
Tullow Oil (LON:TLW) (£326m | SR 72) | H1 working interest production up 7.6% to 43.7 kboepd. Revenue +21% to $496m with adj EBITDAX down 3.3% to $743m. FY26 outlook: production at high end of guidance of 34-42 kboepd. Upgraded FCF guidance of $170 to $250m at $70-100/bbl is unchanged. | ||
Capricorn Energy (LON:CNE) (£321m | SR96) | DNO confirms that its final offer of $5.214 per CNE share remains unchanged and that it will not counter Genel’s increased offer of last week. | TAKEOVER | |
Halo Minerals (LON:HALO) (£314m | SR8) | The BIOS Mining & Infrastructure Class 3 engineering and cost update for the Playa Verde copper and gold tailings reprocessing project in Chile has been completed. Class 3 capital cost estimate is c.$92.8m, with estimated operating cost of c.$2.20/lb recovered copper and a seven-year, 5.0 Mtpa production profile. | ||
Winvia Entertainment (LON:WVIA) (£260m | SR35) | Half-Year Results & Acquisition of The Giveaway Guys and Win Life | H1 revenue +42.7% to £109.7m with operating profit +142% to £12.6m. Outlook: FY26 adj EBITDA expected to be ahead of current market expectations. Acquisition: the companies acquired have a common owner and generated adj EBITDA of £4.25m for the year to 30 June 2026. Total consideration is £19.1m plus a potential earnout. | |
Tribal (LON:TRB) (£180m | SR89) | Increase from c. £189.3m to c. £231.2m, equivalent to c. 105p per share (TRB share price: 83.8p). Irrevocable undertakings: 52.7%. | TAKEOVER (Graham) | |
Andrada Mining (LON:ATM) (£156m | SR35) | H1 FY2027 contained tin production +13% to 576 tonnes, with H1 tin concentrate production +11% to 955 tonnes. Feed grade and processing performance were both improved. Outlook: further improvements in H2 are expected to increase run-rate production to 1,500 - 1,900 tpa contained tin. | ||
Strategic Minerals (LON:SML) (£148m | SR44) | The U.S. Department of War has invested US$9.25m of funding in SML’s subsidiary Cornwall Resources Limited (“CRL”) to significantly accelerate the Redmoor tungsten-copper-tin project, located in Cornwall, UK, through all feasibility studies, and towards a final investment decision for mining. | ||
Likewise (LON:LIKE) (£127m | SR65) | H1 revenue +15.4% to £89.9m with adj pre-tax profit +79.5% to £1.32m. Q3 sales +29.1% with YTD sales +20.7%. FY26 outlook: results expected to be materially ahead of market expectations. Zeus forecasts: FY26 adj PBT +25% to £5.0m, adj EPS flat at 1.3p reflecting dilution from recent fundraise. | AMBER = (Roland) There’s nothing much to dislike about these half-year results, which show strong growth, improved margins and market share gains. However, while I think Likewise was right to raise new £32.5m in new equity recently while demand is strong, the resulting dilution has dampened down EPS growth. With the stock now priced at 28x FY26E earnings and slower EPS growth forecast in 2027, I continue to think the valuation is up with events. I’m leaving our neutral view unchanged today, despite the stock’s well deserved High Flyer status. | |
Phoenix Spree Deutschland (LON:PSDL) (£123m | SR25) | EPRA NTA per share -1.2% to €3.36. €28.1m of sales notarised during the period, with €17.5m of cash returned to shareholders post period end. Outlook: a further €21.3m of notarisations are required to meet the FY26 target of at least €55m. Average prices on apartments for sale were reduced in September by an average of 9%, following a previous reduction in July. | ||
Roadside Real Estate (LON:ROAD) (£100m | SR15) | Has sold an outstanding loan note from Cambridge Sleep Sciences for £4.5m. The cash will be used to support increased working capital due to the acquisition of DA Roberts and higher fuel prices. Net debt is expected to fall in 2027. | ||
Redcentric (LON:RCN) (£98m | SR47) | Revenue -2.3% to $132m with ARR -2.1% to $116.2m. Adj EBITDA -7.4% to £17.4m with adj EPS -13.7% to 3.3p. FY27 outlook: adj EBITDA is expected to be in line with current market expectations. | RH note: these results cover the year to 31 March, so have taken almost six months to produce. | |
4Basebio (LON:4BB) (£87m | SR11) | H1 revenue -75% to £0.3m due to project delays and market headwinds. “Sales orders” for H1 2026 rose by 210% to £1.2m. Net cash outflow of £8.4m during period, cash of £14.1m at period end, “providing a cash runway into late 2027”. Outlook: visibility over £1.2m of revenue to be recognised within 12 months. | ||
Orosur Mining (LON:OMI) (£68m | SR11) | Full-year net loss of $5.9m with cash of $10.0m at 31 May 26. Cash reduced to $7.4m at today’s date. Post period end, the company raised a further CAD$14m through a placement of warrants at CAD$0.32 per share. | ||
Zephyr Energy (LON:ZPHR) (£62m | SR23) | H1 revenue +71.4% to $10.8m with sales volumes +44% to 984 boepd. H1 gross profit +100% to $6.6m with net profit of $1.9m or 0.09 cents per share. | ||
Character (LON:CCT) (£54m | SR77) | Sales in July/August were “very encouraging” and the company reports a strong finish to FY26. Full-year sales are expected to be “broadly similar” to FY25. Margin improvements seen in H1 were maintained in H2. As a result, FY26 adj pre-tax profit is now expected to be c.20% above market expectations. | AMBER/GREEN ↑ (Roland) Today’s upgrade to full-year profit guidance has dropped through to a 19% increase in FY26 EPS estimates, with a 15% uplift to FY27 forecasts. A generous net cash balance also suggests that a shareholder return might be possible. My only real niggle is that sales growth remains minimal. Management guidance is for a flat result in FY26 (y/e 31 Aug), while broker forecasts are for just 3% sales growth in FY27. Profit upgrades have been driven by improved margins, which is great. But I’d need to see stronger sales growth to take a fully positive view, despite the tempting valuation. | |
Sanderson Design (LON:SDG) (£53m | SR98) | Notice from Ropemaker Nominees Limited, a subsidiary of Liberum Wealth. Resolutions proposed to remove Dame Dianne Thompson and to appoint Mr Stephen Brooke as director. The Board will in due course be publishing a circular unanimously recommending a vote against both resolutions. | ||
1947 Oil & Gas (LON:1947) (£50m | SR n/a) | 1947 is an oil and gas production company focused on acquiring, operating and growing a portfolio of producing assets in the United States. Issued 500 million shares at 10p (i.e. £50m). Of these, 202.5m shares were issued to fund the acquisition of Renaissance, a “Houston-based oil and gas production company with interests in eleven fields located in the shallow-water Gulf of America”. | ||
Christie (LON:CTG) (£47m | SR84) | Revenues up 5.4% to £36.0m. Operating profit £2m (H1 2025: £2.1m) after a non-recurring pension scheme cost of £0.4m. The Board anticipates delivery of a full year performance in line with current market expectations. | ||
Ferro-Alloy Resources (LON:FAR) (£39m | SR5) | Revenue $1.8m, operating loss $2.3m. “The Project continues to make good progress with the advancement of several key workstreams during the first half of the year.” | ||
Amigo Resources (LON:AMGO) (£35m | SR77) | Amigo intends to own 51% of Amigo SPV, that will own the Kamiesberg Project. Amigo to be appointed the manager and operator of the Kamiesberg Project. Cost is $33 million on a working capital adjusted, cash-free and debt-free basis. | ||
Hemogenyx Pharmaceuticals (LON:HEMO) (£32m | SR0) | No revenues, operating loss £6.5m. “The first half of 2026… has delivered what it needed to deliver: a trial cleared to escalate in adults and to open in children, a manufacturing base capable of supporting it, the first binding commercial arrangement for the therapy, and the capital advance [sic] the programme.” | ||
Coiled Therapeutics (LON:COIL) (£32m | SR0) | No revenues, pre-tax loss £3.9m. “The Company's focus for the remainder of 2026 and into 2027 is to generate safety, pharmacokinetic and efficacy data from the new AO-252 formulation and advance enrolment in the planned ovarian and prostate cancer dose-expansion cohorts.” | ||
Checkit (LON:CKT) (£24m | SR34) | Total revenue +3% (£6.3m). Recurring revenue +4% (£6.1m). Adjusted EBITDA £0.3m (H1 last year: £0.9m loss). “The first-half results provide tangible evidence of Checkit’s stronger financial foundations.” FSP: Board would not consider proposals below 30p. Three credible acquirers suggested 22p, 25p and 31-33p. The third one decided not to proceed. | AMBER/RED ↑ (Graham) | |
Prospex Energy (LON:PXEN) (£24m | SR42) | Operating loss £905k. “Our priorities for the remainder of 2026 and into 2027 are to maximise the performance of our producing assets.” Cash £525k. FY25 results included a material uncertainty warning from auditors. | ||
Emmerson (LON:EML) (£20m | SR8) | Operating loss $1.8m. The hearing in the case against Morocco will take place from 17-26 July 2028. | ||
Energypathways (LON:EPP) (£19m | SR9) | Fundraising amount not specified. The funds will be used to progress the MESH project, set to be the UK's largest Long Duration Energy Storage (LDES) project. A retail offer to follow. Voluntary temporary pause in the trading of the Company's shares on AIM. | ||
NAHL (LON:NAH) (£17m | SR79) | Parties have agreed that NAHL would receive an amount of £1.85m in full and final settlement of the dispute. The Board had not accrued for this income in its financial results nor allowed for it in its forecasts for 2026. | ||
Eden Research (LON:EDEN) (£17m | SR16) | Expanded label for Mevalone®, the Company's terpene-based biofungicide, significantly broadens the approved uses of the product in the US. | ||
Block Energy (LON:BLOE) (£14m | SR17) | Revenue $2.9m (H1 last year: $3.4m) operating loss $585k. Cash $2.7m. “...future revenues in at least some scenarios might not cover all operating costs and planned capital expenditures, creating a material uncertainty...” $2m secured loan falls due in August 2027. |
Graham's Section
Tribal (LON:TRB)
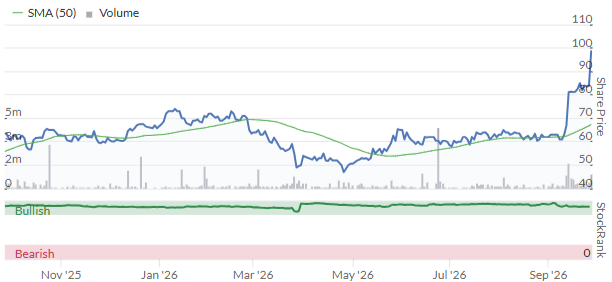
Up 18% at 98.6p (£211m) - Increase in Price for the Recommended Acquisition - Graham - TAKEOVER
It’s a nice bonus for Tribal shareholders today.
Earlier this month, we reported on an “agreed sale” of the company’s operating subsidiaries for £189m.
The buyer is Main Capital, a software-focused PE firm based in the Netherlands
Tribal itself provides Student Information Systems to the education sector (including many different types of institutions: higher education, further education, etc.). We had been moderately positive on it.
The news is as follows: Main Capital is increasing the amount it’s paying to £231m. I make that a 22% increase on the previously agreed price. £231m equates to 105p per share, which is a 66.7% premium to Tribal’s prior share price.
I should highlight what Roland did: that 105p per share is not being paid directly to Tribal shareholders. It’s being paid to Tribal plc. And then it will be up to Tribal to distribute funds to shareholders. They are planning to distribute the funds and liquidate.
Harwood Capital is involved, with a 15.7% stake. Over the past few years, they have proven to be very strong at finding companies where a takeover might be arranged.
In total, there are irrevocable undertakings from 52.7% of shares. This is not a takeover via Scheme of Arrangement, but merely a sale of subsidiaries, and so I think only 50% of votes are required to get it over the line.
Distribution to shareholders: today’s announcement includes the following (emphasis added by me).
The Board, having reviewed and analysed the cash consideration, the cash resources available to the Company and the Company's costs and liabilities and potential costs and liabilities, is highly confident that following Completion of the Proposed Sale, Cancellation and taking into account the expected costs of the MVL, Shareholders will receive Increased Net Cash Proceeds which will total not less than £231,219,773.
This amount is not guaranteed. But if I was holding these shares today, still trading below 99p, I could be tempted to hold on for the full 105p potential payment. The sale is expected to go through in Q4 2026, with the distribution to shareholders happening in two tranches - one in Q1 2027, and one in Q2 2027. So even compared to the current share price, there’s the potential for a decent return over the next 9 months, assuming it all goes through with no problems.
Well done to anyone holding this. It’s only right that a successful software company should achieve a decent premium and a high earnings multiple at takeover time: this new price gives a P/E multiple of c. 22x based on 2026 forecast earnings.
Let’s hope that generous takeover premiums can become a little more common, rather than the c. 25% premiums that we’ve seen so many times in the past!
Checkit (LON:CKT)
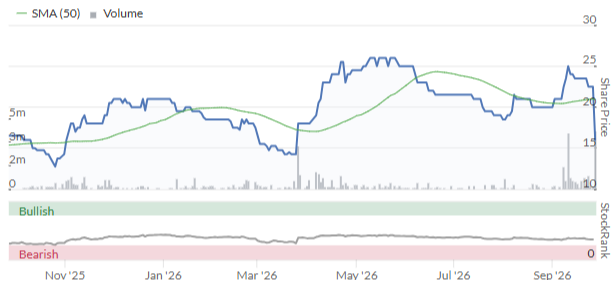
Down 32% at 15.25p (£16m) - Interim Results & Termination of FSP - Graham - AMBER/RED ↑
The termination of the sale process has overshadowed the interim results here.
Back in March, the company said “there is a disparity between the Company's improving performance and its valuation on AIM.”
The share price at the time was 14.25p, with the company saying that its enterprise value was “approximately 1.0x ARR”, which was “materially below levels observed by the Board in certain precedent transactions for businesses with scaled, verticalised subscription platforms.”
Today, they have cancelled the sale process, after receiving three non-binding offers.
One at 22p (they rejected it)
One at 25p (they rejected it)
One at 30p (the buyer walked away, “having concluded that an acquisition of Checkit did not fit closely enough with its existing business.”)
There were other “verbal indications” at various prices, including 40p, but I don’t know if any of those can be taken seriously.
So in the end, nothing happens.
Looking at today’s interim results, the company reports ARR of £12.8m, up 5% year-on-year.
It also reports cash of £3m.
That gives an enterprise value of £13m at the current share price, i.e. the valuation has fallen right back to the level which the company said was materially below its takeover value.
Unfortunately, at its current scale, the business isn’t profitable: adjusted EBITDA is only marginally positive (£0.3m), and there’s a £1.2m operating loss for H1.
Graham’s view
I think a sale at 25p might have been a reasonable course of action for management to take. But value is in the eye of the beholder, and the Checkit board clearly believe that their company is worth 30p+. And so they rejected an offer 75% higher than the prior share price (25p offer vs 14.25p).
Hopefully their strong conviction will turn out to have been justified. It is risky, of course. Checking the cash flow statements, I see that they had a net cash outflow of over £2m in FY26. No dividends were paid. Cash flow was then slightly negative in H1 this year.
They will need to turn their corner to cash generation before too long, or else one of the parties they turned down this year might approach them again, when their position is much weaker.
It’s been a while since I last looked at Checkit: I was RED on it last year. Despite the alleged interest in the company at 25p, I’m inclined to stay RED on it today simply due to the lack of profitability. But that would be a little harsh: the cash burn in H1 was only slightly negative, with the operating loss (£1.2m) mostly down to the amortisation charge (£1m). And it sounds like acquirers were very interested in a 20-25p range. So let’s take a more optimistic stance: AMBER/RED.
Roland's Section
Keller (LON:KLR)
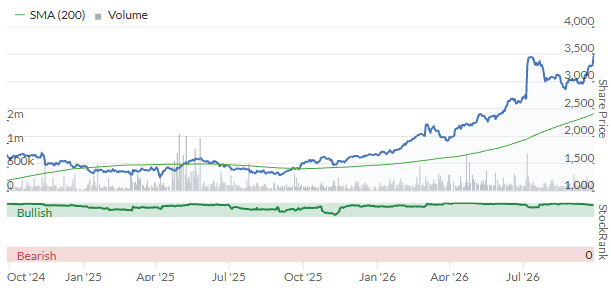
Up 4% at 3,452p (£2.4bn) - Contract variation for I-40 - Roland - AMBER/GREEN =
(At the time of publication, Roland has a long position in KLR)
Today’s update from this geotechnical engineering (groundworks) specialist is short but positive, improving revenue visibility for the next few years.
Contract extensions: Keller has secured a further $650m of work on the I-40 highway reconstruction project in the US.
This takes the total value of work secured on the I-40 project to c.$1bn, of which around 10% has been completed so far.
Including this latest contract variation, Keller expects the work to extend over the next three to four years.
This latest contract amendment increases the value of the group’s order book to around £2.4bn. That’s a 21% increase from the £1.9bn reported at the end of June 2026.
Outlook: due to the multi-year nature of this contract, there is no change to 2026 full year results expectations.
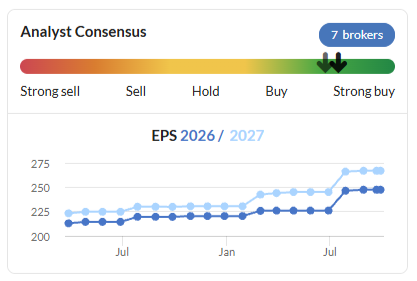
Current consensus forecasts suggest FY26 adjusted EPS of 247.5p, putting Keller on a P/E of c.14x.
Roland’s view
This contract variation should be good news for Keller and its shareholders, providing improved revenue visibility for the next few years.
The only potential concern I’d point out is that this project has now assumed outsized importance for this business. I estimate that c.28% or c.£670m of the company’s order book is now accounted for by the I-40, which is also the company’s largest ever project.
If problems emerge and the profitability of this project falls below expectations for any reason, we could see a big adjustment to profit expectations. We might also speculate about whether the company will be able to replace such a large project within its order book quickly enough to prevent a dip in earnings.
I’d be more concerned about these risks if Keller was a regular construction company. However, Keller is a recognised market leader in a specialist sector, so I am generally inclined to be tolerant of this kind of concentration risk. I think it’s also fair to say that there is no shortage of major infrastructure projects in the US, so if Keller is successful with I-40 it may be in a strong(er) position to win further work.
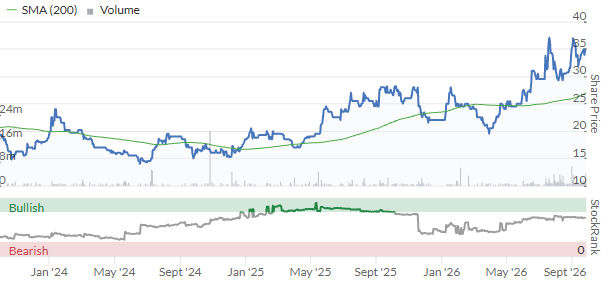
As things stand, Keller is turning into a good example of a company where strong momentum is persisting for longer than might have been expected. I can’t be sure without access to broker forecasts, but I wouldn’t be surprised to see 2027 earnings estimates nudged higher after today, extending a run of upgrades:
The stock has now regained the record highs seen following July’s earnings upgrade, reinforcing the positive price momentum – there are clearly still buyers here:
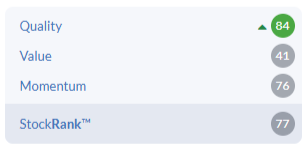
This situation is reflected in Super Stock styling and a strong overall StockRank, albeit with weaker ValueRank:
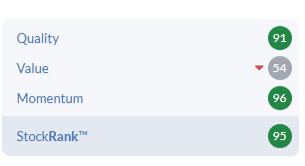
While I’d normally view the stock’s forward P/E of 14 as being up with events, I’m inclined to be more flexible on valuation than I usually would be, given the strong earnings momentum and high returns on capital being achieved at the moment.
For these reasons, I’m going to leave my previous AMBER/GREEN view unchanged today.
Likewise (LON:LIKE)
Up 0.4% at 35p (£128m) - Interim Results - Roland - AMBER =
I flagged up Likewise’s results in The Week Ahead on Friday, commenting that the company is likely to be benefiting from the problems at rival firm Headlam (LON:HEAD).
For those not familiar with the story, Likewise CEO Tony Brewer previously ran Headlam successfully for many years. However, since Brewer’s departure, Headlam has suffered a series of strategic missteps (in my opinion). These culminated with the appointment of administrators at the start of September.
Returning to Likewise, we’ve previously commented on this company’s increasingly demanding valuation and wafer-thin profit margins. Fortunately, today’s results suggest trading momentum is still with the firm, with both an upgrade to full-year profit guidance and a notable improvement in margins.
Let’s take a look.
Half-year results summary
Today’s headline numbers cover the six months to 30 June 2026 and suggest the business is continuing to grow comfortably ahead of inflation and the wider economy:
H1 revenue up 15.4% to £89.9m
Gross margin up 0.8% to 32.1%
Underlying pre-tax profit up 79.5% to £1.32m
Earnings per share of 0.31p (H1 25: 0.09p)
Sales growth continues to gain momentum, too:
Sales increased in Q3 by 29.1% with YTD sales up 20.7%
Trading commentary: Likewise says that recent investment in infrastructure has paid off this year, with a new hub for palletised goods in Leeds providing improved stock availability and limiting the impact of Middle East shipping disruption.
Further operational capacity is being added, with a second cutting shift recruited at Derby and “additional distribution and cutting capacity” added in Wales this year.
Management is now confident of achieving £200m in revenue in 2026. To support further growth, Likewise acquired a new 60k sq ft distribution hub in Corby in August (in the UK’s golden triangle for logistics) and has recently agreed terms for a 47k sq ft hub in Manchester:
Together with the Leeds investment, the Newport extension and increased cutting capacity at other locations, the Corby and Manchester facilities provide substantial additional headroom for the Group's continued expansion as it heads towards its renewed £300 million target.
Profitability & Cash Flow: digging a little further into the company’s financials suggests an improving picture.
H1 operating margin: 2.1% (H1 25: 1.5%)
Trailing 12-month return on capital employed (ROCE): 5.1% (FY25: 4.3%)
While this level of ROCE is likely to be below Likewise’s cost of capital, the numbers are moving in the right direction and may improve further as volumes continue to grow.
Cash generation is also relatively good, with operating cash flow before working capital movements up by 22% to £5.1m in H1. This additional cash was swallowed up by a £1m working capital outflow to support higher inventories and sales growth, but the underlying picture still looks fine to me.
Net debt & £32.5m fundraise: although today’s half-year balance sheet suggests a net debt position of around £12m (excluding lease liabilities), the picture has changed since the 30th of June.
Likewise raised £32.5m through a share placing and retail offer in late July, strengthening the balance sheet and providing improved headroom to support growth investments.
Updated forecasts from house broker Zeus today suggest a year-end net debt position of £6.6m in 2026, which looks manageable to me.
Outlook
Reflecting the strength of trading in the first half and the continued acceleration in the third quarter, the Board now expects underlying profit before tax for the year ending 31 December 2026 to be materially ahead of current market expectations at not less than £5.0 million (FY25: £3.1 million).
Turning to today’s broker note from Zeus, I can see that FY26 adjusted pre-tax profit was previously expected to be £4.0m – so today’s upgrade is a 25% increase, fully justifying the “materially ahead” tag.
Investors expecting a corresponding increase to earnings per share forecasts will be disappointed, though. Likewise issued c.100m new shares in July’s equity raise, increasing the share count by c.40%.
The resulting dilution means that Zeus’s updated FY26 EPS estimates are only “broadly flat” (i.e. slightly lower), while FY27 estimates suggest the pace of growth could ease next year:
FY26E adj EPS: 1.3p (-5.1% vs 1.3p previously)
FY27E adj EPS: 1.4p (+7.7% vs FY26E)
Roland’s view
I think Likewise was wise to raise fresh equity while there's strong investor appetite for the company’s stock.
The growth story here appears to be on track and it’s worth remembering that CEO Tony Brewer has a 7.7% holding, so his interests are well-aligned with those of shareholders.
Scaling up the business appears to be delivering positive operating leverage (improved margins) and presumably reflects continued gains in market share.
Despite this, the immediate benefit to shareholders from today’s upgrade may be limited, due to the dilution involved and the shares already changing hands for 28x 2026 forecast earnings.
While I remain positive about the medium-term growth story, I would argue that at least some of this growth is already priced in.
The StockRanks reflect this view, with a high MomentumRank offset by a low value score:
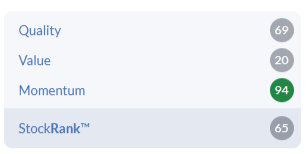
Likewise retains its High Flyer styling, but the limited share price gain today reflects the significant dilution to earnings from the recent fundraise. I think it’s fair for us to retain our neutral view today, especially given the slower rate of EPS growth forecast for 2027.
Character (LON:CCT)
Up 3% at 319p (£55m) - Trading Update - Roland - AMBER/GREEN ↑
Today’s full-year trading update from this toy manufacturing includes a 20% upgrade to full-year profit guidance.
Let’s take a look.
FY26 trading update
Character suffered weaker sales during the first half of the year, which I thought could be a risk to full-year forecasts. However, it looks like I should have paid more heed to May’s ahead of expectations outlook guidance.
In today’s full-year update for the year ended 31 August, management says that sales in July and August (i.e. retailers ordering for Christmas) were “very encouraging” and have “reversed the drop in sales” reported in H1.
As a result, full-year sales are expected to “be broadly similar” to the £100.5m achieved in FY25.
While this doesn’t sound all that impressive, the kicker here is that Character was able to maintain the improved gross profit margin reported in H1 during the second half of the year. This has driven today’s material upgrade to full-year profit guidance:
As a result, the Board now expects the Group's profit before tax and highlighted items for FY26 to exceed current market expectations by approximately 20%.
Revised forecasts: with thanks to Panmure Liberum, I can see that forecasts for both 2026 and 2027 have been upgraded quite significantly today:
FY26E adj EPS: 26.3p (+19% vs 22.1p previously)
FY27E adj EPS: 31.9p (+15% vs 27.6p previously)
Outlook
Despite the current economic challenges, overall trading remains positive as we lead up to the Christmas 2026 season. The Group's product ranges are selling well, and the higher margin is being maintained. With a strong product portfolio, backed by a robust balance sheet and a healthy cash position, the Board looks to the year ahead with optimism.
Cash return? The company also reminds shareholders today that it recently completed the sale of a warehouse in Lancashire for £9.8m. This deal “significantly increased” the group’s cash reserves, which currently stand at over £20m.
This has opened the door to a possible one-off shareholder return:
The Board is assessing the Company's capital requirements and the potential to return any excess cash to shareholders.
Roland’s view
Character’s high volume, low margin business model means that small improvements to gross margins can drop through to significant improvements in the bottom line.
We appear to be seeing that this year. Following today’s upgrade, FY26 EPS forecasts (y/e 31 Aug) have more than doubled in four months:
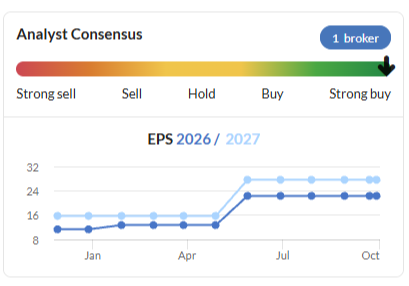
Today’s forecasts put Character shares on a FY26 P/E of 12, falling to a P/E of 10 in FY27.
Although I’m not sure whether we’re likely to see any more upgrades, I don’t think the shares look too expensive for this business.
The main concern I would highlight is that revenue growth remains sluggish, at best. FY26 sales are expected to be broadly flat year-on-year, at £100m.
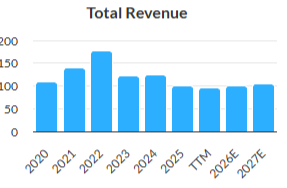
Panmure’s latest estimates for FY27 only show revenue rising by 3% to £103m. The remaining uplift to profits is coming from higher operating margins.
While higher margins are good news, there’s usually a finite limit to what’s possible. When this is reached, earnings could level out if sales growth doesn’t improve.
I took a neutral view on Character in May. With hindsight that looks too cautious, so I’m moving our view to AMBER/GREEN today, in line with the StockRanks
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

38 comments
Just noticed ME International (LON:MEGP) waking up can't see any rns or broker upgrade just wondered if anyone had heard anything ?
ME International (LON:MEGP) well there has been nothing officially anounced since the interims update and stocky hasnt done any updates.
they basicallyu said they were siomply on track at 13th July - so that seems clear message that then there was zero signs of any upgrades.
They did say
Nonetheless, the Board is taking a cautious view of the full-year outlook.
one could read that as being good news that they are confident their forecasts are cautious so hopefuly if anything they might beat at year end ?
or one could perhaps read it as being that with such big variability in year they are simply cautious as to what might happen.
i go more slightly with the first than the last - perhaps though one might wait to see that the trend downwards in expectations has completely finished - i have been caught out by a couple of companies where there were updates that things had stabilised for a while - only to find out it get tougher rather than easier.
not sure ref bottom line money making if the washing stuff increases will more than offsett then photo decreases going forwad - per interims the washing stuff made 54% of EBITDA - so it all seems to be trending in right direction.
ref next year they are expecting quite large jump in bottom line net profit - i would be minded to think we need to see some delivery ref next update for me to be confident ref next year.
Overall though if they are still on track - as they head into 2027 in november i kinda think that the outlook will look much more favourable if the profits are expect to move forwards rather than backwards.
Likewise (LON:LIKE)
I do not hold at the moment, but upscaling capacity to realise enhanced revenue sales target of £300M+ and the further improvement in Q3 with sales increasing 29.1%, this looks to be a clear GREEN for me.
All the best
Agree they seem to have an opportunity to take significant market share from the demise of Headlam. If they can manage this then it will look very cheap. I wouldn't value with reference to next year's earnings as this misses the bigger picture.
It's just been announced that XP Factory (LON:XPF) has sold its 24 owner operated and 5 franchiesd Boom Battle Bars back to the chap to sold it to them, who is now fronting the Frasers backed We do Play . Richard Breeze sold Boom Battle Bars to XP Factory (LON:XPF) for £17.4m in Nov '21 (not sure how many there were then), and the price now is £5m up front and a possible further £6m contingent on sales and ebitda earnouts. The book value was £21.3m.
Why would XP Factory (LON:XPF) sell it, having grown it, at such a thumping loss? Clearly it overpaid for it in the first place, but this smacks of distress surely? Even if the full earn outs are paid, that's just a few hundred grand for each owner operated outlet (well below cost of fit out), assumning some value is attributed to the franchise business. It looks pretty disastrous.
Propel also reports that competitive socialising LFL's are down 9% in 2026 with similar expected in 2027.
The competive socialising "thing" is well and truly deflating, and it was always going to.
Roland's write up on Keller (LON:KLR) this morning prompted some reflection as it demonstrates that along with Stockopedia data a crystal ball is essential to successful stock selection! Historically Keller (LON:KLR) has had a strong stock rank which combined with its strong market position suggested a good opportunity hence my buy at c £10 in July 2018 - unfortunately this was a false signal and the share went nowhere for 4 1/2 years before I lost patience and sold out at less that £8. Without that crystal ball predicting that they would be a major beneficiary from the data centre construction frenzy this realised a 20% loss rather than a long term (8 years+) 'buy and hold' strategy that would have resulted in a multibagger!
Graham, I appreciate I am going slightly off-piste from today's main stories, but given the data security breaches we are continually reading about, surely the somewhat sleepy tech security companies in the UK, namely; NCC, Corero and Bytes ( the 3 I've so far researched this morning as looking reasonable), are worth some focus? Not today or this week, obviously, but I thought I would flag it, as nobody is commenting on that sector and it looks ripe for potential re-rating.
Re Help to Buy
I agree this will work if its desired intention is to act as a sop to make the Socialist housing target look less unobtainable! Seriously, I agree with RDH that this will restart the market. Having said this It is not a good look that we have an industry that due to building costs and inflation etc has to charge prices that make its product unobtainable for its target market. The suggestion that without this kind of life support the industry will not be able to achieve acceptable turnover is hardly encouraging. Of course yet another sticking plaster for housebuilders is now with us but what is the level of pain when this is withdrawn?
Stockopedia stock report for Spectra Systems (LON:SPSY) says it's their half-year results today, which matches last year's date. Is there any news elsewhere?
I was also expecting news. It must be an estimated date.
Spectra Systems (LON:SPSY)
unless there has been a definitive date for company results Stockopedia just has a guess at the release date of results, based on past dates. Usually Spectra Systems RNS's the date with a NOR a couple of weeks beforehand.
HTH
thanks. same for Water Intelligence (LON:WATR)
It would be better to leave the upcoming dates blank rather than guess. Makes you think its confirmed.
Graham
Only VTY has been tagged from the Agenda this morning
That's well spotted FREng, I was a little hasty in my rush to manage the tags today.
Land Securities (LON:LAND) The sale site has 245,000 sq ft not 245.
re Help to Buy - I calm my instinct to dismiss it because it has worked quite well before. Helping first time buyers to borrow attractively will help those who want to get on the ladder but it doesn't make it a good decision. Rising bond yields are not positive and potentially raise the interest hurdle such a scheme has to clear in year 5 onwards. Obviously injecting demand at the bottom does help the whole industry since it is positive for all the housing chain and so does reduce some of the current pressure. Ignoring the moral side of things - the implication for stocks is quite significant because it has been a sector under pressure all year and therefore under owned ....so I am resisting the temptation to dump my Breedon (LON:BREE) because the building season to April next year is likely to be better. Even after today's rises none of these stocks are expensive. For anyone involved it has to be welcome news but I don't plan to stay invested forever .... and likely reduce subject to price progression from here. Just not today.
I can't help but feel the actual policy will not match the press release. But the surprise recent positive review of last Conservative scheme came at enormous public subsidy per dwelling. Where is the pump priming capacity now?
came at enormous public subsidy per dwelling. Where is the pump priming capacity now?
well thats the reality - i think Vistrys numbers suggested that it was like 100k per house they were getting as help per their update last week - thats anything but cheap solution if that is the case. I do concede down south well mass affordable home is a pipe dream without the government simply taking greenbelt and using that or simply taking a huge elemnt of cost on the chin.
Obviously injecting demand at the bottom does help the whole industry
its obviously good for the industry
my issue is that if we have boat load of people who "instantly find a deposit" i would guess that making it uber easy to get your hands on one is simply going to push up the prices that people can pay at that level and next level up? isa that helping if soemone has to pay 20k more but needs 20k les deposit.
imho the only real solutions to the problems are increasing new housing stock at fastrer rate than population is increasing - and bringing as much "affordable housing" on tap as we can afford.
imho it kinda makes sense to give priopity where there is severe shortages to long term resident of that area - eg if family have lived in village for like 2-3 generations - then local younsters who have always lived their should be right at the top of the pile ref afforbable housing.
all i can think with this news is that all other things being equal - people can now aford to pay 30k extra for house that hadnt saved up any meaningful deposit - for soemone who has been saving and is almost ready to buy and has been patiently waiting - well they are gonna find competition for something half decent is so much harder .
Note there is any number of real ways we could help by prioritising those that have been patient and can prove they are ready to own their own home - not convinced that complete free for all helps those that have waited the longest with genuine need.
Personally i would be changing rules compulsarily purchasing unused land and greenbelt land - offer modest compenation - and then just get a huge wad of basic cheap new homes and flats built.
Its a government sponsored ponzi scheme.
It passes a long term liability to young people
It supports house prices - transferring cash to the older asset owners when they trade down , and supports housebuilders by supporting asset prices and increasing turnover..
There is no physical law that says house prices must rise.
I have been predicting a house price crash since 2008 - and may be right one day
Unite (LON:UTG) Interesting that Saba has increased their stake in the company from tiny to about 2.5%.
Like others on here somewhat surprised by the significant rally in Housebuilders, I expected rises of 5% rather than 3 times that, I said before the industry needed a Government scheme so now we have one but only for 1st time buyers and with the caveat that the industry is going to pick up part of the bill. On top the industry levy for new building applies from 1st October which means more squeezes on margins. It seems to me this is net positive for the likes of Gleeson and Vistry but for those building 3 and 4 bedroom homes which is industry staple unclear how these will suddenly start being shifted in volume. One presumes Mr Market thinks this scheme unjams the whole property market..... I am on the side of the skeptics here
The building levy is more significant the further south you travel so of much less significance for those building in the North.
Get out of jail free card for Crest Nic me thinks as its bankers may view lending more favourable!!!
IMO putting the thumbs up at the top is a mistake. I read the article then decide if I like it.
It feels like international government borrowing rates are very much news focus now...since yields on 10Y et al are all rising. On my spread sheet the US was out in front with an 11bp tick up but UK closely behind 7bp and Germany France Ital etc all a little lower. Im not too sure there really is a magic number where the rises begin to tell but a weak bond auction won't be great news. My reading and listening suggests a little higher than you might expect ... .north of 6%... and so it does seem a little early to panic re austerity type measures holding back economies. Unless someone like Bessent has a magic trick it either ends with fiscal cuts or some accounting creativity. I would guess someone has a go at persuading the markets to ignore a class of liabilities and we will see if this provides any relief.
For now - equities are winning the race against Bonds that continue to slide unless you hold very short dated stock. I guess lowish inflation is not the worst outcome for equities but the realisation there is no quick fix is increasingly negative for bonds and the 60:40 portfolio. It's not great news for property but this is overshadowed by government policy this morning.
my memory in these circs is higher bond yields and rates sometimes result in something “breaking” and this triggers a general sell off or worse, a systemic collapse. I’m braced for either with a 50% cash weighting.
Microcap ITIM (LON:ITIM) saw a StockRank jump over the weekend, +58 to 74, driven by a Quality Rank jump of +43 to 89, after its interims returned it to profit with strong operating cash flow. Whilst it hasn't reached a StockRank guide > 80, the Quality jump is the "right type".
However, itim ARR slipped after a customer went bust, so share price progress is dependent on converting the current sales pipeline, and the stock is illiquid. Not for the faint-hearted!
I think Kooth (LON:KOO) just met the criteria. It’s hard to get stock as I guess the Stocko community are piling in!
Do you hold?
Yes I have a small holding.
House builders shares on fire!
I couldn’t believe the 10 % plus rise on persimmon and some other builders at the opening today.
An irrational behaviour to the government announcement of 2.5% deposit for first time buyers?
Lots of short covering.
I am a seller!
Now up over 15%.
Not irrational at all. The last Help to Buy scheme ran for 10 years and generated around c50% of new build sales. Yes... half...!
Likewise (LON:LIKE) from Tony Brewer “The Group has performed strongly throughout the first half and then accelerated into the summer and early Autumn. As a result, we now expect to deliver results for the full year materially ahead of market expectations.
Tullow Oil (LON:TLW) appreciate a view on HY results