Daily Stock Market Report (Mon 5th October 2026) - ENSI, QTX, GFD

Good morning! The main news story overnight is the election in Brazil whose relevance to investors here doesn’t seem particularly compelling to me. So instead l’d like to revisit Friday’s IG group (LON:IGG) story with a short follow-up (disclosure: I’m long IGG).
After warning of lower-than-expected revenue retention, IG’s share price closed 23% lower on Friday evening. There was little meaningful recovery from the low.
CMC Markets (LON:CMCX) was affected by the news despite the warning being related to IG’s profitability, not to overall customer numbers or activity. CMC was down 10% at its worst before recovering to close down 4%.
Plus500 (LON:PLUS) was down 14% at its worst before recovering to close down 5%.
At CMC, both Lord Cruddas and his Head of Global Strategic Partnerships revealed on Friday afternoon that they had bought shares in CMC that day.
At Plus500, they announced on Friday morning that they continued to trade “in-line with current market expectations for FY 2026”. In what sounds very much like a reference to IG’s troubles, they said that their “proprietary risk management framework has been through various market cycles over the years and has demonstrated an established and robust track record over time”.
Unfortunately for me, it seems that I was right: IG’s profit warning was very much an own goal, and its rivals are likely unaffected.
Overnight market movements:
The FTSE is up 0.5% at 10,505
S&P 500 is flat at 7,720
Brent crude (December) is down 0.9% at $101.25/bbl
Gold is up 0.2% at $4,150/oz
Bitcoin is up 0.2% at $86,000
AO World (LON:AO.) stock pitch: we published a Stock Pitch on Friday for AO World, by Dr James Fox.
James argues that AO is:
...a high-quality, cash-generative retailer on a modest multiple. It has net cash (at end of year), a 21% return on capital, a credible path from 4% to 5% margins, and is returning £20 million this year to shareholders while it waits for the market to notice.
The Agenda is complete. Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
National Grid (LON:NG.). (£58bn | SR63) | Regulated businesses have performed in line with expectations, but National Grid Ventures & Other had a strong H1. As a result, FY27 EPS is now expected to be slightly above previous growth guidance of 13-15%. | ||
BT (LON:BT.A).A (£20bn | SR50) | BT has acquired TalkTalk and PlatformX out of administration. The total cash impact in FY27 is c.£400m and BT will protect services for TalkTalk’s c.2.5m retail and wholesale customers. TalkTalk had revenue of c.£1.2bn over the last 12 months & was loss making. Excluding this transaction, BT leaves FY27 guidance unchanged. | ||
Ithaca Energy (LON:ITH) (£4.6bn | SR92) | Acquired assets from Suncor (offshore east coast Canada) for $860m + up to $250m contingent consideration. They are expected to provide average 2P production of c.30 kboe/d from 2027-31. The deal adds 2P reserves of 103 mmboe at c.US$8/boe. Expected to be immediately cash flow and dividend accretive. | ||
Hammerson (LON:HMSO) (£1.96bn | SR54) | The new CFO joins from AEW Capital Management (a US firm) where she is currently Global Securities Chief Investment Officer. She’s expected to take up the role no later than 1 January 2027, subject to visa approval. | ||
Sirius Real Estate (LON:SRE) (£1.38bn | SR61) | H1 rent roll growth of 11.3% year-on-year, with LFL rent roll +5.1%. Acquisitive activity was focused on Germany, where Siriue deployed c.€150m into asset acquisitions at gross yield of >8%, with an emphasis on defence-related occupiers. | ||
Galliford Try Holdings (LON:GFRD) (£715m | SR96) | Appointed to the latest iteration of the £3.0 billion Constructing West Midlands Framework. This includes public sector buildings including education, health, housing and leisure. Galliford has been selected in the Major Works lot for projects worth >£1.0bn. | AMBER/GREEN = (Graham) I suspect it would be more interesting (and negative) news if the company had not been appointed to it. Getting appointed to it, on the other hand, is business as usual. Galliford has been involved with CWM since at least 2020 and I think it was probably involved with it before then, too. After reviewing the company's recent earnings forecasts and valuation, I’m inclined to leave our AMBER/GREEN unchanged today, which may be a little harsh but reflects my view that this sector ought to trade cheaply, even for its most successful companies. | |
Griffin Mining (LON:GFM) (£537m | SR66) | Longserving FD Roger Goodwin is standing down and will be replaced by Asha Santchurn as CFO of Griffin and Griffin Group. Goodwin will remain a director of the company and Company Secretary. | ||
MJ GLEESON (LON:GLE) (£168m | SR35) | CFO Stefan Allanson is stepping down after 11 years. He will be replaced by Andrew Kirkman, who was recently CFO at CLS Holdings. | ||
Aptitude Software (LON:APTD) (£141m | SR35) | Contract renewals of Aptitude Accounting Hub with two of the largest banking groups in the UK and Ireland, for a combined total contract value of £6.5m. | TAKEOVER | |
Quartix Technologies (LON:QTX) (£109m | SR67) | Q3 ARR +£0.9m to £39.7m with trailing 12-month ARR +11%. Outlook: full year revenue to be in line with expectations, with adj pre-tax profit “modestly ahead” of current expectations due to cost savings. (Consensus is for revenue and adj EBIT of £40.3m and £10.1m, respectively.) | AMBER/GREEN = (Roland) This looks like a solid update to me, with good progress on revenue growth, evidence of pricing power and another broker upgrade. While I can see some risks to the medium-term growth thesis here, on balance I think Quartix probably offers value at current levels. I’m quite comfortable maintaining our broadly-positive view. | |
EnSilica (LON:ENSI) (£99m | SR40) | FY May 2026. Revenue +53%, EBITDA increases from breakeven to £5.9m. PBT £2.3m (2025: £3.5m loss). Cash £7.6m. “We now have five ASICs in volume production generating recurring revenue, with a further fourteen chip programmes in design which we expect to convert into long-term supply revenues over the coming years… Ensilica is well positioned to sustain this momentum into FY27 and beyond.” | AMBER/RED ↑ (Roland) Progress last year was positive and it looks like Ensilica’s plan to build a foundation of recurring revenue may be starting to bear fruit. At the same time, cash flow remained negative despite improved profits and today’s outlook guidance is only in line. Closer inspection of broker forecasts reveals that profits are expected to fall this year. On top of this, shareholders need to factor in a hefty dose of dilution as a result of this year’s fundraising, which was needed to reduce debt. I can see the potential for this business to become much more valuable over the medium term, but a FY28E P/E of 50+ and the possibility of continuing cash burn mean I’m staying cautious today. | |
Hercules (LON:HERC) (£28m | SR41) | During Q4 of FY September 2026, has been awarded £5m of new contracts to deliver Civils Projects work for its clients in the UK water sector. The majority are expected to be completed in the next six months. | GN note: no reference to any impact on expectations. | |
Neo Energy Metals (LON:NEO) (£22m | SR24) | “Q3 was another busy period for Neo Energy with a number of important corporate developments, including welcoming Elmarié Maritz as our new CFO and progressing the necessary activities to acquire the mining license at both New Beisa and Henkries.” | ||
Kelso group (LON:KLSO) (£19m | SR49) | Bought an additional 100,000 shares in Saga following Saga’s interim results on 30th September. “Saga is the third Kelso investment to double in value during 2026, alongside Filtronic plc and The Works plc. Kelso believes in running its winners which is why we bought more shares in Saga following these results.” | ||
Team (LON:TEAM) (£18m | SR26) | Buying Hedley & Company Stockbrokers for £3m. Hedley has £383m of assets under control, revenue £2.1m, PBT £0.6m. Price: £3m (half upfront, half deferred, with a mixture of cash and shares). Additional contingent consideration of up to £2m. |
Graham's Section
Galliford Try Holdings (LON:GFRD)
Down 2% at 697p (£703m) - Contract - Graham - AMBER/GREEN =
The market has shrugged its shoulders at this:
Galliford Try, a leading UK construction group, announces that it has been appointed to the latest iteration of the £3.0 billion Constructing West Midlands Framework.
The framework covers public sector buildings for local authorities across sectors including education, housing, health, and leisure. Galliford Try has been selected in the Major Works lot for projects worth in excess of £10 million.
For context, Galliford’s forecast revenues this year (FYJune 2027) are over £2 billion.
So how much will Galliford earn from this framework, and how material is it? More digging would be needed - or perhaps it’s too soon to say for sure.
When it comes to the Constructing West Midlands framework as a whole, I suspect it would be more interesting (and negative) news if the company had not been appointed to it. Getting appointed to it, on the other hand, is business as usual. Galliford has been involved with CWM since at least 2020 and I think it was probably involved with it before then, too.
For more background, here’s the CWM website although I think its list of partners may now be out of date.
The government’s official tendering website has a more complete list of 36 suppliers, published last month, and confirms that Galliford are among the six firms providing works whose value is generally over £10m.
Graham’s view
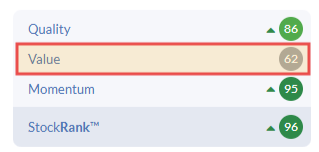
We’ve been moderately positive on GFRD: it’s a Super Stock which raised expectations earlier this year.
It's excellent StockRanks are shown below, although I agree that Value is not too obvious at a PER of 14.5x, given the sector:
Earnings forecasts have held firm, with FY June 27 rising recently:
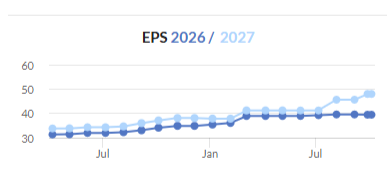
Indeed, checking Panmure Liberum’s note published a few weeks ago (in the aftermath of full-year results), I see that they increased their FY27 adjusted PBT estimate from £63m to £66m.
And the upgrade had something in common with what Roland said all the way back in January: that the upgrade was driven by a slightly higher profit margin, not by an increase in the revenue forecast. Panmure slightly trimmed their revenue forecasts for FY27, FY28 and FY29.
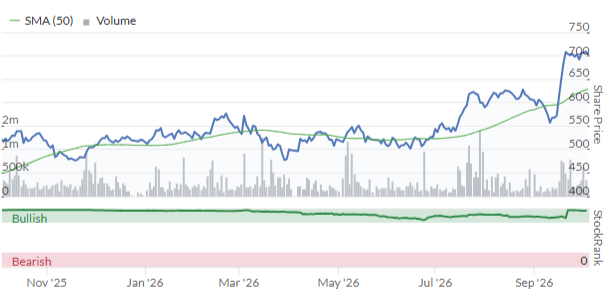
I’m inclined to leave our AMBER/GREEN unchanged today, which may be a little harsh but reflects my view that this sector ought to trade cheaply, even for its most successful companies.
Roland's Section
EnSilica (LON:ENSI)
Up 12% at 83p (£106m) - Final Results - Roland - AMBER/RED ↑
We’ve maintained a negative view on this fabless semiconductor stock this year (Jan & Feb) to reflect concerns around debt, weak profitability and declining earnings forecasts.
Today’s results cover the year ended 31 May 2026. They show a big rise in revenue and reveal that the company ended the year with a modest net cash position, following an equity placing in March. Ensilica has since raised cash again in July, sensibly capitalising on seemingly strong demand for its stock.
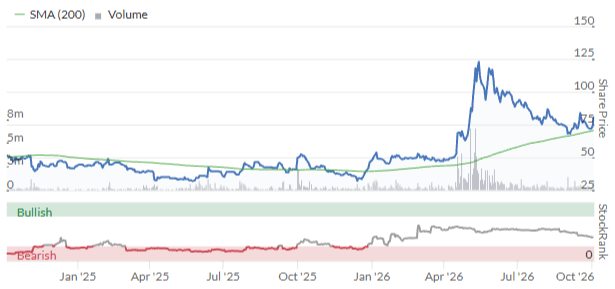
Can I justify a more positive view following today’s results? Let’s take a look.
Full-year results summary
Last year’s headline revenue growth looks extremely impressive and Ensilica returned to profitability last year. However, gross margins fell and the business continued to burn through cash, albeit at a reduced rate.
Revenue up 53% to £27.8m
Gross profit up 31.5% to £9.6m
Gross margin down 5% to 35%
Pre-tax profit of £2.3m (FY25: loss of £3.5m)
Earnings per share of 1.23p (FY25: loss of 3.26p)
Free cash outflow of £2.9m (FY25: £5.7m)
Revenue: I think it’s worth understanding the big increase in revenue. Ensilica’s business model involves charging customers for non-recurring engineering work (design and customisation) and then securing supply or royalty revenues from chips that reach production:
This embeds EnSilica in the customer's product for its entire lifetime, typically seven to ten years and longer in automotive and industrial applications, and converts one-off engineering income into a compounding stream of silicon supply revenue.
Last year’s 53% increase in total revenue was largely driven by non-recurring engineering work, or NRE as the company describes it.
NRE revenue doubled last year, while chip supply revenues rose by a more modest 16% to £6.7m. The company says that chip supply revenue growth was held back by a cyber attack that affected “an automotive customer’s supply chain”.
Management makes the point that this is a slow-burn model that has the potential to deliver much higher recurring revenue in the future:
5 chips in supply, “shipping in volume today”
14 chips in design, “future supply expected”
4-5 new contracts a year, “design-and-supply targeted”
This illustrative chart is provided to show a potential route to Ensilica’s target of c.£100m revenue (note: this is not a company forecast):
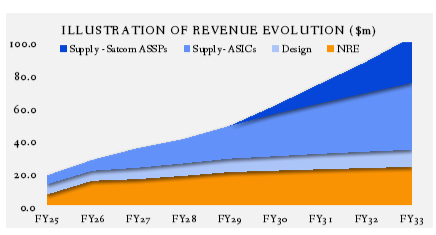
Source: Ensilica FY26 results
According to CEO Ian Lankshear, last year was a turning point for this business model:
FY26 is the year that model began to pay. Five ASICs are now in volume supply, our supply-only proposition has matured into a repeatable offering, and supply revenue is set to take an increasing share of the mix as each programme moves into volume production. Every additional programme that reaches production adds wafer volume, margin and operational leverage without a proportionate increase in cost.
Profit vs cash flow: Ensilica’s improved profitability wasn’t reflected by positive cash generation last year. The main reason for this is that the company capitalises much of its R&D expenditure on to the balance sheet as intangible assets.
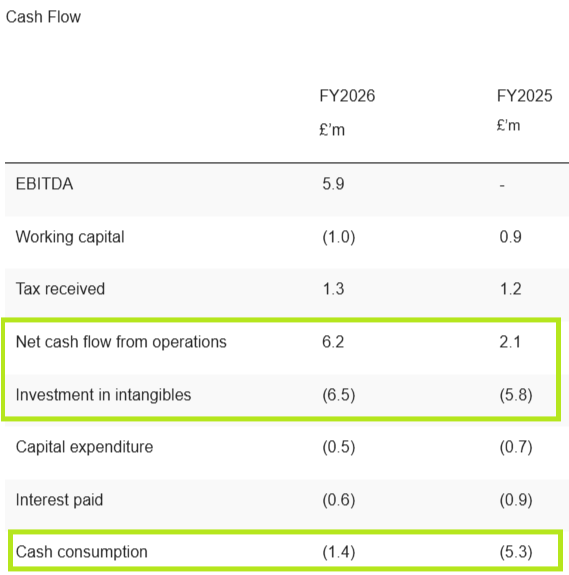
£6.5m of R&D costs were capitalised onto the balance sheet last year, but only £2.0m were amortised. This is a completely legitimate approach and this spending may well deliver increased revenue in the future. But the upshot for now is that Ensilica continued to burn cash last year, despite reporting improved profits.
When R&D expenses are largely salary costs, as I would guess is true here, my preference is for such costs to be fully expensed as incurred. This can push profits further into the future, but it usually means that when profits are achieved, they will also be converted into free cash flow. I consider these to be higher quality profits.
Trading commentary: the automotive sector is the company’s longest-established market, but Ensilica is targeting growth in the growing market for satellite terminals (i.e. end user equipment), which it sees as a potential high volume market.
Trading highlights from the last year suggest steady progress:
$75m automotive contract win with a German tier-one supplier, “our largest automotive win to date”.
Two contracts with a leading European satellite operator to develop two chips for its next-generation satellite network, potentially worth over $50m from 2030 onwards.
Two tape outs completed in FY26, three tape outs completed in FY27 and a further two expected to complete later in FY27 (a tape out is when a finished chip design is sent to the foundry for production).
FY27 order book: more than 80% of expected FY27 revenue is already visible from “existing contracts, supply agreements and customer orders”.
Balance sheet & fundraising: Ensilica continued to burn cash last year, but the company’s previously indebted balance sheet has been strengthened with not one but two equity raises:
March 2026: raised £10.0m at 47p per share
July 2026: raised £14.9m at 91p per share
At the year-end of 31 May 2026, this left the company with a small net cash position of £0.7m.
No comment is provided in today’s results about the current position. However, given that Ensilica raised c.£15m in July, I think it’s fair to assume we can stop worrying about the company’s balance sheet for the time being.
The flipside of this is that shareholders will have to accept some dilution to expected earnings.
Outlook
Today’s FY27 guidance is in line with expectations:
We are therefore pleased to re-confirm market guidance of £32 million to £34 million in revenues and EBITDA of £5.5 million to £6.5 million for the year ending 31 May 2027.
The EBITDA range quoted by the company is fairly broad and neatly avoids the question of whether profits are expected to increase this year.
Fortunately we have access to broker forecasts that provide more clarity and suggest profits will fall in FY27.
With thanks to Allenby and Panmure Liberum for publishing on Research Tree today, I can see the following estimates:
Allenby - FY27E adj EBIT: £2.6m (FY26: £3.0m)
Panmure Liberum - FY27E adj EBIT: £2.5m (FY26: £2.9m)
From what I can see, it looks like growth in Ensilica’s cost base is expected to outpace revenue growth next year, before profits return to growth in FY28.
Investors reviewing the stock also need to consider the dilution that’s resulted from recent share issues.
Earnings per share estimates have been cut significant to reflect dilution from July’s equity raise:
FY27E adj EPS: 1.0p (previous consensus: 1.83p)
FY28E adj EPS: 1.6p
FY29E adj EPS: 3.3p
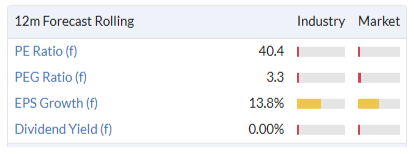
This recent dilution is not yet reflected in the consensus estimates on the StockReport, so it’s likely to have a big impact on Ensilica’s headline valuation metrics.
With the shares currently trading at c.80p, Ensilica’s forecast P/E rises to 80x for FY27E and 50x for FY28E. Both figures are well above previous levels:
Roland’s view
These results show a return to profitability and highlight recent repairs to the balance sheet. It’s clear to me that our negative RED view is no longer justified. The company’s decision to raise a good chunk of equity when the share price peaked in the summer looks sensible to me.
The valuation is a potential concern, as it looks like shareholders may need to wait until 2028/29 before profits catch up with the valuation.
The group’s profitability also remains pretty average – my sums suggest a return on capital employed of 8.3% last year, with an operating margin of 11%.
The caveat to all of this is that I can see the potential for this to become a much more profitable and valuable business in the future. It seems quite possible to me that the company’s slow build of recurring chip supply revenue could support a marked increase in revenue and margins over time.
I’m also encouraged by the ownership structure – CEO Ian Lankshear is that company’s second-largest shareholder, at 11.95%.
Our algorithms styled EnSilica as a High Flyer prior to today’s results, but the StockRank warned of the risks of a demanding valuation:
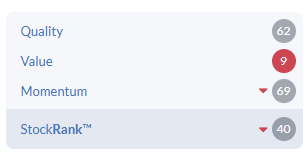
I was originally minded to move up two notches to a neutral (AMBER) view today, but I’ve decided to err on the side of caution and go with AMBER/RED. The main reason for this decision is that a closer inspection of broker forecasts today suggest to me that there’s a good chance Ensilica will continue to consume cash over the next couple of years.
While I don’t expect the company to need to raise funds again for the foreseeable future, I think there’s a fundamental difference in risk between a growth business that’s self-funding from free cash flow and one which is not.
Quartix Technologies (LON:QTX)
Up 4% at 235p (£112m) - Trading Statement - Roland - AMBER/GREEN =
Today’s third-quarter update from this vehicle telematics specialist includes a modest upgrade to profit guidance and shows continued recurring revenue growth.
For a more in-depth review of this business, Mark recently covered Quartix in a Stock Pitch.
Key points:
Annualised Recurring Revenue (ARR) has risen by 11% to £39.7m over the last 12 months
Q3 ARR growth was £0.9m
ARR growth for the nine months to 30 Sept was £3.0m
Net revenue retention – effectively a measure of customer churn – remained stable at 97.3%, albeit below the 100%+ I’d ideally like to see. Management notes that improving NRR is “a priority across all territories”.
Quartix uses ARR as its primary growth metric, but customer acquisition is also important. The group’s customer base has continued to expand this year:
Customer base +6% to 33,873 over the last 12 months
Total subscriptions up 7% to 347,702 over the same period.
I’m encouraged to see ARR growth that’s greater than customer growth. This suggests to me that Quartix has been able to increase pricing or upsell newer customers to more expensive offerings over the last year.
This is important, in my view, because price erosion has historically been a challenge for this business.
Geographic split - US drag? Quartix’s efforts to expand in the US are bold and could potentially open up a large market. But this remains the weak point of the group’s performance, with ARR flat and subscription numbers down 4% over the last 12 months.
In contrast, France, Italy, Spain and Germany have all seen double-digit ARR growth over the last year. Perhaps the company should abandon the US and focus on the UK and Europe?
Outlook
Today’s full-year guidance is confident and nudges profit expectations higher:
Full-year revenue is expected to be in line with expectations
Adjusted pre-tax profit is now expected to be “modestly ahead of current market expectations”
The increase in profit is due to £0.2m of cost savings earlier this year that will not be reinvested until 2027. So we might argue it’s a fairly marginal gain, but it’s positive nevertheless.
Quartix helpfully indicates its view of consensus forecasts as being for revenue of £40.3m, adjusted EBIT of £10.1m and free cash flow of £4.9m. The company confirms that it’s already achieved c.£4.7m of free cash flow in the first nine months of this year.
Updated broker estimates from Cavendish today are positive:
FY26E adj EPS: 16.7p (+2% vs 16.3p previously)
FY27E adj EPS: 17.6p (unch)
Cavendish also notes that full-year free cash flow is now expected to be £5.3m, an increase of 7% versus previous consensus of £4.9m.
Today’s upgrade is the latest in a series we’ve seen over the last 18 months:
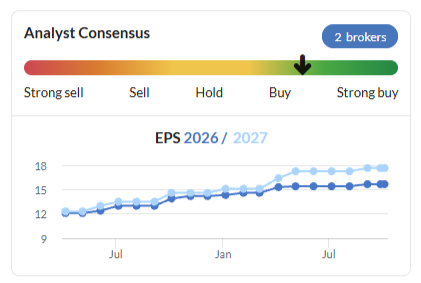
Roland’s view
Quartix’s share price has drifted lower over the last year, even as profit expectations have risen:
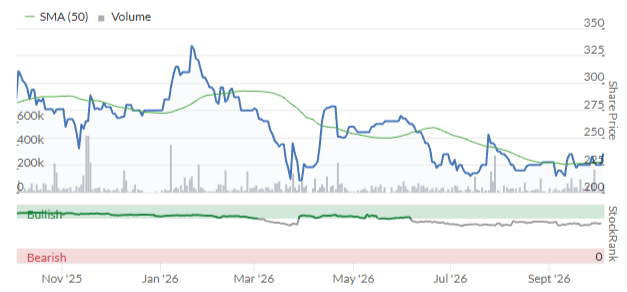
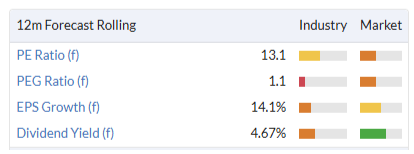
In July, Graham suggested the stock could offer value on a P/E of 14. The valuation has since slipped even lower:
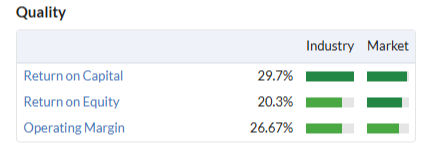
Quality metrics also remain strong, as Mark highlighted in his Stock Pitch.
So why is Quartix getting cheaper? One concern might be that on a free cash flow basis, the share price is arguably up with events. Using today’s upgraded forecasts from Cavendish suggests a free cash flow yield of around 5%.
Another potential issue is that underlying growth is relatively modest. Today’s forecasts from Cavendish suggest revenue growth of 13% in 2026, slowing to 8% in 2027. As I mentioned above, the group’s continuing efforts to expand in the US might not be helping overall performance.
A broader concern is that Quartix’s core business of selling telematic solutions to small fleet operators is always going to be price sensitive and potentially exposed to macro pressures.
Finally, long-term shareholders will also remember what happened when founder Andy Walters tried to retire a few years ago. The resulting snafu required him to return to the business, eject hired management and take control again. Walters is now in his 70s, so will his succession be managed more successfully next time?
One possible exit route might be through a trade sale. Many previously-independent telematics firms have been consolidated or swallowed up by larger businesses, such as tyre companies. I wouldn’t be surprised to see Quartix follow a similar path.
On balance, I think the opportunity here outweighs the potential risks. I’m going to leave our AMBER/GREEN view unchanged today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

35 comments
MelloMonday is back tonight at 5pm and we have a great line up of speakers: https://www.melloevents.com/mm051026
Use code MMSTOCKO50 for 50% off. If you are a shareholder in any of the presenting companies, you are eligible for a free ticket for this webinar with code SHMM26 (must be a shareholder of HRI TBLD, SEEN, FVA).
Full Mello Monday schedule below (subject to minor change):
5:00pm Interview with Katie Potts, (Lead Portfolio Manager) Herald Investment Trust (LON:HRI)
5:30pm Company Presentation from tinyBuild (LON:TBLD)
6:00pm Company Presentation from SEEEN (LON:SEEN)
6:30pm Company Presentation from Fevara (LON:FVA)
7:00pm Results Round Up by Mark Simpson
Hope to see you on zoom at 5pm for our next MelloMonday.
Currys (LON:CURY) and AO World (LON:AO.)
I note the narrative from earlier posters. In fairness I know little about AO World (LON:AO.).
As for Currys (LON:CURY) which I hold. It is the largest omnichannel retailer of white goods in the UK and should benefit from a help to buy scheme if it is resurrected in the budget.
It is trading well, buying back its shares and is financially sound. It trades on a lesser PE than AO World (LON:AO.) and pays a reasonable dividend. I would also mention its mobile network (ID Mobile) that is tradind well and that it is a leader in its sector in the Nordic countries.
I have always regarded AO World (LON:AO.) as a box shifter, but in fairness that may be unkind and I am happy to be corrected. Nonetheless I fail to see why one would buy AO World over Currys.
Just my tuppenceworth.
I don’t know about Brazil politics - presume one conservative/business and one socialist welfare/tax. But believe Serabi Gold (LON:SRB) popular with stocko is waiting for govt mining license (Coringa) to extend the current temporary or make permanent. Will be a catalyst. They employ local people and presume pay bungs, sorry royalties/tax, so that works for both political ideologies. So just down to the size of the envelope I suppose.
business leaders would probably be happier with Bolsonaro, but unfortunately he's not a traditional conservative. He's a Trump fan. We can probably kiss goodbye to the rainforest that his father didn't manage to destroy.
https://x.com/WShak1/status/2107000924078223432?s=20
Just read Mark Simpsons analysis not long ago (thought it was a stocko thing small cap uk) and he well covered. Maybe too detailed for the non mining/gold/etc crew.
Gold is going one way.
I have said it before on this platform, the FCA is a joke. It exists to serve the financial industry. As a regulatory body it is toothless snd spineless.
100% spot on.
All the best
I have a friend who works there. I would agree. He was a stockbroker.
As a customer and subsequent shareholder of Jarvis Securities (LON:JIM) for 20years, I wholeheartedly agree. They were closed down for no tangible reason that I'm aware of other than a slightly unclear statement on payment of interest on cash. Their expert took months investigating the ins and outs, which JIM had to pay for while trolls by the dozen said there must be something wrong, stay away. There was a whisper of lack of control of white label clients and possible money laundering but no action against the management. A RyanAir approach to budget stockbroking upset the CITY and the end was inevitable, maybe the change of government got the FCA on some scalp hunting campaign to score political points, who knows? Now after trying Interactive Investor for 6 months, I'm with IG who seem determined to drive me away with non-existing customer service and hideaway management compared to 25 years of having the Jarvis CEO's email address. I was a regular user of KwickFit years ago and always remember a picture of the founder and CEO on the waiting room wall with the message "If you like our service, tell your friends: If you don't, tell me" followed by contact details.
This is a BBC article from today. It’s a tragic reflection of how serious this whole issue is. The FCA needs to be disbanded and replaced with a custom centric culture with independent oversight at all points. https://www.bbc.co.uk/news/articles/cwm2686gl6kno
whats scary is that hmrc are passing over many of their regualtory powers ref money laundering for accountancy providers to the FCA - so thats a whole bunch of new stuff where people will have to deal with FCA where they have previously managed to avoid direct contact with them.
I will give the FCA some credit ref driving up standards for sketchy money lenders - but plain facts are even then they will be asleep at the wheel for like 5 years - then say its been wrong under their watch for 5 years when the "now advised wrongdoings" where hiding in plain site.
seems like the people who deliberately dont do anything get away with it for years to the extent its to late when FCA even look - and in the meantime people just trying to do their job have uber sketchy set of guidance and enforcement from FCA.
This is the most pertinent quote from the article: ”the FCA was not fulfilling its obligations to the public and whistleblowers and merely "pays lip service" to the rules and regulations.”
They are also a bunch of communists, if you have read the "consumer duty" and idea that you should benchmark yourself against the market to decide if you should be in business or give up you will know what I mean!
Not in the news today but would be interested in anyone's thoughts on the gradual slide in share price at Ramsdens Holdings (LON:RFX) . In theory a takeover price of 675p to be concluded by the end of the year but currently the price has dipped to 632p. Still some regulatory clearance required from the CMA I believe. Sold half on the takeover news but wondering wether to hang on to the rest.
Well you get 9p less now, since October 10th, so you need to adjust the chart a little. Before you got 675+9, now it's 675p and the position has to be financed. Some well known arbs are already in, Trium and Trinitybridge and it's not the most liquid so they're committed, I don't know if the CMA is taking longer than anticipated?
CMC Markets (LON:CMCX) to add to his small purchase on Friday, Lord Cruddas has just added another £1million buy. Confirming Graham's thought's this morning.
EDIT the transaction was actually on Friday.
I agree that long term CMC Markets (LON:CMCX) should not suffer the same loss in confidence as IG group (LON:IGG) . However, chart not out of the woods yet. It currently could be a retest of the underside of the distribution above. It may be that trapped buyers become sellers (as suggested by high volume).
Alternatively this dip could act like a trampoline to higher prices, especially if more good news is issued.
I agree. The price level is a long way from support.
IG's spivvy CEO should be fired immediately. Trying and failing to turn IG into a prop trading firm as well as paying nosebleed prices to add on a gambling business. The market has given it's verdict on this clown.
And if I'm not mistaken he holds a stake in the gamb company IG recently required.
Deleted
AO World (LON:AO.) I read the report, not a holder but have had it on my watch list as I see it as maturing business rather than the fledgling it was 3/5 years ago. Interesting but obvious comparison is with Currys (LON:CURY). The other half always buys from AO as we live miles from Currys and sitting in a Shropshire traffic jam is not my favourite way of passing time. AO has underperformed Currys by 20% in the last 6 months and whether this is a valid comparison I leave others to consider. Obviously delivery costs are rocketing for AO ( AO has transitioned to Compressed Natural Gas for its larger vehicles rather than diesel ) but balance that against the store based Currys with associated costs on staffing etc and those really irritating ads.
I am unclear about the Jessops acquisition, this seems a little odd given how everyone uses a phone for pics these days. There was a good reason why it went bust. True Music Magpie was also troubled when AO acquired
Currys has ID mobile and reducing pension issues
BT (LON:BT.A) The BT acquisition of Talk Talk customer base is likely to cause some issues in the Broadband sphere given this adds more to BT strong hold on the UK. I can see the likes of Vodafone objecting ( cue much outrage for BT ' monopoly') . Having said this since BT supplies the infrastucture for Talk Talk it has a vested interest in the business. Talk Talk has long been either completely awful in terms of service or on the verge of being so. I do wonder how BT will manage this transition so one see short term pain but it will be interesting to see how many customers leave given the alternatives are not numerous unless one indulges Elon Musk. My immediate reaction is this should be a plus for BT, but they have a habit of shooting themselves in the foot one way or the other so turbulence should not be ruled out
BT (LON:BT.A) Obviously with competition etc looking at this they have to be careful what they say but all this talk of maintaining service for vulnerable customers etc gets it over the line and surely shows how strong their hand is. Most of the concerns on results days seems to have been broadband account losses due to churn in the UK market. And with this deal they effectively put that to bed with a bunch of "new" customers - many of which are already on the network. The network investment is virtually complete so they have already done the handwork ... and get to flick a switch .... and put these customers into the machine. My suspicion is the deal looks very good for BT (LON:BT.A) but they can't spoon feed analysts right now for fear of upsetting regulators. The story was all about rising FCF now Capex has peaked and this should allow them to meaningfully move earnings forward to .... so 2028 numbers likely rise a fair bit in time.
( I own so obvs somewhat biased).
In March last year I sold all our BT (LON:BT.A) shares, a note on my spreadsheet says I should have kept them but that's water under the bridge. Today I bought back in, I've never had any trouble with BT, the change from copper to full fibre was both easy and free and I'm really getting everything I want from the 500Mps connection. In contrast, I recently had a holiday and the wifi connection was with TalkTalk and dreadful, my laptop couldn't take the hiccups, neither could I so it was no Stocko for the fortnight. I guess you get what you pay for, many consumers may have gone to TalkTalk to save on money.
I wonder if there would be anything nasty in the budget for the spread betting companies will wait and find out first.
Very interesting discussion re CMC Markets (LON:CMCX). Is this a buying opportunity or is there distribution going on? I followed the Stockopedia "method" of taking profits when a Stockrank clearly drops below 80 which has proved correct ATM. However, the SR value rank is backward looking I believe, so any announcement confirming the earnings forecasts could alter the value rank significantly.
Would appreciate if you had look at EnSilica (LON:ENSI) that I bought into in June and since then they have dropped aprox 30 % in sympathy with semi conductor stocks in general . Does todays finals ( a beat I think ) justify me holding on ?
Roland has covered Ensilica, Fred! Cheers.
IG are cowboys. I remember that when I had a sharedealing account with IG I deposited in GBP but since I lived in Europe (with EUR) they pretended that my account was in EUR and they used to charge me forex exchange fees each time I bought and sold. It added to some 20k in the end and I was really angry. I raised a case with the FCA ombudsman but they sided with IG.
The ombudsman service is supposed to be an independent body that investigates unresolved grievances and complaints of maladministration and unfair treatment but it didn't work in my case. I got the impression that IG and the ombudsman service are in cahoots. I will never forget this experience and will always tell people to beware.
Hi Ben
I have had my share of run ins with FOS, the staff are generally incompetent when it comes to dealing with anything remotely complex and will just side with the firm as it is easy to do and they are very time pressured into getting numbers of cases shifted. I once made this remark to a case officer and was greeted with silence! My last epic with them concerned Scottish Widows who conveniently under paid on a pension transfer from 20 years ago. After shuffling about for over 12 months I took SW to court ( in Scotland) and won my case and the payout I should have been offered in the first instance
I agree FCA are incompetent and I have had a similar experience dealing with the FCA and Barclays. FCA will side with big business.
I made a complaint to the FCA when consolidating my pensions before I retired. One was transferred straight away - another they "nicked" my not insubstantial amount for 20 working days to fund their own business (as markets were rising) before they paid out. The FCA case worker in the end asked me what else I expected them to do, my answer "Force" them to show the workings of how much they say I lost. They would not push it. NO calculation of the number offered was put forward! (PS that made them offer me extra cash as an act of good will so I settled) I only raised the issue as a large number of people wouldn't even know they had been hoodwinked - Turns out I had unrealistic expectations that the FCA would raise the manner in which I was treated and investigate the company to ensure the practice of "borrowing" ended!