Daily Stock Market Report (Mon 8th December 2025) - BKS, JNEO, TET, HERC, MER, SN., BIG, SEIT, MILA, MICC

Good morning and welcome to today's report. Let's see what the newswires have in store for us today.
Today's report is now complete.
Spreadsheet accompanying this report: link (last updated to: 10th November).
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our View (Author) |
|---|---|---|---|
| Unilever (LON:ULVR) (£109bn | SR52) / Magnum Ice Cream NV (LON:MICC) | Completion of demerger of Ice Cream Business | Trading in Magnum Ice Cream NV (LON:MICC) shares will begin at 8am on the LSE. A consolidation of Unilever shares will take place after market close today to maintain the comparability of the Unilever share price pre- and post-demerger. | (Roland - I hold) [no section below] I took an in-depth look at the new listing of Magnum Ice Cream (ticker MICC) in a Stock Pitch last week. One point worth following up is that my attempt to calculate the likely price of Magnum shares when they started trading seem to have fallen wide of the market. From what I can see, the valuation for Magnum shares has come in somewhat lower than expected - the initial valuation of c.€7.8bn is well below the levels I was hypothesising (and which had also been suggested in commentary elsewhere). We'll have to see where things settle out and what the consolidation ratio is for Unilever shares (to be published later today). |
Smith & Nephew (LON:SN.) (£10.7bn | SR69) | Upgraded FY25 guidance, trading margin now to be “at least 19.5%” w/ free cash flow of c.$800m. $200m inventory provision as part of portfolio rationalisation. Looking ahead, exp 6-7% rev growth w/ 9-10% trading profit CAGR. RH note: previous FY25 margin guidance was “between 19.0% and 20.0%”, so today’s upgrade is only slight. The free cash flow upgrade is more significant, up from c.$750m in November and prior to that, >$600m. | AMBER (Roland) [no section below] This medical technology company specialises in replacement joints and wound care products. It always seems to be in a turnaround phase and continues to trade well below pre-pandemic levels. Today we have news of an upgrade to 2025 expectations (see left) and a new set of strategic and financial targets for 2028. The main gist of the new targets seems to be that the company is aiming to scale through improved operational execution, while streamlining its product portfolio somewhat to reduce SKUs and reduce gross inventory by c.$500m. As part of this process, the company will recognise a $200m inventory impairment in its 2025 accounts. For me, this has always felt like a business that should be more profitable and successful than it is. I don't know much about this sector, but my tentative conclusion would be that S&N is missing some element of scale, product fit, pricing power or market share. The stock's 8% ROCE emphasises the average quality metrics - and the lack of the kind of strong profitability that might be needed to create attractive value for shareholders. This isn’t a stock we normally cover, but the lack of any market reaction to today's news suggests to me that a neutral view might be appropriate ahead of the 2025 results. A StockRank of 69 also seems to support this conclusion, in my view. | |
Fermi (LON:FRMI) (£6.98bn | SR1) | Signed contract for supply of <200MW of electrical capacity to Fermi’s 11GW Project Matador Campus. | ||
Harbour Energy (LON:HBR) (£2.96bn | SR72) | Sale of Harbour’s operated interests in Natuna A (28.7%) and Tuna (50%) for $215m cash to Prime Group, an Indonesian oil and gas business. Prime already has a 25% interest in Natuna Sea Block B. | ||
Oxford Nanopore Technologies (LON:ONT) (£1.2bn | SR43) | Oxford Nanopore Tech - Appointment of Francis Van Parys as CEO | New CEO will join on 2 Mar 26. He has >20yrs experience in life sciences and is currently President & CEO of acute care diagnostics specialist Radiometer (part of Danaher). | |
| SDCL Efficiency Income Trust (LON:SEIT) (£683m | SR n/a) | Interim Results | SP -17% to 52p NAVps down 3.3% to 87.6p (vs March 25). Gearing at 71.9% of NAV, FY26 dividend guidance of 6.36p per share unchanged. | No view (Roland) The trust’s managers warn that gearing has exceeded SEIT’s policy limit, constraining the managers’ ability to fund any more growth capex without disposals. Comments such as “A buyers’ market” emphasise the difficult conditions in the listed infrastructure sector at the moment. I think there may be some bargains on offer in this market, but I don’t know enough about SEIT’s portfolio assets to say whether the stock’s 40% discount to NAV is likely to represent an opportunity or a risk. I’m not taking a view today, but I might see this as worthy of further research if I had a keen interest in this sector. |
Avacta (LON:AVCT) (£345m | SR36) | Expects to announce initial Faridoxorubicin Phase 1b data in the salivary gland cancer indication on 17 Dec 25. A presentation will be held on IMC for private investors. | ||
Mears (LON:MER) (£293m | SR80) | Traded strongly in H2 expects FY25 adj pre-tax profit to be at the top end of market guidance. Panmure Liberum updated forecasts: FY25E: adj EPS 52.6p (prev. 50.4p) FY26E: adj EPS 42.6p (unch.) FY27E: adj EPS 40.2p (unch.) | AMBER/GREEN = (Roland) Today’s trading update is clearly positive, but the near-total lack of detail means that investors without access to broker notes may struggle to guess at the expected impact on profits. With thanks to broker Panmure Liberum, we learn that this outperformance is being driven mainly by higher-than-expected revenues from the ongoing asylum programme. However, expectations for a significant decline in earnings as this programme tapers off in 2026 remain unchanged. I am inclined to take a neutral view but I respect the momentum of repeated upgrades and can see the potential for further outperformance if this government spending proves stickier than expected. For this reason, I’m leaving Graham’s previous more positive view unchanged today. | |
Big Technologies (LON:BIG) (£186m | SR23) | New wins in Lithuania, Latvia and Washington state (USA). Agreed Buddi partnership with a US rehabilitation specialist. Trading in line with market expectations. | AMBER/RED = (Mark) Contract wins and an inline trading statement address one of the key risks here. Namely, that all the issues surrounding the legal action against the company and subsequent management changes, would impact trading. However, some huge uncertainties remain, not least the scale of the damages that they will need to pay former Buddi shareholders. The company only looks cheap if those damages are less than the possible £70m in damages sought plus costs, or are offset by a successful similar claim against former CEO, Sara Murray. While I see the attraction of taking a contrarian bet on this, resolution of these issues could go into 2027 if it goes to court. In the meantime, shareholders are exposed to great uncertainty, and a Momentum Rank of just 4 making it too soon to upgrade Roland’s previous, mostly negative view. | |
Beeks Financial Cloud (LON:BKS) (£156m | SR27) | £1.9m/5yr contract win with South African bank and £2m extension with “large FX broker”, bringing total for this client to £6m/5yr. Broker forecasts unchanged. Canaccord Genuity forecasts: | AMBER = (Roland) [no section below] Existing consensus revenue forecasts show Beeks’ top line growing by >10% per year. Against this backdrop, it’s clear that expectations are for the company to deliver a mix of contract wins and renewals/extensions. Today’s RNS (and others recently) appear to be no better than in line with these expectations, so I see this as a business-as-usual RNS. Having said that, it’s always encouraging to see growth companies delivering on forecasts. This update suggests the company is expanding its share of spend with one existing client and successfully securing new customers elsewhere. Using the 16% operating margin implied by today’s (unchanged) Canaccord Genuity forecasts for FY26, these contracts could equate to around £635k of additional operating profit. At least some of this will be spread over five years, but it’s still a useful amount for a company forecast to generate £6.7m of EBIT this year. My main concern with this business remains that it’s quite capital-intensive and has not yet demonstrated the ability to generate tech-style high returns - ROCE remains resolutely under 10%. In essence, a lot of what Beeks does seems to be equipment leasing. On that view, the rolling forward P/E of 25 and in-line performance mean I can’t get higher than AMBER. | |
Treatt (LON:TET) (£126m | SR70) | Interim CFO will be promoted to Interim Group Managing Director, with Group FD and IR lead taking responsibility for finance function. This management structure will remain in place until a new CEO is appointed. | AMBER = (Mark) [no section below] Given all the ongoing takeover news, where a decent-premium bid was blocked by a German ingredients group increasing their holding to 28%, we haven’t really commented on the business recently. Perhaps unsurprisingly once the recommended bid was blocked, the CEO fell on his sword. Today’s announcements give some leadership continuity. However, I can’t help feeling that changes of titles aren’t going to see any significant change in business prospects in the short-term. They also suggest that a new CEO appointment will take some time. Trading is undoubtedly difficult, and the risk is that there is a further short-term profits warning. Even without this, a 16x forward P/E doesn’t look compelling. However, the shares have fallen back following the failure of the takeover offer, and are now at 0.9xTBV. This, plus the willingness of two industry players to either buy shares or the whole business at a significant premium to today’s price, suggests that there is value here for those willing to take a longer-term view. My pre-offer, neutral view, reflecting this mix of short-term risk but long-term value remains. | |
Journeo (LON:JNEO) (£83.3m | SR91) | Recently acquired subsidiary, Crime and Fire Defence Systems, has received initial purchase orders totalling £2.3 million. Work has already commenced, and all three sites are scheduled for completion in 2026. | AMBER/GREEN = (Mark) [no section below] | |
Pulsar Helium (LON:PLSR) (£56.3m | SR17) | Jetstream 5 well: gas was encountered at 255m and 451m depth, with a preliminary bottom-hole pressure reading of ~662 psi, indicating a strongly pressurized system. | ||
Lendinvest (LON:LINV) (£53.5m | SR36) | FuM +14% y-o-y to £5.3bn. Net operating income +29% to £21.5m, mainly due to higher interest income. PBT £1.2m (25H1: £2.4m LBT), EPS 0.6p (25H1: -1.3p). Experienced some temporary slowdown in property purchase activity ahead of the November Budget, but performance for the full year is expected to remain in line with market expectations. | ||
Iqe (LON:IQE) (£49.1m | SR20) | A multi-year extension to its strategic agreement with Lumentum to use IQE's VCSEL expertise has advanced 3D Sensing technologies across Lumentum's broad photonics product portfolio. | ||
Helium One Global (LON:HE1) (£35.9m | SR11) | Commenced operations in southern Rukwa ahead of further testing using an Electrical Submersible Pump which is expected to arrive in Tanzania mid to late December. | ||
Hercules (LON:HERC) (£33m | SR86) | £4.2 million awarded within the Thames Water region £2 million awarded within the Anglian Water region To start in Q1 FY2026 and last for 6 months. | AMBER/GREEN = (Mark) | |
Medpal AI (LON:MPAL) (£29.9m | SR8) | An enhanced journal feature now supports AI-powered analysis of uploaded documents and lab results. The update also introduces German language support. | ||
Wishbone Gold (LON:WSBN) (£20.3m | SR27) | Three diamond drill holes have now been processed with assay results pending. Access road applied for. | ||
Sound Energy (LON:SOU) (£18.2m | SR22) | Initial commissioning activities for the TE-5 Horst development project (20% Sound Energy) has had first gas entered the gas gathering system in preparation for long term gas production into the micro-LNG plant. | ||
Mila Resources (LON:MILA) (£17.1m | SR32) | Gold intercepts returned from the first diamond drill hole include 5m @ 2.78 g/t from 183 m. | RED (Mark) | |
Frontier IP (LON:FIPP) (£12.7m | SR27) | NAV/share down 23% to 61p, partly due to fund raise. LBT £6.3m (2024: £1.3m). Loss per share 10.1p. Cash 30 Jun £2.6m. | ||
Rockfire Resources (LON:ROCK) (£11m | SR23) | Drill results so far in hole HMO-010 are reading high grades of zinc, silver, and lead. Between 97.55m and 98.20m depth, individual spot readings peak at 13.9% Zn, 1.48% Pb and 133ppm Ag. | ||
Kropz (LON:KRPZ) (£10.2m | SR26) | Related parties, Elandsfontein and ARC have loaned ZAR 250 million (US$ 14.4m) at an interest rate of South African prime overdraft interest rate (currently 10.25%) plus 6%). Funding ongoing losses. |
Roland's Section
Mears (LON:MER)
Up 4.5% to 371p (£321m) - Trading Update - Roland - AMBER/GREEN
Today’s update is short and sweet:
Mears Group PLC, the leading provider of housing services to the public and regulated sectors in the UK has traded strongly in the second half to date and anticipates that adjusted profit before tax for the financial year ended 31 December 2025 is expected to be at the top end of market guidance issued on 7 August 2025.
A more detailed update is promised in January. What would have been more helpful for investors today would have been if the company had included a little more detail, both on existing expectations and the reasons for today’s upgrade.
Turning back to August’s interim results does not provide a clear answer, either. While the company did provide guidance on the range of revenue and operating margin expectations, pre-tax profit guidance was for a “range of outcomes derived from revenue and margin guidance above”.
Broker update: fortunately in this case, I am able to access the additional insight provided by broker coverage, with thanks to Panmure Liberum on Research Tree.
PanLib’s note today tells us:
The upgrade is driven by both revenue and margins;
Additional revenue has mainly come from the Asylum Accommodation and Support Contract (where Mears is involved in providing accommodation such as hotels);
FY25 adjusted pre-tax profit forecasts is upgraded by 4.5% from £58 to £61m
It’s a shame Mears chose not to provide this information in its RNS, so it could have been equally available to all market participants.
Outlook & Estimates: PanLib’s earnings estimates for 2025 have increased today, with outer years remaining unchanged ahead of January’s more detailed update:
FY25E adj EPS: 52.6p (+4.4% vs 50.4p previously)
FY26E adj EPS: 42.6p (unch)
FY27E adj EPS: 40.2p (unch)
Today’s upgraded forecasts put Mears on a 2025 forecast P/E of 7, but investors need to beware of falling earnings forecasts for the following two years.
Asylum work is tapering off: the underlying story here is that Mears has done very well from its government contracts to provide accommodation for asylum seekers. However, this is now tapering off. The company says that the government intends to end the use of hotel accommodation in 2026, resulting in a hit to earnings for Mears.
The more detailed guidance provided with the half-year results showed that revenues from the Management business, which includes the asylum contract, are expected to fall by £100m in FY25 and by a further £125m in FY26.
While the Maintenance side of the business is expected to maintain 5%-9% revenue growth over the medium term (vs 8%-9% in FY25), brokers are clearly not yet convinced that Mears can make up the shortfall that seems likely to follow the tapering of the asylum-related work:
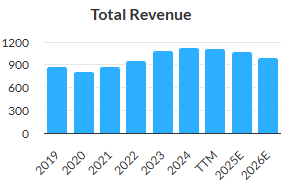
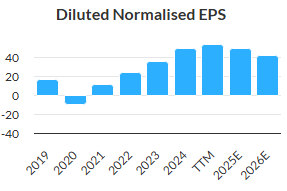
The market will be looking for Mears’ management in January to provide more clarity on the pipeline of new contracts and recent wins. This could help to firm up the valuation, potentially.
The other possibility, given the nature of this work and the complexity of the situation, is that winding down the use of hotel accommodation and providing suitable replacement accommodation where needed will take longer and cost [the taxpayer] more than currently expected. That isn’t impossible and could be beneficial for Mears.
Roland’s view
While quality metrics for this business have improved significantly in recent years, I think it’s worth noting the extent to which Mears has become a property leasing business. This is reflected in the rise in statutory net debt (which includes lease liabilities):
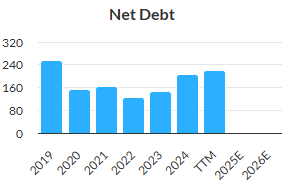
I don’t follow Mears all that closely and am surprised by the scale of the leasing liabilities the business has built up. From what I understand, the majority of this relates to the company securing accommodation under the scope of its asylum contract. In addition, there’s also some exposure to other government-backed areas such as MoD housing and criminal justice (housing newly-released prisoners).
The general idea, from what I can see, is that Mears leases properties with durations/break clauses that are matched to the relevant contracts. This is intended to minimise the risk the company will be left with empty properties on which it is still making lease payments.
I don’t know how bulletproof these arrangements might be, but for me, the politically-charged nature of much of this work is a potential concern, due to the risk of unexpected changes to prevailing policies.
The numbers are certainly significant. While Mears reported net cash of £81m excluding lease liabilities at the end of June 2025, the group’s balance sheet showed £300m of lease liabilities at that time. Around three-quarters of these are classed as non-current (i.e. due in more than 12 months’ time), so I would guess the typical duration of these leases might be 3-5 years.
My working assumption is that any unexpected disruption to sub-letting cash flows could have a material impact on the profitability of a company generating c.£70m of operating profit.
Graham was AMBER/GREEN on Mears following the company’s half-year results in August and a string of earnings upgrades earlier in the year:
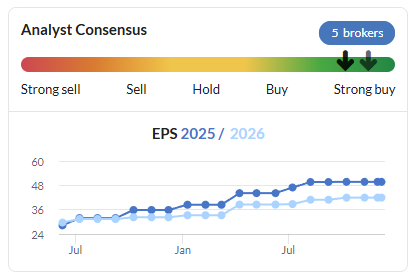
My inclination is to be a little more conservative, given the forecast decline in earnings. But I think the company's continuing near-term momentum justifies leaving our moderately positive view unchanged today, ahead of January’s full-year update.
SDCL Efficiency Income Trust (LON:SEIT)
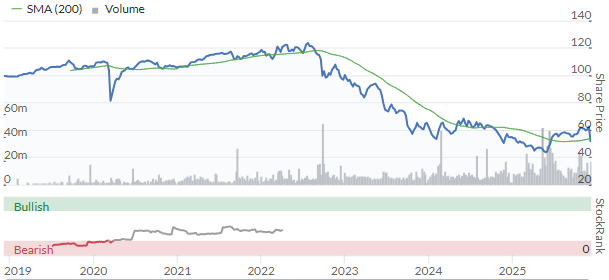
Down 17.5% to 52p (£565m) - Interim Results - Roland - No view
We don’t normally cover investment trusts in detail, but today’s interim results from SEIT have made it the biggest faller in the FTSE All-Share index. I thought it might be interesting to take a brief look at this trust, which appears to offer a tempting 10%+ dividend yield.
SIET’s investments are focused on the “energy efficiency sector” and include projects in the UK, Europe and North America. These include solar projects, a gas distribution network and services to improve the energy efficiency of two steel mills in the US.
Today’s results have been received like a lead balloon, despite SEIT only reporting a fairly modest decline in net asset value and leaving its dividend target unchanged.
H1 26 headline results summary (6 months to 30 Sept 25):
Net asset value (NAV) per share down 3.3% to 87.6p
Portfolio valuation of £1,172m at 30 Sept 25 (£1,117m at 31 March 25)
Investment cash flow from portfolio of £58m (Sept 24: £48m)
H1 dividends of 3.18p per share, FY26 dividend target unchanged at 6.36p per share
Gearing at 71.9% of NAV, above Investment Policy limit
Disposal progress includes sale of ON Energy at 18.75% premium to NAV and “exclusivity agreed on a further disposal expected around year end”
Outlook & Market Commentary
Outlook commentary today is focused on issues that are widespread across the infrastructure and renewable energy trust sector, but appear to be affecting SEIT more seriously than some rivals. Here’s a summary of the key points, as I see them:
Deep share price discounts to NAV mean that the only option to raise funds for growth is through debt or asset disposals;
Unfortunately, SEIT has run out of borrowing headroom and its investment manager has been instructed not to draw down any further debt;
While growth capex remains unavailable, there’s a risk that asset valuations could be downgraded where those valuations already price in growth plans;
Management are working on asset disposals to reduce leverage, but current market conditions “can be categorised as favouring buyers”.
High levels of infrastructure equity dry powder, coupled with pent-up supply from oil & gas majors disposing non-core assets, and extended holding periods driven by limited exit opportunities, have contributed to falling valuations and smaller deal sizes. Boston Consulting Group notes that average deal sizes in infrastructure are 40% below their 2021 peak, with volumes down by 8%, while Roland Berger confirms a 14% drop in 2024 continuing into 2025.
Roland’s view
It’s clear that potential buyers will be aware of the company’s need to sell and able to strike attractive bargains. The slow pace of disposals in 2025 here (and at other trusts) illustrates the company’s point about it being a buyers’ market at the moment. Clearly, competition to buy such assets is not all that strong right now.
In my view, this leaves SEIT in an uncomfortable position. It’s overgeared, unable to raise equity (due to the discount to NAV) and unable to borrow more.
I am not surprised the shares have fallen sharply today.
However, this isn’t necessarily a lost cause, in my view. As I write, the shares are trading at a 40% discount to today’s net asset value. If enough of SEIT’s assets are profitable and cash generative, with viable futures, then this collection of assets could offer genuine value potential at current levels – even if the dividend is eventually cut.
I should stress that I don’t know much about SEIT’s assets at all; this isn’t a stock I follow. It’s possible that they are all good assets, with viable business models and growth potential. Equally, it's possible that they are not so good and deserve to be de-rated.
For me, the big picture here is that SEIT and other such trusts built portfolios based when interest rates were much lower. The impact of rising rates has left many trading at a discount and caught in a Catch-22 situation. Higher funding costs, changes in energy pricing and political factors are all extra complications, as we saw with the failure of the TRIG/HICL deal (disc: I hold TRIG) last week.
In some cases, I suspect we’ll find that the numbers for some of these projects simply don’t add up any more. In others, I think it will gradually become apparent that there is decent value on offer.
I don’t have sufficient insight on SEIT to take a view, but if I was a keen investor in this sector I would probably take some time to learn more about the underlying assets here.
I think it’s inevitable we’ll see some liquidations and some consolidation in the infrastructure trust sector. While it’s not without risk, owning deeply-discounted assets in such a scenario could be a profitable strategy.
Mark's Section
Hercules (LON:HERC)
Up 8% at 44p - New Major Contract Awards in the Water Sector - Mark - AMBER/GREEN
When I looked at Hercules following their Half-year results at the start of October, I liked that they were growing at a reasonable pace without requiring much additional capital, and were on a modest multiple. However, I also had several concerns:
Their disclosures look poor, as they didn’t include a breakdown of their adjustments or segmental reporting at the half year.
We didn’t see a significant increase in forecasts following their major acquisition of NRG. This led me to question whether they overpaid or there is weakness in their core business that is being masked.
Looking at the segmental reporting, almost all of their growth comes from labour supply not civil projects, meaning that they were increasingly looking like a recruiter, not a civil engineering business.
That last concern may be partially assuaged by today’s announcement:
Civils Projects division has been awarded a series of new sub-contract packages from its clients in the UK water sector to start in Q1 FY2026. The new agreements total c.£6.2 million in value and are expected to be delivered in the next six months.
£6.2m doesn’t immediately seem material compared to a £129m forecast revenue. However, Civil Projects had a gross margin of 21% in 2024, compared to 13% for Labour Supply. If these contracts deliver similar margins, they add about £1.3m additional gross profit in 2026. Segmental admin costs seem to largely track inflation, but there may be some incremental cost associated with these wins. Still, this has the ability to add somewhere between £0.5m-£1m of additional PAT. Which is material to the current c.£3m forecasts.
The contracts are split across two water companies:
These clients are delivering crucial upgrades and increased capacity at clean and wastewater treatment sites across the UK. Hercules will manage and deliver projects in the following regions:
● c.£4.2 million awarded within the Thames Water region
● c.£2 million awarded within the Anglian Water region
Those who live in a Thames water area will no doubt be hoping these works help reduce the amount of raw sewage that is being discharged into their rivers! Hercules are certainly hopeful that these contract wins are the first of many in the current AMP8 5-year regulatory cycle:
Hercules is a strategic supplier to contractors operating within the following UK water regions: Anglian Water, Thames Water, Southern Water, Severn Trent Water, Wessex Water, United Utilities, Welsh Water, and Yorkshire Water…As a result, the Board of Hercules expects to continue to secure additional contracts and deliver a wide range of projects over the coming years as AMP8 builds momentum.
Unfortunately, I cannot see any updated broker coverage which would confirm if these wins have already been included in forecast growth.
Mark’s view:
If my calculations are correct and these wins are not already in forecasts, this makes the current forward P/E around 8, after today’s rise. This looks modest compared to the potential for further Civils Project wins. This will also have a positive impact on the Momentum Rank, which is currently the weakest of the three:
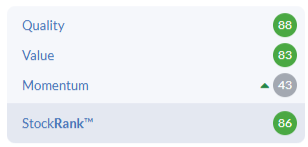
Despite my first two concerns remaining, this news means I’m happy to keep my broadly positive AMBER/GREEN view even at the current higher share price.
Big Technologies (LON:BIG)
Up 5% at 66p - Trading Update - Mark - AMBER/RED
I wanted to take a look at this company today, as a friend commented that it may be cheap despite (or perhaps because of) recent litigation woes. Roland reviewed these allegations in detail here. The most damning of those appear to be that:
[Former CEO] Sara Murray had… improperly diverted or extracted significant sums of money (currently thought to be in excess of £19 million) from the Company and/or members of its Group to herself or persons connected with her
And:
Additional matters have now come to light which further materially adversely impact the position of the Company and Buddi in the Buddi Litigation…These matters centre on the forgery or deliberate falsification by Sara Murray of various documents, including board minutes of Buddi and emails which, on their face, purported to: (i) be sent by certain shareholders in Buddi; and (ii) show their agreement to sell their shares in Buddi to the Company for cash.
That last point sounds like the company will almost certainly have to pay damages to former Buddi shareholders who are suing the company, and the company has pretty much said as much in their latest litigation update. Understandably, these revelations have led to various boardroom changes. Obviously Ms Murray is fired as CEO, but there has also been a change of Non-Exec Chairman and the COO lost their board position, some of these changes appear to have been forced upon them by major shareholders. The company are seeking to recover damages from Murray, while she remains the company’s largest shareholder with 26.7% of the equity. Overall, this just looks a mess.
An initial look at the StockRanks is also not promising:
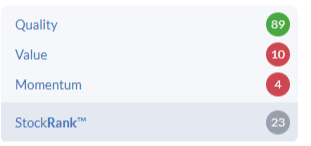
However, in keeping with the academic research on the value anomaly, the Value Rank is based on the historical figures only, and things look better on a forward basis:
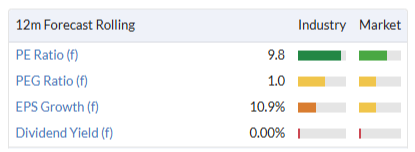
Therefore, today’s update is key when it confirms:
The Group expects to release its full year trading update at the end of January 2026 and new contract wins underpin confidence in the Group's trading in line with market expectations.
Helpfully, they give these expectations:
current market forecasts for 2025 revenue to be in the range of £48.5m to £49.5m, with a consensus of £49.1m, and for adjusted EBITDA to be in the range of £23.7m to £24.5m, with a consensus of £24.1m.
The broker’s note we have access to, Zeus’s, comes in at consensus for adj. EBITDA which they turn into 6p of EPS, for a forward P/E of 11. This doesn’t look immediately attractive, given the events of the last year. However, they also forecast £96.1m of net cash at the year end, which is half the market cap. Importantly, Zeus also forecast that cash balance to rise going forward and reach almost £130m at the end of 2027, as earnings largely convert to free cash flow.
There are several large unknowns remaining, and given my lack of legal expertise, I’ve asked ChatGPT a few questions:
How much will the Buddi litigation cost them? ChatGPT says: “the former-Buddi shareholders appear to be seeking about £70.1m (plus “damages”) and, if they win, total payout to them could easily exceed that number once interest and costs are added — conceivably pushing the ultimate bill into the low-to-mid-£70–100m range under some plausible outcomes.”
How much of that claim can they recover from Ms Murray? I believe that Murray has provided undertakings not to dissipate assets up to £320m, meaning there are assets available to make restitution. ChatGPT: “Practically, the most recoverable slice will be money Murray is shown to have personally received or controlled (e.g. the alleged £19m). Recovering the entire £70.1m headline from one person is possible legally but fact-dependent and unlikely unless her assets or receipts directly correspond to that scale.”
What the company intends to do with the cash balance? For us to consider a cash-adjusted valuation, we need to know they will put that cash to good use or return it to shareholders. They haven't paid a dividend since listing. There was a share buyback program started in September 2024, but this ended after Ms Murray was dismissed. In May’s results statement they said they had “made good progress in identifying an acquisition in the strategically important US market. However, as a result of the ongoing litigation, we have paused these plans to maintain our financial strength.” While there may not be an immediate ability to grow via acquisition, it looks like this is where they will deploy cash when they know how much they have left after damages and costs are known.
Are there any more skeletons in the closet? In my experience, when alleged misrepresentations are found at the core of a company, it often takes more than a change of management to remedy the situation. While in this case, the allegations appear to have been addressed with integrity by the board, they can only deal with the information they have. I have no doubt that there is a real, cash-generative business here, but I am aware how little we can actually know as outside investors.
Mark’s view
Putting all of these together, one could argue that even if the eventual award to the Buddi former shareholders is £70+costs, and the recovery from Ms Murray is negligible, the valuation is not that expensive. However, there will no doubt be huge disruptions to the business from all that is going on here, and a risk that further issues surface. Today’s trading statement, confirming that trading is in line with expectations helps mitigate some of those risks, and I can see why the market has been slightly re-assured by this today. However, I can’t help feeling that a better strategy may be to wait until the eventual outcome of the litigation is known. Investors may end up paying a higher price, but they avoid being stuck in a stock with a Momentum Rank of 4. After all, if the Buddi litigation goes to court, then we may not get a final judgement until sometime in 2027. Until then, or if we have confirmation that Buddi former shareholders are happy to settle, or explore mediation, there will remain an uncertainty that will weigh on the share price. Hence I share Roland’s AMBER/RED view for the moment.
Mila Resources (LON:MILA)
Down 15% at 2.2p - Yarrol Project - Mark - RED
The recent gold price strength has encouraged many smaller gold explorers to pursue more active drilling campaigns. Management of these companies are almost always incredibly excited by their drill results. While I don’t want to pick on Mila Resources (LON:MILA) as it seems not to have been excessively enthusiastic in management comments today, they chose to RNS drill results on a quiet news day on the DSMR:
Significant gold intercepts returned from the first diamond drill hole MYADD0205, including:
o 5 m @ 2.78 g/t from 183 m
▪ including 1 m @ 6.89 g/t Au
▪ and including 1m @ 6.39 g/t Au
o 2.19 m @ 1.1 g/t from 170.44 m
o Allowing for greater dilution of lower grade material between intercepts returns an interval of 14 m @ 1.14 g/t from 178 m
They describe these as “significant”. However, it is worth having a think about what these drill results actually mean. Grams/tonne is effectively parts per million. Mila has only intersected in two 1m sections above 5 g/t. In comparison, Serabi, with a producing underground mine at Palito, has a Reserve Grade (2P) of 7.2 g/t, and Resource Grade (M&I) of 9.6 g/t. Their Cut-off Grade of what they consider economic is 3.70 g/t for underground operations.
What Mila are reporting today, is made clearer by their drill map:
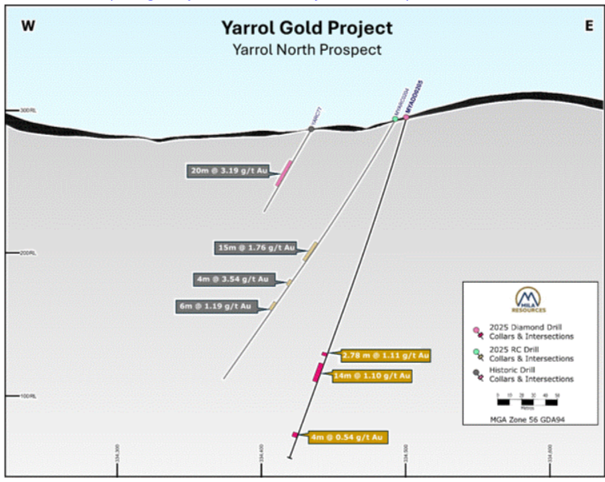
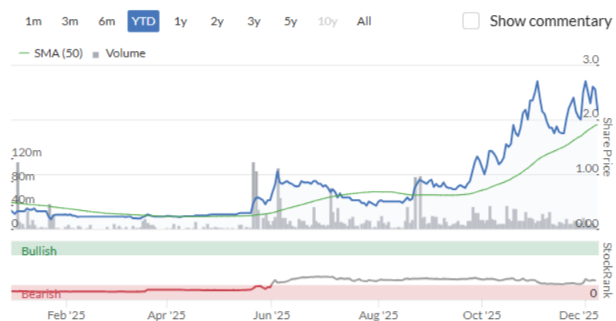
Their highlighted intersections are around 200m underground! That would require a huge open pit, or an extensive underground development. I’m not a sector expert but I see almost no sign from these results that they have identified mineralisation that could be economically developed given these grades and depths. Of course, they may find such mineralisation in the future. However, this hasn’t stopped investors piling into the junior gold explorers this year, as Mila’s share price chart shows:
The other factor with this and similar companies is the time it takes to build a mine. Mila’s photo on their website accompanying the Yarrol project may be more prescient than they intended, as it is two men looking far into the distance!
With a huge amount of drilling still required to show a viable resource (if it is actually there), raise funds and build a mine, any mine is likely to become operational just as the gold price cycle turns and heads south again. While the timing of any such cycle is unpredictable, the capital market cycle that allows companies such as Mila to raise funds for exploration is almost certain.
Mark’s view
While I look at Mila today as it reported drilling results, my view encompasses almost all of the smaller companies that are only just starting drilling prospects today. They may announce drill results with great fanfare, but when I look at the details, I see unimpressive grades at great depths. My view is that the vast majority of such projects will never reach production. Given the time to build a mine, the ones that are in the initial exploration phase today that do become mines will likely become operational in a much lower gold price environment given the capital market cycle. The likely lack of economic returns to shareholders makes this and similar companies RED for me.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

51 comments
Mila Resources (LON:MILA) Interesting commetary above.
Mila proudly announced two seams intersected with 5g / tonne. Agreed this doesn't look viable at current gold prices.
There is a widespread assumption that we have always found new gold deposits, so we will always find new deposits in the future. Perhaps this is not true?
If Mila is one of the best finds in recent years, there is not much gold left worldwide to mine. Serabi one of the largest producers has a mine life of less than 10 years.
It seems that gold prices will be much much higher than the current price of $4,200 in ten years time.
I was reading an article last week and it stated that so far the world has mined 220,000 tonnes of gold. The article also stated that there is 120,000 tonnes of known gold still in the ground. In otherwords, approx 2/3rds of the world's known gold reserves has been mined.
David.
Re brand day at iweb to SW a complete horlicks. New terms offered at II. Still no app at SW. Major UK banks still hopeless?
app is on the way for scottish widows IIRC
that said, unless you're day trading - do you really need an app?
Yes, to sell on the move. Ie confluence up 25% today. Do you work for a bailed out bank by chance?
I have posted a couple of articles on Stocko on the European Aerospace and Defence sector if anyone is interested:
European Aerospace and Defence I | By jamesalastair | Stockopedia
I have also started a substack where there will be additional material written by a couple of retired military colleagues who have additional insight. Anything potentially investment related or actionable that I author, I will also post here on Stockopedia, which I think remains one of the best investor communities available to small private investors.
Although a lot of the European defence stocks no longer look cheap, I believe the market is underestimating the level of disruption to the long established post war architecture. To those that might think I am being a bit mercenary, I would say I had the privilege of wearing the Queen's uniform back in the day; I volunteer for SSAFA (Inverness-Shire & Western Isles | SSAFA) and my wife and I continue to work with extracting and hosting Ukrainian refugees.
The Defence and Aerospace sector has experienced challenges raising funding from some of our banks which I find astonishing and deeply unethical given the level of threat and the sacrifice made by our forebears in two (and other) world wars, and now the Ukrainians.
If you get any value from this, reach out to your local SSAFA branch, either as donor or volunteer. The family needs of veterans and current serving men and women in our armed forces is large and our resources are finite. Thank you for your indulgence in this festive month.
Thank you. Interesting note. Your Substack piece was excellent.
Thank you Simon for your kind words. I am hoping to persuade my friend, who was the (retired) former air attaché in Paris, to contribute an article on the subject of integration of air combat, air logistics, radar and air defence resources across the European theatre.
It looks like the Germans are on the verge of pulling out of FCAS and the Italians have suggested they join the Brits, Japanese and Italians in the Global Combat Air Programme. The decision will be made by Mertz and Macron face to face on December the 11th, but I think the writing is on the wall. Dassault has overplayed their hand. BAE Systems (LON:BA.) Mitsubishi Heavy Industries (TYO:7011) and Leonardo SpA (BIT:LDO) would be the direct beneficiaries as it is unlikely Germany would play much of a role in design at this late stage, although I don't doubt Airbus SE (ETR:AIR) could build wings and fuselages in Germany.
It is interesting that Pakistan claims they shot down 5 French supplied Raffaele jets, albeit without a whole lot of evidence. Pakistan flies a number of jets, some supplied by China. Raffaele have also denied Pakistan's claims (unsurprisingly given the export culture of Dassault). Performance matters as the Russian weapons export opportunities dwindle due to PPP in Ukraine.
Very interesting. And I will be reading your post.
V good articles. Thanks for posting and hat tip for all the charitable work you do. FWIW I know a v bright, all A's, Uni student studying aeronautical engineering and specialising in drone tech. He & his mates refuse to work in the defence sector for so called 'ethical' reasons. It's not just financing that is a problem, it might be recruitment as well. Makes me despair what we're filling the minds of our youngest & brightest with today.
And, extraordinarily, the 'cultivation' of that attitude/view or whatever can in great part be attributed to institutional investment organisations and their blinkered and myopic interpretation of the ESG mantra (now thankfully diminishing). If ever a single element negatively, naively and profoundly misjudged the realities of world issues and the vast threat spectrum to security these have had to those operating in the 'real' world then our 'institutions' have much to answer for.
That's interesting (and sad). He could come with me to Ukraine and I guarantee he will change his mind after a couple of weeks. Nothing like your family and friends being attacked and killed to focuses and change your mind. The son of one our friends finished a degree in Mechanical Engineering and now works for Rolls Royce. He absolutely loves it.
He & his mates refuse to work in the defence sector for so called 'ethical' reasons. It's not just financing that is a problem, it might be recruitment as well. Makes me despair what we're filling the minds of our youngest & brightest with today.
Hi Joe
I worked for British Aerospace straight out of uni but a number of my fellow graduates didn't want to work in defence. And that was at the peak of the Cold War.
It's easy to blame today's young people for the woes of the world, but it's the older generations who created the world they have to live in.
timarr
I believe that Anduril, the advanced weapons company linked to Palantir, were originally based in Silicon Valley but found it difficult to recruit local programmers for ethical reasons. They moved to Colorado and had no problem recruiting there.
The history of world is all about warmongering its in the human DNA. The pacifist mindset only emboldens the Putins and Xi Jinping of this World. The Wests (excl USA) indifference to the threat have us left weak and exposed its time to man up and face the music before its to late.
Hi Roland. As a Unilever (LON:ULVR) holder, I am trying to understand the current valuation of the demerged Magnum Ice Cream NV (LON:MICC) today. I appreciate the in depth look at the ice cream business that you put out last week, but I see that it is trading at about half of your calculated value this morning.
If you get a moment, could you take another look. Is ice cream trading at half the rating of the remaining business or are we missing something? Perhaps there might be a bit of a 'Ben & Jerry' discount in there and the weight loss drug issue as you mention in your article but otherwise I am stumped. Overall, it looks as though Unilever (LON:ULVR) holders are neither richer nor poorer than Friday's close.
Hi sparkler, thanks for your comment.
The aim of the demerger is that Unilever (LON:ULVR) shareholders will be made whole at the point of the demerger -- so neither richer nor poorer, as you suggest. Over time, the valuations will diverge one way or another.
I agree that my share price calculations seem wide of the mark.
From what I can see, the valuation for Magnum Ice Cream NV (LON:MICC) has come in somewhat lower than expected - the initial valuation of c.€7.8bn is well below the levels I was hypothesising (and which had also been suggested in commentary elsewhere).
We'll have to see where things settle out and what the consolidation ratio is for Unilever shares (to be published later today).
This newswire commentary suggest demand for shares in a sugar-heavy snack manufacturer may be a bit soggy, not helped by lack of eligibility for passive index tracking funds (not yet included in FTSE indices) and possible disappointment among investors that there will be no dividend payment until 2027.
The c.£11 share price puts the stock on c.13x my estimate of FY24 earnings - potentially reasonable, in my initial and provisional opinion. I'm still keen to learn more about this.
Roland
Disclosure: I hold shares in ULVR and MICC.
Hi Roland. Thanks for those further thoughts - they are useful. However, I think you slightly misinterpreted my comment (and indeed the company's intentions) about Unilever (LON:ULVR) shareholders being neither better or worse off today. I have added the value of my Magnum Ice Cream NV (LON:MICC) demerged shares to the reduced value of Unilever shares and see that the total is similar to Friday's Unilever price. However, the key rationale for spinning off businesses is surely to realise additional value for shareholders? Perhaps no surprise that nothing has changed in just one day, since there has been time for the Unilever (LON:ULVR) price to adjust to the proposed demerger but over time it is clearly hoped that the value ascribed to the standalone businesses is higher than the conglomerate. Otherwise why waste time doing it?
You talk about Unilever (LON:ULVR) shareholders "being made whole" at the time of demerger and I think you might be missing the gist of this 'management speak'. My understanding is that tonight's share consolidation will simply restore the Unilever (LON:ULVR) share price to where it was on Friday for the purposes of share price related management bonuses. The rest of us investors really don't care, for example, whether we have 500 shares at £42 or 467 at £45, if that makes sense?
Santa Rally this week? 10th onwards, possibly
I think it has the chance of being the same as last year, a Santa Slump, only more so. Sorry.
Who knows! Last 2 years not great
As a matter of interest John, I made a practice portfolio at the time, the 14th of December 2024. It comprises the Most Pessimistic of All.
Looking at it I should have made firm purchases instead, sold all in May 2025 and gone away, ha, ha!
Right Click for a larger view in a New Tab.
Well that old saying is right!!
How were the most pessimistic selected? Seems to be a fantastic result +40%
Thinking back I had the max portfoios real or virtual, was it 10 or 12?. Anyway, I went through all the companies in them to find the most pessimistic They were/are, in current order of best at the top:
Sylvania Platinum (LON:SLP) Centaur Media (LON:CAU) Nexteq (LON:NXQ) Secure Trust Bank (LON:STB) Persimmon (LON:PSN) Watkin Jones (LON:WJG) Taylor Wimpey (LON:TW.) Octopus Renewables Infrastructure Trust (LON:ORIT) NextEnergy Solar Fund (LON:NESF) Braemar (LON:BMS) Vast Resources (LON:VAST) Foresight Solar Fund (LON:FSFL) Petro Matad (LON:MATD) SThree (LON:STEM) and the most pessimistic of the lot, PFC,(Petrofac).
I was actually thinking about Santa Rally / Slump over the weekend.
And thought maybe we are getting a new seasonal trend, where it is a Slump rather than Rally.
As there is so much retail money in the markets now. This money is flighty. December and January are high demand on people's finances (Christmas presents, meals, travel, etc). If this is your average Joe Bloggs, having a go on Trading 212 with his few hundred pounds of savings.... when he needs that in December, guess what, shares will be sold. And only maybe bought back in February after Jan payday.
Just a theory in my head, with absolutely no data to back up.
(on the other hand, end year bonuses usually land in December. So maybe that will be a filip as it gets invested on Trading212, alongside the all-nighter clubbing, gambling, etc)
Any chance for you to look at SEIT
Hi mabie41,
I'll try and take a quick look at SEIT, time permitting.
Roland
Any chance for you to look at SDCL Efficiency Income Trust (LON:SEIT)
Discussion underway over on the Investment Trust thread.
timarr
Hi, i can never find the Investment Trust thread. Could anyone provide a link please.
Thanks
https://www.stockopedia.com/co...
Thanks JimMclad
Does anyone know why we have another spike up in Kainos (LON:KNOS) today? The share price had already been strong after slightly better trading news in September (I hold).
SCSW positive update at the weekend perhaps.
Raised to Buy at BofA a late upgrader
Having watched SAGA for the last year or two whilst sub 150p and prevaricated so much that I missed all of this year’s doubling of the share price, I’ve finally pulled the trigger. Late to the party on this one, but hopefully haven’t completely missed the boat.
Me too! Having listened to the Mello presentation I prevaricated, but finally took a small position at 2.68 on 28 November. I was then planning to take a much bigger stake this morning. Timidity has done me no favour!
Click here to watch - presentation at the Sohn Conference.
Password: ilovekernow
that is reassuring to hear a fund manager/CIO say- but I don't feel like a genius for thinking all of what he has been saying for quite a while.
Saga and Spire
I , too, missed Saga because of so much negative commentary and high debt. The same apply to Spire now. Low profitability, high debt and inability to take advantage of the favourable market. I may try to catch a falling knife but at least I am in good company with Christopher Mills who still appears as 5% holder!
You should have bought my Saga (LON:SAGA) shares back in January when I sold at 117.21p( !!) but good luck with the purchase. Nothing looked positive back then - especially the debt.
https://s3.eu-west-1.amazonaws...
Also Graham was subsequently pretty negative on the stock so seemed a good decision at the time (see Jan 30th 2025 report). Further comment 9th April seemed to confirm my decision:
RED (Graham)
More of the same with terrible unadjusted numbers, a balance sheet with negative net worth and an unappealing debt position. High speculative upside but it's a definite RED from me due to the high risk, complexity and what I perceive as very poor quality from an investment point of view.
Graham was certainly right about the speculative upside (!) so my risk aversion has missed an opportunity - again! Having said that even with the near 3x gain this year would still have been below my buy price of 374.90p back in July 2021.
Yes, it was the general air of negativity which kept me out - that and the fact that I normally buy good dividend stocks. The free cash flow, plus the momentum and the twelve moth projections finally persuaded me. I’ve only bought half a position as a trade, so if it does go Pete Tong I will still have my shirt.
Similarly to you ACounsell I bought Saga (LON:SAGA) at 387p in April 2021 (not a good year to buy!) and stupidly watched the share price crater over the next few years - my inaction I guess was due to not wanting to take a loss. Bad trait, must do better and cut earlier. However I didn't sell, and fortunately the share price has now formed a nice bowl and is heading upwards in anticipation of good results for FY26 following the stated upturn in the H1 results and the reduction of net debt. So from being in a position of down over 75% I am now down just 18%, Think I've just used my "get out of jail card"!
Saga (LON:SAGA)
i think thats always been the frustration with saga that there was always potential for recovery - i think they have done material upgrades in last 3 months ref net profit totals if stocky is right. i know when i had been following more closely it was pretty much one way direction of travel with regard to fortunes of the company and i dont ever remember gettting chunky upgrades !!
personally i still dont trust the board further than i can throw them but if that is genguine lfl upgrade ref prospects recently thats good news for holders - big differences betwen £40 mill profits and £24 mill profits for company with the size of debt they have.
as ever with stuff like this its often about the direction fo flow ref news - so hopefully for holders that flow remains in the right direction.
Does anyone know why the sudden jump up Friday and today? The only recent news I could find was of a hedge fund buying in on CNBC.
Saga (LON:SAGA) slightly late to the party perhaps Lord Gnome, but as some big cheese investor once said (I forget who) "I don't mind being late to the party so long as the party is still going on when I get there". I think the Saga party is just warming up.
@JNEO - Good to see the recently acquired CFDS delivering so soon.
Well today is demerger day for Unilever (LON:ULVR)'sThe Magnum Ice Cream Company N.V. Nice to have a new iconic LSE company albeit HQd in The Netherlands.
If an effing 100 year old ice cream company is the best that a sclerotic market can contrive to interest investors, then god help anyone confining themselves to UK investments. A 20 year comparison with the alternatives is, shall we say, as instructive as the mediocre fare being flogged this morning.
I would agree with Roland that often these demergers throw up interesting opportunities. Mainly because many investors follow your lead and simply sell the new holding to not having something else to think about. For a business making a sensible return on capital and cash generative this could be interesting. Obviously if a semi defensive business were sold off ahead of a year where the economy matures then even more interesting. I remain open minded to considering it especially if the assumption is it is not attractive.
I love magnums but they are expensive compared to the copies in Aldi. As my wife does the shopping guess which ones I get!