Daily Stock Market Report (Tue 21st October 2025) - SQZ, HSW, GMS, WJG, BPM, CLBS, CCH, ECOB, MIND, ARB

Good morning! There's a nice mix of trading updates, plus a few acquisitions, to look at today.
All done for now, thanks everyone!
Spreadsheet accompanying this report: link (last updated to: 23rd September).
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Unilever (LON:ULVR) (£114bn) | Revision to timetable for demerger of Magnum due to US government shutdown. Confident of implementing it in 2025. | ||
BHP (LON:BHP) (£109bn) | “A strong start to the year…”, Copper production +4%, steelmaking coal production +8%. | ||
GSK (LON:GSK) (£66.4bn) | “These ground-breaking data show for the first time that cUTIs, including pyelonephritis, can be treated with an oral carbapenem antibiotic as effectively as with an intravenous one.” | ||
Coca Cola HBC AG (LON:CCH) (£12.9bn) | Agrees to acquire 75% of CCBA for $2.6bn, funded by €2.5 billion of bridge financing plus the issuance of new CCH shares worth 5.5% of enlarged group. CCBA is 33% owned by the Gutsche Family from South Africa, and they are selling their entire stake. Philipp H Gutsche says that they will remain invested in Coca-Cola and in Africa through their new CCH shareholding. Completion targeted by the end of 2026. Leverage expected to be towards the top end of their medium-term target range of 1.5-2.0x Net debt to EBITDA. | GREEN (Graham) [no section below] I’ve only mentioned this stock once before: back in Feb 2024, when I was GREEN on it at a share price of about £23. It’s vastly bigger than most companies we typically cover in this report. However, I do like to keep an eye out for news in the soft drinks sector, and this is big news. CCH covers Coke bottling and distribution in dozens of countries including Austria, Greece, Italy, Ireland, Switzerland, many Eastern European countries, Egypt, Russia, Ukraine, etc. Today we get both a trading update with very pleasant organic growth rates baked into forecasts, plus major M&A news. They are buying 75% of the major Coke bottling operations in Southern and East Africa, “Coca-Cola Beverages Africa”, which generated a PBT of $116m in 2024. That makes the earnings multiple look rather large, but hopefully there has been progress in 2025 and into 2026, which could bring the multiple lower. I’m going to leave my GREEN stance unchanged on CCH as its own EPS progress over the last 18 months does justify the share price gains it has achieved, in my view, and the quality of the business is first-class. The Coca-Cola company owns 21%. | |
| SEGRO (LON:SGRO) (£9.1bn) | Trading Update | £22m new rent signed so far in 2025, of which £22m added in Q3. Momentum building in development programme. LTV 32%. | |
Bunzl (LON:BNZL) (£8.0bn) | Quarterly revenue +0.4%. Decline in operating margin moderated. Full year guidance unchanged. | ||
South32 (LON:S32) (£7.2bn) | FY26 production guidance remains unchanged. | ||
Sigmaroc (LON:SRC) (£1.25bn) | Strong Q3 performance underpins confidence in full year expectations. Revenue +6%, adj. EBITDA +17%. EPS to be ≥ 9.5p. | ||
Atalaya Mining Copper SA (LON:ATYM) (£906m) | Production supports full-year guidance and cash position grows. “In a strong position to deliver on its full-year targets.” | ||
Serica Energy (LON:SQZ) (£693m) | The operator has ramped up production, which has now reached a rate of over 25,000 boepd net to Serica. Auctus Advisors FY25 production estimate unchanged at 27.5mboe/d. | AMBER/GREEN (Roland) [no section below] Some good news for shareholders today as Serica announces that Triton production has returned to expected levels following the latest breakdown. However, it’s worth remembering that group production is expected to drop again in November when repairs start to Dana-operated Bittern field infrastructure. These subsea pipework repairs are expected to take three weeks and result in a temporary reduction of over 20,000 boepd net to Serica. The bigger question now is whether TotalEnergies and NEO Next will exercise their pre-emption rights over Serica’s plan to acquire gas field Culzean from BP – see here. If the deal goes ahead, it could be very significant for Serica and dilute the group’s dependence on ageing, non-operated infrastructure such as Triton. Today’s news is better than it might have been and Serica does continue to look decent value, in my view, with a possible 9% dividend yield. While recognising the risks, I think it’s fair to maintain a broadly positive view here – a position reflected by the stock’s Super Stock styling. | |
Caledonia Mining (LON:CMCL) (£522m) | Quarterly gold production of 19,106 ounces (Q3 2024: 18,992 ounces). Reiterates guidance of 75,500 - 79,500 ounces. | ||
ITM Power (LON:ITM) (£482m) | New flagship 50MW full-scope green hydrogen plant is now available to customers, priced at €50m. | ||
NCC (LON:NCC) (£454m) | Adj. EBITDA to be c. £43.5m, in line with expectations. Revenue down 2.5% on a constant currency basis. | ||
XP Power (LON:XPP) (£280m) | Full year outlook is in line. Material step up in profitability in Q3, expected to be sustained through year end. Q3 order intake +18%. | ||
B.P. Marsh & Partners (LON:BPM) (£242m) | NAV +7.1% in H1 to £349.5m. Total shareholder return 9.5% including dividends. Liquidity £52.6m at the end of H1, liquidity now £3.65m. | GREEN (Graham) The company has been putting its excess cash to use in a variety of ways, including dividends and new investments. None of the new investments are worryingly large - which means that portfolio diversification can have a chance to improve. At a 26% discount to fully diluted NAV, I like the valuation on offer here for one of my favourite UK companies and a proven compounder. Past performance is still no guarantee of future performance, even with exceptional management teams such as this, but I’m happy to stay GREEN on BPM. | |
| Supreme (LON:SUP) (£197m) (announced mid-morning yesterday) | Acquisition of SlimFast UK & Europe | Trade and selected assets of SlimFast UK/Europe for £20.1m from Glanbia (LON:GLB). Reported 2024 rev £25.5m & adj gross profit of £9.7m. | |
ASA International (LON:ASAI) (£194m) | Loan portfolio grows 3% in Q3, +32% year-on-year. Stable loan portfolio quality. | ||
Gulf Marine Services (LON:GMS) (£172m) | Net leverage ratio 1.63x (a year ago: 2.31x). Revenue +10%. Highly confident in achieving adj. EBITDA guidance ($101-109m) and leverage target. Zeus FY25 & FY26 EPS forecasts unchanged. | AMBER (Roland) Today’s nine-month results are certainly not bad and show fleet utilisation recovering, after the geopolitical disruption suffered in the Middle East in Q2. However, the standard quarterly reporting structure does mask a 20% decline in the order book over the last six months. I also don’t feel there’s much clarity on future strategy regarding the development of the fleet. Today’s update follows a 20%+ cut to 2025 and 2026 earnings forecasts in September. Broker forecasts are unchanged today, but on balance I’d prefer a little more clarity about outlook and strategy before reverting to a positive view, so I’m remaining neutral today. | |
Brickability (LON:BRCK) (£172m) | H1 FY26 in line with exps, with rev +4.9% to £347m and adj EBITDA c.£28m. Greater H2 weighting due to building safety delays. FY exps unchanged. | ||
Hostelworld (LON:HSW) (£158m) | Acquiring US B2B event platform OccasionGenius Inc for $12m. Provides city-by-city catalogue of attractions through an API. Forecast ARR of €1.5m. | AMBER/GREEN (Graham holds) Downgrading this share to AMBER/GREEN as the acquisition seems overpriced and unnecessary to me, and is being paid for with bank debt. At least the debt is not too expensive (2% over EURIBOR) and should be paid back from profits over the next few years. | |
Trifast (LON:TRI) (£112m) | H1 FY26 in line with exps, rev -6.4% due to softer demand. EBIT margin improved to 6.3%, FY exps unchanged. | ||
Savannah Resources (LON:SAV) (£96m) | Eight claims in total have now been dismissed with four remaining cases, none of which affect progress with the Barroso Lithium Project. | ||
Pharos Energy (LON:PHAR) (£84m) | Six-well drilling programme underway to increase production from existing fields (TGT) and develop CNV. | ||
Watkin Jones (LON:WJG) (£81m) | FY25 rev of c.£280m and adj op profit in line with exps. Net cash £70m. Timetables extended on some transactions, but strong pipeline for FY26. | AMBER/GREEN (Roland) [no section below] Today’s update suggests this student property specialist could currently have net cash close to its £81m market cap, with net cash of £70m at the end of September and “a significant portion” of a £10m payment received in early October. More broadly, the half-year accounts showed a net asset value of £133m at the end of March. As a value investment, I think this could be of interest. The shares trade 40% below last-reported NAV of 52p per share and debt levels are now quite low. The main uncertainty seems to be around the near-term outlook. Management admits today that it’s seeing delays on some transactions. Consensus forecasts on Stocko suggest earnings of just 1.2p per share for FY26 – equivalent to a P/E of 26. The company says it’s still confident about the medium term, with strong structural drivers. On the other hand, paid research provider Progressive has opted not to provide FY26 forecasts in today’s note, instead preferring to wait for the FY25 results to be published (probably January). At this point WJG will be a quarter of the way through FY26. For a property developer that should presumably provide a good level of confidence in the outlook, but it’s a shame there’s not more visibility now. Despite this risk, I can’t ignore the apparent value here. I also believe the business should be able to make some recovery over time, even though I suspect profitability will remain lower than in the boom years before interest rates rose. I’m going to leave my previous view unchanged today. | |
Agronomics (LON:ANIC) (£66m) | PrimaColl (vegan collagen) has received FDA GRAS clearance (Generally Recognised As Safe) and can now be marketed in USA. | ||
Celebrus Technologies (LON:CLBS) (£57m) | H1 results to be in line with exps, w/ revenue approx $10.3m and adj pre-tax loss of $1.4m. ARR +14.7% to $15.6m in H1, net cash $27.2m. | AMBER (Roland) [no section below] As I discussed earlier this year, Celebrus’s decision to move from annual licences where revenue is recognised on day one to monthly recurring revenue is resulting in a painful decline in revenue and profit. In effect, profit previously recognised upfront is now being pushed into the future. The upshot is that profit and revenue is expected to return to comparable levels from FY28 or FY29 onwards. In terms of trading, today’s half-year update seems fine to me, with annual recurring revenue up by 14.7% to $15.6m. Net cash continues to provide a substantial safety buffer, too. The StockRanks are neutral on Celebrus (SR 48) and I am also leaving my neutral view unchanged today for two reasons. Firstly, profits are expected to be minimal in FY26 and FY27, with material earnings only returning in FY28. I think that deserves a measure of caution on valuation. Secondly, a decision to stop selling third-party software to one of the company’s largest customers (previously a big chunk of revenue) is also due to be working through the accounts in FY26. What I want to see in order to turn positive is a) continued ARR growth and b) evidence the company is starting to generate free cash flow again under its new accounting policies. Hopefully the company will provide more guidance on FY26 with its H1 results in December. Ahead of this, I’m leaving my AMBER view unchanged. | |
Gelion (LON:GELN) (£44m) | dentity of battery manufacturer in 16 Oct RNS was TDK. Aiming to use Gelion’s CAM technology to develop new battery products. | ||
Argo Blockchain (LON:ARB) (£28m) | SP +3% Existing shareholders will be diluted to a 2.5% equity interest following the restructuring. Delisting from LSE but will maintain Nasdaq listing. | RED (Graham) [no section below] We saw serious dilution on the way here. The shares are up today on confirmation of the level of dilution (existing shareholders left with 2.5% of the company) along with news that the LSE listing will be abandoned in favour of a NASDAQ listing. This has been a basket case among speculative UK stocks for some time, but perhaps a new American audience will find it interesting. | |
Eco Buildings (LON:ECOB) (£15m) | SP +75% Manufacture and supply 20,000 homes in Chile, approx €420m revenue over seven years, Govt-backed, delivery from 2026. The company says it plans to set up a factory in Chile in Q2 26 and complete an initial delivery of 607 homes in 2026, funded by a 50% upfront deposit of €12.75m. | RED (Roland) [no section below] Today’s news has put a rocket under the share price of Albania-based Eco Buildings. Today’s contract award appears to have followed the construction of two show homes in Chile earlier in this year, which was reported here. The terms of this deal mean the company will receive 50% upfront for all the properties it’s contracted to build, with the remainder due on delivery and acceptance by the housing authority. This model could perhaps provide the upfront cash Eco Buildings will presumably need to mobilise on this scale. But I think it’s worth noting that this business reported revenue of just €1.8m in H1, with negative free cash flow of c.€1.3m. The H1 balance sheet also showed cash of €183k and net debt of nearly €6m at the end of June 2025. In other words, this is a small, loss-making business with no track record of delivering large-scale construction projects in Chile (or anywhere else). Even in a best-case scenario, I’d expect some growing pains. Remarkably, the company is also in the process of setting up subsidiaries in Senegal and Sudan, while also building an apartment block in its home market of Albania. In addition to this, Eco Buildings is also embroiled in a €195m arbitration case (using litigation funding) in Kosovo, relating to its former identity, Fox Marble. It’s not clear to me how the company will bridge the cash flow shortfall I expect to see ahead of receiving the first advance payment in Chile. I would not be surprised to see a placing underway in the next few days, to capitalise on today’s share price gains. The StockRanks see this as a Sucker Stock (SR 9) and I agree. It’s possible that Eco Buildings will now evolve into a profitable, mid-sized company, but I would want to see more evidence of progress (and do much more research) to convince myself of this. At this stage, I see this as a speculative situation that could go either way. | |
Mind Gym (LON:MIND) (£14m) | Underlying H1 rev -16% to £13.5m, adj EBITDA loss of £1m. Outlook in line with exps w/ H2 weighting. | RED (Graham) [no section below] This is going through a transformation to reboot performance - which is ironic, as the point of MindGym is to help boost the productivity and performance of other businesses. Revenues have been falling for a few years now, and the company is loss-making even at the adjusted EBITDA level - something I always view as a red flag, seeing as adjusted EBITDA profits are the easiest type of profits to make. They have net debt of £1m and are cutting costs, which clearly makes sense in circumstances. However, I wouldn't bet on a turnaround until there are tangible signs of success. It is forecast to make a profit in FY March 2027; for me, it's too soon to bet on that happening. At least the CEO and his wife are well-aligned, owning 55% of the business. | |
Chesterfield Special Cylinders Holdings (LON:CSC) (£11m) | FY25 revenue of £16.5m and adj EBITDA of c.£0.8m, ahead of exps. Positive outlook for FY26. |
Graham's Section
Hostelworld (LON:HSW)
Unch, at 126.1p (£158m) - Acquisition - Graham - AMBER/GREEN
(At the time of publication, Graham has a long position in HSW.)
My initial reaction to this news is negative, because I’m generally looking for organic growth at my investments rather than M&A. Ask an academic, and they’ll tell you that most acquisitions destroy value (for shareholders of the acquiring company, not the target!).
But I’ll try to keep an open mind as I explore this news. The market doesn’t seem to hate it at least, with Hostelworld’s share price unchanged.
What Hostelworld is buying: OccasionGenius Inc.,“a US-based B2B event discovery platform”.
Description:
OccasionGenius empowers businesses to inspire their audiences with a global event dataset delivered via API, comprising a rich, city-by-city catalogue of local 'Things to Do' and a unique global dataset of 'travel worthy' events that inspire travellers to book trips.
Checking OccasionGenius’ website, I see that they target a wide variety of industries including hotels, airlines, residential property, etc. For a hotel business, for example, they can help motivate prospective guests to make a booking, by showing them key events on certain dates.
So why is Hostelworld buying OG instead of simply using it?
Strategic Rationale:
The acquisition accelerates the development of our events capability, giving us immediate access to structured, global event data; content that would otherwise take years to build organically. By integrating this at scale, we expand from accommodation into events, strengthen community connection, and advance our broader social monetisation strategy.
They describe three pillars: 1) enhancing their existing social travel platform (travellers have more reasons to connect with each other), 2) accelerating growth by inspiring new trips that wouldn’t have happened otherwise, 3) creating a unique data set that combines their existing bookings data/social network with event data.
Price: $12m (that’s equivalent to ~€10.3m) on a cash-free, debt-free basis.
Funding: a €10.3m, 3-year loan facility with AIB, paying 2% over EURIBOR (EURIBOR itself is about 2% these days).
Valuation multiple: OG’s forecast ARR is €1.5m by year end, so Hostelworld is paying 7x ARR. That’s bang in the middle of the range of possible ARR multiples, with 6-8x ARR being an average range (don’t get me wrong - this is still a premium valuation, but in the software/SaaS world, it’s considered normal).
CEO comment:
"The acquisition of OccasionGenius is a significant development which positions Hostelworld as the first social travel platform with an integrated offering of social networking, event discovery and accommodation. This acquisition allows us to immediately supercharge our platform with a wealth of content that would take us years to build organically and enhances value creation opportunities for our shareholders."
Graham’s view
I’m trying to justify this acquisition. My first instincts are that Hostelworld could have simply been a major customer of OG, using it across its network, rather than buying the entire company. Or even better, created its own version of the same thing, using its existing cash resources.
But then Hostelworld does have 17,000+ hostels on its platform, in pretty much every corner of earth. Being a customer of OG would mean using all of OG’s global data. Perhaps it really was simpler to buy OG than to pay for all of its data on an ongoing basis? That said, how “global” is OG’s data, really?
I’m also saddened to see the company going back into debt, when it took so long and it experienced so much risk in the effort of trying to get itself out of debt, not that long ago.
Here are my summarised views around this deal.
First, the positives:
Simplicity. Gets all of OG’s data on an ongoing basis. Could be the spark that helps ignite faster growth?
The debt is not expensive at 2% over EURIBOR.
HSW is forecast to generate €14.5m of net income this year, and €18m next year. So it should be able to pay the loan back without difficulty. Leverage multiple is “comfortably below our target of 1x”.
Some of the negatives:
Hostelworld are paying a premium SaaS/ARR valuation multiple for this, when their own shares only trade at 10x earnings and at a price to sales multiple of 2x.
They are voluntarily going back into debt, although this is consistent with their leverage “target” of 1x.
OG is listed as only having 2-10 employees on LinkedIn. It seems to me that Hostelworld could have built their own operation doing the same thing for a tiny fraction of the price paid. They say that getting the same wealth of content “would take us years to build organically”.
I’m inclined to sell my Hostelworld shares today, but I haven’t made up my mind yet.
As far as our colour system goes, I’m downgrading from GREEN to AMBER/GREEN.
I hope I’m wrong, but I’m inclined to think as soon as Hostelworld started building up a net cash balance, the money started to burn a hole in their pocket, and they needed something to spend it on. In formal financial terms, this is called having “a target leverage ratio of 1x”. But is it really necessary for a company like this to run on debt? I don’t think so. If they really wanted to get rid of €10m, they could have expanded the share buyback or launched a tender offer.
I hope the acquisition works out, but it gets the thumbs down for me, as I fear that it’s overpriced and unnecessary, and bank money is being used to pay for it.
B.P. Marsh & Partners (LON:BPM)
Up 1% at 675p (£244m) - Half Year Results - Graham - GREEN
BPM always provides plenty of detail on its investees - it’s a specialist investor in the insurance sector - but what interests me most is the big picture.
And the big picture remains as impressive as ever:
9.5% shareholder return in H1, made up of both NAV growth and dividends.
NAV growth 7.1% to £349.5m.
NAV per share grows to 956.1p; the current share price is a 29% discount to this level.
Diluted NAV per share 909.8p, the discount to this figure is 26%.
We did have a H1 update in September which already disclosed the H1 cash figure of £52.6m (July 2025). The current cash figure is given today as £36.5m.
The company has been cash-rich ever since a large disposal triggered buybacks, a new dividend plan, and various new investments.
(Please note that I have completely different expectations of BPM vs. HSW, in terms of cash management and M&A - one is an investment company and the other is not!)
Comment snippets from Brian Marsh OBE, Chairman. He first points out that £8m of dividends have been paid out to shareholders in H1, and concludes his statement as follows:
…we entered the second half of our financial year in an exceptionally strong position in terms of portfolio holdings and NAV. Our new business pipeline is growing and, with our considerable available cash, we are well placed to make further new investments.
As the insurance rating environment continues to soften, we have balanced our portfolio towards supporting specialist teams that can deliver market-beating returns. This is consistent with what has historically been the signature B.P. Marsh operating model of selecting compelling opportunities in insurance distribution."
Activity: they made three investments in H1 and already made four investments so far in H2. The sizes of these investments vary, but the max size seems to be £10m. I like the discipline: while BPM’s portfolio does occasionally become rather concentrated, they aren’t betting their success on any of these new ideas.
Secondary placing: BPM reminds us that a major shareholder sold its remaining 9.8% stake in BPM in August. Buyers included the investment firm Wellington:
This successful exit and diversification of our investor base, including increased holdings by high-quality investors such as Wellington, reinforces market confidence in the Group's long-term growth strategy.
Portfolio breakdown
Here’s a nice image of the portfolio:
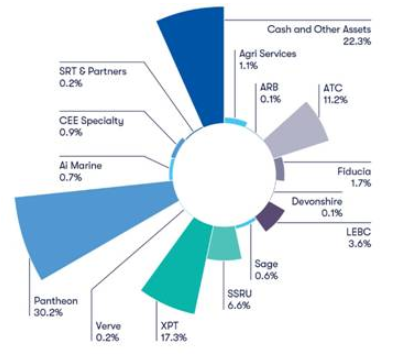
The main investment is Pantheon:
Pantheon is a UK-based specialist insurance broker specialising in property, casualty, professional lines & reinsurance and delegated authority established in partnership with Robert Dowman. Pantheon acquired 100% of the share capital of the Lloyd's broker Denison and Partners Limited.
Comment on insurance market trends from the CIO: rates are soft (down 7% globally in H1), with plenty of capacity, and this trend is expected to continue. But M&A is buoyant and the CEO says there will be “continued opportunities for… investee companies to expand and develop, either organically or through selective acquisition.”
Graham’s view
This is not the most exciting share in the market but it knows how to make money for its investors, as it has done for many years. It’s a good example of a compounder:
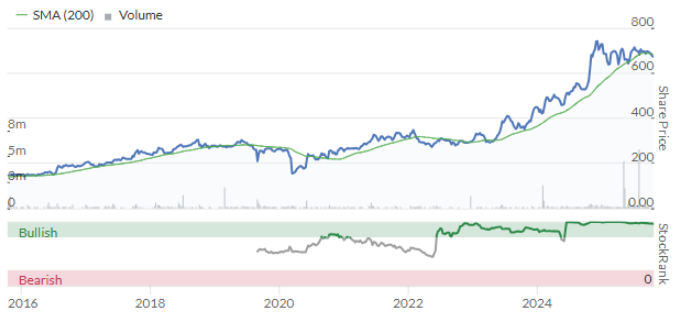
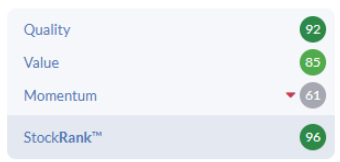
In StockRank terms, it’s a 96, and a Super Stock, and it passes 10 bullish stock screens.
That being said, the sparkling results of FY Jan 2025 are not really repeatable, as they came from an extraordinarily successful disposal. Disposals like that aren’t going to happen every year.
Even so, this is one of my favourite shares and I’m tempted to open a fresh position.
Roland's Section
Gulf Marine Services (LON:GMS)
Up 7% at 16p (£184m) - 9M 2024 Results - Roland - AMBER
I find it’s often helpful to consider the disclosure in a trading update – the information the company is choosing to make prominent and that which it is seeking to obscure or exclude. Shaping the narrative in this way often helps companies to create the impression they want, while distracting investors from other less favourable metrics.
Quarterly comparisons can be an example of this. The standard convention is to make comparisons with the same quarter one year earlier. This may be appropriate for some businesses, especially where there’s seasonality. But it can also mask a sequential change over previous quarters.
Today’s update from liftboat operator Gulf Marine Services is a good example of this. Management reports an order backlog of $457.5m at the end of September, just 2% lower than on the same date in 2024.
Broker Zeus helpfully describes this as “broadly steady” in a new note today. But if we look at the change in Gulf Marine’s order backlog sequentially in 2025, we see that the pipeline of secured future work has fallen by 20% over the last six months:
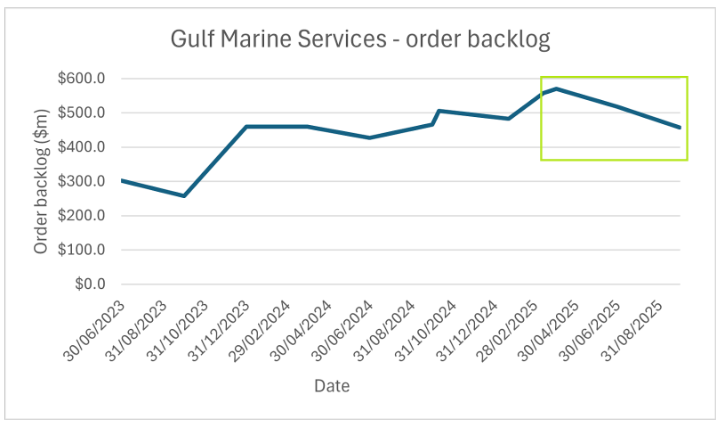
Admittedly, contract wins can be lumpy. I recognise that this may not be a long enough decline to view as an established trend. But while the company still has around 2.5 years’ revenue on its order books, I am not sure I’d describe the order backlog as being stable this year.
I should emphasise that I am not suggesting that either GMS or Zeus are being misleading. Today’s update is perfectly standard quarterly reporting. But I think it’s an example of when we can gain extra insights by thinking about other comparisons we might make, rather than relying solely on those highlighted by the company.
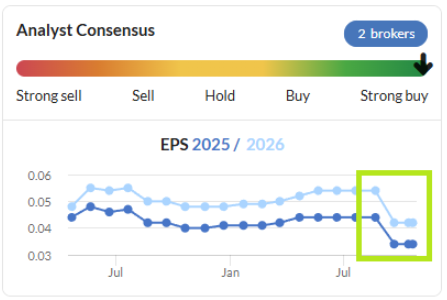
Unfortunately, Gulf Marine has previous form when it comes to selective disclosure. When I wrote about the company in September, management were keen to highlight a small increase to adjusted EBITDA guidance for the year.
What they didn’t mention in the RNS was a 20%+ cut to earnings forecasts for both 2025 and 2026. This was only visible to investors with access to broker notes:
Moving on, let’s take a look at the remainder of today’s third-quarter update.
9M 2025 results summary
Gulf Marine’s standard practice is to report nine-month figures rather than Q3 numbers. So these results cover the nine months to 30 September 2025::
Revenue up 10% to $138.3m
Adjusted EBITDA up 7% to $81.5m
Net debt down 22% to $172.2m
Finance costs down 35% to $11.6m (9M 24: $17.9m) due to lower interest rates & refinancing
Net leverage ratio: 1.63x (9M 2024: 2.31x)
Fleet utilisation down 4% to 88%
Average day rates up 10% to 36.0k
These seem pretty solid figures to me, on the whole. Day rates have continued to rise as vessels roll off lower-cost contracts onto new contracts. When paired with the reduction in finance costs, I’m confident debt levels should continue to fall towards the 1.5x leverage threshold at which the company has promised to consider shareholder returns.
Although debt reduction slowed slightly in Q3 compared to the same period in 2024, this is understandable given the cost of the Saudi Arabia tax settlement earlier this year.
One point that interested me is whether the geopolitical disruption flagged up in June persisted in Q3. This was said to have affected Q2 utilisation, but my sums suggest utilisation did recover in Q3:
H1 utilisation: 87% (H1 24: 91%)
9M utilisation: 88% (9M 24: 92%)
Q3 utilisation: 90% (Q3 24: 94%)
Outlook: CFO Alex Aclimandos says GMS remains on track to meet 2025 objectives, with unchanged EBITDA guidance of $101-109m.
This forecast implies Q4 EBITDA of $23.5m at the mid-point, which is lower than the quarterly average of $27.2m so far this year, so the guidance seems realistic to me.
Today’s broker note from Zeus has also left EPS forecasts unchanged:
FY25E EPS: 3.3 cents
FY26E EPS: 3.9 cents
These forecasts price the shares on c.6x 2025 earnings, falling to a P/E of 5 for 2026.
Roland’s view
Gulf Marine is continuing to deliver on its strategy of deleveraging, which should result in a gradual increase in net asset value. Despite some dilution from new shares issued through historic warrants, this has shown up in the accounts as expected:
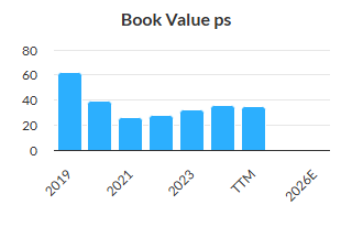
In theory, this NAV accretion should support a share price re-rating over time. In practice, the market has remained a little reluctant over the last couple of years:
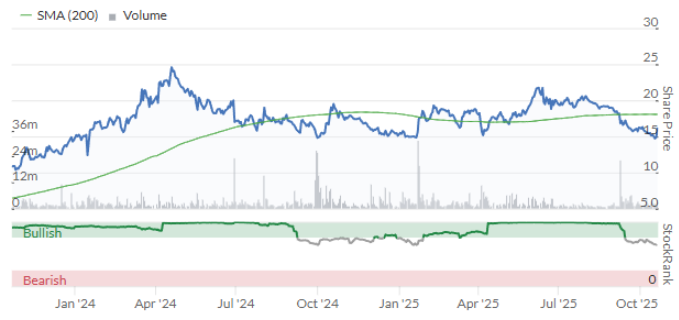
For this reason, GMS shares continue to trade at a hefty 40% discount to book value.
Investors considering the stock today need to ask if this is a fair valuation, or if the shares are too cheap.
In my view, there probably is some moderate value here. But I don’t think GMS is as cheap as it might seem. I’m keen to see if the decline in order backlog continues or reverses and I cannot ignore the reality that at some point, management will have to decide whether to commit funds to fleet expansion and/or renewals.
Mistiming fleet upgrades was the original cause of the company’s debt problems – but the risk remains for the future. Even if fleet investment is managed more successfully than last time, low returns on assets suggest to me that a discounted valuation is probably fair.
I took a neutral view on this stock in September, due to the cut to profit forecasts for 2025 and 2026. Today’s update is in line so I’m left with a difficult choice on whether to revert to an AMBER/GREEN view, or stay at AMBER.
It’s a finely-balanced decision and I suspect some readers may disagree, but I’m going to stay neutral for now until there’s more visibility on the outlook and strategy for 2026.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

46 comments
Do we have any Playtech (LON:PTEC) experts who can shed any light on today's shenanigans? I don't hold, but I'm curious.
Playtech (LON:PTEC)
here is what copilot throws up - i have no idea how accurate this data might or might not be - at face value it kinda suggests playtech may have been the puppetmaster here ref the original smears - i think who knows if i have read correctly or not.
all is fair in gambling love and war - til its not
Background
In December 2021, Evolution filed a defamation lawsuit in the New Jersey Superior Court against law firm Calcagni & Kanefsky LLP and unnamed parties.
The case centered on a 2021 report submitted to U.S. gaming regulators and leaked to media (including Bloomberg) that accused Evolution of operating in sanctioned and unlicensed markets. [igamingfuture.com]
✅ Key Allegations
Evolution claims the report was:
“Highly inflammatory and knowingly false”, intended to damage its reputation and business for anti-competitive reasons.
Produced by Black Cube, a private intelligence firm hired by Playtech Software Limited (a Playtech subsidiary).
Court filings show Playtech allegedly paid over £1.8 million to Black Cube for the investigation. [gaminginte...igence.com], [igamingnews.com]
Black Cube allegedly used:
False identities and disguises to meet Evolution employees.
Secret recordings, later edited to create a misleading narrative. [igamingnews.com]
✅ Legal Findings So Far
New Jersey and Pennsylvania regulators reviewed the allegations in 2024 and took no enforcement action.
In September 2025, the New Jersey Superior Court ruled the report was:
“Objectively baseless” and “not truthful”.
Ordered Black Cube to reveal its client, which was confirmed as Playtech. [igamingfuture.com]
Evolution amended its lawsuit in October 2025 to add Playtech as a named defendant.
Litigation is expected to continue through 2026. [investing.com]
✅ Playtech’s Response
Playtech denies all allegations, calling them “wholly untrue.”
It claims the investigation was lawful, aimed at verifying “credible concerns” about Evolution’s compliance in restricted markets. [readwrite.com]
Hello fellow holders of gold mining shares. Like me you will have been more than a little disconcerted by what appears to be a sharp correction in the price of this category of shares over the last three days or so, following their almost daily drift higher and higher in value, as the increasing price of gold makes the companies mining it more profitable than we might have ever believed before Trump's tariffs and cryptocurrency ventures undermined confidence in the US $. With the price of Gold showing no sign of falling any time soon and the external influences forcing it upwards still in place, I am left guessing that the current fall in price is caused by investors taking their gains fearing we are too close to a peak for comfort, or a realisation that F.O.M.O has played too heavily in the pricing of gold miners share pricing, since I notice that each of SRB, MTL and THX which I hold are affected equally without any warning news of difficulties in operations. For myself, new to both DIY investing and Stockopedia, my instinct is to view this as a glitch and continue to hold for the longer term. I am always interested to hear what others may think
I view gold as a long term insurance policy and tend not to trade. I might trim at the margin, for instance after very strong upturns, but generally don't pay too much attention to the current price. The factors that have driven gold higher have certainly not gone away - central banks will continue to shift out of US dollars while the astronomical levels of US debt is only going in one direction. These are multi-year trends so I would just hold tight - the recent fall is almost certainly just some soeculators taking profits.
Any imapct on your YTD performance is basically irrelevant (unless you need the cash right now of course) . That's the beauty of being a ptivate investor - you don't need to constantly report and justify your investment performance to jittery clients. I'm keeping 10-15% of portfolio in a mixture of physical gold, silver band golden miners.
There's an almost 5% drop in the Gold price today, but maybe as you say profit taking is behind the even bigger drop in the Miners - one day I'll learn to top slice a profit
Personally I don't see any change to the longer term investment case for Gold, just because there might be a temporary lull in animosity between Trump & China.
Miners are a geared play on the gold price so you'd expect a roughly 10% fall in the miners today. Pretty confident they'll be meaningfully higher a few years from now so wouldn't pay too much attention to short term volatility (both on the upside and downside)
Every now and then Serabi Gold (LON:SRB) corrects down to the 50 day moving average. That’s generally when I add to my position. That’s exactly where the price is today. My guess is that it will bounce from the MA but you can never be sure.
Serabi Gold (LON:SRB) down 10% today, anyone have any info?
Gold price is down so virtually all gold plays are also down.
LON.SILG - (etf focussed on silver producers) is down even more than Serabi at -12%
Between then they've certainly taken the shine off my portfolio's YTD performance
On Beach group (LON:OTB) profit warning yes, but looking interesting
A lot of the holiday companies are looking cheap right now - look at the Jet2 (LON:JET2) metrics. Part of the sector issue seems to be compressing profit margins and also worries about the economy. I also wonder if the warmer weather in the UK deterred some travellers from going abroad.
I know some companies have also warned about later booking trends reducing forward visibility. I am a bit more relaxed about this: I had a long conversation with a major listed travel company's senior marketing lead and they were saying this has been the case since the pandemic. Consumers built up habits of booking later to check COVID restrictions, and this behaviour has stuck with consumers to some extent now checking on weather predictions and price. It might reduce forward visibility but none of the companies' results have indicated any significant slowdown in Brits' appetite for travelling abroad.
£JET
i am equally relaxed jet2 has great balance sheet last time i looked and p/e of 6.2 that leaves enough in the tank for material dropoff in profits to not really push p/e over 10.
i do understand the caution here - its often feast or famine in life - so whilst companies would have been very cautious exiting covid ref capital deployment - its easy to get suckered into boom times are here to stay mentality - and glossing over all the extra capacity coming on stream from others and presuming last years custoemr will come back and pay top dollar.
I get the impression JET2 have everything covered - other than the unknown element of - if they have had couple of good years making hay - how much ifs left when the cow has eaten all the hay.
I would happily top up here at todays price as things stand - is it safer to wait and see trend ref next trading update ? - probbaly ?- who knows this share has been up and down like a yoyo over the last couple of years - momentum does lpok particualrly poor at present - thats probably not a shocker.
The stocky rankings are having wobble here - is that predicting doom and gloom to come - or is it just reflective of temporary poor shareprice trend that will reverse when momentum turns ? and the ratings will climb back up
is there a natural supporrt level here ? it does seem to have stayed above 1250 -1300 mostly since early 2024 - so would be intested to know if there might be some support that might suggestn downward trajectory would stop.
I agree and struggle to understand why they are always cautious with their announcements at the end of the day we all know people have the option to go/not go on holiday. No one can predict the future in that respect. I think they should be more positive about their business and try to get the share price more stable.
Did anyone see Panaroma last night on house building? Everyone in the industry said no chance to the 1.5 million target and seeing all the red tape makes me wonder how any housing gets passed at all.
Thinking maybe RR will pull out something massive at the budget to try to get the sector started as the economic benefits are so huge and clearly she needs some growth from somewhere. Maybe that's just wishful thinking.
Yes - the section about Vistry was an eye-opener - had not appreciated they are such a major player. And of course the point about racking up production of bricks (which seems to be discussed a lot on this board) But will the government actually do anything to get things moving -
Yes. No surprise but the 1.5m won't happen. The Vistry factory looked impressive though.
It is so difficult though. Planning processes would need to be changed, but any change is subject to challenge, judicial review etc. For example, right now any person can apply to stop any development and the legal costs of doing so are capped at a tiny figure (5/10k). So any development of any size can be halted for that cost. The waiting list for court hearings is 6 months plus, and then there are appeals etc.
Then we need many more builders. And the rates for dumping rubble are about to increase, adding £30k to the build costs of an average house.
You should read up about the Fourth Turning. It's a bit mumbo-jumbo but the basic theory is that human institutions have a natural span of 4 generations, with one creating institutions (1945-65), the next building upon them (65-85), the third exploiting (85-05) and the fourth experiencing a crisis (05-25). We are at the point where most things were created after the Second World War (NHS, planning system, UN, international institutions etc) and they are all in crisis but cannot be reformed because they are so caked in their own bureaucracy and procedures.
Are Keir and Rachel the visionaries that can build a system for the next 4 generations? Err, no.
great points donald pond.
Are Keir and Rachel the visionaries that can build a system for the next 4 generations? Err, no.
i think Keir or R or both have said they are going to cut red tape for small business - while at same time forcing small business to submit 3 monthly figures under mtd from next april using software they may not be familiar with - its a nightmare at companies house id checking and the like - people have gateways coming out of their ears - reference numbers coming out of their ears - so there is complete mimatch between what they are doing and what they that they will do. how many different id verifications do we need.
ceople have to wait 6 months for tax refunds and avt registrations are routinely getting hacked as anyone can seemingly get data needed to hiack a new vat number online.
That might be corrected if they scrap mandated mtd and make real improvements - building housing theough is probbaly the real bellweather and proof of then pudding - they need radical; change and change quickly to get anything like targets. If they are going down that route they need to free up land for housing do it quickly and while they are doing it why not bank the uplift in value to then government. We probably need a series of new towns like the 70's or whatever - done with minimial hassle. Can the current lot deliver ?? - who knows we may know more after the budget. I have little faith in any political party being able to act efficiently in anything they do.
Wouldn’t the Panorama programme make a great deal more sense if we work on the basis that the Labour government is just over one year into a deliberate 5 year mission to destroy all aspects of the UK economy, albeit they continue to pretend that this is not the case. Unfortunately every action they take is anti-UK and we should expect several more years of this drivel
Sounds like there is a bigger Horizon looming. Box ticking with one hand, a reference book in the other, no work getting done, what could possibly go wrong?
I wonder how that 1970's new town Washington is getting on today. My next door neightbour got a grant for a move up there. He didn't stay long and in the interim the company I worked for toyed with the idea of creating a subsidiary factory there. Didn't happen.
They finally have plans to link Washington up to the metro system now - I saw a few comments last week saying that some areas of Sunderland were surprisingly nice - north east can be very localised there are the really rough spots - there is certainly plenty of areas with posh new estates and some really nice places not far away from the less nice places
Hi rmillaree,
Completely agree on the self defeating bureaucracy of this government. My partner is a practicing accountant and the ICAEW has just notified accountants that the compliance regime is to be centralised under the FCA (OMG!!) but the ICAEW will also continue to monitor compliance matters. Additional bureaucracy and we know how effective the FCA are at doing their current job properly - not at all!!
General Electric Co (NYQ:GE) BEAT
Coca-Cola Co (NYQ:KO) BEAT
Philip Morris International (NYQ:PM) BEAT
Halliburton Co (NYQ:HAL) BEAT
Rtx (NYQ:RTX) BEAT
Just educating everyone that during the dot com bubble bull market the Nasdaq was up 500%!
We are about 85% at the moment and the big companies investing in AI are all cash cows.
This US bull market has only started.
All the best
Naysayers repeatedly saying "crash coming " etc etc
Not before civil war and insurrection though
Agree with your skepticism about the Hostelworld (LON:HSW) M&A Graham. M&A is a wonderful thing in certain sectors and certain situations, this reeks of just buying a business you don't understand and super optimistically thinking it will add lots of value for you that it wont. I have been on the buy and sell side of a few M&As and they're almost always tragic ideas by the buying side, that don't really understand what they're doing, with the people that are in the detail too far from being able to really influence (and usually kept out of the loop until its basically a done deal) and then just trying to make it not be a total disaster afterwards.
With AI, wouldn't it be possible to write a prompt, that then scans the web for all the events being promoted in a city, and then rank them by "size" / "popularity", and then voila.... you have a list of the "Top X Events this week" in this city, that you can use.
Cheaper than an M&A for Hostelworld (LON:HSW) .....
Brickability (LON:BRCK)
i have low conviction hold here pe is under 6)
ref todays update - its a mixed bag.
Main thing is that they are on track to meet year end expectations - thats by far the most important thing so good news here - imho all they need to do is churn out promised "clean" profits in 2026 and 2027 and they will be in good position if there is no material decline thereafter. So in the main job done.
Looking at the detail they say they are on track but ref contracting they say.
The continuing delays being experienced by the BSR have affected the phasing of some of our fire remediation projects in the Contracting division such that we now expect a greater proportion of the division's profit to be delivered in the second half of the year when compared with the prior year.
If they are behind plans - are they really on track? Its the old chesnut of we hope we are on track but we have much work to do - if they do deliver near year end bombshell - well they have warned us today thats a possibility.
imho its always more risky with contracting contracts like that too - as they can be large value and clients can be a right pita. So when stuff like that does go wrong its often not a minor miss.
Hey ho holders needs top make their choice here if there is any risk - to me its risk that they will fall short rather than outperform here - i prefer cautious outlook rather than 100% glass full type.
Net debt as at 30 September 2025 is expected to be approximately £67.0 million on a pre-IFRS basis (H1 FY25: £56.3m), after making deferred and contingent consideration acquisition payments during the first half of £7.2 million.
Net debt progress is still going backwards - thats partly got legitimate excuses with chunky contingent considerations and dividend (£6 mill). In theory contingent consideration aside debt should start to fall pretty quickly - as of now there is zero sign of that happening unfortunately. I dont have any specific reasons to worry here - but i would much rather have seen it stabalise than go up - they are meant to be making getting on for £15 mill every 6 months - perhaps the back end loading means preuming its all ok cashflow will staret to flow in nicely.
With todays update i dont see anyone changing their mind here - albeit they are on target they have 2 red marks here with h2 loading and lack of progress ref debt.
Any chance to have a look at Celebrus Technologies (LON:CLBS)? There is a Cavenish report available and they talk about "repapering" which I think is about moving one time contracts to annual contracts. The revenue figures have taken a big hit and I am wondering whether this is just a results of the accounting changes or something deeper. I don't hold.
Hello chrisgb,
I thought that repapering was something to do with wallpaper, but you are correct - it is the process Celebrus Technologies (LON:CLBS) is going through of transitioning from one-off contracts to monthly recurring revenue.
In short, today's results appear to be in line and the decline in revenue was expected - I'll add a short comment to the table on Celebrus shortly.
Roland
Many thanks Roland.
B.P. Marsh & Partners (LON:BPM)
chomping set of results here - company looks in rude health and discount to NTAV seems about as good as it has been in quite a while.
per results today - diluted nav up 50p per share in 6 months - stonking 12 month return as prior 6 month performance was excellent
The diluted NAV per share at 31 July 2025 is 909.8p (31 January 2025: 847.3p and 31 July 2024: 658.5p)
with diluted NTAV at over 900p and shareprice under 700p - i make that 22% plus discount to NTAV - no brainer at present
The results are set against a softening market too - so looks like they kind of have headwinds here - clearly the firms they are investing in have pretty clear expansion goals and targets -they (their investment companies) generally (not always as sometimes they will aid exit of key people) need assistance if they are expanding their sales - so their investments one would hope are doing much better than the market.
The softening trend in rates has continued throughout 2025, with global rates declining by 7.0% over the first half of 20251, which represented the fourth consecutive quarter whereby global insurance rates have reduced.
A substantial proportion of the market now has access to sufficient capacity, which in turn applies a downward pressure on rates. This is a trend that the Group expects to continue over the remainder of 2025.
I am expecting some mean reversion here at some stage ref returns as the company seems to keep churning out 10% plus compouned growth pa in nav - thats probably too big an ask to be repeated long term - but the more they are delivering now at rates of over 10% pa compounded the better. All the better taht the market has 20% discount applied.
They have been pretty active recently too and will presumably remain so whilst they have excellent spare cash hopefully some solid future decent returns can be made from investments about now.
Possibly as solid a hold as this share has ever been with nav discount current over 20%. currently one of my top holdings - i have thouught about partly cashing in here at some stage as i am overweight here but i aint going to do that at the current price whilst company is still delivering.
Nice review, they do seem to be a very consistent company (I hold) the director sell off last year was the only thing that dipped the share price. It would be nice if they could get it back to those levels, I notice they have been buying back in Sub 700p.
B.P. Marsh & Partners (LON:BPM) Agree lots of positives but the shares have gone nowhere over the past year and though they make much of the return to shareholders - the yield is only 2%
B.P. Marsh & Partners (LON:BPM)
the yield is only 2%
this share is all about the NTAV appreciation its not for dividend yield hunters - its that simple if that keeps going up the shareprice will follow suit as it has done - facts are the shareprice has roughly doubled since Autumn 2023 - so pause for breath is natural. I think its natural for shareprice of companies like this to ebb and flow - say between 25% ntav discount and 5% ntav discount. Note thats presuming company delivering well with above inflcation increases on average ref ntav - with companies like this one shouldnt expect they will always shoot the lights out going forward - they have a decent track record of deliverance though mostly using the same simple plan of attack. Just look at current value of investments compared to cash they have deployed acquiring holdings thats sensational numbers !
if they can get 10% compounded growth they should be investing for more of the same and also buying back shares rather than paying out chomping dividends - imho dividends is the least efficient thing to do here while there is pipeline of decent investments lined up and decent discount to ntav. Note i am not totally against dividends - its just that the divi yield here has zero relevance with regard to how the company is doing and lower is better imho unless they cant find new investments or discount to ntav aint much that divi might trump share buyback.
Assuming people want to hear some potential drawbacks or negatives for the shares we discuss here;
I looked at B.P. Marsh & Partners (LON:BPM) a few weeks ago and really liked what I saw. Right up until I looked at the Director remuneration. Then it went in the "Management are greedy bleeping bleeps" pile.
They have a Joint Share Ownership Plan (JSO), a Share Incentive Plan (SIP) AND a Share Option Plan (SOP). The vesting criteria are CAGR 10% NAV growth which is easily achievable, and the strike price is 10p.
They also pay themselves a bonus every time they successfully sell an investment. I could possibly understand that, but investing in start up and early stage insurance companies is literally what they do. I'm not sure they deserve a bonus for doing what is their job! From memory, those bonuses were paid on top of the standard annual bonus.
I would need to check my records but I think the Directors, there are six I believe, took home more money than they paid out to shareholders in either FY23 or FY24.
And then we come to the fact that the Owner, Brian Marsh, appears to have appointed his daughter as the MD. Now, it is possible she is/was the best qualified candidate in the whole world, but.....
As I said at the start, I did really like the company, and none of the above stops it being a good investment. Personally, I don't invest in companies that appear to be run by Management whose primary focus is their own bank balance. Nepotism is never a good look either.
B.P. Marsh & Partners (LON:BPM)
the high potential overall rewards to directors here have always been present for as long as i have held - there is nothing new here.
If we look at the vesting criteria ref the 10% growth you mention.
first up its compouned over 3 years.
I would say 10% compounded growth is pretty good imho for buisnes looking to
Note there is zero payout out if growth is below 8.5% compounded - so its remuneration based on delivery here rather than remuneration for having the role.
If they deliver increase nav of less than 27% over 3 years then zilch payout.
If we look at the minumum return for full payout thats 3 year nav growth of 33% - for maximum payout to be acheived. The shares amount to 4.5% of base price so i make that 13.6% of growth "max" that could be paid to directors.
Note thats the max they can get - so practicably speaking if they exceed targets thats probably 90/10 split for shareholders and directors.
ref bonuses paid that was £2 million paid ouit based on gains on disposal of £65 million - so 3% of profit made on those investments - 97% for shareholders.
With a business with very key main staff that could walk and setup in competition tomorrow i will accept that setup. Yes they are potentially very well rewarded but 90/10 split ref increase in nav tolerable from my point of view here.
I would need to check my records but I think the Directors, there are six I believe, took home more money than they paid out to shareholders in either FY23 or FY24.
as per my original post - to maximise NAV growth they dont pay out high level of dividends due to funds being reinvested oe remaining invested for long periods of time, You are trying to give the impresion here that directors are getting more than shareholders when thats far from the case - the vast majority of uplift in nav remains with shareholders - yes directors get their pound of flesh but its based on performances delivered adn done in clear and transparent fashion;
And then we come to the fact that the Owner, Brian Marsh, appears to have appointed his daughter as the MD. Now, it is possible she is/was the best qualified candidate in the whole world, but.....
but what ?
she has been at the firm for many years - for small company its pretty normal for people to be promoted within. I dont see anything intrinsically wrong with this as when the proof of the pudding is very evident. Management are delivering good returns here for shareholders (after their cut) and have done for many years total equity has grown from 70 million in 2016 to 326 in 2025 million - well in excess of 10% compounded growth pa for shareholders.
Hi Rmillaree,
We have spoken a few times on here and I find you a very difficult person to discuss shares with. You may not mean to, but in our conversations I find you come across as arrogant and patronising. I do not intend to have a prolonged discussion here, but I will pay you the courtesy of replying.
My initial comment was purely to highlight areas that people may wish to look at. As I said, I like the company and it ticked almost every box for me. The issue, for me, is the Dir. remuneration. You may be happy to accept the levels they have. I am not. That doesn't make me 'right' nor does it make you 'right', it also doesn't make either of us 'wrong'.
My intention was purely to highlight a potential downside. I am always keen to hear potential issues with the shares I own or am considering, I assume most people on here are the same. That seems to be the consensus when that topic is discussed anyway.
A few points though, and I am again going from memory as my notes are on my computer. I think it was FY24 where the six Directors took home more in combined pay/bonuses than the total paid out in dividends to shareholders (some of the latter are also Directors).
That's not "implying" the Directors get more than shareholders, that's pointing out factually that they DID. The company could surely increase NAV more by NOT giving Directors so many bites of the cherry and investing that cash.
Also, an increase in NAV is of limited direct benefit to shareholders. It's the share price (SP) and the dividends that benefit them, albeit I suspect/accept that an increase in NAV is unlikely to result in an SP fall. But, if a company increases its NAV while I own it, that has no direct impact on my portfolio value. It is the SP and any dividends that do.
Again, different people will prefer different things from their companies so we can both be correct or both incorrect in our statements. I am merely pointing out what I perceive to be issues.
Finally, as for the nepotism, you may not have an issue with it, I do. Both opinions are equally valid. All I was implying was that I suspect she did not get her promotion to MD based on her being the single most qualified candidate in the world, more so as a result of her father owning the company. Personally, I want the best qualified people running my companies, not someone appointed by right of birth. That's not to say 'family businesses' are inherently bad, far from it look at Goodwin today, more that I would prefer the person to spend a lot more time learning the business and working their way up, rather than being parachuted in and promoted incredibly quickly. A quick glance at one of the company presentations showing her responsibilities hardly makes her sound like the new Steve Jobs. Other opinions are equally valid.
As I said in my original post and multiple times above, I like the company (were it not for the Dir. remuneration I would be a shareholder) and I was highlighting the issues I had with the company in the spirit of cooperation. If you feel the issues I highlighted are inconsequential, fair enough, it takes multiple opinions to make a market and yours is no more right or wrong than mine.
I shall leave it there and wish you and BMP all the best, sincerely, I hope both do very well in the future.
Eco Buildings (LON:ECOB) has announced a deal to build 20,000 modular houses in Chile for £420m, and its shares are now up tenfold in a month. I have no idea what capital spend that entails or the margin it will generate but it comes out at £21k per house. Anyone who holds should be very pleased.
By contrast, the Bloomberg podcast at the weekend mentioned that it is not possible to profitably build houses in half of London right now, even if the land was provided for free. It highlights how difficult it is for the UK to compete. The US Ambassador responded to Keir Starmer's request for investment yesterday by simply saying that required cheaper energy.
Any UK based business dealing with UK development rules or energy costs is massively disadvantaged versus overseas peers. That's one of the reasons why UK companies are so lowly valued.
Lots of big numbers in contracts recently announced by Eco Buildings (LON:ECOB) .... but how many of those contracts will actually see shovels in the ground? And the full value being built?
Eco Buildings (LON:ECOB) seems to have secured a great deal of work around the western hemisphere with dangerously low funds. Is it not going to have to raise a lot of funds to bridge to project payments? It seems to me such an elevated SP would be an excellent place to sell more equity - but I wonder whether the price for that sale would be near recent price levels.
SEGRO (LON:SGRO) I hold
Third qtr trading update today - not on the agenda ? Can it be added please?
"SEGRO PLC reported a strong third quarter, with £22 million of new headline rent signed, bringing the year-to-date total to £53 million, compared to £64 million in the previous year. Rent uplift year-to-date was 37 percent across 170 rent reviews, renewals and regears. Occupancy remains high at 94.3 percent with customer retention at 86 percent. Development completions totalled 34,800 sq m of new space, adding £8 million of headline rent, bringing the total completions for 2025 to 231,600 sq m, equating to £27 million of expected rent, 89 percent of which is secured. The company invested £286 million in its development pipeline and £228 million in asset acquisitions, offset by £39 million of disposals, with development capex expected to be approximately £400 million for the year."
yes of course, we can add this in! thank you.
I won't bore everyone with why we still hold WJG but after reading today's inline update, I've read what Warren Buffet thought about Walter Schloss and his hunt for bargains -- WJG is in there. Suffice it to say should it ever reach the brokers targets, we'll break even. I'm hoping the team have time to include it today.