Daily Stock Market Report (Tue 29 April 2025) - JET2, W7L, BP., HSW, ABF

Good morning all, let's see what we've got in store for us today!
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
AstraZeneca (LON:AZN) (£163bn) | Rev +10%, adj EPS +21% to $2.49. FY25 guidance unchanged, five positive Phase III readouts. | ||
HSBC Holdings (LON:HSBA) (£147bn) | Adj PBT +11% to $9.8bn, RoTE 17.9%. Q1 divi of $0.10, $3bn buyback. Volatile macro outlook. | ||
BP (LON:BP.) (£57.8bn) | Und. RC profit $1.4bn (4Q24: $1.2bn). Divi 8 cents, $0.75bn buyback. Outlook mixed. | AMBER/RED (Roland) Today’s Q1 numbers appear to have missed expectations and flag up a sharp rise in debt. The company is accelerating asset sales and believes it remains on track to hit 2027 financial targets. However, oil prices are now below the level on which February’s guidance was based. BP’s higher leverage and sector underperformance also makes me cautious, given the uncertain external conditions. There could be value on offer here. But I think BP’s Value Trap styling is a timely warning that the stock may deserve a lower rating than peers. | |
Coca-Cola Europacific Partners (LON:CCEP) (£30.2bn) | Q1 in line, rev +5%, volumes +7.8%. FY25 guidance unchanged. | ||
Associated British Foods (LON:ABF) (£16.2bn) | Rev -2%, adj PBT -10% to £818m. £101m impairment in Sugar. FY outlook unchanged. | AMBER (Roland) [no section below] Today’s half-year results confirm that performance in the group’s Primark and Grocery business is on track to meet full-year expectations. However, the Sugar business is now expected to report an operating loss of up to £40m due to low sugar prices and some structural and regulatory issues. Restructuring efforts are underway. Frustratingly there’s no clear guidance on the impact to group profit expectations this year. However, based on previous guidance, I estimate a c.5% reduction in group earnings, which would be consistent with today’s share price fall. ABF was a Super Stock prior to today and I think the shares are probably reasonably priced on a long-term view. However, I think a neutral stance is more appropriate following today’s update. | |
Beazley (LON:BEZ) (£5.6bn) | Written premiums +2%, renewal rates -4%. Guidance unchanged for FY combined ratio in “mid-80s”. | ||
Howden Joinery (LON:HWDN) (£4.1bn) | Adj rev +3%, LFL +1.8%. Double-digit intl growth. Balancing margin and volume. FY in line. | ||
Entain (LON:ENT) (£4.0bn) | Q1 rev +11%, ahead of exps, FY25 outlook unchanged. New CEO appointed. | ||
Jet2 (LON:JET2) (£2.9bn) | FY25 results in line with exps with adj PBT +9% (£565-570m). FY26 YTD seeing late bookings. | GREEN (Roland) A solid update from this well-run business including news of an unexpected £250m buyback. Broker forecasts for the current year have been upgraded as a result. While there’s some uncertainty about demand this summer, I think the valuation already reflects this. I’m happy to maintain our previous positive view. | |
Breedon (LON:BREE) (£1.6bn) | Rev +9%, some project delays. Slight rise in total volumes, stable pricing. FY25 outlook unch. | ||
Telecom Plus (LON:TEP) (£1.5bn) | Net cust. growth +15%, FY25 guidance unchanged for PBT £124-£128m. Confident outlook. | ||
Travis Perkins (LON:TPK) (£1.1bn) | Q1 rev -2.1% LFL, “challenging”. Merchanting -3.2% LFL, Toolstation +3.7% LFL. | ||
Bakkavor (LON:BAKK) (£1.0bn) | China business sold for c.£50m, net profit of £15m expected on disposal. | PINK (possible offer) | |
Elementis (LON:ELM) (£759m) | Rev -2%, but adj op profit & margins ahead of Q1 24. FY exps unch, but warns of tariff risks. | ||
Alfa Financial Software Holdings (LON:ALFA) (£638m) | Q1 rev +20%, in line with exps. Total contract value “record” £227m. FY exps unchanged. | ||
THG (LON:THG) (£409m) | Rev -3.1%, adj EBITDA +0.3% at £114.4m “in line”. Q1 24 rev -7%, FY25 rev exps unch. | ||
Newriver Reit (LON:NRR) (£346m) | CAL integration on track. LTV c.42%, FY25 UFFO and EPRA NTA to be in line with exps. | ||
Warpaint London (LON:W7L) (£327m) | Rev +13%, adj. PBT +33% (£24.6m). Brand Architekts acq’n completed. Exps unchanged. | AMBER/GREEN (Graham) I'd like to be fully GREEN on this but there are a couple of issues. Q1 has been soft in terms of underlying growth, with quite a lot of month-to-month sales volatility. The company's big opportunity in the US is currently under the cloud of tariffs, whose impact at this stage is highly uncertain. It's a seriously impressive roll-out story all the same. | |
Pinewood Technologies (LON:PINE) (£320m) | All 350 VW/Audi dealerships in Japan. Rollout and revenues to commence in the first half of 2026. | ||
Mobico (LON:MCG) (£206m) | Adj. op profit £188m, in line. Unadjusted loss £794m. New Chair/COO. CEO steps down. | ||
Animalcare (LON:ANCR) (£167m) | Rev +4.9%, PBT £5.8m (LY: £3.3m). Net debt £9m. Randlab acq’n completed. Positive outlook. | ||
Hostelworld (LON:HSW) (£140m) | SP down 3% | GREEN Graham [no section below] | |
MPAC (LON:MPAC) (£126m) | Rev +7%, PBT £3.5m (2023: £4.7m). Net debt £37.5m. On track to achieve 2025 exps. | ||
Inspired (LON:INSE) (£109m) | Regent says offer is 71% premium to Jan 2025 placing price and 43% premium to price at which it began to increase its shareholding. | PINK (under offer) | |
Watkin Jones (LON:WJG) (£85m) | H1: small op. profit. Net cash £73m. Pipeline has “potential to deliver an expected stronger H2”. | ||
Focusrite (LON:TUNE) (£84m) | Rev +5%. Macro uncertainties persist. Exps “remain realistic” given 90 day pause. Debt £18m. | ||
Falcon Oil & Gas (LON:FOG) (£63m) | Pre-revenue. 2024 loss before tax $3m. Debt free with cash of $6.8m as of December 2024. | ||
Manolete Partners (LON:MANO) (£35m) | FY25 realised revenues (£29.5m), EBIT (£2m) and PBT (£0.3m) are ahead of market expectations. | ||
Nexteq (LON:NXQ) (£35m) | Confident in achieving 2025 full year market expectations. Net cash position $30.2m. | ||
Insig Ai (LON:INSG) (£32m) | Q4 and FY March 2025 ahead of previous guidance. Q4 revenue £249k, 11% ahead of guidance. | ||
SysGroup (LON:SYS) (£19m) | FY March 2025: revenue (£20.5m) and adj. EBITDA (£0.9m) in line with market expectations. | ||
KRM22 (LON:KRM) (£9.6m) | Payment of all interest deferred until June 2026, to conserve cash. Floating rate currently at 9.5%. | ||
Touchstar (LON:TST) (£6.0m) | A major order was delayed, but now confirmed for 2025. Solid potential in the sales pipeline. |
Graham's Section
Warpaint London (LON:W7L)
Down 4% to 387p (£312m) - Full Year Results - Graham - AMBER/GREEN
Warpaint London plc (AIM: W7L; OTCQX: WPNTF), the specialist supplier of colour cosmetics and owner of the W7, Technic, Skin & Tan, Super Facialist, Dirty Works and Fish Soho brands is pleased to announce its audited results for the year ended 31 December 2024.
We already covered the 2024 trading update here.
Today we have confirmation of the numbers:
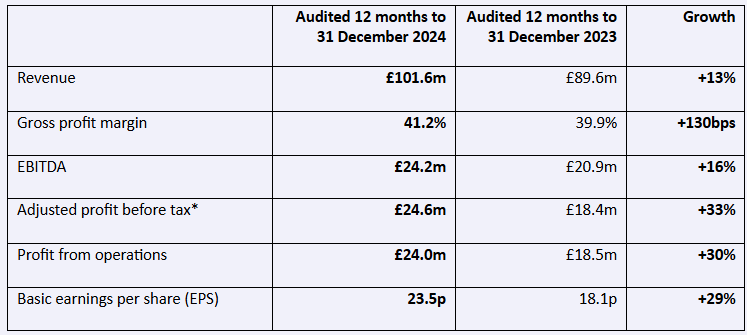
As noted by Mark in February, operational leverage has turbo-charged the performance, giving us 33% growth in adj. PBT despite much more modest growth in revenue.
Cash finished the year at £21.9m, but most of that was escrowed to buy Brand Architekts.
The cash balance as of 8th April: £17.3m.
Dividend: total payout for the year is 11p, covered more than 2x by EPS.
Current trading and outlook: “solid start to trading in Q1 2025”, Q1 sales +14% year-on-year. Excluding Brand Architekts, sales are up 7% year-on-year.
Some seriously impressive brand rollout news:
Italian drug store Tigota is launching products in 200 stores, plus a “capsule collection” (smaller range) going into an additional 400 stores.
Dutch drugstore Etos is expanding its product assortment in all 546 stores.
Superdrug UK rolling out W7 into 140 news stores and travel size products in all stores.
Tesco: 150 store expansion of W7. Boots: Christmas gifting products for the first time in 350 stores.
CVS Pharmacy (United States): expanding W7 range and roll-out to a further 399 stores from August 2025, taking the total number of CVS stores stocking their products to 918.
They are “in talks with other large retailers in Europe, the UK and the US to stock the Group's products”.
Expectations are unchanged:
Despite continuing headwinds, including the effect of increased US tariffs, the Group has significant planned expansion opportunities and the board expects the Group's performance to remain strong and for sales and profits to grow in line with previous expectations over the remainder of 2025 and beyond. Accordingly, the board's expectations for the Group's financial performance in 2025 are unchanged
Estimates: thanks to Shore Capital for publishing on Warpaint today. Consistent with the above, they leave their forecasts unchanged.
Revenue this year is expected to grow by 26% to £128.6m - given that growth in Q1 was only 14%, that implies quite a significant acceleration through the rest of the year.
Shore acknowledges this, saying that their forecasts “do require an improvement in sales momentum for the remainder of the year”.
It sounds like there has been quite a lot of month-to-month volatility recently, with some months being weak and then others being very strong.
Therefore, I can't say that I have a great deal of confidence in these forecasts. To me, this sounds like the precursor to a profit warning. But then, given the volatility and the forthcoming store roll-outs, there is also the possibility of a surprise to the upside!
Adjustments: just a quick note to say that today’s accounts are very clean with only small adjustments, including modest share-based payments, creating very small gaps between EBITDA/operating profit and adjusted EBITDA/adjusted operating profit. Well done to the company for that. We’ll see if this can continue despite the recent acquisition.
Graham’s view
As I’ve said, I think that at this stage it’s difficult to have a great deal of conviction in how Warpaint is going to do this year. They’ll be busy, with lots of exciting expansion projects, but the financial result at this stage is a finger-in-the-air type of prediction.
At this stage it’s difficult to say how long-lasting or serious the tariff problem might be. With over 900 CVS stores in the United States stocking W7L products soon, that is a major opportunity for the company long-term.
The CEO’s comment suggests to me that difficulties with US sales are for now at least offset by opportunities elsewhere. He says with respect to US sales:
…we remain focused on ensuring that sales the Group undertakes remain profitable, whilst benefiting the longer-term strategic positioning of the Group's brands in a potentially improved tariff environment.
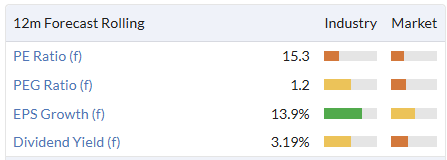
I’m inclined to leave our AMBER/GREEN stance unchanged here to reflect that I do see much more here to like than to dislike. The valuation doesn’t strike me as being particularly expensive for a successful roll-out with international opportunities:
Roland's Section
Jet2 (LON:JET2)
Up 16% to 1,567p (£3.4bn) - FY25 Trading Update - Roland - GREEN
Full year results in line with expectations and £250m Share Buyback announced
This AIM-listed airline and package holiday group is a company I’ve regarded highly for a long time and should probably have bought at some point.
Shares have risen strongly today, in part due to news of a £250m buyback which has prompted an upgrade to FY26 earnings per share forecasts.
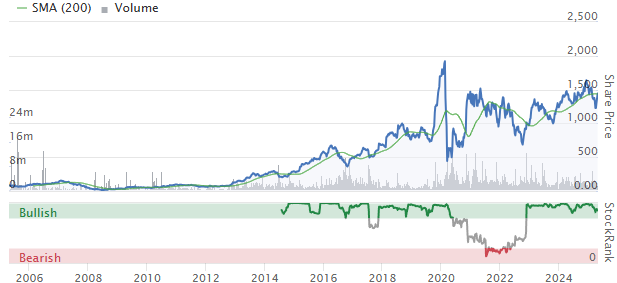
FY25 trading update: today’s update covers the 12 months to 31 March 2025 and looks very reassuring to me. Let’s take a look at the main points:
FY25 pre-tax profit expected to be between £565m and £570m (FY24: £520.1m);
This represents an increase of 9% and is in line with expectations;
Jet2 will also report an additional £10m of disposal profits, largely from the sale of retired Boeing 757 aircraft;
Total cash of £3.2bn and own cash (excluding customer deposits) of £1.1bn;
£250m share buyback programme.
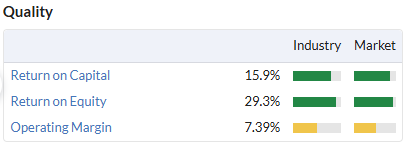
Profit: although 9% profit growth is substantially lower than the 33% growth reported for FY24, it’s still a strong result and should continue to support the attractive quality metrics we’ve come to expect from this business:
Cash/balance sheet: Jet2’s strong balance sheet is another attraction. In addition to providing support for growth investment and fleet renewals, it’s also a useful source of income in itself – net interest received in FY24 was £84m. I’d expect a comparable result for FY25.
However, it’s worth noting that Own Cash is not net cash – Jet2 reported total debt of £1.3bn at the half-year market and my impression is that net cash/net debt will be close to zero in the full year accounts. The company is working its way through a previously flagged £5bn/6yr expenditure programme. Elements of this completed over the last year include:
Opening two new operating bases
Purchasing 4 new Airbus A321neo aircraft using its own cash
Purchasing £159m of shares for the Employee Benefit Trust to reduce future dilution
FY26 trading commentary: Jet2 is continuing to add capacity this year despite more uncertain market conditions:
Capacity for Summer ‘25 is currently 8.3% of Summer ‘24, at 18.6m seats;
New bases at Bournemouth and Luton have contributed about half the new capacity;
So far this year the company is seeing a late booking profile, limiting forward visibility;
The mix of passengers is currently skewed more heavily to (lower margin) flight-only bookings than it was last year
Pricing remains stable, with “modest average increase” in holidays and a “slight increase” to flight prices, helping to offset cost rises
CEO Steve Heapy sounds cautiously optimistic and has promised a fuller update when the results are published in July:
Although still very early in FY26, we are satisfied with progress for Summer 2025 so far.
Outlook: with thanks to broker Canaccord Genuity we have updated forecasts today. Despite the company billing today’s FY25 profit guidance as “in line”, Cannacord has upgraded its earnings forecasts for both FY25 and FY26:
FY25E EPS: +14.5% to 215.1p (previously 187.7p)
FY26E EPS: +7.4% to 223.9p (previously 208.5p)
The previous numbers are slightly ahead of consensus forecasts on Stockopedia, so assuming Canaccord’s modelling is in line with the company’s internal expectations, this looks like a fairly meaningful upgrade.
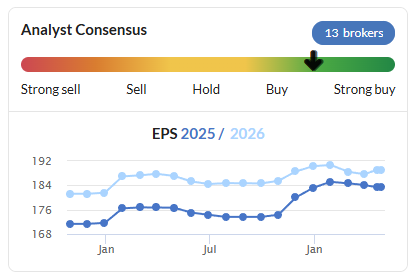
These estimates leave Jet2 trading on a FY25E P/E of 7.3, falling to a FY26E multiple of 7.0. This doesn’t seem expensive to me, even for a travel business.
Roland’s view
Today’s update does nothing to change my positive view on this business. While there’s clearly some uncertainty about the outlook for this summer, past experience with Jet2 is that it’s generally fairly conservative with guidance. I wouldn’t be surprised to see a modest upgrade later in the year.
A strong balance sheet and clear-headed long-term growth model helps differentiate this business from rivals, in my view. Jet2’s long-term record suggests this approach also delivers a high level of customer satisfaction:
I was GREEN on Jet2 in February and I’m happy to maintain that positive view today.
BP (LON:BP.)
Down 3.8% to 348p (£55.1bn) - Q1 Results - Roland - AMBER/RED
Today’s first-quarter numbers from BP have met with a poor reception from the markets despite bullish commentary from under-pressure CEO Murray Auchincloss:
So far this year we have started up three major projects, made six exploration discoveries and have progressed our divestment programme - all while delivering strong operational performance, with over 95% upstream plant reliability supporting the best operating efficiency* on record, and over 96% refining availability.
A fall in Q1 profits versus last year was expected due to lower commodity prices. The problem with today’s results seems to be that they have missed consensus expectations – and not for the first time in the company’s recent history.
Here’s a summary of the main numbers for Q1 2025:
Underlying Replacement Cost (RC) profit: $1,381m (Q4 24: $1,169m, Q1 24: $2.723m)
Net debt: $26,968m (Q4 24: $22,997m)
Quarterly dividend unchanged at $0.08 per share
BP is more heavily geared than most rivals, certainly more so than Shell. Aggressive buybacks have contributed to this – the $4bn increase in net debt in Q1 was partly due to $1.9bn of buybacks. Perhaps in a sign of pressure, buybacks for the current quarter have been scaled back to $0.75bn – the bottom end of February’s guidance.
In fairness, BP says it’s confident that proceeds from divestments and disciplined spending will allow the group to meet its target of net debt of $14-18bn by the end of 2027.
Personally, I’m not a fan of companies buying back shares with borrowed cash. My feeling is that BP should have used the bumper profits of recent years to accelerate debt reduction, rather than relying on divestments in what could prove to be more difficult market conditions.

Outlook: oil prices have continued to fall since the end of the first quarter, suggesting that Q2 will not be any easier for this business:

At current levels, oil is trading below the $70 per barrel on which the company’s updated financial targets were based in February.
Today’s full-year guidance is broadly unchanged, but the company is now accelerating its disposal plans and is targeting $3-4bn of disposals this year, from “around $3bn” previously.
I don’t have access to any broker coverage for BP. But consensus estimates have trended consistently lower over the last year. I wouldn’t be surprised to see them trimmed again following today’s update:

Roland’s view
Today’s Q1 update isn’t great, but to be honest, I don’t think it’s that important either. In my view, investors considering BP at the moment need to focus on the bigger picture:
Cyclical risk – where are we in the cycle? This is harder than usual to understand, given tariff-related uncertainty;
Can BP establish a consistent and successful strategy and reverse its track record of underperformance?
Consensus forecasts for BP have fallen by nearly 45% since April 2024. In contrast, estimates for Shell’s 2025 earnings have only been cut by 18% over the same period.
While the two companies aren’t exactly equivalent, I think this helps us separate the impact of commodity prices from BP’s company-specific underperformance.
BP CEO Murray Auchincloss is currently under pressure to improve performance from activist investor Elliott Management, which has built a 5% stake.
Mr Auchincloss has already announced plans to reverse the group’s 2020 strategy and focus more heavily on oil and gas production, cutting renewable spending. However, Elliott believes the changes don’t go far enough and is reportedly calling for big spending cuts.
BP’s share price has fallen by 35% over the last year and the stock is now – arguably – priced at a level where some cyclical value could be on offer. Stocko data shows BP trading at less than eight times 10-year average earnings, compared to nearly 13 times for Shell:

The company has previously said its dividend is covered by cash down to a Brent Crude price of $40. If Auchincloss can improve profitability and cash generation, then the current 6.5% yield could be safe and the shares could recover strongly when market conditions improve.
On the other hand, there is not yet much sign of the improving momentum we might seek to provide confidence in a turnaround. BP’s MomentumRank has now dropped to extremely low levels, reflecting the combination of a falling share price and falling earnings estimates:

As a result, Stockopedia’s algorithms are now styling the shares as a Value Trap – an underperforming style:

Investors with a keen interest in this sector might want to take a closer look.
However, BP has a long track record of periodic missteps and incomplete recoveries and has underperformed Shell on 1, 2, 5, 10 and 20-year timeframes:

Given BP’s disappointing Q1 result and worsening quantitative metrics, I think it’s sensible for me to downgrade our previous neutral view to be mildly negative. AMBER/RED.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

43 comments
Be interested to hear thoughts on Howden Joinery (LON:HWDN) - They only allow those with a Traders Account which seems archaic to me but for whatever reason (I have to go to Wickes or B&Q )must work for them - but what is their secret ?
Focus equals success. Get 10k+ traders to sell their kitchens for them at good prices. Traders become experts in Howden kitchens through long term familiarity and multiple purchases. Sell 1 kitchen to 1 end customer or sell 1 kitchen per month to 1 trader? Also allows for smaller non-retail/stock branches. Staff are lazer focused or serving the trader and know everything about all their products to the point of helping with designs. Absolute class act!!!
Would disagree with your comments on Howdens. My husband has an account with them but finds them absolutely useless. When it came to us fitting a new kitchen for our own home we went to Wren. Much better quality and the retail price was significantly cheaper than Howdens trade price.
Howden Joinery (LON:HWDN) - Bill Bailey likes them:
They do a number of small things very well from the depot level up to the board level, IMO. Good depots, good manufacturing facilities and distribution and sensible capital allocation, balance sheet management, accounting and reporting.
Depot managers have reasonable autonomy in extending credit and discounts to small builders- so if you're winning business consistently you can get your cabinets etc. cheaper and then pay once the end customer settles the invoice. Also, their depot network has very good coverage nationally and they are generally well-stocked. Depot managers are well incentivised on depot level performance- you can do £150k+ in total comp in a good year, I've heard. This seems to have some interesting knock on effects- if I recall correctly, shrinkage in a typical year is comfortably under 1% which is peculiarly low, for example.
Thanks for all the response - Don't quite get how good ol Bill Bailey manages to get an account with them but never mind. Will monitor from the sidelines and watch out for any more negatives (Barbara ) mindful that there will never be 100% positive feedback.
There are ways to get an account our house had a built in microwave fail and the ex wanted more cupboard space so I jumped through the account hoops as I just wanted one door simple to fix just the how do I get one replacement
so easy enough if you want to do it yourself and don’t have a friend of a friend in the trade
HWDN, their secret, excellent service ,prices and products to the trade, unlike many so called ''trade'' outlets! I had an account with them for 30 yrs, I should know!
Warpaint London (LON:W7L) I hold
Graham I think you left a word out (don't) when saying this
"Therefore, I can say that I have a great deal of confidence in these forecasts."
thank you!
Lots of new today and the only one I hold is Telecom Plus (LON:TEP) , a pleasant long term hold.
I would like to make a request to the writers of this page please. Often, during the day I only get access to read this page on my phone rather than computer. With the summary results can the formatting be changed please so that each cell is formatted to position top left. At the moment when I scroll on my phone I see text in the right box "Summary" with lots of writing. I have to scroll down further until the left box shows the name of the company I'm reading about. I like the name of the company visible on the left box (top) before I read the summary narrative, so I know if it's a company I'm interested in.
Hope this is possible. Thanks.
Jet2 (LON:JET2) and MPAC (LON:MPAC)
I hold both and on an initial read am happy with this morning's announcements.
Jet2 (LON:JET2) is by far the larger of the two positions. In my view this is the best in class travel operator with an excellent management team and remains cheap. The balance sheet is in great shape and the announcement of the £250m share buy back is indicative that Steven Heapy and his management team agree with me regarding the cheapness of the shares.
MPAC (LON:MPAC) The new management team deserves credit for extending the reach of the company to provide end to end packaging solutions via the recent acquisitions and having the conviction to go to the market with the necessary placing at 400p. The trend towards automation is not going to disappear anytime soon.
I dallied and missed the boat at the time, but bought my relatively modest holding as the shares came back with the majority of UK small caps. Again the shares are cheap if the company can achieve expectations. The positive news regarding the pension scheme is also helpful.
My one gripe is that I would like to see the management team put their hands in their pockets and buy a few more shares.
It strikes me that MPAC (LON:MPAC) along with several UK smaller companies is ripe for a bid at the current share price; although hopefully not.
My final thought is that the market for UK shares and good quality smaller companies is starting to turn, if my portfolio is any thing to go by. If so it is about time given the last 2/3 years,
I agree on your Jet2 (LON:JET2) comments (I hold). I think the metrics for this company are excellent EV/FCF is superb and I just don't understand why the market has not backed this share in a more secure (less volatile) way over the past couple of years. Very please to see the uplift today and wish I'd bought more in the recent dip but the share price volatility put me off. This has to be a good long term hold. I'm just back from the States and was surprised at how much more expensive it is over there, with the current politics and likely further US price rises I think more people will go to the EU for holiday (if EU countries will take them) potentially boosting Jet2 (and others) further.
MPAC (LON:MPAC)
There is now a 23 minute Q&A with Mpac Group CEO, Adam Holland & Finance Director Will Wilkins which you can view by clicking here. Much talk of how transformational the acquisitions in 24 are and also discussion on the effects of tariffs and any recession.
For those with a lingering interest in Argentex (LON:AGFX) , it is covered in some detail by Matt Levine in his daily Money Stuff email, one of the Bloomberg Opinion series.
Available without a subscription if you spend 10 seconds demonstrating that the Google search business has yet to be completely driven into obsolescence by ChatGPT. I never held the shares or looked at the company too closely, but it is always interesting to look back and see if any warning signs were there, so I had a brief look yesterday evening.
I wasn't aware of the degree to which "zero zero lines" had proliferated in the FX world (and derivatives is an area would consider myself very well informed about until recently) - basically it appears major clients could use competitive pressures to duck the hassle of initial & variation margin - and you won't find Argentex talking about it in their recent presentations. It looks as if commercial imperatives were allowed to overrule the risk function....a story as old as time.
However, if you look carefully at the 2024 accounts there is a hint - deep into their risk management section of their 2024 accounts, on p24 you see that they effectively admit that they can be net long or net short a currency. And a "blend of terms that enable client margin calls" is very different from "fully collateralised"!
But is that enough to short the stock? Of course not, and they give no idea of the magnitude of long or how short they are willing to go....
I guess the other issue staring in you in the face is that the executive management team lacked financial markets expertise - the new-ish CEO (2023) was fintech/payments, the CFO arriving in 2024 was ex Vodafone/Camelot and there was a Camelot theme to other board members.
And perhaps it is best to avoid companies that trade derivatives with Lord Digby-Jones on the board!
However, the Going Concern note does specifically state that "Sensitivity analysis has been performed in respect of ....... significant increases in volatility requiring further collateral to be placed with the Group’s institutional counterparties", so I think as a shareholder you have a right to feel pretty aggrieved.
Question is what other stocks might be at risk of similar blow up. I think we all know the banks and insurers can blow themselves up and poring over the accounts won't save you - on the other hand the regulators do keep a close eye on them.
However, I would argue all of the spreadbetting firms could easily meet a similar fate - as investors how do we judge that they have a competent risk function, that the executive team is not too naive or too greedy, and that the board is being told what is really going on? The very recent director buys at Argentex (LON:AGFX) would indicate the board really didn't have a clue!?
Yes - Matt Levine is very good at putting these complicated situations into easy to read and humorous articles.
According to the article, zero zero lines have been used since 2010 and now the bulk of FX brokerages offer zero zero lines to corporate clients.
If this is the case, it still does not fully explain why Argentex was the only one to have a problem.
No position
The relationship between outfits like Argentex and their corporate clients is pretty opaque, and there are mentions of structured FX solutions here and there as well so the products they are flogging may be pretty opaque as well.
You can see why a corporate treasurer may not want to make bank transfers every evening to collateralise his FX hedges. That would be a legitimate reason for their offerings.
However, I suspect there may be more to it than this and the very large corporates may have the odd employee who is every bit as sophisticated as the Argentex salesman, or more so. I wouldn't be surprised if the large corporates have the upper hand and were gaming the relationship to their advantage.
I recall that the likes of National Grid (LON:NG.) had sophisticated debt issuance teams who are capable of playing off private vs public issuance and judging where on the curve & in which currency to issue, so I suspect there are companies that take their FX exposure just as seriously.
In other words the competitive edge over the banks from whom their sector has been taking share - not having legacy IT systems was competed away - so they relied more heavily on regulatory arbitrage, specifically around liquidity management, which turned out to be their downfall.
Lots of companies doing similar things points to a potential lack of competitive moat, confirmed by weak growth and profit warnings. I agree the technical aspects are interesting but this ship had been listing for a while.
Thanks MonteCarlo for a really interesting post - our only defence is diversification. As a total AI dinosaur / luddite, I'd be really interested to understand better your point that "..the Google search business has yet to be completely driven into obsolescence by ChatGPT" and how it helped you get the Matt Levine piece? Thanks and apologies to the tech savvy posters hooting with derision at my AI incompetence :-)
I get Matt Levine's articles emailed to me daily (very highly recommended, John Authers being another), but if you search on Google and perhaps venture past page 1 you will find what you are looking for without having to subscribe.
Very insightful. The moment margin discounts (or waivers!) are used to aggressively defend market share in a high volatility sector is probably the sparrow in the goldmine, but you're right, there was no way really to tell, for retail at least, and at least there is some natural justice in how the director buys played out.
And also the other point you raise, some of the spreadbetting firms do indeed appear to run collateral on a very long leash.
Thank you for a very clear explanation of the situation. I hold and have learnt a very valuable/expensive lesson; the existence of zero, zero contracts. However, there remains one thing I don't understand. Given that, despite the liquidity crunch, there were substantial assets over liabilities in the business, say c. £40M, why did the board not let the company be put into administration/receivership? Given the legal protection from creditors the process provides, as a worst case scenario, even if the costs amounted to £10M the shareholders should have eventually received 25p to 30p per share, against the 2.49p per share offered by IFX. It is also a much more transparent process. In fact I expect the business would still have been disposed of as a going concern, but, because of the protections in the process, at a far better price.
Argentex (LON:AGFX)
as soon as the hit hits the fan the directors obligations normally turn to protecting creditors - its common that shareholders are at the back of the queue and directors will probably be unders severe pressure to make creditorss weet if they might be in problems if there is shortfall ref their directoral duties.
I doubt its ever easy to do a cheap liquidation and that would potentially be very expensive on costs - with volume of stuff going through
i would agree shareholeders have been royally shafted and its sad that they couldnt nip the issue in the bud better and find a better out for shareholders - being frank teh risk assessmnet of te audit committe and the two auditors should be brought into question imho. I think it was mentioned volume was in the billions - so i wouldnt like to think how messy that end up trying to fulfil contracts and the like and winding down. Perhaps there was some negative working capital consequences of paring sales back if thats what needed to be done - similar to finance lenders where issues often arise if they try and run of the book rather than increase it.
probably without a better offer on the table the expert advise ws that we under no circumstances want to take this pile of crapola on (adminsitrators/ip's) as going concern - so lets take the best firm offer before they get cold feet and its nice fees for them - directors may get to keep their jobs too perhaps - some of them ?
You've got clearing houses and collateralised positions with clearing members behind the scenes here.
Just because Argentex (LON:AGFX) was facilitating corporates to take exposure without posting margin/collateral doesn't mean AGFX's brokers were affording AGFX the same luxury.
I very much doubt administration would have helped anything, or salvaged anything.
I don't know if AGFX was a clearing member - I doubt it, they were probably accessing the market via brokers & IBs. These counterparties would have closed out their trades and seized/liquidated the collateral on the "b "of "bang". Administrator or no administrator.
That's the business dead there & then. Not only would you have been dealing with all the broker claims on AGFX, but you would also have been dealing with all the broken contracts between AGFX and its client base.
I seem to recall I was still negotiating valuations related to the Lehmans blow-up over 5 years after the collapse. I'm not sure the Lehmans UK administration has finally wrapped up yet! Cleaning these things up takes forever. And a day.
cheers Monty Carlo that makes more sense than my mumbo jumbo for sure
Usually when there is one there is more to come, be interesting to see who else gets crushed by Trump vol in the coming months - I doubt its just these guys taking stupid risk to make a quick quid.
Sorry for everyone that lost out on this one.
I looked at this briefly earlier in the year as I think some people were discussing it here (maybe it was one of Paul's stock picks for the year too?)
Decided not to do because I have a general fear of financial firms doing opaque things that I don't fully understand, which I now take a step further and closing off positions I had that I had some doubts over not fully understanding or believing their books (closed a small Osb (LON:OSB) position I was holding this week)
Stockopedia shows Warpaint London (LON:W7L) down 5%. Thank heavens that their record results and strong outlook were not more positive(!)
Very reassuring update from Jet2 (LON:JET2) deploying its cash wisely. Several positive broker updates recently. Undervalued? Target SP approx 2000p? Comments welcome. I hold.
I think it will depend how the city take the statement about less holidays being booked in advance so can't predict the numbers but rest looks good!
One concern could be higher costs getting new aircrafts or replacement parts for existing ones. Lot of airlines have been moving from Boeing to Airbus for short haul aircrafts in the last few years and I don't know how many Boeings Jet2 has. I'd say this is something to keep an eye on
Morning Abel - Here you go (If you believe a quick AI Search)
I guess a sensible strategy could be grounding Boeing and acquiring more Airbus in case tariffs costs are higher to keep running the Boeing aircraft’s. Also the new Airbus are more fuel efficient so it could potentially increase capex but the running costs could be lower in the longer term
I agree. Long term holder. Flew to Vienna with Jet2 3 weeks ago from Brum. Full both ways. Boeing 737 800. What I like is that in my experience you do not get many rowdy hen or stag parties and they have enough staff on the ground unlike Ryanair and EasyJet.
Jet2 (LON:JET2)
Very reassuring update
totally agree - its probably my most comfortable holding at present. No brainer doing buybacks with current p/e too.
Just came back from Cyprus and had a chat with some jet2 reps. Reported very strong bookings for the rest of this year. No signs of any cost of living issues affecting people booking holidays
I’ve looked at the prices of autumn and winter trips and they are much higher than previous years. Indicates a healthy order intake.
MPAC (LON:MPAC) results look good on a quick scan, but surely they deserve a gobbledegook prize for the following : "We also increased the bandwidth of our senior management team, ensuring that the Group is well placed .... to deliver the synergies identified."
Me neither!!
It means they (finally) got full fibre broadband installed in the management suite.
No more waiting for TikToks to download for them.
Haha silly me!!
MPAC (LON:MPAC)
Agree that looks good on a quick scan.
House broker Shore hold adj. eps for 25 and 26 at 44.2p and 52.3p and introduce 60.0p for 27.
Equity Development - report here - have 45.1p and 54.7p for 25 and 26 and say "This highlights Mpac’s lowly rating; based on FY25 EDE earnings, an EV/EBITDA of 3.8x is at a significant discount to a peer group average of 9.3x, and 6.7x EV/EBITDA at our Fair Value of 865p/share".
MPAC are doing a presentation of results on Friday register at https://www.equitydevelopment.....
MPAC (LON:MPAC)
cheers - forecasts show net debt dropping from £37.5 mil at 31/12/2024 to £15.1 mill at 31/12/2026. So whilst debt may current be chunky - seems clear they are confident ref free cashflow generation (which is what its all about)
NCC (LON:NCC)
Yesterday afternoon Sky (it is always them!) came out with news that PE groups were circling the Escode business of NCC, who then issued a 'very early days' statement at 16 09:
https://news.sky.com/story/buy...
https://www.londonstockexchang...
Well, you heard it here first!! Go to https://www.stockopedia.com/co... and click the link on the first line of that post, go to 55 mins in and listen . Sky £300m to £400m - C Mills £320m to £325m!
NCC (LON:NCC) - is this another case of the bods at Montagu trying to look busy? They've just had to admit that they wouldn't be making a bid for Advanced Medical Solutions (LON:AMS) after a strange announcement that they were considering making an offer there. Even though the price fell about 20% from when they first suggested they might be interested.. I struggled at the time to see what purpose a PE house could have in making an announcement that they were considering making a bid (I realise they haven't here) which only serves to disturb the price against them. Other than to appear busy.
Anyway, I would be particularly wary of any vague statements such as this that involve Montagu as they may not have a serious interest here either.