Daily Stock Market Report (Tue 2nd September 2025) - PLUS, MBH, JNEO, EVPL, ALU, ITH

Good morning!
All done for now - cheers!
Today's Agenda is under construction.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Centrica (LON:CNA) (£7.8bn) | Two nuclear power stations in which Centrica has a 20% share. Electricity for an additional year. | ||
Ithaca Energy (LON:ITH) (£3.9bn) | Gross proceeds of £106m, 3% of issued share capital. Placing price 213.75p (yday’s close: 237.5p). | AMBER/GREEN (Roland) [no section below] Ithaca’s former private owner Delek Group and Italian oil major ENI have trimmed their holdings, raising £106m. Ithaca shares spiked after its interim results on 20 August, so it looks like these two shareholders decided to capitalise on this liquidity. While the discount may seem a little large for a £3.9bn FTSE 250 stock, Delek and ENI still control over 80% of Ithaca shares after this 3% sale, so liquidity is a bit more limited than for some comparable-sized companies. Such large shareholders can only sell when the going is good, so I don’t see anything sinister about this disposal. My view on Ithaca remains unchanged today – for investors with an interest in this sector, I think it could be worth a closer look. | |
Plus500 (LON:PLUS) (£2.1bn) | Clearing membership enables PLUS to expand futures business to new territories and customers. | GREEN (Graham) Another prestigious clearing membership has been achieved, in a move that further embeds Plus500 within the financial infrastructure of the US and Europe. I’m staying GREEN on this as this move marks further progress and another upgrade in its capabilities. It trades at a P/E multiple of 10x: not bad for the best-performing UK stock over some timeframes. | |
Oxford Nanopore Technologies (LON:ONT) (£1.78bn) | Revenue +28% (cc). LBITDA £48m, loss £71m. Cash £337m. Guidance unchanged. | ||
Uniphar (LON:UPR) (£909m) | Rev +8.6% (cc). PBT +22% (€28.7m). Net debt €198m. Confident of delivering exps. | ||
Everplay (LON:EVPL) (£592m) | Rev -10%. Adj. PBT +2% (£20m). FY2025 adj. EBITDA to be slightly ahead of current exps. | AMBER/GREEN (Graham) These shares have appreciated in price by 50% since I looked at them last. The bull thesis has played out and the stock is now in "High Flyer" territory. It passes six bullish stock screens, with half of these being Momentum screens. Today's results, despite offering "slightly ahead" guidance, strike me as being rather mixed, and the company does not currently have a permanent CEO. On this basis, I think it's sensible to moderate my stance by one notch: I'm still positive, but not as outright enthusiastic as I was before! | |
Johnson Service (LON:JSG) (£548m) | Rev +5.5%. Adj. PBT +15.8% (£25m). Further £25m buyback. Adj. op profit to be in line. | ||
Custodian Property Income Reit (LON:CREI) (£351m) | Avg rental uplift 13.5%. 1.5p divi fully covered by EPRA EPS, implying 7.9% yield. NAV 96.7p. | ||
Intuitive Investments (LON:IIG) (£217m) | Nationwide distribution of TEAM CHINA merch at Easy Joy online store, under Lucky Joy brand. | ||
Integrated Diagnostics Holdings (LON:IDHC) (£208m) | Rev +42% (revenue per test +29%). Adj. EBITDA +78%. Outlook: rev growth >30%. | ||
Ecora Resources (LON:ECOR) (£183m) | The sold subsidiary has 2% net smelter return royalty. $16.5m cash upfront, $3.5m contingent. | ||
Avingtrans (LON:AVG) (£151m) | US subsidiary wins two contracts from long-term existing customer. Rev weighted towards FY27. | ||
Beeks Financial Cloud (LON:BKS) (£146m) | Purchased small stake in Swiss network technology firm, will deploy ÜberNIC in data centres. | ||
Alumasc (LON:ALU) (£121m) | FY25 rev +13%, adj PBT +9% to £14.2m. FY26 “likely to be H2 weighted” due overseas sales. | AMBER/GREEN (Roland) [no section below] There are plenty of reasons why a construction materials group might be reporting disappointing results at the moment – but Alumasc is still doing well. Today’s results are in line with market forecasts, with profits up in all three operating divisions. Operating margins were respectable at 12%, but this extends a two-year decline from the 14% high seen in FY22. Management says that lower margins are due to a higher proportion of overseas sales. This factor is also expected to result in an H2 weighting to profits in FY26. This may not be a problem, but profits have historically been quite equally weighted across the year. When combined with the company’s mention of “short-term volatility” and “medium term growth drivers”, I wonder if there’s a slightly increased risk that results could fall below expectations this year. Broker FY26 forecasts are largely unchanged today and the stock’s P/E of 11 seems fair to me. I’m happy to maintain Mark’s moderately positive view from July, but I don’t see this as a compelling opportunity right now. | |
Severfield (LON:SFR) (£96m) | FY26 exps unchanged with significant H2 weighting. UK/EU order book £420m at 1 Sept. | ||
Michelmersh Brick Holdings (LON:MBH) (£91m) | PW: PBT -29.3% to £2.9m. UK stronger, EU “very challenging”. FY25 to be “broadly” flat vs FY24. | BLACK (AMBER/RED) (Roland) A disappointing set of results, flagging up a combination of market headwinds and one-off company problems. H2 should be stronger, but full-year performance is no longer expected to show any growth relative to 2024. That’s a big downgrade from previous expectations for earnings growth of c.25%. I’ve previously been a fan of this business, in part due to its very experienced leadership. The new CEO/CFO team lacks industry experience and appears to be taking over at a difficult time. If macro conditions improve then we could see a good recovery, but I think there’s still some risk of further downgrades. I’m less positive about Michelmersh than I was and am happy to stay on the sidelines for now. | |
Audioboom (LON:BOOM) (£81m) | All key operational elements now integrated, including ad marketplace, inventory & sales. | ||
Journeo (LON:JNEO) (£71m) | Total consideration of £12.7m for critical infrastructure protection firm that specialises in high security fencing and CCTV for utility sites and similar. Valuation: 9.3x FY25 PBT. | AMBER/GREEN (Roland) | |
Fiinu (LON:BANK) (£65m) | Will raise £1.4m by placing 9.4m shares at 15p. 50% premium to 6 Aug subscription. | ||
Tialis Essential IT (LON:TIA) (£17m) | £50m/5yr framework contract from existing customer. Improves revenue visibility for next year. | ||
Defence Holdings (LON:ALRT) (£13m) | Defence Technologies brand will provide “sovereign AI capabilities” Two MoD applications underway. |
Graham's Section
Plus500 (LON:PLUS)
Down 1% to £29.58 (£2.1bn) - New Strategic Membership with ICE Clear Europe - Graham - GREEN
Plus500 has come a long way from the days when I disparagingly referred to it as a “bucket shop”. Over the years it has grown, expanded and achieved an impressive degree of licensure in a wide range of geographies.
This trend continues today with a new clearing membership at ICE Clear Europe, part of the Intercontinental Exchange (ICE).
ICE is a financial giant responsible for many of the world’s largest exchanges, including the NYSE.
This is what clearing membership at ICE will mean for Plus500:
This clearing membership enables the Group to strategically expand its futures business to new territories and customers, further scaling its clearing services to cover a broader range of futures products across multiple asset classes, offering customers a more seamless trading experience.
“Clearing membership” means the ability to settle trades for other institutions - it’s an important and, in a financial context, a prestigious responsibility.
Plus500 already had clearing membership with ICE Clear US:
Building on the Group's existing clearing membership with ICE Clear US, obtained earlier this year, this additional clearing membership further enhances Plus500's industry-leading infrastructure, optimises cost efficiencies and unlocks opportunities to cater to a wider, more diversified B2B customer base through an enhanced clearing offering.
CEO comment:
"We are extremely pleased to secure our membership of ICE Clear Europe, which complements our existing ICE Clear US membership. As we continue to evolve into a provider of global market infrastructure, clearing memberships remain a key pillar of Plus500's growth strategy for our global futures business, and this new membership will further expand our clearing capabilities across multiple asset classes in European markets…
Graham’s view
I treat Plus500 with much more respect these days than I did before. I still think that Plus500’s retail customers are, on average, less experienced than the retail customers of other trading platforms, and I still think that I was right to be cautious about Plus500’s risk management practices.
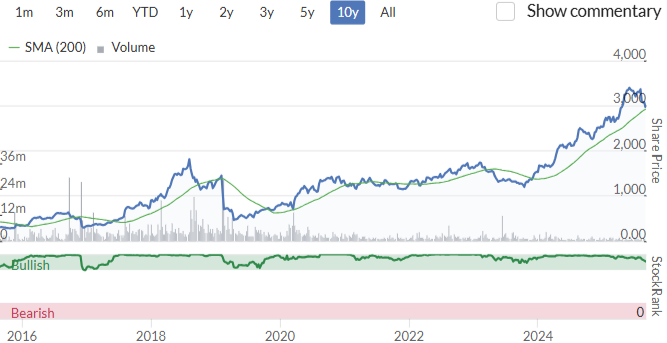
But there is no denying that whatever risks Plus500 took in the past (and possibly still takes today?), it has generated enormous wealth for its shareholders - it is the best performing UK stock over some timeframes, giving shareholders the holy trinity of share price appreciation, large buybacks and dividends.
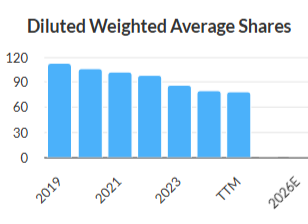
The share count continues to decline:
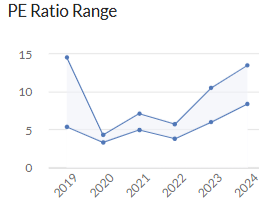
Today it trades at a P/E multiple of 10x. I think it’s uncommon for the market to allow it to trade much higher than that.
I’m staying GREEN on this, as I have done quite a while now. Please see my analysis of its recent interim results for more.
Everplay (LON:EVPL)
Down 1% to 400.1p (£555m) - Half Year Results - Graham - AMBER/GREEN
everplay group plc, a leading global independent ("indie") developer and publisher of premium video games, working simulation games and children's edutainment apps is pleased to announce its unaudited results for the six months ended 30 June 2025 ("H1 2025" or the "period").
Everplay is the new name for “Team17”, which was most famous for making Worms, but its new name is designed to let us know that it’s in a new era now.
Most revenues are from third-party IP, but its own IP still contributed 35% of H1 revenues.
Also worth mentioning that the majority of its revenue is actually from its back catalogue (140 titles), not from new releases.
The overall half-year results are as follows: revenues down, but profits up.
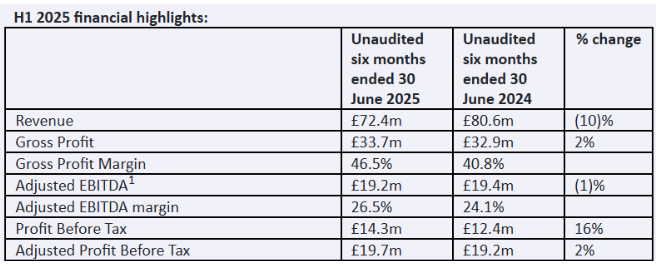
The revenue decline is attributed to various causes - timing of license revenues, fewer physically distributed sales, and a strong prior year performance of the back catalogue.
As an “indie” developer, it is less reliant on the strong performance of any particular title (in contrast with something like Frontier Developments (LON:FDEV)). It has both a large back catalogue and a steady stream of new titles.
In H1 alone we have four new titles, and another three are scheduled in H2. That’s at the “Team17” division only - there is also a German games publisher and a publisher of children’s apps.
The German publisher (“astragon”) saw a particularly sharp 35% revenue decline in H1, but we are told that its release schedule is set to favour H2 over H1.
CEO position: their CEO left rather abruptly in May, and the search for a successor continues. Frank Sagnier is Interim Executive Chair.
Outlook: adjusted EBITDA to be slightly ahead of current market expectations, those expectations being revenues of £173.6m and adj. EBITDA of £46.9m. It’s interesting that the share price is slightly down despite this positive guidance. Maybe the market is disappointed to learn that no CEO is expected until next year?
The main thrust of the outlook statement is positive:
The Group has continued to perform well to date in H2 2025, driven by the strong performance of the new releases launched in H1 and to date in H2, as well as ongoing back catalogue momentum.
New release revenues are expected to be significantly higher in H2 2025 relative to H1 2025, following the launch of new titles including Date Everything!, LEGO® Bluey™ and Firefighting Simulator: Ignite, along with the full launch of Sworn and the first dedicated products for Switch 2. In total, we expect around 10 new games to be released over the course of 2025 (GN note: that’s across all divisions).
Graham’s view
I have mixed feelings about today’s results - overall, it’s solid, but there is little to get overly excited about.
I will point out that the adj. EBITDA figure (£19.2m) converts to nearly £20m of adj. PBT - this is an example of a company where I don’t get too excited and upset about the use of EBITDA.
If we want to be really strict, the actual PBT is only £14.3m. But I’m comfortable with the adj. PBT figure.
Cash and cash equivalents are an impressive £59.5m, so it should be very secure from a balance sheet point of view.
These shares have increased in price by nearly 50% since I analysed the company in March.
I was GREEN on it then. I think that with the valuation having increased rather dramatically over the last six months, I can now moderate my view on this back to AMBER/GREEN.
It was trading at 10.6x earnings then, whereas it is now trading at 15.6x.
The bull thesis has played out - it was too cheap then, and the stock is now perhaps up with events. But I still like this company and I’m happy to remain somewhat positive on it - if I was holding it, I’d probably not be in any rush to sell, unless there was some urgent need for the cash!
I note that the share passes six bullish stock screens, but half of these are to do with momentum. It’s truly a “High Flyer” now: the type of stock where some investors might already be planning their exits.
Roland's Section
Michelmersh Brick Holdings (LON:MBH)
Down 9% to 89p (£85m) - Roland - Half Year Results - BLACK (AMBER/RED)
After rival UK brick producer Forterra recently upgraded its 2025 profit guidance, I was cautiously optimistic today’s results from premium brick specialist Michelmersh might also bring good news.
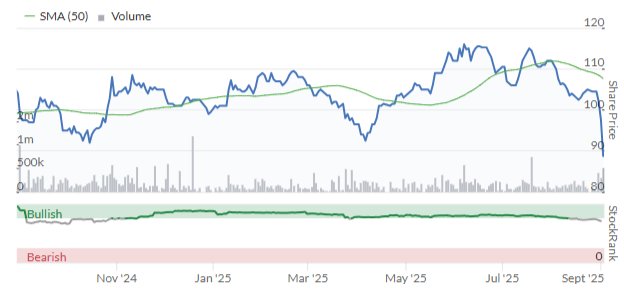
Unfortunately that’s not the case – Michelmersh has issued a profit warning today. Brokers covering the stock have cut their 2025 earnings estimates by 15%-20%.
Let’s take a look.
H1 results summary: a mixed picture
Today’s half-year figures show revenue flatlining and a sharp fall in profit in H1, alongside a big reduction in net cash. To some extent this might have been expected; we knew that significant capex and manufacturing shutdowns were planned in H1 as Michelmersh upgraded several key plants.
However, the commentary in today’s results makes it clear that combination of delays and continuing difficult market conditions mean performance was below expectations.
Revenue up 1.1% to £35.8m
Pre-tax profit -29.3% to £2.9m
Earnings per share -26.7% to 2.47p
Net cash down £1.5m (Dec 24: £6.0m)
Interim dividend held at 1.6p per share
Trading commentary: a mix of company-specific and broader market conditions seem to have weighted on H1 performance and expectations for the remainder of the year.
Shutdowns at the Michelmersh and Florens (Belgium) factories completed on schedule, with orders despatched from inventory and no impact on expected sales
A shutdown at Carlton overran by two weeks due to delays in the manufacture of a key piece of tooling. As a result, manufacturing and despatches fall below expectations. Management says this was the “the most significant drag on H1 profit”
However, pricing Industry conditions remain difficult with “highly competitive” pricing during the first half of the year as mothballed industry production capacity was brought back online, leading to elevated inventories across the sector
Michelmersh says UK brick despatch volumes are still around 25% below 2022 peak levels, but that its focus on premium products is allowing to outperform the market:
Order intake ahead of normalised manufacturing volumes in H1, underpinning a balanced order book profile for the start of H2
Even so, my feeling is that profit margins may have come under pressure to secure these orders:
Highly competitive pricing environment mitigated by a continued focus on collaboration with customers to support stable average selling prices
Belgium: this business only accounts for around 5% of sales, but demand seems to have fallen off a cliff since 2022. Brick demand is said to be 40% below 2022 levels and the company reports a further 20% fall in housing permits during the first half of the year.
As a result, production at Florens is being suspended during the third quarter, with the intention of resuming production in Q4. When combined with the maintenance shutdown in Jan/Feb, this will mean Florens has been non-producing for nearly half of 2025.
Outlook
No further maintenance shutdowns are planned for the second half of the year and management expects to report a stronger H2 performance. However, industry headwinds combined with the impact of the Carlton delays in H1 and the planned shutdown in Belgium mean that full-year results are now expected to be “broadly in line” with FY24.
To put this in context, earnings were previously expected to rise by around 25% this year.
With thanks to brokers Canaccord Genuity and Cavendish, updated earnings estimates are available on Research Tree today. These show reductions of 16-22% in FY25 EPS estimates and similar cuts for 2026:
EPS estimates | Cavendish | Canaccord Genuity |
FY25 | 8.5 (prev. 10.1p) | 7.6p (prev. 9.8p) |
FY26 | 10.1p (prev. 11.4p) | 8.9p (prev. 11.0p) |
Cavendish appears to be a little more bullish than CG. Averaging these two estimates gives a FY25 EPS estimate of 8.1p, 16% below the 9.7p consensus figure shown on Stockopedia ahead of these results.
After this morning’s (relatively modest) share price fall, that leaves MBH shares trading on a forward P/E of 11 with a possible 5%+ dividend yield.
Boardroom changes: another point I think is worth mentioning are the changes taking place in Michelmersh’s boardroom from today.
As planned, chief executive Peter Sharp stands down today and will become the company’s “industry advisor”. He’s replaced by former CFO Ryan Mahoney, who has been with the firm for around four years.
Alongside this, Michelmersh has also announced its new CFO today, Rachel Warren. She joins from logistics group Wincanton, after a career mostly spent with IAG.
What strikes me about these changes is that the company no longer has any top execs with in-depth experience of the brick industry; for both Mahoney and Warren, Michelmersh is their first job in this sector.
In contrast, Peter Sharp and former co-CEO Frank Hanna both had 30-40 years of experience in the UK brick sector.
Brick production is an intensely cyclical and capital-intensive business. I can’t help feeling that long experience might be valuable in senior leadership roles. Perhaps this explains Peter Sharp’s move to the newly-created role of industry advisor.
Roland’s view
Mark picked up some negative vibes when he covered Michelmersh’s trading update in May, noting that “pricing pressure makes it sound like hard work” to hit forecasts. Sure enough, forecasts have been cut sharply today.
I still think Michelmersh is fundamentally a decent business with good recovery potential when industry conditions improve. It’s clear that at least some of the H1 weakness was due to one-off delays at Carlton. There shouldn’t be any more issues of this kind in H2.
However, my confidence in this business is a little lower than it was, in part due to the lack of in-depth industry experience in the C-suite.
I’d also note that Michelmersh’s returns on capital are only just high enough to be of interest, in my view. The StockReport shows an average ROCE of 9.5% since 2019:
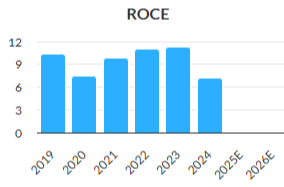
Michelmersh is now trading below its book value of £94m and still has a net cash balance. The company has a well-invested production base with no major capex planned and the ability to increase output. I’d expect cash generation to improve in H2, as well.
Given the one-off nature of much of the H1 profit shortfall, the shares could be cheap at current levels. Higher production would also be likely to support positive operating leverage and improved margins.
However, I can’t ignore the lacklustre industry outlook and evident pressure on pricing. I would imagine that 2026 forecasts still carry some uncertainty at this point.
Given our knowledge that further periods of weakness often follow an initial profit warning, I’m going to downgrade our view by one notch to AMBER/RED today.
Journeo (LON:JNEO)
Up 5% to 438p (£73m) - Roland - Acquisition of Crime and Fire Defence Systems - AMBER/GREEN
We seem to have commented on transport systems provider Journeo frequently recently – most recently yesterday, when the company announced a contract extension in its core market of bus operators.
Today’s news is a little different. Journeo has announced a significant acquisition that appears to be targeting a new business sector. The company will pay up to £12.7m to acquire Critical Fire and Defence Systems Limted:
CFDS specialise in protection of Critical National Infrastructure sites including utilities and high security industrial and commercial applications. CFDS provide a range of solutions to enhance security infrastructure including cutting-edge access control systems, complex perimeter intrusion detection, and high-performance thermal, infra-red and visual surveillance systems.
About CFDS: looking at the CFDS website and its latest accounts, its main specialist market appears to be the gas utility sector, for which it provides high-security fencing and surveillance solutions.
Here’s a summary of the last three years’ financial results for CFDS:
Y/E 30 April | Revenue | Pre-Tax Profit |
2025 | £17.3m | £1.4m |
2024 | £12.1m | £0.5m |
2023 | £13.6m | £2.0m |
These figures suggest growth hasn’t been entirely consistent – my impression from a quick review of the CFDS accounts is that the business may have suffered some growing pains and one-off project issues in FY24, in particular.
Recruitment and retention of skilled staff is also mentioned as a significant challenge.
Journeo + CFDS - a good fit? Journeo says CFDS will add to its capabilities in providing critical solutions across markets such as public transport and infrastructure, including “major railway stations, international airports and nuclear power generation facilities".
CEO Russ Singleton says the acquisition is a logical addition:
This acquisition aligns with our strategy of taking our core capabilities into adjacent markets and strengthens our offering and broadens our reach.
Valuation & Financials: Journeo will pay up to £12.7m for CFDS, with the payment structured in three parts:
£10.7m initial cash consolidation
£2m in deferred cash payments repayable after 12 and 24 months
£1m in new JNEO shares with a minimum 24-month holding period
CFDS is expected to have over £1m cash on completion, hence the total consideration is £12.7m.
Based on the CFDS FY25 accounts, Journeo is paying a multiple of just over nine times pre-tax profit.
This does not seem excessive to me, assuming the run-rate of revenue and profitability CFDS achieved last year is sustainable.
Naturally, we don’t know anything about the CFDS order book or longer-term outlook. However, demand for infrastructure security and surveillance seems likely to be evergreen and growing, in my view, so I don’t see this as a major concern.
Revised FY25 & FY26 estimates: today’s update helpfully provides details of the expected financial contribution CFDS will make during the remainder of Journeo’s current financial year, which ends on 31 December:
Revenue: £4m
Pre-tax profit: £0.4m
FY25: Previous market expectations were for group revenue of £52m and adjusted PBT of £5.2m. Adding the CFDS contribution gives us new revenue and PBT guidance of £56m and £5.6m respectively.
Broker Cavendish has translated this into a FY25 EPS estimate of 26.5p, an increase of 6%.
FY26: Journeo expects CFDS to contribute £17m of revenue and £1.4m of adjusted PBT in FY26, in addition to existing expectations of £55m and £5.8m. This gives us new revenue and PBT guidance of £72m and £7.2m.
Management says this guidance is “prudently allowing” for integration costs. However, what strikes me is that Journeo expects CFDS’s performance in 2026 to be flat relative to its FY25 performance. For whatever reason, the growth delivered by CFDS last year isn’t expected to repeat next year.
Cavendish has increased FY26 EPS estimates by 20% to 33.2p as a result.
Roland’s view
This is quite a large acquisition for a company of Journeo’s size. The acquisition consideration is nearly 20% of the group’s market cap and CFDS will add over 30% to group revenues.
Journeo shares are up by 5% at the time of writing, reflecting this morning’s FY25 EPS upgrade. That suggests investors are not yet pricing in any further gains from cross-selling, synergies or improved market reach.
I am inclined to take a neutral view on this acquisition as well. I can see that it has the potential to provide adjacent services to some of Journeo’s current offerings, but I can’t help feeling that there is only limited overlap.
In addition, integrating large acquisitions always carries some risk and I would be interested to understand why no further growth is being forecast for CFDS over the next 18 months.
On balance, I’m going to downgrade our view by one notch to AMBER/GREEN today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

51 comments
Sorry, I don't comment often, it was regarding the stock report conclusions on Michelmersh 02/09
Hidden implications in the boring announcement today from Sosandar (LON:SOS).
A capital reduction on the balance sheet is necessary for the company to have the ability to pay dividends or do a share buyback.
Rationale in the full shareholder circular here: https://wp-sosandar-2021.s3.eu...
This is interesting because:
(I hold in the Boon Fund)
Days like today where i wonder if it is just better to invest in index funds...
And this is not a knee jerk reaction, been thinking about this a while. If you cannot best an index fund, why bother?
Lot less work too, i am lazy!
I'm in my 40's, work full time, family etc etc
A short on fste250 index mcx looks a sure thing rather than fste100 international shares $ based
You are recommending a short to an amateur investor ?
You could get sued for that !
You have a v good point and I have been gradually moving across to such trackers. I have four at the moment covering various areas.
I have found that you can research a company until the cows come home, all looks well and suddenly a profit warning appears. Surprise, surprise, you discover that the directors have been economic with the truth.
For a full time worker I’d say you seem to spend an awful amount of time during the day posting comments on sites like this . And always saying exactly the same thing about how unappreciated your shares are by the market : join the club !
So I think you are quite right. Its clear that investing in individual shares is not for you, as much as anything for your mental health.
Put it all in a tracker and forget about it is my advice
As Investor Hunter has already implied, Alumasc seems worthy of a fairly full mention, if you can manage it. Capitalisation of about £130 million, so very much within your Small Company niche. As an amateur investor, I have little to go on, apart from Stocko data, but I am impressed by their website (most British companies have sub-standard ones). I hold already, and topped up today.
Try registering with Investor Meet Company (it's free!) and you can watch the presentation the CEO and CFO of Alumasc (LON:ALU) just gave this afternoon. Of course they will accentuate the positive but it gives a good idea of the underlying drivers which have been allowing them to outperform a sluggish construction market and their initiatives on new product development, entering new export markets etc. I wish Michelmersh Brick Holdings (LON:MBH) would do the same! (I hold both)
Michelmersh Brick Holdings (LON:MBH) gave a presentation today on the Engage platform. There was a link in the results announcement. I do not know if there is a replay facility.
Thanks!
Roland, I refer to a recent Article by you on "Cash Rich Companies". Question: How do I set up the Screen?
The experienced leadership seems to be exiting with a whimper --- perhaps some fresh faces are needed that can harness the experience within the business to start performing to at least set expectations rather than significantly below them.
You haven't replied to a particular post nor mentioned the company in question. ????
Solid full year numbers from Alumasc (LON:ALU) . 13% revenue growth and 7% organic growth vs. a rubbish-to-slow UK construction/building market is very impressive. Shows product is really in demand despite tough markets.
Yes good numbers year passed, wouldn't be so sure next full year
Getting into dangerous territory on 10-yr and 30-yr gilt yields https://tradingeconomics.com/b...
If governments can't get a grip on inflation and deficits ....markets will force them to!
Rachel Reeves gone by the end of the year.
Sooner the better, the market seems to be very nervous about the budget
Deja vu
But whoever takes over could be worse.
Ange ? think of the tax savings though
This is a systemic problem facing all western economies - welfare bills exceed what countries can afford. But the UK's lack of growth and budget deficit is a particular concern - as shown by the long-term interest rates. The risk? A brewing sovereign debt crisis. That was the big fear during the freefall of the 2008/10 financial crisis - and the real reason that certain banks had to be bailed out. Hence the moves into gold.
Any thoughts on how you see it playing out Topvest ? no western governments seem to want to cut back on spending which is what they need to do so if they won't do that I can only see yield curve control and higher inflation ahead.
I was watching a podcast yesterday that was saying the US has added a trillion dollars to the deficit in the last two months alone all be it a lot of that is being used to refill the tga.
There still seems plenty of appetite for short term debt in the US at the moment so they most likely have a much longer runway than the UK before the problems really start to bite but I can't help but feel Trump will speed up their day of reckoning also.
So many stocks on sale right now!
Be aware that stock prices can go lower and move to the bargain bin quite easily.
Yes feels like the autumn sell off is just beginning - wouldn't be rushing in just yet.
I certainly won't be
Howard Marks writes good memos. His latest is below in the link. He isnt overly pessimistic but does suggest to 'reduce aggressive holdings and increase defensive holdings'
https://www.oaktreecapital.com...
Anyone getting a little nervous?
France seems to be a catastrophe waiting to happen. Gilt yields at 23 year highs here. Reeves under extreme pressure and talk of her being squeezed out depending on which papers you read.
Never mind the US deficit, I see Ray Dalio is warning again, and lofty expectations for AI stocks.
Maybe it is an age thing but I am starting to take money off the table.
I am nervous as well .... we are probably similar in age :-)
AI is a bubble waiting to burst, whilst new industries will be created, productivity will increase for users of AI ... i do not believe the hundreds of billions being invested will generate a return for all investors ... so there will be few winners and many losers. The difficult question is when to get out !
Any to your point, governments cross the world have taken on too much debt. Not many options - Austerity, Default, Inflate ... all will cause indigestion. The million dollar question is if you take your money out of the market, where do you invest to generate a return ?
A zero return could be a good result if there is a crash
Gold or gilts would worth considering. Even cash in many share ISAs, now gets interest, l get 4% at the moment. Cash ISAs as well pay around 4%, you can quickly transfer between Share ISA ps and cash ISAs now on some platforms.
Hello rusty, agree with you there
Been nervous for several years now - What with Ukraine and Gaza, Trump and Putin to name but a few - but what I think and what the Market think seems to be miles apart so the end is not quite in sight - yet
Gilt yields are a key issue. A number of us here on this Board had the view back in Spring that the fiscal headroom (circa £9 billion) would be insufficient against rising gilt yields. So it has proved.
Autumn budget will need to recoup another estimated£40 billion to balance the finances and I would guess that there will be another shortfall of a further £20 billion in spring 2026.
The Prime Minister has realised the game is up and as a last throw of the dice will probably replace Ms Reeves . I doubt that this will help the financial situation - your can only raise these sums of money from changes in big taxation - VAT, Income Tax and NI.
Difficult times ahead..
Remember: if all the information you're getting is from News sources, then it is very likely to be biased negatively in this day and age.
Gloom and doom headlines sell, and negative articles gets pushed to the top of the algorithm and shown more often.
Don't disagree with any of the above other than Ray has made a good living out of predicting the end of the world for the last two decades.
I think you are expressing what a lot or us feel Don’t lose money “Warren Buffet”
Hi Graham,
Any chance you could look at Integrated Diagnostics Holdings (LON:IDHC) today please?
Thanks, Graham.
Ok Graham! thanks for the request.
Journeo (LON:JNEO) Repetition of my post yesterday pm….Journeo (LON:JNEO) Millaree has a fair point, but the reality of keeping in business (and critically meeting forecasts in the market) is firstly maintaining momentum in securing and growing existing contracts. The meaningful game changers of acquisitions and new contracts are likely far less frequent events. JNEO will use its growing cash pile, but to make a fully informed, de-risked, earnings enhancing, meaningful acquisition takes time. I feel confident that we shall see such an event in the coming months. Until then maintenance of momentum of the likes announced today will do me fine - and the frequency of contract announcements is strong.
This acquisition may not be quite as some might have expected, but to my mind it looks as though Journeo has achieved just what I describe - execution will be interesting. And significant cash still remains.
Journeo (LON:JNEO) - On first reading, it looks to me like they have overpaid quite significantly. for a non-core business with no clear strategic fit. I will be interested to read other's views on this. I hold.
It does not look that expensive to me. PBT is forecast £1.4 for 2026, there is some cash and assets as well. That is below Journeo (LON:JNEO) PE ratio.
Yes it does look non core but they expand into different areas that could be a good thing. Security will be key in the future, look at the cyber attacks on Marks and Spencer (LON:MKS) and the NHS.
Security will be key in the future, look at the cyber attacks on Marks and Spencer (LON:MKS)and the NHS.
The target installs CCTV. It’s hardly Crowdstrike Holdings (NSQ:CRWD) or Palo Alto Networks (NSQ:PANW)
Like you, however, I don’t think they’ve overpaid. The question is whether they’ve over-reached into only mildly-adjacent services, or it’s a masterstroke?
Journeo (LON:JNEO) The Cavendish view is positive. EPS upgraded by 11% for current FY and 20% for FY2026. TP of 602p - nicely aligned to LTIP target.
Journeo (LON:JNEO)
Journeo (LON:JNEO) - On first reading, it looks to me like they have overpaid quite significantly. for a non-core business with no clear strategic fit. I will be interested to read other's views on this. I hold.
I could see why you would think that it does appear left field - Journeo are at their heart very much primarily an IT services company nowadays. So i see that ITR protection systems is very complimentary to what they do. Look at their current clientbase and ask yourselves if there current client list could benefit from some of the Crime and Defence technology and there is to me compelling possibilities ref cross selling - this company had £3 mill of admin costs too - so intergate into main company and there areb possible efficiency gains here too.
Looking at the 2025 results the company increased sales from £12 mill to £17 mill last year alone. So seems like company is doing well. Looks like its husband wife company too - so perhaps more scope Journeo to push business forward compared to 2 people who are getting closer to perhapos having plans to retire.
£1.4 PBT added in for next year to bottom is pretty decent sum.
So yes i agree "not cheap" but if it brings sustainable extra profits of £1 mill plus at bottom line long term that should pay dividends.
I re-crunched some figures ... it still looks expensive, but not (as I posted before) "excessively so". I am still not convinced on strategic fit. Crime and Fire Defence Systems install security perimeter fencing and CCTV. The other side of the coin is that with Putin's goons looking at asymmetric deniable ways of hurting the UK, this will be a growth area.
Home » Crime and Fire
Journeo (LON:JNEO)
I am still not convinced on strategic fit.
Journeo do CCTV and remote monitoring solutions themselves do they not? Looking at the customer base could some of their current customers have a need for the products of Crime and Fire i would say yes - it looks like there is stuff that Journeo has not concentrated on before but customers might need some of that stuff. Plus the other way too too. It would seem to me there is scope with regard to the cctv element of both units to be merged so that costs are reduced and best overall solution is acheived. the limited customer list on the wesbite is decent with the likes of Sellafield. I would like to think ten potential for SAAS type revenues is decent in acquired company if they need to provide continual ongoing servicves ref products installed.
I hope you are right as I hold a decent position and will continue holding. This acquisition also makes me wonder if Journeo have run out of decent targets in their core competency.
The sector Journeo (LON:JNEO) operate in doesn't seem that target rich - at least not in terms of Plcs. Only Tracsis (LON:TRCS) looks to be something of a comparator along with Cordel (LON:CRDL) . Clearly happy to be corrected. I cannot find much in the way of private companies either. This could a good thing relative to a lack of competition, but possibly limiting in acquisition opportunities. That said those in the private sector are harder to identify and generally where they exist will often only be for sale when the owner, or one or more of the principal founders, needs to cash in. I believe they have other targets and that this acquisition has come about through historical relationships, knowing the company well, seeing its benefits and opportunities and the fact that one of the target's founders wished to cash in and retire.
Journeo (LON:JNEO)
This acquisition may not be quite as some might have expected, but to my mind it looks as though Journeo has achieved just what I describe - execution will be interesting
At a first glance it does seem somewhat outside their core competence zone perhaps - however to me this looks an absolutely cracking deal. They have had the confidence to today update 2026 PBT expectations by £1.4 mill - so thats a cracking uplift to expectations for next year - hopefully onwards and upwards something towards £7 mill post tax profit in 2027 - with current market cap of £70 mil imho that makes the current price look good value despite the shareprice already being close to historic highs. So whilst price paid may not be a bargain here the prospects ref that new acquired unit look sound.
. The Acquisition will also have a positive impact on FY26 revenue and adjusted PBT, which are expected to increase by £17m and £1.4m respectively, above current FY26 market expectations of £55m and £5.8m