Daily Stock Market Report (Mon 1st September 2025) - KNOS, JNEO, SUP, TIG, DOM, DIA, XPF, SATS

Good morning!
Meteorological Autumn has begun and, as usual, we expect a vast quantity of interim results statements to rain down on us this month!
All done for now, cheers!
Spreadsheet accompanying this report: link (last updated to: 11th August).
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Great Portland Estates (LON:GPE) (£1.24bn) | Acquired long leasehold in The Gable, WC1, for £18m (£409/sq ft). Net yield 6.4%, will refurbish. | ||
Kainos (LON:KNOS) (£851m) | After “solid Q4 2025”, expect FY26 rev at upper end of forecasts with adj PBT in line (f/c: £66.4m) | AMBER/GREEN (Roland) While today’s update is not an earnings upgrade, the tone and content of the commentary do suggest improving momentum and a likely return to growth for this IT services group. The valuation doesn’t seem unreasonable to me on a forward P/E of 16, especially given the strong net cash position. I think it’s fair to upgrade our view by one notch to reflect the seemingly more positive outlook. | |
Genuit (LON:GEN) (£840m) | Commercial ventilation provider, focused on UK education sector. Paid £55.6m (12x FY25E EBITDA) | ||
Domino's Pizza (LON:DOM) (£771m) | SP +8% | AMBER/RED (Roland) [no section below] Investors have cheered Domino’s decision to splurge £20m on buybacks just weeks after the stock slumped on a profit warning. In accounting terms, the market may be correct – my sums suggest this buyback could generate a c.12% effective return at current share prices. Broker EPS estimates have been notched 2% higher today, accordingly. As always with this business, my concern remains that the balance sheet looks poor to me, with negative book value and more debt than I would like to see. Today’s update suggests year-end leverage will now be 2.3x EBITDA. That’s probably affordable for Domino’s, but profits are expected to fall for the third consecutive year in 2025. In this situation I would prefer to see the experienced CEO focusing on operational improvements and deleveraging, rather than debt-funded financial engineering. With the stock trading at 10-year lows on a P/E of 11, I acknowledge that Domino’s could be cheap. However, I’m going to leave our view unchanged today as there’s no new information on trading. | |
Craneware (LON:CRW) (£758m) | New $100m/3yr facility on lower rates. Also initiated $284.2m proposed reduction of capital. | ||
Supreme (LON:SUP) (£211m) | Paid £1.65m for brand + up to £3m for inventory/defcon. Revenue previously peaked at £8m. | AMBER/GREEN (Graham) This may be a controversial stance seeing as Supreme is heavily involved in vaping distribution and it has a majority shareholder (the CEO). But on valuation and business prospects, I like the outlook for shareholders here. I tend to be a fan of very small, bolt-on acquisitions, and Supreme are using them both to diversify away from vaping and to increase their access to retailers. I like what they're doing. The shares trade at a P/E of about 10x. | |
Gateley (Holdings) (LON:GTLY) (£170m) | Paying up to £9m for “boutique IP firm” w/ rev £4.7m, adj PBT £1.4m. Consideration 75/25 cash/shares. | ||
Team Internet (LON:TIG) (£152m) | Rev -36% to $263.9m | AMBER/RED (Roland) [no section below] | |
Activeops (LON:AOM) (£130m) | Previous termination by EMEIA ControliQ customer is now fully reversed with contract renewed. | ||
Dialight (LON:DIA) (£87m) | SP -7% Confident of meeting PBT exps (FY 3/2026). Cautious on sales outlook. Demand remains soft. Adjusted PBT forecast is $5.7m (£4.2m). | RED (Graham) [no section below] Some curious wording, with the Board saying “they are confident of meeting market expectation” but this applies to PBT only, not to revenues, and it sounds like revenues are under quite a bit of pressure. I was RED on this when I reviewed it last year. Full-year results published in June (for FY March 2025) showed the company making heavy losses, thanks to £21.6m of “non-underlying items”, which are primarily to do with a legal battle against a former manufacturing partner. These results also included another “going concern warning”, due to the risk of breaching bank covenants. Net debt was $17.8m. With a poor-sounding update today, I think RED remains the correct call here, from a risk point of view. Note that high-risk shares can still perform extremely well - these shares are in fact up by over 70% since I reviewed them last year. But I wouldn’t sleep soundly owning this stock. | |
Journeo (LON:JNEO) (£68m) | Variation to £10m First Bus UK agreement. Add’l £3.5m. Option to extend by further two years. | GREEN (Roland) [no section below] Another week, another contract win for this transport systems provider. In this case, a £10m deal agreed with First Bus’s London unit in May has been extended by a further £3.5m to include the provision of the company’s latest 5G vehicle gateway, digital CCTV and digital wing mirrors and field service maintenance. Once again, there’s no detail on the financial impact of this deal, but I’m happy to remain positive, given apparent strong momentum here and a very reasonable cash-adjusted FY25E P/E of 14. Journeo’s interim results are due later in September, which should give us the chance for a more in-depth review of this situation. | |
MTI Wireless Edge (LON:MWE) (£43m) | Order from existing customer for construction and delivery of integrated shelters. Approx $1.1m. | ||
Eenergy (LON:EAAS) (£23m) | Great British Energy Solar Partnership Midlands Lot 1: solar PV systems for schools. | ||
XP Factory (LON:XPF) (£17m) | March 2025 results. Rev +19%. 3 new Escape Hunt sites. Adj. op profit £3.5m. Cautiously optimistic re: meeting expectations. Net debt £4.8m (March 2024: net cash £0.1m). Outlook: recent openings trading in line or ahead of expectations. Unseasonal weather impacted Q1. Q2 has rebounded with 8.6% LfL growth at Escape Hunt, 0.2% LfL growth at Boom. | AMBER/RED (Graham) [no section below] The owner of Boom Battle Bars and Escape Hunt reports another statutory loss, consistent with its track record. I tend to be harsh on leisure businesses (restaurants, cinemas, and the like) that trumpet adjusted EBITDA despite depreciation being one of their heaviest and most important charges (£3.8m this year for XPF). Revenue is up 19% with increasing scale; more meaningful are the 3.2% like-for-like growth at Escape Hunt and the 2.3% like-for-like growth at Boom. With increased labour costs working against the company, I fear that faster LfL growth is needed than it’s currently achieving. On the balance sheet, tangible equity is zero. I think the market is pricing this correctly by keeping it firmly in nano-cap territory for the time being. | |
Satsuma Technology (LON:SATS) (£13m) | Quarterly results (to August) plus restated quarterlies to May. Revenue ≈£0. £169m raised. | RED (Graham) [no section below) The key point here is that the convertible loan note has a conversion price of 1p per share, vs. current share price 2.4p). It seems to me that investors at the current share price are asking for big trouble, as logic dictates that the share count should explode. | |
Chill Brands (LON:CHLL) (£11m) | Primary distribution partner in UK for RELX vape company (not RELX plc!). | ||
Abingdon Health (LON:ABDX) (£10m) | Successful establishment of activities at Madison, WI with five development projects underway. |
Graham's Section
Supreme (LON:SUP)
Up 2% to 183p (£218m) - Acquisition of 1001 carpet care brand - Graham - AMBER/GREEN
An interesting little deal for Supreme:
...the acquisition of the trade and intellectual property of 1001, the iconic carpet care brand trusted by consumers for decades ("1001") for a fixed consideration of £1.65 million (including £0.35 million of deferred consideration) from the US-based WD-40 Company. The transaction also provides for the purchase of inventory at book value, with additional contingent consideration, associated with future sales growth, up to a maximum of £3 million.
Supreme is perhaps most well known for its vaping brands, but it has a range of activities and brands beyond that.
88vape
Typhoo Tea
Battle Bites - protein bars
Millions & Millions - vitamins
Elfbar vape distribution
Duracall/Panasonic battery distribution
See here (external link) for the complete list.
While I'm generally cautious when it comes to M&A, I have no issue when it comes to small, bolt-on acquisitions like this.
At its last full-year results, Supreme reported net cash (excluding leases) of £1.2m - a modest figure, but PBT was over £30m. In the current financial year, PBT is forecast to reduce only slightly. So current profits should easily pay for today’s acquisition many times over.
The strategic rationale sounds smart to me:
This acquisition is fully aligned with Supreme's M&A strategy, strengthening its portfolio of everyday essential consumer goods. With Supreme's vertically integrated platform and distribution network spanning 40,000 retail outlets, 1001 presents a compelling opportunity to accelerate growth at minimal incremental cost….
Expansion of Supreme's portfolio with another well-recognised consumer brand
Immediate earnings enhancement
Access to new retail customers, including Aldi
Longer-term potential to develop 1001 into a broader household cleaning brand, a high-growth category particularly within the discount retail channel
Estimates: we are told that 1001’s revenues for FY August 2025 are expected to be c. £4.5m. It looks like Equity Development have left their estimates unchanged for now: for FY March 2026, they forecast revenue of £240m (+4%) and adjusted earnings per share of 19.5p (down 5%).
Graham’s view
This reminds me very much of the Typhoo Tea acquisition - that was another well-liked old British consumer brand, bought up by Supreme at a modest price (£10m). This is even smaller than that, but the motivation looks similar.
The big picture for Supreme is that it is grappling with the ban on single-use vapes. That ban has been in place for a few months now, and my understanding is that the vape industry has moved on to rechargeable and refillable systems that are in line with new regulations. Supreme sells 88vape, Lost Mary, Elf Bar and other vape brands that are compliant with the new rules.
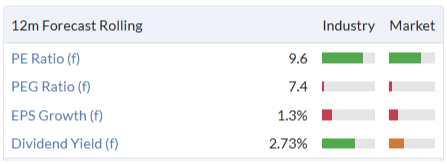
While noting that Roland was AMBER on this in July, I would tend to have quite a bullish view on smoking/vaping as an investment category (please note that I own BATS). Therefore, I’m inclined to be moderately positive on Supreme at this valuation:
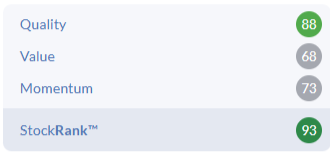
I also note a StockRank of 93 (and it’s a Super Stock):
When it comes to management, I would have a positive view of their M&A strategy, as deals like that announced today (and Typhoo Tea) strike me as opportunistic, interesting, and quite low-risk.
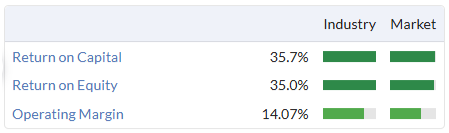
Supreme has earned excellent quality metrics over the years, which I think helps to prove that it’s more than just your standard low-margin distributor. I think of it more as a brand owner, although its pure distribution activities have also been highly profitable:
The CEO behind the strategy is a 56% shareholder. I didn’t realise that he owned so much of it, but I did expect him to own a large percentage - that’s consistent with an ambitious but low-risk M&A strategy.
Some people will want to stay away from any stock with a majority shareholder, and others (for good reasons) will avoid the vaping category. But on valuation and its prospects, I have to say that I like the outlook for shareholders here. So I'm upgrading our stance by one notch. The main risk is that vaping profits will be volatile, and there is vulnerability to any future regulatory changes. But as things stand, it seem to me that the industry is successfully navigating the changes announced so far.
Roland's Section
Kainos (LON:KNOS)
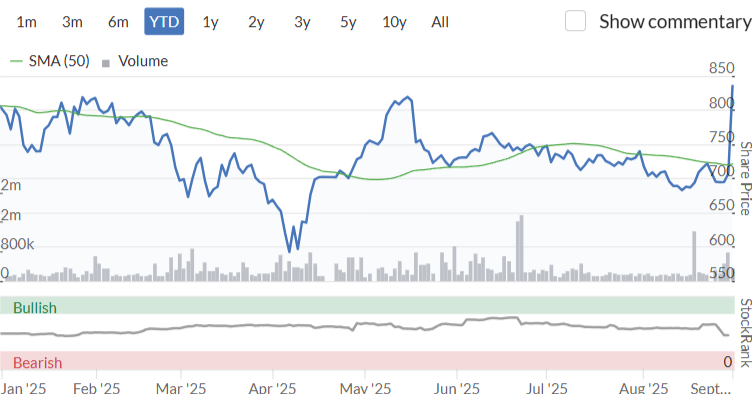
Up 18% to 836p (£988m) - Roland - Trading Statement - AMBER/GREEN
Today’s half-year update from this IT services provider guides investors to expect revenue at the upper end of forecasts for the year ending 31 March 2026 (FY26). Profit forecasts for FY26 have been left in line for now, perhaps opening the door for an upgrade if momentum remains strong.
The market has given this news a resounding thumbs up.
Let’s take a look at the main points from today’s update;
Following a strong sales performance in Q4 2025, Kainos delivered “further sequential improvement” in H1, creating “opportunities for further operating progress” during the rest of the year;
Kainos is recruiting additional staff and ramping up use of contractors to support new projects across all three of its operating divisions.
A brief summary of highlights is provided for each of these divisions.
Workday Products (add-ons to the Workday (NSQ:WDAY) system): “strong growth”, passing $100m annualised recurring revenue (ARR) in July. Working with partners including Diageo on a new Pay Transparency product. This is due to launch in Q3 to support the EU Pay Transparency Directive that comes into force in June 2026;
Workday Services: Kainos is a specialist in deploying Workday’s Finance, HR and Planning products and expects to report a return to growth during the current year, “driven by improved results in our core European and North American markets”
Digital Services (in house software products developed for clients): “secured several significant programmes” including new contracts with the Home Office, NHS England and the Driver and Vehicle Standards Agency. Also seeing strong revenue growth in North America, but performance in the commercial sector during H1 remained “muted and below prior-year levels”.
Outlook & Estimates: today’s update provides fairly clear guidance as it includes details of current consensus forecasts – this is very helpful for investors trying to digest RNS updates efficiently and should be standard practice, in my view.
Kainos says FY26 revenue is expected to be at the upper end of expectations, while adjusted pre-tax profit is expected to be in line with current consensus forecasts. This gives us the following guidance:
Revenue: at the upper end of £378-393.4m
Adjusted pre-tax profit: current consensus is £66.4m
There’s also an updated note available from broker Canaccord Genuity on Research Tree today - many thanks. CG’s analysts have left their FY26 estimates unchanged for earnings of 51.1p per share.
That puts Kainos on a current year forecast P/E of 16 at the time of writing.
Roland’s view
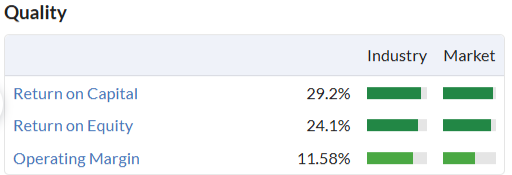
Kainos reported net cash of £134m at the end of March and the group’s CEO is a 5% shareholder. When paired with the group’s impressive quality metrics, this is enough to make me think it might be an above-average business:
Profit growth since the 2016 IPO has been strong, albeit inconsistent:
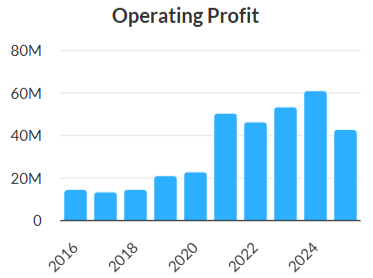
Kainos benefited from exceptional growth in healthcare revenue during the pandemic and this has subsequently normalised. However, today’s update strikes a confident note. I think it could be a sign that the business is now returning to a more normal growth trend.
Graham and I have taken a neutral (AMBER) view on this IT services and technology group on three occasions since last November’s profit warning:
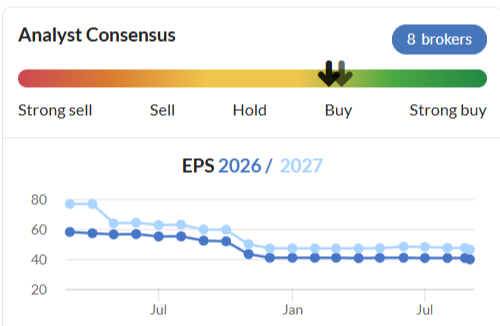
Today’s update has triggered a double-digit share price gain, but I think it’s worth remembering that profit expectations are unchanged today – this isn’t a big upgrade.
Even so, I think the tone of today’s update provides some reassurance that last year’s profit warning is firmly in the rear-view mirror. I’m also impressed by the group’s seemingly strong presence in the UK public sector – an area where IT spending seems likely to increase.
While I note Stockopedia’s Falling Star styling, I think we could soon see this improve if Kainos continues to display positive momentum. I’m going to tentatively upgrade our view to AMBER/GREEN today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

52 comments
Supreme (LON:SUP) The majority of their revenue comes from vapes. They’re basically a listed corner shop.
Kainos
One relevant point not mentioned to day. Brendan Mooney retired a couple of years ago.
He clearly was not happy with way company was being run.
Last year he returned as CEO and we are now seeing the benefits of his return.
He owns over 5% of equity.
I hold.
There was an Intrerview this morning with Cohort on Radio 4 , not sure if it was the Chairman or CEO as I came to it late he sepcificaly stated that Cohort were involved with suppling items to the new warships.
Anyone on here a member of an investment club? My village investment group received a very sad letter from ii over the weekend. Basically they have notified us that they are shutting all investment group accounts. They give no reason for this. They have given us two months to get out and find another broker. If we don't we will have our access to our account severely restricted and will have to pay a penal account charge.
The letter ends 'We'd like to thank you for being a valued ii customer'. Yeah, right.
Is this the start of Aberdeen's enshitification of ii? (look it up, it's a real word).
I suspect in the modern world its just too much hassle doing - if its unecessary admin hassle it make sense that they dont support to keep costs down for individuals. Not nice but fact of life.
i wander if practicably speaking its possible to set something up on trade212 or similar and do matched trades - if thats now going to be the norm here and you cant get replacement provider.
its not their fault that money laundering rules are such now that doing anything is a reet chow.
I like the thought of our investment group being involved in money laundering.
Groups are limited to a maximum of 20 members. We each put in £20 monthly. It’s option money and social not serious.
I’d like to know what lies behind their decision.
well thats the problem with rules
you have to "know your clients" at the outset thats basic on every level now with many entities and hmrc are pushing up standards (other than their own) - perhaps they may have been able to gloss over that perhaps in the past but i suspect not so much nowadays. So much more mechanical and less room for saying its trivial so we dont need to bother compared to the good old days.
Thanks. Also learned “crapification”.
Same thing happened to us ,difficult to find another broker but eventually bestinvest agreed to take us .
Thanks Mike, I will try them.
My club too had the sod-off letter from ii and I have spent a long time phoning/emailing around today. AJ Bell, Hargreaves Lansdown, Charlie Stanley and Halifax have likewise withdrawn share club services. I thought I had cracked it with iDealing whose website specifically referred to SCs but not so, website needs updating : sorry (huh!) for your time wasted.
James Latham (LON:LTHM) announced on Friday they have received planning permission to build their own national Distribution Centre somewhere in East Anglia at an estimated cost of £65m . I'm keen to find out where this will be and try to understand the economics of such a high spend for this company. Having tried over the weekend Ive failed to find any reports of just where this new build will be - yet it must be public knowledge if planning permission has been granted. Has anyone any input - thanks
James Latham (LON:LTHM)
and try to understand the economics of such a high spend for this company
What is puzzling to me is how this company has managed as long (250 years plus?) as it has done without a specific national Distribution Centre.
They have laid out the logic below - and i would say for a long established company like this its likely to get a very long period of use out of a huge investment like this. Ok its not nice to see cashflow from 2 years profits vanish but the facts are i would trust a long established company like them to know what they are doing - and it would have seem pretty obvious benefits to me having one large central hub - thats "up with the times" so they can push the business forward. They are possibly looking at timeframes over the decades where the future payback of having top notch facilities will make life easier. Automation and technology has moved on so much over the last 5-10 years - now is probably a pretty good time to be investing in stuff like this imho.
The NDC will provide more control and security over the storage of imported products, help support development of value-added products and allow the Company to increase its product ranges and improve stock throughput. The NDC will also improve the internal distribution service within the UK allowing depot locations to hold a wider balanced range of products and improve service and product availability for customers and the business to continue to grow through the existing depot footprint.
I am not currently holder (current price looks decent value - but they havent exactly shot the lights out the last couple of years) but if i was i would be happy enough with a one of investment like this bearing ikn mind how long the company has been established and is likely to continue doing what it has done.
James Latham (LON:LTHM) As a holder of these shares I’m really encouraged that they are using their cash to invest in the long term future of the business. And I have confidence in the management and owners that they know exactly what they are doing.
I much prefer to see this rather than buy backs/ special dividends/ etc etc from companies - it almost suggests that such companies have run out of ideas as to how to improve and grow their businesses by using their cash resources, which sounds bizarre to me.
With the markets a little stagnant and moribund, and perhaps with management having some time to breathe, in
many ways its an ideal time to focus on these kind of self help projects to improve and embed efficiency/ profitability/ customer appeal. So that when things do pick up, as they surely must, they are in a perfect position to benefit.
Here you are Bohenie- this is Gemini AI research generated so be aware"
Location and Cost Update
James Latham PLC announced on Friday, August 29, 2025, that it has received planning permission to build a new National Distribution Centre in East Anglia. While the specific town or city has not been publicly disclosed, the company has confirmed it will be a purpose-built, 300,000 square foot facility.
Regarding the cost, the company's official announcement specifies a total investment of £45 million, not £65 million as previously reported. This will be funded from existing cash resources and is broken down into two parts: a £6 million initial investment for the land and a further £39 million over the next two years for construction and fit-out.
The Economics of the Investment
This substantial investment, while high, is driven by a long-term strategic plan to "future proof" the business and improve profitability. The key economic rationales are:
James Latham (LON:LTHM) thanks - I don't know where I got the £65m fig from so good to see its correctly £45m but we still don't know where in East Anglia it will be located - which as I stated seems strange as planning permissions are surely supposed to be public knowledge ?
It must be in the west part, if it has good transport links. Maybe near Huntingdon?
Just found this " it will be near the A14 and west of Cambridge,"
I read that it will be near a port so Felixstowe region is a possibility.
No it is near Cambridge, according to one report. Felixstowe does not have good transport links. The A14/12 is a nightmare. It is a national distribution centre, so it makes sense to be fairly central, not out on the east coast.
I don't know why this is secret.
Thanks Rusty and you are right about Felix. Also bear in mind Tilbury also growing in importance - hence the depot they already have and upgrading at Thurrock. The A14/M11 makes sense - but how can it be secret ?
Also the A1 is close by. Maybe best not to rely on one port, l don't know about now but ships were waiting days to get into Felixstowe a few years ago. Some went elsewhere, such as Rotterdam.
You're welcome :)
(may or may not be a hallucination)
James Latham plc, one of the UK’s largest independent distributors of timber and panel products, is in the process of developing a new national distribution centre (NDC) near St Ives, Cambridgeshire.
Location: A 120,000+ sq ft site at Glendale Industrial Park, St Ives (Cambridgeshire)
Purpose: To serve as a central national hub for Latham’s logistics, improving stockholding and delivery efficiency across the UK
Status: Planning approved in 2023, development ongoing in 2024–2025
Hmm - Glendale appears not to exist. The development will be 300,000 sqft not 120000 and pp has only just been granted so Ive no idea where your report comes from - hallucination indeed!
Agreed Bohenie - I can't find anything to back it up. Chat could be omniscient, prescient or plain mad. Only time will tell. There's a fine line between genius and madness. Very odd.
James Latham (LON:LTHM) I hold. Personally, I have absolute confidence that these guys know what they are doing and will have thoroughly planned this project - after all, they have a large amount of their own money at stake ! So, exact location for me not really a concern.
Carclo (LON:CAR) is back from suspension. Shares are up 13% but Stocko is showing this as still suspended.
Management of Team Internet (LON:TIG) are pleased to report that all three segments have "delivered well against their strategic objectives". That is just as well because revenues are down a thumping 36% and they made an operating loss of $7m against a $23m operating profit last time. One of the more ridiculous reports about 're-positioning' that I have seen! I don't hold.
September's investment trust thoughts board is here https://www.stockopedia.com/co...
Investment trust thought board
Thanks Charles for posting this. It is one of my favourite sections of the Stocko. Much appreciated.
Thank you Yadi
Journeo (LON:JNEO) Yet more positive news. Momentum here looks to be stronger by the month.
Journeo (LON:JNEO)
Momentum here looks to be stronger by the month.
I think thats perhaps a bit of a stretch. The company needs to sign continual contracts to make ends meat.
Note the comany has not really done any meaningful upgrade of forecasts this year (during the year) - now we are into September there are only 3 full months of the year left (2 full months before xmas people !). Note i would expect that new contract signings probably are unlikley to get an immediate quick hit to earnings most the of time.
So to me although pleasing - really the current trend in "net profit" is anything other than gaining momentum . last year £4.5 mill - this year £4.1 mill - next year - £4.6 mill. and thats not changed.
so i would say to me the company is simply in tickover mode - after the step change in profit levels delivered last year thats not all bad - but personally i tend to concentrate only on projected sales net profits and in that regard we have had very little meaning ful progress recently. Note i am happy holder here and i do get the impression that upgrades are perhaps more likely than downgrades - but in the absence of firm news from the company otherwise i think its very much year of "consolidation here" rather than meaningful improvement over what we expected 6 months ago.
Agree. Not much more meet on the bone!
Journeo (LON:JNEO) I agree Charlie, strong momentum in positive business flow and contract wins, I think they are averaging one RNS a month detailing these wins.
Singleton said the medium target was to double the business and they are very much on course to do that.
Journeo (LON:JNEO) Millaree has a fair point, but the reality of keeping in business (and critically meeting forecasts in the market) is firstly maintaining momentum in securing and growing existing contracts. The meaningful game changers of acquisitions and new contracts are likely far less frequent events. JNEO will use its growing cash pile, but to make a fully informed, de-risked, earnings enhancing, meaningful acquisition takes time. I feel confident that we shall see such an event in the coming months. Until then maintenance of momentum of the likes announced today will do me fine - and the frequency of contract announcements is strong.
BAE Systems (LON:BA.) are the primary beneficiary of a £10billion contract to supply warships to Norway.
UK secures £10bn deal to supply Norway with warships - BBC News
Might this bring new orders for Cohort (LON:CHRT), I hold, whose subsidiary, Chess, supplies its Sea Eagle systems?
I don't know about the implications for Cohort (LON:CHRT) .
Interestingly, I have read that many Norwegian politicians are complaining that the British battleships are inferior to those built by several other nations, but the decision was taken so that the UK and Norway can jointly patrol the northern European seas to search for Russian submarines.
Cohort MD on R4 this Am. You can listen on sounds app - around 6.20AM
Membership of JEF with command and control systems outside a disintegrating US-led NATO would have been a key issue. I wonder if this is a prelude to Canada joining JEF?
Yes Cohort (LON:CHRT) will benefit - piece on this morning's R4 Today
AI says:
Cohort (LON:CHRT) Cohort through its subsidiaries, supplies two key technologies to the Royal Navy’s Type 26 (City-class) frigates:
1. Ancilia Trainable Decoy Launcher System (via SEA):
-Description: Supplied by Cohort’s Systems Engineering and Assessment (SEA) subsidiary, the Ancilia is an advanced electronic warfare (EW) soft-kill countermeasure system. It replaces the legacy Sea Gnat fixed decoy system across the Royal Navy’s escort fleet, including the Type 26.
-Contract Details: Part of a £135 million UK Ministry of Defence contract awarded on March 26, 2024.
-Status: Being integrated into Type 26 frigates, starting with HMS Glasgow (commissioning late 2026, initial operating capability 2028).
2. Sea Eagle EO/IR Fire-Control System (via Chess Dynamics):
- Description: Supplied by Chess Dynamics, a wholly owned subsidiary of Cohort plc since its acquisition in December 2018,
- Contract Details: Awarded in 2022 to Chess Dynamics under Cohort, with installations planned during the fitting-out phase of HMS Glasgow (2025-2026). The system supports export programs, including Australia’s Hunter-class frigates.
- Status: Ongoing integration, with sea trials expected in 2027.
Interesting. I hold BAE Systems (LON:BA.) , and am wondering about buying Cohort (LON:CHRT) . However, I see that there were significant share sales from four different Cohort directors in July.
I've been thinking exactly the same. However, the price has come off a bit, perhaps to reflect the director selling activity so maybe a good time to start a position.
If I recall correctly those Directors sales were straight after an "Ahead of Expectations" announcement which surprised me too (I hold both BA and Cohort).
Cohort (LON:CHRT) It was a good time to take some profits. I hold and have topped up last week. The main seller still has 3%. If there is more selling then l may be concerned.
Yes it will. I also hold Cohort (LON:CHRT). Chort's Sea Eagle and Decoy system are direct beneficiaries.
Canada and Australia are also going with the new type 23 anti-submarine frigate, although the ships will be built in their domestic yards. The Norwegian and UK ships will be built in BAE's shipyards on the Clyde which is great news for Scotland. Maybe the SNP will reconsider releasing funds to train apprenticeships in welding, but I doubt it ... far too steeped in Queen Margaret Union student politics.
Goodwin (LON:GDWN) are heavily involved in providing components to the Type 26
https://www.goodwinsteelcastin...
Norway doesn’t have any foundry capable of producing these components …and Goodwin are currently embedded on all RN vessel programmes …and all the most significant US naval vessel procurement programs.
I hold rather a lot of the shares for this & many other reasons
Supreme (LON:SUP) adds 1001 Carpet cleaning to its arsenal. They don't make ads like this anymore....mores the pity 1001 carpet cleaner advert
the days when adverts were cheerful
1001 cleans a big, big carpet
For less than half a crown
One for the oldies amongst us. 1950s or was it 1960s ?
Supreme (LON:SUP) - Another smart acquisition. I can see them building this category to £10m/annum over the next 3 years with their platform. Its quite a niche area that P&G and Unilever keep out of. Just Reckitts as the big brand with Vanish I think.