LIVEDaily Stock Market Report (Wed 18th Nov 2026) - JET2, HAS

Good morning!
It felt very “2026” to see Jensen Huang asking, on X, to come back as the CEO of Nvidia:
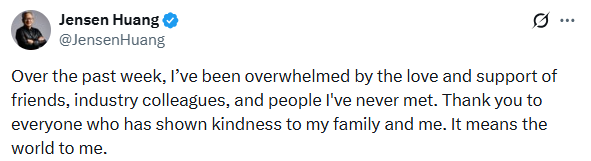
His post has received 44 million views and 1 million likes. Based on the “ratio” (comments vs. likes), and the tone of the replies, sentiment on X at least seems favourable to him.
However, the company's Chairman said yesterday that “The Nvidia board unanimously accepted his resignation and does not intend to reinstate Jensen as CEO”.
The company has raised its revenue growth forecast for next year, from 70% to 75%, and increased its ongoing buyback programme from $85 billion to $235 billion. And so the company’s incredible momentum continues, at least in the short-term.
Overnight market movements:
The FTSE is down 0.2% at 10,675
S&P 500 is up 0.3% at 7,360
Brent crude (January) is down 1.6% at $91.70/bbl
Gold is down 2% at $3,772/oz
Bitcoin is up 0.5% at $64,600
Roland Head joins me today.
The table is complete.
Companies Reporting
Name (Mkt Cap) | RNS | AI Summary* | Notes |
|---|---|---|---|
GSK (LON:GSK) (£75.6bn | SR72) | US approval for its ALK-positive lung cancer drug Nelkarmi came ahead of the FDA's 27 November 2026 target date. The accelerated approval covers previously treated patients. In the trial, 49% of those who had only alectinib responded, and 32% of those who had two or more prior ALK inhibitors and chemotherapy. Hepatotoxicity was the most common reason for stopping treatment. | ||
SSE (LON:SSE) (£32.3bn | SR60) | Adjusted earnings per share nearly doubled to 66.5p in the half-year, in line with expectations, as regulated network profits rose and a record £2.6bn was invested. Adjusted net debt and hybrid capital rose to £11.4bn. Management is “confident in delivering strong 2026/27 adjusted EPS of 168–193 pence”. | ||
Experian (LON:EXPN) (£24.8bn | SR60) | Organic revenue growth of 7% and 11% higher ongoing Benchmark EBIT led a strong first half, and a further US$500m buyback was announced. Full-year organic growth is now guided to 6–7%, reflecting higher interest rates on US mortgage volumes. Benchmark EPS rose 15% to USc97.5 and the interim dividend rose 9%. The company still expects Benchmark EBIT growth of around 10% and margin expansion of at least 50 basis points. | REVENUE WARNING | |
Severn Trent (LON:SVT) (£10.0bn | SR52) | Adjusted earnings per share jumped 17.6% in the first half as capital investment rose 36.9% to £1,053m. Basic EPS was flat at 76.0p, against 75.7p. The interim dividend rose 3.6% to 52.2p, and full-year investment guidance now sits at £2.3bn–£2.5bn, up from £2.2bn–£2.5bn. | ||
Smiths (LON:SMIN) (£7.2bn | SR69) | Full-year guidance is unchanged after a flat first quarter, with a Middle East drag on John Crane offset by Flex-Tek. Organic revenue was flat in the quarter to 31 October 2026, though the DRC acquisition lifted reported revenue 6.1%. It still expects about 4% organic growth, weighted to the second half, and a margin of about 21%. | ||
Melrose Industries (LON:MRO) (£6.0bn | SR21) | Melrose Industries - Trading update – guidance for full year unchanged | Full-year guidance is unchanged, and Garden Grove has approval to restart. Group revenue rose 4% in the four months to 31 October, in line with expectations. Engines grew 3% against a strong prior year, Airframes 5%. Guidance excludes Garden Grove, whose 2026 operating profit hit is put at £40–45m. | |
ConvaTec (LON:CTEC) (£4.7bn | SR50) | Revenue growth guidance is raised after growth picked up in the second half. Group organic growth excluding InnovaMatrix was 6.6% in the ten months to 31 Oct 2026. It now expects FY26 growth of 6.25–7.0%, up from 5.5–6.5%, with the operating margin target of at least 23% unchanged. | ||
Ithaca Energy (LON:ITH) (£4.2bn | SR70) | Record quarterly adjusted EBITDAX of $663m lifted the nine-month figure to $1.8bn, up from $1.5bn a year earlier. The dividend guidance for 2026 rises to $560–580m from $500–530m, and full-year production guidance narrows to 123–127 kboe/d. A $860m Canadian acquisition is expected to complete in H1 2027. | ||
Rotork (LON:ROR) (£4.0bn | SR73) | Orders held up in the four months to 31 October, with growth of a mid single-digit percentage on an organic constant currency basis. Oil & Gas was more subdued than expected because of Middle East disruption, but it still expects further progress in 2026. Net cash was £25.8m, and the ABB takeover should complete in the first half of 2027. | TAKEOVER | |
Jet2 (LON:JET2) (£2.7bn | SR96) | Record passengers and revenue in the first half, but operating profit fell 18% to £588.3m as the company cut prices to fill seats. Revenue rose 5% to £5.63bn. The interim dividend is held at 4.5p, and the board says it is “premature to provide guidance for full year profitability”. | AMBER/GREEN = (Roland) | |
Hill & Smith (LON:HILS) (£2.2bn | SR57) | Buys the business and assets of Southwest Galvanizing Inc. for $77 million. In the 12 months to 31 December 2025, Southwest reported revenue of $31 million with "good margins, albeit below those of the Group’s Galvanizing Services division." | ||
Genus (LON:GNS) (£1.5bn | SR39) | Full-year profit is still expected in line with market expectations, but a weaker Brazilian real and Mexican peso add a £3–4m currency hit. Trading in the first four months was solid, with profit weighted to the second half. Pig genetics was resilient, while the dairy business was challenging on low global dairy prices. Management expects a "material improvement" there in the second half. | ||
Hays (LON:HAS) (£868m | SR49) | Profit is set to come in well above forecasts. First-half pre-exceptional operating profit should be at least £35m, against consensus of £24.8m. It expects a stronger second half again. German net fees have improved and should return to modest like-for-like growth in the second quarter, while other divisions are stable. | AMBER ↑ (Roland) | |
Workspace (LON:WKP) (£652m | SR53) | Rents held steady, but a 6.6% fall in property values cut net asset value per share 11.9% to £6.05, and the board has deferred the interim dividend until the full-year results. The six-month loss before tax widened to £121.2m from £71.1m. Trading profit after interest fell 17% to £25.4m, which the company says is in line with expectations. Loan to value rose to 38% from 35%, and disposals are slower, with the £200m target due by March 2027. | ||
Enquest (LON:ENQ) (£520m | SR93) | Sells UK upstream business and associated infrastructure, through the sale of EnQuest Britain Limited, for up to $960m. US$840 million in upfront cash consideration, and up to US$120 million contingent consideration. Acquisitions in Malaysia remain on track to complete on 31 December 2026. | ||
Marshalls (LON:MSLH) (£436m | SR95) | Full-year profit is in line with expectations after resilient trading. Revenue was £544m in the ten months to 31 October, flat on a like-for-like basis, as roofing growth offset weaker housebuilding. Net debt fell £24m to £131m. That outlook assumes "no further deterioration in trading conditions". | ||
SThree (LON:STEM) (£353m | SR98) | SThree will unveil its new human-led AI operating system at Microsoft’s annual flagship Ignite conference in San Francisco later today. It is designed to operate as one connected intelligence across workflows, with AI agents coordinating and executing increasingly complex work from one stage to the next, while SThree’s people apply their expertise and judgement throughout. | GN note: this is a Reach announcement (a non-regulatory press release). | |
S&U (LON:SUS) (£234m | SR65) | Record lending is being funded by two new three-year securitisation facilities, while early arrears have risen temporarily. Capital receivables hit £646m, up 16%, and net borrowings were £319m. Advantage loan advances rose 20.0%. The company says it has provided for the arrears and expects them to normalise. Reflecting growth in profits depends on "a number of internal and external factors". | ||
Fonix (LON:FNX) (£186m | SR86) | Trading is in line with management expectations after a positive start to the financial year. The company says UK momentum is "strong" and its international and product expansion strategy "continues to progress". No figures were given. | ||
CLS Holdings (LON:CLI) (£173m | SR25) | Full-year earnings guidance is down after higher interest rates, adverse currency moves and delayed lease starts. It now expects 2026 EPRA earnings of 3.6–4.6p a share. Group vacancy rose to 15.4% from 14.5% at 30 June, mainly on the Spring Gardens departure, but leasing picked up and it remains on track for its £100m disposal target. | PROFIT WARNING | |
Peel Hunt (LON:PEEL) (£110m | SR79) | Revenue fell 15.1% to £63.2m in the six months to September, but costs fell too, and pre-tax profit slipped 23.5% to £8.8m. Adjusted pre-tax profit fell 36.4% to £11.9m. Trading in the second half is "more challenging" in Execution Services and Research & Distribution, though the board is "confident of delivering a full-year outturn in line with market expectations". | ||
MPAC (LON:MPAC) (£103m | SR62) | Full-year revenue and operating margin will both come in behind previous expectations, with delayed orders and US tariffs blamed. Revenue is only marginally ahead of last year on an underlying basis. Net debt was £47.8m on 13 November, up from £43.5m at the end of August, and the group says it is still operating within its banking covenants. | PROFIT WARNING | |
Speedy Hire (LON:SDY) (£62m | SR43) | Revenue rose 3.1% to £211.6m in the six months to 30 September, but higher interest costs left an adjusted pre-tax loss of £7.1m. Net debt rose to £166.1m, leaving leverage at 3.2 times, and free cash flow was negative £6.9m. The board expects "a second half weighting" and says FY2027 expectations "remain unchanged". | ||
ECO Animal Health (LON:EAH) (£55m | SR91) | Eco Animal Health Gp - New Aivlosin® marketing authorisations | Its antibiotic Aivlosin has new marketing authorisations in Paraguay and Honduras, plus import permits for Saudi Arabia and Oman. Commercial sales have already begun in Saudi Arabia and Oman, using existing infrastructure. | |
Victoria (LON:VCP) (£38m | SR48) | The refinancing has been put off. The board has deferred the Refinancing Transaction and is agreeing an amended timetable with Koch and the steering committee of 2028 Notes holders. "The Transaction Support Agreement, which obliges the parties thereto to support the implementation of the Refinancing Transaction, continues to remain in full force and effect until 31 December 2026." | GN Note: the lack of detail provided as to why the refinancing has been deferred strikes me as highly alarming. | |
Getbusy (LON:GETB) (£38m | SR27) | A new two-way link with Intuit's ProConnect and Lacerte tax software extends SmartVault's AI client-intake tool across the whole tax preparation process. | ||
SysGroup (LON:SYS) (£29m | SR57) | Adjusted EBITDA rose 4.8 times to £1.0m on revenue up 10.7% to £11.0m. Organic revenue grew 5.0%. Trading has started the second half “positively”, in line with market expectations. | ||
Vianet (LON:VNET) (£21m | SR87) | A US rollout for a major restaurant group is complete. Beverage Metrics is now live across about 100 Yard House restaurants, owned by Darden, and has performed in line with expectations through multiple period-ends. No contract value is disclosed, and there is no reference to any impact on market expectations. | ||
Potter & Moore (LON:PAM) (£15m | SR79) | Profit nearly halved in the first half as sales fell and raw material costs rose. Revenue dropped 6.7% to £25.6m, and pre-tax profit fell 47.7% to £0.8m. The board still expects full-year results "broadly in line with current market expectations", with sales weighted to the second half. | ||
LPA (LON:LPA) (£11m | SR81) | A second rail contract from the same global train builder takes the combined value to £2.7m. The new £1.3m award is for a complete LED interior lighting system, with deliveries running from the first half of FY27 to early 2028. It follows the July 2026 award for inter-car jumpers. No reference to any impact on expectations. |
*AI summaries are reviewed by the writing team.
Analyst notes
Today's results show a sharp reduction in pricing power and profit margins over the peak summer season. However, Jet2 appears to remain on track for a respectable full-year profit and continues to benefit from a strong balance sheet. I'm happy to maintain our broadly-positive view on this well-run business.
This recruiter's share price is up by nearly 40% this morning following a big upgrade to guidance, which I estimate could translate to a 44% increase in adjusted operating profit for the current year. I'm encouraged by progress, but with a FY27E P/E of >30 I think a measure of caution is still prudent, so I'm moving our view up to neutral today.

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

36 comments
Goodwin (LON:GDWN) Got a good write up in The Times today -
https://www.thetimes.com/business/companies-markets/article/should-you-buy-shares-in-goodwin-5tgqs395t
the 13p calculation is silly. More like £1.46 on the existing share count and taking the £110m valuation as the guide
Huang, with an ego so big it's embarassing. But he won't see it that way of course just like some other headline figures in the news of late.
Huang, with an ego so big it's embarassing. But he won't see it that way of course just like some other headline figures in the news of late.
He founded and built one of the greatest companies ever created. I think he has earned the right to a bit of ego.
Unassuming does it better!
Huang, with an ego so big it's embarassing
Gotta disagree, you need confidence and ego to persevere for this long.
He set Nvidia up in 1993 and battled on for many years until the AI revolution arrived and gave him the fame and recognition he has now.
Good Results from REIT British Land Public (LON:BLND) today. I can’t find them on Stockopedia, except for Reuters brief summary.
So here Is the initial part of their update today:-
“ STRONG FIRST HALF, UPGRADED FY27 EARNINGS GUIDANCE
Jo McNamara, Chief Executive, said:
“British Land delivered a strong first half, with 12% like-for-like net rental growth, investment activity and cost control driving a 5% increase in Underlying EPS. Reflecting this performance and our continued momentum as we enter the second half, we have upgraded our FY27 Underlying EPS guidance to 31.0p, representing growth of 7% year on year.
My first two months have reinforced my confidence in the quality of our assets, people and customer relationships. Our core markets represent 90% of our business and offer attractive opportunities, with strong occupational demand and constrained supply supporting further rental growth.
The ambition is simple: exceptionally talented and driven people, working in the right structure, empowered to execute a clear strategy at pace to deliver sustainable earnings growth, attractive returns and growing dividends for shareholders.”
FINANCIAL
• Underlying Profit £166m, up 7% (HY26: £155m)
• Underlying earnings per share (EPS) 16.1p, up 5% (HY26: 15.4p)
• Dividend per share 12.88p, up 5% (HY26: 12.32p)
• EPRA cost ratio 12.5% (HY26: 17.4%)
• Total property return +3.9% and total accounting return +3.4%
OPERATIONAL METRICS
• Portfolio occupancy 96.4%1: Campuses 95.2%1, Retail & London Urban Logistics 97.8%1
• Leased 1.4m sq ft, 7.9% ahead of previous passing rent and 10.4% ahead of ERV with 1.1m sq ft under offer, 11.6% ahead of ERV
• Campus leasing: 689k sq ft, 14.8% ahead of ERV. 396k sq ft under offer, 11.2% ahead of ERV, with a further 109k sq ft let or under offer in the six weeks post period end
• Retail & London Urban Logistics leasing: 739k sq ft, 7.3% ahead of ERV and 674k sq ft under offer, 12.1% ahead of ERV
• Retail park leasing 9.6% ahead of previous passing rent
• Like-for-like net rental growth +12%: Campuses +25%2, Retail & London Urban Logistics +2%
1Occupancy excludes developments completed in the previous 12 months
2 Excluding Storey. Including Storey, Campus like-for-like net rental growth is +26%
BALANCE SHEET
• EPRA Net Tangible Assets per share 599p, up 2%
• LTV 39.6% (FY26: 39.2%)
• Group Net Debt to EBITDA 7.0x (FY26: 7.7x)
• £2.9bn of financing activity, including a £775m syndicated RCF at an initial margin of 90bps, with 13 banks
• £2.0bn undrawn facilities and cash, with no requirement to refinance until 2030
• Fitch Senior Unsecured credit rating at ‘A’ with stable outlook (affirmed July 2026)
CAPITAL ACTIVITY
• £765m of capital activity, including £247m of assets disposed at a net initial yield of 4.7%, broadly in line with book value
• Exchanged or under offer on a further £328m of asset disposals, including deals agreed post period end
• Acquisition of Telford Bridge Retail Park for £30m at a topped-up NIY of 8.3%
• Acquisition of Life Science REIT completed on 20 April 2026
• Progressing 1.7m sq ft committed development pipeline on a de-risked, capital light basis
PORTFOLIO VALUATION
• Values up 1.5%: Campuses +1.6%, Retail & London Urban Logistics +1.2%
• ERV growth +3.0%: Campuses +3.9%, Retail & London Urban Logistics +2.0%, with retail parks +2.7%
• Net equivalent yield +3 bps to 6.1%: Campuses +6 bps to 5.7%, Retail & London Urban Logistics -1 bps to 6.6%
SUSTAINABILITY
• GRESB rating of 5* for both standing investments and developments
• 76% of the portfolio rated EPC A or B
OUTLOOK
• Upgraded FY27 Underlying EPS guidance to 31.0p, representing growth of 7% year on year
• Continue to expect 3-6% p.a. Underlying EPS growth over the medium term.”
Victoria (VCP)
Graham is right to be alarmed I believe. Long suspected this one was heading for some kind of crisis. No doubt debt interest rates are ramping up the pressures.
Will make an interesting case study when and/if the denouement I expect comes to fruition.
I hope people have got out well in time.
Cairn Homes (LON:CRN) Three NEDs, each buying 25,000 shares.
Seems unusual. Maybe it's an obligation for NEDs at CRN
MPAC (LON:MPAC)
zero surprises they have continued to struggle here - obviously with very chunky net debt of £40 mill plus - they are kinda forced to presenting an uber positive outlook on things - with that kinda of debt well saying you gonna gonna make profits that hardly service the debt isnt really an option - you gotta offer some hope teh future will be better.
random excuses order of the day again here - i did briefly hold shares here (sucker i am ) when they seemed to be a business moving forward before the wheels came off - perhaps us failures may have been partly beyond their control but the financials really did blow up in a bad way as they simply never hit the sales expectations they had after expanding (as every be wary when its about acquisitions)
If they had no debt they would perhaps be under less pressure here and could be given time - but at present with teh chunky debt 350p looked a toppy price before todays bad news and 300p looks a toppy price after the update. do i trust management to deliver promised numbers this year and next - nope and thats the problem here there aint alot of credibility here at present - if they have agood undelrying business they appear to be managing it badly or simply over promising (which might be needed to give them time ref banks)
obviously they will probably still expect better times next year than this - well they would wouldnt they.
Nothing to like here at present - i think there might be a semi decent business under the hood in some parts of the buisness so not saying they cant fidn tehir mojo - to me though with the dbet they have not sure why anyone would take the risk of updates like todays. I see it qualiffies for Altman Z-Score screen for shorting - taht kinda sums up where they are at present.
I avoided once the business went on an acquisition led spree in the USA. Despite all sorts of bullish noises this is yet another UK business trying to grow across the pond and failing to grasp the nettles. Reminds me of Oscar Wilde...........
Marshalls (LON:MSLH) . Market reaction to today's trading update feels a little harsh. Will you be covering the update Graham?
Marshalls (LON:MSLH)
dont know a alot about this company - they perhaps are in a similar boat to Eurocell (LON:ECEL) which i own.
You just have to look at the key lfl trading highlights compared to last year to see why people will just jog on ref this share - mostly in negative numbers compared to last year - albeit roofing is showing some growth last 4 months.
Note it doesnt look a bad business here - they are on track for decent profits compared to prior years and expect more next year - not sure where the more next year is coming from next year though as things stand (reduced finance costs and efficincies preumbaly ?) hopefully they are simply making the best of not brilliant conditions.
Nice drop in debt here - debt dropping quickly should in itself help move profits forward and or perhaps allow for bolt on acquisitions - seems very similar in profile to Eurocell (LON:ECEL) and Norcros (LON:NXR) which i own just eeking out enough to perhaps make a long term investment pay out ok. ref improving market conditions - i gave up hopes that there would be real uptick anytime soon quite a while back. As long as they deliver forecasts it kinda looks ok with debt coming down quickly.
I thought the results were really the best that could be expected when you see what has come out from the likes of Ibstock and BRCK etc. I think Marshalls (LON:MSLH) is a classic recovery stock and you look to buy ( tin Hat on) when the dawn is darkest so in my opinion wait for the next interest rate rise which my gut tells me could be the last one given tipping the economy into recession is a risk that needs to be given closer consideration. Some widening of the new Help to buy is pretty well inevitable in my view since the current tinkering around the edges is unlikely to provide the volume of housing starts that Rayner needs to justifiy her policies.
Trebles all round if my dusty crystal ball gets a result!
I was going to say that Marshalls (LON:MSLH) looks like a solid bet while we wait for a recovery in the housing market. Then I noticed that the Z score has been bad ever since the Marley roofing acquisition in 2022. Lots of goodwill and intangible assets on the balance sheet. I suppose a deterioration of trading at Marley could see some of those assets written down. Hopefully they can can significantly reduce the debt load before that happens
Thanks to rmillaree, Martin Verlaine and Retail Punter. Lots of food for thought - hold for possible housing recovery or sell before any further potential deterioration??
Marshalls (LON:MSLH)
Then I noticed that the Z score has been bad ever since the Marley roofing acquisition in 2022. Lots of goodwill and intangible assets on the balance sheet. I suppose a deterioration of trading at Marley could see some of those assets written down. Hopefully they can can significantly reduce the debt load before that happens
everyone takes their own viewpoint ref intangibles w/off - to me historical adjusts have no real relevance to the forward looking picture if they are intangible in nature and not cash related. Yes it can be confirmation that you might have overpaid - but by the time your w/off stuff well you have a handle on whats going anyway and you cant turn then clock back.
I wouldnt really count the intangibles as an asset in the first place normally if i am doing calcs unless perhaps isa clealry a sellable brand name (eg ferervtree) - and even then i would ignore for purposes ref solvency etc.
So i default to my old school calcs - if we had £155 mill of net debt and £38 mill of profits - and we are trending towards £121 mill 12 months later and perhaps down to £105 mill 24 months later - thast great debt reduction . The company is very quickly becoming more solvenct and less risky even if then altman scores may sugest otherwise - the debt coming down at a lick though and hopefully the net assets are increasing (perhaps not as same speed if dividend is being paid) should ignoring any goodwill adjust make ten aaltman score look much better.
I wont deny that £120 mill of debt is chunky - but if they can pay £25 mill off in average year whilst maintaining dividend - well that in my wheelhouse ref the "asset paying for itself" - you kinda want acquisitions to be fully paid for in 5 years so you can move onto the nexct one - taht tactic has worked well for Norcros (LON:NXR) and looks like it might work well for Marshalls (LON:MSLH) - note i think net debt here compared to profits is higher than eitehr Norcros or Eurocell - profits have been ramped up though anothe rlevel - so seems at face value that the acquistion itself may have been sound even if what might ideally be 5 year packback in 7 years.
Hopefully they can can significantly reduce the debt load before that happens
I doubt it matters much to be honest debt doesnt seem out of control - and with expected increase in profits next year they have something in the tank if they are to fall short - even at £30-35 mill profits they should be able to pay down debt quite quickly - at soem stage you might need to look at divi cover.
The proof of the pudding is the good clean cashflow coming through - compare that to companies like BRCK (LON:BRCK) and MPAC (LON:MPAC) - where they are struggling to stop debt spiralling upwards despite having had the benefit of the acquisitions - for any acquisition lead company you really want to follow the cashflow soon after acquisition - and it should be good with the extra profits you are normally bringing in. for example Norcos debt went up to £65 mill at 31/3/2026 with Fibo acquisition - in mid october it was already down to £55 mill and debt will be trending to nil within 5 years ish.
Ok with deferred payments sometimes it takes longer so brick may have some excuses that they needed to make those payments (and they have new acquisition) but night and day between the god uns and the bad uns here looks like Marshalls (LON:MSLH) are in the well run camp.
Marshalls (LON:MSLH)
I suspect all the companies you mention rm are all likely treading water these next couple of years (or more?) until the housing markets get properly moving again.
Pistol
Jet2 (LON:JET2)
Very Jekyll and Hyde update today - operationally speaking everything is a ok with regard to the grand plan -this is one of my larger holdings and perhaps one I am uber comfortable holding at present.
Thatch’s the good news done - ref the ye outlook they have only gone and and done a saga are blanked us ref ye expectations - that’s stupidly crazy - I don’t care how big the range of expectations is I just want something - pretty pathetic really. Ok let’s just say it’s in the range 150-300 mill - whilst that may be large range at least it’s a range - and that’s the point, they must have targets.
The 2 main issues are unhedged fuel prices and on sold tickets - I have full confidence the outcome will likely be acceptable but I don’t like the going awol bit that’s just of no use to me - or analysts - ok there may be a nod and a wink to brokers - but that’s bad crack - as they will likely be able to work out where are management expectations are teaming.
Anyway super annoying we are here too me it’s not a huge biggie if profits are well down due to elevated oil prices h2 - airlines will always have a few less good years - is there some over capacity and too much competition on price- jury is out. Overall they are well on track to have higher sales more efficient fleet and easily see out any trouble ahead
Jet2 (LON:JET2) not a fan of any Airline stocks so my view maybe a little coloured. I would have thought the cost of hedging fuel had increased markedly and at some stage you need to decide if this is viable. I am not terribly bullish on the outlook for oil prices so arguably the position makes some sense. I think aside from the fortress like balance sheet ( to me the major attraction ) it is the behaviour of the consumer over yet another very hot and dry summer that makes me wonder how tolerable temperatures are to the holiday maker as any slight reaction in load factors is a material consideration to the likes of Jet2. As I never take package holidays I think others may have a more joined up view on whether the PE owned Easy Jet provides more or less competition.
On the other hand AIM stocks transitioning to the Main Market recently have not had a great record so some weakness in the share price could be anticipated
Jet2 (LON:JET2)
not a fan of any Airline stocks so my view maybe a little coloured
yep sounds like its coloured from then getgo - with airlines you have to look a say a 4-5 year period to judge a company - there will be really good years wehn thye are in sweet spot - normal years and uber bad years. random stuff can hit profits at any time.
take a look at their numbers from 2023 onwards and you wont see any that doesnt make good reading. go back pre covid and it will be similar.
So whilst you may not be afan of airlines you have do admit they can genarate decent profits on average - can have very undemanding rating compared to many sectors - and Jet2 specifically have a casty iron strong balance sheet (to a certain extent that can be useful when shit hits the fan)
Ryanair has grown to $30 bill market cap company - so clearly if you do it right you can end up with a good end result.
The good news is its a pretty simple buisness model if you ignore the swings and roundabouts.
I would have thought the cost of hedging fuel had increased markedly and at some stage you need to decide if this is viable.
At the end of the day everyone is in the same boat here - its just tricky short term if you have sold a seat at price x - and your margins are low (as yopu make money on extras)
facts are for each passenger fuel is approx £30 per passenger
if fuel goes up 50% - thats an extra £15 on the price of a ticket max (ie its not temporary spike)
is anyone not going to go on holiday for the sake of £15 - not many
So whilst fuel prices may hurt bottom line short term - long term they are just an integral cost ten "entire industry" passes on
Have people stopped eating in greggs when meal deal went from £3.50 to £5.25 - nope.
So its all imho very viable an not a problem - more a problem is over capacity and big boys having price war - its in none of their interests though to be havinga price war - or running marginal routes than might make a loss.
Dont get me wrong after covid eevryone was uber cautious with capital and there is probably soem over expansion going on now - that just sorts itself out though - if it aint profitable route it will get shut down
I think aside from the fortress like balance sheet ( to me the major attraction ) it is the behaviour of the consumer over yet another very hot and dry summer that makes me wonder how tolerable temperatures are to the holiday maker as any slight reaction in load factors is a material consideration to the likes of Jet2.
have to totally disagree if you think the masses will stop going abroad - most people i know love their holidays - and the older seem to be more keen to travel than any generation ever.
Yes short term at present its tailwinds - but as per comments earlier up if you are making £250-300 mill in a bad year - well thats not too bad they have proved they can make £400 mill in a sweet spot year - trending to £500 mill with increased capacity they have.
ref competition it is what it is - i think they all would prefer to make margin - and they all know then implications of startinag proce war that doesnt suit them.
As Jet2 are expanding - there is scope for them to tone that back at some stage if they need to - no biggie imho
On the other hand AIM stocks transitioning to the Main Market recently have not had a great record so some weakness in the share price could be anticipated
short term price doesnt over worry me - i have bought added here in range 1100p up to 1400p over time - i probably wont sell below 2000p unless something fundamnetally goes wrong. if aim still has inheritance reliefs it kinda makes sense some may sell if it leaves aim - thats no biggei to me.
Basically if we accept they on average are returning 10% per year to shareholders or very close to that in poor year - and growing volume at the same time - imho thats a pretty simple business model - and they have pretty much been delivering that yoy ignoring covid - yes it was tailwinds teh last 2 years and headwinds now - but the market kinda understands that with airlines - profit warnings come along more than some more predictible companies - but also when they have a poor patch and set expectations lower generally the terend is back upwards yet.
Its no biggie to me if eps is 130p this year and 150p next year - i would be hoping that eps will be trending back up over 200p sometime in the next 36 months - that will depend on whether it like now or whether its like 1 to 2 years ago - the extra volume they are adding should be their friend all other things being equal.
RE:Jet2
Some fair points Martin about the sector - though I would say that I think that Jet2 is the one of the better travel operators.
One point which isn't mentioned is that the cash is inflated by customer deposits. In previous reports this has been mentioned but not today. This has to be taken into consideration.
I think that Jet2 is a decent company. If you look at the risk/ reward of the company however it looks to have a modest uplift at best.
This is another company which I struggle to see how the Stockrank (96) is justified. I suspect that the customer deposits inflating the cash position are not taken into consideration.
Jet2 (LON:JET2)
This is another company which I struggle to see how the Stockrank (96) is justified. I suspect that the customer deposits inflating the cash position are not taken into consideration.
have they not been making 10% plus compuound returns for shareholders each year on average oost covid (and probably pre) - not sure what qualities you think the company is lacking when it comes to juding them by - in the 4 year period 2025 2028 looks like they will genrate half their market cap in bottom line profits for shareholders !!! whats not to love about that kind of real profit generatation ? yes profits are trending down at present thats just the sector they are in - in peak years they arent given 15 * trading multiple as there will be a spanner in the works here and there.
is 10% pa compounded return not enough ? its more than enough for me.
Excellent Results from FTSE100 oil share Ithaca Energy (LON:ITH) today, and a further dividend increase ahead. The yield is already over 10%. Ithaca Energy (LON:ITH) fell to astonishing £1 in late 2024 and luckily I averaged down a then 30% loss at that price. Good chance of a combination of very high yield and capital growth on top after recent “transformational“ acquisition.Full details on that in the commentary.
SysGroup (LON:SYS)
Strong operating leverage delivered in today’s HY results and seems that Heejae Chae is building something similar to what he did with Scapa Group plc (from 17p to 215p before acquired).
Early days here.
I hold at much lower prices.
All the best
@SysGroup (LON:SYS)
cheers yiannos - had a quick look through the h1 figures and everything seems to be trending nicely - cash conversion running ahewad of profits is always a bonus.
As you say its very much early days - at the profit and loss bottom line level despite the really good improvements in lfl numbers - there isnt a huge amount flowing through to teh bottom line h1- looks like most of the trade is managed it services so that bit of the business is unlikley to deliver great operational gearing - presumably they need to find sweet spot ref added value stuff - or simplyu get uber efficient at deliver reasonable margins - if they could trend to 10% to the bottom line that would be a game changer.
I get the attraction here with a sector that should be bouyant cashflow being decent compared to profits and things trending nicely ref putting the prior years of losses firmly in the background - as you say early days it is but trending nicely.
Another trading update, another profit warning slipped out through the broker over at Jet2 (LON:JET2). FY28 EPS cut by 8% 'reflecting new FY28E fuel cost inflation projections'.
Looks like prices are under pressure too. Good for customers. Not so good for profits.
Jet2 (LON:JET2) are best in class IMO.
Yeah - if today's counts, that's the third this year, by my count. It doesn't really seem like the market's cared through each of these warnings. Which certainly suggests most of it's in the price.
No SSE?
SSE is in the table! With the new format, it might go up missing some entries on the initial sweep, but I'll then add various entries until it's complete.
Thanks Graham!
Just me of does SSE have a nice long term bowl forming?
Enquest selling its North Sea assets! https://www.investegate.co.uk/announcement/rns/enquest--enq/sale-of-enquest-s-uk-north-sea-business/9880546
That's in the table now, too!
Quite some decision, overall Positive.
The real kickers are the complete removal of NS decomm liabs and the hefty reduction in debt.