Jet2 H1 results: Share price dips on 18% profit drop – why we remain positive

Analyst’s view:
Today's results show a sharp reduction in pricing power and profit margins over the peak summer season. However, Jet2 appears to remain on track for a respectable full-year profit and continues to benefit from a strong balance sheet. I'm happy to maintain our broadly-positive view on this well-run business.
Down 4% to 1,424p (£2.54bn) - Half Year Financial Report
High fuel prices and consumer cost-of-living pressures are always going to be a difficult combination for Jet2. So today's half-year results - following the peak summer season - are a key milestone.
Although the company says it's too soon to issue full-year guidance, I think today's numbers provide some clues about the direction of travel and the possible outlook relative to last year. Let's take a look.
Half-year summary: record passenger numbers
Jet2 says it saw record passenger numbers of 15.4m (+9%) during the six months to 30 September. However, while passengers are still keen to fly, it seems they don't want to overpay. These financial results make it clear that both pricing power and profit margins came under pressure in H1:
Revenue up 5% to £5,632.6m (vs 9% increase in passengers)
Operating profit down 18% to £588.3m
H1 operating margin: 10% (H1 26: 13%)
Pre-tax profit down 19% to £652.2m
Earnings per share down 11% to 266.1p
Interim dividend held at 4.5p, with £250m buyback ongoing
We've often commented on Jet2's strong balance sheet and operational excellence. Further evidence of both is provided today:
Net cash up 5% to £2,183.8m
Load factor up by 1.5% to 89.7% (a measure of how full each flight is)
First season at London Gatwick delivered average load factor of >90% from June - Sept
Nine new A321neo aircraft added, now expects to operate 142 aircraft in Summer 2027
Flight-only customers +20%, Package Holding customers +4%
Regardless of Jet2's qualities as an operator, travellers won't pay more than they have to. With competitors including Ryanair competing for the firm's customers, flight prices fell sharply in H1:
Flight-only ticket yield per passenger (exc. taxes) down 14% to £104.82
Average package holiday price up 1% to £945
Non-ticket revenue per passenger sector up 1% to £26.23
Advance sales made at 30 September down 2% to £2,459.6m
A 1% increase in package holiday prices and non-ticket revenue seems unlikely to cover the impact of inflation and advanced sales are also lower, highlighting the trend towards later bookings.
Outlook
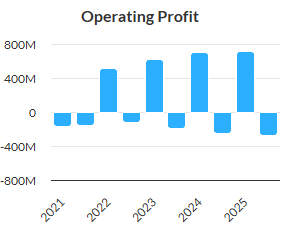
More than most, leisure travel and short-haul flying are highly seasonal businesses. Businesses such as Jet2 routinely generate an operating loss for the winter period that's offset by bumper profits during the summer season:
Where does today's commentary leave us in terms of the full-year outlook?
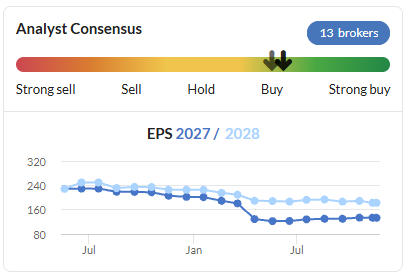
Consensus estimates have drifted lower this year:
... but today's management commentary is vague:
While it remains premature to provide guidance for full year profitability given the proportion of the Winter season still to book and continued volatility in jet fuel prices for our remaining unhedged requirement, we will continue to take responsible action on seat capacity and operating costs in response to the external environment.
I don't have access to any updated broker forecasts this morning, but I do have forecasts published by Canaccord Genuity in September. Using these and the company's results, I can draw some tentative conclusions about the outlook:
FY26 | FY27 | |
|---|---|---|
H1 op profit | £715.2m | £588.3m |
H2 op profit | -£275.6m | -£328m (implied) |
Full year op profit | £439.6m | £260.3m (CG forecast) |
Today's results show H1 EBIT falling by 18%
The implied FY27 H2 EBIT loss I've calculated above is 18% greater than the H2 loss generated last year.
So my guess would be that if conditions remain broadly as they are at present (or as Jet2 expects them to be), then today's results are probably broadly in line or perhaps slightly below existing expectations.
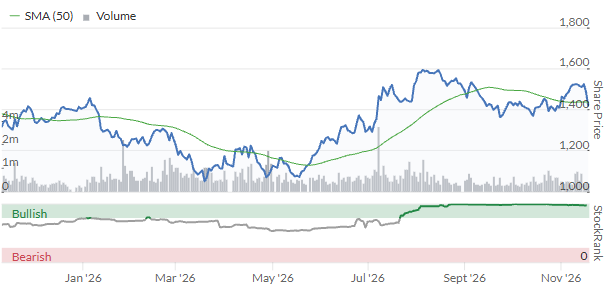
I think this view is justified by this morning's share price action - the shares are down by just 4% at the time of writing, suggesting the market doesn't expect a big cut to forecasts:
Roland's view
When Ed looked at Jet2 in September he noted that "demand appears to be robust", with fuel hedging and FX well managed.
Those conclusions still seem to be true today, with 50% of jet fuel requirements hedged for next summer at prices 41% below current spot prices.
Jet2's valuation continues to look relatively undemanding to me and the group's strong balance sheet provides extra resilience. Although today's update might lead to a slight downgrade to forecasts, I think a broadly-positive view remains fair for Jet2, which remains a profitable and growing business.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Jet2 (9)
Comments here are also visible in the Daily Stock Market Report
Jet2 (LON:JET2)
Very Jekyll and Hyde update today - operationally speaking everything is a ok with regard to the grand plan -this is one of my larger holdings and perhaps one I am uber comfortable holding at present.
Thatch’s the good news done - ref the ye outlook they have only gone and and done a saga are blanked us ref ye expectations - that’s stupidly crazy - I don’t care how big the range of expectations is I just want something - pretty pathetic really. Ok let’s just say it’s in the range 150-300 mill - whilst that may be large range at least it’s a range - and that’s the point, they must have targets.
The 2 main issues are unhedged fuel prices and on sold tickets - I have full confidence the outcome will likely be acceptable but I don’t like the going awol bit that’s just of no use to me - or analysts - ok there may be a nod and a wink to brokers - but that’s bad crack - as they will likely be able to work out where are management expectations are teaming.
Anyway super annoying we are here too me it’s not a huge biggie if profits are well down due to elevated oil prices h2 - airlines will always have a few less good years - is there some over capacity and too much competition on price- jury is out. Overall they are well on track to have higher sales more efficient fleet and easily see out any trouble ahead
Jet2 (LON:JET2) not a fan of any Airline stocks so my view maybe a little coloured. I would have thought the cost of hedging fuel had increased markedly and at some stage you need to decide if this is viable. I am not terribly bullish on the outlook for oil prices so arguably the position makes some sense. I think aside from the fortress like balance sheet ( to me the major attraction ) it is the behaviour of the consumer over yet another very hot and dry summer that makes me wonder how tolerable temperatures are to the holiday maker as any slight reaction in load factors is a material consideration to the likes of Jet2. As I never take package holidays I think others may have a more joined up view on whether the PE owned Easy Jet provides more or less competition.
On the other hand AIM stocks transitioning to the Main Market recently have not had a great record so some weakness in the share price could be anticipated
Jet2 (LON:JET2)
not a fan of any Airline stocks so my view maybe a little coloured
yep sounds like its coloured from then getgo - with airlines you have to look a say a 4-5 year period to judge a company - there will be really good years wehn thye are in sweet spot - normal years and uber bad years. random stuff can hit profits at any time.
take a look at their numbers from 2023 onwards and you wont see any that doesnt make good reading. go back pre covid and it will be similar.
So whilst you may not be afan of airlines you have do admit they can genarate decent profits on average - can have very undemanding rating compared to many sectors - and Jet2 specifically have a casty iron strong balance sheet (to a certain extent that can be useful when shit hits the fan)
Ryanair has grown to $30 bill market cap company - so clearly if you do it right you can end up with a good end result.
The good news is its a pretty simple buisness model if you ignore the swings and roundabouts.
I would have thought the cost of hedging fuel had increased markedly and at some stage you need to decide if this is viable.
At the end of the day everyone is in the same boat here - its just tricky short term if you have sold a seat at price x - and your margins are low (as yopu make money on extras)
facts are for each passenger fuel is approx £30 per passenger
if fuel goes up 50% - thats an extra £15 on the price of a ticket max (ie its not temporary spike)
is anyone not going to go on holiday for the sake of £15 - not many
So whilst fuel prices may hurt bottom line short term - long term they are just an integral cost ten "entire industry" passes on
Have people stopped eating in greggs when meal deal went from £3.50 to £5.25 - nope.
So its all imho very viable an not a problem - more a problem is over capacity and big boys having price war - its in none of their interests though to be havinga price war - or running marginal routes than might make a loss.
Dont get me wrong after covid eevryone was uber cautious with capital and there is probably soem over expansion going on now - that just sorts itself out though - if it aint profitable route it will get shut down
I think aside from the fortress like balance sheet ( to me the major attraction ) it is the behaviour of the consumer over yet another very hot and dry summer that makes me wonder how tolerable temperatures are to the holiday maker as any slight reaction in load factors is a material consideration to the likes of Jet2.
have to totally disagree if you think the masses will stop going abroad - most people i know love their holidays - and the older seem to be more keen to travel than any generation ever.
Yes short term at present its tailwinds - but as per comments earlier up if you are making £250-300 mill in a bad year - well thats not too bad they have proved they can make £400 mill in a sweet spot year - trending to £500 mill with increased capacity they have.
ref competition it is what it is - i think they all would prefer to make margin - and they all know then implications of startinag proce war that doesnt suit them.
As Jet2 are expanding - there is scope for them to tone that back at some stage if they need to - no biggie imho
On the other hand AIM stocks transitioning to the Main Market recently have not had a great record so some weakness in the share price could be anticipated
short term price doesnt over worry me - i have bought added here in range 1100p up to 1400p over time - i probably wont sell below 2000p unless something fundamnetally goes wrong. if aim still has inheritance reliefs it kinda makes sense some may sell if it leaves aim - thats no biggei to me.
Basically if we accept they on average are returning 10% per year to shareholders or very close to that in poor year - and growing volume at the same time - imho thats a pretty simple business model - and they have pretty much been delivering that yoy ignoring covid - yes it was tailwinds teh last 2 years and headwinds now - but the market kinda understands that with airlines - profit warnings come along more than some more predictible companies - but also when they have a poor patch and set expectations lower generally the terend is back upwards yet.
Its no biggie to me if eps is 130p this year and 150p next year - i would be hoping that eps will be trending back up over 200p sometime in the next 36 months - that will depend on whether it like now or whether its like 1 to 2 years ago - the extra volume they are adding should be their friend all other things being equal.
RE:Jet2
Some fair points Martin about the sector - though I would say that I think that Jet2 is the one of the better travel operators.
One point which isn't mentioned is that the cash is inflated by customer deposits. In previous reports this has been mentioned but not today. This has to be taken into consideration.
I think that Jet2 is a decent company. If you look at the risk/ reward of the company however it looks to have a modest uplift at best.
This is another company which I struggle to see how the Stockrank (96) is justified. I suspect that the customer deposits inflating the cash position are not taken into consideration.
Jet2 (LON:JET2)
This is another company which I struggle to see how the Stockrank (96) is justified. I suspect that the customer deposits inflating the cash position are not taken into consideration.
have they not been making 10% plus compuound returns for shareholders each year on average oost covid (and probably pre) - not sure what qualities you think the company is lacking when it comes to juding them by - in the 4 year period 2025 2028 looks like they will genrate half their market cap in bottom line profits for shareholders !!! whats not to love about that kind of real profit generatation ? yes profits are trending down at present thats just the sector they are in - in peak years they arent given 15 * trading multiple as there will be a spanner in the works here and there.
is 10% pa compounded return not enough ? its more than enough for me.
" yes profits are trending down at present that's just the sector they are in"
This is my point.
On a forward looking basis the uplift(if any) looks modest.
Another trading update, another profit warning slipped out through the broker over at Jet2 (LON:JET2). FY28 EPS cut by 8% 'reflecting new FY28E fuel cost inflation projections'.
Looks like prices are under pressure too. Good for customers. Not so good for profits.
Jet2 (LON:JET2) are best in class IMO.
Yeah - if today's counts, that's the third this year, by my count. It doesn't really seem like the market's cared through each of these warnings. Which certainly suggests most of it's in the price.