Daily Stock Market Report (Wed 23rd Sep 2026) - W7L, JD., ASY, ING

Good morning! No major overnight news to report, just a couple of headlines that continue familiar themes we’ve been covering:
Iran: after threatening to “annihilate” Iran if they don’t make a deal with him, President Trump says there have been “very good” talks in New York between US and Iranian envoys, through a Qatari mediator. Iran has reportedly made a proposal that sets out their conditions for ending the conflict. According to CNBC, “a senior Iranian official said Tehran could reopen the strait within a week if the U.S. eases military pressure and lifts its blockade of Iranian ports”.
Rising interest rates: the ECB recently made its second interest rate hike and is expected to continue raising rates. Bloomberg quotes the president of Bundesbank saying yesterday: “I cannot exclude if we are being confronted for a longer time with high energy prices like this that we have to go into the mild restrictive territory of monetary policy”. Another rate hike is anticipated before the end of the year.
Let’s move on to the company announcements…
Overnight market movements:
The FTSE is up 0.4% at 10,760
S&P 500 is unchanged at 7,770
Brent crude (November) is down 0.9% at $98.50/bbl
Gold is down 0.5% at $4,335/oz
Bitcoin is up 0.3% at $86,500
The Agenda is under construction. Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
AstraZeneca (LON:AZN) (£197bn | SR56) | Trixeo has been approved in the EU for the maintenance treatment of asthma. It’s the only triple-combination therapy approved in the EU for patients 12 years and older, independent of exacerbation history. | ||
Diageo (LON:DGE) (£36bn | SR69) | CFO Nik Jhangiani will stand down in 2027. He will be replaced by Joanne Wilson, currently CFO of WPP and previously at companies including Britvic, dunnhumby and Tesco. | ||
Airtel Africa (LON:AAF) (£11.3bn | SR90) | The IPO would be a secondary offering of shares sold by existing Airtel Money shareholders, with no new capital raised. Airtel Africa currently owns 77.85% of Airtel Money and expects to remain a long-term strategic shareholder following the IPO. | ||
WPP (LON:WPP) (£4.2bn | SR88) | CFO Joanne Wilson will be stepping down to take up the CFO role at Diageo. | ||
Renishaw (LON:RSW) (£4.0bn | SR71) | Revenue +14% to £816m with pre-tax profit +27% to £150m. Adj EPS +30% to 179.5p. Outlook: FY27 has “started strongly as we continue to benefit from the current upturn in demand for semiconductor manufacturing equipment”. Expects further “strong progress” on revenue and profit. | ||
JD Sports Fashion (LON:JD.). (£3.7bn | SR93) | Sales-0.7% to £5,899m with adj pre-tax profit -19.7% to £282m. Adj EPS -13.7% to 3.97p. FY27 outlook: guidance unchanged from Q2 statement; expects adj pre-tax profit of £700 to £800m. | AMBER = (Roland) Today’s half-year results don’t add much to what we learned from August’s Q2 trading statement, which also included a profit warning. Guidance is in line today, as I’d expect, and the high StockRank reflects the potential value that’s on offer here if JD can deliver on forecasts. My concern is that the company needs to deliver 63% of EPS in H2 to meet forecasts, while remaining heavily dependent on a turnaround at its largest supplier Nike, which generates c.40% of group sales. It’s this combination of circumstances that has prompted me to remain neutral today, despite JD’s Super Stock styling. | |
Big Yellow (LON:BYG) (£1.63bn | SR52) | Contracted to sell Bracknell industrial estate for £6.3m. | ||
Cordiant Digital Infrastructure (LON:CORD) (£969m | SR86) | Portfolio revenue +20.2% to £106.6m with EBITDA +2.0% to £43.6m. Consolidated gearing of 39.8% with net leverage of 4.54x. Dividend target of 4.45p unchanged and covered 1.6x by adjusted funds from operations after scheduled debt repayments. | ||
Ceres Power Holdings (LON:CWR) (£924m | SR13) | Revenue +8% to £22.8m, in line with expectations. Gross profit -3% to £16.1m with operating loss reduced to £13.7m (H1 25: £17.2m). Net cash of £172m. | ||
Tungsten West (LON:TUN) (£716m | SR36) | Has entered into a binding eight-year supply and offtake agreement with US firm Elmet Technologies for 1,000 tonnes per annum of contained WO₃ from Hemerdon. Agreement has over £1.4bn of indicative nominal value and current market prices and FX rates. | ||
Pantheon Infrastructure (LON:PINT) (£546m | SR66) | H1 NAV per share down 5% to 123.9p with NAV total return of -3.3%. H1 dividends of 2.25p with 10.3% total shareholder return. Outlook: macro backdrop remains turbulent but structural drivers behind the portfolio remain in place. | ||
Boku (LON:BOKU) (£351m | SR33) | Revenue +5% to £66.5m with operating profit -59% to £4.8m. Total payment volume +16% to $8.6bn with blended take rate -8% to 77bps. Outlook: H2 trading to date has been in line with expectations. FY26 expectations unchanged from July update (revenue $135-142m and adj EBITDA of $38-42m). | ||
Petrotal (LON:PTAL) (£270m | SR91) | Development drilling resumes with spudding of well 25H, paving the way for expected material production growth. Total group production averaging 12,286 bopd in September, +600 bopd month-on-month. | ||
Judges Scientific (LON:JDG) (£252m | SR48) | “Challenging markets weighted on H1 performance”. Revenue -21% to £55.7m with adj pre-tax profit -75% to £3.2m. Adj EPS -72% to 39.0p. Interim dividend +10% to 36.0p. Outlook: H2 order intake improved, full-year expectations maintained. CFO is stepping down in September 2027. | ||
Andrews Sykes (LON:ASY) (£226m | SR60) | Strong demand for cooling products. Revenue +7.7% to £40.9m with operating profit +2.7% to £10.3m. EPS -1% to 17.6p, interim dividend held at 11.9p. Net cash of £14.5m. Outlook: continuing high demand for cooling products in the UK and Europe. Full year performance is expected to be materially ahead of 2025. | AMBER = (Graham)
If this had a “value” earnings multiple - let’s say single digits - then I’d happily upgrade our stance on it. But the trailing P/E is about 14x, and the ValueRank is very average. I’m used to seeing stocks in this sector trade cheaply, but Andrew Sykes does not. Therefore, while this might be the best little equipment hire company that’s listed on the market, I just don’t see why it should be rated much more highly than it already is! | |
BTG Consulting (LON:BTG) (£184m | SR75) | Acquired property and asset management business Hornbeam CPAM Limited for £4.0m. Hornbeam’s FY26 pre-tax profit was £0.6m, with net assets of £1.3m. | ||
Warpaint London (LON:W7L) (£178m | SR86) | Revenue -17.8% to £40.5m with pre-tax profit -33.2% to £4.9m. Adj EPS -46.6% to 4.5p with net cash +21.5% to £20.7m. 2026 Outlook: expect revenue towards the lower end of current market expectations, with adj EBITDA within the current range of analyst forecasts. Shore Capital updated forecasts: - FY26E adj EPS: 18.3p (prev. 20.0p) - FY27E adj EPS: 18.5p (prev. 21.1p) | PROFIT WARNING (AMBER =) (Roland) Warpaint’s broker Shore Capital has trimmed its forecasts for 2026 and 2027, confirming my 7am suspicion that this could be a profit warning. Weak H1 trading appears to be due to a mix of soft consumer demand and some adverse timing effects. A stronger performance is promised for H2 and there are some specific reasons why the Q4 festive period should be stronger. Even so, with 75% of revised earnings now needing to be generated in H2, I think there’s still scope for further disappointment. I’m staying neutral today as I think the valuation and net cash position provide some downside protection and suggest that patience could still pay off here. | |
Savannah Resources (LON:SAV) (£150m | SR n/a) | Raised $36m before expenses at 5.5p per share (c.490m new shares). | Shares currently suspended. | |
Pharos Energy (LON:PHAR) (£125m | SR86) | Working interest production flat at 5,650 boepd, in line with guidance. Cash generated from operations +59% to $50.6m. Outlook: 2026 production guidance range narrowed to 5,300 - 5,900 boepd (prev. 5,200-6,400 boepd), reflecting lower than expected production in Egypt. | TAKEOVER | |
Aurrigo International (LON:AURR) (£109m | SR24) | H1 revenue +19% to £4.2m, with adj EBITDA loss of £3.1m (H1 25: £1.6m) and pre-tax loss of £3.8m. Automotive revenue +53%, first defence contract secured. | ||
Foxtons (LON:FOXT) (£108m | SR50) | Acquired agents in Birmingham and Watford, plus a lettings portfolio in Reading. Total consideration of £6.0m, including £1.2m of defcon. Total revenue of £3.2m reported across the four acquisitions in their most recent financial years. Expect to be earnings accretive from FY27. | ||
SDI (LON:SDI) (£98m | SR79) | SDI reaffirms that it expects to deliver full year results in line with market expectations. | ||
Aminex (LON:AEX) (£87m | SR9) | Subsidiary Ndovu met with ARA Petroleum Tanzania to consider work programme and budget for 2026/2027. The joint venture approved both work programmes and budgets, with gross expenditure of up to US$75m projected across the remainder of 2026 and 2027. | ||
Chapel Down (LON:CDGP) (£79m | SR25) | FY26 Adjusted EBITDA to be materially ahead of market expectations. Net debt is also expected to be lower than market expectations. H1 net sales revenue +19%. Adjusted EBITDA +27% (£1.3m). Loss before £551k. | ||
Orosur Mining (LON:OMI) (£77m | SR13) | Gross proceeds up to C$14m. 43.75 million “units” sold at c. 17p each (last night’s close: 18p). Each unit consists of a share plus half of a warrant. | ||
Kooth (LON:KOO) (£64m | SR65) | H1 revenue £30.8m (H1 2025: £32.1m) including £0.7m negative FX movement. ARR increased £1.2m to £62.9m. Profit after tax £2m (H1 2025: £1.3m loss). Net cash £23.1m. “The Group expects to deliver underlying results broadly in line with expectations for the year before the potential impact of foreign exchange movements.” | ||
Zephyr Energy (LON:ZPHR) (£63m | SR23) | Q2 production averaged 914 barrels of oil equivalent per day, net to Zephyr. Q2 production totals exceeded management’s forecast. Strong cash flow in Q2 due to greater-than-expected production levels and higher than anticipated commodity prices. Borrowings from senior lender c. $19.9m, vs. $22.1m in November 2025. | ||
Ondine Biomedical (LON:OBI) (£60m | SR9) | Five hospitals in Southern Ontario are using Steriwave® nasal photodisinfection to support infection prevention for patients undergoing major orthopaedic and spine surgery. | ||
R E A Holdings (LON:RE.). (£55m | SR91) | Revenue $88.6m (H1 2025: $92.4m), reflecting delays by customers in taking deliveries of CPO over the period which are now being caught up. PBT $25.9m. “Encouraging outlook for palm product prices, supported by strong demand for vegetable oils, the continued expansion of Indonesian biodiesel programmes and constraints on growth in global oil palm hectarage.” | ||
Gelion (LON:GELN) (£33m | SR5) | Six patents granted to protect innovations in thermal management, cathode-electrolyte design and anode protection relating to Lithium-Sulfur technology. | ||
Kavango Resources (LON:KAV) (£32m | SR4) | Revenue $2m, operating loss $1.8m. Preliminary Mineral Resource Estimate totalling 33,900 ounces of gold at 2.68 grammes per tonne declared at Bill's Luck Gold Mine. Going concern note: “...the Group will require additional funding during the forecast period in order to meet its planned expenditure and to continue to develop its projects.” | ||
Portmeirion (LON:PMP) (£26m | SR50) | Interim Results & Update on Proposed Name Change to Spode Group plc | The name change “reflects the global reach, heritage and resonance of the Spode brand in our markets, intellectual property considerations and increasing simplicity in a digital world.” H1 revenues down 2%. Headline loss before tax £4.5m (H1 last year: £2.8m loss). Net debt £6.2m. “We have made a solid start to the second half of 2026, trading in line with expectations… We remain mindful of the uncertain macroeconomic environment and the Group’s significant Q4 trading weighting.” | |
KRM22 (LON:KRM) (£20m | SR13) | Contract value £0.9m split equally over three years is with “a major software vendor in the capital markets industry.” | ||
Ampeak Energy (LON:AMP) (£17m | SR10) | H1 revenue £2.2m (H1 2025: £3.5m). Pre-tax loss £4.7m (H1 2025: loss of £4.6m). “The development of battery energy storage projects remains the cornerstone of the Company's growth strategy… Ampeak enters the second half of 2026 with significant momentum.” | ||
Zinc Media (LON:ZIN) (£17m | SR33) | Revenue £13.2m (H1 2025: £22.9m). Adjusted EBITDA loss £0.9m (H1 2025: profit £0.9m). £8m of revenue that was anticipated in H1 moved into H2. “Due predominantly to the delay of a significant multi-million contract in the Middle East, which is now expected to be produced in FY27, the Group now expects to deliver £38m of revenue and £1.4m of EBITDA.” | PROFIT WARNING (FY26 revenue forecast on the StockReport is £44.9m vs. guidance of £38m given today.) | |
Ingenta (LON:ING) (£12m | SR79) | Revenue £5.1m (H1 2025: £5.2m). PBT £0.7m (H1 2025: £1.2m). “While reported revenues were modestly lower, this was driven largely by currency movements and the wind-down of legacy work, rather than any weakening in our core proposition… we remain confident in the Group’s long-term growth trajectory.” | AMBER = (Roland) These results highlight £2m of recent contract wins which may support future earnings. But the company admits that efforts to expand its sales team are running behind schedule and the impression I get is that Ingenta is struggling to expand beyond its existing core business. This isn’t without attractions – profitability is strong, as is the balance sheet. However, the lack of both earnings visibility and momentum mean I’m staying neutral today, despite the potential value on offer. |
Graham's Section
Andrews Sykes (LON:ASY)
Up 5% at 569p (£238m) - Half-year Report - Graham - AMBER =
We haven’t looked at this equipment hire company in a while. A year ago, Mark was neutral. Let’s get up to speed.
We do have year-on-year progress:
Revenue +8% to £40.9m
Continuing EBITDA +9% to £14.8m
Operating profit +3% to £10.3m
EBITDA is probably useful as one of the metrics for management to look at, but I definitely wouldn’t want to look past depreciation at an equipment hire company.
Net funds have increased to £14.5m (Dec 2025: £13.2m, June 2025: £6.9m), and this is after deducting £13m of leases. The cash balance is over £27m.
UK revenue was up 11.4%, driven by the hot weather: “With the UK experiencing record breaking temperatures in May and June, there was significantly increased demand for comfort cooling equipment which increased air conditioning revenues by almost 40% compared with the same period in 2025.”
Europe revenues were up 14%, but the UAE business had “an extremely challenging period due to the well-publicised geopolitical events occurring in the region”. UAE external revenues fell 28.8% and they also suffered a £1m bad debt.
Interim dividend is unchanged at 11.9p, accounting for the majority of the company’s H1 earnings per share (17.6p).
Outlook: more of the same, thanks to the heatwaves:
Trading in the second half of the year to date has been positively impacted by the continuing high demand for the Group's comfort cooling products seen in the UK and Europe at the end of the first half of the year… As the summer season ends, the Board anticipates the Group's UK and European trading performance will trend towards more normal levels.
The Middle East business remains “subdued”, but Andrew Sykes expect this will be more than offset by the strength in the UK and Europe.
Balance sheet: net assets are £55m and this is fully tangible.
Graham’s view
If this had a “value” earnings multiple - let’s say single digits - then I’d happily upgrade our stance on it.
This is a family-owned business with a really strong track record of profitability over many years.
Successful management is demonstrated by excellent quality metrics:
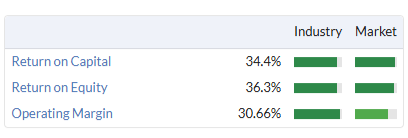
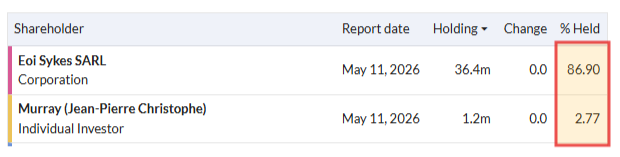
Although some may be put off by the extent of family ownership. The free float is actually tiny (Eoi Sykes is ownership vehicle used by the Sykes family, and JJ Murray is the Chairman):
However, the main reason I’m not upgrading our stance is simply the sector it’s in: equipment hire, where I believe there tends to be a ceiling on the economic returns that are possible, and where I suspect that Andrew Sykes is close to this ceiling.
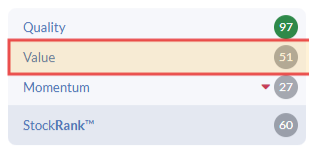
And I’m used to seeing stocks in this sector trade cheaply, but Andrew Sykes does not. The trailing P/E is about 14x, and the ValueRank is very average (see below). Compare against the earnings multiples at the likes of Speedy Hire (LON:SDY) and VP (LON:VP.)
Interestingly, there are no broker forecasts. That can sometimes be the case for family-run businesses that don’t need to raise capital and aren’t too concerned about their share price.
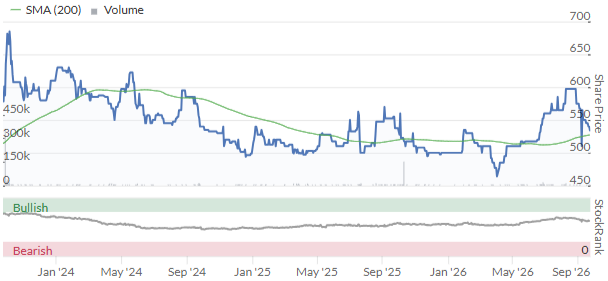
Overall, I do have a very positive impression of this business. It might be the best little equipment hire company that’s listed on the market. I just don’t see why it should be rated much more highly than it already is!
Roland's Section
Warpaint London (LON:W7L)
Down 12% at 197p (£156m) - Interim Results - Roland - PROFIT WARNING (AMBER =)
This cosmetics business has been on a downgrade cycle over the last couple of years. The stock is down by 69% from its July 2024 highs. Earnings estimates for the current year had already been cut by nearly 40% before today’s half-year results, which include (another) profit warning.
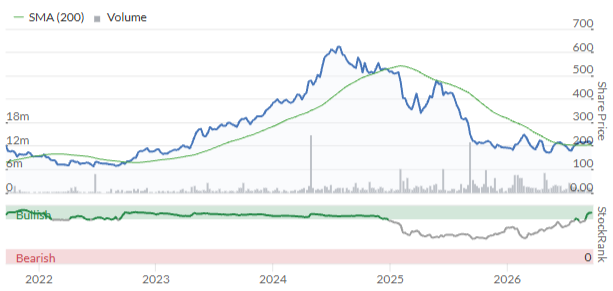
Although Warpaint’s sales and profits are normally H2-weighted due to the importance of the festive period, the company says the H2 weighting will be “significantly” heavier than usual this year. While I believe there are some good reasons to believe this could happen, this guidance could also be a sign that the company is having difficulty meeting forecasts.
Today’s results provide mixed messaging on the outlook for the remainder of the year, as I’ll explain. What is certain is that as Martin has observed in the comments, this is a business that needs a good Christmas.
Half-year results summary
Warpaint’s headline figures for the half year do not make for reassuring reading. Sales fell sharply during the period, “with continued pressure on consumer spending and cautious ordering by retailers across a number of our principal markets”.
These figures would have been even worse without a £2.5m contribution from the Barry M brand, which was acquired in February 2026:
Revenue down 17.8% to £40.5m
Gross margin up 2.3% to 47.3%
Adj EBITDA down 36.4% to £6.8m
Pre-tax profit down 33.2% to £4.9m
Adjusted earnings per share down 46.6% to 4.5p
Net cash up 21.5% to £20.7m
Interim dividend up 6.3% to 4.25p
The improvement in gross margin is encouraging and suggests efforts to improve sourcing are paying off. Even so, the underlying increase in gross margin was only 0.8%; the remaining 1.5% came from selling through Barry M inventory that was acquired at a discount to book value.
More broadly, it looks like the loss of volume has resulted in a nasty dose of reverse operating leverage, with profits falling faster than sales. Warpaint’s operating margin for the half year dropped to 12.8% (H1 2025: 15.3%).
Looking at the split across the group’s brands suggests the weakness was broad based, with further headwinds from some adverse timing effects, especially in the US and Australia:
W7 sales down by 19.8% to £23.9m
Technic sales 29.8% to £8.7m
Brand Architekts sales down 24.1% to £4.4m
Barry M: this brand was acquired out of administration in February 2026 for £1.4m and contributed £2.5m sales of the period. Margins are said to be “slightly higher” than W7 and Technic and the deal has also enabled the company to expand its relationship with Superdrug.
Positive progress: a big chunk of today’s management commentary is used to highlight recent progress with new and existing customers. Here’s a flavour, from CEO and 20% shareholder Sam Bazini:
Importantly, our brands and customer relationships remain strong. We have made encouraging progress with a number of major retailers, including Rossmann, Superdrug, Tesco and Tigotà, ecommerce continues to grow, and the Barry M brand has been successfully integrated into the Group.
Outlook & Broker Estimates
Based on the company’s detailed commentary, I think there probably are some good reasons to expect a stronger H2 weighting than usual this year.
At the same time, I think it’s fair to say that the targets being implied for the second part of the year and for Q4 in particular are quite demanding. Today’s Q3 update provides additional detail on this.
Q3 update: sales for the nine months to 30 September are expected to be c.£69m, with Q3 revenue of £28.5m around 5% higher than for the same period last year.
Crunching the numbers tells me that in 2025, the company generated c.73% of revenue in the first nine months of the year, leaving 27% for Q4.
Today’s figures suggest that in 2026, management expects to generate around 66% of revenue in the first nine months, leaving 36% of sales for Q4.
To make matters worse, revenue is now expected to fall slightly short of expectations this year, with additional profit contribution being expected as a result of higher margins:
The Board currently expects revenue for the year ending 31 December 2026 to be towards the lower end of the range of current market expectations and Adjusted EBITDA to be within the current range of analyst forecasts
(Note: we’re told that consensus forecasts prior to today were for revenue of £103.3-112.6m and adj EBITDA of £22.4-24.0m.)
With thanks to Research Tree, we have access to updated forecasts from Shore Capital this morning. Shore is Warpaint’s NOMAD and joint broker, so its numbers should be a good indicator of management thinking.
Shore Capital’s analysts have trimmed revenue expectations and cut earnings forecasts for both 2026 and 2027 today:
FY26E revenue: £103.5m (-4% vs £108m previously)
FY26E adj EPS: 18.3p (-8.5% vs 20.0p previously)
FY27E revenue: £106.0m (-6.4% vs £113.3m previously)
FY27E adj EPS: 18.5p (-12.3% vs 21.1p previously)
I think it’s notable that the cuts to 2027 estimates are actually larger than those for 2026.
It’s also worth highlighting that these forecasts imply that Warpaint will need to generate 75% of earnings in H2 this year. That’s significantly more than usual.
Roland’s view
Today’s results will be a disappointment for investors (including me) who were hoping that June’s in-line update indicated a turning point after a series of downgrades:
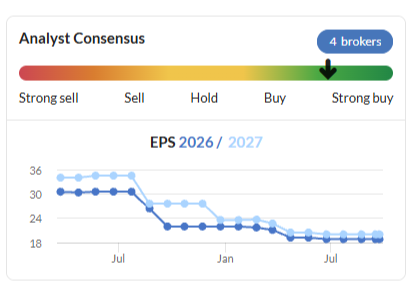
However, I think it’s fair to say that there are still some points in favour of this founder-led business. Warpaint remains a relatively high margin and cash-generative business, with a strong balance sheet.
Trailing 12-month return on capital employed of 18.7%
TTM return on equity of 14.8%
After this morning’s fall, Warpaint is now trading on less than 11x 2026 forecast earnings, with a covered 7% dividend yield. I’d argue that a fair amount of bad news is already priced in.
The business is still expected to return to growth next year, with today’s forecasts suggesting that both sales and profits will rise in 2027.
So what could go wrong? In the near term, I guess the main risk is that H2 sales will fall short of revised expectations and higher margins will be unable to pick up the slack. That could result in another profit warning in Q4/Q1.
On a medium-term view, perhaps the bigger risk is that the company’s core W7 and Technic brands will lose their growth momentum and will be replaced in shoppers affections by other contenders.
I don’t know how likely this is. While I think the company’s increasingly strong presence with major retailers including Superdrug, Tesco and Walmart is probably a positive factor for longevity, I wouldn’t rule out further pressure on margins.
I moved our view on this business up by one notch to neutral in June. Given that today’s downgrade is relatively mild and the valuation looks undemanding, I’m going to leave that previous AMBER view unchanged today.
JD Sports Fashion (LON:JD.).
Down 3% at 76p (£3.6bn) - Half-Year Results - Roland - AMBER =
We last covered this footwear retailer in August, when JD used its Q2 update to warn on profits (again).
Today’s half-year results leaves guidance unchanged and doesn’t seem to contain anything much of note.
As expected, half-year profits are down sharply, leaving a substantial H2 weighting if JD is to meet revised forecasts:
Sales down 0.7% to £5,899m
Gross margin down 0.2% to 46.8%
Operating margin down 1.2% to 5.0%
Adjusted pre-tax profit down 19.7% to £282m
Adjusted earnings down 13.75 to 3.97p per share
While us Brits tend to think of JD as a UK-centric business, the company now generates the majority of its sales and profits (38% and 42%) in North America, following a series of acquisitions over the last decade.
Unfortunately, it’s this region that also placed the biggest drag on the groups’ results in H1. The UK was the other main detractor from performance.
H1 adjusted operating profit:
North America down 32% to £123m
Europe down 2% at £52m
UK down 15% to £94m
Asia Pacific up 4% at £25m
As previously, management blames performance in North America on “weaker core consumer sentiment”, and a “highly promotional market”. JD also mentions what are euphemistically described as “footwear product cycle headwinds”. As far as I can see, this is a coded way of referring to the ongoing turnaround at Leverage Shares 2x Nike Etp (LON:NKE2), whose products generate c.40% of JD sales.
It’s probably worth revisiting the chart I’ve used previously showing JD and Nike’s share price performance over the last 10 years:
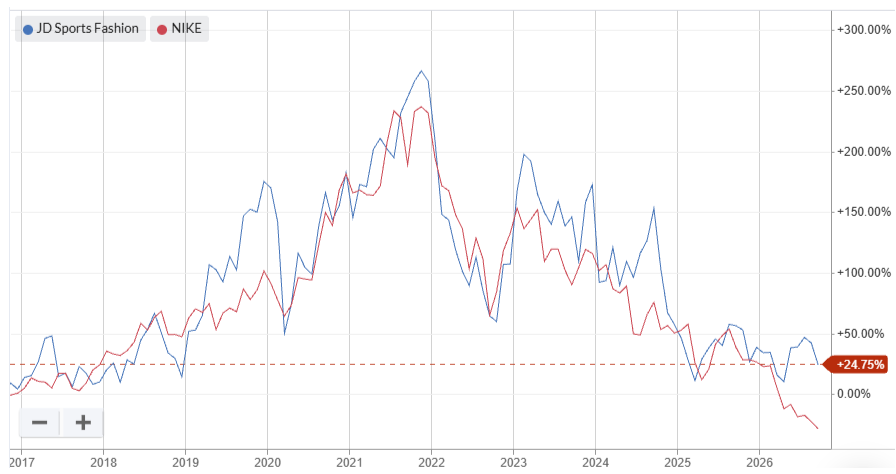
Profitability & Balance Sheet: while the fall in operating margin to 5% in H1 was a little disappointing, I think this probably needs to be seen in the context of full-year performance. From what I can see, consensus forecasts suggest the full-year margin should return to c.7%, broadly in line with prior years.
Net cash of £168m at the end of the period is a reminder that JD remains a fairly cash-generative business, as well.
I don’t see any imminent fundamental concerns, if JD can deliver on existing forecasts.
Outlook
Full-year guidance was cut in August, but is unchanged today:
FY27 adjusted pre-tax profit of £700m to £800m
FY27 free cash flow of £460m to £520m
If JD can deliver on this free cash flow guidance, then that could see the stock trading with a free cash flow yield of c.13%. In my view, that is probably too cheap for this business.
Consensus earnings forecasts also suggest a very moderate valuation:
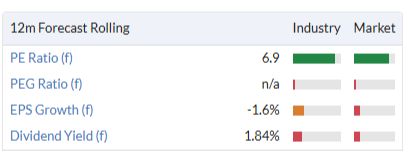
Roland’s view
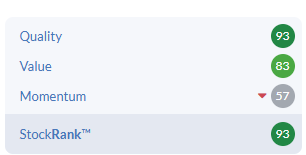
JD’s quality and value credentials support a strong StockRank and Super Stock styling.
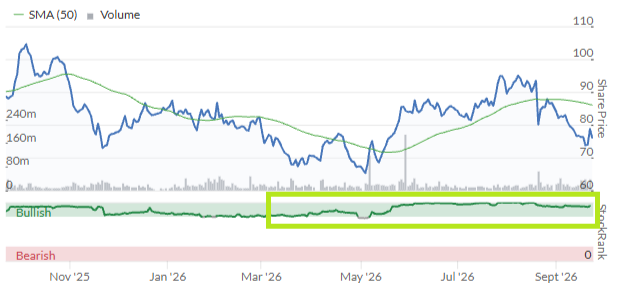
The company’s StockRank has moved steadily higher this year, too – potentially a positive indicator:
Against this backdrop I’m a little conflicted. I respect the factor scores and the apparent value on offer here.
However, I’m wary about JD’s persistent poor momentum and the risk that H2 earnings could disappoint. Perhaps my main concern is that JD’s fortunes appear to be so closely linked to those of Nike – a business it has no control over.
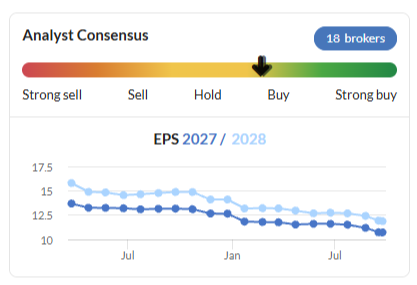
Today’s H1 EPS of 3.97p means that JD needs to deliver 63% of its earnings in H2 in order to meet FY27 consensus estimates of 10.7p per share. I’m not sure how likely this is.
For these reasons, I’m going to retain my previous neutral view on JD today, with the caveat that the shares could be cheap and would probably deserve an upgrade on any sign of improving momentum.
Ingenta (LON:ING)
Down 14% at 70p (£11m) - Interim Results - Roland - AMBER =
This micro cap software business provides intellectual property and content management systems for the publishing industry. I’d guess this could be an interesting niche in the AI era, with opportunities for innovation.
Checking back through the archives, I see Graham was AMBER/GREEN in April and moved our view down to AMBER in June to reflect a lack of visibility on earnings.
Half-year results summary
Today’s results highlight Ingenta’s strong balance sheet but don’t show much sign of the growth I’d hope to see in a business of this size:
Revenue down 2% to £5.1m
Adj EBITDA down 22% to £0.7m
Adj earnings per share 14.7% to 5.00p
Interim dividend unchanged at 1.75p
Net cash of £4.6m (Dec 25: £4.7m)
Looking a little more closely suggests to me that the company has some sticky core customers, but is not generating much in the way of new business:
Commercial revenue up 5% to £3.9m, driven by “additional Managed Services revenue from the existing customer base”.
Content revenue down 7% to £1.3m, “due to lower implementation and consultancy revenue”.
92% of group revenue was recurring in nature.
Despite my scepticism, Ingenta says that the half year was a positive period for new business, with over £2m of new revenue secured to be delivered over the next three years:
The new business includes providing our ConChord IP management software to an influential US record label, a new contract for the deployment of Edify to a leading US university publisher and the provision of our legacy commercial software products to an international trade publishing customer in the Australian market.
Management also says that Ingenta has “significant sales proposals awaiting customer decisions in H2 2026”.
Acquisition: In August, Ingenta acquired a 24.9% stake in a company called FirstAida Limited in July, in exchange for 798,061 shares. Based on today’s share price I estimate this at £559k. There’s also some deferred consideration due if FirstAida revenue tops £500k, plus an option to acquire the remainder of the business.
The company sees FirstAida as a strong fit, although it’s evidently also an early-stage business. Perhaps Ingenta’s chairman and 27% shareholder Martyn Rose is hoping FirstAida will provide new growth opportunities?
Strong strategic fit, extending Ingenta's capabilities into AI-led IP infringement investigation while creating significant cross-selling opportunities
Dr Dan Brown, founder of FirstAida and Entrepreneur in Residence at University College London, joins Ingenta's Board as Non-Executive Director
Outlook
Full-year expectations are unchanged, at least at the EBITDA level. However, efforts to ramp up sales activity appear to be running behind schedule:
The Board remains confident the Group is on track to meet EBITDA expectations for the year, and is actively pursuing a range of initiatives to enhance future performance and profitability. The Group’s plan to invest in its sales team has taken longer to execute than expected, given the difficulty in recruiting suitable personnel, but remains a priority for the second half of the year.
With thank to house broker Cavendish, I can see that 2026 forecasts are unchanged today:
FY26E adj EPS: 8.6p
There are no forecasts for 2027 (indeed, these 2026 forecasts were only published in June).
Roland’s view
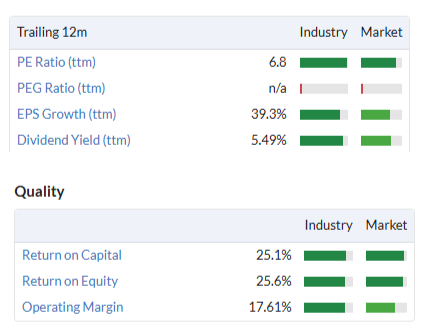
Ingenta appears to have some attractive characteristics, with strong quality and value metrics:
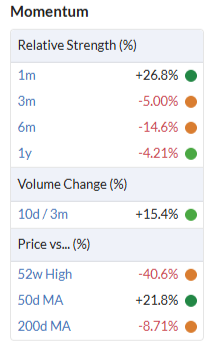
However, momentum is a clear weakness. Profits are expected to fall this year and there are no forecasts for 2027. Technical momentum has also been fairly weak recently:
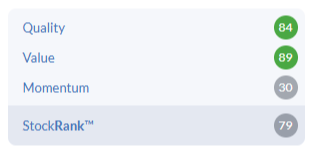
This situation is reflected in the StockRank, which styles Ingenta as a Contrarian stock:
This situation might reward more in-depth research and understanding of Ingenta’s products and the sectors in which it operates.
However, my initial impression from this brief review is that a neutral view remains appropriate from our factor-led perspective, due to the lack of earnings visibility or momentum.
I’m going to leave our view at AMBER today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

30 comments
Possible bid for Ashtead Technology Holdings (LON:AT.) at 80% premium ...
timarr
error ignore
Citrini Research, the ones who posted a SCiFi article (Feb 2026) which was largely responsible for the SaaSpocalypse Selloff have an update. Very topical because META have just launched "MUSE". https://www.citriniresearch.com/p/agentic-reality
Previous Article (forward looking educated SciFi): AI destroys software → software valuations collapse → employment collapses → economy suffers.
> They did say it was written partly as a thought exercise and I believe they were surprised by how much traction their article got. A blog version of a viral video perhaps.
Latest Article written to be much less controversial methinks: AI agents change the economics of consumer behaviour./ Who owns the customer when the customer no longer does the shopping?
> Note admits "the card companies are probably not going to be the losers here" as they suggested VISA and MasterCard may be at risk in Feb
My take is: the winners will be those companies that can effectively take advantage of how AI changes the economics of consumer behaviour. And gets the timing (and IT decisions) correct, not too early not too late - if you are relying on individuals across the planet to change their buying behaviour (and for them to trust AI to make purchases) there will be early adopters, there will be later adopters, but the key question is when does the critical mass make the change. IE YES ITS POSSIBLE, BUT WILL IT AND WHEN.
It will be interesting to see how the likes of Salesforce perform over next week or two. Although the MUSE thing seems to be creating a stir so muddy waters.
Side thought: Pershing Sq - 13 Aug 26 - six new holdings, including Netflix NFLX.O, Visa V.N and Mastercard MA.N, marking the billionaire investor's biggest portfolio overhaul in years. Putting this with the Citrini thing only suggests Ackman might be on the right path, long way to go.
All very interesting from a wider world point of view if not for the investment.
The FTSE 100 is about the only index in the western hemisphere in positive territory!
Has Burnham resigned????
Chapel Down (LON:CDGP) just listened to the IMC presentation. All sounds good, targeting 1% of the global champagne market-currently they have 0.4%. Marketing initiatives are impressive . I hold it to get the 33% discount on the wines, but it does seem that maybe I should be looking at it as a growth story, though the journey is sometimes better than the arrival. The albarino wine they release once a year is pretty good- comparable with a good Galician one., and the sparkling wines in particular the Kit's Coty and the Brut reserve are pretty good.
That 1% target by Chapel Down (LON:CDGP) ... Did they say by when?
I think I listened to a presentation by them earlier this year... And they gave a date in the mid-2030s...!
Clearly there are supply side growth drivers though. Vineyard acres owned, planted, and maturing all healthy growth next few years in terms of harvest volumes. Demand is the key.... As whole industry has expanded supply side alot in the last few years...
No- 0.7% by 2030. 1% as you say 2035.
Following 2 posts from subscribers earlier about Hargreaves Lansdown dealing procedures I to am growing increasingly frustrated with them. I have been a client since 2004.
Their actions seem almost deliberate. Seriously thinking of moving to another Broker.
It's infuriating isn't it! Just moved all my personal accounts to interactive brokers - saving hundreds of pounds a year too
I really don't know what they are trying to achieve. I find it amazing that they have added functionality which now allows you to trade blind but in doing so makes the system more clunky for those customers who want to know the price before they deal. Limit orders still use the old page design which is a constant reminder of how how poor the revised approach is.
Would be interested in any comments regarding the following announcement from Pollen Street (LON:POLN) . https://newsfile.refinitiv.com... Share price up 13% in response
I hold POLN having bought a week or so ago following a mention on the Investment Trust thread. Haviong used Gemini AI to do some research on likely values arrived at this "If a binding takeover offer materializes, a realistic acquisition price will likely land in the 1,100p to 1,300p range per share to secure board approval and institutional shareholder support. However, if strategic discussions fail to produce a firm bid, the stock risks retracing back down toward its fundamental support levels around 800p–850p"
Brokers target pricing for POLN are 1120p-1320p based on the growth of AUM- target is £10bn . They hold about £500m in portfolio investments.
Pollen Street (LON:POLN) (I hold)
I believe its going XD tomorrow for a div of 28p so there will be a small move downwards.
Pollen Street (LON:POLN) I hold and in truth not one I wanted as the stock came from another investment and POLN promptly cut the dividend. I have held ( in my ISA) as the yield helps fund my modest life style (!) better than paying tax on any SIPP withdrawal as I am somewhat averse to funding more Socialist spending. I had expected some corporate development once Shawbrook was floated so I will await developments with interest.
Investment Weekly comment
https://www.investmentweek.co....
Gresham House Energy Storage Fund (LON:GRID) H1 missing
NAV per share of 131.30p as at 30 June 2026, up 15.8% (31 Dec 2025: 113.34p)
Portfolio revenues of £34.7mn and EBITDA of £23.5mn, up 9.5% and 14.5% respectively from H1 2025
Yes but since they have suspended the dividend since 2024 ( a small interim payment was made) not sure what the attraction is.
HL seem to have changed their dealing process very much for the worse as far as I can see. I have told them so!
I agree all there changes make their site much more difficult . their app was excellent now rubbish .I have have told them but I DONT THINK THEY CARE
Same, agree. Very poor, considering moving. App now so slow to load.
Hi I have a small account with HL where I trade regularly. I do not use the app ( must have some form of aversion to this means of trading ) I have utilised the new dealing set up and not had any issues via the website. I must say, from experience , that I seem to be able to get price improvements from them which AJB cannot match. I would never attempt to trade in the fixed interest market with the latter as its prices are generally not competitive in any volume
Is this for equities or bonds, where you have seen HL have better pricing quotes for? And UK or Intl?
Hi
Both equities and fixed interest in one instance i compared the buy price on AJB to that on HL and the latter was superior. I do not generally deal in large cap stocks so some amerlioration of the spread which prevails is always something I am looking at
Warpaint London (LON:W7L)
Hi Graham
Are you commeting on the ( admittedly poor) results. I see the price has dived which is understandable given consumer background . Some of the metrics do not look awful and at my low purchase price this constutent of my income portfolio yields circa 10%. Yup it needs a merry Xmas
Morning Martin,
Warpaint London (LON:W7L) is on the list for this morning!
Roland
Warpaint London (LON:W7L)
the update here is of the horrible sketchy type.
they key here is are some brokers now going to downgrade stuff outside the range explicitly given todayr.
I much prefe companies to give us straight talking ranges rather than dance around the issue. so you tell us its between now x and y not - say it wil be just above then bottom - near teh bottom suggests the lower point of the range may have dropped ? despite your proterstyations otherwise.
Perhaps it doenst matter - the company has partly nailed its colours to the mast by sticking with Adjusted EBITDA of between £22.4 million and £24.0 million - but its clear that they have huge amount of work to done to get there - if ever a company wasa setting us up for further bad news later on - well thast what they have done today. So perhaps even if they had simply narrowed range i am not sure tehn market and the brokers wil believe it
this is perhaps the important blunt bit - they clearly need things to go as expected - and they have much work to do - are they being over rosy here ? only time will tell
As previously indicated, the Group's performance in 2026 is expected to be significantly more second half weighted than in prior years, reflecting the timing of larger customer orders and planned rollouts, significantly increased Christmas gifting activity, continued growth in ecommerce and a contribution from Barry M
lets see what the update broker numbers wil be - and will they also update next year ?
Ok we have broker updates in and they are telling us what the company refused to say - in the absence of the company saying next yeas it was as previuously expected - its clearly not now - do brokers genuinly work in the dark when choosing to downgrade next years figures ? is this really not a nod and a wink from the company whilst at same time company not telling shareholders that real truth. whats tehn point of compoany updating everything if the real truth about thne future and change is simply not communciated to shareholders - but is communicated to brokers - sigh.
Andrews Sykes (LON:ASY) Time to look at the details on this one ? Or turn the heat up on their statement.
EDiT. Apologies for my confusion this morning, The update was from Cordiant Digital Infrastructure (LON:CORD) and not Custodian Property Income Reit (LON:CREI) I think it is best if I withdraw my incorrect request (below this edit) for comment on Custodian Property Income Reit (LON:CREI) Graham unless there’s obvious demand for you to comment on Cordiant Digital Infrastructure (LON:CORD) instead.
It would be good if you could (perhaps briefly) comment on the Custodian Property Income Reit (LON:CREI) update today. Looks solid overall but does this section explain the slightly negative share price reaction?
“Steven Marshall, Executive Chairman of Cordiant Digital Infrastructure Management, said:
“The Company’s Buy, Build & Grow strategy is delivering. We acquired well-positioned platforms with secured power and strong customer relationships, and we are now building on them by expanding capacity, entering adjacent markets such as AI compute and winning medium- to long-term contracted revenue from enterprise, cloud and public sector customers. The growth phase is where value is created, and the investment opportunities in front of us are expected to deliver attractive returns above the Company’s target net return of 9% p.a. Demand for what our platforms offer currently exceeds the capital available to meet it, and securing the funding to pursue these high-return investments is our central priority.”
Be great if you had time to have a look at Pantheon Infrastructure (LON:PINT) team nice well covered dividend and share price has been trending upwards nicely last two years for something that relatively defensive.
Thanks the Phoenix, I've taken a note of that! G
Appreciated Graham.