Daily Stock Market Report (Wed 26th November 2025) - Budget LIVE, CBOX, BEG, PETS, JDG, IOM, KETL, SDY

Good morning! It's finally here!
We'll be following today's Budget news with a dedicated section inside this report, as it happens.
Spreadsheet accompanying this report: link (last updated to: 10th November).
Budget Live Stream (now finished)
12:34: The Chancellor begins her statement, with the OBR's analysis having already been published on their website!
12.39: Strong words on economic stability and debt reduction as a percentage of GDP.
12.41: Notes that the economic growth forecast at the OBR increased from 1% (at the start of the year) to 1.5%. Lower productivity forecasts from the OBR are blamed on the other political party.
12.44: Widens eligibility for EIS/VCT schemes so they can stay with companies for longer. 3-year exemption from Stamp Duty for companies who list in the UK.
12.46: Big ISA news: from April 2026, £8k of the £20k ISA allowance will be designated for investment rather than cash. Over-65s will still have their full cash allowance.
12.52: First small modular nuclear reactors to be built with Rolls-Royce in Anglesey.
12.55: Government debt c. £2.6 trillion , 83% of GDP. Deficit is £28.8bn, and deficits are planned until a surplus in 2028/2029. Debt is planned to be down by the end of the forecast period.
13.02: Pensioners whose schemes were rescued by the Pension Protection Fund will now enjoy inflation indexation.
13.07: Digital ID to crack down on tax evasion and fraud.
13.10: Welfare reform: face-to-face assessments for disability payments. Changes to universal credit to get more people back to work.
13.12: Abolishes access to Class 2 National Insurance contributions for people living abroad, and requires a minimum of 10 years of contributions to access the State pension.
13.13: Income taxes: freezes to personal tax thresholds for three years, to 2031.
13.15: Taxes on Investments: Increases basic and higher rate of tax on savings, dividends and property income by 2%.
13.18: Council Tax surcharge: an additional £2,500 to £7,500 will be charged on homes worth more than £2 million.
13.19: Salary sacrifice: from 2029, there will be a £2,000 cap on salary sacrifices into a pension.
13.19: CGT relief on employees of businesses will fall from 100% to 50% relief.
13.25: Gambling taxes: Increases remote gaming duty from 21% to 40%. Increases online betting duty from 15% to 25%. Abolishes bingo duty.
13.26: Will not increase NI, Income Tax or VAT rates.
13.31: Two-child benefit cap is scrapped.
13.34: National Living Wage: as previously reported, it is set to increase from £12.21 to £12.71.
13.39: It's done!
13.44: Response by Kemi Badenoch: describes the Budget as a tax raid on working people to fund handouts. Higher taxes on workers, savers, investors, cars, pensioners, etc. "All it delivers is higher taxes and out-of-control spending".
Graham's summary: the FTSE is up 0.6% today, the pound is little changed against the dollar, and there's no meaningful change in the 10-year gilt yield. So as far as markets are concerned in the short-term, this has turned into a non-event.
Looking at the particular measures, the one that stands out is the ISA change. Most people reading this are likely to be far more interested in an S&S ISA rather a cash ISA anyway, but perhaps this measure will cause more money to flow into AIM/Main Market shares? Although there is no introduction of a "British ISA" that would have forced people to do this rather than invest internationally.
The National Living Wage increase is not new or surprising.
The freezes to tax thresholds may affect the consumer in the medium-term, but there is no immediate direct effect on businesses.
Higher taxes on investment income will affect small businesses and landlords, which I assume will mean more investors leaving the buy-to-let sector.
In gambling, the 888/Evoke share price (I hold this one) is down 13% in response to higher taxes. The land-based Rank casino group is up 12%.
An interesting Budget: not as dramatic as it might have been, but with plenty for us to chew on in the days and weeks ahead.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our View (Author) |
|---|---|---|---|
Intertek (LON:ITRK) (£7.1bn | SR71) | Acquired PTL, a “leading flooring products testing company” in North America. PTL has 26 employees and generated £4.3m of revenue in 2024. | ||
Energean (LON:ENOG) (£1.69bn | SR42) | Q3 pre-tax profit -30% to $268.2m. Q3 prod 151 kboepd (85% gas), slightly below 156 kboepd in the prior year, but in line with FY guidance of 145-155 kboepd. FY outlook unchanged except net debt now exp $3.1-$3.2bn (prev. $2.9-$3.1bn). | ||
Pets at Home (LON:PETS) (£937m | SR81) | Rev -1.3%, pre-tax profit -29% to £36.2m. Interim divi held at 4.7p. Vet revenue +6.7%, retail revenue -2.3%. FY outlook unchanged for adj PBT of £90-100m. | AMBER ↑ (Roland) [no section below] In The Week Ahead last Friday I explained why I was starting to think that PETS could be a potential contrarian situation. The stock has suffered a four-year share price decline and multiple profit warnings over the last 12 months. But today’s results are in line with expectations and do not seem to suggest any fresh problems to me. Cash generation remains strong and while margins are lower due to lower volumes, operating cost growth seems to have been manageable in H1. I don’t think there’s anything fundamentally wrong here. PETS still has nearly 8m loyalty club members and sharpening up its retail execution ought to create some opportunity for improved performance, in my view. Now that the pandemic pet boom has washed out of the sales figures and the equity valuation, I am starting to feel this business could be worth a closer look. A forward P/E of 13 and still-covered 5.8% dividend yield could represent a sensible entry point in my view. The caveat to this is that the company’s last profit warning and the unscheduled departure of its former CEO are still relatively recent and near-term performance could still disappoint. To reflect this I’m switching to neutral today and will await further updates with interest. | |
Elementis (LON:ELM) (£893m | SR59) | Acquires Alchemy Ingredients for c.$22m. This business develops rheology modifier ingredients for cosmetics and skin care products and is expected to generate $6m of sales this year. | ||
Workspace (LON:WKP) (£702m | SR40) | Sold three properties in London for £41.7m, in line with Sept 25 valuation and at a net initial yield of 7.9%. All were identified as “low conviction buildings” in a recent review. Asset sales now total £94.1m so far this year. | ||
Auction Technology (LON:ATG) (£349m | SR64) | Rev +9%, adj EBITDA -4% to $76.8m. Reported operating loss of $(134.2)m due to impairment. FY26 performance to be in line with market exps, with revenue growth of 4%-5%. | ||
Judges Scientific (LON:JDG) (£309m | SR29) | CEO David Cicurel steps up to non-exec chair. Group Business Development Director becomes CEO. Existing chair becomes deputy chair. | AMBER = (Graham) [no section below] Founder and major shareholder (8%) David Cicurel has without a doubt been one of the best CEOs on AIM. Now age 75, he ran an acquisition strategy that multiplied shareholders’ wealth many times over. Unfortunately, the JDG share price did get overheated about five years ago. On top of that, the company became a victim of its own success, as its size required it to find larger targets that could move the needle. In recent times, it has also experienced weak demand in the scientific research sector. So there hasn’t been any further share price progress since late 2019. That’s the backdrop to Mr. Cicurel’s move to the position of non-Exec chair. His successor as CEO is not a surprise: Dr. Tim Prestidge joined JDG from Halma in 2023 and has been working under Mr. Cicurel as Group Business Development Director. I think this is a fine appointment but I am going to remain neutral on JDG shares for the time being. It will be worth watching for signs of a strategy reboot that could get this moving again. | |
Helical (LON:HLCL) (£244m | SR43) | EPRA NAV per share 349p (H1 25: 348p). Total EPRA Accounting Return 1.0%. LTV 28.2% (March 25: 20.9%. EPRA EPS 2.4p, interim dividend 1.5p. | ||
Begbies Traynor (LON:BEG) (£172m | SR86) | Real estate consultancy Kirkby Diamond acquired for £8.25m. In FY25, Kirkby Diamond generated £6.2m of revenue and adj PBT of £1.1m. Will integrate with BEG’s Eddisons business. | AMBER/GREEN ↑ (Graham) I’ve gone back and forth on this one this morning. On balance, I think it deserves an upgrade. Even though it’s trading at a PER of 10x, which I generally consider to be its fair value, its quality metrics have improved and I think they can continue to do so. While it’s not a quality compounder in the traditional sense, its M&A strategy does appear to be working well. So I’m a bit more optimistic on this one. | |
Mobico (LON:MCG) (£133m | SR8) | YTD revenue +5.4%, “large scale cost reduction programme underway”. Outlook: adj op profit towards lower end of £180-195m range. | ||
Speedy Hire (LON:SDY) (£117m | SR71) | Revenue +0.8%, adj PBT loss of £(7.2)m. “Subdued market conditions”. Outlook: FY26 expectations remain unchanged with H2 weighting to revenue and profit. FY26E adj EPS 2.6p (-9% vs 2.8p previously) | AMBER = (Roland) [no section below] My cautious view on this equipment hire business is largely unchanged from my comments in early October. But I think it’s worth highlighting that despite management’s unchanged outlook statement, broker Panmure Liberum has cut its EPS forecasts today (see left) – our thanks for making these forecasts available. While EBIT expectations from the core UK business are unchanged, PanLib now sees lower (zero!) profits from a JV in Kazakhstan due to contract delays. The broker also expects to see higher interest costs than previously, due to increased leverage of 2.2x EBITDA (net debt £119m). PanLib’s forecasts for FY27 have been left unchanged for now, but I wouldn’t bet against a further disappointment in JV profits – I don’t really understand why a small UK company like Speedy Hire would get involved with an overseas JV of this kind. I think I can hang on to my previous neutral view here today, but only just. | |
Cake Box Holdings (LON:CBOX) (£92m | SR57) | Rev +53.5%, adj EBITDA +33%, due to maiden contribution from Ambala Foods. Adj pre-tax profit -4.5% to £2.7m due to increased finance costs following acquisition. FY outlook: in line with exps, with seasonal H2 weighting. | AMBER ↓ (Roland - I hold) Today’s results show strong top line growth, but a much larger rise in costs means that bottom line profits actually fell in H1. I think it’s possible that enhanced H2 seasonality will mean this situation reverses in H2 and allows the company to meet full-year forecasts. But I’m not entirely convinced and am also a little wary about the increased risk from higher leverage. On balance, the share price looks about right to me at current levels, so I’m moving down one notch to a neutral view today. | |
Avation (LON:AVAP) (£87m | SR54) | "Demand for passenger air travel remains strong… This encouraging backdrop supports our ability to place the remaining aircraft from our orderbook on lease at attractive terms and successfully transition aircraft between airlines as and when leases conclude.” | ||
Strix (LON:KETL) (£82m | SR72) | SP -2% Revenue £64.6m, net debt £70.3m, leverage 2.5x, for 6-month period ended 30 September 2025. Group is trading broadly in line with market expectations for FY26. The company also announces an “accelerated debt reduction programme", as it seeks to reduce Chinese inventory by £8m. It has also started factoring its debts in Italy (i.e. selling its invoices at a discount for immediate cash). Key sentences: “the Board is assessing a variety of operational and corporate actions to enhance stakeholder value”. There is “ongoing supportive and open dialogue with the existing lending group”. Target leverage is 1.5x in the next 12-18 months. CEO steps down “by mutual agreement” from May 2026. | BLACK (RED =) (Graham) [no section below] We turned RED on this kettle controls producer in July after a profit warning. We’ve had concerns about the debt load and the company also appears to be concerned as it makes debt/leverage reduction a top priority. The current leverage multiple of 2.5x is on the high side for most industries and a £70m debt load does seem substantially larger than Strix can comfortably carry. As for the core kettle controls business, it’s in a fight against copycats to protect its IP - the current value and the longevity of its patents were always the core assets here in my view. The company has to prove that these are still intact while also growing its newer divisions (Billi water filtration and its “Consumer Goods” division). And they will have to find a new CEO to do it. Equity Development today cuts its PBT and EPS estimates for the company by 10%, as a “broadly in line” trading update is, unsurprisingly, a profit warning in reality. Our RED appears to be the correct call for now. | |
Spectra Systems (LON:SPSY) (£61m | SR66) | Five-year service agreement with a customer for the maintenance of existing sensors as well as the new generation sensors which are replacing them. Service revenue approx. $6.7m revenue from 2026-2030. | ||
Arrow Exploration (LON:AXL) (£32m | SR50) | Update on operational activity at the Mateguafa Attic field on the Tapir Block in the Llanos Basin of Colombia. Testing results of M-6 Well indicate it is capable of higher rates; ultimate flow rate will be determined in the first few weeks of production. | ||
FIH (LON:FIH) (£31m | SR66) | Revenue +4%. Net cash before leases £16.1m. Challenges in the FIC (Falkland Islands Company), expected to continue to significantly impact the performance of the division for the remainder of the year. | ||
iomart (LON:IOM) (£29m | SR45) | H1 results in line with the October trading update. Revenue +25%, organic revenue down. Net debt £109.6m. Outlook within the range of current market expectations. | RED (Roland) [no section below] I haven’t looked at this web hosting and IT services business for a while and am shocked at how far the situation has deteriorated. Today’s interims show a near-10% decline in organic revenue “due to previously disclosed customer churn”, with overall revenue only propped up by the acquisition of Atech in October last year – a £57m deal priced at 17x EBITDA, which looks to have been expensive and potentially misguided to me. Even with the contribution from Atech, Iomart’s adjusted EBITDA fell by 34% YoY in H1, while the accounts show an H1 operating loss of £1.8m. The icing on the cake is that the acquisition plus further cash outflows in H1 mean that net debt has more than doubled to £109.6m over the last year. That’s three times the market cap and gives a leverage multiple of 3.1x EBITDA. The turnaround story is that Atech could help Iomart to become a strong player in providing Microsoft Solutions to UK SMEs. I’m not yet convinced. Broker Cavendish is forecasting a tentative return to profit in FY27 (y/e March), but with negative cash flow and this level of leverage, I think there’s some risk to the equity until leverage falls or profitability improves. Personally, I am not sure Iomart has the scale, technical capacity or pricing power needed to return to its former level of success, so I’m going to take a negative view today. | |
Tungsten West (LON:TUN) (£21m | SR20) | Has signed heads of terms with Duo Group for the Engineering Procurement and Construction works package for the New Build Crushing, Screening and Ore Sorter Facility at Hemerdon. | ||
RTC (LON:RTC) (£12m | SR90) | “Despite a challenging UK economy which has impacted recruitment generally, and the significant additional cost burdens imposed by the government's decision to increase employers' national insurance contributions in the Autumn Budget 2024, the Group's expects to deliver [results] that are broadly in line with last year." | ||
Genedrive (LON:GDR) (£10m | SR4) | Notes the recent media coverage of its Genedrive® MT-RNR1 ID Kit, which reduces the risk of deafness in newborn babies. Introduced initially by NHS Greater Glasgow and Clyde. |
Graham's Section
Begbies Traynor (LON:BEG)
Up 1% to 108.65p (173m) - Acquisition - Graham - AMBER/GREEN ↑
Begbies already announced a small acquisition yesterday, which we didn’t comment on due to its small size. But let’s quickly do that now: it was the £1m acquisition of Network Auctions, a property auctioneer:
The addition of Network Auctions will add scale to our existing auctions business and further develop our national coverage in the south east of England.
Network Auctions will get folded into the Eddisons group.
Today’s announcement is a bit meatier:
Kirkby Diamond (real estate consultancy) is bought for £8.25m
Cash-free and debt-free purchase.
Kirkby Diamond will also join up with Eddisons.
5 locations, 62 staff.
This acquisition extends Eddisons' strategic footprint to cover the entire M1 corridor, and aligns with our strategy to strengthen our service offering and expand our market coverage.
Key financials: Kirkby Diamond generated £6.2m revenue and “normalised” PBT of £1.1m in FY January 2025. Net assets £1.4m.
Valuation is 10x normalised after-tax profits, which is perhaps on the high side for a smaller business in this sector? But:
Deal structure: £5m up front,of which £3.5m is cash and the rest is new BEG shares. Earn-out of up to £3.25m if profits are maintained and increased in the coming years.
Let me revise what I just said: the valuation is probably reasonable, given the conditions attached in the earn-out!
The MD of Eddisons says “Kirkby Diamond is a great fit with Eddisons, culturally and strategically, and I look forward to taking forward the growth opportunities that the deal presents."
Ric Traynor says:
"Kirkby Diamond has excellent relationships with a broad range of clients and a strong track record of growth and we very much look forward to working with them as part of the group. The acquisition is in line with our strategy to develop our property advisory and transactional services division by enhancing and broadening our service offerings and geographical coverage. It takes the division to an annualised revenue run rate in excess of £50m derived from a wide range of property services and nationwide coverage."
Graham’s view
I’ve always had a lot of respect for Begbies, and I’ve found it interesting as a hedge against economic weakness (due to its restructuring/insolvency services).
However, it has expanded and diversified over the years, so it’s less of a pure-play on economic difficulties now than it was before. Which is perhaps not a bad thing, for investors who prefer a smoother performance.
As noted by Roland previously, the use of its own shares has caused gradual dilution:
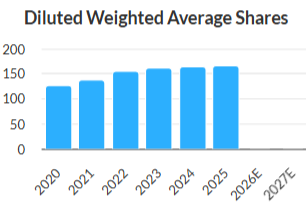
But the company has also been delivering the profits to justify its strategy:
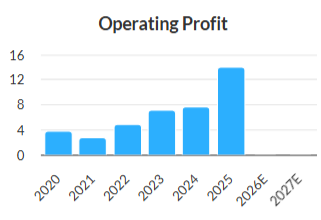
From a chart perspective, these shares first hit 108p in March 2020. They have taken a long time to grow into this valuation:
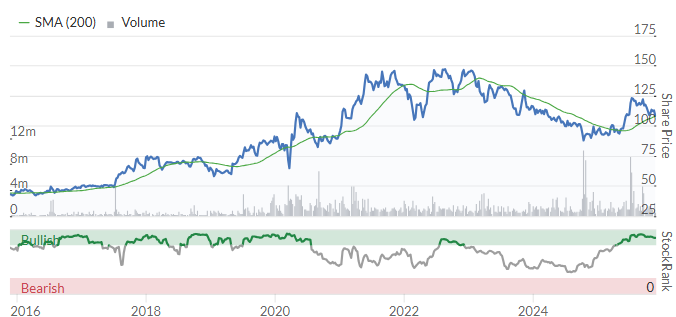
I’ve talked about the major factors at play here many times, as have Mark and Roland. See Dec 2024 for the last time I went over them. At the time, I said that a PER of 10x made sense for a large professional services business like this.
Today’s valuation:
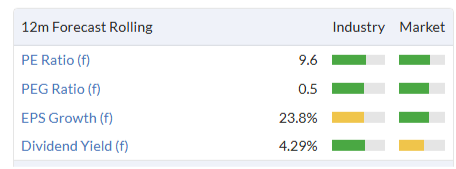
Estimates: Equity Development are forecasting adjusted EPS of 10.8p in FY April 2026, and then 11.5p in FY April 2027.
So the market is very much sticking to a 10x P/E ratio (10.8p EPS forecast vs. 108p current share price).
I think this could offer some nice upside if the company continues to perform as expected.
Is it a quality compounder? Perhaps not in the traditional sense, though I’m sure management would point to their successful M&A strategy as evidence that it is.
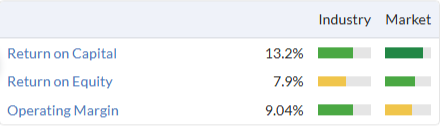
I have noticed that their quality metrics have improved since last year, and I think they could improve further depending on the heaviness of the adjustments to this year’s results.
These Stockopedia quality metrics are based on the unadjusted figures, so the adjusted figures would be even better:
And the StockRank has risen to an impressive 86:
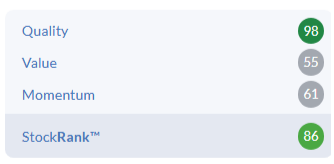
Putting it all together, I think I’ve seen just enough to raise my stance on this to AMBER/GREEN. It's still trading around the level that I considered to be fair value, but I trust the M&A strategy to keep delivering. So I think an extra dose of optimism is justified.
Roland's Section
Cake Box Holdings (LON:CBOX)
Down 1.4% to 207p (£91m) - Half Year Results - Roland - AMBER
(At the time of publication, Roland has a long position in CBOX.)
Today’s results from egg-free cake specialist Cake Box appear to be something of a mixed bag. The market reception has also been uncertain. I’ve been digging through the accounts and have found a few points I think are worth highlighting.
HY26 results summary
Let’s start at the top with a look at the headline figures. These accounts cover the half year to 28 September 2025:
Group revenue up 53.5% to £28.8m
-> Cake Box sales up 18.9% to £22.3m
-> Initial contribution from Ambala acquisition of £6.5m
Pre-tax profit down 7.4% to £2.6m
Underlying EPS down 11.5% to 4.58p per share
Interim dividend +5.9% to 3.6p per share
Revenue & sales: I think progress here looks broadly positive. At Cake Box, like-for-like sales rose by 6.3% (HY25: 2.0%), suggesting above-inflation sales growth in the seasonally weaker first half.
Total franchise sales rose by 14.6% to £47.6m while franchisee online sales rose by 25.9% to £11.3m (remember these are franchise sales, from which Cake Box receives a share).
The gap between LFL growth and total growth was bridged by 11 new store openings (9 Cake Box, 2 Ambala), taking the total to 284 at 28 September 2025.
Marketing efforts also seem to be bearing fruit. Traffic to the company’s website rose by 18% to 2.6m for the half year, while its email and SMS databases grew by around one third to 990k and 390k respectively.
Profitability & Leverage: the picture here looks a little more mixed to me.
While revenue rose by 53.5%, the accounts show a much larger 73.6% increase in overheads, to £12.6m.
As a result, H1 operating margin fell to 11.5% (HY25: 15.0%).
My hope is that stronger sales in the seasonally-important H2 will offset this increase in costs, so that the annualised impact is lower. But it’s certainly something I’ll be watching – the initial impact of the acquisition of Ambala appears to have been dilutive to margins.
Dropping down to pre-tax profit reveals another headwind. The company borrowed significantly to fund the acquisition of Amabala and is now paying hefty levels of interest. Finance expenses in H1 were £729k, up from £130k in the prior year.
As a result of this and the reduction in operating margin, Cake Box’s pre-tax profit fell by 7.4% in H1, despite a 50%+ increase in sales! Not ideal.
Net debt of £11.6m (excluding leases) does not look unmanageable to me, in itself. But this is an increase from the £9.0m reported at the end of March, despite the Ambala acquisition falling into the prior year.
Looking ahead, my feeling is that deleveraging might be quite slow as the company plans to spend £5m over the next three years on the construction of a new warehouse.
Current leverage works out at around 1.2x adjusted EBITDA, so doesn’t look too high on this measure.
Using my preferred comparison with net profit gives a multiple of around 3x – that’s also within my comfort zone, but I wouldn’t really want to see it much higher.
Accounting errors!
Scrolling down to the footnotes revealed some accounting restatements that have had the unfortunate effect of reducing last year’s reported profits.
These corrections were prompted by errors the company has discovered in its accounting for the acquisition of Ambala:
£270k of fees associated with the acquisition were capitalised into goodwill when they should have been expensed;
A £157k liability relating to deferred consideration should have been released in the FY25 results but was not;
A £506k corporation tax refund was recognised in the accounts, but the company is obliged to pass this amount to the sellers so should also have recorded a corresponding liability. The impact of correcting this is that FY25 reported pre-tax profit has been restated at £5.88m (previously £6.15m).
In terms of impact and severity, none of this is a disaster. But it seems a bit sloppy and I think it’s also disappointing that these errors were overlooked by Cake Box’s auditor at the end of last year.
Checking back to June, I see that the FY25 results were delayed due to an audit requirement for more time to cover the acquisition of Ambala – but they still missed some errors.
This is not the first time Cake Box has suffered accounting errors, albeit the 2022 events were under a previous CFO and different auditor.
Outlook
Looking ahead, the momentum of the first half has continued into the second half of the year and we are on track to deliver full year performance in line with our expectations despite the consumer environment remaining challenging.
Today’s in line outlook statement implies a significant H2 weighting to results. The company’s H2 adjusted EPS of 4.6p still leaves nearly 10p per share to be earned in H2 to meet consensus forecasts of 14.3p.
There’s been a debate on how credible this is in the comments this morning. I can understand why investors might be sceptical – a big weighting to the second half of the year is often a sign of a possible miss.
In this case, it’s worth noting that Cake Box’s business has always had a significant H2 weighting for obvious seasonal reasons.
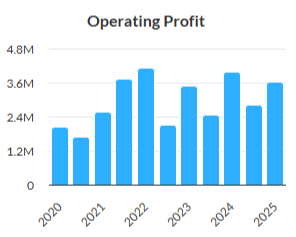
Crunching the numbers shows me that the H2 weighting last year was around 60%.
Applying the same calculations to this year suggests an implied H2 weighting of around 68%.
That’s a big increase, but my impression from today’s results is that the acquisition of Asian confectionary business Ambala may actually have increased the seasonality of this business. Management say that the Eid and Diwali celebrations – both in H2 – have always been a significant driver of profitability for Ambala.
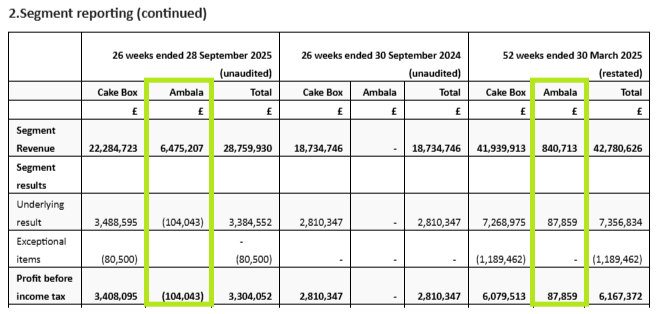
Checking today’s segmental results shows that Ambala was loss-making in H1, but generated a pre-tax profit margin of 10.5% during the partial H2 period trading post-acquisition last year:
Management had a sensible opportunity to introduce some flexibility into full-year guidance today, but they chose not to. Make of that what you will.
Personally, I think there’s an increased level of uncertainty, but I can see a plausible case for Cake Box still making its full-year forecasts based on today’s guidance.
Estimates
House broker Shore Capital has taken its cue from Cake Box’s management and left its forecasts completely unchanged today:
FY26E adj EPS: 14.3p
FY27E adj EPS: 16.7p
FY28E adj EPS: 19.2p
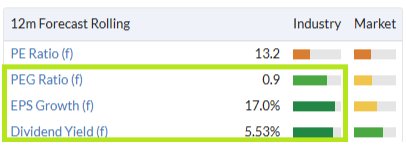
These estimates suggest earnings growth could outperform the wider sector, potentially justifying a low-teens earnings multiple:
Roland’s view
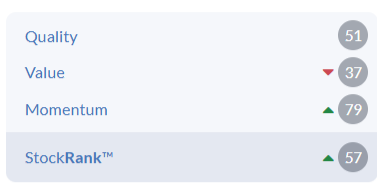
I hate to sit on the fence, but I think I’m going to mirror the StockRanks and cut my view by one notch to neutral after today’s half-year results.
I can see both opportunity and risk here, but on balance I am not sure I’d want to pay all that much more for Cake Box shares without some evidence that profitability and growth remain on track following the acquisition of Ambala. AMBER
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

58 comments
After my earlier post, I have just seen a very nasty sting in the tail: "Venture Capital Schemes:
Reduce the VCT scheme Income Tax relief from 6 April 2026" - up front tax relief dropped from 30% to 20% which will kill listed VCT investment dead as its not really that attractive at 20% tax relief. The table looks wrong as the tax effect is included in 27/28. So, Rachel will stop investment in start-up companies through VCTs....not exactly pro-growth! VCTs attracted c£1bn of investment last year.
https://citywire.com/wealth-ma...
Hi Guys,
I was particularly looking forward to your assumptions on mobico today, and a few others that are blank.
Appreciate you were copying the budget updated from the news, but will there be a catch up?
Cheers
Hey Chris, yes I'll catch up on Mobico tomorrow. Anything else you'd like covered in particular?
That would be awesome Graham, thank you for replying...
Business Rate taxes are going down, for properties less than £500k ratable value, which apparently is 99% of all high street premises? But only for Retail, Hospitality, Leisure businesses.
Could be good for those with large estates - maybe like Works co uk (LON:WRKS) and Card Factory (LON:CARD)
Online businesses with large warehouses will have to pay more....
Rank (LON:RNK) is up quite a bit today, but I don't know if it should.... it generates a fair amount of its profit from its online gambling app in the UK, so will be hit.
Albeit it will have the benefit from Bingo (abolishment of the 10% tax). And offline casinos are not affected at all - and will probably see more punters go in. Going forwards, online gambling is going to have worse odds for customers, given the high tax. So if you're a savvy gambler, you will go to the high street casinos or betting shops.
(I hold in the Boon Fund)
Thanks for the summary Graham. In my view, it was undoutedly a poor budget delivered by a weak government. Delivery has been absolutely shambolic from the endless leaks, Rachel Reeves scary talk on tax rises and the OBR release fiasco. As an investor though it was much better than expected, so I'm relieved. I think that the most ridiculous proposal was taxing interest at 2% higher than the standard rate from 2027/28. That was incredibly stupid...why is this merited - is saving bad?
Its because too many in this country lives payslip to payslip (or on benefits payment), so the "voter base" for Labour probably have no savings, dividends, or property to be worried about this tax....
I thought it was disappointing that there was not more done for the housing sector. Some talk about further investment in planning and some commitments to infrastructure spend / improvements. But these seem to small to move the dial, i.e. there was no catalyst that I could see to get this situation improving quickly. Looks like this market may remain subdued for another year. I had bought some housebuilder stocks on the hope for some budget assistance, will have to re-consider, not feeling very confident after todays budget.
"General betting duty, paid on other forms of sports betting, will remain at 15 per cent in betting shops - but from April 2027 will rise from 15 to 25 per cent online. Remote gaming duty, paid on online casino betting, will rise from 21 to 40 per cent from April 2026."
But IG group (LON:IGG) up 10% this afternoon. Have they escaped this?
I think it is due to the ISA rules change, which if I understand correctly means you still have a £20k allowance but £8k must be spent on stocks / shares (effective from April 2027). So this could be the reason for the price jump.
Doesn't really make sense as ISAs make up only a smallish part of their business - they are mainly a spread betting firm. AJ Bell have much more exposure to ISAs yet they were only up 3%. Maybe it's relief that they weren't hit by a new gambling tax, although CMC and PLUS only saw small rises so a bit of a mystery.
Yep that's a good point. Can't see any reason specific to them, so IG 10% up looks a bit odd when looking at the other listed companies. I hold and did review my position earlier today. I think it still looks reasonably valued at the moment, especially with the very strong balance sheet. Maybe there is a big buyer who was waiting for the budget to pass without incident. Looks like volume has picked up a bit in the last week (just looking at the stocko chart).
IG group (LON:IGG)
Maybe it's relief that they weren't hit by a new gambling tax
that would be my guess - specifically any "per transaction" tax is potentially much more damaging to a high volume transaction business model than increasing tax on profits.
Spreasbets should be excluded from this as most people loose money it would drive tax rev down due to CGT offset.
It's not talking about taxing the customer, this is about taxing the operator on their profits. Most spread betting is already exempt from CGT and has never been allowed for offsetting losses.
I think what's interesting is whether IG (and other similar companies) will at some point be regarded as being within the gaming sector. I think at the moment they are considered within a financial sector that includes financial instruments / banks / advisors etc. This should mean they are not subject to the higher tax rate; and I doubt this will change anytime soon. Not 100% but I think this is how they're classed / grouped.
Apparently financial spread bets are subject to a general betting duty of 3% of the firm's gross betting profit. This is unchanged in the 2025 budget. I guess IG group (LON:IGG) got off lightly because the rest of the betting industry was clobbered.
No mention of any meaningful attempt to cut the excessive Government spending that I can see.
Tbh it sounded like the opposite. Continued attempts to position spending as "investment".
Good to see public sector pensions untouched.....
were you hoping they would be increased?
"13.19: Salary sacrifice: from 2029, there will be a £2,000 cap on salary sacrifices into a pension, with contributions above that being taxed in the normal way." - I think this applies to NI only? So higher tax payers pays only 2% while the employer pays 15%?
I've cut the confusing part out of that sentence, thanks Tring Boy!
I think the 2029 date is extremely clever - if that can be plugged into making the future numbers looking more sensible - but there is no immediate hit - then it kind of gives us the best of both worlds - some breathing space before the actual bad news hits - but future stuff look better.
Can we perhaps infer that labour have conceded they will not be in power from 2029 ?- so best time to make the worst stuff hit is exactly when they are leaving the room. They do give themselves a backup "story" if in 2029 the economy is going better or thgey can do some decent jackanory stuff - then they can say there is now no need for all these extra tax hikes as things arent as bad as they were in 2025.
I think this applies to NI only? So higher tax payers pays only 2% while the employer pays 15%?
at face value yes - but practicably its probably the end of salary sacrafice for many full stop above 2k!
what you need to remember though is that most of these schemes only exist due to the employer saving money too. the employer doesnt need the hassle of people wanting to make oversized contributions they might want to tinker with every 5 minutes.
So if they have the hassle of monitoring and doing extra calcs and they have to pay 15% NI for the priviledge of continuing to offer that they will all simply limit ss to 2k per year perhaps - other than the odd company that needs to retain the high earning peeps. Note its the same 15% as a salary but its most deffo a chow employers dont need or want setting up stuff like that - unless they see the benefit of actively assisting employees ref tax.
I do wander though if having lower base and higher employers pension contributions could sidestep these new rules - it might be a murky line between salary sacrafice and employers pesnion contributions at highe rlevels not linked to salary sacrafice?
I concur with this view as a business owner, we’ll likely scrap it.
Agree. As you say, the way around looks like being to reduce employee's gross pay (with their permission) and for the employer to make higher contributions directly into their pension.
Some large companies already do this for higher paid employees. The employee's salary package consists of a base salary and a pension contribution made directly into their pension (which doesn't attract NI I think). This is typically 15-20% of base salary. The employee can choose to take the pension contribution as additional salary but will of course pay NI & Income Tax on the extra salary. It is surprising (or is it given the governments incompetence!) that they haven't addressed this work around unless of course it is hidden in the small print to come out over the next few days.
True, it applies to NIC. The largest impact is on NI - employers' NI at 15%.
But it also has an impact on tax thresholds. With salary sacrifice, the sacrificed salary is taken off your gross; if not sacrificed, it is included in the gross (and so can tip you into the higher tax bracket) and you then reclaim it. This can produce a timing difference and also push you into the 80 per cent tax bracket on the first £500 earned above the basic rate limit. It will also have an impact on pay above £100,000 (the 60% tax bracket) and also those claiming child benefit above a certain salary level.
But it also has an impact on tax thresholds.
You have lost me a bit here pj8
Would you agree that these changes only affect NI and not tax ? see below
would you also agree that compared to other methods of getting same gross amount into your pension pot then thats nearly always tax neutral (ras might benefit those on uber low salaries and there can be differences ref tapered annual allowances)
- ie my stance is that salary sacrafice isnt more tax efficient (ref tax only) than bog standard relief at source . One should avoid the 60% tax issue whether SS or ras. If one has 102k basic pay and one gets 2k into pension pot
From April 2029, only the first £2,000 of employee pension contributions through salary sacrifice each year will be exempt from NICs. Contributions through salary sacrifice, like all pension contributions, will still be exempt from Income Tax (subject to the usual limits).
Employers and employees can still make contributions above £2,000 through salary sacrifice arrangements. However, employee contributions above this amount will be subject to employer and employee NICs like other employee workplace pension contributions.
80% already for landlords with mortgage due to 20% tax credit, rather than full expensing.
What's that worth after 4 years with 3+% inflation?
Anyone know whether CGT rates or allowances have changed?
No mention of that in her speech. What no one has picked up on yet in the media is the killing of some energy levies for domestic users. No detail in the speech, but she said it amounts to £150 off the average total bill. If so, that is about 8.5%, should be noticeable to all and will lead directly to an inflation reduction,
No budget news yet on the North Sea.
Thus far, no significant market reaction to the budget. A small increase in bond yields but also a small rise in £ sterling.... devil is always in the detail but so far so good. I will withhold a qualitative view until more is written about various policies ...
Bond market has improved ... rising and therefore yields slightly lower... a more positive vote. £ Sterling remains slightly up. No shocks so far.
OBR leak. The ineptitude of our public service officials is breathtaking. Gold plated pensions and seemingly never held to account by being sacked. I despair.
OBR leak
accident or someone having a jiraffe?
Being reported that the Office for Budget Responsibility has leaked the Budget in error.
Much of the content had been spun in advance - but a bit of a shambles if correct.
EDIT : the OBR has "apologised"
One key point for investors - lower growth forecasted.
The document has been removed from the OBR's website. The document can be found here: https://www.scribd.com/documen...
Roland and Graham, I like the addition of the direction of travel indicators next to your colour coding in the table (up, down or =) - nice touch.
Cheers Tim! We thought it was a fun little addition, and helpful to show the direction of travel.
Any thoughts on the management succession at Judges Scientific (LON:JDG) ? David Cicurel, the founder and biggest shareholder who has run the business for over 20 years, turns 77 next May. So no surprise that he is finally stepping back to be non-executive chairman. Tim Prestidge, who joined the group in February 2023 from Halma, takes over as chief executive. Given his background, ex-Halma and Renishaw, he looks a sensible choice on paper.
Perhaps Judges Scientific (market cap £309m) can eventually grow into another Halma (market cap £13.6bn). Judges, which has seen its share price collapse from £118 in May 2024 to under £50, currently trades on just over 15 times earnings (according to Stockopedia), whereas Halma is on over 30 times.
However, Cicurel’s comment that “choosing the perfect timing is never easy, particularly given the present trading environment” suggests that Judges has some way to go before it regains its former glamour rating.
Judges Scientific (LON:JDG)
Perhaps Judges Scientific (market cap £309m) can eventually grow into another Halma (market cap £13.6bn).
is it possible or probable that as they get bigger - there simply arent the compelling amount of "easy" acquisitions where its great exit route for sellers plus great purchase price for Judges.
I dont follow the kinds of deals they do too closely - but i suspect it may be harder to add easy obvious value as they grow if they start or are buying out larger established business compared to "founder sellers" who may have built business up and be using sale partly as a means to retire?
I know whatever they did their secret sauce used to work back in the day - but is that still as bulletproof as it was? and was that much easy due to their much smaller nature and each deal materially enhancing earns as % of the whole.
i note their net profit in 2019 was higher than 2024 - to be fair to them 2025 is showing decent jump so not sure of the overall trend is still decent but lumpy?
Klement on Investing this morning has a very interesting article on the links between tax, government spending and GDP and basically advising us
“don’t buy or sell stocks because you think taxes are going to go up or down.”
https://klementoninvesting.sub...
Strix (LON:KETL)
As usual "broadly in line" = down a bit. Equity Dev. reduces adj. dil. eps for the 15m to 3/26 from 6.0 to 5.4p. Zeus reduces from and to exactly the same figures and reduces those to 3/27 and 3/28 more drastically to 5.7 and 6.3p.
In terms of valuation Zeus says "At 6.2x reduced FY27 earnings and 4.4x EV/EBITDA, the absolute valuation of Strix prior to today was discounting a worst-case scenario" while Eq. Dev. has fair value "based on a comparative peer group model" of "89p / share (down from 95p) to reflect the reduction in estimates but remains at a significant premium to the current share price".
Probably the more significant item is that CEO Mark Bartlett, who has presided over a decline in SP from 380 at the end of Aug. 21 to 34.3/34.95 15 mins. ago, has fallen on his sword. Much will depend on who is appointed to the post.
When the Stocko team does the budget analysis, I'd be interested to know if the banks get bashed in any way.
Just to put a marker in the sand ..... UK Bond rates are .......
2Y 3.78% 5Y 3.95% 10Y 4.52% 20Y 5.2% 30Y 5.35% ..... UK 10Y are +50bp US rates and +100bp France ....more other Europe. The challenge today is to achieve a convincing growth and finance plan with only a tolerable move in these numbers.......adverse moves of 10bp + are fairly aggressive but not unheard of..... £ sterling is often also a better gauge of market reaction ... if anything it looks a little firmer at the moment suggesting all is ok ( from financial markets perspective - not a political view).
Helpful - thank you
cheers RDHOWARTH - fingers crossed and tin helmets to the ready today.
I'm off to hide behind the sofa now.....
Goodness me, iomart (LON:IOM) is a shocker of a company, isn't it? I was seduced into buying it twice in the distant past, lost money both times and sold out. Every time they report they seem to lose more customers due to 'churn' and a once solid, profit-making and cash generating business paying a good dividend is now loss-making, cash-consuming and heavily indebted. Amazingly they have persuaded investors to stump up for a series of unsuccessful acquisitions along the way, none of which has changed their fortunes. Good luck to the new CEO - you will need it!
Cake Box Holdings (LON:CBOX) will be hit today, profit and earnings down H1. Blaming interest costs of acquisition. Hmm. Going to need around 10p earnings H2 to hit forecast. Tough
Cake Box Holdings (LON:CBOX)
Going to need around 10p earnings H2 to hit forecast. Tough
It might be tough and lining up later profit warning but they have explicitly stated they are fully on track. Not even a mention of broadly or anything - today is perfect opportunity for them to have slighly moderated expectations and they didnt.
Outlook: Trading remains on track to deliver another year of growth in line with market expectations
· Trading remains on track to deliver another year of growth in line with market expectations despite the challenging consumer environment
I hold no opinion either way as to whether they will hit targets.
Morning JohnDoe, we'll certainly be taking a look at Cake Box today!
Roland
I'm surprised hasn't dropped
Hi Roland - how did you generate the Operating bar chart for Cake Box Holdings (LON:CBOX) in the write up this morning. I've had a quick look at the stock report but can't see it.
Thanks,
Imran
Hi Imran,
You can find this on the Accounts tab, under Income Statement:
Roland