Daily Stock Market Report (Wed 2nd September 2026) - MOTR, RGG, AEP, CLX, CRN

Two major market movements to let you know about this morning.
Firstly, oil marched higher and is now over $95, after rising about $4 since yesterday.
Oil had been making it through the Strait of Hormuz, in modest quantities, as the US focused more on economic aggression against Iran, rather than outright military action.
But the US has now hit Iranian “air defense sites, radar systems, maritime assets and facilities, mine laying capabilities, and communications sites”, along with two tankers, and Iran has made counter-attacks against US bases.
With the oil price rising, the markets are looking at the potential for interest rate hikes - and this leads me to the second major overnight market movement: interest rates.
Bond yields have risen further for both the US and the UK. The US T-Note is yielding 4.8%, while the UK’s 10-Year Gilt is at 5.2%, about 100 basis points higher than its low earlier this year:
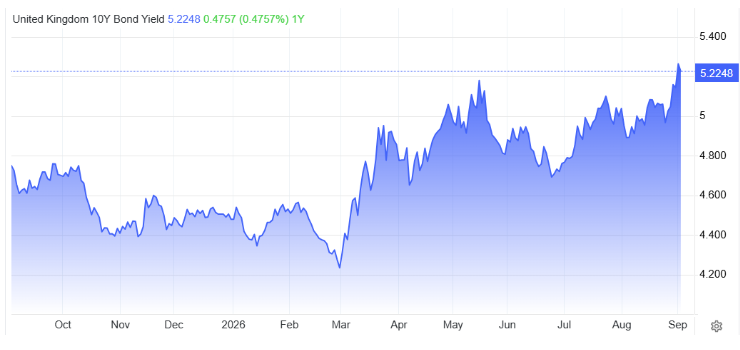
Source: tradingeconomics.com
An article on Bloomberg last night suggested that “together with higher inflation, higher borrowing costs will knock about £12 billion off the government’s £23.6 billion buffer against its fiscal rules”.
Interesting times ahead for the new Chancellor John Healey.
Overnight market movements:
The FTSE is down 0.4% at 10,750
S&P 500 is down 0.1% at 7,625
Brent crude (November) is up 0.9% at $95.50/bbl
Gold is down 0.2% at $4,320/oz
Bitcoin is up 0.3% at $77,700
Leaving it there for today, cheers! Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
BP (LON:BP.). (£85bn | SR99) | Tyler was already a NED and has been interim Chair since May 2026. His appointment is confirmed from today. | ||
Halma (LON:HLMA) (£13bn | SR56) | Acquired water quality monitoring and analysis specialist Pyxis for up to $200m (c.£148m), including earn-outs. Pyxis was founded in 2013 and is expected to generate c.$39m of revenue over the year to 31 March 2027. | ||
| Cairn Homes (LON:CRN) (£1.41bn | SR78) | Interim Results | H1 revenue +60% to €455.5m with operating profit +75% to €74.8m and adj EPS +82% to 9.3c. Forward order book +23% to €1.89bn (5,020 units). Outlook: now expect revenue and operating profit at top end of guidance (c.€1.08bn and €185m, respectively) with ROE of c.17.0% (prev. c.16.5%). | GREEN = (Graham)
I don’t see any need to change stance today, especially considering the improved full-year guidance. Cairn is generating sector-leading ROE and its prospects continue to improve, as the order book continues to grow. The danger? This is economically sensitive, of course, so investors should bear that in mind. I do think that Cairn buying back its own shares is a little aggressive at current levels. For housebuilders, I prefer when buybacks take place at a discount to NAV, whereas Cairn trades at a high premium. But overall, I remain a big fan of the story here and as such I remain fully GREEN. |
AEP Plantations (LON:AEP) (£771m | SR94) | H1 revenue +8.3% to $249.7m with pre-tax profit +5.1% to $65.8m, including a $9.1m non-recurring gain. Average ex-mill CPO price was -1.2% at $853/mt and palm kernel price was +7.4% at $793/mt. Outlook: confident of achieving market expectations for the full year. | AMBER = (Roland) Today’s half-year results show H1 profits were held back by delayed cropping and higher overheads. However, the company’s guidance for a stronger H2 seems reasonable enough to me and I’m happy to view these results as being in line. While the FY26E P/E of 8 may seem cheap, it’s worth noting this is based on elevated CPO and PK prices. On a more normalised view of pricing, I’d argue the stock has re-rated and that further upside is dependent on commodity pricing. For this reason, I’m maintaining our previous neutral view today. | |
Avon Technologies (LON:AVON) (£545m | SR35) | Team Wendy Ceradyne has received an order worth $20.3m from the US DLA under the Feb 2022 framework. This order fulfils the maximum volume authorised for the current year. | ||
Ecora Royalties (LON:ECOR) (£419m | SR64) | Total portfolio contribution (underlying revenue) +75% to $31.3m, with pre-tax profit of $24.3m (H1 25: loss of $10.9m) and free cash flow of $12.1m. Outlook: expect critical minerals portfolio to continue volume growth in H2, benefiting from commodity price tailwinds. | ||
Custodian Property Income Reit (LON:CREI) (£397m | SR65) | LFL rental values +1% in Q1, driven by +1.6% in the industrial sector. 1.5p dividend approved for the quarter, fully covered by EPRA earnings per share and in line with full-year target of 6p per share. | ||
TT electronics (LON:TTG) (£241m | SR66) | H1 revenue -4.1% to £228.1m with adjusted pre-tax profit +85.9% to £15.8m. Adjusted EPS +200% to 5.7p per share. Outlook: the Board expects 2026 adjusted operating profit to be ahead of current market expectations (previous consensus: £35.0m). | (will cover this by the end of the week) | |
Rentguarantor Holdings (LON:RGG) (£127m | SR39) | Jan-Aug revenue +472% to £8.45m, with adj net profit of £2.87m (H1 25: £(392)k. Number of applications +174% YoY, contracts +311% YoY. Outlook: Board now expects 2026 revenue and adjusted net profit to be “materially ahead” of expectations (previously: revenue £9.1-10m and adj net profit £1.2-2.4m). | GREEN ↑ (Graham) | |
Motorpoint (LON:MOTR) (£109m | SR48) | Trading volumes stronger than expected with “favourable” supply dynamics. Outlook: now expect pre-tax profit for y/e 31 March 2027 to be £9.8m to £10.8m, ahead of market consensus (previously: £9.1m to £10.0m). Shore Capital upgrades FY27E adj EPS to 9.3p (prev. 9.0p) | AMBER ↑ (Roland) A strong update which sounds confident on both demand and supply. One factor that’s not mentioned today is the impact of interest rates, which prompted a profit warning in April. While I’m a fan of this well-run business, I think it’s worth remembering how sensitive its profits are to small changes in pricing, costs or interest rates. I think there could be the potential for further gains here, but I don’t think the business can escape its exposure to macro factors. With the shares already trading on a mid-teens P/E. I’m moving my view up by one notch to be neutral today. | |
Ten Lifestyle (LON:TENG) (£92m | SR74) | The change of the Company's name from Ten Lifestyle Group plc to Ten Technologies Group plc has now been registered at Companies House and is effective. Ticker, ISIN, etc. remain unchanged. | ||
Aminex (LON:AEX) (£70m | SR9) | At a meeting convened by the Tanzanian Ministry of Energy, the Government did not approve a proposal by the operator to extend and delay the project timetable and instead confirmed a revised implementation schedule to which all parties agreed. The Ntorya to Madimba pipeline will be completed in time to receive first gas from the Ntorya field in December 2026. | ||
Calnex Solutions (LON:CLX) (£52m | SR59) | Trading in the year to date is in line with market expectations. “…the Board remains confident in the Group's prospects for FY27 and continues to expect the targeted investment being made this year to support accelerated growth in FY28.” | AMBER = (Roland) | |
Corero Network Security (LON:CNS) (£37m | SR18) | Significant new contract with a leading UK-based fixed and mobile telecommunications and connectivity provider. Alongside one of its strategic alliance partners, Corero has secured a 5-year contract for a total contract value of $3.4 million. Also wins a 3-year contract with a total contract value of $0.5 million. | GN note: is this material news? Annual revenues at CNS are c. $30m. | |
Bezant Resources (LON:BZT) (£34m | SR24) | Hartree, Bezant's financing and offtake partner, will participate alongside Bezant in the financing of the accelerated payment arrangements related to the ownership of the NLZM Processing Plant. | ||
Kendrick Resources (LON:KEN) (£29m | SR17) | “Certified laboratory assays have now been received for three drill holes (TKDD002-4), each returning highly impressive LREO grades over significant widths and further reinforcing the scale, continuity and high-grade potential of the Teufelskuppe mineralised system.” | ||
Rome Resources (LON:RMR) (£22m | SR19) | Updated mineral resource estimate for Kalayi tin deposit at the Bisie North Project in the Democratic Republic of Congo. A 45% increase in contained tin, a 32% increase in resource tonnage and a 10% increase in average grade. | ||
Kazera Global (LON:KZG) (£17m | SR18) | The South African Department of Mineral Resources and Energy has formally approved the application by the Company's wholly owned subsidiary, Whale Head Minerals, for a Mining Right over Sea Concession 2A located in the Northern Cape, South Africa. | ||
Kelso group (LON:KLSO) (£16m | SR43) | 30th June: NAV per share 2.9p, up 23% for the period. Net assets £13.2m. Update 31st August: NAV per share 3.3p. Net assets £15.2m. Gross investments £23m using 33% gearing. Ten investments in established companies in UK small and mid caps. | ||
Orcadian Energy (LON:ORCA) (£14m | SR9) | Has entered into an agreement with an American developer of offshore data centre infrastructure. The Agreement establishes a 90-day process to enable due diligence, commercial validation and negotiation of a definitive Earlham and Orwell energy-to-compute transaction. |
Graham's Section
Rentguarantor Holdings (LON:RGG)
Up 15$ at 90.25p (£146m) - Trading Update - Graham - GREEN ↑
This one has been on a tear, more than trebling in a few months:
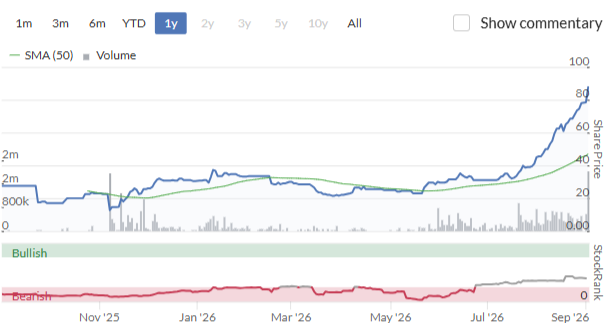
I’ve been moderately positive on it, calling it one of the most exciting growth stories I cover in this report, but also describing the valuation as “bonkers” if you are only looking at the current numbers.
I used that word “bonkers” at a market cap of £83m, only last month.
Today we are at £146m.
But this morning we’ve had an outstanding trading update to justify the ongoing share price gains, covering the eight months year to date.
There’s a nearly 500% increase in revenues, and the company can now report positive adjusted EBITDA and adjusted net profit:
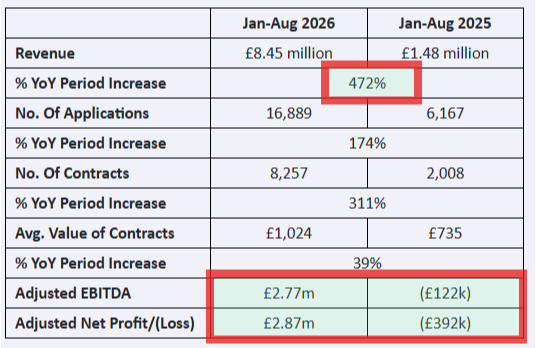
At the interim results to June, RGG reported a year-on-year revenue increase of 250% (to £3.4m).
So in the last two months alone, unless I’m mistaken, there has been revenue of over £5m.
RGG confirms that August monthly revenue was £3.17m.
So the company has already evolved from a startup into what we might call a medium-sized, profitable business.
Note the increase both in the number of contracts and the average value of contracts (up 39%) to £1,024:
Contributing to this growth is the number of higher value tenants now applying to have a professional guarantor in lieu of paying a number of months' rent up front, following the Renters' Rights Act.
As I’ve remarked before, the growth at RGG does have a legitimate explanation in the form of the RRA, which creates greater risk for landlords and therefore a stronger focus on the guarantor.
Cash has improved to £7.5m. The company repeats what it said at the interim results: that it will consider its dividend policy at the full-year results.
Outlook: couldn’t be any stronger.
The Board believes that the combination of accelerating customer demand and expanding commercial partnerships will result in revenue for the financial year ending 31 December 2026 (FY 2026) being materially above market expectations. The Board also considers that the Group's increasing operational scalability and improving profitability will lead to the Group's adjusted EBITDA and adjusted net profit for FY2026 being materially ahead of the market expectations range for the period.
It is now the Board's target for the Group to deliver revenues in excess of £14 million and a net profit in excess of £4 million in 2026. The Board has also increased its target expectations for 2027, and is increasingly confident that its target of 100,000 contracts by 2029 is becoming more of a reality at current growth rates..
Prior market expectations are helpfully provided: 2026 revenues of £9.1m to £10m, adjusted EBITDA of £1.6m to £2.7m, and adjusted net profit of £1.2m to £2.4m.
These expectations have been blown out of the water: revenues are now expected to be about 50% higher than the midpoint of the prior range (£14m+ vs. £9.5m), and net profit guidance is now expected to be double the midpoint of the prior range (£4m+ vs. £1.8m).
Cavendish forecasts: these are some of the best upgrades I’ve ever seen.
Revenue: 2026 £14m (previously £9.5m), 2027 £28.3m (previously £20.7m), 2028 £43.8m (previously £33.1m)
PBT: 2026 £3.7m (previously £1.2m), 2027 £8.2m (previously £4.6m), 2028 £13.2m (previously £8.5m).
If anything, the upgrade for 2026 strikes me as being possibly a little undercooked, as the company itself has said it expects net profit of £4m. If that’s true, then a PBT forecast of £3.7m this year is conservative.
But what’s really exciting is the potential for profits to keep compounding from there.
Graham’s view
I don’t think I have much choice but to turn positive on this today:
It has crossed over into profitability, and is already producing material profits.
Huge upgrades to its financial forecasts for the next few years.
All of this growth is well-explained by the introduction of the Renters’ Rights Act.
On top of all that, the valuation at the current level is not even particularly demanding compared to EPS forecasts. If the 2028 Cavendish EPS forecast of 5.9p turns out to be accurate, for example, the shares are currently trading at just 15x that forecast.
Given the growth that the company’s achieving, the numbers for 2026 alone don’t seem all that relevant, and it seems right to value it on its potential a few years from now. Maybe I was bonkers for not turning GREEN on this sooner?
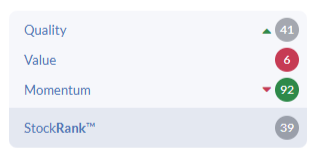
The StockRanks still don’t believe in it, by the way. Their analysis of Value is more backward-looking, so that makes sense:
Cairn Homes (LON:CRN)
Up 6% at 235.6p (£1.49bn) - 2026 Interim Results & €50 Million Share Buyback Programme - Graham - GREEN =
We already looked at the H1 trading update from this Irish housebuilder in July, when I maintained my positive view.
Let’s go straight to today’s full-year guidance, to see how it’s changed from July. We have small but pleasant upgrades, with the company effectively saying that its headed to achieve at the top end of the ranges previously given:
Revenue of c.€1.08 billion (previously €1.05 billion - €1.08 billion);
Operating profit of c.€185 million (previously c.€180 million - €185 million); and
ROE of c.17.0% (previously c.16.5%).
The company says that it expects to deliver 6,000 homes in the next two years (2026-2027), compared to 12,000 homes in its entire first decade. It was founded in 2014.
So clearly, the positive momentum is continuing. But let’s drill into these H1 numbers a little bit:
H1 revenue +60% to €455.5m
Average selling price +1.6% (i.e. volume is the main growth driver, not ASP)
Operating profit +75% to €74.8m
There’s large H2 weighting - operating profit in H1 is only 38% of full-year guidance - but I would expect the company to have excellent visibility over H2 performance. It knows at this stage which developments are finishing and ready for delivery.
Net debt has increased from €171m (Dec 2025) to €194.5m (June 2026), but it is still down considerably year-on-year. It was over €300m a year ago.
Given the strong profitability expected in H2, the company is going to buy back shares:
…the Group is well positioned for strong cash generation and profitable growth throughout the remainder of 2026 and into 2027. Reflecting this confidence, Cairn today announces a new €50 million share buyback programme, increases its interim dividend by 10% to 4.5 cent per share and upgrades FY26 ROE guidance to c.17.0%...
The company is already paying out about half of its annual profits in the form of dividends, but it seems to me that it can afford to make this buyback too. After-tax net profits are expected at c. €144m this year, so it’s possible to pay out half of this in dividends and still have more than €50m left over for buybacks.
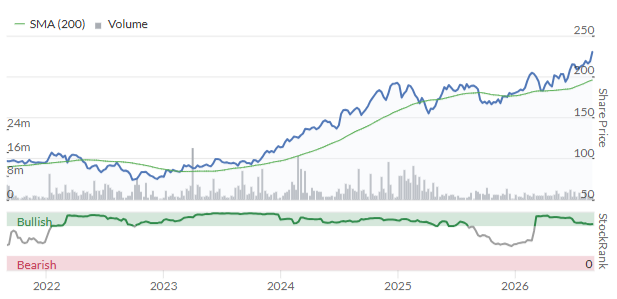
Cairn has form for buying back its shares, having done so from 2022 to 2024, but this buyback will be taking place at much higher levels: the share price is has more than doubled since 2022-2023:
Graham’s view
I don’t see any need to change stance today, especially considering the improved full-year guidance.
Cairn is generating sector-leading ROE and its prospects continue to improve. Here are the latest order book figures:
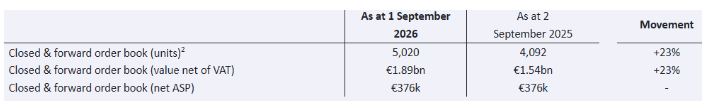
At the H1 trading update, the company said it had 4,800 homes with a value of €1.8 billion in its order book. So that figure has continued to increase in recent months (to 5,020 homes with value €1.89 billion).
The danger? This is economically sensitive, of course, so investors should bear that in mind. For what it’s worth, I don’t see what is going to upset the apple cart for Irish housebuilders: demand continues to exceed supply by a wide margin. So long as the Irish economy remains reasonably strong, there will be far more prospective first-time buyers than there are new homes being built.
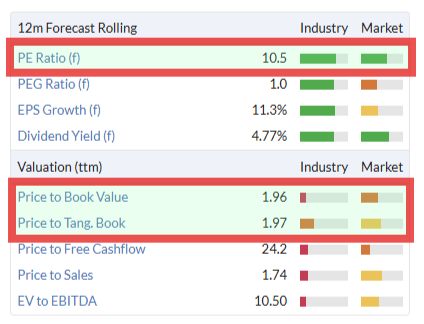
I do think that Cairn buying back its own shares is a little aggressive at current levels. For housebuilders, I prefer when buybacks take place at a discount to NAV, whereas Cairn trades at a high premium. Also, the PE multiple is about 10x, so I wouldn’t say that it’s obviously a bargain:
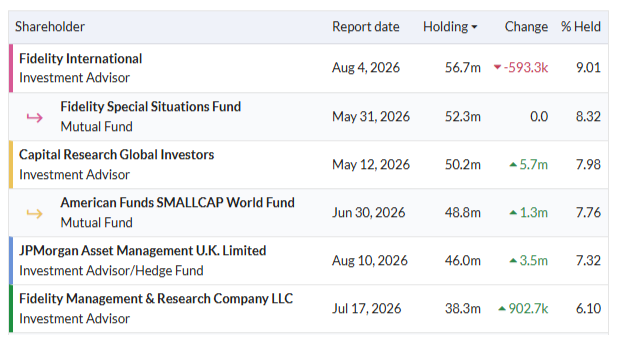
So I’m not a fan of the new buyback. This is a case where I’d prefer to see special dividends, letting shareholding decide what they wish to do with the proceeds. Dividends are probably not too inefficient from a tax point of view for Cairn’s institutional shareholders, who are very much blue-chip in nature:
Overall, I remain a big fan of the story here and as such I remain fully GREEN.
Roland's Section
Motorpoint (LON:MOTR)
Up 8.5% at 141p (£120m) - Trading Update - Roland - AMBER ↑
Today’s trading statement appears to be an unscheduled update issued solely to upgrade the used car supermarket’s financial guidance for the current year.
Management commentary is brief but positive:
Trading volumes have been stronger than anticipated, supported by our strategic initiatives, including accelerated investment in technology, data and AI, with margin improvements yielding higher profitability per unit. Supply dynamics remain favourable and we are pleased to announce a further store has been secured to open in Spring 2027.
Outlook & upgraded guidance: as a result of strong trading and “increased confidence in vehicle supply conditions” and successful technology upgrades, profits for the year ending 31 March 2027 are now expected to be ahead of market consensus:
New guidance: FY27 adjusted pre-tax profit to be £9.8m to £10.8m
Previous consensus estimates were from £9.1 to £10.0m
Taking the mid-point, this represents an 8% increase to pre-tax profit expectations.
Broker estimate: with thanks to house broker Shore Capital this morning, we also have updated earnings forecasts:
FY27E adj EPS: 9.3p (+3.3% vs 9.0p previously)
FY28E adj EPS: 12.1p (unch)
These estimates put Motorpoint on a FY27E P/E of 15, falling to a P/E of 12 in FY28.
Roland’s view
From an operational and customer perspective, I think this is a very well-run business with an attractive share of the UK used car market.
However, as an investment we need to remember that Motorpoint’s profits are extremely sensitive to small variations in used car supply costs, interest rates and pricing. With sales of c.£1.3bn, a 0.1% change to the group’s pre-tax profit margin can add c.10% to pre-tax profits.
This was apparent when I last wrote about the company in April. Despite a bullish-sounding 8% increase in sales volumes, Shore cut FY27 earnings EPS forecasts by around 30% to 7.8p to reflect the impact of higher interest rates.
The same broker is now forecasting FY27 earnings of 9.3p per share – a 19% increase in four months. Zooming out to look at the consensus view over the last 18 months shows that current forecasts are still well below the level seen this time last year:
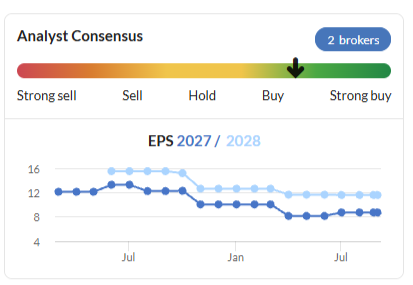
In today’s update, Motorpoint sounds very confident about vehicle supply conditions and positive about consumer demand. Interest rates aren’t mentioned, but could remain a wildcard – like many car dealerships, stock is financed through a specialist debt facility and the company also depends on commission income from the finance deals it sells to customers.
I don’t think it’s a coincidence that Motorpoint’s share price remains a long way below the levels seen during the zero interest rate era:
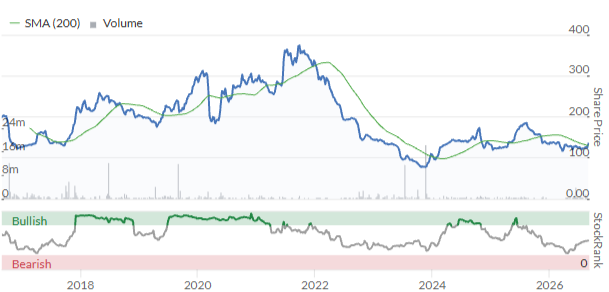
I admire this business and have a lot of confidence in owner-CEO Mark Carpenter (10% shareholder). But I don’t have a crystal ball – and neither does he. I think it’s fair to say Motorpoint will remain exposed to macro factors beyond its control.
It’s also true that this is an ultra-low margin retailer whose profits are dependent on high volumes and rapid stock turnover.
I was AMBER/RED in April, but that’s no longer an appropriate view. However, with the stock already trading on a mid-teens P/E, I’m not sure I’m confident enough to make the leap to AMBER/GREEN. The StockRanks also remain fairly lacklustre:
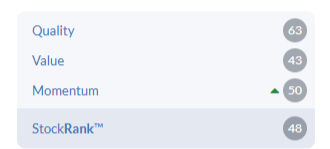
I’m going to move up one notch to neutral (AMBER) today, with the caveat that investors with insight into the used car sector may well choose to take a higher-conviction view (positive or negative) than me.
AEP Plantations (LON:AEP)
Down 3.2% at 196p (£730m) - Half-Year Results - Roland - AMBER =
This palm oil producer has tripled over the last two years and is well liked by the StockRanks:
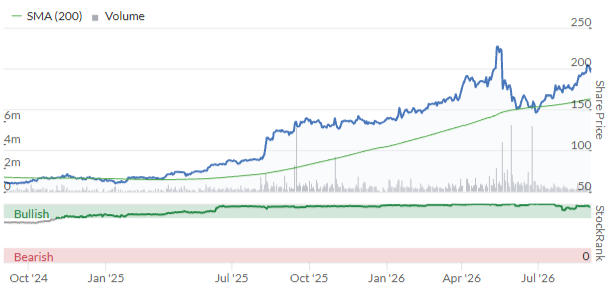
Today’s results leave expectations largely unchanged but suggest an H2 weighting will be needed to meet full-year forecasts. This may explain today’s slight share price dip.
Half-year results summary
These accounts reveal a sharp increase in operating costs and weaker like-for-like production. This combination put pressure on profits margins for the period, despite an increase in overall production and revenue:
Revenue up 8.3% to $249.7m
Pre-tax profit up 5.1% to $65.8m, (including a one-off, non-cash $9m accounting gain relating to the Pinago acquisition)
Pre-tax profit excluding one-off gain down 9.3% to $56.8m
Earnings per share up 3.1% to 12.71 cents
For some reason AEP was able to acquire Pinago for $158m, below the $171m fair value of the assets acquired. This resulted in a so-called bargain purchase gain of $9m:
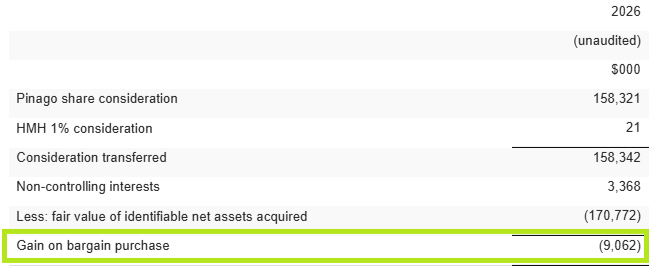
I don’t see much point in including this in my view of profits – it’s a one-time non-cash gain that doesn’t reflect operating performance.
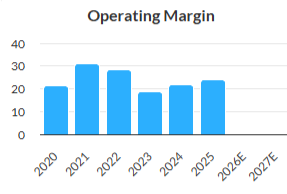
Using my view of underlying operating profit, AEP’s operating margin fell to 21.4% in H1, from 25.7% for the same period last year. This reflects a 123% increase in administrative costs – albeit some of these were acquisition-related:
Administrative expenses increased to $10.5 million from $4.7 million, mainly due to higher corporate expenses, including acquisition-related costs for Pinago and PT Jaya Jadi Utama, and the inclusion of two months of expenses from Pinago.
While 21.4% is still a strong margin, it’s at the lower end of the range we’ve seen over the last five years:
Balance sheet: despite spending $158m on the acquisition of Pinago and $25.9m on dividends and buybacks in H1, AEP ended the half year with net cash of $96m. That’s about 10% of the group’s market cap. This is an impressive display of strength, highlighting the strong cash generation of this business when commodity prices are high, as they are currently.
Commodity prices: AEP’s revenue is entirely driven by the market prices of Crude Palm Oil (CPO) and Palm Kernel Oil (PKO) – both commodities are extracted from the palm fruit grown by the company’s plantations. (Mark provided an excellent primer on this business in his write-up of MP Evans here.)
The commodity price environment has been favourable in recent times and remained so in H1. This is particularly true for PK prices, which have roughly doubled since 2023 and rose further in H1 26:
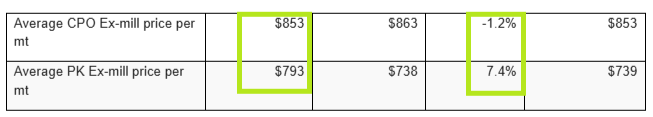
I don’t know whether the strength in PK will persist. Prices have historically been more volatile than CPO and I note that broker Cavendish is using a lower PK price of $400/t for FY27 and FY28, “assuming the recent strength is a temporary spike”.
Of course, if this strength persists, it could drive some nice upgrades to forecasts in 2027. I estimate that the $393 difference between recent PK prices and Cavendish’s FY27 forecast assumption of $400/t was equivalent to around 9% (c.$22m) of H1 revenue – a material amount.
Production volumes: AEP can’t control pricing but it can aim to maximise production volumes, particularly in strong markets. The company’s H1 performance seems a little mixed in this regard, with timing factors seeming to hold back some production.
Fresh Fruit Bunches (FFB) production rose by 2.7% to 544,700 tonnes - this included 29,000t from Pinago, without which FFB production would presumably have fallen by 2.8% to 515,700t.
The company says production was held back by “a delayed cropping cycle” and the ongoing replanting of some of its plantations.
Production has trended higher since June and is expected to be stronger during the second half of the year.
In addition to its own produce, AEP also buys in FFB from external growers to fill capacity in its mills. External FFB bunches purchased rose by 12.9% to 669,800 tonnes during the half year.
This supported an overall increase in CPO and PK production:
CPO Production +4.3% to 223,600 tonnes
PK Production +5.3% to 55,500 tonnes
Outlook & Broker Estimates
AEP’s house broker Cavendish has tweaked its 2026 EPS forecasts upwards to 32.7 cents per share today (previously 32.2 cents) – slightly above consensus:
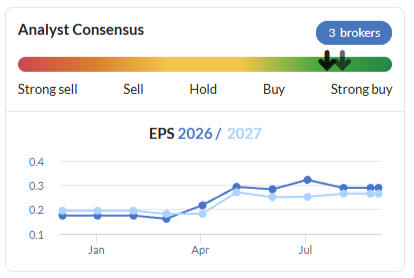
Based on the company’s H1 earnings of 12.71 cents, this means AEP needs to generate more than 60% of its earnings in H2 in order to avoid missing its house broker’s forecasts.
While we are often cautious about H2 weightings, I think this forecast seems credible enough, based on expectations for stronger production in H2 and “elevated” CPO prices over the coming months.
Cavendish’s estimate puts AEP on a 2026 P/E of around 8.1 with a 3%+ dividend yield.
While this may seem like a bargain multiple, it’s worth remembering that commodity stocks often trade on a low P/E when prices are high. This is the market’s way of recognising that commodity prices tend to move in cycles and may fall at some point.
While forecasts for 2027 and beyond remain uncertain, in my view, it’s worth noting that the current consensus view is that profits are likely to be lower next year.
Roland’s view
AEP is expanding and upgrading its estates and appears to be on track to deliver another strong year, assuming today’s guidance remains valid.
Commodity prices aside, another factor to consider is whether changing conditions in the Indonesian palm oil market will affect profits. Starting in 2027, palm oil producers will have to sell their oil to a government export agency which will then negotiate international sales.
Although AEP sells all of its oil to domestic refiners and thus isn’t directly exposed, I can imagine there could be second-order effects from this change that are hard for us to predict.
Mark was neutral on AEP in June, based on his view that the stock has now re-rated and that further upside is dependent on commodity prices. I share this view, so I’m going to stay neutral today.
Calnex Solutions (LON:CLX)
% at p (£m) - AGM Trading Update - Roland - AMBER =
I reckon this network testing equipment specialist is one of the more interesting IPOs of recent years.
Calnex floated in 2020 at the start of a period of peak profits, before suffering a nasty cyclical collapse in earnings. Founder-CEO Tommy Cook (19.7% shareholder) has since been rebuilding the business with a more diversified portfolio that’s expected to provide a more durable platform for medium-term growth.
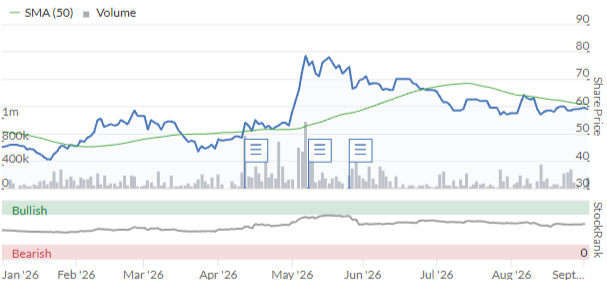
Ed Sheldon covered the company’s full-year results in May, noting diversification into markets such as defence and data centres, together with a 73% increase in pre-tax profit for the year. He stayed neutral on valuation grounds, which proved to be a good call – the share price has drifted lower since then:
That brings us up to date ahead of today’s AGM update:
Trading in the year to date has been in line with market expectations. Supported by a strong balance sheet, differentiated product roadmap and growing customer opportunities, the Board remains confident in the Group's prospects for FY27 and continues to expect the targeted investment being made this year to support accelerated growth in FY28.
Calnex reports continued progress with diversification and new product development:
Diversified product portfolio is continuing to drive growth, including a recent “digital infrastructure win with a major US financial institution”.
The company’s telecoms business “maintains its leadership position, albeit in anticipated lower growth markets”.
Engagement around the “next-generation Sentry data centre assurance offering continues to develop positively”.
Development of a 1.6Tb/s synchronisation testing product is also progressing towards planned launch next year, building on the success of a 800 Gb/s product (half the speed!).
Outlook
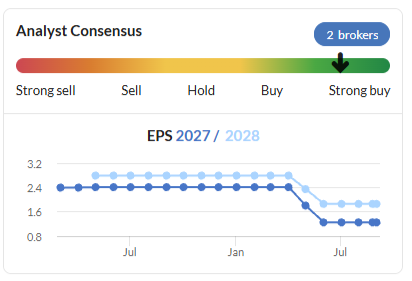
Forecasts from broker Cavendish are unchanged today and suggest a strong recovery in earnings over the next 18 months or so (Calnex has a 31 March year end):
FY26 actual adj EPS: 0.80p
FY27E adj EPS: 1.2p (+50% vs FY26)
FY28E adj EPS: 1.9p (+58% vs FY27)
These estimates are in line with the consensus view (from two brokers) on the StockReport:
Roland’s view
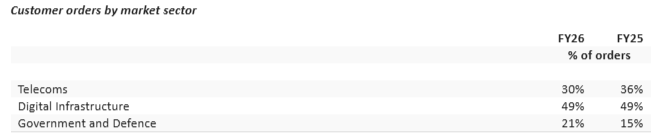
Calnex has significantly reduced its exposure to the telecoms sector, which was previously its core business. This only generated around 30% of revenue last year, with the balance coming from the faster-growing Digital Infrastructure and Government & Defence segments:
Encouragingly, customer tenure remains strong. Last year saw 79% of revenue come from repeat customers, with the company’s top 10 customers boasting an average tenure of 13 years.
Perhaps the only slight negative last year, in terms of diversification, was that customer concentration increased. Calnex’s top ten customers generated 56% of FY26 revenue, up from 46% in FY25.
I think it may be possible that Calnex has rotated its previous overexposure to the (cyclical) Telecoms sector into a heavy exposure to the hyperscaler and data centre market. This too may be vulnerable to a slowdown at some point, if the AI build-out slows.
While I still think this is an interesting business with good medium-term potential, I think the current valuation already prices in plenty of continued growth:
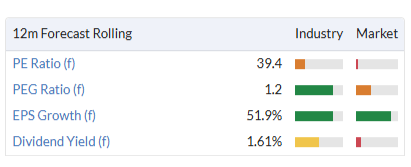
A PEG ratio of 1.2x looks about right to me, in terms of valuation, so I’m going to leave our neutral view unchanged today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

38 comments
I knew I should have bought Rentguarantor Holdings (LON:RGG) on the first "materially ahead". This chart is quite something.
Yes, I checked the junk folder, they were alerting within Stockopedia but not emailing, could not find anything wrong but just started to work again this morning ( 3rd )
Re:RGG
Traditionally the largest rent guarantee company in the UK has been Housing Hand. Its website claims
"As the UK’s largest rent guarantor service, we’ve supported over 100,000 students and professionals from all around the world. With more than 4,000 trusted partners, we’ve guaranteed over £1 billion in rent helping people settle into homes they love."
Housing Hand has often been used by students who are unable to satisfy normal guarantor requirements A key benefit from a landlord's perspective is that it puts the cost and obligation back to the student tenant. This removes the Landlord from a potentially difficult situation and conversation over a failed credit check.
Also, some Landlord Insurance policies require a guarantor. Their criteria as to what constitutes a satisfactory tenant and guarantor can be a awkward .Much easier for a Landlord to duck the whole process and go with a guarantor company.
And so to Rent Guarantor (RGG). I am intrigued as to the growth of this company which can only have come in a number of ways...
Price - cheaper product, increase market share
Better product - more market share
Third party agreements - marketing leverage
Better promotion .
Increase in the market size
Taking on higher risk proposals
Or possibly a combination of all of the above. If it is mainly the increase in market size ( as suspected), then I would expect other entrants into the market.
For the immediate future this seems like an interesting company, though if I were a serious holder I would be checking both the Housing Hand and RGG websites to see if there was any evidence of them fighting it out for business, as this might suggest the end of market growth.
These products are very useful, but like many other consequences of the Renter Rights Act makes it more expensive for renters to rent.
No position
Well done Graham, for providing the early alert, enabling those of us you had previously advised on the possible meteoric rise of RGG to increase our shareholding and watch in fascination throughout the day as the share price jumped in the same way as so many others tipped by Ed Croft's recent webinair, have. Please do keep up the excellent work.
Do I take it then that you are now a shareholder? I recall your comments after Ed’s webinar on bad debt concerns (& which I responded to as its a business I now know quite well & have been holding for a few months)
As a long term holder of GBG (LON:GBG) I am sitting on a nasty loss.
I have been in and out of this share for over 10 years now but the competition in the USA seems to be very strong and the Company just seems to be failing to address the issues it faces from numerous competitors. I would welcome any views from other subscribers.
TMI said in August that they decided to spend £6m as a result of feedback on GBGGO from 4 clients-Uber, Fedex, Temu and Equifax-which is the top 3 global consumer credit reporting agencies. Pipeline has 225 leads and he suggests it is his conviction buy of the year. SCSW in September edition has said the customers lost were on a legacy product. Guidance is reduced to 1-3%-not 5%. The news is disappointing but not fatal! He still rates it a buy.
Both TMI and SCSW have been very useful for me over time and on their views I am holding, suffering the same pain as yourself.
There was some debate in the comments yesterday regarding gilts, this timely podcast may help those looking at gilt investments.
https://podcasts.apple.com/gb/...
Bodycote (LON:BOY) Does anyone know of the timetable / last dates for CVC and any other suitor to put forward counter-proposals to the Veritas offer ?
I thought it was today.
There were some comments about it yesterday.
Bodycote (LON:BOY) Does anyone know of the timetable / last dates for CVC and any other suitor to put forward counter-proposals to the Veritas offer ?
It's 5.00 pm today for CVC.
https://www.stockopedia.com/a/...
timarr
Bodycote (LON:BOY) Does anyone know of the timetable / last dates for CVC and any other suitor to put forward counter-proposals to the Veritas offer ?
Actually, I think the Veritas offer extends the deadline - there's a day 53 rule after a formal bid has been submitted for a competing offer.
timarr
Good morning all,
Re Corero Network Security (LON:CNS)
Edison have a new note here
Graham/Roland - will you cover Kazera? The news out today is very significant for the company. Zeus have published a fairly detailed note.
We tend not to cover small mining companies, so I don't think so, spglet. Feel free to share your thoughts here though, if you think other readers would be interested! G
You're probably right it's not the right stock for this forum. Anyone with a Research Tree subscription and an interest in small speculative resource stocks can check it out.
I've had shares in Kazera Global (LON:KZG) for quite a few years and I am very familiar with all its ups and downs, but I believe this is the point where it reaches adulthood and becomes a place for semi sensible investors with an appetite for some risk. Recent key events - SAI partnership, and then today's news.
These events transform their balance sheet, and provide very healthy growth over the next 12 months. They will become a similar size to Kenmare Resources (LON:KMR) fairly quickly but without the capital requirements. I believe SAI (part of a large Chinese conglomerate) will make a bid for the whole company in time.
If you get a chance your thoughts on Rentguarantor Holdings (LON:RGG) would be appreciated. Up 120% since it appeared on my Momentum Jump screener just 5 weeks ago.
What does the momentum jump screener consist of?
Wondering if the CEO Foy has a good sense of the business and profitabiltiy. He sold £2m worth of shares in June at something like 29p. Had he held on for just a couple more months, he'd have sold for £6m instead. Obviously hindsight, but you'd hope he'd have had some sense that trading was going well enough for a market beat and that the SP would respond in kind
That sale was the only reason I didn't invest
Anyone else not receiving alerts to their email ? Mine have been down for a couple of days, tried contact via the green button.
Mine have been fine. Have you looked in your spam folder?
It must be only a matter of time before TT electronics (LON:TTG) are acquired. DBAY hold 29%.. Either way good to see a turnaround happening here, if you have the time I'd be interested to hear your thoughts.
As a fellow TTG shareholder Ben I’ll slightly temper your enthusiasm if I may. Following the DBay rule book they don’t rush their bids nor do they overpay. They’ve got their blocking holding in place so are quite likely to take their time
Given todays results I’d prefer for them to remain listed & I’ll continue to add on any weakness
If you could cast your eye over AEP Plantations (LON:AEP) that would be great! A solid compounder that has delivered another set of good results with the acquisition settling in nicely and contributing to the profits.
Thanks, Graham.
Interim results out today from Cairn Homes (LON:CRN) look good. Not in todays list but would appreciate a view
Morning Gudge58,
Thanks for flagging this up, they somehow got missed earlier.
I've added Cairn Homes (LON:CRN) to the table (and the list) for today.
Roland
Hi Roland , I did put in a wee comment when the' week ahead 'went up over the weekend , that this might be very interesting ,and so it has proved to be.
More completions , better cashflow , increase dividend ,and new 50 M euro buyback, and the future looks strong too. This is helped ,no doubt. by the Irish government having a substantial surplus ,and therefore adding support ,with 'help to buy' , but also the desperate need for more property.
I particularly like the fact they run their own apprenticeship scheme ,thereby reducing any skilled shortage ,for the future.
Anyway ,very satisfied investor ,especially as I did my first major buys at just under the £1 ,and with TIME succumbing to takeover ,this is now my major holding. Tony
Amazing what a government can do when they don't fund NATO!
Not sure what the current situation is but:-
Ireland's corporation tax receipts reached €28.1 billion in 2024 — up from €4.6 billion in 2014. Corporation tax now accounts for 29% of all tax revenue, up from 11% a decade earlier. That's over €5,000 per person in Ireland.
The concentration is startling. Foreign-owned multinationals accounted for 84% (€20 billion) of all corporation tax in 2023. The top ten corporate groups paid 56% of total receipts. Three corporate groups are estimated to account for 38% of all corporation tax.
Ireland is basically a legitimate tax scam similar to the offshore islands that heard no evil see no evil back in the day - much needed taxes that should be going to UK plc are going to Ireland PLC - whilst we sit here twiddling our thumbs - i think corp tax revenue per head of population is something like 2-3 X plus what it is compared to uk. Basically ireland is scooping up the taxes that should be paid by the entire eu plus ukl. No wander they are happy to fund the EU to the tune of say £250 per head of population per year when they are raking in $3000 plus per year from the likes of apple google and facebook being based there.
Note uk plc could easily tax the cash that departs the building to these multinations m, or give an incentive for them to pay taxes here - its bordering criminal that we let this cash leave the uk -tax free , at minimum there should be an online sales tax levied of 10% plus. In the old days when funds went to the likes of Johnston press proper uk based entity at least the cashflow was getting spent mostly in the uk - so premises paying business rates and employees paying taxes and uk corp tax being paid - there is literally none of that when its syphoned straight out to ireland **- thats not even mentioning the vat loss too if its a non vat registered business paying google for adds thats another 20% not colected that would be collected if hgoogle were uk based - we are stupid beyond belief
Ireland is fortunate that the other countries have allowed the current position to fester.
** in theory there may be anti avoidance rules here but they are probably super easy to sidestep - simply get all your r&d based in the uk then get the uber generous benefit that the uk provides in that regard.
Good morning Graham,
If you get a chance to look at Cairn Homes (LON:CRN) who have updated the market today with a positive looking statement it would be appreciated. Not sure this can be reflected across all house builders, but welcome your thoughts.
Best wishes
Greyster
This time of year, best bet is to keep laptop closed, and come back end November.
Not entirely relevant (understatement) to today’s results but I see Goodwin (LON:GDWN) FY results were loaded on to Stockopedia overnight; the performance of the part of the business which is being actively marketed for sale has been ignored in terms of FY26 results. So revenue and EPS are shown as having significantly dropped when in reality they were up 27% and over 100% respectively.
This all seems quite bizarre to me as no sale has taken place and the business continues exactly as was previously the case. I realise Stockopedia use an external company to load its results but IMHO that doesn’t justify complete garbage being loaded, giving rise to ridiculously unrepresentative metrics for Q, V, M, etc
We are meant to be able to rely on these metrics when assessing companies but GIGO is certainly the case here
Thoughts welcome…
You are absolutely right Mr Shanklin 100. What you have to remember is international reporting standards. Assets held for sale are treated differently in accounts. This blurs the accounts and like right of use assets and discounting of leased assets make a company's accounts difficult for the untrained eye to follow. It is all part of a ongoing trend for the last 50 years to turn accountancy into an exact science. This is poppycock. It did not give an accurate picture of Carillion etc. and despite all the research and slide rules, property valuation and value of goodwill are still guesswork. C'est la vie.
Fair point PFowler
We should obviously put following mechanical rules above creating a fair and reasonable representation of a company, in this case Goodwin (LON:GDWN). How very stupid.
It's the 2nd ;)