FTSE 350 income: screening for top dividend growth opportunities

In my piece last week I showed how a simple screen might be a useful tool to find sustainable high yield stocks in the FTSE 350.
This week I want to approach income from the perspective of strong growth rather than yield. So I’ve created an alternative screen that looks for stocks with strong dividend growth characteristics.
Why would I consider this approach? For me, dividend growth investments fall into two possible categories (sometimes both):
Quality growth stocks: rapid, well-supported dividend growth can be an indicator of a small/mid-cap quality business that’s growing fast. In this scenario, the company’s share price will often rise at a similar or even greater rate than its dividend.
Contemporary examples of this might include Tatton Asset Management (LON:TAM) or Jet2 (LON:JET2). These companies have five-year average dividend growth rates of 13.8% and 7.6% respectively. Both have been multibaggers over the last 10 years:

Cash multibaggers: over longer periods, successful dividend growth investments can reach a point where the cash income received from the shares exceeds the original investment.
In other words, the investment will deliver multibagger returns in cash, not just through share price gains.
The most famous example of this is probably Warren Buffett’s stake in Coca-Cola Co (NYQ:KO). Buffett’s company Berkshire Hathaway owns 400m shares that originally cost the firm about $1.3bn. That’s equivalent to an average cost price of about $3.25 per share.
Coca-Cola’s dividend currently stands at $1.89 per share, according to Stockopedia. That gives Buffett’s shares a yield on cost of 58%.
In other words, Berkshire Hathaway doubles its original Coca-Cola investment in cash income alone every two years. That’s without factoring in share price growth:

A word of warning! Warren Buffett has owned Coca-Cola shares since the dawn of time 1988. Investing in potential dividend compounders is a long-term strategy that is only likely to work well with high quality businesses. Essentially, this is an income variation of the compounding quality approach.
Over shorter periods, the income received from dividend growth stocks may be significantly less than the cash payouts from sluggish high yielders.
I’ll return to this theme in the final article of this series, when I’ll consider some of the factors involved in choosing between dividend growth and high yield.
In the remainder of this article, I want to discuss my income growth screen and consider some possible examples of interesting dividend growth shares.
FTSE 350 dividend growth screen
Screening is always a balance between being too restrictive and insufficiently selective. I tend to err on the side of easing my rules and doing additional manual checks to filter out unsuitable candidates.
Screens are meant to be a list of ideas for further research, so I think it makes sense to accept a little extra work in return for a more varied list of possible opportunities.
In this screen, I’ve tried to find companies with above-average profitability, a track record of earnings and dividend growth and a sustainable dividend.
The growth element of this screen means that it makes more sense to consider smaller companies than it did for the high yield screen.
As a result, I’ve set the minimum market cap at £300m to match the smallest companies in the FTSE 250. In reality, I think it might be worth going a little lower still.
In terms of absolute dividend yield, I’ve set a minimum forecast yield of 1%.This is obviously too low for any investor seeking a worthwhile income. But I think it can make sense where dividend growth is serving as a proxy for strong underlying business growth.
As always, it’s important that all investors understand what they’re trying to achieve and DYOR. There’s no one-size-fits-all solution.
With that said, here’s a snapshot of the screening rules I’ve used:

You can see and edit this screen here.
The screen returns 32 shares at the time of writing. Here’s a snapshot of those with a StockRank of 80 or higher:
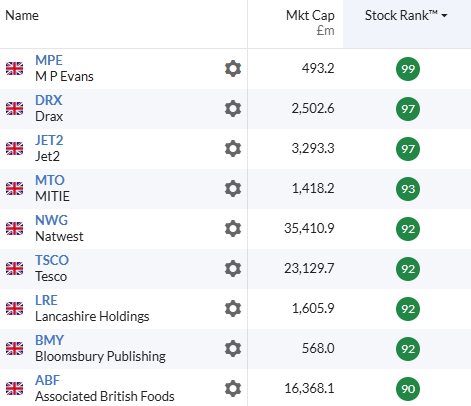
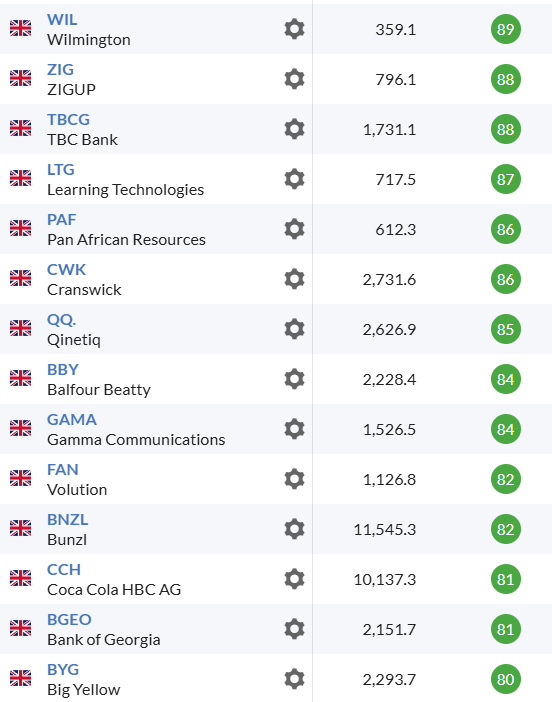
In the remainder of this article, I’ll take a look at a few of these that look interesting to me at the moment.
Jet2 (LON:JET2)
As an investor, I’m a big admirer of this well-run travel business, which operates a budget airline and package holiday business. Having been a customer a few times, my experience is that the service is also hard to fault.
The company’s growth record is deeply impressive, in my view. Revenue has risen at a CAGR of 16% since 2019, while earnings have grown by an average of 13% per year over the same period.
Jet2’s dividend has risen by 7.6% CAGR since 2019 despite the pandemic. Since 2014, the payout has grown at a CAGR of 18%:

The stock’s quality metrics are surprisingly good for a business of this kind:

Having said all of that, a cyclical travel business and a capital-intensive airline do not obviously fit the sustainable quality growth profile I’m looking for.
Is Jet2 the exception to the historical rule that airline stocks rarely make good long-term investments? That’s an individual decision.
However, the shares are rated very highly by Stockopedia’s algorithms at the moment, perhaps suggesting that the current positive run has further to go.


The consensus outlook for earnings is also fairly positive:

Alternative UK consumer stock: for a more conservative and higher-yielding UK consumer stock, Associated British Foods (LON:ABF) could be worth considering. Megan reviewed this family-controlled conglomerate in the DSMR recently – read her thoughts here.
Qinetiq (LON:QQ.)
FTSE 250 defence group Qinetiq has become a little more pricey since Paul took a positive view of the stock in May.

However, the company has also benefited from several broker upgrades this year and is a beneficiary of the broader strength in the European and US defence sectors.

Qinetiq’s dividend has grown at a CAGR of 6% over the last decade, a rate brokers expect the company to maintain over the next couple of years:

While the yield is low, the payout is covered more than 3.5x by earnings and the balance sheet looks fine to me, with quite modest net debt. Cash generation appears to be quite good, so I wonder if there’s scope for more generous payouts as the business expands.
One possible concern might be that profitability has been somewhat inconsistent in recent years:

However, forecasts suggest a gradual recovery in margins from FY25 and I don’t think the shares look too expensive for a business of this kind:

The StockRanks have a broadly favourable view, but flag up some weakness in value.

This score reflects the stock’s High Flyer style – further gains are possible but any disappointment could trigger a sharp de-rating. I’m inclined to remain positive though, given the broader macro backdrop and US exposure of this business.
Alternative Industrial stock: an alternative choice from the Industrial sector might be distribution group Bunzl (LON:BNZL). This business supplies a vast range of goods such as cleaning and safety products to customers all over the world.
It’s a remarkably well-run and solid business in my view, with strong competitive advantages. The dividend record is outstanding, with a 10-year CAGR of 7.4% and 30 years of unbroken growth:

Bunzl shares have risen by 670% over the last 20 years, in a nice example of how long-term dividend growth can be reflected in share price growth.
Gamma Communications (LON:GAMA)
This business communications technology group is not a company I’ve paid much attention to until recently, but I wonder if this has been a missed opportunity.
Gamma boasts an excellent long-term profit growth record and some very respectable quality metrics:


The firm’s share price has risen by 625% since IPO in 2014…

… a record that’s been reflected in a dividend growth CAGR of 12.6% per year. Payouts have been made every year since 2015, its first full year of listing:

The dividend yield is low, at 1.2%. But again, I see this as an indicator of underlying business growth, with the potential for more generous payouts in the future (the balance sheet has net cash).
Broker forecasts suggest the historic double-digit dividend growth rate may be maintained:

Again, a High Flyer styling is a reminder of the risk of a sharp correction if growth does disappoint. However, broker earnings have trended higher this year and the outlook seems fairly positive.

If Gamma’s profitability and growth rate can be maintained, I suspect the shares could easily grow into the current valuation.

Gamma Communications could be worth further research, in my view.
Alternative Technology stocks: for a different way to play the enterprise IT sector, Softcat (LON:SCT) and Computacenter (LON:CCC) (I hold) might be worth a look. Both are valued-added resellers that have successfully built service businesses on top of box-shifting operations.
Disclosure: at the time of publication, Roland owned shares in Computacenter.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

16 comments
Shares increasing their dividends for multiple years are attractive, but if the initial yield is tiny it’s a long wait before the yield becomes substantial. I go for shares and Investment Trusts already paying sustainable big dividends. And some of those manage annual increases too.
I’ve provided minimal text in the rest of this post because it’s a thread seeing little follow up, so I’ve just listed some of the big dividend payers in our portfolios with a bit of info on some of them. These shares and Trusts provide very substantial annual income. The benefit of that is felt particularly during bear markets. And when a new share or Investment Trust buy is financed by the dividend income.
THE SHARES:-
Aviva (LON:AV.) 474p. Up 20p today after recent falls and up after a positive update. Dividend yield 8% and it’s being increased year on year.
Legal & General (LON:LGEN) 216p. It’s at a 1 year low and now yields 10% with small 2% annual increase.
M&G (LON:MNG) 196p. 10.6% dividend.
Phoenix group (LON:PHNX) 493p. Dividend 11.3%
Abrdn (LON:ABDN) 138p. Terrible record of Management failures but it now looks priced in. Started buybacks at £5 and continued with them for 6 years. 11% dividend but a cut possible.
Polar Capital Holdings (LON:POLR) £5. Fund Managers are having a difficult time with outflows……but Polar looks the best of the bunch. Dividend 9%.
Smiths News (LON:SNWS) 61p. Recent big dividend increase so now yields 12% and further dividend increases likely.
THE INVESTMENT TRUSTS:-
Commercial Property sector looks to have bottomed. Some of the Trusts in the sector pay big dividends …..ahead of likely share price increases ahead, especially so if interest rates fall further.
Aew UK Reit (LON:AEWU) 96p. I’ve held for several years and with dividends included the gain is over 100%. A quality Trust …yet at a 13% discount to NAV.
Alternative Income REIT (LON:AIRE) 71p. Dividend 8.3%. Discount 12%.
Supermarket Income REIT (LON:SUPR) 68p. This is a multi year low…..despite their main tenants being the big supermarkets. Dividend 9%. Discount is a wide 24%.
Schroder European Real Estate Investment Trust (LON:SERE) 70p Dividend 8.6%. Discount a very wide 35%!
Henderson Far East Income (LON:HFEL) 226p. Dividend 10.8%. At a small premium to NAV. Performance has been awful for several years as too much emphasis was placed on continuing the multi year dividend increases. But new Management and new strategy are showing signs of working. And that big dividend is looking secure and with more annual increases too.
Excellent and balanced analysis on Henderson Far East Income (LON:HFEL) here:-
https://cdn.janushenderson.com...
Amedeo Air Four Plus (LON:AA4) 51p. 13.6% dividend and they have promised to pay it until at least 2016, but take the 50% discount to NAV with a pinch of salt. Terminal value of the planes they lease to Emirates is still guesswork…..but with Boeing’s woes optimism on that is increasing.
btw…..some of the above have only seen modest share price gains so far but others (e.g Amedeo Air Four Plus (LON:AA4) up 50% on my buy price):have done well. Plenty more upside potential for most of them. So well worth checking them out?
Hi ken
Shares increasing their dividends for multiple years are attractive, but if the initial yield is tiny it’s a long wait before the yield becomes substantial. I go for shares and Investment Trusts already paying sustainable big dividends. And some of those manage annual increases too.
It depends on why you're investing of course, but many high dividend payers offer an attractive yield because the market thinks they have a low chance of capital appreciation. Businesses that pay out a large proportion of their earnings aren't reinvesting in future growth.
I looked at two businesses in my portfolio at random - Aviva (LON:AV.) and Relx (LON:REL), the former a high dividend payer and while the latter offers lower dividends but higher growth. Over 10 years the total shareholder return per for £1 invested (capital plus dividends) for Aviva was 47p (the share price actually declined over the decade) while for Relx it was £2.85.
Over the period Aviva paid out 37p in dividends and Relx 42p per £1 invested. Note though that Aviva had a capital return a few years ago worth an extra 20p.
Of course, higher dividend payers have a role in many portfolios - I hold many on your list - but we need to be realistic if that's all we hold then unless the dividends are reinvested the overall value of the portfolio will likely decline in real terms over time. In periods of low inflation this doesn't matter so much but when inflation rises it has a real purchasing power impact.
Ideally, of course, these higher dividend payers recover their mojo, start generating earnings growth and they rerate (the longstanding John Lee approach to small caps). Long suffering Aviva holders seem to be experiencing this under Amanda Blanc. Legal & General (LON:LGEN) on the other hand looks like a value trap - its earnings are barely covering its dividend which means future dividend growth is constrained, as is investment in the business. I'm hopeful that investments in AI can significantly reduce backroom costs but I may well be smoking something suspicious ...
By all means point out the virtues of a dividend in the hand over future capital appreciation in the bush, but it's not a one way ticket to wealth and if done thoughtlessly will be exactly the opposite. On the other hand investing in a handful of quality stocks at the right price pretty much guarantees long term wealth accumulation, albeit with lower initial dividends, without needing to do much in the way of active management.
timarr
Excellent post as always timarr. Only Total Return matters. I have never understood the attraction of high yield investing. It is wrong headed IMO to invest in equities purely for income . Si
simoan.
I’ll reply to timarr’s quality reply separately. I have never suggested buying equities purely for income. I have a balanced portfolio that includes a mining portfolio along with shares and Investment Trusts that pay minimal or no dividends. And when buying high yielders I’m looking for,and often getting big capital gains too.
ken,
Sorry, I was responding directly to timarr and making a separate point. I was not referring to you or your post. As you will be aware, there is a school of HYP investing which only concentrates on the highest dividend yielding shares and in the early days of Stockopedia there were a few articles by Stephen Bland. Luckily, that has all died off. It’s a dead end investment philosophy IMHO.
All the best, Si
' in the early days of Stockopedia there were a few articles by Stephen Bland'
I well remember Stephen's contributions to the Motley Fool. He would choose a share of the week, invariably greeted by a chorus of thanks from his band of acolytes. One week his selection was Northern Rock, at a time when it was obvious to most that it was going bust. The usual outburst of gratitude greeted this selection.
I well remember Stephen's contributions to the Motley Fool. He would choose a share of the week, invariably greeted by a chorus of thanks from his band of acolytes.
He once recommended some crap gambling company focused on the US which I posted on, to point out there were a whole nasty bunch of US regulations coming down the line. He responded by a post that I think I can only describe as "unpleasant" but included some reference to me being a specky computer nerd (which to be fair, was true in all respects).
Anyway, the regulations came in and the stock went bust and his pithy advice to his acolytes was "shit happens".
Strategic ignorance my arse ...
timarr
As a fellow speccy computer nerd (retired from computers), I agree wholeheartedly.
I see he has a Guru screen on here: https://www.stockopedia.com/sc...
Has not done too badly, if you add on the dividends and compound them it would a reasonable performance.
Thanks for that reply timarr (and btw for explaining elsewhere about readership numbers).
You’ve misunderstood my post, but that’s my fault in not explaining my methods with high yielders, nor that I don’t only hold high yielders. I kept text and info at a minimum simply because as I pointed out, readership of the post was likely to be so low as not to be worth the time it takes for a thorough post.
My key investment tactic is to buy heavily in big market dips when most are saying don’t, including high yielding shares with capital gain potential. There are often incredible bargains available then. I was not btw suggesting that all the shares and Trusts in my post were buys now. They were examples of the incredibly high yields still available AND with the likelihood for a few of even further dividend increases
You mention Aviva (LON:AV.) and Legal & General (LON:LGEN) . I bought (and posted on Mike Walters site at the time) Legal & General (LON:LGEN) after the covid falls at just 155p.It’s now 40% higher and the dividend yield at my buy price is 14%.
Aviva (LON:AV.) is one of the few shares in my portfolio I didn’t panic sell (too late!) in the covid crash. I bought around £3.60 years ago. I averaged down at just £2.50 after the covid crash, but only with a small stake because of my rule of a maximum in each share and buying more broke it. That buy has almost doubled.
Yes. Aviva (LON:AV.) has been a lousy long term performer as timarr pointed out. But neither Legal & General (LON:LGEN) nor Aviva (LON:AV.) are lousy performers if using my tactic of buying quality in the big dips when most are selling. That’s the tactic favoured by Warren Buffett and who am I to disagree with him!
Perhaps in another post I’ll post the gains and losses, excluding the big dividends, of the big dividend paying shares and Trusts in my previous post.
Hi ken
If we take Legal & General (LON:LGEN) as an example it's instructive.
LGEN has only traded below 155p on one day in the last decade - 19th March 2020 at the start of the Covid panic, and then only for a short period of time. So it was a smart piece of timing on your part. Mine on the same day was Pearson (LON:PSON). Let's go with that and add in Relx (LON:REL) again for good measure.
Here are the Total Shareholder Returns for each stock since the Covid low point (or my PSON purchase price).
Both Relx (LON:REL) and Pearson (LON:PSON) have generated significantly better returns for shareholders than Legal & General (LON:LGEN) even though their yield on cost is lower.
From which I conclude that buying anything half decent at the low point of the Covid panic would have yielded very good returns.
I hold all of the above, btw.
timarr
Obviously I know I'm talking to myself here, but I think it's only fair to point out that if you reinvest dividends rather than taking them out then the superiority of Pearson (LON:PSON) and Relx (LON:REL) over Legal & General (LON:LGEN) narrows. But you'd still have been about 25% better off investing in the former than the latter since 2020.
Enough of that, time to go to Essex.
timarr
That “talking to yourself” was why my original post was so thin on detail and hence misunderstood. Interest in a lot of very good threads here is minimal unfortunately.
As for your performance comparisons, isn’t this a daft game? I.e taking 3 shares at random to support our case. I could easily come back with big dividend payers that have way outperformed and then you with more examples where they haven’t!
e.g I bought TP Icap (LON:TCAP) at just over £1 two years ago when the dividend was about 7%. Share price is now up 150% in 2 years and dividend yield at my buy price 15%. Reinvesting the big dividends would already have given an even better return. How does that compare with Relx (LON:REL) and Pearson (LON:PSON) over the same period?
As for Legal & General (LON:LGEN) . But for the share price fall to lowest since June that hasn’t yet been made up, when they bowed to pressure to start buybacks and did so by cutting future dividend increases from mid single digits to just 2%, the performance on your criteria with dividends reinvested, would have been similar to Relx (LON:REL) and Pearson (LON:PSON.
btw….I agree about Stephen Bland.
Hi Roland,
Qinetiq (LON:QQ.) Down 8% today on what seem pretty reasonable results including an increase in cash allocated to share buy backs. PE at 13.7 (as per Stocko) doesn't look demanding and demand likely to be strong going forward with the 'Trumpian' pressure on defence spending and Putin's continued war mongering. Any thoughts on the significant drop in share price?
Had this with Clarkson (LON:CKN) which I bought at £1.95 in 2002 when they paid 15p per share dividend. Today they are £37 a share and pay £1.04 per share dividend. One of my very long term holds - thankfully all shielded from Capital Gains and income tax ... I can't say I have had many of these so it's nice to see an article like this. Thanks!
Interesting to look at things this way Roland. Excellent read