How Imagination Technologies showed the risks of Momentum Traps

Today’s share price collapse at Imagination Technologies saw the stock fall as far as 66% during trading - and many private investors will be feeling the pain. It was triggered by news that Imagination’s biggest client Apple is set to pull out of a long standing licensing deal with the company.
Before today, Imagination showed the worrying signs of being a Momentum Trap. In its favour, its shares were supported by positive price momentum and brokers had been upgrading their earnings forecasts in recent months. But it was still financially weak and the stock looked expensively priced. Today’s slump shows just how Momentum Traps can suffer when sudden disaster strikes. So what were the warnings signs and how can investors be aware of them?
What’s the deal?
Imagination supplies the technology behind the Graphics Processor Units used in Apple's most popular devices. Last year, Apple paid £60.7 million in fees and royalties for the privilege. That accounted for about half of Imagination’s total revenue. This year the figure will be closer to £65 million.
But the deal will now end over the next 15 to 24 months, although legal wrangles and negotiations could ensue. In a statement, Imagination questioned Apple’s ability to bring the technology in-house without infringing on its intellectual property rights. It suggested that talks were now focused on “potential alternative commercial arrangements for the current license and royalty agreement.”
But Apple isn’t just Imagination’s biggest customer, it’s also one of its biggest shareholders, with a reported stake last year of 8.48%. Indeed, just a year ago Apple confirmed that it had been in talks to buy Imagination, but those discussions apparently went nowhere. If Apple now starts selling down its stake in the company, it could put extra downward pressure on the price.
Strong momentum...
A sequence of profit warnings and poor interim figures wrapped up a dire year for Imagination in 2015. But a restructuring of the business helped the share price recover through 2016, and the stock ended the year up 88%.

Click here to see the Imagination Technologies chart
These changing fortunes were reflected in increasingly optimistic broker forecasts. Since last September, the broker consensus EPS forecast for 2017 has risen from 5.4p to 6.3p (last month).

Together, these two momentum indicators contributed to a rise in Imagination’s Momentum Rank from just 8 (out of 100) in January 2016 to 87 in February this year. The stock had clearly caught the attention of analysts and investors and its popularity was driving the share price.
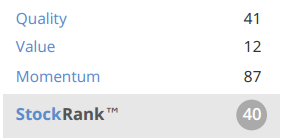
However, there were warning signs that this momentum was at risk in recent weeks. In March, brokers trimmed back their forecasts and the share price lost ground. As a result, Imagination’s Momentum Rank fell sharply to an unremarkable 55.
… but questionable Quality and Value
With a market cap of £761 million just prior to the Apple announcement, Imagination doesn’t fit the mould of the typical blue sky story stock. But it’s clear that hope played an important factor underpinning the price - as well as the presence of Apple as a major customer and shareholder.
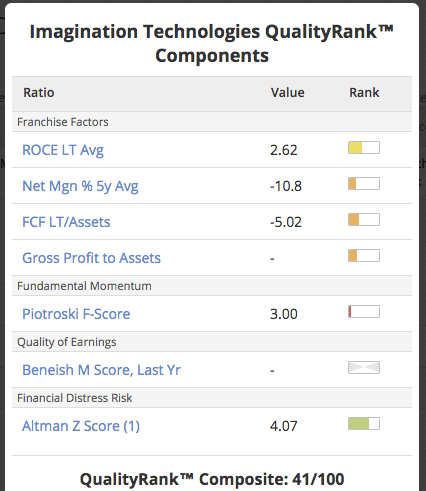
The company has posted net losses over the past two years, while earnings, margins and return on capital employed have all slumped over the past five years. Imagination achieves a lowly three out of a possible nine passes against the Piotroski F-Score of improving financial strength. As a result, it’s Quality Rank is just 41.
Yet despite these concerning quality scores, Imagination shares have consistently looked expensive. With a Value Rank of just 11, the stock is on the cusp of being one of the top 10% most expensive shares in the market. The strong momentum in the shares over the past year has exacerbated this.
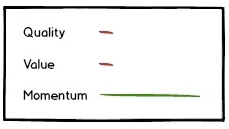
Put together, Imagination’s strong momentum but lacking quality and expensive valuation positioned it as a classic Momentum Trap. At the first sign of trouble, investors with high hopes and expectations were always likely to run for cover. The news that Apple is set to end its current arrangements with Imagination is perhaps their worst nightmare.
Stocks with this kind of single-factor exposure are often worth avoiding. With an overall StockRank of 25 before today, Imagination had very little exposure to the factors that have historically driven investment returns. In the absence of any momentum, it’s likely that it will sadly find itself in Sucker Stock territory in the near future.
You can find out more about some of these themes with this article on the perils of Momentum Traps, as well as this overview of all the StockRank styles, plus Ed's webinar on them here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
22 comments
RNS released this morning by the company relating to sale of MIPS business and confirming Canyon Bridge approach. Buried at the bottom of the release is the comment that another offeror is still in the wings and hasn't yet declared its hand. Add this to speculation that Imagination Technologies (LON:IMG) is considering a law suit against Apple for various patent infringements etc., and is potentially now bankrolled by a well funded backer (the People's Republic of China) which changes the balance of power and one could infer Apple might be the party in the wings and this could turn into an interesting contested bid as Apple looks to settle by buying Imagination Technologies (LON:IMG) rather than getting bogged down in expensive litigation process. Then again, could just be me adding 1 + 1 and getting 5. One to watch ...
Gus.
---------
Imagination Technologies Group plc
Sale of MIPS and update on Formal Sale Process
Sale of MIPS
Imagination Technologies Group plc (LSE: IMG, "Imagination", "the Group"), a leading multimedia, processor and communications technology company, has agreed to sell its worldwide MIPS CPU business ("MIPS"), including all MIPS Intellectual Property ("IP") and patents, to Tallwood MIPS Inc, a company indirectly owned by Tallwood VC of Palo Alto, CA ("Tallwood") for a total consideration of $65m in cash.
Tallwood is a Silicon Valley-based venture capital firm with years of experience in the semiconductor industry.
As separately announced today, Imagination has also reached an agreement on the terms of a recommended offer for the Group at 182p per Imagination ordinary share.
The sale of MIPS is on a cash and debt free basis and subject to customary adjustments. $40m of the proceeds are payable in cash at completion and $25m in cash six months after completion.
The sale is conditional on shareholder approval (if required under Rule 21.1 of the Takeover Code) and on the completion of the corporate reorganisation to separate MIPS from the remainder of the Group. Completion of the sale is expected to occur in October 2017.
Following completion of the transaction, cash proceeds will be used to reduce the Group's debt, with the balance applied for general corporate purposes.
Andrew Heath, Chief Executive of Imagination, said:
"This transaction, which is separate to the offer for Imagination by Canyon Bridge, will ensure MIPS remains an independent licensing business.
"MIPS has gained notable momentum over the last year or so having secured a number of design wins, and made good progress towards profitability.
"This significant progress, allied to Tallwood's investments in the semiconductor industry, will provide increased customer choice and new job opportunities based on the continued growth of the MIPS business."
Update on formal sale process
Imagination announced on 22 June 2017 the commencement of a formal sale process under the Takeover Code in respect of the Imagination Group and engaged in discussions with a number of potential purchasers.
Further to the announcement today of the terms of a recommended cash offer for the Imagination Group and the disposal of MIPS referred to above, the formal sale process under the Takeover Code in respect of the Imagination Group and the sale processes for MIPS and Ensigma businesses have now been concluded. One party has not confirmed whether its interest in the Imagination Group has terminated and accordingly it remains a potential offeror for Imagination for the purposes of the Takeover Code.
Accordingly for so long as this party remains a potential offeror, the Company is required to seek shareholder approval for the sale of MIPS at a General Meeting for the purposes of Rule 21.1 of the Takeover Code. A circular is expected to be posted to Imagination shareholders shortly.
Reports overnight that Canyon Bride (the Chinese backed fund that Trump recently dinged from buying a US technology company in the interests of "national security") has offered 182p share in cash. Decent result for employees and short term speculators, maybe less so for longer term holders out of the money.
Gus.
Imagination reminds me a little of Volex who fell out of favour when apple dropped the connector used on early I-phones.
So the stock price was pumped up partly by people who thought the association with a high profile company like Apple was an asset, but also by many who saw how the stock price was moving, asked themselves "How could they all be wrong?" and thought they'd better jump aboard. The surge was unrelated to any qualities intrinsic to the company itself.
This is what used to be concisely summed up by the word "bubble".
Imagination was not just a Momentum Trap, but basically a poor quality business from a business perspective view. Over reliant on one customer, operating in a sector (electronic hardware) that is very vulnerable to sudden shocks, poor recent profits, over-emphasis on EBIT, etc. I wrote an article on the ShareSoc blog yesterday on the subject. See: https://sharesoc.wordpress.com/2017/04/04/imagination-technologies-and-why-you-should-avoid-such-companies/
Interestingly Purplebricks (LON:PURP) comes up as a Momentum Trap.
Interesting thread, thanks Ben. It has prompted me to look through my portfolio to see if there are any potential momentum traps (not a phrase I have heard before). While I have a lot of high M scores, they are mostly accompanied by high Q scores (although often by low V scores too). The two that fall short of this are Impax Asset Management (LON:IPX) (V26, Q75, M99) and IQE (LON:IQE) (V23, Q38, M99).
I regard Impax Asset Management (LON:IPX) as a long-term hold based on my qualitative research. They are in an interesting space, growing AuM at a very respectable rate and diversifying geographically. I suspect their Q score will rise over the next couple of reporting periods and as they pay a decent divi, riding out any short-term price volatility shouldn't be too challenging.
IQE (LON:IQE) on the other hand seem to have all the hallmarks of a momentum trap as explained in this article. I am not a long-term holder of this company, although happily sitting on a 30% gain from around 2 months ownership. Logic would suggest it might be time to bank some profits. However, in 2016 they invested heavily in Capex to increase their production capability - for what? There is plenty of speculation that IQE's VCSEL technology will be used in the new generation of Smartphones (iphone 8?). Something of an inverse parallel (for now) to the problems being encountered by Imagination Technologies (LON:IMG). Certainly, there is high risk in holding IQE - amplified by the news yesterday from IMG.
The other point raised by this discussion is the dependence on a dominant customer. Zytronic (LON:ZYT) (which I hold) carries this type of risk, although they are trying to expand their footprint and sales channels. Certainly something to keep a close eye on for those of us holding this share (V58, Q91, M76). Some further food for thought as I look to rebalance my portoflio as we enter the new tax year.
Thanks again for a thought provoking article.
So I've been scratching my head wondering why people would have invested in this stock.
If you're a quant investor then I don't know how you ended up in this stock.
For me, I'd be looking for at least two of the QVM ranks > 80.
Some might say ... "It's just appreciated 88% from it's multi year low in 2016"
"So what" is my reply.
There are numerous other stocks that have appreciated > 88% with a much better risk profile.
A post digging into the performance of the top decile of stockranks a few years ago indicated that a basket of stocks from that decile didn't necessarily outperform lower deciles (in terms of number of winners or their gain %age) BUT they did have significantly less (I think it was zero in the data that was studied) stocks that exhibited a catastrophic reduction in the share price (which I think was defined as > 30%) which dragged down the overall performance.
For me the takeaway from that post was "Fish in the statistically safer pond"
Apologies it was 3 stocks from the top decile that had lost > 30%.
Here's the post from Ed and the whole post and thread is interesting.
http://www.stockopedia.com/content/a-gratuitous-de...
Just to keep everyone in the loop, we're working on StockRank style categorisations for the whole market. It's been quite a heavy R&D project for us, and not as simple as using strict 60/40 cutoffs. We've delved into all kinds of modelling processes using data science, fuzzy cluster algorithms, 3D cubes & cylinders and pipe cleaners in our search.
We've finally settled on a solid system and are computing StockRank styles for the whole market. Next step is to add them into the StockReports... am not sure whether they will make it into this version of the site, but they will in the new version.
Anyway, long story short, Imagination Technologies would certainly have been labelled a "Momentum Trap". We're using a tolerance level which labels about a third of the market in winning styles, a third in losing styles and a third unclassified or style neutral. It's quite a broad style categorisation, so I wouldn't use it on its own for portfolio construction, but the style categorisations do provide a new data insight into many stocks.
If you don't know what I'm talking about...
- Original blog - http://www.stockopedia.com/content/towards-a-taxon...
- Webinar - http://help.stockopedia.com/product-guide/stockran...
Ed - In your blog " Towards a taxonomy of stock market winners" I can't seem to find a category or profile that defines "Momentum Trap" . Should I be looking somewhere else for this?
Actually - I called it a glamour trap in the original blog...
Actually we're working on volatility classifications too... Imagination Tech would have been labelled a "Speculative, Mid Cap, Momentum Trap" in our classification pre-fall.
Hi Ed,
How are you arriving at the label speculative and what are the alternative labels?
Thanks in advance
Phil
It's a simple volatility classification... we're using up to 10 year price histories for the volatility rating... but making some crafty adjustments to normalise rarely traded securities or those with short histories.
We've been discussing either 4 way or 5 way classifications... and probably heading towards 4 classifications. Currently looking at conservative, moderate, aggressive and speculative as labels. Would be interested in feedback.
The reality is that 'conservative' is still anything up to a 25% annualised volatility - which isn't exactly conservative ! All stocks are speculative, but less so once diversified.
(The actual volatilities will be available too).
Whenever my stocks turn into MomentumTraps (for me that means only MomentumRank > 80) I tighten my notional stop losses and look to take profits and close out the position. This can be hard as often they've been big winners.
An example where I proactively sold 50% of my stock before any stop loss was breached was one of my biggest winners Corticeira Amorim (the Portuguese Cork producer). Quarterly results came out in Feb and in late March the quality rank dropped and the price wavered around the ominous £10 mark. Despite it being one of my best performers (+254%) I decided to immediately sell 50% as it was too big a position to let it just run given the warning signs. I tightened my notional stops on the remaining 50%. The price has subsequently rallied without breaking the tightened stop loss so I still hold 50% of my original position and I hope it can continue to appreciate despite the reduced quality rank. Time will tell.
Commiserations to the holders of Imagination Technologies (LON:IMG).
Phil
I do hold COR as well. I'm struggling to understand why the QR has fallen when many of the Q criteria such as ROA, ROCE, ROE, has improved considerably, up about 80%. Debt has almost halved. Gross margin is the same as last year but Op. margin is up 80%.
Realistically, I doubt many would have caught this one. I'd say diversification is the main takeaway!
Peter
I think the key takeaway here is not so much being wary of momentum traps but being wary of businesses with just one or a very small number of large customers.
Lesson here may also relate to companies reliant on intellectual property, again compounded by a large customer with deep pockets. As Imagination Technologies (LON:IMG) shareholders found out to their cost, the primary asset (key personnel) can simply up sticks and relocate to the customer taking the IP with them in their heads.
Also, patents and copyright are fine in principle but due process is notoriously expensive and time consuming ( especially in the US) and however good your case, you still need significant resources and willpower to take the Apples of this world on. Maybe worth a call into Burford Capital (LON:BUR) if the management feel they do have a watertight case on copyright infringement!
Gus.
You see "momentum" is a dirty word in investing!!! I remember lots of other once great stocks that had "momentum" and then crashed and burned suddenly (Carter and Carter). Momentum can be a dangerous way to get into fashionable areas of the market that blow up. It can potentially add value but I think it should be treated with extreme caution.
Just my view as I know many on Stockopedia would have a different view. Also fair enough that the quality and valuation filters on Stockopedia picked up Imagination as weak.
Imagination - I was never a big fan of this given that it didn't appear to have core technology for mobile devices. ARM by contrast designed the core low power processing chip. Imagination designed graphic chips which aren't as important as the main processor.
I think height is bad.