SIF Portfolio: I review Judges Scientific and the IG Design placing

One of the characteristics of a screen-based approach to investing is that it may sometimes be difficult to find stocks which satisfy all of your criteria.
My Stock in Focus screen is a case in point. Only a few weeks ago, there were around 20 stocks qualifying for the screen at any one time. Since the EU referendum, that total has fallen dramatically. As I write on 26 July, the screen has hit a new low -- just four stocks qualify, three of which are already in the SIF portfolio.
The one stock remaining is Trifast. It’s an attractive enough stock but would push the number of Industrial stocks in the portfolio to 4/12. This seems too high to me, especially as Trifast isn’t massively cheap and forecast growth is relatively modest.
Instead of adding a new stock this week, I’m going to look at two other companies.
IG Design placing
Last week’s portfolio addition was packaging and giftware firm IG Design. No sooner had the virtual ink dried on my article than the firm announced a £5.25m placing. With a lot of companies this would be a cause for concern, but in this case I think it’s probably fairly prudent.
The cash will be used to help fund the recently acquisition of US firm Lang Companies (which I discussed here). The remainder will be used to fund investment in new manufacturing capacity in the UK and to increase the group’s capacity to make further acquisitions or investments.
The placing of 3,000,000 shares was done at 175p, which IG Design says was a 5.1% discount to the average mid-market closing price for the 5 business days preceding the announcement. That’s a pretty small discount. It’s encouraging to see that both new and existing institutional buyers were keen to take part.
The new shares represent dilution of 5%, which is fairly modest. The recent increase of 1.7p per share to earnings forecasts is being left unchanged following the placing, as management believes it can deliver this level of earnings per share despite the increased share count.

Overall, I share commenter Gus’s view that IG Design is fixing the roof while the sun shines and making the most of strong demand for its stock. The placing certainly doesn’t change my view on the IG Design, which will remain in the SIF portfolio.
Should you carry on avoiding Judges Scientific?
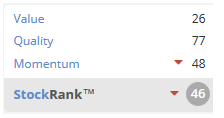
One of the biggest StockRank fallers of the last month is Judges Scientific. Judges’ StockRank has fallen from 62 to 46 over the last 30 days, mainly thanks to a plummeting MomentumRank score.
The decline isn’t surprising given the recent profit warning. But I suspect a number of investors may be wondering whether now is the time to bottom fish ahead of an expected recovery.
Judges’ latest profit warning indicated that full-year earnings would be “substantially below expectations”. Stockopedia’s consensus forecast has now been updated to suggest that a 10% reduction to about 100p per share is now likely. A similar reduction has been pencilled in for next year:
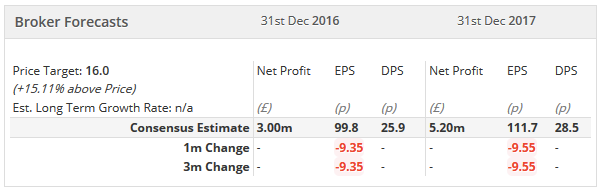
To me, 10% doesn’t seem enough to justify Judges’ use of the word “substantial”. News that orders at last year’s £9.6m acquisition Armfield are “well below the first half of 2015” are also a concern.
However, the firm’s two brokers will have taken a steer on their updated forecasts from management. The market also seems to have accepted this relatively benign interpretation of the profit warning.
Judges Scientific’s share price has climbed back from a post-warning low of about 1,250p to 1,400p. This gives a 2016 forecast P/E of 14 and a dividend yield of just 1.9%.
Given the uncertain outlook and the strong wording of the recent warning, this valuation looks quite full to me. Stockopedia’s algorithms also suggest the outlook may get worse before it improves. From a purely quantitative view, I believe Judges Scientific remains a stock to avoid.
One rank isn’t enough
The StockRank system has delivered impressive results over the last few years. Its founding principle is that a combination of Quality, Value and Momentum factors make a stock more likely to outperform.
High value pairings of two out of the three ranks can also do well, but the statistical evidence suggests high single ranks do much less well. Judges’ doesn’t meet the requirement for two or more high-ranking factors:
The low ValueRank makes it clear that there is very little historic value in the stock. Judges’ shares look expensive relative to historic earnings and have a low historic dividend yield. They trade at a high price-to-book value:
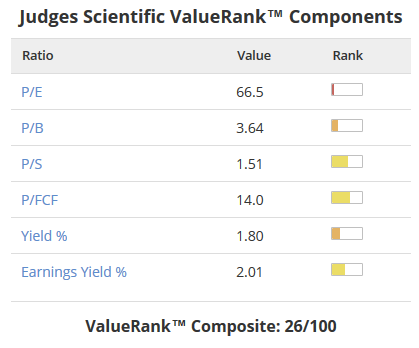
These figures tell me that any increase in the value of Judges’ stock is likely to be driven by future growth, not past performance.
A QualityRank of 77 is more reassuring. Management seem to have been able to generate strong free cash flow and gross profit from the company’s assets in the past. The Piotroski F-Score of 6 is also relatively reassuring:
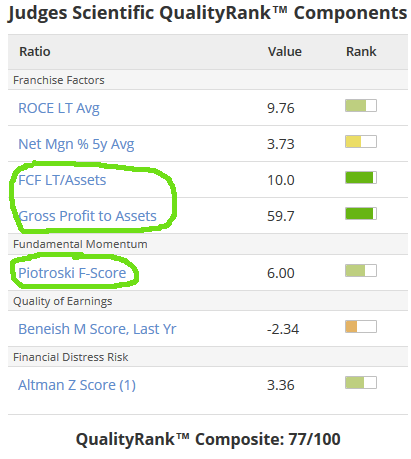
The problem is that these quality factors are backward-looking. As yet we don’t have any obvious catalyst for future share price growth.
This role should be fulfilled by momentum, which when combined with high quality can deliver very strong results. But Judges’ recent profit warning has put a spanner in its MomentumRank, which has fallen from 80 to just 48 since the start of July. Here’s why:
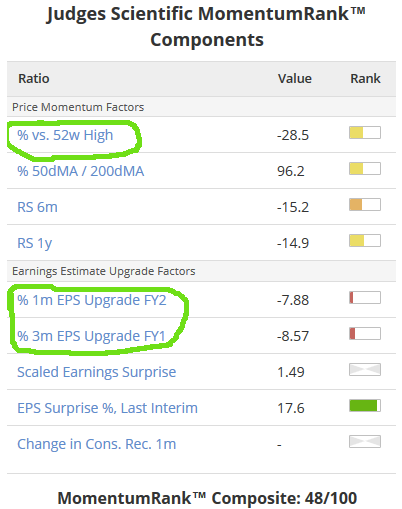
The shares are well down from their 52-week high. Earnings estimates for this year and next year have been cut over the last three months.
A falling star
High quality needs strong value or momentum credentials in order to be attractive. Judges Scientific has neither.
In my opinion, there’s a real risk that Judges’ problems will continue. The stock may now be a falling star, a former high flyer whose powers are fading.
Paul Scott rightly comments that Judges Scientific has a good quality management team. They may turn things around. But it’s not a risk I want to take with my own money, or with the virtual cash in my SIF Portfolio fantasy fund.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

2 comments
Judges should benefit from the recent 9% fall in sterling
We should hot forget that the CEO has a strong record of good management, sound conservative buying, understatement, under-promising and over delivering.
For all these reasons I reckon Judges should remain a long term hold.
Sniggolb,
You could absolutely be right.
My appraisal is based (deliberately) on the figures and StockRanks only, to provide a quantitative view of the stock in keeping with the Stockopedia methodology.
Only time will tell which of us is right!
Regards, Roland