SIF Portfolio: Is IG Design a gift at this price?

This week’s addition to the portfolio is giftware firm IG Design. This company was until recently known as International Greetings.
As with last week’s addition, IG Design meets both my screening criteria and those of the Jim Slater ZULU Principle screen. It also qualifies for the Value-Momentum Screen and the Robbie Burns-inspired Naked Trader-esque Screen.
I was interested to see that while each of these three guru screens uses different criteria, they have all delivered annualised returns of about 18% since their inception. Another point worth noting is that these three screens all have broadly similar ethos.
All look for fast-growing stocks with good fundamentals, at a reasonable valuation. Such high flyers and super stocks can continue growing far longer than expected. The kind of stock that can beat the market over long periods.
A potentially big market
IG Design also scores well with Stockopedia. At the time of writing, the company has a StockRank of 97. Paul Scott was also impressed in his latest write-up.

Although it may seem odd to add another stock from the Containers & Packaging sub-sector to the SIF portfolio alongside Macfarlane, I think the two companies are different enough to make this acceptable.
Whereas Macfarlane makes postal packaging for consumer goods companies, IG Design is focused on giftware and in markets all around the world. IG Design sells through a portfolio of its own brands, alongside licensed ranges such as Thomas & Friends and Disney’s Frozen.
Another attraction is that less than 40% of IG Design’s revenues come from the UK:

Although the weaker pound will make dollar-denominated imports from China into the UK more expensive, IG Design said in its recent results that it’s “well hedged into 2016/17”. Earnings in the US and Europe will also translate more strongly into sterling than before the referendum.
Overall, I’m confident that IG Design is relatively safe from Brexit fallout, unless the economic impact becomes much more serious than currently seems likely.
Well-timed acquisition could boost growth
IG Design shares have risen by 133% since the start of 2015, which might suggest that most of the upside is in the price. But earnings rose by 13% last year and are expected to climb by 23% this year. The group also announced an acquisition in the US last week which could add further upside potential.
Lang Companies Inc designs and supplies “branded consumer indoor and outdoor home decor and lifestyle products”. The group had turnover of $34.4m last year and estimated EBITDA of $1.25m. Like IG Design, Lang operates its own brands and has licensed ranges which include NBA and NFL-branded gift items.
IG Design believes significant cost-savings on sourcing will be possible from next year. The figures I’ve mentioned above suggest that Lang could easily add around 10% to IG Design’s turnover and profits. As Lang operates in US dollars, the pound’s recent decline should provide a further boost to IG Design’s reported profits (in sterling) from this business.
Still good value?
Even the best company in the world is only a good buy at the right price. IG Design’s ValueRank of 69 suggests to me that it could be good value, but not a bargain.
A look at the figures suggest this is a reasonable assessment. IG Design trades on 15 times trailing earnings but on a far more impressive 8.5 times trailing free cash flow. The earnings yield of 9.1% is reasonable although not outstanding, as is the 2% dividend yield.
My love of free cash flow knows no bounds, but when presented with a P/FCF that’s much lower than the equivalent P/E, I do like to look more closely. One-off factors can sometimes inflate cash flow in single years.
In this case, IG Design’s cash flow generation was boosted by a £3.4m reduction in working capital last year, despite rising sales. However, the group’s free cash flow last year was £13.8m, even after £4.3m of acquisitions.
In other words, even if the working capital reduction was stripped out, free cash flow would still have been around £10m last year. That would have covered total interest and dividend costs of c.£3m by more than three times, which is reassuring.
Solid quality
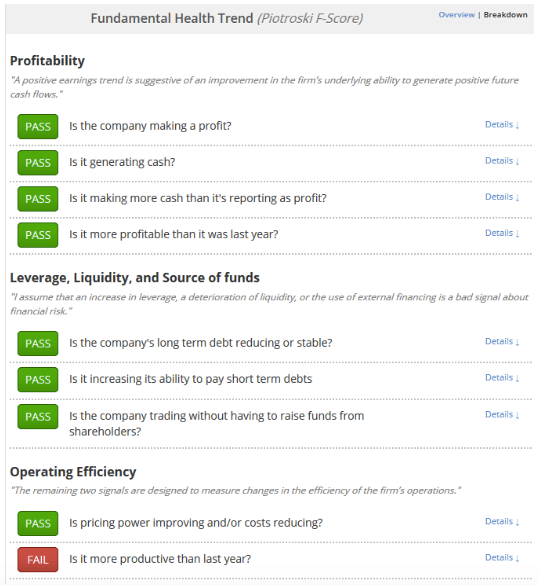
IG Design’s highest rank score is its QualityRank of 91. This is largely thanks to a near-perfect Piotroski F-Score of 8 out of a possible 9:
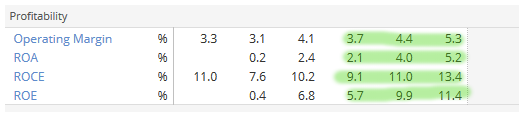
As you’d expect, profit margins are not especially high on the firm’s products. IG Design’s 5-year average net margin is just 1.7%, according to Stockopedia. But the average return on capital employed over the same period was a more impressive 10.4%. ROCE has risen in both last last two years:
IG Design’s own measure of net debt was £17.5m as of 31 March, when its financial year ends. Stockopedia takes a different view, reporting net debt of £30.9m.
The difference between these two figures appears to be £13.7m of current year liabilities which appear on IG Design’s balance sheet under “other financial liabilities”. The bulk of these (£12.0m) are classified as “other creditors and accruals”. It’s not entirely clear to me what these represent, but given that they are due for repayment during the next twelve months, it seems prudent to include them with the firm’s borrowings.
On that basis, I’d classify IG Design’s debt levels as acceptable but not optimal (from a shareholder perspective). With net debt of roughly four times last year’s post-tax profits, I’d like to see further reductions in borrowing.
Fast-moving momentum?
IG Design’s MomentumRank has risen from 60 to 84 over the last 30 days. The most obvious reason for this is the 13.2% hike in forecast earnings which followed the Brexit devaluation of sterling (and the group’s results) at the end of June.
The shares’ momentum now looks attractive on all fronts:
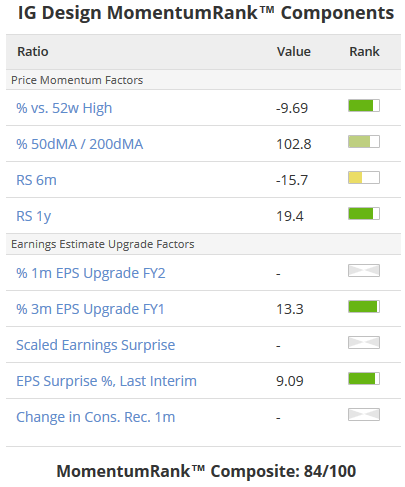
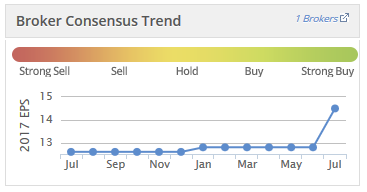
IG Design beat expectations with its last results. Expectations for the current year are also improving.
Price momentum is strong, too. The stock is less than 10% below its 52-week high and both relative strength and momentum are strong:
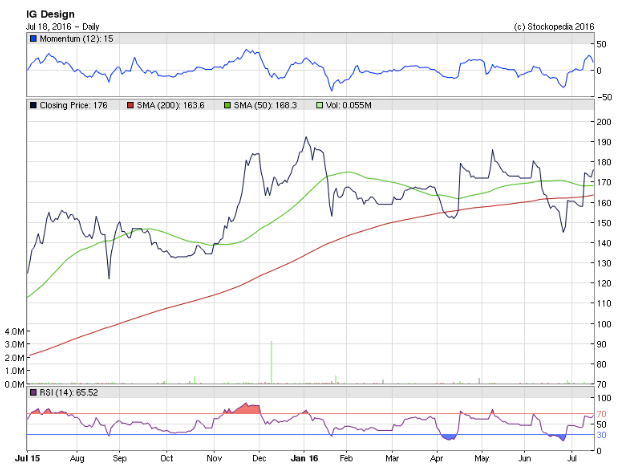
IG Design is in
I have to admit that investing in a stock that’s already delivered such a long run of growth does make me slightly nervous. But all the evidence suggests to me that this strong performance could continue. The group seems able to act as a consolidator in a fragmented market that only seems to grow each year.
I will be adding IG Design to the SIF portfolio on Wednesday. If you’re a shareholder -- or if you’re not -- leave a comment below and let me know your thoughts.
As always, this article is my opinion only. Please DYOR before making any trading decisions.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

8 comments
A +ve write up in MIDAS today highlighting IG Design (LON:IGR) manufacturing and sales diversification, which will benefit the company if sterling stays weak against the dollar.
Cards now make up <9% of sales with other stationary related buys filling the void. IGR has had a good run recently as the market recognized its earnings potential, but on a EV/FCF of 13.9 it still looks resonable value to me. Ian
http://www.dailymail.co.uk/money/investing/article...
Excellent summary of the case for investing in the company. I have been a holder for about 10 months topped up after the Brexit referendum wobble and happy to continue holding.
Good sign that the share price edged up slightly today notwithstanding the announcement of a placement of 5%/3 million shares at a discount of 175p. Likewise, didn't appear to be any material pre-placement selling by insiders dragging the share price down last week that is often the case with other AIM shares.
Gus.
Hi Roland,
Possibly a Stockopedia software point, rather than one strictly for you, but the broker consensus trend graphic above shows April being the same as March and May. However, the broker consensus trend graph on the Stockreport as of today, shows a spike for the EPS being forecast in April, of going up to 13.50 for April, before coming back down to 12.80 again for May.
Do you have any idea why there is the difference?
Ta
Chris
Hi Chris,
Interesting question! I've no idea about this, to be honest.
The screenshot I used above was taken a day or so before the article was published, i.e. 17/18 July. I wouldn't have thought historic broker forecasts for April would have been updated in the way the changed graphic implies.
I'll ask the question and put an update here if I find out more.
Regards,
Roland
Roland,
I am a holder too and like the metrics for this company. In relation to the F Score of 8/9 vs. a perfect score 9/9, IG shows as close as it is possible to be to a 9. It Fails the Asset Turnover test, but if you click though for the detail the actual difference is insignificant 1.66 vs. 1.67 (<1%).
IG Design Details: Asset Turnover (Piotroski) = 1.66 , Asset Turnover (Piotroski), 1y Ago = 1.67So effectively 9/9 F Score, modest PER, exposure to the diverse export markets, well hedged short term, increasing broker upgrades and 52 Week high momentum makes this a high probability winner to me. Ian
Hi Ian,
Yes, it's often the case that the fails in the F-Score test are only marginal -- it's always worth having a look to check for yourself.
Regards, Roland
I think the recent placing knocks 1 off the Piotroski score.
I don't really understand the need for the placing.
I sense it was a case of fixing the roof while the sun shines. As per the recent SCVR from Paul,
http://www.stockopedia.com/content/small-cap-value-report-29-jun-2016-igr-bram-zzz-140051/ ,
the balance sheet debt levels are "satisfactory" and given the recent good run in the share price and plans to grow the business with new investment (as per the Placement RNS) it probably makes sense to issue some fresh equity at a decent price to give a bit of wiggle room. Seems prudent in my opinion.
Best,
Gus.