SIF Portfolio review, plus PSN, GOG, IGR & PAF

As the summer ends, results season is drawing to a close. The outcome for the SIF Portfolio has been fairly positive, in my view, with several H1 laggards making up lost ground over the last few weeks.
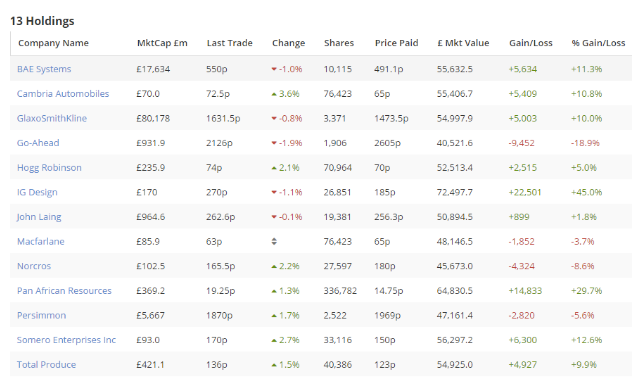
The portfolio now contains thirteen stocks, so is well on the way towards my target of 15-20 holdings. Monthly rebalancing will start in late October, when my first holdings reach six months of age. Ahead of that, I’m going to review results from some of the portfolio’s biggest movers, and ask how well the SIF portfolio is matching its brief. This was:
Affordable growth. A blend of value, growth, quality and momentum. Hopefully with an emphasis on managing risk through diversification and the avoidance of outliers.
Here’s a snapshot of how the portfolio looked after markets closed on 6 September:
The story so far
Alongside the official Stock in Focus Portfolio fantasy fund, I also maintain a portfolio in the Folios section of my Stockopedia account that mirrors the fantasy fund. The benefit of this is that I get to benefit from a greater level of reporting and analysis.
Here’s a screenshot from the Analysis tab of the portfolio, which give an idea of the overall characteristics of the SIF portfolio:
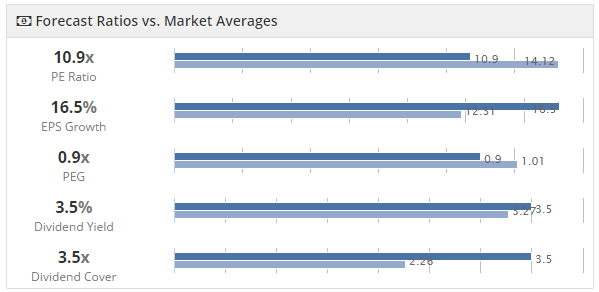
The dark blue lines represent the SIF portfolio, the pale blue is the market. These show that the forecast P/E of the portfolio is below the market average, while forecast earnings growth is above average. These combine to give an attractive PEG ratio of 0.9. I’m also very happy with the 3.5% portfolio yield, which is well covered by forecast earnings.
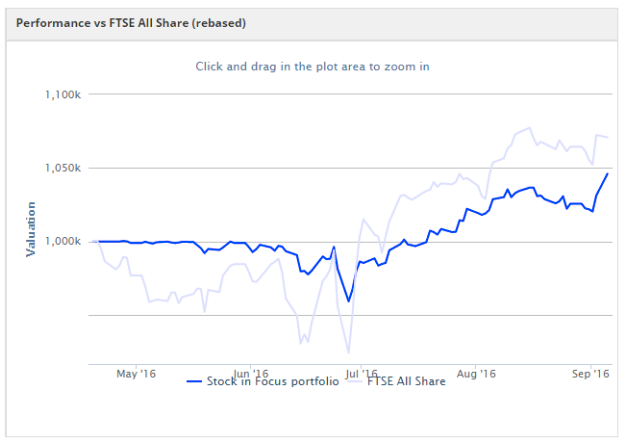
Given my target profile of affordable growth, I’m pretty happy with this profile. Although the portfolio is still too young to draw any conclusions, it doesn’t contain any stocks that make me uncomfortable. Performance so far has lagged the benchmark FTSE All Share, but with so few stocks in the portfolio at first, this was to be expected (in my view).
Results review
Eleven companies have issued trading updates or results since they were added to the portfolio. I’m not going to try and cover them all in the space of one column -- instead I’ll focus on the best and worst performers so far.
Go-Ahead Group (-19%)
My decision to add bus and train operator Go-Ahead to the portfolio was poorly timed. The FTSE 250 firm’s shares fell by about 20% shortly after, when Go-Ahead warned that future profit margins on its Govia Thameslink franchise would be lower than expected.
However, the firm’s statement stopped short of a profit warning. Last week’s results seemed to confirm that problems with this troublesome franchise -- which includes Southern Rail -- haven’t done much damage to profits.
Adjusted operating profit for bus operations climbed 8% to £100.4m, while rail adjusted operating profit climbed 37% to £57m. Net debt was broadly flat and the full-year dividend climbed 6.5% to 95.85p, giving a trailing yield of 4.5%.
Go-Ahead looks cheap enough to me, on 11.3 times forecast earnings and with a price/free cash flow ratio of 9. I’m certainly happy to continue holding at this level.
Persimmon (-6%)
Housebuilder persimmon was another large stock that fell heavily shortly after joining the portfolio thanks to the EU referendum.
The shares have recovered somewhat since then, and are now down by just 6%. Persimmon’s recent interim results confirmed my view that it’s one of the more attractive housebuilders at present. The group’s £1.75bn order book is equivalent to around seven months’ sales, while its £462m cash pile is equivalent to 149p per share, comfortably covering next year’s planned capital return of 110p per share.
Personally, I have reservations about housing stocks. I believe the data and commentary that’s emerged from the results season are starting to hint at a slowdown. But this is far from certain. We won’t really get a clear picture until later this year. In the meantime, Persimmon shares look about right to me, on 10.5 times forecast earnings and with a forecast yield of 6%.
Pan African Resources (+30%)
Gold has been on a tear this year. My addition of South African miner Pan African was well timed. The shares have pulled back from their August high of 24p, but remain one of the strongest performers in the portfolio.
Although the complex interplay of exchange rates and the risks of running a mining company in South Africa still concern me, Pan African’s performance so far this year has been strong.
Broker forecasts have been steadily upgraded. The shares look good value despite their gains, on 10.5 times forecast 2015/16 earnings, falling to 6.2 for 2016/17. Minimal debt and a fast-rising yield are also attractive. If you believe gold is likely to remain stable at current levels -- as I do -- then these shares still look attractive, in my opinion.
IG Design (+45%)
Top performer so far is giftware group IG Design, which has risen by 45% since joining the portfolio on 20 July!
I don’t take credit for this stunning performance, as I simply added the stock to the portfolio when it appeared in my screen. I’m not sure my timing would have been so good had I not been prompted in this way.
In any case, IG Design shares have rocketed higher since the firm’s full-year results were announced on 29 June, along with details of a US acquisition. Adjusted earnings rose by 15% to 13.2p per share last year, and are expected to climb further this year.
However, the shares’ rapid ascent means that IG Design now trades on a forecast P/E of 18. That seems fairly full to me, so further gains may depend on whether broker forecasts are upgraded as the year progresses. This is something Paul Scott thinks may be possible, after a bullish Q1 update.
What about the rest?
At the time of writing (on 6/9), four other stocks have delivered gains of 10% or more since the portfolio was started. BAE Systems, Cambria Automobiles, GlaxoSmithKline and Somero Enterprises have all posted double-digit gains. These are the result of a mixture of strong results, exchange rates and improved sentiment. Total Produce is also within a whisker of double figures, up 9.9%.
The only notable faller I’ve not covered is Norcros, which is down by 8.6%. There’s no obvious reason for this, as the firm has delivered two strong trading updates since joining the portfolio. Norcros stock now trades on 6.3 times forecast earnings, with a forward yield of 4.3%. I’d be happy to add more at current levels, if this was permitted.
I’ll get back to stock analysis next week. In the meantime, please share your views on these stocks or any of the others in the portfolio in the comments below.
Disclosure: Roland owns shares of BAE Systems and GlaxoSmithKline.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

7 comments
Hi Roland,
Good work with the portfolio.
I was wondering how you managed to chart the Performance vs FTSE Allshare? Is there an option to do this in the folio section?
Paul
Hi Paul,
Thanks for the comment. All Fantasy Fund portfolios are tracked against a benchmark, which I've chosen to be the FTSE All Share.
This functionality isn't currently available in the Folios section of Stockopedia. That's one reason why I run this portfolio as both a Fantasy Fund and in the Folios section of my account -- both offer different analytics. The Fantasy Fund is also public, so I can share it here.
You can find out more about the Fantasy Funds here:
http://www.stockopedia.com/fantasy-funds/
My SIF portfolio fantasy fund is here:
http://www.stockopedia.com/fantasy-funds/stock-in-focus-portfolio-6449/
Hope this help!
Roland
Rolan,
Thanks for the reply. It's a shame the feature isn't available in the folio section as this is where I keep my real portfolio. I will lodge a request for it as it is a good feature.
Paul
Roland
Many thanks for the interesting update. I am looking forward to your October rebalancing with interest.
I hope you will explain, in some detail, how you approach assessing the status of the holdings with regard to your criterion, and then your rationale with regard to your decisions, be they to sell whole holding, slice, hold or add to. As I am keen to learn ideas about this aspect of portfolio management. Particularly as your investing objectives seem to align closely with mine (I hold 7 of the same stocks as your SIF).
Regards
Howard
Howard,
Thanks for your comment. In essence this is a rules-based portfolio which uses a screen to pre-select shares. You can see the full set of rules I work to here:
http://www.stockopedia.com/content/introducing-the-stock-in-focus-portfolio-128456/
When it comes time to rebalance, I will sell shares which no longer qualify for the screen. The only situation in which I would top slice is if a share doubles during the holding period.
I'm basically running this portfolio in a similar way to the Stockopedia Guru Screens. The only difference is that I am allowed a certain amount of freedom to select which stocks to buy and pursue a minimum level of diversification. I will also start rebalancing after six months, rather than quarterly.
Finally, I should also reiterate that this is not my personal portfolio, it is a model portfolio I'm running and developing for Stockopedia. I do own some stocks in the portfolio (which I disclose) but not all.
I hope this makes things a bit clearer.
Regards,
Roland
Roland
Thanks for the rapid response and explanation, I look forward to seeing what occurs in October.
Regards
Howard
Seconded.