Small Cap Value Report (16 Sep 2019) - Black Gold, ESL, GLE, HAT/RFX, FIF, LTG, ALFA

Good morning,
Timings - I have a lot of other work commitments every day this week, so I plan to write these reports very early - just so you know!
RNS announcements on my radar today (list is growing):
- Eddie Stobart Logistics (LON:ESL)
- MJ Gleeson (LON:GLE)
- H & T (LON:HAT) / Ramsdens Holdings (LON:RFX)
- Finsbury Food (LON:FIF)
- Learning Technologies (LON:LTG)
- Alfa Financial Software Holdings (LON:ALFA)
Black Gold
Brent crude was up as much as 19% overnight, with a high around $70 (versus a close of $60 on Friday). It has dropped back as of now to c. $65.50.
Drone strikes on Saudi Aramco knocked out 50% of Saudi Arabia's oil production, or 5% of total daily production, according to an expert quoted by CNBC.
Oil stocks might be fun this morning!
8.15 update: Royal Dutch Shell (LON:RDSB) is up 3%, BP (LON:BP.) is up 4%, Gulf Keystone Petroleum (LON:GKP) is up 6%.
Eddie Stobart Logistics (LON:ESL)
- Share price: 71p (suspended)
- No. of shares: 379 million
- Market cap: £269 million
This company had a nightmare RNS last month, announcing that its CEO was standing down with immediate effect, that revenue recognition needed to be more prudent in future, and that profitability would therefore be "significantly lower".
On top of all that, the shares were suspended (pending clarification of the company's financials).
Interim Results
In the previous update, the company said that it expected to release interim results in early September.
It hasn't published them yet, and doesn't give a new forecast of when they might be out. Instead, it merely says that it will publish them "following further clarity"!
As far as the H1 results are concerned, ESL says it expects revenue of £450 million and underlying EBIT of £10 million to £11 million.
Context: in H1 last year, ESL produced revenue of £359 million and underlying EBIT of £18 million.
Full-year outlook
Three bullet points are given for the company failing to meet expectations this year:
· An adverse performance against an ambitious budget alongside delays in the implementation of operational efficiencies;
· Provisions made against customer recoveries, a significant proportion of which relate to underperforming contracts which have been exited during the year; and
· Delays on a significant property consultancy project and lower than planned property utilisation.
Counting the above, it looks like at least 5 reasons to me.
When I see something like this, I tend to think that something worse than bad luck is responsible for it.
Given the abrupt and recent departure of the CEO, and the fact that the treatment of contracts has been questioned and found wanting, I am inclined to think that previous management gave a very unrealistic picture to the Board and to shareholders. It could be that they were simply too ambitious but, for whatever reason, there was a severe mismatch between what the Board thought was possible versus reality.
Avoiding accident-prone companies and sectors is an important part of what I try to do with my own portfolio. I've never invested in logistics companies and having seen so many problems occur at them, the truth is that I have no real desire to!
If a Board of Directors are unable to figure out the true financial performance of their own company, then how on earth are minority shareholders supposed to figure it out?
Anyway, let's scroll on to see how this RNS finishes:
Steps taken - the company is conducting a "wide-ranging review" - ok.
Capital structure - the dividend is cancelled. ESL's balance sheet has been negatively impacted by the growth of the business (!), by a reduction in EBIT, poor cash collection and excessive dividends. Net debt has grown from £155 million as of the end of H1. ESL is therefore considering raising new equity.
Offer update - DBAY Advisors, which is a 10% shareholder in ESL, has sent in "a preliminary expression of interest". It might make an offer for the entire company, or it might not!
My view
Firstly, some speculation on the offer - if ESL needs fresh equity, this could provide an opening for DBAY to make an opportunistic (cheap) bid.
DBAY could offer to take out other shareholders and to recapitalise the company at the same time, replacing its debt load. They might not need to pay too much for the existing equity, unless other shareholders are willing to cough up funds for the recapitalisation, too.
Studying logistics companies in recent years, I have found that they suffer misfortune of one kind or another all too often. It's an example of a B2B, contract-driven sector where I sleep better by not getting involved. Those investors who have some sector expertise might do well with the right company (e.g. Clipper Logistics (LON:CLG) hasn't made any terrible mistakes - long may it continue!) but finding that right company strikes me as difficult.
The equity value at ESL is highly uncertain now, not least due to the fact that a fundraising of one sort of another is coming. We don't know how desperate the company is for fresh equity, and we don't know the terms at which it might be offered. So the financial prospects for shareholders could be anything from "not bad" to "dire".
MJ Gleeson (LON:GLE)
- Share price: 845p (-0.6%)
- No. of shares: 54.6 million
- Market cap: £461 million
Slightly larger than our traditional cut-off, let take's a gander at results from this housebuilder and "strategic land specialist".
Headling numbers are good:
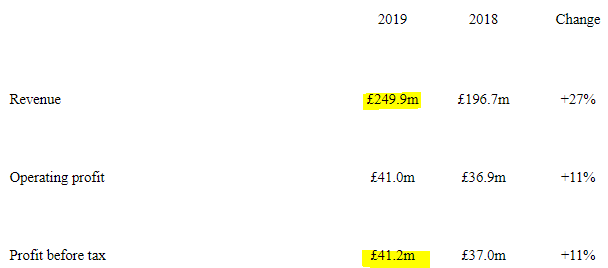
The company reports its ROCE - good!
ROCE falls from 26.% to 25.9%, which is less good, but it's still very high on an absolute basis.
Note that Stockopedia thinks Return on Capital is a bit lower, at 22% (this is not uncommon, as Stockopedia uses unadjusted numbers).
Housebuilding is a very lucrative activity, when conditions are right. When conditions are wrong, of course, profitability can collapse.
For now, conditions are pleasant and Gleeson continues to make hay.
In the homes business, volumes are up 25% (1,529 units) and operating profit up 15% (£30 million). The pipeline has grown, too - very important. The company is looking for the number of units sold to increase by another ~33% by 2022.
The "strategic land" division has also done well, and the Board has decided to keep it rather than sell it:
The division had a record year and continues to benefit from high levels of demand for consented land in prime locations from both large and medium-sized housebuilders. The division has a strong portfolio of sites and anticipates that it will continue to maintain its successful track record in promoting potentially high value developments through the planning system.
Market context
Some interesting tidbits here.
1) Young first-time buyers and low income families in the in the North of England continue to access mortgage finance on attractive terms and the Help to Buy Scheme, helping the demand for Gleeson's low-cost homes to remain "robust".
2) No-deal Brexit not considered a major threat for Gleeson, relative to other housebuilders. In their own words: "we employ small, locally based suppliers and subcontractors... and do not rely on foreign labour". And Gleeson thinks its larger suppliers are well-prepared for a no-deal Brexit.
CEO - interim CEO in position since June, looking to make a permanent appointment.
Outlook - "comfortably on track" to meet its long-term unit sales target and confident for the current year and beyond.
My view
It's hard not to like what this company does: helping young people get out of the "rent trap" by buying their own low-cost home.
Checking back to the last time I covered this share, I mentioned three risks:
- most customers use Help to Buy - regulatory risk
- macroeconomic risk (ever present for housebuilders)
- execution risk
On the Help to Buy scheme, what do readers think - is it here to stay? Or should investors pencil in the risk that it gets taken away at some point? (thank you to readers for pointing out that its current extension lasts until 2023, only).
Macroeconomic risk: other sectors (e.g. banks) are virtually pricing in a recession now. Should housebuilder stocks price it in, too?
Execution risk: the land pipeline and number of plots are growing, so perhaps execution risk is reducing as the company grows?
When it comes to valuation, Gleeson has made great gains and the market cap now stands at an even larger premium to its net assets of £204 million, or 374p per share.
Existing shareholders may not see any particular reason to sell, but should prospective buyers be interested at these levels? From my perspective, this valuation makes no allowance for economic weakness, implying that the company's business model is robust enough to generate attractive ROCE throughout the economic cycle.
That seems a bit too optimistic to me, but what do I know?
H & T (LON:HAT) and Ramsdens Holdings (LON:RFX)
(Please note that I have a long position in HAT.)
This was very interesting news over the weekend.
Albemarle and Bond has shut stores - possibly all of them - but the company has not yet confirmed anything.
Bad news for customers
It has caused anguish among customers. Two of the customers spoken to by the Liverpool Echo said that they are going to the police to talk about what A&B has done with their jewellery.
According to A&B's homepage, pledged items "will be held securely in our Pawnbroking Centre for the duration of the loan".
The procedure to get the items back doesn't sound very convenient:
Once you have repaid your loan in full, you will need to return your original Pawnbroking Agreement to us via Royal Mail signed for 1st class post. The Postage cost of £1.90 will be deducted from your final redemption amount, at no additional cost to you. Once your loan has been repaid in full and we have received your Pawnbroking Agreement we will arrange for your pledged items to be returned to you. This may take up to 10 days.
This is much worse than simply turning up at the store to collect the item. I can understand why customers would feel angry about it (besides the fact that family jewellery has been transported from the local shop to an unknown location!).
A&B says "we were unable to contact all customers prior to the closure date". I wonder if any customers were contacted prior to closure?
The National Pawnbroking Association has criticised A&B:
"Their decision to downscale UK operations is a strategic matter for the company but the NPA has expressed its concern that the communication of their actions to their customers falls below the standards expected of its members... In particular we are most unhappy with the fact that customers cannot get through to the helpline."
Good or bad news for other firms?
My instincts tell me that this is good news for rivals H & T (LON:HAT) and Ramsdens Holdings (LON:RFX), who are seeing a major competitor struggle and perhaps permanently shut down. What's not to like about capacity getting taken out of the industry?
Obviously, the fear is that A&B's struggles could reflect difficulties which the other firms might experience, too.
A&B has been private since its administration many years ago (when I was unfortunately a shareholder and experienced my first and only 100% wipeout!). From public accounts, however, we know that it has been loss-making in recent years. After a period of over-expansion and loose lending, it looks like it failed to ever properly turn itself around.
So hopefully, its demise is a consequence of its own mistakes, poor management, and poor brand, rather than any fundamental problem in the industy. H&T and Ramsdens are profitable with good outlooks.
To give you some context: A&B has 116 stores, versus H&T with nearly 250 and Ramsdens with c. 160 (following acquisitions from The Money Shop, which failed as a consequence of its own strategic errors).
H&T shares are up by 2.5% this morning, while Ramsdens shares are up by only 0.5%. While I don't know the exact geographical layout of A&B, I do know that it has (or had) a heavy presence in London and Birmingham, which are H&T's home turf. It would make sense, therefore, if H&T enjoyed a stronger benefit from the collapse of this entity.
Finsbury Food (LON:FIF)
- Share price: 71p (+8%)
- No. of shares: 130 million
- Market cap: £93 million
Finsbury Food Group Plc (AIM: FIF), a leading UK speciality bakery manufacturer of cake, bread and morning goods for the retail and foodservice channels, is pleased to announce its preliminary results for the financial year ended 29 June 2019.
As discussed last time, I find it difficult to get excited about this company, for many reasons.
Credit where it is due: Finsbury's like-for-like revenue performance of 4% is better than I would expect, based on its track record.
Also, the company's adjustments to its results have calmed down. Adjusted operating profit for the year is £16.8 million, while statutory operating profit is £15.3 million. Not bad.
But the cash flow statement helps to illustrate that this is still a complicated picture:
- £17 milliion spent on an acquisition (this company has a lot of M&A activity)
- another £3.5 million of "costs relating to closure of bakeries and acquisitions"
- a negative working capital swing of £5.5 million
- capex spend of £11 million, much higher than depreciation of £7.4 million.
The CEO says:
As we come out of our intense investment phase, with capital expenditure of £11.0m in the period, the Group will continue to benefit from the investments made for years to come.
Net debt at period-end is c. £36 million, with £48 million of debt offset by £12 million of cash. I would encourage all companies to publish their average net debt, too, so that we don't have to worry about window-dressing!
My view: this looks cheap but it's a leveraged, low-margin business with limited IP. Cheap for the right reasons, in my view.
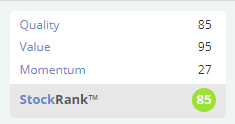
The StockRanks disagree with me:
Learning Technologies (LON:LTG)
- Share price: 119p (-2.6%)
- No. of shares: 668 million
- Market cap: £795 million
Learning Technologies Group plc ("LTG" or the "Company"), the provider of services and technologies for digital learning and talent management, is pleased to announce its half year results for the six months ended 30 June 2019.
Mentioning this one briefly, as some of you are following it.
Rather than a single company, it's better thought of as a portfolio of companies. It lists ten major brands on its website (3 under "Content and Services" and 7 under "Software and Platforms").
At the H1 trading update, LTG said:
"Adjusted EBIT is anticipated to be ahead of expectations at not less than £20.0 million for the first half of 2019."
Today, it says:
Adjusted EBIT ahead of expectations, up 134% to £19.4m
Am I going crazy, or is there something a bit off about this?
Outlook
Trading is in line with upgraded expectations. Net debt has been reduced to <£8 million.
My view
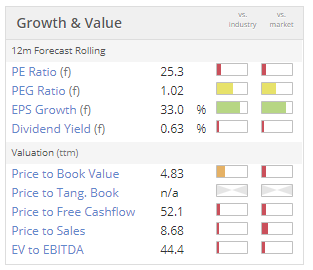
I don't have a strong view on this one. Stockopedia is nervous about the valuation, giving it a Value Rank of only 4 (out of 100!). It must be doing something very special to justify this rating:
Alfa Financial Software Holdings (LON:ALFA)
- Share price: 77p (-17.6%)
- No. of shares: 300 million
- Market cap: £231 million
Trading Update and Notice of Results
This is a software company, serving the asset finance industry.
It listed in 2017 with an IPO price of 325 pence.
It has been an unhappy ride for investors. Alfa reports today that H1 operating profit is only going to be about £5 milion (versus £8.6 million in H1 last year), after projects were delayed and customers reduced spending. "Broader macro uncertainty" gets the blame.
Revenue for the full year is expected to be "in the region of £63-£65 million". That would be the smallest result since 2015, two years before it listed on the public markets. Profit will be significantly below previous expectations.
This company enjoyed super growth in revenues and profits in the two years prior to IPO, and has been on the decline ever since. There's a surprise!
All done for today. See you tomorrow - same time, same place.
Cheers
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

31 comments
Am loving the random order of posts on the new platform.. NOT
It's not quite random. Responses in a thread are attached to that thread, so may appear below older posts on other threads. But I agree - tracking down a lot of recent posts is now so hard it's not worth the effort.
If you are going to implement threaded posting you really need an option to jump to the next unread comment. (Always used to be a quick tap of the space-bar back in the Newsgroup (Usenet) days.)
I notice £K3C are up 15% on tomorrow's (presumably great) results.
Am I right to have a bad taste in my mouth, or is there an innocent explanation?
P.S. Nice to have something go up for a change.
Here's the Trinity Exploration and Production (LON:TRIN) presentation at ShareSoc London Sept 19.
Jeremy Bridglalsingh, Managing Director & CFO talks through the latest results (half year ending 30th June 2019), released 10th September 2019.This covers:
Why Trinidad? – 00:18
Who is Trinity? And management shareholdings – 02:49
Asset Summaries – 04:22
2019 Interim results & post period highlights – 05:56
Increasing margins & financial resilience – 11:10
Margin drivers – 12:01
Organic growth path: Reserves & Production – 14:59
Onshore: optimising base production – 16:54
Onshore: growing base production: doing it differently – 19:28
FCF generation – 22:26
Offshore: Further development of Galeota Anticline – 27:39
Modus operandi – 30:02
Summary – 30:39
Q&A: 30:56
#LTG.
I read the half year results to confirm the ahead of expectations update of 22 July, rather than that the company was ahead of expectations again.
This is where the confusion regarding the EBIT lies:
Hope this makes the situation clearer.
From the results
H119 H118 Change
Adjusted EBIT (pre IFRS16 and SBP adjustments) 20.0 8.9 +125%
Adjusted EBIT 19.4 8.3 +134%
At the last AGM LTG management were highly impressive and are delivering excellent growth in a dynamic sector.
In other news, I see that Direct Carrier Billing platform Bango (LON:BGO) are up c. 7% on news that they have signed (yet another) new partner. (Announcement released intra-day at 12:49)
This looks like a very typical 'story stock announcement' firmly supporting the story, but with no financial whatsoever and some vague numbers which could be (but are probably not) indicative of the size of the prize.
The deal is with AE Tolls in the US and allows users of toll roads to "place road toll charges on their monthly phone bills."
Maybe I am too sceptical here but that suggests to me that it is not available to Pay As You Go mobile customers. I have to wonder then, how many US mobile phone users who are on a contract do not have access to GooglePay or ApplePay or a contactless card? (I presume that is a thing in the US?)
Now despite the fact that it makes no sense to me, I do agree that this has to be a positive that AE Tolls have chosen to use Bango (although early adopters of tech are often given significant incentives).
We are given though no idea of how big AE Tolls are (so I'm guessing very small), we are however told that in 2018 the total US electronic Toll market was $21Bn and that $6Bn of that was from 'untagged users' (ie those that don't already have an account with the toll operator).
So the Bango market opportunity here is some fraction of a fraction of $6Bn pa and only that they'll make fractions of a cent on the dollar - doesn't sound too impressive.
However of course it is indicative that the 'story' is still going. More importantly I believe Bango will be releasing their latest results very soon and as they have been telling us for some time that they are now profitable - it will be interesting to see if that is actually true.
I was previously short Bango, no position at the moment, but still very sceptical. However I might yet be tempted to invest at some stage if I can get more comfort that there IS a sustainable profitable business here.
Edit : In the time it took me to write the post, Bango have retreated most of the days gains and are now showing up only 1.7%!
The take up of contactless cards in the USA has lagged a long way behind civilisation but is forecast to accelerate.
Not Invented There syndrome.
Thanks John.
In fact I couldn't resist the temptation to look a little further into the Bango (LON:BGO) announcement.
So I google AE Tolls and nothing comes up except their own website and various news stories on today's announcement.
Hmm - crunchbase has a little more and it transpires they were 'founded' in 2015 & received $400m in seed funding in 2017. No evidence that they have any customers whatsoever. (In fact until today I'm pretty sure they didn't even have a product.)
From joining the limited dots, they are not a toll operator at all, they are a start up seemingly specifically targeting sell the Bango technology into the toll market (all of the have worked in tolls previously).
However it is not all bad following their brand website tapNpay.info shows that they do actually have a deal.
Anyone that :
Can register for an account and pay their tolls via the monthly mobile bill.
And if they are one of the first 500 to sign up (reinforcing my view that this has only launched today) then tapNpay will cover 10% of their first $100 of tolls.
Now every business has to start somewhere and despite my scepticism this could turn out to be the next big thing.
However, the announcement from Bango gives us no indication whatsoever of how early stage this actually is. The $6Bn addressable market (and that is "End User Spend" not AE T or Bangos potential cut) alluded to in the RNS is so far in the distance as to be unimaginable.
Crazy that the market should have reacted to this at all.
In fact the offering doesn't even seem that attractive to me. If I can understand the tech - it is based on ANPR and if users sign-up to this service then instead of being billed by mail they will be billed directly to their phone bill. It doesn't really seem any more convenient than signing up for an online account for the Dart charge (for those using the Dartford Crossing)
I am probably to cynical, but it seems a bit desperate to me if you have to RNS (to be fair I now note it was RNS REACH - ie news not market sensitive information) something of this scale.
PS - reading back on my comments today I see I have had an atrocious Grammar/Auto Correct day, I hope it didn't irritate folks to much. It irritated me immensely and I am usually quite tolerant of such things. Although I do of to say that there is one particular mangling of the English language that really does annoy me. (Did you see what I did there?)
Learning Technologies (LON:LTG)
Somewhat strangely there are two adjusted EBIT numbers used in the accounts - so its not as ridiculous a situation as it seems - note the other EBIT figure has come in bang on the money including the % increases used - so it seems like the numbers do add up if the July release related to the other adjusted EBIT.
Its more the confusing presentation used and also the somewhat cheeky/misleading "ahead of expectations" without clarifying that they are actually presumably exactly on the numbers as previously outlined in July - so not ahead of previously announced expectations at all? - perhaps they find the timeline of expectations hard to follow - that would be sorted by a nice stockopedia subscription :)
Adjusted EBIT (pre IFRS16 and SBP adjustments) 20.0 8.9 +125%
Adjusted EBIT 19.4 8.3+134%
Great spot on £LTG "ahead of expectations" - I've looked at it before and been put off by the valuation. Now I'm even more cautious because of the way management communicate to shareholders. #neverjustonecockroach
Some slightly tangential thoughts about Albemarle and Bond.
I suspect the reason that clients pawned assets have been removed to "be held securely in our Pawnbroking Centre" is that the situation is at least as messy as it appears.
I except we may very shortly see Landlords 'repossessing' there stores and in this event there would be a risk that the pawned items would be seized (whether legally or not I don't know) or damaged.
So A&B's actions I believe are to secure their clients assets. However, I doubt it is entirely altruistic :
1. If they lost their clients assets, the probably could not enforce the remaining loan, nor could they recovery by selling the asset.
2. If they fail to take good care of the clients assets there could (guessing - I am not a lawyer) be implications possibly exceeding the notional value of the asset and/or the loan.
Some possible implications for H & T (LON:HAT) & Ramsdens Holdings (LON:RFX) ?
If it is this messy, then it probably decreases the likelihood of either (or another player) taking over any stores as going concerns.
A&B have indicated that they will keep the goods for the duration of the relevant loan, and that they can be recovered on repayment of the loan. This will not be a comfortable position for clients (many of whom probably cannot readily find the cash to repay the loan immediately), nor I suspect will it be convenient to A&B's owner's or creditor's .
There has to be the possibility then of these loans and associated assets being sold on to someone remaining in this business, could be HAT or RFX or of course someone else.
This story began to break late on Thursday and there hasn't been a dramatic reaction in either share price. I think there are pro.s & con.s
+ The removal of competition.
+ The possibility of acquiring some new businesss
- All pawnbrokers to be seen (by the market) as risky. [I'm with Graham on this and think in fact we are seeing the differences between 'quality' & 'non-quality' businesses.
- Clients make come to look on Pawnbroking as less safe. They may be more tempted to pay higher interest on an unsecured payday loan, than risk 'the family silver' with a pawnbroker.
This last point largely depends on how this all plays out. At this stage the uncertainty looks like quite a negative, however if this can be managed through without any of the clients losing their goods then it may quickly go away.
On balance I think it is probably a positive and have this morning increased my position in H & T (LON:HAT)
There is not too much to choose between the two - Stocko give both and SR of 97 (and with a similar make up), but I slightly favoured H&T before and had therefore a better feel for the business
I hold MJ Gleeson (LON:GLE) having taking advantage of the price dip earlier in the year when the CEO left and I surmise sold his entire shareholding.
The results were pretty much as expected I think, reflected in little movement in the shareprice.
Interesting comment on the Strategic Land business :
I translate this as simply saying, nobody offered enough money. That's probably not too surprising given the level of nervousness in the market, of course there is a risk that in the event of a proper slowdown, the "open market" value would be even lower, but in the longer run the value would recover.
It may seem questionable to sell such a successful part of the business, but in reality the two businesses (Building houses in the North and Trading Strategic Land in the South) have few synergies as far as I understand it. So I suspect some form of "de-merger" remains a potential for the future.
I have wondered in the past why they do not branch out to add Southern Building & Northern Land trading, but on reflection I think they have probably found the sweet spot in each market.
I am not too concerned about 'execution risk' here at least in the sense that I don't any unique risk to Gleeson here.
The cyclical market risk (we could be at the top of the market for house builders?) remains a concern and makes me a slightly nervous holder.
Help to buy, however, is a little more nuanced and I covered this off elsewhere earlier in the year.
To summarise me view :
So I am happy to continue to hold for the moment but continue to look for clouds on the economic horizon.
Just a last thought on the premium to book value; I don't personally regard it as too high - the market is effectively just anticipating the gains that Gleeson will make on it's landbank, the strong ROCE numbers give support to that anticipation. Of course this does make them more vulnerable to economic slowdown and cyclical reductions in land values.
If and when I sell, it will probably be on the macro, rather than company specific.
Edit : @HornBlower - we crossed in the post, but it looks like we agree on that point! :-)
We are rather assuming no Corbyn government in this.
I wouldn’t see them continuing the Help To Buy Builders Yachts scheme.
Nonetheless £GLE look like the lower political risk in the sector and could be beneficiaries.
MJ Gleeson (LON:GLE) given their average selling price of £129,000 I would think that when HTB ends there will be some new form of help for low cost buyers whoever is in power at the time
HornBlower has pointed out M J Gleeson's remarkably low average selling price per house of £129,000. I think this must be close to the lowest in the quoted housebuilder sector. These houses almost all end up in the hands of people who need them to live in, rather than buy them for investment, so I would think that this side of the business is therefore more resilient to a cyclical downturn than that of many housebuilders. I notice that Gleeson is the only housebuilder held by highly successful fund manager, Keith Ashworth-Lord, and this is what triggered my interest in the company.
Morning Graham
Excellent HY update from LTG.
Rev up 85%,recurring rev now 74%, EBIT up 135%.
Surprisingly negative SP action at open but now rising.
Would be interested to hear your thoughts.
I hold
Michael
https://www.investegate.co.uk/learning-tech-gp-plc--ltg-/rns/half-year-report/201909160700143638M/
Open Orphan (LON:ORPH) presentation at ShareSoc last week, is here.
Presentation by Cathal Friel, Co-Founder.
ORPH came out of a reverse takeover of Venn Life Sciences earlier this year. Cathal Friel outlines what they do, and their vision.
Graham would be interested in your comments on FDM where the chart looks like it is forming a base after the sharp reaction to the last results
Good Morning Could you possibly comment on Griffin Mining (GFM) half year results . This company seems to have tumbled down the Stockrank charts over the last year. I believe it was a favoured stock of ED's at a conferance in 2018 (may have been Mello not sure)
RE Griffin Mining (LON:GFM)
Neither Graham nor Paul, routinely report on miners (or oilers) - me neither as I do not really understand them!
However in relation to :
Griffin Mining (LON:GFM) was a member of Ed's 2018 NAPS portfolio as you can see from the link here
NAPS is a purely factor based portfolio approach that by it's nature produces both winners and losers. This was one of the losers (down c. 25% in 2018 I think). Ed takes a stance of being pretty much deliberately ignorant of anything except for the factors for the purposes of NAPs.
Anyway, whilst I have really no insight into Griffin Mining (LON:GFM) at all, I can see that the StockRank has been picking up recently and is toying with the 70+ ('green') level. If today's numbers are good (share-price reaction of minus 4%, suggests not that good) it could see the SR rise further.
Graham
Reports over the weekend that Albemarle and Bond pawnbrokers are in trouble and closing stores.
https://www.bbc.co.uk/news/business-49690753
I don’t know the sector well but as H & T (LON:HAT) have been discussed here in the past and I believe you currently hold that share (or have in past) it would be interesting to have your view on whether there are any implications for the prospects for H & T (LON:HAT).
H & T (LON:HAT)
Thanks Graham - I meant to add a section about that. G
£RBGP looks to have made an interesting acquisition:
Max consideration of £22m for a business that earned PBT of £4.3m last year.
Max cash cost of £8.8m and rest in shares @120p and 140p or the SP if higher.
Regards,
Dave S.
Begbies Traynor (LON:BEG) : It's an RNS REACH communication ( non-regulatory news such as marketing messages, corporate and product information.)
RNS Reach announcements are tagged "RNS-R" in the "Source" column of the Market News service and as RNS – RCS on Thomson Reuters terminals. The latter was used for today's announcement (see the title)
Thanks Carcosa - We don't all have the same level of knowledge, every little explanation helps someone
£FIF please Graham. Been having a tough year or so given cost inflation across the board, but still seems a very well run outfit, with a decline in earnings for this year of only 10%. Think there may be some good value in the stock.
Good idea to cover Finsbury Food (LON:FIF) - I'll check it out. Thanks. G
Begbies Traynor (LON:BEG) - good morning Graham, this morning Begbies Traynor (LON:BEG) have rns's that one of their subsidiaries have taken on 4 more staff. Is this really worth an RNS or is there something I'm missing? Holding as a hedge against recession and disruption.
I would suggest that with the recent slaughtering of the Begbies Traynor (LON:BEG) share price all because of some dubious rant in the Share Prophets publication then every RNS helps!
My morning smallcap tweet:
Angling Direct (LON:ANG), £C21
Angling Direct (ANG) trading - slight slowing of store LFL to 13.5% in June-Aug vs 15% in H1 trading RNS (to end July). Overlapping periods, so comparison may not be useful.
21st Century Technology (C21) H1 rev down 11%, pretax -£0.4m (+£0.35m). Blames slump in new vehicle purchases. Order intake is up.