Small Cap Value Report (20 Jan 2020) - FEVR, SOS, BOOM, KAPE, DIS, MCON, APTD

Good morning!
I'm giving Paul a break after a couple of mammoth weeks on the job here.
His top holding has announced a trading update, and there are plenty of other stories for us to digest.
I'm not sure how far I'll get, but these are all the small-caps I noticed which made announcements this morning.
Finished at 5.20pm: Made it as far as APTD.
- Sosandar (LON:SOS)
- Audioboom (LON:BOOM)
- Kape Technologies (LON:KAPE)
- Distil (LON:DIS)
- Mincon (LON:MCON)
- Aptitude Software (LON:APTD)
Not covered today:
- AFH Financial (LON:AFHP)
- Argo Blockchain (LON:ARB)
- Accrol Group (LON:ACRL)
- Renewi (LON:RWI)
- Bonhill (LON:BONH)
- M&C Saatchi (LON:SAA)
- Tekcapital (LON:TEK)
- Coral Products (LON:CRU)
In the world of big-caps, Fevertree Drinks (LON:FEVR) announced revenue growth of 10% - "below the Board's expectations, primarily reflecting subdued Christmas trading in the UK".
Fever-tree's margins have also declined, and it says 2019 earnings will be 5% below those of 2018.
That is not baked into any public forecasts I can see, and I would therefore expect to see significant selling pressure on the stock this morning.
Long-term prospects are probably still excellent, I think - I've been thinking about buying into it for a while, and will be checking to see how far it falls today!
Sosandar (LON:SOS)
- Share price: 28.25p (pre-market price)
- No. of shares: 163 million
- Market cap: £46 million
I'm happy for Paul and other holders of this share:
Revenue for the full year on track to be ahead of market expectations
But the loss for the year will also be higher then expected:
Given the upfront cost of acquiring new customers against the benefit over the lifetime of the customer, the Company expects this investment to result in the net loss for the full year being higher than previously anticipated with the increased benefit to be experienced in future years.
Sosandar's plan is to build its customer base through aggressive marketing spend, and then to profit in the long-run on the back of significant repeat orders.
There is no doubt that it could work. I understand that a customer list and a customer relationship are valuable assets. It might be worth suffering losses in the short-term, for the sake of building them.
But in the end, I think you still need a differentiated product or customer experience, not just a big marketing spend. Without that element of differentiation, the business will ultimately wither, if the market spend slows down.
For now, Sosandar's revenues are enjoying the rush caused by a big advertising budget.
Key highlights of today's Q3 (October to December) update:
- Q3 revenue of £3.8 million (versus combined Q1 and Q2 revenue of £2.8 million)
- active customer database >110,000 (up 93% year-on-year, up 47% during the quarter)
- repeat orders +140% (not too relevant, since the company is still so young)
Figuring out the customer list
I've been a little slower than expectations this morning (!) due to some work trying to figure out the customer database at Sosandar.
The CFO has written back to me to confirm that the customer database (currently standing at 208k) includes prospects, i.e. people who have given their email address but haven't placed an order yet. While this is an interesting number, I can't use it to analyse customer longevity, since it doesn't necessarily have anything to do with orders.
The success of the business plan hinges on this notion of longevity: will customers come back, unprompted by expensive advertising, to make more orders? It is these unprompted orders which will ultimately create a profitable business.
Focusing on "active customers" (i.e. those who have placed an order in the last 12 months), that metric is up from 62,200 in March 2019, to 110,000 December 2019.
And repeat orders reached 51k, out of 84k total orders in the quarter.
That doesn't sound too bad, actually: it means that 60% of the orders in the quarter were of the profitable kind, rather than first-time orders triggered by a costly advertisement on TV, Google, etc.
Cash drain
Sosandar reports a cash balance of £6.9 million at the end of September.
By the end of December, this had reduced to £4.2 million, i.e. down by £2.7 million.
The company points to a £1.6 million increase in inventory during the quarter, "increased stock landing pre-Christmas for post-period selling".
If the company intends to grow, then inventory is only going to go in one direction and so I would expect cash to be continuously converted into inventory.
Setting that that to one side, the ex-inventory cash burn is £1.1 million.
Current trading
Trading in January sounds good:
Sosandar saw steady progress in performance month-on-month, with October revenues up 108%, November up 138% and December up 153% year on year. This momentum has continued post-period, with January tracking up over 160%, and pleasingly repeat order performance is exceeding that in the highly successful Autumn/Winter period.
My view
As much as I enjoy gambling, I don't do it for large sums. So let me be clear that I've never seriously considered investing in this one, as I consider it to be a startup.
The cash burn is very significant, although I wouldn't necessarily fault the company for this: it is carrying out its business plan, albeit with slightly more aggression than might have been anticipated.
A growing pile of inventory is inevitable if it intends to grow. Similarly, if the plan is to rapidly grow the customer base, the upfront losses are inevitable.
Many industries work on this basis, not least financial services. One of my former employers used to suffer nasty losses whenever it signed up a new customer, as the bonus for the salesman would be worth several years' worth of revenues from each customer. The company expected the customer to stick around for decades, however, so it was good business. In insurance, we call it "new business strain".
The FY March 2020 forecast was for a pre-tax loss of £3.8 million. I will presume this is now going to be £4 million+.
If things go to plan, then FY March 2021 should see many of the recent customers making fresh orders without expensive prompting - perhaps just with the prompting of a cheap email.
The final result will depend on how aggressively the company wishes to keep growing: will it continue to spend on TV ads, for example? Or will it harvest the proceeds of work done in previous orders, and accept a greater proportion of repeat orders?
The problem with valuing a share like this is that a valuation exercise needs a "steady state" or a reasonable terminal growth rate. Extreme growth rates can't last forever, but predicting whether they will end in success or failure for a company like this relies on all sorts of assumptions.
The primary assumption is customer lifetime value. I've stolen this chart from a PIworld video produced in December (about five minutes in):
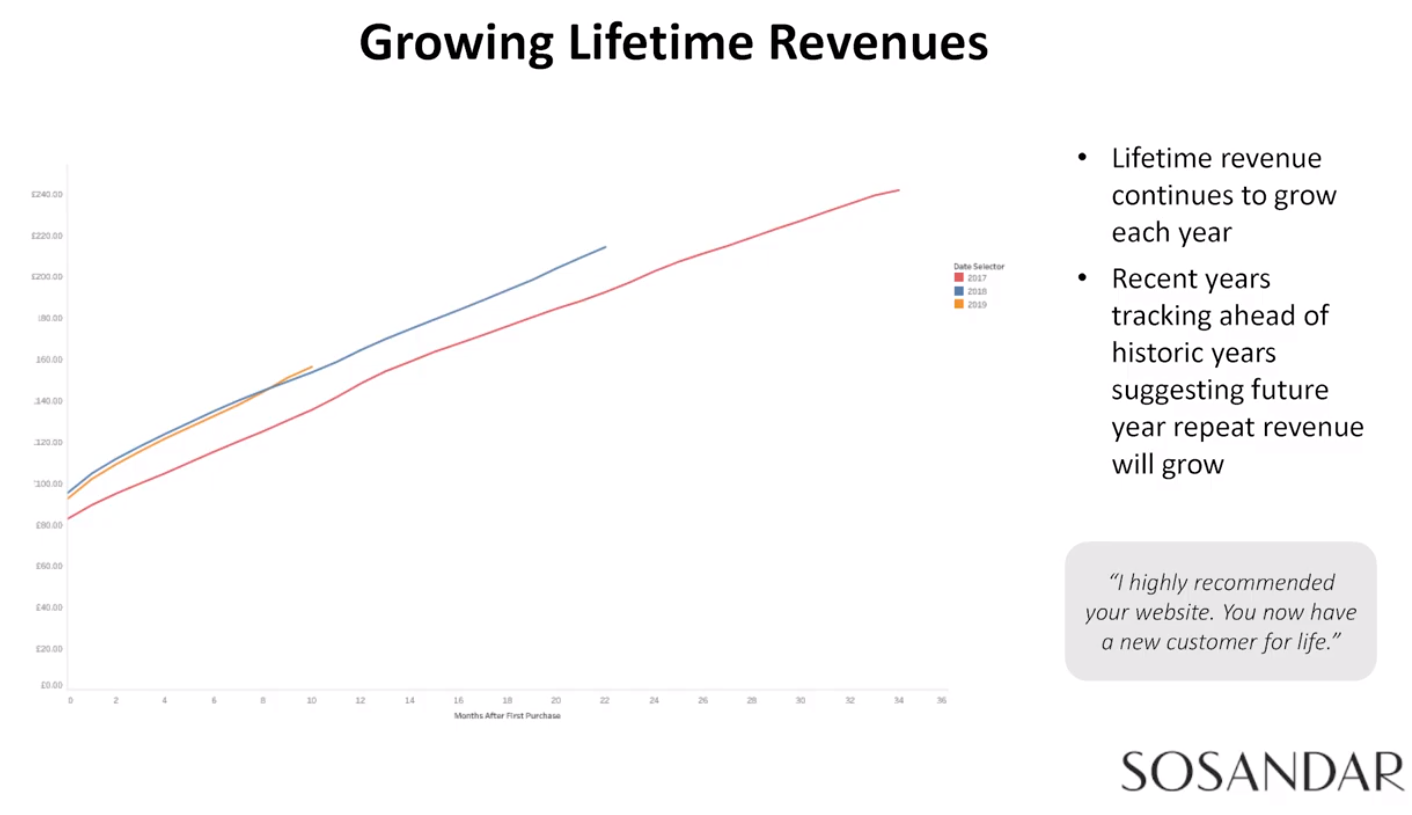
What it says is that the average customer continues to generate revenue for Sosandar, even nearly three years later (the red line). There is perhaps an ever-so-slight reduction in the rate of revenue generation by these customers. The question is: at what point do they start to level off and stop becoming revenue generators?
The blue line shows more recent customers, over their first approx. 2 years since acquisition. They are more valuable than the earlier customers, and they continue to generate revenue at a steady pace. Great news for Sosandar!
If I was seriously considering this share, I'd want to know how many years it will take until a customer pays off their acquisition cost. Has anybody asked the company this?
It might be commercially sensitive info, since it's the sort of basis on which these online retailers compete against each other. More expensive marketing means faster growth, but needs a much bigger customer response to justify it. And if you spend more per customer acquisition, then you will have to wait longer for each customer to pay back their acquisition cost.
The main risk that I would like to flag, which might turn out to be a false alarm, is the possibility of another fundraising.
In April 2019, the FY March 2020 operating loss was forecast to be £1.6 million. As stated above, I think we can now pencil in a loss of £4 million+.
Back in April, I said that I was leaning towards the view that another fundraising would be needed "in about a year". The subsequent fundraising happened much sooner than that, in July.
At the time, Sosandar's cash pile was c. £3.6 million, i.e. not much smaller than its current level.
I would therefore pencil in another fundraising over the next twelve months.
I could be wrong about that, but if I'm right, then shareholders need to take into account the possibility that it happens at an unfavourable level.
That's the big problem with companies which need cash injections. If it happens at a low share price, and if you don't take part in it, then the dilution can be a serious drag on your future returns.
FY March 2021 now seems to be a make-or-break year for Sosandar. If repeat orders come through in sufficient numbers to fund the company's marketing budget and other overheads, it will have proven the business model. If it doesn't, then it will remain in the highly speculative bucket in which it currently sits.
Some back of the envelope calculations:
- 51,300 repeat orders in Q3 annualises to c. 205,000 repeat orders
- average order value £102 implies £21 million total order value
- after returns and COGS, you might get gross margin of £5 million from this (based on H1 performance stats)
Putting it all together, I can no longer see FY March 2021 producing a breakeven result, unless marketing spend was stripped to the bone and the company was content to let the gross margin from repeat orders cover its overheads. Which would sacrifice its growth opportunity, at least in the short-term.
It's still very possible that this could come good for shareholders, but it's only suitable for the adventurous, in my view!
Audioboom (LON:BOOM)
- Share price: 234.4p (-3%)
- No. of shares: 14 million
- Market cap: £33 million
Audioboom (AIM: BOOM), the leading global podcast company, is pleased to provide an unaudited trading update for the 12 months ended 31 December 2019.
This started life as a tech company, with an audio platform. It's now a content company, buying up podcasts to publish on the platform.
I've been bearish on it for as long as I can remember. The platform didn't seem to have any chance of succeeding as a stand-alone product.
Its current incarnation as a publisher involves paying upfront to make and buy content, and then hoping to get a return on the investment through advertising income.
2019 sees it turn in an adjusted EBITDA loss of $3 million, which is at least a reduction on the loss in 2018. Revenue nearly doubled to $22 million.
This bit is comical:
The Board is pleased to report this strong performance for the year to 31 December 2019 with the Company exceeding market expectations for the first time in its history.
This is comical because:
- a) Audioboom has been around for a long time,
- b) it is still making significant losses, and
- c) exceeding market expectations only requires a company to set conservative forecasts. That's basically the only thing a company needs to do, to exceed market expectations.
To get a sense of H2 growth, let's compare it versus the H1 result:
- H1 revenues $9.8 million
- H1 adjusted EBITDA loss $1.4 million
So in H2, we must have had:
- H2 revenues $12.2 million
- H adjusted EBITDA loss $1.6 million
This doesn't provide us any evidence of operational leverage working in the company's favour in H2, but at least there was some revenue growth.
My view
As a stand-alone audio publisher, producing content and monetising it through advertising, I actually find this story less attractive than the Netflix ($NFLX) business model.
At least with Netflix, there is recurring revenue from customers.
With Audioboom, the customers are principally the 300-odd advertisers. It could work, but I'd prefer to see a focus on having thousands of individual customers paying small amounts every month or every year, instead of selling B2B. Especially if it's premium content - aren't customers usually happy to pay for content of superior quality?!
We can also compare Audioboom to Youtube*, which makes most of its revenues from B2B advertising.
YouTube works well as a consequence of the network effects at play: it's the default place where people go to publish their video content, because it happens to be the place where all the viewers are.
Audioboom doesn't have the scale to support significant network effects, so instead of creators coming to it with their content, it has to buy their content off them - much less attractive.
Good luck to Audioboom, but I see zero evidence so far of a sustainable business in the making.
*I have a long position in Alphabet ($GOOGL), the parent company of Youtube.
Kape Technologies (LON:KAPE)
- Share price: 169p (+5%)
- No. of shares: 154 million
- Market cap: £260 million
Kape (AIM: KAPE), the digital security and privacy software business is pleased to provide an update on trading for the year ended 31 December 2019.
I covered this stock in November when it announced the large (£74 million) acquisition of a VPN company ("PIA").
The company says it has a "SaaS operating model". While the phrase "SaaS" is over-used and overvalued at present, I have been impressed by this company's numbers to date:
Kape's user base grew to 2.35 million subscribers at year-end (30 June 2019: 1 million), comprising 74.3% organic growth within the privacy vertical not including PIA. Reflecting the growth in our customer base, Kape expects to deliver $98.8 million1 in revenues from existing customers in future financial years, up 260% (30 June 2019: $38.0 million).
That $98.8 million includes deferred revenue (where the customer has already paid, but the revenue hasn't been booked yet) and what the company calls "first renewal of the existing user base". If it only counts one renewal, then maybe it's a conservative estimate?
This goes back to the Sosandar debate, which applies to many companies across different industries. When you acquire a new customer, how long will you have them for? And therefore how much revenue will they generate?
FY December 2020 guidance is reiterated, and is important since the company is now much larger after the acquisition:
- revenue $120 million - $123 million
- adjusted EBITDA $35 million - $38 million
The market cap is worth c. $340 million, and net debt is around $36 million. If you want a number to compare against EBITDA, the enterprise value is c. $376 million, giving us an EV/EBITDA multiple around 10x.
I expect that the amortisation charge will be pretty big in the wake of the acquisition (usually there are a lot of acquired intangibles that have to be amortised). Many investors are happy to ignore this charge and look at EBITDA instead.
Where exactly is it?
Noting that Kape is registered in the Isle of Man, I have checked the locations of its employees on LinkedIn. This is what I get:

I'm not sure what to make of this but clearly it's something you would want to be aware before investing in it!
The same test for the recently acquired company, Private Internet Access, shows almost all employees based in the United States.
(By the way, this is a very handy service by LinkedIn. All you need to do is type in the company name at the top (as if you were searching for an individual).
When you find the company page, click "People" and you get company analytics. Seeing where the company's employees consider themselves to be resident is a great help to find out where the company is "really" based, not where it tells you that it is based!)
The bottom line for Kape is that its recent acquisition is based in the US but its PLC employees are a more mysterious bunch.
Sell-side analysts have made no changes to estimates, despite EBITDA coming in slightly ahead of expectations for 2019. EBITDA is forecast to reach $40 million in 2021, generating free cash flow of $20 million.
Based purely on the numbers, this looks fairly valued to me at present. I can't tell whether the company's services are truly differentiated or not, but I do think that it looks quite promising from a quantitative point of view.
Distil (LON:DIS)
- Share price: .801p (+14%)
- No. of shares: 502 million
- Market cap: £4 million
Allow me to briefly mention this tiny tiddler. It develops spirits brands - its flagship brand is Redleg Spiced Rum.
I took a loss on this share last year, after buying it at an average of 2.3p and then exiting at 1.7p.
At current levels, I'm wondering if I should look at it again (though it's really too small now):
Year-on-year third quarter (October to December) revenues increased by 7%, supported by continued levels of up weighted marketing investment.
"Marketing investment" sounds much better than "marketing spend"!
Unfortunately, financial year-to-date sales are down 13% in both revenue and volume, "with marketing rates maintained".
The outlook for FY March 2020 is "broadly in line with market expectations". Sell-side forecasts are unchanged for PBT of £210k. It also has a cash balance of £1 million.
My view
I'm tempted to buy back into this, but I won't - it's too small, illiquid and low-growth, and competing in crowded markets.
Rum volumes are up 16% and it's that category where I think Distil could be on to a winner. For now, the declining gin sales are camouflaging the excellent progression in rum. But of course it is hard to say whether Redleg Rum will have real sticking power.
Separately, I note that an individual called Roland Grain, via an Austrian company, has been stake-building in Distil in recent months.
Roland, described as a "dedicated whisky lover", appears to be a shareholder and director of a company called Manly Spirits.
So I reckon that Distil makes for an interesting bet at this valuation. The market cap is no longer very speculative in relation to current profitability, there is at least one brand which is growing well, and we have some interest in it from a stake-builder with industry expertise.
The problem is that its current scale doesn't justify it being publicly listed, and it's unlikely to reach significant scale for years. Economically, the correct thing for it to do is to give up on the listing and grow in private.
Most shareholders don't seem to want that, so they will continue the long wait for a major to take it off their hands. I hope they achieve a decent price! I do agree with them that it is probably too cheap at present.
Mincon (LON:MCON)
- Share price: 84.5p (-3%)
- No. of shares: 211 million
- Market cap: £178 million
Rare value on offer at the moment from Mincon, whose share price reached 150p in August 2018.
This is an Irish engineering group with an excellent track record of profitability over the years. It specialises in drilling equipment (i.e. the opposite of £SOM!)
Commentary from this management team always strikes me as reserved and realistic.
Today's news is that it is buying a Finnish manufacturer for whom Mincom is the primary customer: Mincon was responsible for €9 million of the Finnish company's €13 million total revenue last year. Mincon is paying €8 million to take it over, or 3.6x EBITDA. Sounds fine.
While I tend to be wary of M&A (most deals probably destroy value), I'm encouraged when I see deals between companies who already have strong commercial relationships. They likely have a level of understanding which will make combining the two cultures that much easier.
Aptitude Software (LON:APTD)
- Share price: 544p (-15%)
- No. of shares: 56 million
- Market cap: £306 million
Trading update, Board changes & Notice of results
This financial software provider was formerly known as Microgen (MCGN). Its homepage says that it makes "financial management software for the CFO office".
Update - the 2019 result will be in line with expectations.
There is a slight problem with its software for insurance companies, as the new accounting rules which it is designed to tackle might be delayed for 12 months. This has made it more difficult to sell the software:
These delays have had minimal impact on 2019 recognised revenue but have suppressed Annual Recurring Revenue ("ARR")1 growth as at 31 December 2019 from what would otherwise have been achieved.
Another problem has been the strengthening of Sterling. Aptitude must have lots of dollar income:
Despite the strengthening of Sterling versus the US Dollar in the final quarter of 2019, which reduced the Group's ARR at the year-end by £0.9 million, ARR increased in the year to £28.6 million, growth of 22% on a constant currency basis ("C/C") (31 December 2018: £23.5 million; 30 June 2019: £27.0 million (both comparatives restated for C/C)).
Outlook
The company cuts the profit outlook for 2020 in the most benign way possible. 2020 will only be marginally more profitable than 2019, because of all of the company's wonderful investment opportunities (in its Poland centre of excellent, in the training of its clients and its own employees, in customer support, and in various professional services):
With the Board's overall revenue growth expectations for 2020 unchanged, the above investments (together with the aforementioned foreign exchange impact on ARR) are likely to result in 2020 adjusted operating profits being marginally ahead of those expected for 2019.
You have to read twelve paragraphs before you get to the profit warning. Not good enough! I should give it joint-first place with Sosandar, which also took twelve paragraphs and bullet points today before giving us the profit warning.
My view
The enterprise software space looks extremely bubbly to me, and APTD is no exception. Not all of these companies are going to be long-term winners, and stratospheric earnings multiples provide no downside protection if things don't work out as planned.
I'm out of time for today, but thanks for your interest everyone! I'll be back first thing in the morning.
Best wishes,
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

65 comments
XLMedia (LON:XLM)
The RNS states...
"On 18 January 2020, the Company became aware that a number of its casino sites have been manually demoted by Google, which impacts the visibility of the sites and their ability to generate meaningful levels of online traffic, and hence revenues, from new visitors."
Google says...
"
Google issues a manual action against a site when a human reviewer at Google has determined that pages on the site are not compliant with Google's webmaster quality guidelines. Most manual actions address attempts to manipulate our search index
....
Why do manual actions exist?
Ever since there have been search engines, there have been people dedicated to tricking their way to the top of the results page. This is bad for searchers because more relevant pages get buried under irrelevant results, and it’s bad for legitimate websites because these sites become harder to find. For these reasons, we’ve been working since the earliest days of Google to fight spammers, helping people find the answers they’re looking for, and helping legitimate websites get traffic from search."
https://support.google.com/webmasters/answer/9044175?hl=en
Reads like XLM had some natural search optimisation on their web sites to improve their rankings. I remember back in the day popular techniques were loading the web page with hidden text with repeated key words (not real copy) and hiring outsourced agencies to work through blogs with comment pages adding back links to their site. That was many years ago, suspect it's more sophisticated now.
They can fix these issues, google do tell them how. However, having fixed what the issue is their natural search ranking will likely be lower than before.
XLM "owns more than 2,300 content-rich informational websites" that harvest internet traffic which they then sell impressions, banners etc to earn revenues. Google want real content driven web sites to come top of search results, so can be a cat and mouse game.
XLMedia (LON:XLM)
They issued a RSN at 4:00pm basically saying there's a problem but they can't at the moment quantify it.
To me this simply created a false market in their shares for 30 minutes - and may continue to do so tomorrow if they don't say anything further - driven by uncertainty and fear.
Did they have to issue it ? Perhaps someone can advise me on the rules.
Surely a request to suspend the shares would be better.
It reminds me of Staffline some time ago when they simply said they couldn't produce their accounts due to an unspecified and unquantified issue and then a few hours later requested a suspension - after a drastic SP fall. Again a false market was allowed for several hours.
Phil
(Sympathies to anyone holding)
i did comment over 18 months ago mothercare had it and got slated hence dont comment no more.. glad i was correct
Sosandar (LON:SOS) and broader...
I think the SCVR report today has been an exceptional source of learning. I feel that as a customer I am getting excellent analysis when both Graham + Paul are able to provide detailed, specific and balanced analysis as they see it which then encourages a variety of posts from informed subscribers.
Sosandar (LON:SOS) has been at the back of my mind all day for a couple of reasons..... (1) I thought the price might fall further in reaction to an RNS which is in fact a PW (Profit Warning) albeit at the same time a SiS (Sales in Surplus!) and with the heavy volume possibly implying there might be support for the share price around these levels and (2) although the facts seem to be that the CASH was an over spend of 1.6m for an extra 0.6m of sales (verses forecasts), I very much doubt that the mgt team just willy nilly spend on marketing and if they were going to CASH overspend then surely they would have reduced marketing spend and just have to live with the consequences that sales would only go up "only 100%" and not the 136% that they actually did. (whatever the share price - the sales growth, the product delivery and brand development is an impressive achievement).
I was also minded of Purpleski's comments as well as my own thoughts.
Anyway the conclusion I came to , and wondered was there a Stocko community solution, is that our thoughts and posts are very much governed by our investment strategy. I am cautious and am looking to protect on the downside and try to achieve modest cumulative upside. Thus I tend to focus on the downsides of SOS (what they say as well as what they do) and because it doesn't give me my needed level of certainty, I feel uncomfortable and conclude it is not an investment for me. My post reflected this. Similar to Purpleski.
Sosandar (LON:SOS) though has many exciting features. Unlike the majority of my investments it has the potential to rise many fold in value by holding over several years - a la Dart, BOO etc... As Paul regularly points out , there will be bumps in the road if this is the path. Of course also maybe one of the bumps or an external factor will cause problems and the price might fall 50% or more (i'd hope for the vast majority of my investments this is very unlikely). But if this is your investment strategy and you have a portfolio of similar high risk / high reward shares, then Sosandar (LON:SOS) fits that criteria (and you will post similarly).
the end result is that we both post, with opposing views, yet we are both correct as Sosandar (LON:SOS) still fills the correct criteria for our respective strategies.
So, in conclusion, I wondered if like StockRanks, there was any merit to develop a "StratCode" (maybe just the current RiskRating) for us investors and then as well as declaring if we have an economic interest in the particular share we are commenting on, we also declare our typical investment strategy. So my post might be more useful to other 'Cautious Compounders' (Balanced) than to 'Risk Riders' (Highly Speculative), and maybe posts might cause less agitation as it would be more obvious the inclination of the author. i.e. a share (Sosandar (LON:SOS) being a good example) is not for my investing strategy, but that doesn't mean I am saying you are wrong holding it for your particular investment strategy.
thanks for reading! :-)
Excellent analysis Graham on Sosandar (LON:SOS), it does spark a thought on cognitive bias and how none of us can be objective when we have a position, it is simply an impossibility.
It would be extremely useful if you and Paul occasionally "take the other side" of each other's positions. Ideally independently of news flow and in practical terms, when there isn't much news flow. (and assuming a degree of sector/domain expertise). Maybe as separate cameos supplemental to SCVR? Done in a friendly but objective manner it could provide a lot of insights and balanced arguments.
Coral Products (LON:CRU) is at the bottom of Graham's very long list. In case he doesn't get that far this company can be summed up by two words - serial disappointer. The future, however, is always good provided shareholders hang on to their rose tinted spectacles.
8/6/17 PW problems at one subsid but "Overall Coral remains profitable, cash generative and with a strong asset base". CEO and CFO go.
11/10/17 Upbeat AGM statement "the Group has continued its improvement .."
12/1/18 PW "Group's results for the year ended 30 April 2018 will be materially below market expectations".
At this point I got out - I held in a dividend portfolio and that looked in danger (yes - subsequently cut completely) but also I had simply lost confidence in management who told you all was fine and a couple of months later told you it wasn't.
23/10/18 another upbeat AGM starement "With October well advanced we expect a much-improved performance overall for the six months to 31 October 2018. We remain confident of further progress in the coming year"
26/3/19 PW "the Board therefore now expects the Group's results for the year ending 30 April 2019 to be materially below both Management and Market Expectations". Confirms interim dividend would be paid but turned out to be last.
25/9/19 PW at AGM after first 4 months "sales and profits are below management's expectations...expect to still report a satisfactory outcome for the year as a whole.".
Today "we are likely to report a small loss before taxation overall for the full year and a small drop in EBITDA from the previous year. We are confident that we can build on this base and in our future performance."
Since no broker dares to produce a forecast these days we do not have anything with which to compare that statement but the market reaction says it all. Bargepole territory IMHO.
Coral Products (LON:CRU) was a Neil Woodford holding in the Patient Capital Trust at one time. I don’t know if it still is. It is almost becoming a case of make sure you avoid anything touched by him as more often than not they seem to disappoint.
Thanks Graham for the LinkedIn tip, in terms of finding where staff are located. Very interesting as I currently hold Kape.
Graham thanks for the Kape Technologies (LON:KAPE) review it has been on my watchlist for a while, I did not know about the Israeli connection that is a bit off putting.
You're very welcome, Herbie. Glad to be able to point it out. G
In September Simon Thompson at Investors Chronicle recommended Kape. He's normally pretty savvy. However, the more I googled their people and products the less I liked.
XLMedia (LON:XLM) has just tanked 33% due to Google demoting some of its websites. Has anyone heard of this happening before?
In terms of websites yes, 'smackdowns' are quite common when the Google search algos find something wrong with a website.
This thing was always a risk for XLMedia, it has thousands of websites (does anyone have a list?) but many of the ones I have seen were rather poor, more written for search engines and only tenuously providing real information to customers.
Not sure if it will be a quick fix, and obviously other sectors it operates in may be affected in future.
Having re-read it again I think it should be marked further down tomorrow in the absence of any more detail clarifying exactly what has happened. A demotion can be incredibly harsh, virtually killing organic search queries overnight.
But I'd assume XLMedia are also large customers of Google, paying lots for Adwords, and they may have some fast-track mediation services to restore their ranking, or for them to diagnose it very quickly.
I don't think there is any explanation for bringing this news out at 4pm.
From memory, I think the exact same thing happened to them last year as well.
Yes, as the business of XLMedia (LON:XLM) is to direct internet traffic, logically they should be best placed to fix the issue. However if it was a minor, day to day issue i doubt they would have informed the market.
Yes, it happens relatively frequently. Google's algorithm is constantly being evolved to serve users the best search results. A websites rankings can be affected both positively and negatively when google rolls out an algorithm update.
Graham, thank you for the LinkedIn tip. Excellent.
No probs! G
Sosandar (LON:SOS). Presumably an element of cash burn is because they are having to pay cash up front to finance stock levels given the new suppliers they are using with whom they have no credit history ? One would expect this to fall away as they establish the relationship.
So what are your thoughts on KAPE please?
Graham, thank you for your detailed and insightful write up of £SOS. One comment is in relation to the "back of the envelope calculations". These are all based on repeat orders and there are no new customers acquired, and therefore, marketing spend ceasing.
If the marketing results in an additional 25k customers per quarter, then revenue would increase by an additional £4.3m (25k x 4 x £84 [excl VAT] x 51% retained).
This would increase gross profit by an additional £2.2m, resulting in total gross profit of £7.2m
If we assume marketing was the main cause of the cash burn and it continues at £1.1m quarterly, this results in £4.4m per annum (excl. inventory). I don't believe SOS has provided figures on how much they spend on marketing.
Hi Reacher, thanks for that. I left out new customers with first-time orders to get a sense of what the company might be able to earn from existing, profitable repeat business. Your calculations provide some further possibilities, from which we might be able to guess at the full-year result (after putting in some numbers for overhead expenses).
Cheers
Graham
I'm pleased with the update today on Afh Financial (LON:AFHP) which is growing nicely, partly through organic growth (over 10% of inflows of funds) and substantially through an acquisition strategy which is targeting 'mom and pop' style businesses which, judging by previous announcements, are happy to sell at a low multiple especially when faced with increased regulatory requirements. These acquisitions seem to have gone well to date. Adjusted EPS for y/e 10/19 is 32.8p but you probably need to take out share-based payments at least from this figure which I'll do when I have more time later. So the p/e ratio for 2019 is probably around 13-14 and for 2020 likely much lower, which in my opinion makes this a growth at a very reasonable price share.
In my opinion the share price dipped last year because the company said it would relax its acquisition strategy and consolidate the gains it had made, which raised questions about the scale of future growth. However, alongside good news on its organic growth, today it sounds like it is gently warming up again to acquire more businesses:
" In the light of the December 2019 general election, the result of which we believe will deliver greater political certainty for the country, AFH will continue to focus on driving the organic growth of the business, providing professional and cost-effective services to clients while seeking appropriately priced opportunities to expand its captive distribution throughout the financial sector, to drive increased profitability and shareholder return."
I hold.
Fevertree Drinks (LON:FEVR) I hold but am likely to exit my remaining position this week after holding for nearly 5 years. I don’t think there is enough clarity on growth expectations in the US and I think sentiment has turned against the company.
Sosandar (LON:SOS) I don’t hold. I dabbled for short while but decided it was too blue sky. I do keep a watchful eye as companies like this (Boohoo (LON:BOO) Next (LON:NXT) Asos (LON:ASC) ) are going to replace the high street I am certain but whether Sosandar (LON:SOS) I think is far from sure.
I would rather wait this out for a while and see how it develops. If it comes good and say doubles from here I buy at 60p. If it then 10 bags to £3 I have made £2.40 instead of £2.70 still a good return but I think a better risk reward bet.
So I stay on the sidelines looking for positive news over the coming year.
Fair enough but you only 5 bag for the same capital invested. invest £5k at 30p and goes to £3 = £50k. Buy at 60p and goes to £3 = £25k. Therefore you are halving the potential reward. The key about the risk reward is whether you consider that if it doubles to 60p the odds of it 5 bagging are better than half the odds of it 10 bagging at 30p. Personally I don't think they are as current trading stands and therefore would prefer to be long now. I think at 60p many of the risks to them going to 300p are the same as at 30p (mis-steps to fashion collection, over-expansion etc) but obviously that's very subjective and tricky to quantify in absolute terms.
Hi David
On Sosandar (LON:SOS) I should not have used the word bag as it seems to be a bit emotive.
Currently I really don't think there is any visibility as to whether Sosandar (LON:SOS) will be another Boohoo (LON:BOO) or a zero. Therefore I am happy to give up 30p of profit by buying at 60p (of course it always assumes that I have the confidence at 60p to buy that I don't currently at 30p. The mind can mess with you in funny ways!).
I accept the percentage returns on the investment will be wholey different but in money terms I think the risk better.
If by £1,000 worth of stock at 30p and the price rises to 300p my gain is £9,000.
If one year later the price has risen to 60p and I buy the same number of shares (3333) my gain at 300p would be £8,000. I have given up a £1,000 of gain for, in my opinion, for a "better" bet and of course I have had use of the money in that year when it is not invested in £SOS. But I am prepared to make a bigger bet (£2,000 instead of £1,000) because my outcome is less uncertain.
Maybe my thinking is muddled but I think I know what I mean!!
Howard Marks' memo this month You Bet! is excellent (and entertaining) on betting and investing. It is at:
https://www.oaktreecapital.com...
Regards
Michael
"If one year later the price has risen to 60p and I buy the same number of shares (3333) my gain at 300p would be £8,000. I have given up a £1,000 of gain for, in my opinion, for a "better" bet and of course I have had use of the money in that year when it is not invested in Sosandar (LON:SOS). But I am prepared to make a bigger bet (£2,000 instead of £1,000) because my outcome is less uncertain."
What you are ignoring here is the opportunity cost of paying 60p rather than 30p. It has cost you an extra £1000. Assuming you would have deployed this at the same rate of return, that extra £1000 would have also earned an additional £9000.
Hi bryan1311
I agree but in my senario the extra £9,000 in the future is not worth the risk, with my current knowledge of Sosandar (LON:SOS), of the price going to zero.
By my strategy I am trying to reduce uncertainty. With my (and I stress my not anybody else's) I would not risk an investment in SOS but there is a possibility that I would in the future if the odds of things working out for the company increase. Of course reduced uncertainty has a cost (I win less betting on red that I do on number 8 but my uncertainty is reduced).
Why not buy them them at 15p then, you would have made even more money.
My point was related to the mathematics rather than SOS as an investment. If you can point me to a functioning time machine, then yes, I’ll buy them at 15p!
Your time may come again. Why buy at 30p when you can buy at 23p?
You can now buy nearer 20p.
The institutions look to be leading the exit charge given the volumes.
Going to be squeaky bum time given the cash burn rate if/when it does need more capital.
hi Michael,
Risk/Reward is still the same. To compensate for the fact you've missed the double you have to risk twice the capital to achieve a lesser return. This is understandable if you think that at 60p the shares are more than twice as likely to hit 300p than they do at 30p but I'd argue that is probably not the case.
On the other hand if you wait until they have achieved profitability and are still under 60p then I'd say that is probably a fair reflection of better risk/reward. There is of course no guarantee they would be so you risk losing the trade entirely.
Just an idea but If you are cautious but like a stock then perhaps there is a better way to achieve a more balanced risk/reward, which is to average in to the shares based on positive metrics. Just by way of example (ignore the numbers, its just the principle) let's say you want to risk a max of £3000. You could buy £1000 now, then another £1000 if sales targets are hit in the half year and the share price is rising and then a final £1000 on profitability if momentum is still good. You could trail a stop loss based in case of lost momentum etc.
I am thinking of this approach with Augean (LON:AUG) which having done some research I now really like. It appears to have a tremendous moat and an expanding market as well as good pricing power. EPS over the next 5 years has a CAGR exceeding 20% and it trades on a fwd PE of 12 and is highly cash generative. I can see this as a big compounder over next 5 years. My concern is the £45m HMRC tax demand that Augean (LON:AUG) whilst disputing, have shelled out to cease any further penalties and interest. If they win this money comes back but if not it is unclear what the impact will be on future profitability. So I've bought a half position, will wait a few months to check business is progressing well and see what the HMRC case brings and then on good news average up at a higher price. I've therefore protected my downside, with a clear plan on when to purchase the full position.
Sosandar (LON:SOS)
I think the Company is feelings it way through what the size of its addressable market is, and the cost of addressing it.
The inevitable question is whether the marketing investment needs to be maintained to keep the revenue growth and the stickiness of those new accounts. The jury is out, and would need someone with specific experience of online selling to second guess the realities on the ground. To some extent this was the Amazon model for many years. The danger is that this looks like a continuing fund raising model rather than the business plan which assumed some kind of earlier plateau for sustainability? The share price value is going to need to be buoyant to sustain the business if more fund raising is required.
It would be interesting to know if the business plan is going to be adjusted for a new tipping point for sustainability.
I'm interested in Kape Technologies (LON:KAPE) too. My take on this morning's update and the reference to user growth; I think they have just restated the existing 2020 earnings forecast. They also tell us about a large increase in subscription numbers, which could mean future revenue increase. I'd be more excited if they also upgraded the future earnings forecast for 20/21. I guess it all comes down to the % of subscribers that decide to renew, which they don't say much about historically or otherwise.
The focus for the coming year will be product and platform integration/rationalisation as previously stated. I think it's an exciting company, but think the announcement doesn't change what we already know.
Hi Graham
I would be interested in your thoughts on Record (LON:REC) post its TU last week. Seems to be gaining momentum and performance fees are starting to flow.
Doubt you will have time today but if you could come back to it at some time I would be grateful.
Phil
Thanks for the headsup Phil. Will see what I can do, if anything. Unlikely to have a chance today. G
Sosandar (LON:SOS) from the pov of a woman a shy over 40 an ex city worker (LIFFE) currently a freelancing (media) country bumpkin, the new collection is superb, I’d say their best yet, not my day to day faire as it’s all far too smart, but I can see why more feminine ladies / city customers love it, and can definitely see the loyalty shining through the Trustpilot reviews which the overwhelming majority are so positive, most people only bother leaving warning reviews after a negative experience. The clothes seem very inexpensive to me particularly as customers can get a further 10% off signing up to a mailing list (could be costly strategy but I hope they’ve built it in to the original price) plus they are targeting a more solvent part of the market.
I hold (and might even buy a dress.... or some boots?) mmm
Sosandar (LON:SOS)
So to beat market expectation by £0.6m cost them an extra £1.6m.
Whilst the brand is still so new we don’t actually know the loyalty or lifetime value of a customer.
I’m long currently but this update isn’t reassuring....
Really? I think you are missing the point on that spend. Acquisition of customers comes with an immediate upfront cost on marketing. Once that customer is acquired the average lifetime value of a customer should be many times that investment as all their stats appear to show, and that is the key metric.
If a customer costs me £100 to acquire today and then with nothing more than email marketing or the odd brochure spends £100 per year for the next 20 years do I care if that customer only spent £100 in their first purchase and made a net loss of £50 - No! my IRR on that is huge.
For me the update is hugely reassuring. They have good data and can pinpoint where marketing is effective and where it isn't and have enough information now to see the customer reorder rates and average basket values. Not only that but they now see lifetime value of each customer acquired as being much larger than they anticipated, potentially spanning into decades. It therefore makes a lot of sense to rapidly acquire customers at the expense of short term profits.
I agree, and also particularly impressive when it’s been such a difficult trading period for so many retailers. Growing huge % revenue without profit worked for Amazon, so I’m happy to continue to hold.
To suggest that new customers could place orders for decades is stretching credibility. Fashions change. Customers want to try new products. I have bought many clothing items online but they come from a whole range of retailers.
No it isn't. If you take the time to read the narrative you will see that they originally expected the range of customers to be in the 25-45 age range but it is actually a 25-70 age range. In other words their appeal is much wider than a niche demographic. As long as they stay on point with fashions then there is no reason at all for customers not to keep going back. That doesn't mean they won't also buy elsewhere of course but who is to say they won't buy a dress or the like each year. Brand loyalty can be surprisingly sticky, even in fashion retailers. Mis-steps in new ranges is the key risk to brand loyalty, which is where credibility of management come in.
Irrespective, the company is too early stage to truly ascertain the full lifetime average value of an average customer, but they clearly know that it appears to be much higher than they thought, which is the point of the example. The lifetime value of the customer, based on re-order rates and values, is significantly higher than the initial acquisition cost. The difference spread over the lifetime value is the IRR on that spend. The business model is important to understand.
Not sure I missed the point - the comment "we don't know the loyalty or lifetime value of a customer" seems to cover your points quite succinctly.
If you look at the graph Graham kindly posted in his analysis you will see that whilst we don't know the "final" lifetime value it is clearly more than the acquisition costs already. It is still climbing and is likely to do so for a long while to come.
Morning all!
Just to say I am looking forward to Graham's (and anyone else's) thoughts on Tekcapital (LON:TEK) .
A superficial skin of this "high spec / value trap", it looks undervalued (possibly deeply) at 0.2 of book value (if BV can be believed), but it also appears to generate meaningful revenues and a profit at the HY stage.
It also recently appointed David "brain the size of a planet" Willets (former high powered Policy Wonk , MP and Universities Minister) to its Board recently, and commented that " we think it is sagacious to wait until we report additional progress in our current portfolio before launching this effort" in relation to a possible new investment in the "cannabidiol space".
It seems to like announcing oodles of news emanating from it's Portfolio, which seems to be being revalued (upwards of course!) but there's little of substance for us to go on in terms of profitability of these investments. Amber flag?
Despite sounding cynical, I have been curious about Tekcapital (LON:TEK) to the point of taking a small starter position, but have not really been able to follow up with a deeper dive to date.
It's last FY results were 25 Feb.
Wow! Lots to look at and digest today, Graham. The ones I'd particularly appreciate would be:
Afh Financial (LON:AFHP) - this may not be a beat against forecast but revenue and eps growth looks very strong and management sound very confident. I hold
Sosandar (LON:SOS) - I was very cautious about their ability to meet revenue targets that looked like quite a stretch. And they have exceeded them. Paul's view that customer acquisition is more important than short term profits looks right to me. I hold
Fevertree Drinks (LON:FEVR) - the share price valuation is based on cracking the US. While the slight fall in UK revenues looks disappointing, this is not important as Fevertree Drinks (LON:FEVR) is already close to market saturation. But is 33% revenue growth in the US enough to give us confidence that FEVR will repeat its stellar UK growth in the UK? I'm not sure
Aptitude Software (LON:APTD) - I don't know enough about this one but it sounds interesting
Morning Graham. Would appreciate comments on Kape Technologies (LON:KAPE) if you have time, although I see the kist is already pretty long! Cheers!
kist? Read list!!
Gimmers - as KAPE has been requested by several readers, I'm happy to prioritise it! G
Many thanks Graham!
Fevertree Drinks (LON:FEVR)
Not much to like about todays update, particularly the lowered expectations for US growth in 2020, the confidence they have for an uptick in 2021 in the US seems pretty meaningless at present.
I will continue to hold but the news today really cuts back my expectations for any return in shareprice to previous higher levels short term.
Hopefully they have now "reset" expectations so future news will be be better, we will just have wait and see.
Henry Boot (LON:BOOT)
Slight miss here , other than that everything seems reasonably on track .
Sosandar (LON:SOS)
Excellent news they are ahead of expectations on revenues. The original sales targets looked very stretched so well done them for exceeding targets. Probably more important though is will this lead to them upping the 2021 sales targets? - if not the 2020 beat won't be as impressive bearing in mind its cost them more than previously planned (again) to get where they are. If sales targets for 2021 are updated that will be happy days for holders meethinks.
Logic would dictate though if they are ahead in 2020 sales numbers this should also be positive for 2021? - what do others think.
They say the US growth will be a one-off hit and return to normal. It sounds like they will be posting revenue generating expenses as a contra-revenue it seems. A little bit strange but not unprecedented.
"The Group has already conducted a number of successful trials with key customers, providing both parties with compelling evidence of our ability to unlock the wider potential of this very significant market over the medium and longer term. However, implementing these initiatives is expected to result in a one-off impact on net revenue growth in 2020 and as a result, we are revising our growth forecasts for the US business to low double digit for the year ahead before returning to previously expected growth rates thereafter."
Which group Thornabian? I hold A Fevertree Drinks (LON:FEVR) and follow Sosandar (LON:SOS)
Thx.
Fevertree Drinks (LON:FEVR) update.
Good morning team!
Here's my summary of key points in Sosandar (LON:SOS) (I'm long) trading update out today, (together with my comments in brackets);
Bullish
Neutral
Overall - I think the better than expected revenue growth rate should trump any disappointment about increased losses.
Marketing is costing way more than originally planned, but it's working. Once customer is recruited, they tend to become (not remain, as they're new customers!) loyal and repeat spend. Therefore lifetime value for these customers could be absolutely huge, and span decades in future. That's really the crux of why this company is so interesting. As they say today;
I imagine we should see a spurt of buying today, and a higher share price. Then maybe some profit taking, as the higher losses sink in? Just a guess, we'll soon find out!
Regards, Paul.
Note to Graham: feel free to paste into main report, if you wish to. I'd also be interested to hear your take on it.
I do find the Sosandar (LON:SOS) Trading Update fascinating. Not invested. Not short.
it is amazing that they have achieved 100% annual growth so all should be rosy….
...and yet I think their statement is inconsistent. it is almost like "...they do protest too much". I just can't get my head around the explanation that ".....now see they opportunity as bigger than we first thought..." !! i would have assumed given all the massive potential they have previously talked about, that SOS themselves expected to become a company with sales of £200m to £500m in 5 to 10 years (that is huge growth....) so what are they expecting now? and why does this matter when current sales are £10m? they recently had a fund raising, much larger than initially expected, and i'd have thought as part of that due diligence they might have considered flexed growth scenarios... but obviously not!! it's great to boast of great sales but it seems to me there always tends to be a "but...." with £SOS.
at a more basic level I am surprised they were so late in announcing this Trading Update. Are their systems not able to produce sales numbers more quickly than 3 weeks into the New Year??
or, (with my cynical hat on), did they need a few days to discuss with advisors about how to draft the message of ".... great sales but bigger loss and CASH outflow..."
time will tell. too much risk for my investing strategy. good luck all holders.
"so what are they expecting now? and why does this matter when current sales are £10m? they recently had a fund raising, much larger than initially expected"
They expect to be raising more money. Finding that growth is an expensive lark but keeps the punters happy.
I have no position. I recognise the opportunity and that loss making sales can be turned to high profits in the fullness of time. My caution is that this requires a level of financial control and management that they haven't demonstrated to my personal satisfaction. I've not met them and can't see how I would reassure myself on this until they have already done it - when the price will be much higher than it is now.
I’ve read a few comments here and elsewhere about the date of the Sosandar (LON:SOS) trading update.
My reading is that January selling was stronger than expected and they presumably wished to note the 160% January revenue growth (so far) and so strong start to the year. Hence reporting later in the month.
If they had reported much earlier and so not been able to include any meaningful January guidance then people could have speculated about how post-Christmas revenue was doing.
Damned if they do. Dammed if they don’t!
My morning smallcap tweet: Sosander revs up rev but loss up.
Sosandar (LON:SOS) Lightwaverf (LON:LWRF) M&C Saatchi (LON:SAA) MaxCyte Inc (LON:MXCT) Bonhill (LON:BONH) Renewi (LON:RWI) Distil (LON:DIS) Audioboom (LON:BOOM) Coral Products (LON:CRU) Accrol Group (LON:ACRL) Warehouse REIT (LON:WHR), AFH Financial (LON:AFHP)
Sosandar (SOS) sees FY rev ahead of market expectations after last Q rev £3.8m, up 136%. "Following the increased investment in customer acquisition as previously announced, the Company has seen a substantial growth in its active customer database which now stands at over 110,000, an increase of 93%." But guides FY net loss higher than previously anticipated due to high marketing spend.
LightwaveRF (LWRF) Q1 trading: rev at £1.06m down 8%. Blames "shortage of certain lines of stock in December 2020 following a record performance for the Black Friday and Cyber Monday period as previously announced." Er, Black Friday was in Q1 so that's a BS explanation. "We are pleased to see our overall sales performance returning almost to 2019 levels."
M&C Saatchi (SAA) sees FY U/L pretax in line, net cash at least £15m, substantially ahead of expectations.
MaxCyte (MXCT) guides FY rev $21.6m up 30%, beating market expectations. Profit?
Bonhill (BONH) guides FY rev £24.4m, EBITDA £2.3m, lower than market expectations as £0.25m of custom marketing contracts slipped into FY20. £2.8m integration and restructuring costs. "We have seen a promising start to 2020 with improved client engagement, order flow and an increased level of RFPs across all the businesses."
Renewi (RWI) will list on Euronext on 30 Jan. Trading in line.
Distil (DIS) guides FY profit broadly in line with market expectations. Q3 rev up 7% "supported by continued levels of up weighted marketing investment." Up-weighted? Uuuugh.
Audioboom (BOOM) guides FY rev up 91% to $22.2m. Adj EBITDA loss reduced 36% to $3m. Co "exceeded market expectations for the first time in its history." Not the best boast to make.
Coral Products (CRU) guides FY small pretax loss and lower EBITDA. Blames delay in the delivery of the MBRS tooling and "continued uncertainties".
Accrol Group (ACRL) FCA has closed its investigation relating to certain RNSs from April 2017 to November 2017. and will not be taking any action.
Warehouse REIT (WHR) inc div target for the year to 6.2p (6p). Thereafter a progressive dividend policy.
In line: AFH Financial (LON:AFHP)
A quick opinion on Kape Technologies (LON:KAPE) would be great Graham
Aim Listed - digital security and privacy software business is pleased to provide an update on trading for the year ended 31 December 2019.
Looks like massive growth in users
"user base grew to 2.35 million subscribers at year-end (30 June 2019: 1 million), comprising 74.3% organic growth within the privacy vertical not including PIA." (their latest acquisition)
All sounds provisionally positive
"We have entered 2020 in a very strong position, focused on driving earnings growth and maintaining our historic levels of strong cash generation, alongside maximising the positive impact of our acquisitions."
Yes. I would welcome views about Kape Technologies too. A transformational deal in a sector that is very topical ? Optimism well placed or is the good news already in the price?
I feel the same way on Fevertree Drinks (LON:FEVR) US market is key for them long term so the emphasis for them on the brand there is important. I own a small amount which I bought just below 1900 but would certainly buy more if it drops.
It is a very good brand and business with £128mio in cash and great margins. In time, I see the US being its biggest market.
Audioboom - Delivers a beat on Full Year revenues, with very strong growth. EBITDA loss declining ahead of expectations. One of the few ways to invest in Podcasts in UK. Interested in others views.
Sosandar (LON:SOS) Summary
Revenue for the period was above management's expectations at GBP3.8m, a 136% increase on the same period in 2018 and significantly exceeding the revenue generated for the entire first half of the financial year (GBP2.8m).
Net cash of GBP4.2m
Nice growth in revenues and Customer acquisition but...
Given the upfront cost of acquiring new customers against the benefit over the lifetime of the customer, the Company expects this investment to result in the net loss for the full year being higher than previously anticipated with the increased benefit to be experienced in future years.