Small Cap Value Report (Tue 9 April 2019) - Mello 2019, SOS, CBOX, LUCE, DEB, TPFG, BILN, PAM

Good morning!
Lots of updates to look at today.
This list is final:
- Sosandar (LON:SOS)
- Cake Box Holdings (LON:CBOX)
- Luceco (LON:LUCE)
- Debenhams (LON:DEB)
- Property Franchise (LON:TPFG)
- Billington Holdings (LON:BILN)
- Premier Asset Management (LON:PAM)
Mello 2019
A quick reminder that Mello is coming up next month, with a Trusts & Funds event on Wednesday 15th, followed by the main event.
There is a 40% discount for the main event with the discount code STOCKO40, and then the Trusts and Funds event can be added to your trip for the princely sum of £10.
The conference will incorporate the Mello Awards, so you can get your nominations in now if you'd like to influence the awards ceremony!
It will be a great chance to meet a wide range of company CEOs and fellow investors, and I look forward to seeing many of you there.
(Update by Paul Scott, who owns shares in SOS.)
Sosandar (LON:SOS)
- Share price: 28p (+6%)
- No. of shares: 116 million
- Market cap: £32.5 million
Excellent update - sales ahead of last Shore Capital forecast of £4.35m. Not sure why the company uses odd phrase "comfortably in line", instead of ahead?!
Gross margin improved to 57.7% in Q4, which I've calculated on a spreadsheet using the H1 numbers, and the Q3 trading update, plus of course today's update. This is a very high gross margin, for a company ordering small production runs. It indicates strong pricing power, and that most styles are being sold mostly at full price (little discounting). An absolutely key metric - very few competitors of this size will be getting anywhere near that level.
Cash burn (once you strip out increased inventories) is about £0.75m, down from £1m per quarter previously. That's all as planned, so I find it most odd that some posters here mention cash burn as if it's a surprise. It's not, it's as planned. They're driving growth, and that costs money. I reckon breakeven revenues are about £12m p.a.. Likely to get fairly close this year, with house broker forecasting £9.5m revs this year (ending 31/3/2020). After that, it moves into substantial profitability, and of course then the market cap would be multiples of the current level, as the market prices in continuing growth.
Another key metric is repeat orders - which are running at 54% of all orders. This proves that customers love the product, because they come back to buy more. Also, marketing spend drives additional customers, which together with repeat orders, is what's fuelling this exceptional growth.
After some terrible updates from, e.g. Quiz, and Bon Marche, I think some people mistakenly might have thought this would read-across to Sosandar. It hasn't, they're trading as well/better than expected. So I'm very pleased with this update.
Graham's view: I've played around with a few of the numbers.
Firstly, the balance sheet: the £3.6 million cash balance will be needed to fund a loss in the current financial year, FY March 2020, of perhaps £1.6 million (most recent consensus forecast visible to me), plus inventory build-up and any other balance sheet expansion. And then more of the same in FY 2021, unless it starts to become cashflow-positive by then.
Now to the income statement, where I am reverse-engineering the estimate for administrative expenses in the current financial year, assuming a 58% gross margin.
Consensus forecasts seem to suggest that a £1.2 million increase in administrative expenses this year (from £5.9 million to £7.1 million) will be able to support a £5 million increase in revenues (from £4.4 million to £9.5 million), and the loss will wind up at £1.6 million.
I've had to work this out back-to-front, so take it with a big pinch of salt:
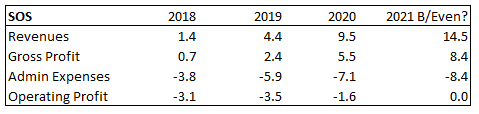
On this basis, I can therefore agree with Paul's view on breakeven in the sense that if administrative expenses stayed fixed at £7 million, breakeven would be achieved with £12 million of revenues at a 58% gross margin.
However, I would bet that administrative expenses would need to grow to support higher revenues. If the existing customer base came back unprompted and without any need for marketing spend, then maybe administrative expenses wouldn't need to grow very much. So far, it does seem that Sosandar's customers are very loyal.
However, it would be pretty unheard of, for a business like this to see its revenues roar higher while administrative expenses stayed flat.
In the table above, I assume that another £1.3 million increase in administrative expenses would be needed to grow the top line by another £5 million in FY 2021. In that scenario, Sosandar achieves breakeven.
I don't know if this forecast is too optimistic or pessimistic, and this is why I don't invest in early-stage companies! There's a very wide range of possibilities around these numbers. For what it's worth, I am leaning towards the view that another fundraising will be needed in about a year.
Cake Box Holdings (LON:CBOX)
- Share price: 159p (+1.6%)
- No. of shares: 40 million
- Market cap: £64 million
There are some obvious similarities with CAKE here, but CBOX has its own unique identity.
It's a franchisor selling egg-free cream cakes from 114 stores. It makes most of its money by selling food product to its franchisees.
The usual disclaimers for new shares must apply: this company has been listed for less than a year.
Today's update is in line with expectations:
- like-for-like sales growth of 6.5%.
- revenue up 30% due to store openings and LfL growth.
- new warehouse & distribution centres in Bradford and Coventry
It is forecast to do £5 million of pre-tax profit in FY March 2020, so the forward multiple looks quite reasonable.
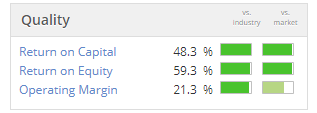
Stockopedia has noticed the high quality of earnings (thanks to the franchise model). It also pays a dividend.
This is definitely worth researching in more detail, in my view. Unfortunately, the spread is rather wide - otherwise I would probably open a small, starter position, pending further research. When the spread is too wide, I can't afford to do that!
Luceco (LON:LUCE)
- Share price: 80.35p (+5.6%)
- No. of shares: 161 million
- Market cap: £129 million
Luceco plc, a manufacturer and distributor of high quality and innovative LED lighting products, wiring accessories and portable power products, today announces its audited results for the year ended 31 December 2018 ("FY 2018" or "the period").
This has enjoyed a super recovery in the share price for anyone who bought when sentiment was most bombed out. Participants in the IPO, however, are still nursing a nasty loss.
I covered it in July 2018 (share price 34p) and January 2019 (share price 55p).
It claims to have 16% market share in UK wiring accessories, and 43% in UK portable power.
Here is a nice breakdown of the revenue movement in 2018:
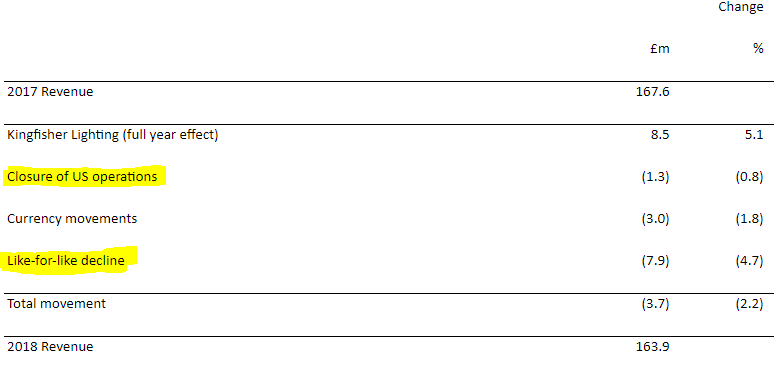
The closure of US operations is a good thing, since they were loss-making.
The like-for-like decline is a bit more worrying, and is blamed on destocking by UK retailers and weak consumer condifence.
Luceco is exposed to UK high street conditions but also highlights that it supplies a few pure-play online retailers. Their share of the group's sales is still tiny at 3.4% of the total.
The company is also exposed to copper prices and currencies - the collapse in the share price a year ago was caused by the failure of the previous finance function to manage these exposures. Luceco now seems to be on top of them.
Net debt has reduced to £32 million, another sign of stabilisation.
Debenhams (DEB)
- Suspended at 1.83p (market cap £22 million)
STOP PRESS - Debenhams has gone into administration. The equity is wiped out.
The good news for the business is that it will continue without disruption to customers, suppliers, landlords, etc. The ownership of the holding company has merely been transferred from the previous equity holders to the secured lenders.
The pre-pack administration will now be followed by a sale process. The chances of any distribution being made to shareholders following the sale are slim to none.
It's bad news for Mike Ashley and Sports Direct (SDI), who will see their 30% shareholding in Debenhams wiped out.
As recently as this morning, SDI was publishing RNS statements about its proposals to rescue the value of the equity. Unfortunately, its proposals were rejected by the Debenhams Board:
While SDI has made a number of highly conditional proposals, each of which was fully considered by the plc board, none were deemed deliverable given conditionality, timing and other stakeholder obligations and considerations.
That's a bit vague but I'm not going to use up too many brain cells figuring out exactly what went wrong with Mike Ashley's proposals.
The bottom line is that we have another casualty in high street retail, and another clear warning about the danger of getting involved in this sector.
Paul has written many times about the danger posed by Debenhams shares and deserves kudos for that.
The share price has been in a major downward spiral since 2012/2013. Hopefully anyone who wanted to get out by now has already recovered at least some of their initial stake.
Property Franchise (LON:TPFG)
- Share price: 154.5p (+5%)
- No. of shares: 26 million
- Market cap: £40 million
The Property Franchise Group PLC, one of the UK's largest property franchises, today announces its final results for the year ended 31 December 2018.
(Please note that at the time of publication, I have a long position in TPFG.)
Nice results from this estate agent franchisor.
In addition to its conventional estate agent brands, TPFG owns a small, profitable hybrid estate agent - Ewemove.
Ewemove has just produced pre-tax profit of £0.4 million, "in a year when most competing hybrid estate agents produced losses" - not bad. TPFG bought Ewemove for £8 million back in 2016.
In hindsight, that deal doesn't seem to have worked out as well as it was hoped. Only half of the contingent consideration associated with it became payable.
Overall, though, TPFG strikes me as a very responsible company. It keeps a tidy balance sheet and focuses on earning strong returns.
Then when it tries something a bit different, like Ewemove, it keeps it at a modest scale until it proves the concept. This might be less exciting than what happens with the likes of Purplebricks (LON:PURP), but it provides a great deal of safety.
And it's not as if investors have suffered at TPFG: the dividend has risen for three years in a row, with the forecast yield approaching 6%.
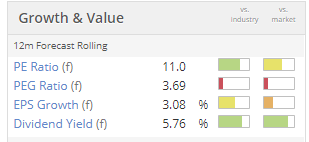
The StockRank is 97, i.e. this is a Super Stock.
Outlook is positive, with strong views that lettings are the right place to be:
...the private rented sector will continue to grow because of macro-economic drivers - continued high levels of net inward migration to the UK, the formation of smaller households because of changing family circumstances and lengthening life expectancy, the unaffordability for many people of owner occupation, negligible investment in social housing building programmes, and the lack of alternative investments with similar yields and potential for long-term capital gains.
My view
I've watched the latest interview with CEO Ian Wilson at piworld. Mr. Wilson highlights that acquisitions might be considered over the next two years, and I can understand why.
Debts have been paid down so that the company now has cash of almost £4 million, versus just £1.6 million of borrowings.
Most of the amounts borrowed are due to be paid back later this year,
As the borrowings move to zero, TPFG will have to decide what it wants to do with its large, royalty-based cash inflows.
In 2018, it generated £5.1 million in operating cash flows, before changes in working capital. Capex needs are modest, so you get a huge conversion to free cash flow.
I've been aware of this company's attractions since 2017 and have decided to take the plunge today with a starter position. Having studied it and admired it for a while, I don't want to risk seeing it continue to do very well while I'm sitting on the sidelines without even a small stake!
Competitors include Belvoir Lettings (LON:BLV) and M Winkworth (LON:WINK). They look like good companies in their own right, too, though they don't have the hybrid offering that TPFG does.
One other thing I should mention is the Tenant Fee Ban, coming into force from June 2019. This could create some disruption but I ultimately expect that fees will be passed on to landlords instead (who might pass them on to tenants). I will observe and will consider adding to my stake if business continues to run very smoothly over the summer.
Billington Holdings (LON:BILN)
- Share price: 290p (+4%)
- No. of shares: 13 million
- Market cap: £37 million
Billington Holdings Plc (AIM: BILN), one of the UK's leading structural steel and construction safety solutions specialists, is pleased to announce its audited results for the year ended 31 December 2018.
I haven't looked at this company since it's full year results statement a year ago.
Highlights:
- 5% increase in revenues (£77 million)
- 11% in increase in PBT (£4.9 million)
- Cash increases to £9.3 million
Outlook
"...trading in the current year has got off to a very positive start, with all divisions enjoying strong order books and we are seeing a robust pipeline of potential new work and opportunities."
Last year, I was looking for clues in the statement about where the company might be in its cycle. The signs seemed good for continued growth, and that has indeed turned out to be the case.
Signs for the company in the immediate future seem even better, with an "unprecedented" amount of secured work.
There is a reference to increasing capacity in the structural steel market, so that operating margins are expected to stay flat around the current level (6.5%).
On the demand side, consumption of structural steel is forecast to increase by just 0.5% in 2019, before picking up again to grow by 2.3% in 2020.
On this basis, maybe the big-picture view is a little bit more mixed. Brexit will also have to be navigated as the company has a lot of dealings with the EU. But I'm guessing that it's still too soon to call the top of the cycle.
While I haven't studied this company in any detail, my impressions on the surface remain positive, as they did a year ago.
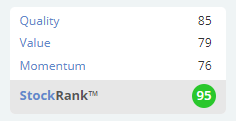
This is another Super Stock:
Premier Asset Management (LON:PAM)
- Share price: 200p (-2%)
- No. of shares: 106 million
- Market cap: £212 million
Net inflows have unfortunately reduced to a trickle at PAM in Q2. Its UK equity funds suffered a net outflow.
This reflects what I said yesterday about retail investors not participating in the recent UK share buying spree. PAM reports "record low investment industry net flow figures", and "net outflows for the industry as a whole".
Here is its list of funds - you can see that it has a strong bias to UK equities, within a multi-asset offering.
I'm not quite as fond as this as I am of Impax Asset Management (LON:IPX), because I'm not sure if PAM has a niche that can grab customers in a world where passive funds dominate.
Also worth pointing out, as I said last time, that performance seems to have been a little bit average over the past few quarters.
On balance, I do still have a positive view of Premier, and will keep it on the watchlist.
I've run out of time for today - that was a busy round of udpates.
Have a great evening.
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

54 comments
I'm v late on the Sosandar (LON:SOS) chat but here goes...
I think Q4 evidences a bit maturation in the business. For the first time they seemed to be pushing some discounting and an 'outlet' section to their website. This seems an inevitable thing as business grows. The reduction in sales Q4 v Q3 and season change is likely to drive some need for stock clearance no matter how well managed. Having an 'Outlet' seems a good idea as minimises the idea of permanent sales and also means the outlet kit on sale isn't current so less cache.
Q4 (first quarter of 2019) was a particularly tough time for UK retail. LK Bennett, Debs, Top Shop, Orla Kiely (franchised all over the place - not clothes but playing into the SOS demographic in house stuff), ASOS, Bonmarche, Superdry, Pretty Green, Select, etc all showing the strains out there. Boohoo decent results to end of Dec were more muted UK and stellar Europe and US. Will be interesting to see how they come out in Q1 2019.
Overall, it seems likely that SOS faced some headwinds. Very hard to benchmark it to past experience or expectations as so young and morphing in nature. Is the headwind a blip or something more persistent? Dunno.
However, if £1m is bad quarter with headwinds then assuming some ongoing growth perspective it seems that 50% growth on FY19 in FY20 is a decent-ish conservative base (there's nothing really conservative for a company this young and raw obvs!).
Looking at past online high gross margin growers it seems that if you can grow at 50%+ pa top line then 10x sales is a valuation that can be put on you. More generally, I think the window is 5-10x current revenue (so £4.4m currently means £22-44m versus actual of £30 currently). I'm not going to deny that this is a well dodgy valuation analysis...but its my reading of history for companies that succeed and don't die.
SOS seems to be growing above 50% pa with expectations at the 100% level and it has a business that should be higher net margin than Boo and definitely ASOS (though lacks the more mega scaling capacity of ASOS so duration of high growth).
This isn't what I'm usually comfortable with. However, last year I decided to test my boundaries on what I could invest in (I tend to be an awkward contrary sort looking for neglected value with growth drivers too...I don't like just buying asset or cash flow backing alone).
Generally, I'm looking for misperception and I reckon that SOS fits the bill. I can't argue its value though. I deal with this by only having about a 40% position in SOS. That means I can swallow a disaster and a zero. I couldn't go all in like Paul but he's a different sort of investor to me
Thanks abtan. Perfect analysis of conversion rate and is does often frustrate that people automatically assume that by doubling the marketing spend then you’ll double the conversion rate. It’s importnant management realise that it doesn’t matter how many people you send to the site if the products/value and above all for me website ease of use is not up to it then no one is going to be ‘converted’. They all go hand in hand.
On conversion it may be worth considering the impact of PSD2 on this come September 14th. Probably a lot of people have noticed that they're already getting popup messages asking for SMS one time passwords during the checkout process - that will increase after the deadline, because of the requirements on the banks to authenticate cardholders.
Today merchants can choose to opt out of this and take the hit if the transaction is fraudulent, but after the date they can't. It appears that quite a few merchants aren't ready for this, but even for those that are you'd expect this to hit conversion as it adds friction to the checkout process - and any increase in friction tends to cause an increase in abandoned transactions.
What's unknown is that because this is across the board it may not have a major overall impact - basically people have to go through this process to make a payment regardless of who their bank is or who the merchant is. And there are ways of reducing the friction if the merchant and their payment processors are switched on (although it seems that a lot of them aren't).
My guess is that a lot of online retailers will see a glitch in earnings in September, which will gradually recover. But no one really knows.
timarr
Apologies for yet another Sosandar (LON:SOS) post. I had a few further thoughts that I don't think were mentioned above:
So one would expect a boost in Q1 of 2019-20.
I don't think there's anything worrying about the fluctuations in conversion rate, but I do find it worrying that management are saying that conversion rates decreased because marketing spend decreased, as in my mind there is much more to conversion than just getting people onto the site.
As always thoughts appreciated!
Cheer
A
Hi abtan,
Re Sosandar (LON:SOS);
So one would expect a boost in Q1 of 2019-20.
I don't think that's a valid comparison. The reason being that SOS received the IPO monies late in 2017. Therefore, Q3 of FY 03/2018 would have only had partial benefit from placing monies, whereas the following quarter, Q4 would have had the full benefit of bigger marketing spend post IPO. That would have been a big benefit to Q4 revenues vs Q3 revenues last year.
Whereas this year, Q3 and Q4 reflect a constant level of available funding, but management made a strategic decision to greatly reduce marketing spend in Q4 - the house broker's latest note says that marketing spend was reduced 64% in Q4 vs Q3.
I think we're generally in danger of over-analysing the detailed numbers here, and forgetting that this is still an early stage business, where everyone (including management) is still learning about seasonality, impact of marketing spend, etc.. Therefore people are quite often drawing incorrect conclusions from not comparing apples with apples.
I prefer to look at Sosandar more in overview;
There is nothing else on the UK stockmarket like this, with such large potential % upside. The only other options are ASOS (LON:ASC) and Boohoo (LON:BOO) - but do either of those have the potential to be a 10+ bagger from here? Probably not.
It's not without risk, as it's still small, and loss-making. But it's becoming increasingly clear that Sosandar is (high probability) likely to be a major success, if you take a long-term view.
Regards, Paul.
"Test & repeat model working extremely well, with a 4-week lead time now on repeat orders, and customers pre-order via the waiting list functionality. High Street retailers simply cannot compete with that, it's a huge advantage of being small & nimble"
Not sure this is correct Paul. The fast-fashion/'test & repeat' concept was pioneered by High Street retailer Zara in the 1990s. Zara/Inditex was the first to develop a method of quickly reacting to changing trends, using agile supply chains based on sourcing production close to headquarters to speed its "lead times" — from the beginning of the design process to a product reaching stores — to about three weeks.
This business model has been copied by many UK online clothing retailers including BooHoo, Missguided & now Sosandar. It has also been copied by other High Street retailers, including H&M.
There is little that is new at Sosandar (LON:SOS) . Not the business model, nor the 'talented' management team nor the earnest optimism of its keenest shareholders. Hope burns eternal.
Hi Paul
Thanks for the detailed thoughts.
To add to your post, the 2018-19 growth is even more remarkable given that only a portion of Easter 2018 and none of Easter 2019 was included in Sosandar (LON:SOS) 's 2018-19 financial year.
Hi abtan,
The marketing at Sosandar (LON:SOS) is becoming increasingly sophisticated, as they learn what works. It would be worth you having a chat with them, so they can explain this to you.
They track what return they get from every form of marketing. It's all targeted. They then learn from response rates, and quickly ditch online ads that don't work, and drive harder ones that do work well.
Same with other forms of marketing such as posting out catalogues - if customers don't respond, then they're dropped off the mailing list. Email marketing is important, as it contains fashion ideas, editorial, etc. This is a good way of promoting slow-selling lines, and highlighting best-sellers where a repeat order is in progress.
There's all sorts of stuff going on. If you talk all this through with management, it's a lot more data-driven than investors perhaps realise.
Putting this all together, it seems to me that we should get a big uplift in sales during Apr-Jun, as that's when the marketing machine will be cranked up again, to coincide with high seasonal demand. If you look on the website, a load of best-selling sell out lines have just come back into stock. Therefore, these will be pushed hard with marketing, over the busy Easter fashion selling period.
The revenue forecasts are high, set at over 100% y-on-y growth this year. I thought the forecasts were very ambitious last year, yet they beat them. So we'll see.
Regards, Paul.
Hi Paul
Thanks again for the response.
I'm not questioning the Sosandar (LON:SOS) marketing strategy or conversion optimisation. They might both be very good at both.
I'm questioning the presumption that there is a correlation between increased marketing spend & increased conversion rates.
I used to work for an e-commerce company (now FTSE100), crunching the numbers on CTR's, CPC's, price elasticises, etc....
It was amazing seeing what small changes to the website did to conversion rates, from price increases AND decreases, to subtle changes to the colours of action buttons. From memory I believe bounce rates were even 14%-16% lower when customers landed on content pages as opposed to product pages.
So conversion was more influenced by on-site factors, rather than the marketing strategy, which, as you have noted, is mainly done off-site.
For what it's worth, I too see the bull case for Sosandar (LON:SOS) and hold a few.
Cheers
A
Petards (LON:PEG) announce their results tomorrow. Here is an extract from my blog (see my profile page):
Recent Events
Since September 2018 there have been no contract win announcements, and although during the same period in 2017 there was only one contract win announced, this will have been a disappointment to some.
For the past three years they issued their full-year results bang in the middle of March and there was some expectation they would do so again this year. It wasn't until the 25th March that they announced that they would come out tomorrow, 10th April. There is always the suspicion that bad results take longer to prepare than good ones and that perhaps they were hoping to soften the blow of missing expectations by being able to announce a contract win.
It is therefore unsurprising that the share price has been drifting down recently, however if results are in-line with a positive outlook then they look good value with Stockopedia reporting a forward PE of 10, a PEG of 0.5, potential for improving margins to improve their quality score and long term growth opportunities.
Current expectations
Expectations are for a turnover of £18m vs £15.6m in 2017, with an normalised EPS of 2p vs 1.78p.
Declaration
I hold shares in Petards and am likely to add on neutral or positive news tomorrow.
Paul: Re Sosandar (LON:SOS)
"Gross margin improved to 57.7% in Q4, which I've calculated on a spreadsheet using the H1 numbers, and the Q3 trading update, plus of course today's update."
Not being critical, but I have a VERY slightly different figure to you, so wanted to see which of us (me most probably !), has an incorrect calculation.
When I now analyse a company, I start with the AR financial notes then build a P&L, BSheet, CFlow etc. up from there (as best I can) - this way, I'm hoping that any 'red flags' in their accounts or my calcs. show up earlier as opposed to me trying to work out where I've gone wrong :o)
Anyway, from SOS: (sorry, but not sure how to do a table on here !)
H1
£1,844k Revenue
£834k C of Sales
£1,010k Gross Profit
54.77% GM
Q3
£1,600k Revenue
£747k C of Sales
£853k Gross Profit
53.30% GM
Added give:
Q1-Q3
£3,444k Revenue
£1,581k C of Sales
£1,863k Gross Profit
54.09% GM
Todays Y/E update
£4,440k Revenue
£1,998k C of Sales
£2,442k Gross Profit
55.00% GM
Take Q1-Q3 from the Y/E (to hopefully give Q4 alone)
£996k Revenue
£4178k C of Sales
£579k Gross Profit
58.15% GM
As I said, only a very minor difference, and if you have time, please let me know where my calc's have gone wrong - That 0.45% could be worth a lot if SOS takes off :o)
I was once told that if a B/S was £1 out it could be £1,000,001 and £1,000,000 out in each side ;^) - Patisserie Holdings (LON:CAKE) school of accounting I believe ! lol
Interestingly I had another Q4 GM figure for Sosandar (LON:SOS) - 56.7%
But I can see that you have used actual revenue and COS figures, whereas I used the published rounded % figures. Quite a difference!
So I agree with your numbers, but happy to be corrected.
Hi DJCP,
As I said, only a very minor difference, and if you have time, please let me know where my calc's have gone wrong - That 0.45% could be worth a lot if SOS takes off :o)
That's just a rounding difference I think, we're both saying near enough to 58% gross margin for Sosandar (LON:SOS) in Q4.
My calculations are as follows (as you can see, they're very simple);
Regards, Paul.
Hi Graham thanks for another great review of the day's news
Regarding your comment "Competitors include Belvoir Lettings (LON:BLV) and M Winkworth (LON:WINK). They look like good companies in their own right, too, though they don't have the hybrid offering that TPFG does."
Can you comment any further on Belvoir vs TPFG (I just bought into Belvoir Lettings (LON:BLV) today before reading your review of Property Franchise (LON:TPFG) )
I note that belvoir do both sales and lettings also is that what you mean by the hybrid offering? (Or does that mean that they are online only?)
I went for Belvoir Lettings (LON:BLV) mainly because of lower PE and PEG when compared to Property Franchise (LON:TPFG)
Hi IV, you're welcome. By hybrid, I was referring to Ewemove which works a bit like Purplebricks (LON:PURP). TPFG owns that but I don't think Belvoir Lettings (LON:BLV) or M Winkworth (LON:WINK) have anything similar. Cheers.
Hi Graham, the discount code STOCKO40 doesn't seem to get me any discount. I was wondering if you might know what the problem is. I can only make it for the Thursday would that be the problem? Best
Hi Camtab, please tweet to carmensfella or visit this thread:
https://www.stockopedia.com/content/mello-2019all-you-need-to-know-452333/
In case there is a problem with big caps, you could try Stocko40?
Graham
I’m a bit surprised about the comments that the gross margin at Sosandar (LON:SOS) is good because it is higher than might be normally expected.
The first thing that occurs to me is that as it is the gross rather than net margin it very much depends on what is included in cost of product.
But looking at it another way high margins do not stay high for long in markets that are highly competitive. They get competed away as the “me too” competitors realise there is money to be made in that area, unless the company has a sustainable competitive advantage. In this particular case, it is too early for the brand to be a competitive advantage, the links to influencers is not a great advantage (competitors will simply link to alternative influencers), and the targeted marketing towards a supposedly underserved segment can be copied easily. Arguably, by going public so soon the company has revealed its strategy and tactics in detail which makes it even easier to copy.
It seems that the only competitive advantage that may be sustainable is the fashion and design insight of the two founders. But in my view that is terribly weak. To be significant it needs them to get it right every season and for the inevitable lookalikes that will crop up to be clearly inferior.
So, nice to have the high gross margin in the short term but even if it is real it’s not going to be sustainable over the longer term in such a competitive business and so I would not place all that much store by it.
All good points with regard to Sosandar (LON:SOS) and their target market.
Purely anecdotally my SO and her sisters are bang in the target market for the brand but as far I have heard remain unaware of it, of course I could point them in that direction but I am keeping a watching brief at this moment
I hold and took the opportunity to top up late last week (I was waiting for the Brexit dip but that seems a little less likely now)
"£100 for a polo shirt, you must be joking? "
I quite agree. I've never understood the mentality of someone prepared to pay £250 for a t-shirt, just because it's got a particular brand on it. One of my friends used to take the pi** quite cleverly by having a little green crocodile badge on a safety pin, which he used to pin on to £5 t-shirts.
I also think that the days of being able to sell tat at ludicrous prices just because of a brand are coming to an end. For a start, there are so many fakes around that are indistinguishable from the real thing that people wearing the real thing no longer attract the envious looks that they so much crave. I believe that in China some women have now taken to displaying the receipt on the bag / whatever, so that observers can see that it's genuine!
I also think that it's increasingly seen as just vulgar to flash expensive brand names. In the `good old days' these brands tended to be worn by aristocrats and people who were genuine stars - icons like Frank Sinatra, Audrey Hepburn, Elizabeth Taylor and so on. But nowadays they're worn by rap singers and reality TV contestants. Most people who could afford to buy these brands don't want to be associated with such people.
Another factor is the general trend against conspicuous consumption and in favour of products that are fairly low key and (the magic marketing word!) `sustainable'. Despite the embarrassing efforts of luxury brands to try and greenwash themselves discerning consumers can see them for what they really are - a con trick aimed at people who are stupid, vain and excessively wealthy.
So all in all I think Sosandar have arrived at exactly the right time. Many women have seen the light and are turning their backs on overpriced `high fashion', but still want high quality, good-looking and on trend clothes. They don't want to buy the junk fashion that low end retailers churn out, particularly after seeing TV documentaries of the horrible environmental consequences of such clothes, and they are both willing and able to pay a reasonable price for good quality clothes.
Most (though admittedly not all) of the women with whom I've discussed Sosandar are very positive about it, and it's this reaction from actual customers whose opinions I respect that originally persuaded me to invest and to hang on to my shares.
I was going to say that if those same women start saying it's gone off then I'd come back and warn you, but unfortunately as a non-subscriber I'll be shut out by then!
Come on Clitheroekid, subscription to stockopedia is only the cost of a polo shirt! :)
A look at Reneuron - considering the news-and-rise ?
The question for me on Sosandar (LON:SOS) is not so much why to invest, but why now? If they do execute well and become profitable within a couple of years, then the opportunity will still exist. FWIW, I offered to pay for my significant other to buy any item from their website as a test of the service offering. 6 months on she still hasn't taken me up on it because she describes the products as mostly "weird". She is absolutely target market and what she does buy in large number are Boden dresses and to a lesser extent French Connection and Esprit. I think the idea that Sosandar (LON:SOS) have some kind of moat is fanciful but the truth lies in the numbers and not in my partners' singular experience. Time will tell, but whilst I wait to see the outcome, I will sleep better invested somewhere less reliant on the squeezed middle, post-B****t consumer.
Mission Marketing (LON:TMMG) i am writing this on my really slow tablet so may give up!
Actually look good : all numbers from continuing operations
Revenue +13% £77.6m
Headline PBT + 25% to £9m
Reported PBT +41% to £7.5m
DPS +24% to 2.1p
Talks about growing revenue c. 5% a year and improving margins from 12% now to 14%
Paying down bank debt, no longer aproblem in my view
With £95m of goodwill on the b/s it's still a "weak" b/s in traditional terms, negative tangible assets, but personally not a problem for me given it's a marketing business
Still some future liabilities to pay future earn out agreements in cash - i'd rather they pay earnouts in cash than issue equity at 6x PER valuation!
New CEOfrom bigdog agency
My view, should be trading on a much higher multiple, perhaps management should think about using cash to buy their own shares, rather than issuing more equity to make future acquisitions?
Management do deserve some credit given what's gone wrong at Porta Communications (LON:PTCM) and also shares have recovered from 2010 when company nearly went bust (trading below 10p)
Disappointing analysis of Luceco in my view. You really have to look at the H1 and H2 results separately. The turnaround in performance is clear. Margin recovery is good and proper hedging now in place for copper pricing. The company presentation reveals a great deal about performance and how they have developed a clear and much more focused strategy going forwards.
With respect, did I say anything that was incorrect about £LUCE? I acknowledged the hedging & stabilisation of performance under the new finance function. Not sure what you are looking for, TBH.
Nothing incorrect Graham but I felt it didn't take full account of the much improved 2H numbers. Operational performance is improving despite a challenging UK market. I also like the much clearer strategic focus on professional markets that I gleaned from the company presentation. Appreciate your analysis - perhaps I should counterbalance any criticism with gratitude for many great pieces of analysis you do.
Game over for Debenhams (LON:DEB) shareholders I'm afraid.
Pre-pack administration announced today. Bondholders now own the operating companies, which are continuing to trade as normal. The plc only is in administration. This almost certainly means a 100% wipeout for shareholders I'm afraid.
I hope nobody here got caught out on this one, the writing has been on the wall for some time. Bondholders call the shots in this type of situation.
Regards, Paul.
Sosandar (LON:SOS)
I too am interested in Sosandar, triggered by Paul Scott’s positive review. Paul does have expertise in this sector.
My view is it is a small start up and only has a market cap of £30m, which is tiny in the scheme of retailing.
The only thing that matters is product and growth. The rest they can figure out, although appreciate cash burn and funding are important to keep the runway long enough to survive.
On product, I have looked through their web site, their niche seems fairly pitched. Clothing targeted towards British women in their middle age that want to wear something fashionable and neither frumpy (like M&S) nor young fashion clothing (like ASOS or BooHoo) Women knowing they would look ridiculous if they kept buying younger persons’ clothing but don’t want to dress like their mother. It’s a but like middle aged men moving towards Paul Smith and away from Diesel as they get older.
I think it’s an interesting idea and has potential, given this demographic is not well served, is a large group and has strong purchasing power.
Another positive point from their web cast is they understand the concept of controlled testing for both product and size distribution. I like this a lot as it means they don’t have to be omniscient.
So, I am considering buying SOS, purely on the product play as if they can generate serious sales, the execution should follow. I know I’ll have to hold them for a couple of years and ignore most of the metrics, other than cash burn and sales. Such is start up investing.
I agree with your comment that it's 30+ women moving away from the cheaper end of the market who are buying Sosandar (LON:SOS) clothing, but I hope they're not getting the Paul Smith experience. Everything I have bought from Paul Smith in the last 2 years (1 long sleeve top, 1 polo, 1 t-shirt) apart from socks has been of such poor quality I won't ever shop there again. Cheap materials, shrink and fade in the wash. I really hope Sosandar do better.
My wife apologised to me for the poor quality of the dinosaur polo (like this one: https://www.paulsmith.com/uk/men-s-slim-fit-white-embroidered-dino-polo-shirt) that was a Christmas present. Shame, they used to do nice stuff.
If Paul Smith was listed, I think I'd be short.
£100 for a polo shirt, you must be joking?
I think a lot this expensive stuff is poor quality and sold by marketing, one pair of expensive jeans I had were probably the worst for wear I've ever had and I've had plenty of cheap ones which lasted about 10 times longer. You can get brand name polos now for about £5 each, did not shink or fade in the wash, even in Asia.
One complaint about Sosandar (LON:SOS) has been the materials, very few are natural. I think there is a market for this, something they could consider.
Morning - I'm going to have a look at Mission Marketing (LON:TMMG) results. Share price up +6%
issuing shares (at current price) to pay for earn out obligations both RJW and Krow Communications. Interestingly 65p is the trigger for managements "growth" incentive scheme. I'm a bit grumpy about this scheme, which seems to me rather unhealthily in favour of management at the expense of long time shareholders.
I'll read the release and report back if there's anything else to add.
I am still struggling to understand why Sosandar (LON:SOS) is a quoted investment. A company with £4.5m of sales and losses of not much less, with a current cash burn of £3m per annum is usually a venture capital stock. If this turns out to be the next Asos or Boohoo then all will be fine, of course. How anyone can tell at this stage, I really don't know.
Billington Holdings (LON:BILN)
As far as I can see they beat profit forecasts today and gave an upbeat outlook into FY2019. Particularly liked:-
"The level of secured work Billington takes forward into 2019 is unprecedented and ensures that we can look to the future with optimism. Undoubtedly 2019 will present its challenges, however, we are confident it will be another successful and progressive year for the Group."
This ties in with the major contract wins announced in November 2018 and:-
"Billington continues to monitor both the challenges and opportunities which may result from the UK's exit from the European Union. To date we have seen no discernible impact on trading or enquiry levels."
Phil
Hold a small stake
Could I ask that you review the date of this article - I think today is 9th April! Views on TMMG and AMER would be welcome.
Keywords Studios (LON:KWS) FY18 analyst presentation given yesterday by Andrew Day, CEO & David Broderick, CFO.
https://www.piworld.co.uk/2019/04/09/keywords-studios-kws-fy18-results-presentation/
A superb presentation. Really worth a watch. KWS keep on doing it very well. The market is growing at 9% a year, outsourcing is still less than 50%, so lots of market to grow, across many services lines. Clients are up selling to multiple service lines. They now supply 5 service lines to Fortnite! (Benefitting from being game agnostic.) Still a sector with loads of tiny players, so ripe for consolidate. Andrew goes into depth about each of the service lines. There are case studies of integration of VMC, Art service line and audio service line. And, you get all the analysts Q&A. It's long but worth it, even if you just skim through it.
according to the BBC Mike Ashley spent £150 million acquiring 30% of Debenhams, the current market cap is £22.5 million meaning if the shares hadnt been suspended that 30% is worth about £7million
dam :-(
almost feel sorry for him
Graham, can I put a request in for billington results look good today
thanks
Hi ambrosia, I will see if I can get around to Billington Holdings (LON:BILN). Cheers! G
Sosandar (LON:SOS)
pj0077
Nice try at a hatchet job :)
The Sosandar (LON:SOS) customer database rose from 100,000 in 3Q to just 105,000 - has the company really reached maturity already?
Might be nitpicking but it was less than 100k to over 105k - over 5% increase in 3 months in the quiet 3 month period isn't anything like maturity - thats over 20% - yoy growth - ok not enough if projected forward to hit targets but in summary the maturity comment is just a joke when forecasts are for sales to go from 4.2 mil to 9.5 mill and the company has not indicated they are unhappy with these forecasts - thats over 100% growth. One stat taken out of context can be whateover you want it to be if you believe the earth is flat :)
Just as worrying is the drop in the conversion rate to 2.92%
Conversion rate increased 76 bps to 2.92 on a proper LFL comparison so the conversion rate is not down on the official metric - you do have a good point though that the conversion rate YTD has dropped from the previous update - this could be entirely seasonal though if they generally struggle to convert as much in the quiet period of the year.
and a fall in average order size.
Again on the official YTD comparisons they are actually up 10% not down - ok there is a drop come the year end -from previous update but again this could be entirely seasonal. It would make sense the bumper size orders are just before XMAS or summer and not in February and March
Average order value increased 10% to £103.19.
with retail comparing non LFL metrics can sometimes if not always be meaningless.
It is a shame the company didn't give some LFL comparisons for Q1 - not sure someonelse can work these out perhaps? - again though the quiet period of the year may not give much away - all that really matters is whether they are on track for current forecasts.
Sosandar (LON:SOS) is a tiny start up that should be growing exponentially if they really do have something different to offer. I don’t think comparison with mature businesses such as Bonmarche tells us much.
The cash burn issue is possibly not so much an expectation of profitability prematurely but more an issue of whether a further fund raise will be needed this year and the consequent dilution of existing shareholders. Increasing inventory is a bit strange unless you believe that you will not be able to fulfill orders otherwise or there will be significant purchase cost savings from bigger orders. What happens if it is a wet summer and those summer dresses are not so popular?
Better margins do not necessarily indicate pricing power to me at this stage in the company’s progress. When new products are introduced it is the early adopters that are buying, not the early majority, and early adopters tend not to be price sensitive in their nature - they are looking for features other than price. So, we need to wait longer in my view to see if pricing can be maintained as the company runs out of early adopters as it grows and needs to start penetrating more price sensitive areas of the market.
Overall good progress, but still very high risk despite the progress in my view.
Re Sosandar (LON:SOS) and the "significant investment in stock of £260k was made at the end of Q4 to fulfil the peak demand going into Q1"......
I take this as no more than a positive lead indicator of confidence in future sales although I would be interested to know if this is mostly to:
i) expand the range - without hopefully straying far from women's outerwear fashion
ii) make deeper buys of ranges to reflect more confidence in selling through bigger volumes.
Either way, we should not get hung up on the micro-detail. Bounce rates, ave basket size, re-order rates etc will be volatile given the small size and changing product mix and marketing support on a rapid growth trend.
Until proven by at least another years trading, this is an early stage punt in a very small company and turnover at any decent level of margin (ie >50%) is the critical variable.
I own shares as I believe in the story that they are effectively addressing an under-served market well and thus have a good and ever increasing chance of reaching at least £30+Mn turnover pa - by which point they should have been a great investment.
Setting the turnover-for-success bar so low means I also worry less about them focusing on a potential small, relatively demographic (affluent , middle-aged, post fast fashion fashionistas). Even if it does not spread beyond this group, that is probably big enough.
At the moment we are not looking for the next M&S - more £SDRY 3 years after the first Cheltenham stall !
My concern about long term success (ie going from £30+ to £300+Mn annual turnover would be I don't seen any original creative idea in their product. Rather, reflecting the magazine background of owners, they deliver what the creatives have made fashionable eg what next after animal print!.
However, delivering on trend, good value and re-wearable fashion (that was not exactly cutting edge) with good customer service worked out very well commercially for £NXT !
Here's hoping and willing to wait another 12-18 months to find out !
Morning!
My initial reaction to Sosandar (LON:SOS) update. This is my largest long position;
Excellent update - sales ahead of last Shore Capital forecast of £4.35m. Not sure why the company uses odd phrase "comfortably in line", instead of ahead?!
Gross margin improved to 57.7% in Q4, which I've calculated on a spreadsheet using the H1 numbers, and the Q3 trading update, plus of course today's update. This is a very high gross margin, for a company ordering small production runs. It indicates strong pricing power, and that most styles are being sold mostly at full price (little discounting). An absolutely key metric - very few competitors of this size will be getting anywhere near that level.
Cash burn (once you strip out increased inventories) is about £0.75m, down from £1m per quarter previously. That's all as planned, so I find it most odd that some posters here mention cash burn as if it's a surprise. It's not, it's as planned. They're driving growth, and that costs money. I reckon breakeven revenues are about £12m p.a.. Likely to get fairly close this year, with house broker forecasting £9.5m revs this year (ending 31/3/2020). After that, it moves into substantial profitability, and of course then the market cap would be multiples of the current level, as the market prices in continuing growth.
Another key metric is repeat orders - which are running at 54% of all orders. This proves that customers love the product, because they come back to buy more. Also, marketing spend drives additional customers, which together with repeat orders, is what's fuelling this exceptional growth.
After some terrible updates from, e.g. Quiz, and Bon Marche, I think some people mistakenly might have thought this would read-across to Sosandar. It hasn't, they're trading as well/better than expected. So I'm very pleased with this update.
Regards, Paul.
The Sosandar (LON:SOS) customer database rose from 100,000 in 3Q to just 105,000 - has the company really reached maturity already?
Just as worrying is the drop in the conversion rate to 2.92% and a fall in average order size.
There are a few dark clouds hovering over this 'blue-sky' stock.
Sosandar (LON:SOS)
HI PJ0077
Should we expect the growth to be straight line throughout the year?
From today's RNS (quoted out of context, of course!) ".... the peak seasonal months of April-June"
Therefore my assumption is the coming quarter is the one that will potentially shift the dial and matters most. I could be wrong again of course.
Only a 5% increase in the customer database but do not forget they don't spend much on marketing in the quiet Jan-Mar period, as a seasonal low. Marketing spend cranks up again about now, so customer growth will increase again. It looks like they did £1.0m in revenues in Jan-Mar, which is better than I expected in the quietest quarter
In summary..... Quiet season, and low marketing spend. Yet did £1.0m revs compared with peak season (and heavy marketing spend) of £1.6m. Implies very good repeat customer spending - a key metric
Hi PJ,
The Sosandar (LON:SOS) customer database rose from 100,000 in 3Q to just 105,000 - has the company really reached maturity already?
Just as worrying is the drop in the conversion rate to 2.92% and a fall in average order size.
There are a few dark clouds hovering over this 'blue-sky' stock.
You're not taking into account the seasonality, and big reduction in marketing spend (as planned) from Q3 to Q4. So I wouldn't expect much increase in customer database, in the quietest quarter of the year, when they don't spend much on marketing.
The customer database growth should accelerate in Q1 (Apr-Jun) as that's a much busier trading period, and marketing spend is correspondingly increased - this was explained in the interview I did with management here. They target growth with marketing spend, at seasonally busy times of year - to get the fastest & biggest payback on marketing spend.
Conversion rate - good point, I'll ask management why it has dropped from 3.47 in Q3, to 2.92 for the full year. Although note that it was 2.75 in H1. So the 2.92 full year figure is actually an increase over the H1 figure. Looks like Q3 was an outlier - probably because it's the seasonally busiest time for year, so customers are looking to buy for Xmas parties, etc. Whereas in Q4 (Jan-Mar) maybe more people are just browsing? I'll ask for some colour on this anyway when I speak to management shortly.
I think the dark clouds are in your mind, not reality! ;-)
It's not a blue sky stock. It's delivering fantastic revenue growth, at high gross margins. That is not blue sky. I would define as blue sky being a company with nil, or negligible revenues, and a fancy idea. Whereas SOS is set to be profitable next financial year.
Bottom line, is that revenues are consistently beating forecasts, and that the extra gross profit generated is being spent on increased marketing spend. That's the planned strategy. Remember when this listed, it was forecasting £3.0m for the current year, which I thought looked very ambitious. It's actually delivered £4.44m - that's 48% ahead of the original plan. You won't find many early stage growth companies that out-perform on planned growth.
I'm not saying it's a blue chip. There are obviously execution risks, but given the excellent track record so far, I'd say the concept is proven. Given the quality & experience of management, risk:reward looks highly favourable to me.
Regards, Paul.
Paul,
In your SCVR of 9th January you suggested that cash burn would be £0.5m in Q4 so I'm surprised that you're not surprised that the actual figure is double that. I find it equally interesting that it's occurred during a period of low marketing spend.
Hi cockerhoop,
In your SCVR of 9th January you suggested that cash burn would be £0.5m in Q4 so I'm surprised that you're not surprised that the actual figure is double that. I find it equally interesting that it's occurred during a period of low marketing spend.
The underlying cash burn in Q4 was about £0.75m. Above that, they spent an extra £260k on stocking up, just before the year end. That £260k is not really cash burn, because the stock will be sold for more than double its cost price.
For me, the key numbers are revenue growth & gross margin. Both are very good. Maybe I under-estimated the cash burn? Trouble is, the company doesn't publish detail in the P&L costs, so any estimate from me contains rather more guesswork than I would like.
I should probably rely on the Shore Capital forecasts more, as their analyst has access to the detail which I don't.
The latest house broker note shows net cash of £3.6m at 31/3/2019, and has this dropping only £0.5m this year, to £3.1m net cash at 31/3/2020. That seems a bit ambitious to me, but time will tell.
Regards, Paul.
Hi Paul,
Broker forecasts appear to have reduced net cash since January - £4.1m (31/3/19), £3.6m (31/3/20) was noted in your earlier article.
I'm not sure it's correct to consider investment in stock as exceptional item when the company is forecast to double revenue in the new FY. Investing in stock is an inevitable consequence of expansion.
I'm interested in your view of Q4 revenue taking into account both competing effects of seasonality and the growth story. The reduction from £1.6m (Q3) to £1m seems to me to be lacklustre. I've done a back of a fag packet comparison with boohoo where the reduction post Christmas compared to pre Christmas is far less pronounced.
Cheers
Hi Cockerhoop,
Fair points, well made.
Slightly crossed wires on the inventories point though. What I'm saying is, that management explained they have spent £260k more on inventories than forecast, and as they pay for stock pro forma, then this had a corresponding reduction in cash. Hence why the underlying operational cash burn was c.£0.75m, not £1.0m.
What is striking is how SOS has managed to greatly increase revenues, with very little increase in inventories, which is great in one way, as it means that stock turn is very rapid - i.e. product is selling out fast, and at full price - which is the holy grail of fashion retail. On the other hand, it implies that they maybe haven't been buying in enough depth - thus meaning that there is unfulfilled customer demand - a nice problem to have, as you can increase sales just by increasing production runs. Although management are keen to have scarcity value on their products - i.e. to educate customers that things sell out fast, hence buy it now, or miss out.
Therefore, buying in greater depth should lead to increased sales. But it also means absorbing cash into inventories somewhat. On the other hand, bear in mind that SOS buys stock with cash up front now. As it grows, and builds relationships with factories, it will be able to move to more normal 30 day payment terms. That would free up cashflow.
I had a call with mgt today, to query a few points as follows;
They don't see any need for a further fundraising, but noted that there is institutional interest - who want to invest in placings. Therefore, the way I look at it, if they do need a small top-up fundraising, it would be quick & easy, done direct with 1 or 2 Instis. This is exactly what they did in Oct 2018. Two instis offered them the money, unsolicited, so they accepted, in order to drive growth faster, at less than 10% dilution - so what's the problem?
They're adamant that cash burn will reduce this year.
Conversion rate - was 2.75 in H1, then spiked up to 3.47 in Q3, with the full year number being 2.92. Therefore H2 was better than H1, but Q4 lower than Q3. I asked what caused the Q3 spike, which they said was down to the heavy marketing spend, and Xmas sale - both drive people to the website, who want a particular item they've seen in a brochure or online ad. It dropped back in Q4, as there was much lower marketing spend in Q4. The same factors affected the lower increase in customer database. They're going to switch to reporting active customer numbers in future, to fall into line with other eCommerce companies. It sounds to me as if the "customer database" number is not a terribly meaningful number. Active customers is more appropriate, so I'm happy with this change.
To a certain extent, I think a lot of this is background noise. All that matters to me, is that revenues have beaten forecasts, consistently. Costs seem to be running a little high, but personally I don't have a problem with that - the biggest cost is marketing, which they can flex up and down however they want, with very short lead times.
I appreciate that some investors may not be happy with investing at this stage, whilst it's still loss-making. But the point is that the concept is proven now (whereas at IPO it was just a punt). If you wait until it's profitable, you'd obviously have to pay way more for the shares. So my rationale is that, based on my sector experience, I think this now has maybe an 80% chance of success in 2 years (defining success as achieving, or coming within say 10% of the existing broker forecasts). The valuation would likely then be substantially higher than it is now - I reckon 100p is achievable in that timeframe.
So, we can either back it now, and have a 4-bagger, with some risk. Or wait and see, but have to pay maybe 4 times the current price, once the risk has gone. Looking further out (maybe 3-5 years) it seems entirely possible to me that we could be looking at 200-300p per share, if the bull case plays out.
When you talk to management, it's crystal clear that they are quietly confident about achieving the plan, and incredibly focused, working flat out to get things right.
Regards, Paul.
EDIT: By the way, it's helpful to have readers challenging the bull case, and raising queries or disagreements.
Thanks for the reply Paul appreciated.
Call me a cynic but think they've been pretty shrewd with their fundraising - it's clear that if they hadn't raised £3m in Oct 18 when approached they'd need to raise more urgently now. So they managed to get funded without any alarms or giving the appearance of being 'needy'. Could certainly see something similar occurring next Autumn.
FWIW I think the website content is excellent & does differentiate itself from competitors with the magazine style narrative.
Good numbers from Sosander (LON:SOS), but yesterday afternoon's hike in buying interest looks very sniffy!
Property Franchise (LON:TPFG) FY18 results
Good set of results in spite of market backdrop. Rev up 11%, and profit up 19.4% if you strip out one off exceptional gain, FY17. Robust balance sheet. CEO is very bullish about the market and where TPFG sits. Stephen English flagged in his recent interview, highlighting the appealing franchise model.
Here's an overview by Ian Wilson CEO: https://www.piworld.co.uk/2019/04/09/the-property-franchise-group-tpfg-fy18-results-overview-by-ian-wilson-ceo/
My morning smallcap tweet: Fat knight fails to rescue Debbie from clutches of lenders.
Sosandar (LON:SOS), Appscatter (LON:APPS), Colefax (LON:CFX), Connect (LON:CNCT), Pelatro (LON:PTRO), Debenhams (LON:DEB), £7DIG, Stride Gaming (LON:STR), Collagen Solutions (LON:COS)
Sosandar (SOS) guides FY rev up 228% to £4.44m, comfortably in line with market expectations. Gross margin 55%, up 558 bps. Loss expected to be in line with market expectations. I hold.
appScatter Group (APPS) RTO of US co Airpush and placing at 26.8p, a 55% premium! Placees get 1:1 warrants.
Colefax Group (CFX) tender offer for 8% of shares at at least 550p. SP is 475p.
Connect Group (CNCT) renews magazine distribution contract at £130m PA.
Pelatro (PTRO) secondary placing of 8% of co at 80p, a 17% discount.
Debenhams (DEB) Wipeout? Deadline passed for Mashley fat knight rescue to be approved. His post deadline £200m offer also rejected. Access to second half of new debt "will now only be available to the group's subsidiaries upon transfer of those subsidiaries into the ownership of a lender-approved entity." Would wipe out shareholders. I'm short.
7digital Group (7DIG) New CEO, CFO start. Decide material further equity and/or debt funding needed in the next quarter to meet going concern hurdle, significant dilution for holders.
Stride Gaming (STR) warns H1 net gaming rev 5% lower than expected. Also £400k extra technology and marketing investment in 51% held Passion Gaming.
Collagen Solutions (COS) guides FY rev up 18%, head of market expectations. Loss lower than expected. New FY trading in line.