Small Cap Value Report (4 Sep) - BLTG, KNOS, BNN, IQE, BVXP, JSG, TAX

Good morning!
It's Labor Day in the US which tends to make the global financial markets a lot quieter than usual. US institutions will be taking the day off.
And while the North Korean hydrogen bomb test might have spooked a few people, the FTSE is only a few points lower as of 8.45. Gold is up another 1% around its 1-year highs.
I don't usually devote any time to macro issues here, but Wall Street being closed and a hydrogen bomb seemed worth mentioning!
I will be starting stock coverage with Blancco Technology (LON:BLTG).
Cheers,
Graham
Blancco Technology (LON:BLTG)
- Share price: 77p (-25%)
- No. of shares: 64 million
- Market cap: £49 million
Updates on Revenue and Management
There has been a sea of red flags here for considerable time, both at Blancco and at its predecessor entity Regenersis.
In stock investing, there is such a thing as a smell test, and when a company fails it then you are nearly always better off staying away.
For a review of the various ways that Blancco has stood out as a low-quality offering, have a look through the archives here. It's very genesis as a stock market company was in a failed growth strategy dreamed up by investment bankers. Its accounts have been a mess, cash flow and balance sheet weak, key people have left, etc.
The red flags keep piling up here:
Blancco Technology Group plc announces that, following matters that have recently come to the Board's attention, the Board has decided to reverse £2.9m of revenues represented in two contracts that had previously been booked during the financial year ended 30 June 2017.
Revenue growth is still expected to be quite large (15% in constant currency), and cash flow is not impacted. But it confirms over-aggression in the company's revenue recognition policies.
The CEO tacitly takes responsibility by leaving with immediate effect, and the CFO becomes the new Interim CEO.
Remember that the Chairman is leaving next month, and we already had a CFO resignation in March this year.
Something has been rotten about this share from the beginning. In my opinion, it's not yet investible from a corporate governance point of view. Well done to the Stockopedia algorithms for identifying it as a Sucker Stock.
Kainos (LON:KNOS)
- Share price: 289p (unch,)
- No. of shares: 118 million
- Market cap: £341 million
My first time looking at this IT business offering digital services and digital platforms. Much of its work is focused around the implementation of Workday software - that's a US company with which I do have some familiarity. Workday competes with Oracle and SAP in human capital management (HCM) and other forms of "enterprise resource planning", to use the modern jargon.
Today's update says that full-year results (to March 2018) are set to be in line with current market expectations, based on current trading. Digital Services has delivered a "solid performance" while Digital Platform has seen very strong Workday-related growth offset by "investment" in Kainos' healthcare platform.
Checking some historic metrics, I see free cash flow conversion averaging around 100% here. Today's update confirms that the Group continues to have "a robust balance sheet and good cash generation".
My opinion
I quite like this business. Quality Rank is 96, though if you mix that with an already-high valuation, you get merely a good Magic Formula rating:
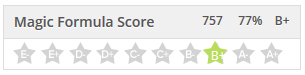
To provide a little bit of caution, I should point out that the current phenomenon of large numbers of companies migrating to the cloud for HCM solutions is not something that will last forever. According to some Workday research (external link) I've been reading, about 50% of the Fortune 500 have already made the decision about which HCM provider they will use. I wonder what percentage of large UK & European companies have made the decision yet and have moved?
Once they have effectively all moved, the current very high levels of demand for related consultancy and migration services might die down a bit. It might be several years away, it's just something I'd bear in mind if I was considering an investment here.
Overall, I'm fairly impressed by what I've read about Kainos so far. I would need to see a bit more in terms of how to justify the current valuation, but it does look worth studying in greater detail.
BNN Technology (LON:BNN) (this section written by Paul Scott)
Hi, it's Paul here. Graham has just texted me to say he has to pop out for an hour, so he's let me loose on this report to add some sections between now and lunchtime!)
Suspension of trading on AIM - this is a Chinese company on AIM. Therefore it is uninvestable as far as I'm concerned. I've had a 100% ban on any AIM Chinese companies for several years now, which has served me (and readers) very well. The trouble is that so many Chinese companies which list on AIM are frauds. We've known that for a while now, e.g. Naibu & Camkids blowing up. Plus there have been others. The whole thing is a sick joke in my view. The purpose of Chinese companies listing on AIM has mainly been to extract money from British investors.
BNN is not a company I've even looked at before, but it looks as if something has gone seriously wrong. Its shares have been suspended immediately, because;
Immediate suspension of trading. Resignation of CFO. Suspensions of both the Company CEO and the China CEO
It's not clear exactly what has gone wrong, but it's clearly serious.
The (now former) CFO, Scott Kennedy has resigned, and seems to have blown the whistle on some kind of wrong-doings within the company;
Mr Kennedy, as part of his resignation, has made a number of serious allegations with regards to the Company and the actions of Mr Darren Mercer, Chief Executive Officer and Mr Wei Qi, China CEO and Group Chief Operating Officer.
The company is now conducting an investigation.
My (Paul) opinion - I'm guessing here, but this sounds like it might be misappropriation of funds.
BNN raised £25m in a placing in Apr 2017, so possibly that might have proved too tempting for management?
Given the high prevalence of fraud at Chinese companies on AIM, we simply cannot trust any of them, in my view. It's too risky, so why get involved? I cannot understand why anyone would put money into a placing for a Chinese company on AIM.
Mark Slater reckons that Hutchison China MediTech (LON:HCM) is a rare exception, with good corporate governance. Personally though, each time a Chinese AIM stock blows up, it just reinforces my conviction that it's safest to avoid the whole lot. Why waste time & money trying to pick a needle in a haystack?
Anyway, I hope no readers were daft enough to have punted on BNN. It really is best to completely avoid all AIM Chinese stocks. Not just China either. There's usually something wrong with most overseas AIM stocks. They list on AIM because it has effectively no regulation with any clout. So it's an easy place to rip off gullible punters. Also the culprits never seem to be brought to justice. Where's Costis, with his stolen loot from Globo, for example? Sadly, white collar crime on AIM does pay. Which is why we have to be so careful, and not be a mug punter that is parted from our money.
At this stage, we don't know what has gone wrong at BNN, but it's clearly serious, as the company says in today's announcement.
IQE (LON:IQE) (this section written by Paul Scott)
(in which I, Paul, hold a long position)
Results & analyst meeting - this is a very interesting stock, and currently my largest long position. It's reporting tomorrow, and eagerly awaited news about the new Apple iPhone is one of the potential reasons to think this stock might out-perform.
I wrote very positively about IQE recently, when it was 90p. It released an intriguing RNS which sounded like potentially game-changing profit potential is in the pipeline. Several brokers have been issuing increasingly upbeat research notes lately, indicating potentially considerable upside on 2018 & 2019 forecasts.
Several readers have asked me if I can attend the analyst meeting tomorrow. So I tried to book a place, but unfortunately Instinctif Partners said no. It's just for proper analysts. Hmmmm, that's not very helpful. I don't usually have any trouble going to analyst meetings, and indeed do it all the time. Usually companies are very pleased to meet me, and thereby establish a link with 10k readers per day here. So I put a call in to IQE, asking if they would grant me access to the meeting.
Anyway, I've tried, but at the moment it's not looking promising.
Whatever the case, I'll be reporting on IQE tomorrow. I know the market cap has now risen well above our usual range here, but it's such an interesting company that it's an exception.
Bioventix (LON:BVXP) (this section written by Paul Scott)
Share price: 2545p (up 15.9% today)
No. shares: 5.14m
Market cap: £130.8m
Trading update - shareholders here must be delighted with a positive update today. This company is pretty much unique on the London market, to my knowledge. It's a tiny company, with only about a dozen staff, which produces specialist antibodies for use by pharmaceutical companies. There are long lead times to developing the products, and specialist knowledge. This enables the company to deliver spectacularly high profit margins.
The Board is pleased to report that revenues for the financial year ended 30 June 2017 are expected to be marginally in excess of 7M (2015/16: 5.5M). Since the cost-base of the Company continues to follow a similar shallow trajectory as in previous years, both revenues and profits before tax are expected to be ahead of market expectations for the year ended 30 June 2017.
A friend tells me that some of BVXP's customers report royalties in arrears, on a self-certifying basis. Hence why the figures for year ended 30 Jun 2017 are being revised at this late stage.
My opinion (Paul) - this is a remarkable little company. The bull case is compelling. The only reason I've (wrongly!) avoided the shares in the last few years, is that its tiny size & dependence on a handful of key people struck me as a risk factor.
The company is quite unusual for a highly rated growth stock, in that it pays generous & rising divis. The accounts are excellent - profit reliably turns into cash, there are no accounting issues at all here, everything looks fine to me.
Remember that this is a bull market, and considerable multiple expansion has taken place. When we first looked at this stock, it was on a PER of only 13. That has now roughly doubled to mid-twenties. I think a high PER is indeed justified, whilst the company keeps reporting strong performance. Some of the upside has come from forex benefits, which is worth bearing in mind.
I feel that high ratings are justified, providing companies keep reporting positive results & newsflow. That's exactly what Bioventix has done, so it looks good to me.
Incidentally, I don't recall ever mentioning this before, but Stockopedia has a neat feature on every company's StockReport, where it flags up which guru screens that share has passed. So you can click on that link, to view the relevant stock screen, which might flag up similar companies. This can be a very handy way of finding good stock ideas, and it's worked for me on a number of occasions.
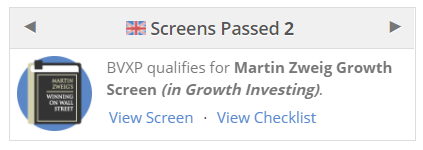
I've not looked at the Martin Zweig Growth Screen before, but this is a snippet of some of the stocks within that screen (I've sorted this list in ascending market cap order, and have selected the view which shows StockRanks);
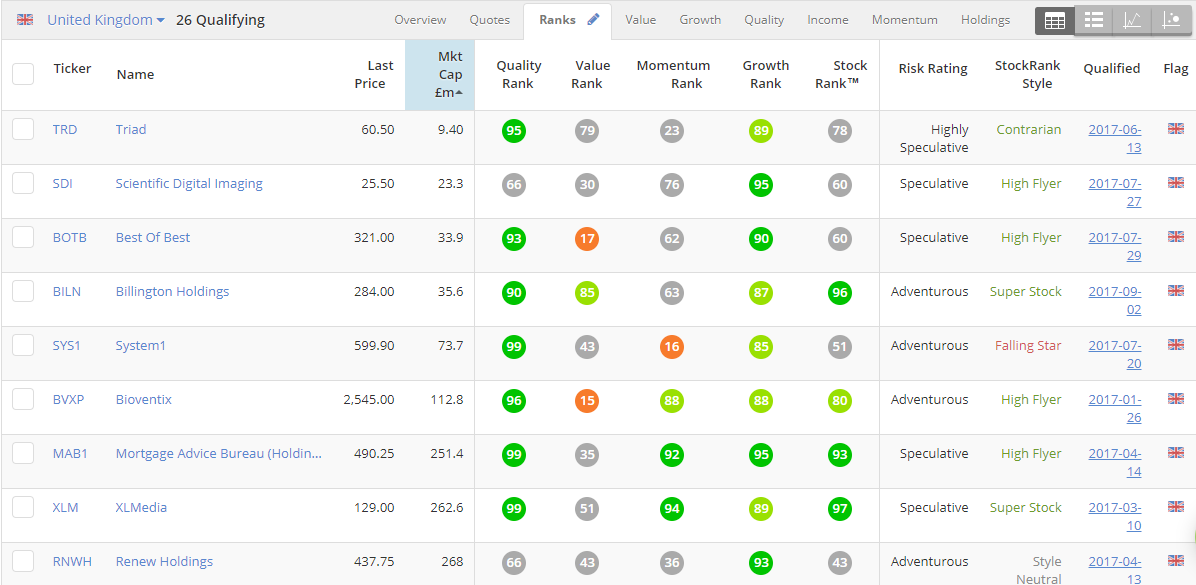
I hope that is legible. If not, I'll re-do the picture.
The stock screening features on Stockopedia are great fun for playing around with on a Sunday afternoon, when the market is not open to distract me. I've often found some smashing stocks in this way, that otherwise would have flown under my radar.
Also, you can tweak all stock screens to better fit your own personal investing criteria, which again I find very handy. I try to design stock screens which pick up as many of my current favourite investments as possible. That is a great way to find other shares with similar characteristics to the ones which are performing best in your portfolio.
Johnson Service (LON:JSG) (this section written by Paul Scott)
Share price: 141p (unchanged today)
No. shares: 366.5m
Market cap: £516.8m
Interim results - for the 6 months to 30 Jun 2017. This is a textile services business - supplying & cleaning linen and workwear for hospitality companies & others, I believe.
The headline numbers look good on a quick skim.
However, I do want to flag my concerns over the balance sheet. The group has grown through acquisitions, and this has hollowed out the balance sheet. NAV is £157m. However, once you strip out intangible assets, NTAV (a much better measure of financial strength) reduces to just minus £2.6m. I don't think that is anywhere near adequate as a capital base.
However, I should point out that net debt has been falling decently in the last 18 months. It is reported at a still-too-high £90m.
I recall how in a previous recession, a business in the same sector went badly wrong. The reasons were: too much debt, and needing to write-off a lot of the hire products because they had been under-depreciated, and/or clients with branded products went bust, rendering those products almost worthless.
Combine that with a far-from-cheap PER, and I cannot see any value here.
That said, the outlook comments today are good, in particular;
...The addition of PLS, together with continuing strong performance across all our existing brands gives us confidence in the second half performance. We expect results for the full year to be slightly ahead of current market expectations.
I've just started reading Keith Ashworth-Lord's book called "Invest in the Best". He sounds some excellent warnings about groups which grow through acquisitions, many of which ultimately go wrong. So that's worth bearing in mind.
Although for now, JSG seems to be doing well. I am nervous about the hospitality sector - where there is over-capacity, and a lot of weaker players are struggling. Could that mean JSG suffers from customers going bust in future? It's a very real risk. So that's another reason to be a bit careful with this stock, and don't all into the trap of over-paying for something which might have got a bit ahead of itself in valuation perhaps?
OK, that's me (Paul) done for now. I'll pass the baton back to Graham!
Tax Systems (LON:TAX)
- Share price: 80p (unch.)
- No. of shares: 80.7 million
- Market cap: £65 million
This has only been on the market for a year or so in its current form, after reversing into a cash shell.
It provides corporation tax software along with related services to UK & Ireland clients, and Paul has covered it here.
I am very cautious about valuations in the business software sector at the moment, but am trying to approach this with an open mind.
Nevertheless, there are prima facie reasons to be sceptical of the valuation here.
- Operating loss of £0.7 million.
- Low half-yearly revenues (£7 million) versus the market cap.
- Higher enterprise value of almost £90 million, once net debt is included.
- Negative net tangible assets of minus £35 million.
Putting all that to one side, the company achieved £3.3 million in cash generated from operations, before exceptional expenses.
The exceptional costs do have a solid justification, in my view, so on the basis that the numbers are trustworthy, almost £1 million in costs which resulted in the operating loss relate to one-off events.
However, while debt remains elevated, finance costs will too. These costs came in at £0.8 million in the latest half-year period. The CEO notes in his report that:
"..it is critical that we continue to function effectively and get the right balance between developing the business but not overstretching it by having too much leverage."
The other very big item on the income statement, bigger than the two just mentioned put together, is amortisation, which amounted to £3 million. Most of this is the amortisation of customer contracts.
The trick you need to watch out for is when a company strips out amortisation from its adjusted operating profit (as Tax Systems (LON:TAX) does) and also continues to spend resources capitalising lots of new intangible assets, over multiple time periods. When that happens, you can be fairly sure that the company is just trying to eliminate certain ongoing, predictable costs from its adjusted profit figures.
But we can give Tax Systems (LON:TAX) the benefit of the doubt that it is not doing this, as its capitalised development costs were less than £0.6 million (£576) during the period, i.e. much less than the amount of intangibles which it amortised.
Below shows how I would estimate pre-tax normalised cash flow for the interim period, using the figures given in the statement. I am willing to add back the very large non-cash amortisation, but I also deduct £576k as an estimate of normal development spending (it is the amount of development spending which the company actually capitalised over this period).
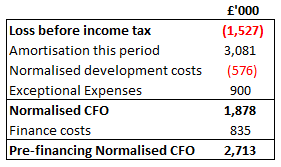
A new subsidiary ("OSMO", purchase value £3 million) was only owned since April, so it would presumably make a small improvement to the results if included for the entire half-year period.
And then the whole thing needs to be annualised, and we can make growth assumptions based on the most recent pro-forma like-for-like growth rate of 7%.
My opinion
My conclusion from all of the above is that the valuation is not as expensive as it first appears. The lack of profitability stems from the amortisation of goodwill, which stems from the assumption that the value of the customer contracts paid for at the formation of the company is headed toward zero.
Like nearly everything else in the sector, it is also probably overvalued at the moment, but it is fair to put it on a respectable multiple. Stockopedia has it on 17x.
The gearing makes it a high-risk play.
That's all for today. Many thanks to Paul for chipping in with several stocks midway through!
Cheers
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

48 comments
probably already been mentioned - but IQE has formed a fairly clear VCP pattern. As a stage two stock it seems to be on its third base, the pick up in volume shows the increase in institutional attention. The reaction today seems very positive, could be another 1-2 bases left in the stage two move - definitely likely to pick-up in volatility
There might be a connection between institutional investors not challenging high executive pay and cosy meetings at some companies. Just saying.
IQE (LON:IQE) interims statement link below:-
https://www.investegate.co.uk/iqe-plc--iqe-/gnw/iqe-plc---h1-2017---interim-results/20170905070017H1432/
Results per se are not especially exciting but plenty of Delphic comments in the notes about investment and growth potential with an "H2 mass market consumer device association" to keep the next generation I-phone speculation bandwagon going.
Gus.
There could so easily be a major improvement with AIM - if current boss Marcus Stuttard was replaced by Tom Winnifrith.
Hi, I mentioned Nanoco a week or two ago on here. Just in case anyone was looking at it, I'm very cautious at the moment following the recent update. It has promising technology but in my opinion it's probably best to tread very carefully until there's evidence of strong revenues building.
Regards
Andrew
Re: Central Asia Metals (LON:CAML) rhomboid1 offered a thesis earlier in today's comments which seems plausible. I'm not thrilled about today's news but there is nothing to be done other than wait for details of the proposed transaction and accompanying prospectus. I had one similar earlier this year in Diversified Gas & Oil (LON:DGOC) which worked out well but I am less confident in this instance.
Re: IQE (LON:IQE) They also invested in further capacity in 2016 which some people were questioning at the time. The new facility might not even be for Apple supply chain or even for VCSELs - perhaps it is for their base station work with MACOM? Or it could be for other high demand products.
Re: Bioventix (LON:BVXP) I have just been looking at the Finncap upgrade - 89.3p eps for 2017 and 2018 forecasts are under review,pending new guidance. Happy holder.
Hi all,
Does anyone have any idea about the reverse takeover at caml? (central Asia metals)
Am newish to investing and can't get my head around what possible outcomes there may be as it isn't a situation I have come across before.
Thanks in advance
Regards, Will
Paul,
BVXP, the knowledge is not in the people but the process, if the staff leave the company can employ some graduates to the same job as the process has been defined. This will be another ABC,which I have held since Adam was a lad.
A remarkable company.... Buy it, sleep on it imo
the prohibition of the likes of Paul is a total disgrace and IQE should tell their advisors to stop being so pompous
Email on its way to IQE from me too.
This IQE discussion has brought to mind something about which I have always been confused, namely the definition of trading on inside information. If a select group of analysts obtain information from a company's management which is not generally available to all and is price sensitive and that information is subsequently conveyed to clients and they trade on it is that not market abuse? Similarly if Paul or anyone else has a meeting with management, or if there is a non public meeting such as Mello, would this not potentially be also? I imagine the safeguard is that the management team must not disclose anything which is not publicly available, but then if that is the case what is the benefit of an analyst meeting with them?
They will have to sign an NDA or similar to receive privileged info if they are wall crossed. I also imagine this may be a factor as Paul wont have a formal compliance dept. and they are worried about the risk of insider info leaking out.
Theoretically, all the price sensitive information is contained in the results announcement.
Personally, I find watching or listenting to analyst presentations very useful some of the time. It really depends on the management team. The Q&A is usually most useful since the questions are normally asked by people who know the company well. Some management teams are very good at punctuating their presentations with useful factoids that help make the points. I would cite the recent results announcement from NCC (LON:NCC) (available on youtube). That presentation contained a number of factoids that weren't in the results announcement. For example: 1) there was no systematic performance review system under the previous management team 2) the company only billed completed contracts once per month leading to a significant amount of deferred revenue 3) the company, when asked to perform consulting work, frequently didn't ask the customer to issue a purchase order leading to invoices being rejected and subsequently having to get the paperwork sorted 4) the company undertook multiple office moves in the same year with, at times, double office running costs 5) after acuiring Fox IT, a contractor to the Dutch government, the previous management team didn't inform the Dutch government that the cryptologically advanced secure communications system they were delivering to the Dutch government now had a non-Dutch, eventually non-EU parent company leading to a months long suspension of the contract. Are any of these price sensitive? No. However, the mosaic effect of learning these things helped me understand how a company growing organically at 20% could suffer such a huge loss in profitability last year and why management were confident going forward.
Hello Paul, interested to hear that you are reading Keith Ashworth-Lord's book called "Invest in the Best" as, although not revolutionary, it does reaffirm many basic investing ideas and I certainly enjoyed the book and would recommend it to others. Keith is one of my favourite fund managers and his Buffetology Fund has had an impressive few years, although too short a time for definitive conclusions. One of his long time acquaintances and work associates is Ian Page, CEO of Dechra Pharmaceuticals which is held by the Buffetology Fund and which reported it annual results today. Unfortunately Dechra is a bit bigger than you would normally cover but if you get a chance I think an accounting eye over the results would be very valuable as, despite fast growth, I fear it may raise some concerns similar to those you expressed about Johnson Service today. Thanks.
emailed saying surprised as company such as IQE don't know who Paul Scott is. that's like saying they don't know who Prince harry is....
love to get a response back from them on that
Hi Paul, I know the team at IQE pretty well and hopefully you will find an invite on its way!
FREEDA do you think you could get the good people at IQE (LON:IQE) to share their Investor presentation that will be aired at tomorrow's meeting with us mere mortals? They could even put it on their website....
here's hoping
Email sent to IQE expressing my disappointment.
E-mail sent to IQE
Tern...I did very well on these before as a 10 bagger. Bought recently in a placing; bit down today though.
Sold my IQE....directors sold recently at a lower price and I can see this taking a heavy fall tomorrow unless the results are very special indeed. Of course they may be. But expectations are really high now about iphone10 etc. So banked my profit and will watch from sidelines. I might have to pay more to buy back in of course
Re the IQE (LON:IQE) presentation, I suggest that those of us who hold shares make our views known via an email to their investor relations at investors@iqep.com
1. Let Paul in tomorrow
2. In future livecast the presentations. Burford Capital would be a good example to follow. As they pick up some US investors it will be expected it as a matter of course.
Good idea John, I just sent them this:
Hi
I am a shareholder of IQE and while I may have a modest holding in comparison to some of your high net worth and institutional investors, it is significant within the context of my own portfolio.
I understand that Paul Scott from Stockopedia has not been granted access to tomorrows Analyst presentation, on the basis that he is not a 'proper analyst'.
I find this quite absurd and urge you to reconsider. Paul has a very large and loyal following and I would imagine that the total percentage of IQE owned by readers of his blog adds up to to a much more significant number.
Paul has been a big advocate of your company and a lot of your investors rely on his analysis when making investment decisions.
The world is changing and companies like Stockopedia are set to have an increasingly large impact on where people decide to invest their money. I think it's important that firms like yours embrace this change and open your doors to the people leading it.
Regards
Ben
I have emailed IQE as suggested. I hope others do too.
Re IQE (LON:IQE)
Hi Paul
You right
"Several readers have asked me if I can attend the analyst meeting tomorrow. So I tried to book a place, but unfortunately Instinctif Partners said no. It's just for proper analysts. Hmmmm, that's not very helpful. I don't usually have any trouble going to analyst meetings, and indeed do it all the time. Usually companies are very pleased to meet me, and thereby establish a link with 10k readers per day here. So I put a call in to IQE, asking if they would grant me access to the meeting."
I would say that you are a more proper analyst than most that will be attending tomorrow.
I am a comparative newbie having been properley investing for five years but feel at the moment I am getting the idea. My portfolio went nowhere (10% increase) for three years but has more than doubled (£220k to £490K) SINCE Jan 2016.
What I do not understand is why certain people (analysts) should be privy to information given out by the company and other investors are not able to see/hear/read this information. I can understand propriatary research has to be paid for but information being given out by the company should surely be diseminated in real time to all via some broadcast medium - YouTube, Twitter or other web cast technology?
ON Bioventix (LON:BVXP) I hold. this is a great little company which I have held since Oct 2015 and have bought consistently since. I will continie to hold for the long term.
As a former analyst I might suggest that there is a culture of not wanting to invite anyone to analyst meetings who might ask awkward questions. I had published a "SELL" note on Standard Chartered, and curiously I dropped off their email invite list to presentations. I mentioned it both to their Investor Relations and also their corporate broker (UBS) but somehow they kept forgetting to put me on their list to invite me to presentations.
Then I made a comment about them not inviting me which made it into the press (I've just searched for it but get this message "Some results may have been removed under data protection law in Europe") and was miraculously back on the list.
Anyway - I think the PR people think that there is no upside inviting Paul. And potential downside. I think they are wrong - but remember they work in PR and they are not paid to think.
Thanks Bruce.
Shows our little I know! But for me information that is deseminated by the managers of a quoted company should not be for the chosen few any more than, for example, the company's accounts are or information that they choose or are obliged to put out on RNS.
Certainly shareholders (if not everybody) should be able to at least hear these analyst meetings even if they can not ask questions. After all they do own the company and the managers are working for them not the analysts! (I can accept that if all attendees were allowed to ask questions the meetings would become impossible).
Surely if information is being placed in the "public" domain i.e. outside of the direct managers, accountants, lawyers and advisers of the company then the information should be available to all, in this day and age, in real time, even if all are not allowed to ask questions. For me it is more about the "all" being able to hear the information at the time.
Anyway I will take John Eustace's advice but I would like the LSE take a stand on this and make (as Ramriddge says) it a listing requirement that analyst calls/meetings are webcast.
Re: IQE ...
Speculation (http://www.macworld.co.uk/news/iphone/iphone-8-release-date-rumours-price-features-specs-3639808/) is suggesting that the new iPhone will be launched on Sept 15th and onsale in the UK by Sept 22nd.
Surely that means that any IQE technology that is included has already been manufactured and shipped to component manufacturers that supply Apple. IQE production would have had to have been in place months ago.
But IQE with Welsh Assembly Support has only just acquired further manufacturing space.
What am I missing?
Phil
Hi PhilH, You wrote:
"Re: IQE ...Speculation (http://www.macworld.co.uk/news/iphone/iphone-8-release-date-rumours-price-features-specs-3639808/) is suggesting that the new iPhone will be launched on Sept 15th and onsale in the UK by Sept 22nd. Surely that means that any IQE technology that is included has already been manufactured and shipped to component manufacturers that supply Apple. IQE production would have had to have been in place months ago. But IQE with Welsh Assembly Support has only just acquired further manufacturing space. What am I missing?"
IQE has 7 manufacturing facilities around the world. In the Mello presentation in January 2016, the Finance Director said IQE's utilisation of its manufacturing capacity was about 50% at that time. So IQE had plenty of spare capacity to ramp up its manufacture of VCSEL wafers for the launch of the new iPhone. I assume Apple will not want to manufacture too many of the new iPhones before it knows definitely what the demand for them will be from the public. Presumably the further manufacturing space to be leased from the Welsh council will be for the anticipated increase in demand for VCSEL wafers next year, which suggests that IQE's existing 7 manufacturing facilities will be running at near full capacity by then.
Hi pka,
Thanks for your response.
Wouldn't increases in things like inventories, purchasing of materials show up in the previous financial reporting?
TIA
Phil
hi paul have you any ideas why a danish investment co.would buy 11% of numis shares last thursday
Re. IQE (LON:IQE) I find it amazing that a hi tech company such as IQE doesn't provide public live webcast of their results presentations.
Similar (and smaller) US companies do so as a matter of course and full transcripts are published within a few hours after a presentation.
Re: IQE (LON:IQE) I gather that the analyst presentation will be made available to all but that doesn't include commentary or Q&A - I agree that more would be preferable but this company is now in the hands of IIs and their HNW clients and that's the audience IQE are playing to. After all, us smaller PIs have had a chance to load up for a while now!
IQE. Paul, here is one of your 10K readers who has held since 2009 (well, net of a sale of 33% when it breached 70p). Unsurprisingly it is my largest holding also. I do find the conventional analysts in companies like this are way too cautious on both the upside and downside. Understandably I guess; if you forecast a 30% earnings increase an the company produces 150% you will be praised for your insightful recommendation but deep in the doo if the numbers are switched. For this reason I would be much more interested in hearing your views as you are not obliged to make recommendations, merely observations and some indication of how you regard the company in terms of exposing your own hard earned moolah to its endeavours.
Given its dramatic increase in value it is likely there is a decent number of private investors that hold material stakes, I think IQE and its PR team are taking a bigger risk than most in excluding you and I hope the company changes its PR's mind. At the very lease they should make a webcast of their presentation publicly available.
BTW, for an extremely well articulated explanation of the bull case, have a read of the ADVFN posts by Sweenoid.
Blancco Technology (LON:BLTG) - This has been like watching a slow motion car crash - morbidly absorbing as long as you are watching from afar.
The total lack of explanation or context in today's update for the revenue reversal beggars belief and I think the PR company has to take some of the blame for that. Without elaborating as to how or why the reversal has happened, investors are naturally going to assume there are question marks over other numbers in the accounts.
Thus far the company has only spoken of write downs and reversals in respect of FY17, however I struggle to see how these problems can be isolated only to FY17 given their July update spoke about the write-off of receivables arising from:
In theory I suppose it is possible that their previous approach to revenue recognition, although aggressive, produced numbers which were "true and fair", but the write down of receivables this year in relation to last year's revenue suggests otherwise, and there must be a high chance of prior year restatements which is not something the company has thus far countenanced, or at least not in public.
And if we do get prior year restatements, disclosures on revenue recognition in last year's annual report like "The [audit] Committee was satisfied that the assumptions used were appropriately scrutinised, challenged and sufficiently robust", make you wonder about the entire financial control environment. Indeed it might be reasonable for investors to assume these revenue recognition disclosures in the annual report are a work of fiction:
It seems to me it's not just the executive management that has questions to answer, but also the non-executives who sit on the audit committee who appear to have been asleep on the job, and possibly the auditors who signed off on last year's numbers.
And just to top it off the directors' remuneration looks obscenely high - £3m last year which is higher than the £2.6m adjusted operating profit they are now guiding towards for this year.
Having said all that, I have a suspicion (it's no more than that) that there could be a decent core business hidden behind the poor governance and weak financial controls. There is no way I would even think about investing though unless and until there is more clarity on revenue recognition, they get some credible management in place who have done a proper kitchen sink job, and there is minimal risk of further dilution due to poor cashflow.
I'm not a holder of Blancco Technology (LON:BLTG). I find the announcement equally curious. I would want to know how the board's "attention" was drawn to this contract where the revenue was de-recognised. Did the auditors write to the audit committee? Did the interim CFO bring it up? When was this revenue originally booked? Under the previous CFO or under the interim CFO? The interim CFO must have performed some review of the accounts receivable because they wrote off part of the balance. Why didn't this contract come up 2 months ago when that review was completed? It's hard to imagine a scenario where the interim CFO is entirely blameless. I don't understand why he's been elevated from interim CFO to interim CEO.
Disappointing to hear about your experience re IQE (LON:IQE) meeting tomorrow Paul.
As a big holder, I would have welcomed your take on proceedings.
I'm not expecting them to say anything directly about Apple but do hope they might be able to make it obvious with guidance.
Persevere.
Do either of you have any thoughts on the rns today from Central Asia Metals (CAML)?
Warning pure speculation!
My guess is it's connected to 19% shareholder https://en.m.wikipedia.org/wiki/Kenges_Rakishev
I'm guessing he wants to reverse some privately held interests into Central Asia Metals (LON:CAML) to avoid the hassle,delay & scrutiny involved if he were to attempt to IPO them independently, no idea whether it's good or bad for holders but I'm guessing it'll take a while to find out ..
Thanks, rhomboid.
Thanks for offering up that possibility rhom - not likely to be good for PIs if you're right but I'll keep an open mind until we get the facts (not that there is any choice in the matter).
He's very well connected!!
Might be a difficult person to deal with if he tried to throw his weight around. Still Nick Clarke always comes across as a very sound and reliable.
I hope that is not true ref Central Asia Metals (LON:CAML). I can only see that as being bad as I would guess a reason for doing that might be to then sell it off as it is monetised as shares.
Hi Rhomboid
Saw this on ADVFN. In tune with your Central Asia Metals (LON:CAML) speculation. I hold btw.
Could be Kenges Rakishev is lining up a London quote for SAT & Company?
Since November 2006 Kenges Rakishev is the large shareholder and chairman of the board of SAT & Company (KASE: SATC), a diversified industrial holding combining more than 30 companies across different industrial sectors, such as mining, metallurgy, construction, mechanical engineering, oil trading, minerals exploration and recycling.
From 2008 Sat & Company rapidly increased its international presence through acquisition of the new assets in China and Turkey (ferroalloy plants and mining companies exploring ferroalloys, chrome, nickel, zinc and coal). According to Bloomberg, by the beginning of 2013 market capitalization of Sat & Company made up $500 mln. By December 2015 Rakishev gained control over 75,61% of the company's shares.
In June 27, 2013 Central Asia Metals (LON:CAML) became the sole owner of Kounrad copper project in Kazakhstan by exchanging 20% of Central Asia Metals (LON:CAML) shares into 40% of Kounrad stake owned by Kenges. Thus, Kenges was appointed as non-executive director of Central Asia Metals plc.
On March 13, 2014 Kenges Rakishev joined the board of directors of JSC "National Company "Kazakhstan Engineering" - large holding combining 27 enterprises of the defensive industry and munitions factories of the Ministry of Defence of the Republic of Kazakhstan. He left the board one year later, upon the appointment of Imangali Tasmagambetov as the new Minister of Defence.
I'm afraid I don't share any excitement in KNOS - on a current p/e of 30 they seem very expensive considering in the last prelims the revenue was only +7% and the profit figures were flat. I also have had first hand experience of KNOS in the provision of a document management and workflow solution and I don't particularly rate them that highly...
Tern (LON:TERN) issued its half year report today and fell 12%. It's an AIM listed investor in Internet of Things companies, last reported on in SCVR a long time ago (having just raised some cash at twice the current price). It's a "contrarian" stock but as the new chairman has a well-deserved favourable reputation, I may open a position. TechmarketView is positive about one of its companies, Device Authority (formerly Cryptosoft).
Another interesting pointer on BLTG was back in April when, after a round of profit warnings and management firings, there was a certain amount of comment that "the bad news is behind us" and i "ts time to get back into a growing company" etc. But right at that time Finncap gave a "Sell" recommendation with a 100p target (while the price was over 150p).
I pay only modest heed to a bullish broker call with a heady price target, but an actual "sell" call is a different matter entirely. I hit the eject button immediately. Thank goodness.
Precise, clear and unambiguous. Great.
Morning Graham!
Yet more bad news from Blancco Technology (LON:BLTG) as you report above. I've checked back through the archive, and see you did a terrific demolition job on the shares back in Mar 2017, here.
Also, I flagged up more problems, especially with revenue recognition (which looks to have been much too aggressive, here in Jul 2017.
Today's update says that adjusted operating profit for the year ended 30 Jun 2017 will be not less than £2.6m. Note that this compares very badly with a forecast of £5.5m for the same metric given on 6 Jul 2017 by the company.
When you look at this history of this company, it's looking more & more like a sophisticated pump & dump. Remember how former mgt were constantly appearing at investor evenings & shows, to pump up the share price? Then they ditched their own shareholdings at close to the peak, before the bad news started to flow. I have mentally blacklisted former management here, especially Matthew Peacock, who seems to have left behind a trail of destruction, once he'd banked his profits.
I totally agree with your point about it being best to avoid companies with a bad smell. The run of bad news at BLTG has been astonishing - just one thing after another. Why get involved when you don't have to? I certainly wouldn't buy this share, at any price. We just can't rely on the reported numbers at all, in my view.
Regards, Paul.