Small Cap Value Report (Fri 01 Dec 2023) - JHD, MERC, MIND, DPEU, ATG

Good morning, it's Roland and Graham here with today's report.
The RNS feed is a bit quieter today, as it's Friday, so we're hoping to catch up with some backlog items from earlier in the week.
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions
on them as possible candidates for further research if they interest
you. Our opinions will sometimes turn out to be right, and sometimes
wrong, because it's anybody's guess what direction market sentiment will
take & nobody can predict the future with certainty. We are
analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or
serious problems, so anyone looking at the share needs to be aware of
the high risk. Sometimes risky shares can produce high returns, if they
survive/recover. So again, we're not saying the share price will
necessarily under-perform, we're just flagging the high risk.
Agenda
Summaries
Mercia Asset Management (LON:MERC) - 28.5p (£127m) - Interim Results - Graham - GREEN
This regional investor posted interim results this week. The investment thesis I set out at the start of the year remains intact, I think: Mercia offers a strong cash position, a healthy 3rd party fund management business, and a big discount to NAV. Share buyback now underway.
DP Eurasia NV (LON:DPEU) - 84.5p (£124m) - Interim Results - Graham - AMBER
Corporate drama as the DPEU’s majority shareholder wants to buy it for 85p per share, but they didn’t come to an agreement with DPEU’s “extremely disappointed” board before making the offer. The company is trading very well and I agree the bid is opportunistic.
Mind Gym (LON:MIND) - down 3% to 37.4p (£38m) - interim results - Roland - RED
This corporate training software group has reported a big H1 loss and significant cash outflows. The outlook for H2 is much stronger, but I think there’s still a risk Mind Gym could run short of cash before a turnaround can be effected.
Auction Technology (LON:ATG) - down 23% y’day (£589m) - final results - Roland - AMBER
Cautious guidance for the year ahead has triggered a cut to profit forecasts and a big share slump. But I think this previously overpriced 2021 IPO has some attractive qualities and could potentially be starting to offer some value.
Quick comment (no section below)
James Halstead (LON:JHD) - AGM Statement - 198p (pre-market) (£855m) - Roland - GREEN
Jjust a quick comment to highlight today’s AGM Statement from this AIM-listed, family-run, floorcovering business. Trading is said to be ahead of the prior year and the company will approve its final dividend today, marking an impressive 47th year of dividend growth.
This business is highly profitable, very cash generative and in my view extremely well run. The shares have 10-bagged over the last 20 years – just an example of the quality available (selectively) on the UK market. As Ed as highlighted in his recent multibagger research, supposedly boring companies can sometimes outperform more exciting options. That's certainly been the case here:
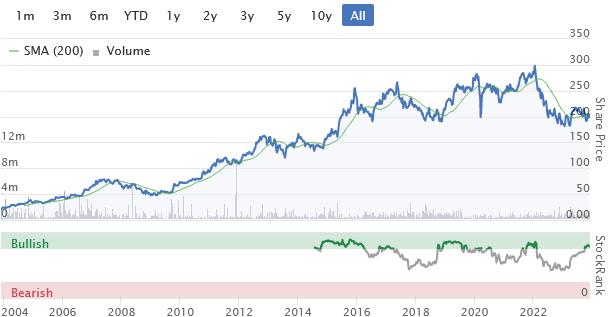
I think the shares look reasonably valued at 200p, given Halstead’s track record.
Graham's section
Mercia Asset Management (LON:MERC)
- Share price: 28.5p
- Market cap: £127m
This one has been in the backlog for a few days. Let’s cover it now at last.
Mercia Asset Management PLC (AIM: MERC), the proactive regionally focused, profitable specialist asset manager with c.£1.5billion of assets under management ("AuM"), is pleased to announce its interim results for the six months ended 30 September 2023.
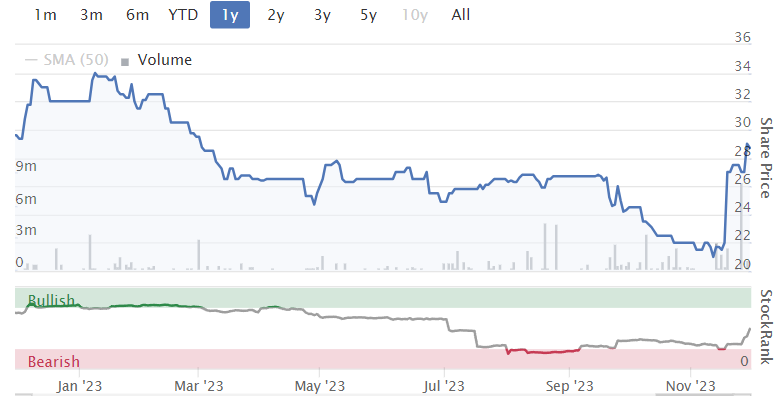
The last time I wrote about this was in my Ten ideas for 2023, published back in January. The share price that day was 33.5p.
At 29p today, it hasn’t been a year to write home about in terms of share price performance:
However, the actual operating performance of the company continues to encourage.
Here are the highlights from the interim results to September, which were published this week:
Revenue £15m (H1 last year: £12.2m)
Adj. operating profit £5.5m (H1 last year: £3.6m)
Fair value of its direct investment portfolio: £142.5m
Cash position was £36.5m at the end of H1, rising to £60m following the sale of an investment (“nDreams”).
Net assets per share were 45.3p at the end of H1 (56% above the current share price). I think NAV was boosted by an additional penny by the sale of nDreams.
Mercia is both a 3rd-party fund management business and a direct investor. 3rd party funds under management are at £1.26 billion, little changed over six months, “with no redemptions”.
Buyback - there is a £5m share buyback, “reflecting strong cash position of the Group and confidence in the business”. Seems like a sensible move, especially considering the discount to NAV. The share count will be reduced by a few percentage points.
The Chief Financial Officer acknowledges that “relatively recent share buybacks in the specialist asset management sector have done little to positively affect share price performance and a resultant reduction in discounts to net asset value.”
CEO comment:
Mercia's competitive advantage comprises its people, geographic footprint, long-term investment performance, supportive stakeholders and broad capital deployment capabilities in the private markets, which continue to experience a healthy level of capital availability, in contrast to the public markets. Challenges in the private markets do exist however and relate to the cyclical nature of venture investing, based on sector and business stage.
Mercia will invest between £0.5m-£20m into a business: I like this range, where private market deals can offer excellent value. We have seen other successful investors deploying these small amounts before (think of the likes of Judges Scientific).
It is strategically looking to grow its 3rd party fund management business now, rather than focusing on its own investment portfolio.
It might even sell parts of its own investment portfolio and use the proceeds to fund bolt-on acquisitions for its fund management business:
…we are now taking a more cautionary approach to direct investing. Reflecting this caution, we have paused adding new companies to our direct investment portfolio, although we will continue to support the existing portfolio. In parallel, we will concentrate on accelerating the growth of our managed funds' operation, both organically and via very selective acquisitions, by utilising some of the proceeds from direct asset realisations, such as the post period end profitable exit from nDreams.
Long-term goals: in April 2021, the company set a target of total AuM (3rd party and own funds) of £1.6 billion by March 2024.
It won’t be easy to reach this but they are currently at £1.46 billion, so they did ok (AuM was £960m when they set the target).
They also wanted to achieve average PBT of £20m p.a. over the three years to March 2024. This is very unlikely to be achieved.
Outlook is positive:
There currently exists strong growth potential in Mercia's managed funds' operation across all three pools of private capital. With our focus on scaling the profitable delivery of our fund management operations, we anticipate continued momentum through the remainder of the current financial year and beyond.
Graham’s view
I continue to see this stock as offering a tremendous amount of value and potential at this price. It is cheaper than it was when I first spoke positively about it a year ago, but the company’s performance over the year strikes me as quite good.
I will acknowledge that the income statement shows a statutory operating loss of £1.3 million, not helped by a negative movement of £1.6m in the fair value of Mercia’s investments. Given the income climate this year, I think this could have been a lot worse! But the enormous cash balance, the dividend payment and the buybacks all suggest that the company is in rude health.
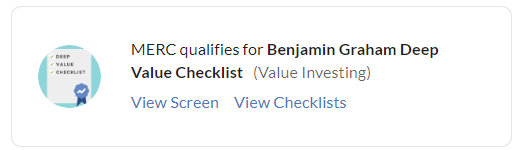
I also note that this stock passes a prestigious screen:
DP Eurasia NV (LON:DPEU)
- Share price: 84.5p
- Market cap: £124m
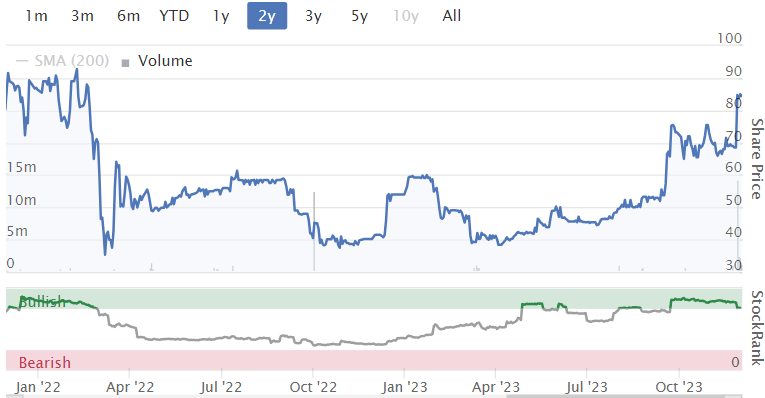
These shares have finally achieved a “bagger” status for anyone who managed to buy in at the lows:
Earlier this week, it was announced that Jubilant Foodworks was happy to pay 85p for the DPEU shares it does not already own.
Jubilant Foodworks:
was already a 49% shareholder of DPEU.
holds the Domino’s master franchise for India, Nepal, Sri Lanka and Bangladesh.
It didn’t take a great deal of wisdom to think that Jubilant wouldn’t mind owning 100% of DPEU, rather than 49%. This is something I speculated about before. But the eventual price was hard to guess at, especially considering that DPEU’s own finances have at times seemed precarious.
The offer is a 24% premium to the prevailing share price. Compared to the average premium we see being offered to prevailing share prices, I would say this is the bare minimum.
Interestingly, the board of DPEU don’t seem overly impressed by the offer. On the evening of the 28th, the day of the offer, they said:
The Offer is both unsolicited and unexpected. For the time being, shareholders are advised to take no action.
Jubilant has also started buying DPEU shares again, and has now brought its stake up to 53.5%.
DPEU’s board have been caught by surprise, and are still analysing the offer. Today they say (emphasis added):
DP Eurasia has worked openly and constructively with Jubilant Foodworks operationally and recognises the value that it brings. However, the Board is extremely disappointed that Jubilant Foodworks decided to proceed in this unsolicited and opportunistic way and without first seeking to reach an agreement on terms which the Board would be able to endorse as in the best interests of all stakeholders.
The Board is determined to protect the interests of the Company's minority shareholders and other stakeholders, continues to advise shareholders to take no action and will outline its position in a further update early next week.
Trading update
Coincidentally, the day of Jubilant’s offer also saw the publication of a trading update for the ten months to the end of October..
The number of stores (also including Coffy) is up 87 to 761.
System sales more than doubled to 6.2 billion Turkish lira.
After making accounting adjustments for hyperinflation in Turkey, system sales are considered to be up 38%, with like-for-like growth of 29%.
Liquidity: 402 million Turkish lira (£11m) and an undrawn bank facility for 523 million lira.
Outlook: in line with guidance.
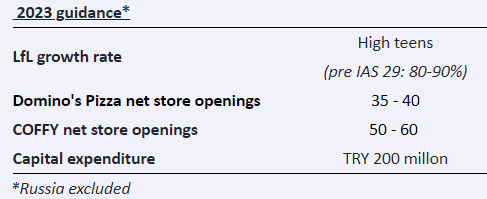
Long-standing CEO Aslan Saranga provided a generous amount of commentary, here’s an excerpt:
"We are pleased to report sustained like-for-like growth well above inflation as well as achieving continued network expansion while navigating geopolitical and macro uncertainties. Our strategy enables us to combat the high levels of volatility in the regions in which we operate and, as Q4 progresses, we are seeing the impact of our efforts becoming increasingly visible in terms of volume generation and customer acquisition…
"This has been another excellent period for the Group, and we look forward to a strong end to the financial year."
Graham’s view
I’ve been following this stock for a long time, hoping to see the day when it would finally come good and become a quality Domino’s stock.
The strong trading update suggests that the day might be closer than ever, but it looks as if the majority shareholder has noticed the same thing and wants to enjoy the company’s success on its own.
Let’s do a quick comparison. There are 1,200 Domino’s in the UK and Ireland, and Domino's Pizza (LON:DOM) is worth £1.48 billion. That’s £1.2 million per store.
Excluding coffee shops, DPEU has about 700 stores and is valued at around £125m by this offer. That values each store at £180k.
Naturally we can assume that a store in the UK and Ireland is worth considerably more than a store in Turkey or Georgia. But is it worth six times more?
I would not be at all surprised if DPEU’s board and minority shareholders held out for more from Jubilant.
Roland's section
Mind Gym (LON:MIND)
- Share price: 37.4p (-3%)
- Market cap: £38m
“MindGym (AIM: MIND), the global provider of human capital and business improvement solutions, announces its half year results for the six months ended 30 September 2023.”
This software group appears to provide corporate training and performance management solutions, covering areas such as “WellWorking”, “Leadership development” and “Personal effectiveness”.
Today’s interim results are described as being in line with “recently revised expectations for the full year”. This refers to a profit warning issued in October, when revenue guidance was cut from £62.6m to £48.4m and profit forecasts were reversed into a full-year loss.
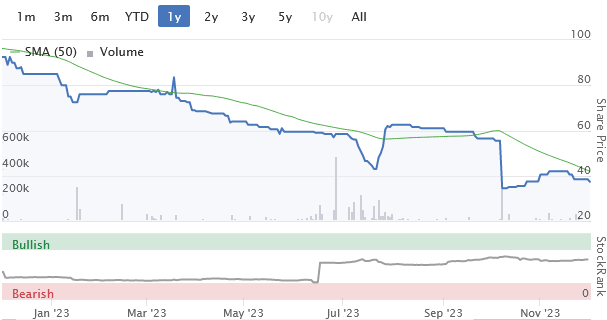
Paul covered the profit warning here and went RED on the stock, so I thought it would be useful to take another look to see if today’s accounts and commentary provide any additional information or highlight a turnaround opportunity.
H1 results summary: October’s profit warning was attributed to weakness in US markets. This seems to have been due to a slump in spending by US tech firms. That’s evident in today’s numbers, which cover the six months to 30 September 2023:
Revenue down 22% to £20.9m
US revenue down 33% to £11.1m
EMEA revenue down 3% to £9.8m
Reassuringly, trading in EMEA seems to have remained stable. The company says a £2.0m contract that was delayed in H1 was launched successfully in September and should deliver revenue in H2.
However, profit and cash performance for the half year was dire, despite an impressive-sounding gross profit margin of 85.4% (H1 FY23: 87.5%):
Adjusted EBITDA loss of £4.1m
Reported pre-tax loss of £13.2m
Cash at bank: £2.1m (31 March 2023: £7.6m)
Capital expenditure: £3.0m (H1 FY23: £2.2m)
As Paul commented, Mind Gym capitalises a lot of its software development spend onto the balance sheet. This capitalised spend represents real cash outflows during the reporting period.
We can see from the highlights above that Mind Gym burned through £5.5m of cash during H1. The cash flow statement shows us why:
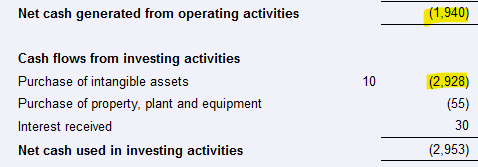
Operating cash flow was negative for the period. In addition, the company spent (actual cash) £2.9m on software development that was capitalised. This gives us a total of £4.9m, reflecting the £5.5m reduction in cash during the period. (The remaining £0.6m reflects lease payments, which are reported further down the cash flow statement in financing activities.)
Cash position/spending cuts: Mind Gym says that it had £2.1m of cash on hand at the end of September and access to £2.0m of its undrawn £10.0m debt facility, “which it does not expect to utilise”.
In order to reduce cash burn, the company says it is planning big spending cuts:
Operating expenses will be cut by an annualised £4.5m, generating savings from H2, but incurring a £1.1m restructuring charge
Capex (i.e. capitalised software development) will be paused, except on digital assets that are already revenue generating. This is expected to reduce capex by £3.5m to an expected level of £2.5m in FY25.
The reduction in capex has triggered a £6.6m impairment charge, which is reflected in the pre-tax loss of £13.2m above. The impairment relates to software that was under development but has now been paused and is no longer expected to become part of an identifiable commercial product. This is one of the accounting requirements for capitalising software spend, hence an impairment charge was needed.
Personally, I am not entirely convinced that Mind Gym will be able to complete this restructuring process and return to profitability without running short of cash. However, the outlook for H2 does seem to be significantly improved.
Current trading & outlook: trading is said to be in line with the board’s revised expectations for the full year.
The company says that conversion of sales opportunities in the US “remains slow”. However, the picture in EMEA is brighter; there have been “several notable project wins” since the start of October.
H2 FY24 is also expected to see significant benefit from the Energy framework (the delayed £2m contract I mentioned earlier). Six-month forward bookings at the start of October were higher than the same position 12 months ago. As a result, management expect the business to be profitable during the second half of the year:
Combined with the impact of the revised cost base, this will enable a return to strong profitability in H2 FY24
However, this seems to refer to H2 profitability only, not full-year profits. An updated note on Research Tree today from Mind Gym’s house broker, Liberum - many thanks - confirms that a full-year loss is expected for FY24, with negative earnings of 1.7p per share.
Earnings are expected to rise to +2.2p per share in FY25, according to Liberum.
Founder-CEO stepping aside: until now, this business has been run by founder and 55% shareholder Octavius Black.
Mind Gym has now appointed a new CEO, Christoffer Ellehuus who will join in January as CEO designate. Mr Black will be stepping aside to become executive chairman.
Roland’s view
My reading of today’s results suggests that if everything goes exactly to plan in H2, Mind Gym might be able to scrape by without running out of cash.
Personally, I think there’s still a material risk of a cash crunch that could result in a fundraising or expensive short-term debt funding.
Investors with an in-depth understanding of the company’s pipeline may feel more confident than me, but personally I think this situation looks too risky to be appealing. I’m going to stay RED on this one until I see evidence the group is operating sustainably.
Auction Technology (LON:ATG)
- Share price: 498p (down 23% y’day)
- Market cap: £589m
Auction Technology Group plc ("ATG", "the Company", "the Group") (LON: ATG), operator of world-leading marketplaces for curated online auctions, today announces its financial results for the year ended 30 September 2023.
This is a specialist online auction group that operates in areas such as art and antiques, providing software that allows auction houses to sell to online bidders.
This was (opportunistically?) floated by private equity in early 2021 and became ludicrously overvalued during the pandemic, in my view.
This week’s slump seems to have been triggered by a slightly softer outlook than expected, but these interim results do not seem too bad to me. I wonder if the shares may be approaching a level at which they could start to offer value.
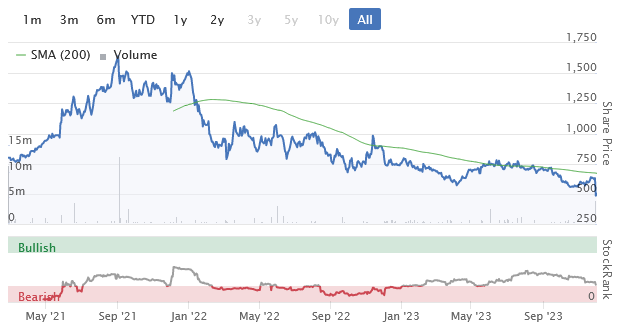
Graham previously covered this business in May. Let’s bring the record up to date with a look at this week’s final results.
Full-year results highlights: ATG’s full-year numbers seem to show some positive trends:
Revenue up 13% to £135.2m
Operating profit up 34% to £22.5m
Operating margin: 17% (FY22: 14%)
Adjusted earnings up 11% to 32.6p per share
Adjusted net debt down by 12% to £115.7m
Cash generated by operations up 17% to £57.7m
These numbers value the shares on a trailing P/E of 15 and seem to show positive cash generation and an attractive operating margin.
A quick look at the cash flow statement suggests to me that the business generated about £29m of free cash flow last year, excluding acquisitions. That looks like an impressive level of cash conversion, when compared to reported post-tax profit of £16.9m.
One possible concern is the rising cost of debt; the company’s weighted average interest charge doubled from 4% to 8% last year. However, net debt is falling and there’s no major refinancing due to 2026. I don’t see any critical concerns.
Trading commentary: Auction Technology Group provides a range of value-added services in addition to its core auction software. These include a payment gateway, shipping service, and digital marketing solutions.
Value-added services revenue rose by 27% last year and now accounts for 18% of total revenue. If the services are good, then I’d imagine that this revenue line could continue to grow at a higher rate than underlying auction activity.
The value of items auctioned on the group’s systems was fairly flat last year, with total hammer value (THV) up 3% at constant currency. Management says there was a small decline in H2, reflecting more normal conditions in Industrial & Commercial markets and softer conditions in Art & Antiques auction markets.
Acquisitions: the company acquired ESN during the period, which is described as “a leading US estate sales platform”. Integration is underway and the business is said to be “performing ahead of initial business case”.
Current Trading & Outlook: I haven’t seen anything in the company’s FY23 results to explain this week’s share price drop. So I have to conclude that the trigger for this fall is probably in the outlook statement.
The company is striking a cautious note at this stage:
THV and GMV growth have been impacted by macroeconomic factors over the course of the year. In the short term, the business continues to be impacted by underlying market growth which remains relatively uncertain.
However, continued growth in value-added services is still expected to support a 5% to 8% increase in FY24 organic revenue.
Total revenue growth in FY24 is expected to be higher than this, due to the contribution from ESN.
Management expects to maintain last year’s adjusted EBITDA margin of 47%.
There’s an updated broker note from Cavendish on Research Tree which helpfully provides updated earnings forecasts.
Cavendish has trimmed its FY24 earnings forecasts from 36p to 33.9p per share. This would still represent a small amount of growth from FY23 adj eps of 32.6p, but might explain the weak sentiment towards the stock this week.
Roland’s view
This week’s results do not seem too bad to me, while the more cautious outlook is unsurprising, in my view.
The updated broker forecasts price Auction Technology shares at around 14 times forecast earnings. This doesn’t necessarily seem too expensive to me, for a business with double-digit margins and reasonable cash generation.
If this business can continue to make steady incremental progress, then I think the shares could be approaching a level where they offer some value.
I’m not sure there’s any rush to get involved here, but I will be keeping a more interested eye on this business than I have done to date.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

66 comments
Is anyone else having problems with the news feed ? I'm regularly logging in and finding 0 news items for both my feed and the general feed ?
No. I get too many, often about 15% of the whole market. The markets are closed so I would not expect many now.
105 on my feed out of 880. Are you still having problems today? If so, you should report it.
Journeo (LON:JNEO) - does anyone know whether development spend R&D spend in the form of developer wages is capitalised, whether partly or in total? Many thanks.
From memory Journeo (LON:JNEO) capitalise very little BnB but would need to double check on the details
Thanks David.
Today a very good friend of mine has alerted me about a laughable research on Rua Life Sciences (LON:RUA)
Only last week the same PAID research was claiming that the company’s strategy lowered the risk of an equity raise. Today an equity raise was announced and the price has dropped about 45%.
Todays research claims that the shares are worth 542p-currently trading at 12p!!
Never touched this company , never will , but everyone should be very very careful about all these different researchers available and their crazy valuations.
Re: the research on Rua Life Sciences (LON:RUA). Would be interesting to know who did the "research"? Sounds like any connection to them would be a red flag
Rua Life Sciences (LON:RUA)
https://www.stockopedia.com/co...
https://www.stockopedia.com/co...
The two more recent ones have not been posted on here:
https://www.equitydevelopment....
https://www.equitydevelopment....
Did anyone make money out of Quarto yesterday?? (I know we are all serious investors here). When I looked first thing (I was at Mello) they were 60p down 40% against a rns announcing they are delisting from the main mkt and no intention of joining Aim. Great I understand what has happened (unusual). I looked again just after lunch over a pound. Back to my normal complete confusion. I assume investors don't believe them or don't feel they will get the obligatory 75%. Lau and Montecristo own approx 72% and the announcement says they have irrevocable undertakings of 72.4%. Yes totally confused. So I would expect them to fall again today.......uhhh...they are only up 9%. Did I miss something? Oh yes the company is offering a tender for the shares so that will be ok then. Only no price is mentioned. Is it me?
The RNS was first put out as a delisting without price and presumably people panicked. About an hr and half later the details were put through but only on the national storage as a (not-guaranteed) 150p / share tender, with almost all insiders committed to not tendering. Quick traders who had that on watch got in from 75p. AFAICS at 120p its potentially 25% return in a couple months IF everything goes to plan. https://x.com/sam88990/status/...
Thankyou I missed that entirely. Much appreciated. The smog clears.
Very good Mello Conference this year. Unfortunately I was only able to visit for Thursday and Wed evening (when I sat on a table within hearing distance of the GREAT Paul Scott, ooo the aura!!) I was going to say hi Paul but you were ushered away to something. Anyway I thought the sessions with Christopher Mills and the Cockney Rebel made it worth while alone, with the cream on the cake being able to see Journeo (which lead to an investment) and hear Gervais Williams expressing a view that Small Cap UK stocks will have a great year next year.......ah well here's to hoping. All the best.
Re ME International (LON:MEGP) some insights from Berenberg:
Berenberg believes ‘overlooked’ ME Group developing well
ME Group (MEGP), formerly Photo-Me, is on track for record profits this year but still remains ‘overlooked’, says Berenberg. Analyst Eleanor Spencer retained her ‘buy’ recommendation and target price of 200p on the stock, which was trading at 128p on Thursday.
The group, which operates photobooths, laundry services, and food vending machines in 19 countries, confirmed it will deliver record profit before tax in full-year 2023, hitting the top end of guidance. ‘For the second half, this implies £40m in adjusted profit before tax - up by 52% year-on-year – 5% ahead of our estimates,’ said Spencer. ‘While we believe its Feed.ME division may have grown slower than expected, both Wash.ME and Photo.ME developed well.’
Spencer said the update confirmed ‘resilient consumer demand and improving machine roll-out rates’. ‘We think ME Group remains an attractive, overlooked growth story and with shares trading on just 6.7x full-year 2024 enterprise value/EBIT, we think its stock looks cheap,’ she said.
I love Stocko charting tools. Breaks above 150 then we can put some 'washing in the bag, and take a photo whilst doing it'.
Does anyone have any thoughts/insight on Petrofac (LON:PFC) ? Sharp SP decline over the last few days with no news/RNS? Thanks, Chris
PFC won and is still winning lots of oil services contracts both onshore and offshore . No one can explain the sharp fall in its share price including brokers.
PFC must come out and issue a statement about the reasons or non-reasons for the dramatic fall in its share price.
According to LSE there are over 7% short positions almost all added to in November
Petrofac (LON:PFC) ..given the history of bribery & the SFO’s successful prosecution a couple of years ago…I’d suggest it’s possible that something else has been uncovered…possibly by one of parties that is now shorting the stock….total guessing on my part I should add
Petrofac (LON:PFC) bonds have been in distressed mode for some time now. I don’t really understand why it took so long for its share price to collapse!
yiannos1 - I've been trying to find Petrofac's bonds and they aren't on any of my lists - do you know where they are listed?
Frankfurt
Thanks yiannos1 - for anyone else who is interested here is the chart:
According to the bond prices (under 50 now) all existing shareholders will be wiped out in Petrofac (LON:PFC).
Agreed on Petrofac (LON:PFC) situation looks bad - seems like the bonds are hovering on the edge of an expected equity wipe out on a refinance imo. I won’t be touching the debt or equity here. The distressed debt / special situation bond teams will be looking at the situation ant these levels and working out recovery rates - they will have more than just an ‘edge’ over any retail so be careful.
The figure for shorts is correct.
Good summary of the current position from Berenberg, note that there is a risk of dilution and that's probably what underlies the fall in the share price: 'In a worst-case scenario, Petrofac may be forced to renegotiate its financing agreements, potentially leaving shareholders significantly diluted. Alternatively, if the company is able to overcome this liquidity crisis, we believe the outlook could be brighter and valuation would increase significantly," said the analysts.'
News expected 20 December apparently.
For old news but probably still pertinent the best source I have seen concerning this company in the last 2 years has been shareprophets.com (paywall and occasional bad language) https://shareprophets.com/EPIC...
This is from Petrofac (LON:PFC) August results.
"In the operating context of a relatively small number of historic contracts currently in execution in E&C, the maturity of that portfolio and the new awards being at an early stage in their contract life cycle, the near-term liquidity forecasts are reliant on a small number of relatively high value collections, the timing of which are not wholly within the control of management.
Whilst the liquidity forecasts, on a mitigated severe but plausible scenario, show that the Group maintains positive liquidity and remains in compliance with the minimum liquidity financial covenant throughout the Assessment Period, delays in these collections could pose a risk to covenant compliance and to the Group’s liquidity.
Until such time as these near-term collections have been secured, therefore, there is a material uncertainty that the Group can maintain covenant compliance and positive liquidity throughout the Assessment Period."
Down ~80% since results. Chart is horrific with volume increasing.
Good to see you back Wolfie boy
Brickability (LON:BRCK) interim results presentation just started on InvestorMeet...
(I hold)
Did anyone see Journeo (LON:JNEO) at Mello per chance. Be interested to hear what people thought.
I did, spoke to the CEO, Chairman and FD and they were all brimming with confidence. Seem to have lots of momentum behind them and winning multiple contracts. If they execute on their NY contract then hopefully they will win orders for phases 2 and 3 (CEO sounded hopeful/optimistic). Also their Scandinavian purchase, although small looks like a great entry point into Europe and platform for cross selling. They are on the lookout for further small strategic purchases. No large foreseeable CAPEX spend on the horizon, increasing shift towards SAAS and higher margins.
Overall very bullish was my take but just for the record I do hold :)
Thanks BurntOnions
I really wanted to get to Mello and see them but alas had to attend a board meeting abroad mid part of the week.
My sense is that there’s a lot of momentum behind the business globally and a lot of market to go for. I feel that with patience this has the hallmarks of a company that can multi bag. Net cash, strong order books, growing market, growing credibility, good platforms in key locations and a strong mgmt team. It seems your perception of the meeting gives me some validation. I’m thinking of buying more here but waiting a bit to temper enthusiasm post results.
Thanks for the write up - appreciated and understand you are long and therefore biased!!!
Yes multi bagger potential for sure, only £37m market cap and net cash on the books with no major CAPEX requirements.
Other snippets of info were regarding the runway they had as surely there are only so many buses and train stations you can equip with hardware but the CEO reckons they are more than 10 years away from any sort of market saturation in the UK and there is a constant cycle of upgrading equipment.
They also talked about getting their recurring revenues up to a level where from January 1st their fixed costs would be covered
And finally medium term goal was to get revenues up to the £100m mark (from the current £46m)
I can't think of anything else just now, I will also be topping up on any pullbacks.
Good luck!
I think covering fixed costs with recurring was an aspiration rather than something for Jan 1. In conversation afterwards they made a lot of piggy backing on their clients for international growth : Transdev in the states for airports and the media company internationally with whom their MTA contract sits . I agree all bullish but I also hold . Given how big the manufacturing piece is post Infotec , I think it’s a bit overdone to try and think of this as a SaaS company anytime soon . Software is 25% of 6mn ARR so tiny even if growing fast . Closing their manufacturing in Coventry and moving in with Infotec would be very synergistic if they ever needed to .
I hadn’t realised the importance of the Scotrail contract . It’s a bit delayed but if it works on all Scottish trains , maybe it gets rolled out nationwide . I think 400p is reasonable shortish term = 15x a n upgraded 27p for 2024
Agreed but we need to stop talking about it as the price is going up and I was hoping to get some more a bit lower!!!
It would be so nice if people could remember to make clear what company they are talking about! I had to go back through 4 posts to discover it was Journeo (LON:JNEO) .
Apologies, you're absolutely right
Journeo (LON:JNEO)
Good summary from Burnt Onions. I couldn't help but be Impressed by the presentation and the numbers. I don't hold and would have bought yesterday, but felt that I needed to get a better overall understanding of the business before hitting the buy button.
The share price rise today was no doubt a consequence of yesterday's Mello outing.
I was also impressed by the presentation from Ultimate Products (LON:ULTP). Another stock I don't own, but very much on the buy list, if the opportunity and funds align.
As Shein, I believe, contributed to (though was not solely responsible for) my biggest ever single loss because of my investment in Boohoo (LON:BOO) I thought I would post this link to the FT article on the IPO of Shein next year.
Reclusive Shein founder Sky Xu prepares to enter the spotlight with IPO
https://on.ft.com/415DDx6
I certainly will not be a buyer, but it will interesting to have another online fast fashion direct to consumer quoted company to compare ASOS (LON:ASC) and Boohoo with.
Regards
Michael
Vertu Motors (LON:VTU)
Today's RNS reveals that yesterday's large buyer was not Cinch as educated guesses on here yesterday suggested (including me).
The buyer was Nivag Holdings Ltd who bought 11.3m shares (3.31%).
A bit of digging reveals that Nivag Holdings is the private company of Gavin Hydes who is CEO of The Joe Duffy Group, a major Irish car dealership. In 2021, following buying out minority interests, his stake in Joe Duffy was 90%.
Interesting stuff. Looks like the pot may be beginning to boil for a bidding war for Vertu?
Snazzy
Vertu Motors (LON:VTU) . I think it's better than that. The RNS stated yesterday's buyer was TDR Capital and they hold a larger amount, 6.07%. Today's RNS Nivag purchase took them to 3.31%. Interesting.
hi GN100
Vertu Motors (LON:VTU). I hold.
To clarify:
Conversation on here yesterday was that the identity of yesterday's buyer was likely to be Cinch, in which case they would have increased their stake from 6% to 9.3%.
Cinch's stake is in the name of TDR Capital who own Constellation Automotive Group who in turn own Cinch.
As it turns out, yesterday's new buyer (Nivag Holdings Ltd) effectively appears to be The Joe Duffy Group who bought an initial holding of 3.31%.
Cinch upped their holdings on 28/11 (per RNS dated 29/11) to 6.07%.
Will be interesting to see how this plays out.
Snazzy
They seem to be too small to bid for Vertu Motors (LON:VTU) as their revenues are only 10-12% of VM.
Looks like Cinch will need some allies here.
Vertu Motors (LON:VTU) Thanks Snazzy for the clarification. As you say - interesting to see what happens. I hold.
Braemar (LON:BMS) results were finally published last week. We have a FY23 Finals & H1 FY24 interims webinar with management at 1pm today including a Q&A. Register here.
Thanks Graham for the update on Mercia Asset Management (LON:MERC) - I agree this looks tremendous value. Trading at a big discount to NAV with about half market cap in cash and with a buyback underway.
On top of the investment portfolio and the cash, you get a good quality asset management business which appears to have a strong niche and seeing good growth (mainly held in institutional closed-ended funds, so you don't have the constant risk of redemptions that effect the retail fund managers). I think the asset management business is worth around 15p, so that would bring the total NAV to about 60p.
Vertu Motors (LON:VTU) The plot thickens…
https://www.stockopedia.com/sh...
Vertu Motors (LON:VTU) Any idea who Nivag Holdings are?
Do subscribers here pay much attention to the Beneish M-Score? I ask because Good Energy (LON:GOOD) passes 9 Long screens but fails the M-Score. The screen itself has returned -36% over the last year! So not very effective. Good's StockRank is 99.
Hi eParo
i think that given the Beneish M score screen is to identify companies you want to avoid - a negative result shows that the screen is working
Hi eParo, I asked this on the green button about Good Energy (LON:GOOD) and got the reply below.
Me: Looking at Good Energy (GOOD), how can a a company with a high quality rank also have a high earnings manipulation M-score? What should I be looking for to resolve this?
Answer: The QualityRank encompasses more ratios than just the earnings manipulation score. Please see here for further details. The return on capital is very high. This would boost the QualityRank. The company also has a 9/9 Piotroski-F Score.
It didn't explain what's behind the high M-score, but hope it helps you somewhat. As a result, I did buy some but I'm chasing the rising stock price with my soft stop-loss (which is a Stocko alert, not an order with my trading platform) so if it turns, I hope not to lose the gains I've made. Dare to dream.
Mello thoughts .
If anyone interested as Fridays always slow .
Some titbits from Mello
Re- Christopher mills
Posh bloke though not quite as posh in real life knows his onions and brilliant insights .
Seems keen on Carrs and there is clearly a sea change of activity following harwood pressure to restructure .I’m going to start to build a position to watch this unfold .
Also mentioned Eckoh and pendragon .as ones he’s building on
Ref - Sanderson / Lisa Montague
Packed out presentation and very focused and presentable . Looks a great CEO
I reckon they have a pretty compelling “moat” in the ability to digitally print matching fabrics and wallpapers. Digital versus tradition printing has no Set up on screens etc .
Collared her after and has a chat with her and aFD .
The production side is basically break even and profits coming from license , though you need one to get the other she suggested .
I said the comments “royalty revenues are lumpy” has been made (on here) and asked whether she was confident the future royalty income was a rising tide set to increase long term and she very much thinks so.
Asked the FD about stock as it looks 3-5 million too high and he said it would be heading that direction .
Impressive, though accepting breakeven in production and profit on license I think is questionable and given their clear production advantages and ability no reason not to get the production to be making profit .
Colefax is a customer of theirs and I hold both, in the next months I’ll be selling Colefax on strength and increasing SDG on weakness .
Tried to sell her a new boardroom table too .
Ref - Richard Staveley
Packed out room, regular presentation which was well received
Can’t say enough good stuff .
Looked a bit flustered when questioned on the pressure tech 14.5% load with convertibles which puts them in a heads you win tails you win at pressure tech but just about pulled it off
Didn’t mention Pennant which they ate trying something with but that looks one to watch
Talked directly to him after about titon , congratulated him on ousting chairman and gane of thrones kingmaker Keith Ritchie and they are ready to get to work. If they can divest the Korean operation ASAP they will Sort that
REF - Filtronic
Spoke to them few times and went to presentation
CEO is grounded and likeable seemed to like interest and I said I’d like to see their operation which he was ok with and will open it up to others .
Presentation was hard work given the subject matter reminded me of my mech eng suffering in lectures as I have somewhat limited attention span.
Looks great IP and with “he who cannot be named” as their biggest customer either Valdemort has launched a satellite programme or Elon Musk is buying .
FD was a bit young and has gone internally from FC to FD so steady pair of hands though don’t think he would be much use in a shot hit the fan situation which they look like is not on their radar .
Ref - cockney rebel
Really interesting and learned a lot. I’m not much one for Chartists but really liked his buying at the start of a bell curve strategy . think I’ll pay more attention to him
looked for Jonno but didn’t want to be the guy going round reading badges. Saw Paul but he was always surrounded so left him to his audience .
Quite interesting mix of people definitely not the usual Sheffiekd crowd I knock around with in the fat cat so somewhat out of my comfort zone but really enjoyable interesting trip .
please excuse all typos and spelling mistakes
Thanks planetx. Did Cockney Rebel say anything about Avon Protection (LON:AVON)?
Yes he did , didn’t register with me sorry but I know it was discussed but I wasn’t concentrating at that point
Interesting feedback, thank you.... wish I could have made the journey but just done a London trip and couldn't make it this time.
Enjoyed this, thanks.
Sanderson Design (LON:SDG)
planetx
I said the comments “royalty revenues are lumpy” has been made (on here) and asked whether she was confident the future royalty income was a rising tide set to increase long term and she very much thinks so.
Asked the FD about stock as it looks 3-5 million too high and he said it would be heading that direction .
Impressive, though accepting breakeven in production and profit on license I think is questionable and given their clear production advantages and ability no reason not to get the production to be making profit .
Cheers planetx - useful to here any updates as to how they think licencing will do. Somewhat annoying that they cant make money selling stuff - i know they need to get their stuff out there but i would like to think anyone going to the trouble of selling stuff at volumes they do would ensure they eek out some minimum margin. I wander how press ganged they were into being confident about future prospects though ref licencing particualrly if the other side of teh business makes no money - is any ceo ever going to stand there and say i think we have hit peak licencing and future deals may be harder to come by ? if they did would they still have a job? - hey ho as things stand its ticking over so i guess holders just neeed to have the faith (or not and sell)
Millaree
To be fair I don’t think they want it to be breakeven production .
Looks like they are really targeting the US market and the targeting of interior designers over there .
I’m more than happy to back her, she seems agile and even if it’s breakeven at the moment if she is good she won’t let it stay there .
The US is growing really well and they haven’t yet made a real push so I’m very much on the positive side .
As a side note I’ve held SDG for over 25 years and she is the one that gets it .
Licensing is big money when done correctjy . A friend of mine is representing the Conan Doyle estate and has taken it from a non cohesive family bunfight to a real cash cow and he is literally signing deals all over the world .
Thank you Planet X for your comments on Mello. Very helpful for one who couldn't be there.
Your pub looks good too.
I was there as well Planetx and agree with all of your comments except re Sanderson Design (LON:SDG) where i was quite underwhelmed. A quality company, quality product and a competent CEO but now I understand how their business is won in the USA, which is crucial to growth given the rest of their markets are very flat, I can't get excited about their immediate future growth prospects. Traction and penetration over there sounds a very slow process and it looks like it will be a while before we know if they have cracked it or not.
I have held off from buying until I see the directors put their hands in their pockets and buy some shares themselves, that will be my 'tell' that things are starting to garner pace.
Just my honest interpretation based on their presentation and chats with the CFO and CEO.
Burnt onions
I get your points but I’m taking the other view .
Your own words are a good pointer when compared to sone of the dross on AIM and terrible management
“A quality company, quality product and a competent CEO”
Not too many AIM companies can claim that also have a mountain of cash, great brands , and stock of 25 million .
I think it’s cheap .
Christopher mills big opening statement about how they judge a company was
“If I could buy and own the whole company “ is their starting point
Would I buy SDG , yes reckon so .
I can't disagree with you planetx and if i was a holder I would happily sit there, collect my dividends and bide my time, just didn't get enough of a 'buy it now signal before it runs away from you'. But i'm happy to be wrong and wish all holders the best of fortunes with SDG, I can't see it going south just not immediately north :)
Think we’re agreed, I would not rush in it’s going sideways for a while now , always spikes on a good RNS then drifts up and down depending on which way the wind blows x
I’m only buying the dips (last buy was 98p ) as it does gyrate quite a lot currently between 100-120p which is quite a big trading range
Personally think it will break into the 120-140 range soon then stay there for a period only breaking out of that if there is a bit of an AIM recovery in which case everything is up
Planet X thank you. As always your posts contain a lot of details and are invaluable Must have taken ages to type all that.
Lovely useful post.....thx
I thought I'd give a quick plug for Graham's YouTube channel; Graham Neary - Financial and Investment Commentary - YouTube
I always scan now to see if he covers a stock I own as the discussion is always educational and informative with extra comment above what appears here,