Small Cap Value Report (Fri 24 July 2020) - FCCN, RNO, CALL, BEG, CHRT, HOTC, WINE

Good morning, it's Paul here with Friday's SCVR.
Update at 13:07 - Today's report is now finished.
I nodded off after lunch yesterday, so there's still a section missing on Cohort (LON:CHRT) . I've been through all the accounts, and taken notes, just need to write them up. So I'll catch up with that later, and indicate here when it's done. Now done - it's in today's report below.
UK retail sales for June have come in reasonably robust in the circumstances, down -1.6% year-on-year (better than -6.4% forecast).
UK PMI survey data (confidence) have just come out, and look surprisingly strong. Composite PMI (flash, for July) is 57.1, versus 47.7 in June. That's very reassuring indeed. Similarly strong PMI data has also come out today in France & Germany. Therefore, it looks like economic recovery in the UK and Europe's biggest economies, is well underway. That gives me more confidence to sit tight on my long positions, and that the time for shorting may have now passed? Possibly? Nobody knows, because markets anticipate these things, and hence often do the opposite of what we might expect.
Face masks in shops, etc, become supposedly compulsory today, but police say it's unenforceable. I'm finding it bearable, wearing a light, cloth face covering, that's reasonably comfortable. So it's really not a big deal, and can only help (ie. it can't make things worse).
.
French Connection (LON:FCCN)
Share price: 11.5p (up over 100% today, at 13:09)
No. shares: 96.6m
Market cap: £11.1m
(I'm long)
The RNS is actually called "Trading Statement", but I've renamed it to be more accurate!
This is a bit of a game changer. I was worried that FCCN might run out of cash, and go bust. However, that risk has now disappeared for the next 2 years, because it announces today a new £15m working capital facility with Hilco (restructuring experts). FCCN says this is sufficient for its needs. Hopefully Hilco might give FCCN a push to do a pre-pack administration on the moribund stores portfolio? FCCN did not qualify for Govt financing schemes, but hints that it has deferred tax and other payments, which will need to be paid sooner or later.
Collection of wholesale receivables (a substantial part of the balance sheet) better than expected during the lockdown period - good news.
Own website sales up 24% over last 15 weeks - not great, it should be a lot more than that in my view.
Stores - initial sales since re-opening have been low, but good conversion of people in the shop into buyers.
Outlook - no guidance given.
My opinion - this is a huge sigh of relief, and we could see a bounce in the share price today. The risk of a 100% loss should have disappeared for 2 years now, giving the business time to continue the recovery that was underway prior to covid. Once those onerous leases are ditched, there should be a profitable wholesale & brand licensing business remaining. I've been saying this for years, because it's true - look at the divisional performance figures.
.
Renold (LON:RNO)
Share price: 10.6p (up 1% today at 13:12)
No. shares: 225.4m
Market cap: £23.9m
(I'm long)
Renold, a leading international supplier of industrial chains and related power transmission products, issues the following statement ahead of its Annual General Meeting to be held at 11:00am today. The statement provides an update on the Group's first quarter of the financial year ending 31 March 2021 ('the Quarter').
Q1 is April to June 2020, in other words.
Today's update is light on detail!
Group performance during the first Quarter has remained in line with the Company's Results Statement issued for the year ended 31 March 2020. Renold has been profitable and cash generative in each month of the first Quarter of the new financial year.
Whilst Group order intake has reflected the challenging market conditions, gradual improvements have been seen since April 2020.
It is still too early to give specific guidance for the year ahead.
However, with the strategic actions and cost saving measures taken to date, the Board is confident that the Company can manage through the current period of disruption. Renold is well positioned to benefit as markets stabilise and demand recovers.
.
My opinion - there's not enough information in this update for me to go any further with this.
What it seems to be saying, is that things are bad, but not disastrous. If it can get through the crisis without having to raise fresh equity (which was suggested could be achievable, in its last update), then there could be nice upside here on a recovery. That's why I took a small long position in it after the last update. I'll neither buy more, nor sell, on today's news.
.
Cloudcall (LON:CALL)
(I'm long)
The recording of the investor presentation earlier this week is now live - here is the link.
It's a stock we've followed here for years, always seemingly on the cusp of good things. So I can understand that many investors are sceptical. But it does sound as if the company is on the right track now.
.
Begbies Traynor (LON:BEG)
Thank to Edward John Canham and others, for flagging up this interesting, regular quarterly report - useful background reading for investors, although it rarely contains any surprises.
Obviously financial distress for companies is up again. Here's an interesting point I hadn't considered before;
The rise could have been much higher, were it not for reduced court activity due to the coronavirus pandemic which has substantially reduced the number of CCJs and winding up petitions being taken against indebted companies.
CCJs lodged are down 40%, and winding up petitions are down 73%. That backlog is likely to unwind at some point.
This sounds ominous;
... it is likely that the true impact of the coronavirus pandemic will only become apparent during the third and fourth quarters of 2020 as government support initiatives are unwound and courts fully reopen so that enforcement action can be taken.
There must be lots of bad debts building up, particularly with smaller businesses in sectors such as retail, hospitality, travel, etc. Who takes the hit, and will bad debts pull larger companies down as well, maybe?
The effervescent Julie Palmer of Begbies concludes cheerfully;
"The latest figures from our Red Flag Alert research show that there is a dam of company financial distress waiting to break upon the UK economy. Despite more than 30,000 businesses having fallen into distress since the start of the year, the real level of corporate underperformance is being concealed by inaction on distressed businesses in the courts.
More sector detail is given.
Here's an additional point from me;
Credit insurance - many companies insure themselves against bad debts by using insurers like Euler Trade Indemnity. I remember dealing with them years ago, when I realised they were actually more important than out bank, as they insured a lot of our supplier base. So I used to go to their offices and give them a presentation on our annual results. They were a bit of a nightmare, since they switched cover on and off, on a whim, causing a lot of disquiet amongst our suppliers, and hassle for me to get cover reinstated repeatedly.
Anyway, trade credit insurers must be pulling cover left, right, and centre, at the moment. That can often tip companies into insolvency, because suppliers may refuse to deliver goods, if they can't insure the invoice. Or demand cash up-front, if there's no insurance.
These issues must be hurting a lot of companies. At least listed companies have better access to funding, so may not be so badly affected.
We need to keep this issue at the forefront of our minds. How solid are receivables, within current assets? What level of provision might be needed for bad debts? Is there concentration risk from big customer(s) that could go bust, within receivables. There's often something buried in annual reports about this kind of risk, so it's worth checking.
.
Cohort (LON:CHRT)
Share price: 591p (up 4% yesterday)
No. shares: 40.96m
Market cap: £242.1m
This is a group of 5 companies, mainly focused on the defence sector, with the MoD being a big customer. It has diversified into other areas too.
The main share price rise happened from 2010-2015. Then it traded sideways for several years, and has had a more recent spurt upwards;
.

.
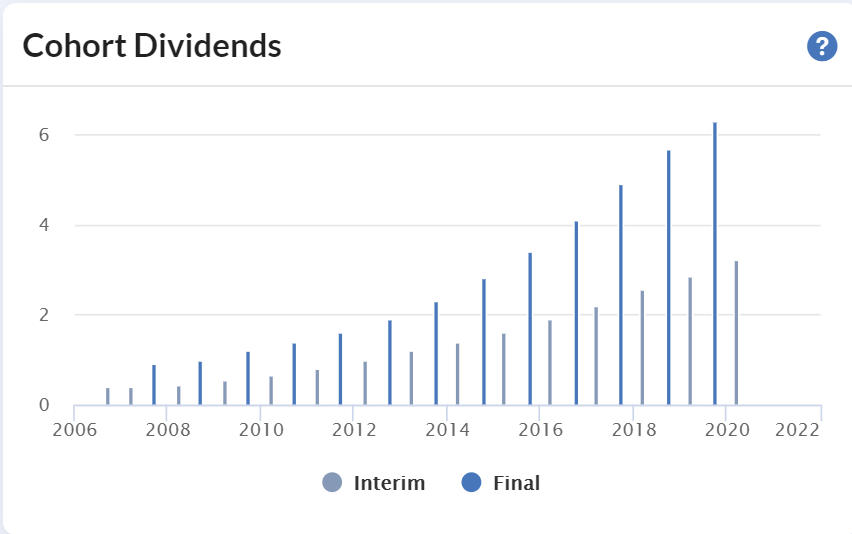
There's been a steady stream of growing divis too, although the rise in share price has kept the yield quite low;
.
Note that the final divi stream is continuing, despite covid, with a final divi declared of 6.9p (up 10%), giving a total of 10.1p - a yield of about 1.7% - worth having, but not madly exciting. It sends a strong message of confidence in the business, by continuing with increasing divis.
Results for FY 04/2020
EPS 37.1p (up 10% on LY) - looks a beat against consensus by TR data of 34.9p, but the company says results in line with its RNS of 21 May 2020.
Net debt £4.7m, down 27%. Note that this masks £25.2m of long term bank debt, offset largely by a £20.6m cash pile. This suggests to me the year end cash balance is probably at a seasonal, or window-dressed high. Hence underlying debt is higher than it might at first appear. Not a problem, I'm just pointing it out so you're aware.
Order intake down 34%. Looks nasty, but company says this is as expected, due to a large multi-year contract win last year. Order book covers 75% of forecast revenue for the current year, FY 04/2021 - that looks solid.
Covid - estimated to have hit profit by c.£1m
Profit growth has all come from the Chess acquisition - so some question mark over growth from other businesses.
Guidance - company says FY 04/2021 expected to be in line with FY 04/2020. Great to have some proper guidance, and demonstrates that company has decent visibility on earnings.
Balance sheet - looks OK to me. NAV: £81.8m , less intangibles of £55.3m, gives NTAV of £26.5m - adequate.
Cashflow statement - only unusual items are £3.7m purchase of own shares, and £1.5m sale of own shares. Everything else looks as I expected.
My opinion - this looks a decent collection of 5 quite high margin, niche businesses. I like it.
PER of 15.9 is probably about right.
I wouldn't know how to assess the group's future prospects, so overall I'm neutral on this one.
.
Hotel Chocolat (LON:HOTC)
Share price: 304p (up 9% today, at 12:08)
No. shares: 125.5m
Market cap: £381.5m
Hotel Chocolat Group plc, a premium British chocolatier and omni-channel retailer, today announces a post-close trading update for the 52 weeks ended 28 June 2020 ("FY20"), and an update on recent trading, the Group's financial position and outlook.
Obviously the physical stores were closed during lockdown. What interests me most at the moment, is how adaptable companies are, in moving sales online. There looks to be a big tick in this box for HOTC;
In total, digital sales accelerated to over 200% year-on year in the fourth quarter. In addition to increased gifting sales, digital sales growth throughout the period was supported by a 47% year-on year increase in the sales of subscriptions and recurring purchases, including Hot Chocolat refills for the Velvetiser in-home system.
That's impressive.
The revenue shock in H2 from closing the stores (and temporary closure of its factory) is much lower than I would have expected, due to successfully moving sales online;

That's astonishingly good actually, considering that all the shops were closed 12 weeks from 22 March to 15 June.
Underlying profitability -
The Group anticipates underlying pre-tax profit to be in line with expectations. In the light of current and anticipated trading performance the carrying value of existing fixed assets is being reviewed. This review may give rise to a higher than historic impairment charge, but any such adjustment will be a non-cash charge and will be confirmed at the release of preliminary results, scheduled for 29 September 2020.
I'm not bothered about fixed assets being written down, that doesn't matter. I'd be more worried about what the leasehold liabilities are for any loss-making shops. That could be a cash drain for years to come, if town centres don't recover enough to make them viable.
Store re-openings - no figures provided unfortunately;
119 of 125 UK locations are currently open for business. Sales in "High Street" locations are performing more strongly than in city-centre "commuter" locations. Whilst total sales from physical locations are lower year-on-year, digital growth remains very strong and Group-wide sales since the end of the period remain in line with management expectations. A similar pattern has been seen in both the USA, and in Japan, which is operated by a joint-venture partner.
.
Forecasts - only 1.2p for FY 06/2020, and 2.2p for FY 04/2021. Hence the share price of 302p looks insanely high on a conventional PER multiple valuation basis. However, I think that is missing the point. What this share really is all about, is the potential to roll out the Hotel Chocolat brand internationally. Not just stores, but also online. It's the strong growth & resilience of its internet offering over the covid crisis that really makes me sit up & take notice.
My previous scepticism may have been misplaced. I don't think I can bring myself to pay up such a high valuation for a business that's likely to be trading little above breakeven for a while, and may have years' worth of problem sites to wriggle out of, possibly? But the brand clearly has strong appeal, otherwise online sales wouldn't have rocketed during lockdown.
Overall then, my conclusion is: very expensive, but could be exciting long-term, maybe.
.
Naked Wines (LON:WINE)
Share price: 392p (down 3%, at 12:56)
No. shares: 72.88m
Market cap: £285.7m
Trading Update & Director Changes
Sales up 67% in June vs LY, Q1 sales up 77%. Benefit from covid, as wine sales moved online.
So why is the share price down today? Looking back, the last update said that sales in April & May were up 81%, so a bit of a deceleration in June, albeit still superb revenue growth.
Online businesses can dial up the marketing spend and generate accelerated growth.
I covered the recent results statement here, hopefully capturing the positives, negatives, and unknowns.
Overall, I remain neutral, but a bit sceptical. Who cares what I think, the share price has doubled this year, so well done to holders!
.
That's it for today, and the week. Enjoy the weekend!
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

91 comments
Oh dear.
At this rate the Stockopedia discussion board is going to become a shadow of it’s former self.
I agree. This site is a great venue for high quality ideas, high quality commentary and great feedback on stocks, shares and markets. It is a shame it is competing with discussions, albeit very important and interesting but not directly linked to financial markets.
I have been patiently been waiting to add to holdings in Easyjet and Dart and wonder whether next week may be an opportunity. I understand they are both still well capitalised and therefore able to withstand some more short term pressure. Still short John Menzies.
Here’s how, all mask discussions into the Lockdown thread, i had many a damn good rant in there about that and still could about all the incompetence of the state, this week masks, then gloves, and something else next week for sure, it is inevitable that more madness will follow, but it should live elsewhere. Muzzle thyself mask commentators
https://www.stockopedia.com/content/lock-down-586923/
Gloves!
Don't give them ideas. After that, it will be personalised bog seat covers.
Paul, thanks for a brilliant week's worth or reports. Are we overdue the next episode of the 'Bournemouth Chronicles' ? Have a relaxing week-end.
Dennis.
Hotel Chocolat (LON:HOTC) I'm sceptical on their store prospects. Many are in high footfall areas or shopping malls. For either impulse buys, business gifts, or personal gifts (birthdays, housewarming, anniversaries, valentines). No surprise online sales went up 200% but that was from a small base. Their store portfolio is mainly city centres and transit hubs.
Impulse buys: depressed as white collar middle class (target audience) largely working from home.
Business gifts: looks difficult given all companies are probably scrutinising unnecessary costs at the moment.
Personal gifts: maybe holds up well, but online, customers have a huge range of choice as opposed to a few shops on their commutes home.
Paul, my extremely, experienced and senior nurse wife would say that wearing masks for longer periods (ie not the 20 minutes at a time that clinicians usually do) and without changing them each time, etc, etc, does actually hold a number of health risks to the user. As so often in life, there is little that is truly risk free.
https://www.meehanmd.com/blog/2020-06-12-healthy-people-should-not-wear-face-masks/
Nice, Marigold.
I think face masks are a theatrical prop rolled out now the outbreak (small compared to the cost of smoking, diesel, obesity, etc) is contained.
Oh Thank Goodness all those politicians spared us from a winter flu and gave some of us our money back. We best do what they say or else we might end up on a ventilator. Rishi will cover the bills.
Thanks Paul, Could you do a report for Begbies itself?
Hi George
If you look up Begbies Traynor (LON:BEG) and then go into the discussion tab you will see the report when they issued their finals, today was just a report they issue quarterly on the state of the market not a report on them.
Or click on Discuss on the left and then search for Begbies Traynor (LON:BEG) lots of stuff there.
Thanks
Tommy
Meanwhile, back in the markets, a pretty profound announcement this afternoon from Indivior (LON:INDV)
Agreement with US Department of Justice
In short Indivior had a court case hanging over them about the opiod crisis and potential "mis-marketing" , the scale of which could have bust the company.
Up until now, they had professed their innocence, but they have essentially plea bargained to settle for $600m payable over 7 years.
The share price is up of 50% this afternoon, but still substantially down on where it was in 2018 before this all kicked.
I have not go an up to date view on valuation as there was a secondary issue for them in that they had effectively lost their monopoly on their main product to generics.
Has anyone been keeping tabs on this?
EDIT : Now dropped back a little to be "only" 40% up on the day, so I've taken a small speculative position and will have a proper catch-up over the weekend.
In the interests of full disclosure (not that I imagine my views have any influence on the market) I should just add that I did have another look at Indivior (LON:INDV) over the weekend and concluded that it is too complicated for me to want to take further at this time.
So I sold out this morning for £1.50. (Missed the top) Nice to have made a months income over the course of the weekend, but I am kicking myself for not being braver, it was obvious that this was good news that had not been fully reacted on giving the timing.
Not taking undue risks is all well and good, but when you KNOW you are right,sometimes youjust have to back yourself.
It is not the first time that I have underinvested in an extremely high probability scenario - I need to give this some more thought I think.
Had a look at Naked Wines (LON:WINE) but the share based payments look excessive to me. If they get gain a foothold in the US market then they could do well but how long will this situation last, looks like growth is slowing down already.
Now ken - you know we can't talk about Centrica (LON:CNA) on here as it's a £2.741 billion company and so doesn't qualify ;)
Up to Paul, of course, to say if he gets upset by chat about covid and "guide" us to avoid the subject.
I do think it's pretty central to the investment debate though and have absolutely no doubt that mandated wearing of face masks is going to have absolutely no impact on the "second wave" or "spike" that we will have to endure.
I think with the Centrica (LON:CNA) there is a whole range of debates which are relevant to here as there are numerous Macro things within there including wholesale fuel prices, customers paying their bills, is this winter going to be warm or cold, and whether historical debt fueled expansion into North America is the right thing to do which reads across to shares such as National Grid (LON:NG.) and Tesco (LON:TSCO) not to mention £WINE...
Hi Paul,
Great to read your report and thoughtful insight everyday. 1st post below hopefully well received by all.
With regard to Euler Hermes, my company is a client of theirs and as such, I can confirm that they indeed have been pulling credit limits, left right and centre. Of course, they are very risk averse to certain sectors (hospitality, retail, etc) and other factors including COVID impact on their appetite to maintain limits.
We are in neither of these sectors (more akin to your old stomping ground) but have suffered from underwriters removing limits due to financial information being too old (NOT filed late) and no-one wanting a company failure logged against their underwriting card.
However, as I said to my senior contact there only last week; there has to be some value in the policy. If they only give cover on the 'solid gold' clients, we may as well self-insure and save the premium. I quipped that it isn't as though I am currently getting good value from the sports hospitality that they usually treat me too!
In fairness, they understood my point and our ongoing review of removed or reduced limits is broadly seeing a positive reception and some being reinstated.
On a positive note, from our SME, serving multiple sectors; retail (real and virtual) industrial, automotive and more:
Our business continues to recover across all sectors, sales in Q2 were down around 35% although still profitable and down less in July, debtors are broadly paying in time with no strong concerns, cash flow is very positive as the reduction in sales wound down the debtor book. Demand is (IMO) good (reducing stocks) for the moment but who knows in the longer term. Much better than I forecast or planned for... but perhaps that is the secret.
Having done the sales pitch, regrettably for readers, we are not quoted nor looking for investors nor (if you are a banker) borrowing currently.
KR as always.
£SUK2 +2.4% on the day.
FTSE100 -1.5% so far.
IG Group (LON:IGG) Big drop of around 10% yesterday, hovering around its a day low of 737p, barely changed, Plus500 (LON:PLUS) dragged lower in sympathy.
International Personal Finance (LON:IPF) breaking below its support level of 60p
Is that more to your taste, Mr Mitchell?
Does anyone know if Paul did his response to the OptiBiotix Health (LON:OPTI) email he had this week?
No, I've not had time (nor particularly the inclination to waste time on OPTI), but I'll look at it at some point, maybe over the weekend or next week.
Hotel Chocolat (LON:HOTC) I don't understand the forecast EPS. Given they made 9.6p last year and revenues are up, this drop in the forecast is presumably due to the asset writedowns? Why would that also be an issue next year? I'm obviously missing something here.
Hi Paul, what's your latest thoughts on RBG
Ref pubs
I had my first venture back into my local whetherspoons yesterday and the covid stuff really was minimalistic - it looked like the same amount of tables (probably less though) and deffo still the same amount of tills - simply with the addition of a line like a shop and a tiny perspex shield that would be lucky to catch owt (if anyone sneezed) if the server is anything taller than 4 foot tall and fatter than a rake. Based on this my imrpession is that whetherspoons should have the potential for minimalistic lost revenue (caveat ref closing times later) if the punters are still turning up - obviously that minimalistic lost revenue may still unduly affect the bottom line - especially if all the customers are sticking to the ruddles and 1.29 a pint. They did chuck me out at 11.30 though so at present there will be a material loss of late night revenue - i suspect that closing time won't last for long. Social distancing in general was pretty much non existent. Note like my local military precision local where i queued at the door - was marched to table well spaced out brought drinks and then told i had to drink up and leave pronto as i turned up at at 9.25 not realing they shut at 9.30 - i should have seen the clue when i noticed a friend leaving by the back alley - couldnt understand why they would be going home at 9.30. I have now defaulted to going to my local posh champage bar first and sampling the 2 cocktails for a tenner - Mojito has some competition when the good staff member allows the Limoncello Spritzer on that deal - quite a nice drink.
I think i finally may have found an upside to covid - replacing the trauma of getting served at whetherspoons when there was ten shouting to be served at once with a nice orderley queue where we all get served in order. My not so tall friend will probably be the happiest he has been since they removed the toilet helpers from all the local bars when i tell him he will get served when it is his turn.
I will never forget the time he nearly peeded his pants waiting for the toilet attendant to take his break - only for the toilet attendant to rush back from the far side of the pub to help him when he did think the coast was clear.
I notice on twitter they are opening an ever increasing number of bars. They say successfully but I presume that means with social distancing rather than financially.
They are doing brunches now so clearly tackling the 11am-11pm market. Interestingly on a call I attended with management they said that 80% of their revenue came before 11pm so the missing nightclub scene isn't disastrous in itself. They are aiming to optimise food and spread custom out through the day so I think that will be the key to how successful investors see the reopening.
I was away this weekend. Booked 3 gastro type pubs (midlands and yorkshire regions) for food and drinks. All pretty seamless. other than some sanitiser and a one way system all fine. plenty of people there. I spoke to the owner of one pub and he said on some days they are back to 80% of pre covid revenue. On quiet days its 50%. Found that interesting.
My local in London looks pretty busy as well. Not at pre covid levels certainly but plenty of people inside and out. I'm increasingly optimistic that Revolution Bars (LON:RBG) will make it through the other side.
Heel struggle to fill his predecessor's boots
Must admit that I hate wearing a mask, and hate being forced to wear one, and henceforth will only visit shops when it is completely unavoidable.
On top of that, the huge downside is that many people wearing masks seem to think that 2m (or even 1m in many cases) socially distancing does not apply to them. So for a highly questionable small benefit of masks we lose one of the most important public health measures of the whole pandemic.
No surprise that in countries like the USA, where everybody is apparently wearing masks, Covid-19 is running amok.Also think its incredibly unhelpful for politicians to so obviously flout social distancing. Note to idiots:
In the meantime, Norway looks at the evidence and states they are totally pointless.
Total nonsense about the USA. They test the most people and have around 4 million confirmed cases so far of which nearly 1.5m have made a full recovery and 150k deaths. Out of 300m plus people. It’s the MSM trying to make trouble for Trump.
"Total nonsense about the USA. They test the most people"
This site may help. You can sort the tests/1m of population column to see where the USA comes.
https://www.worldometers.info/...
Totally agree. People with masks think they dont have to distance. There is no scientific proof that masks do anything with regard to viruses. In fact they are harmful as your body does not get enough oxygen and you keep rebreathing the same air.
12.07 and only 25 comments - what can we do to spur interest? Oh, I know:
Just been to local high street - bizarre to see shoppers all wearing masks but no shop assistants doing the same.
And Sainsbury's, Asda and Co-Op today saying they won't enforce wearing by shoppers. Not to mention that no-one seems to know exactly what the "rule" is if you go into a cafe and buy a sandwich or coffee to take away.
Its no muzzle, balaclava, or multiple choice of disabilities for me.
I don't see how society and the economy can function when we pander to unnecessary fear of a dubious hidden enemy.
Dubious ? The evidence seems pretty clear to me
Not as far as I can see.
The total UK or Worldwide deaths from Covid-19 is a residual fraction of annual mortality and the global population.
The figures have also been discredited and weaponised politically by everyone with a cause and agenda.
Nothing convinces me that we should have sabotaged everything over this.
Turning to the masks issue: What specification? What test regime? Who pays? Who provides? Who disposes of?
Why am I exempt for having Asthma and several other disabilities, and why is it acceptable for diesel vehicles, known to kill more people than COVID-19, to be ubiquitous?
We need to end these games and get the economy back to full speed.
countless discarded masks now littering the streets... Don't envy those who have to pick up and disposes of them. Personally, I don't wish to wear them but will out of politeness although much easier to avoid the transaction in the first place and keep my money in my pocket.
Please leave the wingnut conspiracy theories on Facebook where they belong.
Partly because this newsletter does not include resource / gold stocks or bio stocks (this has been fully explained before of course). But with gold about to break $1900 I guess many of us are buying gold and resource stocks at this time!
Gold just crashed through 1900...high of 1904.60. Difficult to ignore. Now for $2000. That is going to be a huge target.
"Please mine more nickel"...Tesla's Musk urged this week.
The lack of comments today could be because the Companies updating don’t appeal. But it’s a shame for Paul when posters revert to their strong opinions on covid and face masks (and not Investment/market effects of covid) as both have been argued to death, and nothing posted here will change anything. More worrying investment wise could well be the growing spat with China.
Today is a bit of a dull day for trading updates and results, so maybe lack of comment on the Companies Paul has updated on is because few hold or are looking to.
One interesting result not so far mentioned is from Centrica. Some good news at last which puts Centrica in a much healthier position and share is up today. Have no idea yet whether Centrica is now a classic recovery share as except for the update today I haven’t followed events, but share price is well up so has Centrica turned the corner at last?
Never likely to own Centrica again.
Telecom Plus (LON:TEP) is my only energy company. SR of 93 and doing well.
Ken
I think the issue of face masks, as initially raise today by Paul, is extremely important to investors because they will affect people's behaviour and the impact on businesses and infection rates is currently very unclear.
Some people will feel safer from today and will venture out to shops more than was the case. Other people will be annoyed about masks and may do less shopping. Who knows what the balance will be.
What is very unclear is what masks will do to infection rates. My personal concern, and I am very cautious, is that there is already less and less conformance with 2m or even 1m social distancing in supermarkets (the busiest shops I visit), not helped by the disappointing and highly irresponsible examples set by politicians elbow bumping or obviously being in very close proximity to others.
We know that hand washing and social distancing, and probably the warmer weather, are the reasons why UK infection rates have reduced so greatly. In comparison to these, the masks most people are wearing perhaps have a very minor practical benefit... ...provided social distancing and hand washing is maintained.
But my impression is that social distancing guidance is being followed less and less and I suspect masks will make this worse. We really don't want to go back to a more general lockdown.
Early on it did seem to be clear that those wearing masks, considered themselves to have gained immunity and therefore were not exercising social distancing.
Whilst I agree there appears to be little conclusive evidence that masks reduce transmission for this virus, I do think there may be a benefit.
I agree that compliance with social distancing has been waning, in this regard though, i think the fact that "everybody" has to now where them in shops may have some benefit. It will be a clear visual reminder that this is not over, so could act to reinforce the broader message to "stay alert".
(I never liked that message much anyway - I had me constantly wonder what those that were dozy gits to start with were supposed to do.)
On the other hand whilst there are some people indicating very vocally that they will never set foot in a shop again whilst masks are mandated - I think they will prove to be a tiny minority. Probably offset by people who feel more confident with everyone else masked.
So personally I don't expect the economy to collapse in a bout of mask-phobia.
"On the other hand whilst there are some people indicating very vocally that they will never set foot in a shop again whilst masks are mandated - I think they will prove to be a tiny minority. Probably offset by people who feel more confident with everyone else masked.
So personally I don't expect the economy to collapse in a bout of mask-phobia."
The economy has already collapsed and the masks were little to do with it.
The masks instil fear whether it is fear of the imagined disease or fear of the security fuhrers telling people what to do.
Whilst we have the situation that some members of the community need to cower away from their fellow human beings, we won't have a working economy at full speed.
We need to be showing everyone that they are safe and that fear of this media concocted doomsday disease is completely out of proportion to substantially more important manageable threats and diseases.
Reminder: We are back to 1961 levels of Government debt, economic productivity has collapsed, the tax take slumped, at the same time as the largest splurge of The Public's cash in history. My home town, an airport town, is in major recession with considerable economic hardship, job losses and destruction - all unnecessary.
UK_Investor_8888
There are 45,000+ people in the UK who could vouch for the fact that it is not a media concocted doomsday disease - if only they could still speak.
Bonitabeach
Of course this is horrible, Bonitabeach. We all know someone who has died of some cause sometime somewhere.
Google ONS says:-
"There were 616,014 deaths registered in the UK in 2018, an increase of 1.5% from 607,172 in 2017. There were 3,248 deaths registered to children aged under five years in the UK in 2018; the corresponding mortality rate was 4.4 deaths per 1,000 live births, which is the lowest rate on record."
45K / 616K isn't that concerning to me: Its disease. Disease kills people. The other 571K also matter. We seem to lose perspective.
There are reports and commentaries stating that current excess mortality is below average... meaning we may have sadly and tragically ended people merely a few months earlier anyway.
I was talking to an 80 year old local recently: deaf because his ears are blocked, can't see the GP because they won't treat non emergency cases. WTF. Proportionality.
The masks instil fear whether it is fear of the imagined disease or fear of the security fuhrers telling people what to do.
This is nonsense. I, and all those I know, are far more likely to go into shops if I can be sure others will be wearing them. They reduce fear, not increase it.
There is ample evidence that masks reduce transmission of the water droplets that contain most virus from infected people to others, and that they also provide some benefit in the other direction, though less. If we are going to bring this epidemic under control, and keep excess deaths under 50% of expected deaths, as was achieved in March and April by the lockdown, and let some form of economic normality return then simple measures like masks and social distancing are essential. And require very little of those asked to follow them. The alternatives are to let it rip, as some in govt apparently did early on, and see vastly higher death rates, or maintain lockdown, or cycles of severe lockdown, which are not only much harder for all of us who have to live with that, and will cause far more damage to the economy.
I find it impossible to understand the position of those who object to such a simple step, which while it clearly won't stop all infection, can play an essential part controlling spread and allowing people to begin to lead normal lives, and for economic recovery. And to reduce the likelihood of a far worse outbreak over next winter.
I find it impossible to understand the position of those who object to such a simple step, which while it clearly won't stop all infection, can play an essential part controlling spread and allowing people to begin to lead normal lives, and for economic recovery. And to reduce the likelihood of a far worse outbreak over next winter.
Agreed. Although, to be honest, I find it even more impossible to understand people ranting about this on Stockopedia. Are they confusing Paul Scott with Dominic Cummings? Do they think it will make a difference?
In any case, surely they should be out on the High Street defiantly breathing on everyone, ripping masks off old peoples' faces and heroically shopping to save the economy, rather than sitting in darkened rooms tapping out evidence free conspiracy theories?
Of course, perhaps they're so busy being angry about things they haven't noticed that UK retail has already recovered to where it was before lockdown ...
... right, off to the gym.
timarr
"Of course, perhaps they're so busy being angry about things they haven't noticed that UK retail has already recovered to where it was before lockdown ..."
Has it? If so, I'm amazed. Assuming that you're discounting online sales.
Time will tell I guess. Personally, I'm expecting retailers (excluding online) to start complaining before too long that footfall and sales are still, or more, depressed despite mandated face masks and the government to then guide that as things are now much better then masks in shops now recommended but no longer necessary to be mandated.
Off to the gym? Luckily, no masks needed there.
Hopefully the above not misunderstood as a "rant".
Has it? If so, I'm amazed. Assuming that you're discounting online sales.
If I’d meant that I’d have said that. Retail spending up 10% YoY in June, online spending up 48%. It would be very optimistic to expect that to reverse significantly by merely freeing people from the tyranny of light cloth face coverings. The economy is recovering nicely so far, it’s just doing it in a different way.
Most of the posts about masks here aren't investment related at all. The "investment" case is simply loose cover for people to express their strongly held but largely unevidenced beliefs. A true discussion would go look for some actual data rather than simply expressing opinions. For instance, this from Goldman Sachs on the potential economic impact of a face-mask mandate in the US:
https://www.goldmansachs.com/i...
These calculations imply that a face mask mandate could potentially substitute for lockdowns that would otherwise subtract nearly 5% from GDP.
The gym is fine without masks because people in at risk groups won’t go there, they don’t have to. The same isn’t true for retail generally which lots of old and vulnerable people have to use as they don’t have alternatives. Putting up with the minor inconvenience of a mask in order to reduce their risk even a tiny bit is a small act of kindness that costs the wearer almost nothing.
timarr
Lip reading
Facial expression
Smiling / teeth expression
Clarity of voice
For those of us who are hard of hearing, softly spoken, autistic, asbergers, and with anxiety issues, there is a significant cost to face masks. This has never been done in The UK before.
Don't assume that whilst its not a problem for some, it isn't a problem for others.
There are numerous Disabilities Acts setting in law the principle that we must not discriminate against members of our society.
For those of us who are hard of hearing, softly spoken, autistic, asbergers, and with anxiety issues, there is a significant cost to face masks. This has never been done in The UK before.
What's that got to do with investing?
timarr
Because, Timarr, there are millions of consumers (market participants) in this country/economy severely effected.
And if the death/autistic/mute/disabled can't participate in the economy as before everybodies shares don't perform as well.
You make less money.
You lose the benefit of some of their contribution to the economy and their tax contribution.
What about the cost of not wearing face masks if infection spreads more rapidly or widely as a result? That could result in another lock down, causing the economy to crash even further and many share prices to plummet.
Other countries seem to be able to manage this (i.e. mask wearing). If Spain, Italy, France and Germany can do it why can't we?
https://www.statista.com/statistics/1114375/wearing-a-face-mask-outside-in-european-countries/
Previously fascist/axis countries with a tendency towards left-leaning authoritarian government: note the extremism of the French and Spanish authorities' lockdowns.
That other european countries did it, does not necessarily mean or prove that the masks did or did not have an effect.
The second (subsequent) waves may or may not happen irrespective of the masks.
For example, if COVID-19 got into a water supply, food, clothing, gym, care home, transport system, etc.
As a free-marketeer minimal-government-ist, I would rather The Government policy be that the show must go on despite a minor surgence of one minor disease when all other disease is ignored.
Why is HM Gov allowing all these "variances" to the mask policy, for example for the shop workers, sandwich providers, pubs, gyms, etc?
They don't know what they are doing: Boris's Government flip-flops and deviates due to media pressure, not logic.
It does not have to follow that a rise in R or cases needs a full lockdown. More granular localised lockdowns, on a case by case basis, would be less economically destructive.
How many cases were there in darkest Eaat Anglia or the periphery of Cornwall?
Still nothing to do with investing. Can't you take this off to a political website rather than cluttering up the posts here?
timarr
Show us how, Timarr.
Show us how, Timarr
Write to your MP. Set up a petition and get a debate in Parliament. Strip naked, paint yourself red, white and blue and chain yourself to the gates of Downing Street.
Because if you feel this strongly about you should do something affirmative rather than just posting about it on an obscure investment website.
timarr
Already way ahead of the curve:- Some of us are trying to get the economy back to normal.
Timarr
Professor Jonathan Van Tan himself, the most eminent expert in Respiratory Diesease in the UK, back in March/April did not think then that there was evidence that Public wearing of masks was a significant tool.
There is IMHO evidence that for 99.9% of people COVID-19 is not a life threatening disease.
The perceived threat is therefore over exaggerated, the masks largely theatrical props for The Public where at any one time 99% of people we encounter do not have a transmittable form of the disease.
Personally, I'm staying away from the emporiums as much as a I can to have the easiest life.
I had to visit Evans Cycles this morning (to get a race wheel trued): Evans Cycles are very busy. Couldn't do me so a one man band bike mechanic did it on the spot and he's working 7 days a week at full capacity.
Clearly the bike and e-bike industry are having a good pandemic.
I await hard sales data with baited breath on retail.
My only retail stock is Scs (LON:SCS) . Paul's comments on the lack of a positive trading update and the recent significant pull back in builders £TW Persimmon (LON:PSN) for example, shows we've still got big problems.
Good luck!
Hi Paul, everyone,
A friend recently sent me a new crowd funding investment opportunity with the company Moneybox - https://www.moneyboxapp.com/cr...
Usually I pass on these but I've heard a lot of good things about their product and it's got my attention. The product makes investing easy and to me feels similar to the likes of Monzo.
It would be interesting to hear if anyone has any particular thoughts about the opportunity!
Cheers :)
Hi Kieran
With regards to crowdfunding in general, I have been following this blog at http://www.ecf.buzz/blog
It's really allowed me to open my eyes to what has happened to the many crowdfunded companies. Whilst the blog is biased negatively, it awakened me to the reality that with crowdfunded companies:
- accounts are unaudited
- salaries of founding members are up to their discretion
- there is a general lack of information to undertake sufficient due diligence.
Good luck with the due diligence!
Evening Maxistaxis,
Thanks for the link and definitely good points! Maybe the opportunity isn't so enticing after all :). I'll need to do much more investigation but there are quite a few negative points.
Appreciate the info and have a great weekend.
Cheers,
Can i just say re French Connection (LON:FCCN), thank god!!!!!!
French Connection (LON:FCCN)
I don't think God had anything to do with this finance arrangement; Beelzebub more likely.
Hilco Capital Ltd is not a charity and will ensure all those who are desperate enough to enter within its orbit will pay dearly for the ineptitude that has placed them there.
Bonitabeach
No position.
The point on trade credit insurance is an excellent one and is something everyone should be watchful for as trade credit being pulled can lead to shares being wiped out. Take Scs (LON:SCS) as an example. In the last crisis, their equity value was wiped out when trade credit was pulled and they were swooped up by private equity for almost nothing. Since relisting a few years back they now hold significant amounts of net cash in case that situation arises again and they need to pay suppliers upfront (in last crisis they were meaningfully indebted and so had no flexibility to be able to do so). Nonetheless, even though they are now sitting on a lot of cash, in their last interim results (March) they flagged an ‘Emphasis of Matter’ note stating that their going concern status could be at risk in a bad COVID situation. So, even companies that optically look good from a balance sheet perspective (as Scs (LON:SCS) does now) can still be wiped out if trade credit is pulled (as was no doubt included in their stress scenario test which led to the ‘Emphasis of Matter’ requiring disclosure). Companies that rely on trade credit and already have meaningful net debt are the ones to really avoid in times like this.
We have one of those RNSs today that brings some small joy: Mr Peter Foot has appropriately returned to the role of Finance Director of Shoe Zone . Hopefully a safe pair of hands :)https://www.stockopedia.com/share-prices/shoe-zone-LON:SHOE/news/shoe-zone-plc-board-appointment-urn:newsml:reuters.com:20200724:nRSX9388Ta
Ah you beat me to it! I was going to make a similar quip about Mr Foot having a sector-specific surname, giving him an unfair advantage!
But I expect he'll have to toe the line....
Otherwise, he gets the boot?
I’m sure he showed the other candidates a clean pair of heels ...
Wasn't he the sole candidate?
He's on his uppers now!
Instep with the best!
Always helps to get a foot in the door!
Is the company listed on the footsie?
Previously he was a sole trader.
I'm sure we're all pleased that the Shoe is now on the other Foot
Very good guys you make me smile
Ceres Power Holdings (LON:CWR), (I have held in past) guessing you saw last week IP group sold another big chunk of stock...
Just a reminder to join piworld's webinar today 24th July, 1pm for: An Hour with Mark Slater, Chairman & CIO at Slater Investments. Mark will discuss current markets, how he's handled the CV19 turbulence, and much more. Plus the opportunity to ask your question. Register here.
If you missed it, here's last week's (very popular!) piworld webinar: An Hour with Andy Brough, Head of the UK & European Small & Mid Cap team at Schroders.
Other company results webinars forthcoming on piworld:
Ig Design (LON:IGR) FY20 results webinar Friday 31st July, 12.30. Paul Fineman, CEO and Giles Willets, CFO will present FY20 results followed by Q&A. Register here.
Imimobile (LON:IMO) FY20 results webinar, Wednesday 5th August, 10.30am. Jay Patel, CEO & Mike Jefferies, CFO will present the FY20 results, followed by a Q&A. Register here.
We look forward to seeing you!
Thoroughly recommend the Andy Brough webinar.
Begbies Traynor (LON:BEG)
Issued its quarterly "Red Flag" update today. Pretty grim but worth a read. Makes the point that a lot of firms surviving on government support at the moment are only delaying the inevitable.
Phil
Naked Wines (LON:WINE) dipped my toe in on this one. Very strong looking chart and interesting presentation Paul provided a link to on scvr recently. Will their new customers stick around? Recent acquisition activity in the US with pure online plays adds some extra spice to this one.
They have, IMO, significant problems with new distribution warehouse. My last two deliveries have been sent out late. True they tell you they are delayed but twice in a row is an issue. Also the second delivery has still not arrived and has been delayed again. Whilst they give a monetary gesture , (does not help profits), they need to fix quickly or they will lose customers.
PS Should add that their communication of the delays is excellent but.....
agreed, I had a problem recently where two bottles were missed. Human error of course and was very quickly resolved via email. Will keep a close eye on that, hopefully teething issues that will be sorted out.
Yes I doubled my money on Naked. C19 was a catalyst for demand but their historic customer retention is incredibly high. If they replicate that in the US, which is the worlds largest direct to consumer wine market, they are on to a winner. Increased demand and C19 staffing issues are likely causes of issues with delivery.
My morning smallcap tweet: No boos but cheers for WINE
Naked Wines (LON:WINE) Safestyle UK (LON:SFE) Tissue Regenix (LON:TRX) Sareum Holdings (LON:SAR) French Connection (LON:FCCN) M P Evans (LON:MPE) Nucleus Financial (LON:NUC) Andrews Sykes (LON:ASY), Renold (LON:RNO)
Naked Wines (WINE) June rev up 67% as lockdown boost continues.
Safestyle UK (SFE) guides H2 rev down 34%. Order intake in last 8 weeks up 23%, ahead of mgmt exp. Initial installation revenues only marginally ahead due to capacity limit but up 17% in last 3 weeks. Outlook "not yet clear whether the recent performance is sustainable in an environment where confidence and consumer demand remain uncertain."
Tissue Regenix (TRX) starts first phase of its planned manufacturing capacity expansion programme in US. Demand, in particular the BioRinse orthopaedic product portfolio, continues to grow and the first phase will increase BioRinse processing capacity by 50%.
Sareum (SAR) encouraging results for its small molecule dual tyrosine kinase 2 (TYK2) and Janus kinase 1 (JAK1) inhibitors in disease model studies of systemic lupus. Is that a computer sim then? This may lead to the development of a therapy for lupus that does not involve the harmful side effects of systemic immune system suppression.
French Connection (FCCN) slow start to sales since store reopening. "We are seeing sales volumes grow week on week, as further relaxation of the lockdown continues, however we anticipate this to be a gradual process especially in larger cities." New £15m working capital facility, "expects will be sufficient to cover the Company's cash requirements, based on its current conservative expectations of future trade." I hold.
M.P. Evans (MPE) guides H1 fruit prodn up 34%, palm oil up 31%, palm kernels up 28%. Palm oil price up 17%. Expects to maintain div.
Nucleus Financial (NUC) Q2 assets under administration up 3% and up 13% on Q1. "The Covid-19 pandemic has had a significant impact on all our lives over the last four months." Thanks for that.
Andrews Sykes Group (ASY) 23.7p special div.
In line: Renold (LON:RNO)
any chance you could have a look at Ceres Power. It has progressively dropped 20% in value despite positive news and institutional investment.
Bought Ceres a few times recently but the drop since last week is quite large, probably like everything else though.
All the fuel cell shares have fallen 20% plus.I suspect it is profit taking.Their share price rises have been ballistic so no suprise.If govts are committed towards building an infrastructure for hydrogen transport then the sub-sector is a buy and hold .Toyota has announced that it will build a hydrogen car which suggests Japanese govt may be investing in hydrogen infrastructure.
Ceres has the China connection which could go both ways. China could follow Japan.On the other hand the West is looking to pick a fight with China
I don't see any news out today from Ceres Power. The shares I cover each day here are companies that have issued results, trading updates, or other significant news.
They are just around the corner from me in Horsham..I might have to wander past and listen through the keyhole....just kidding - although sometimes a chat with staff can reveal all sorts.Every time I called G4M over the last few months for musical kit they kept telling me how busy they were and really stretched.