Small Cap Value Report (Fri 24 Sept 2021) - BUMP, SFE, ITS, JDG, TMG

Good morning, it's Paul and Roland here, with the SCVR for Friday. Today's report is now finished, have a lovely weekend!
Agenda -
Paul's Section:
Seraphine (LON:BUMP) - (from y'day) - a profit warning just after 2 months of listing - is this a record? I have a rummage through its prospectus, and conclude this is actually quite an interesting business - supplying niche maternity clothing. Supply chain delays from China caused a shortage of stock in July & August. That's since been fixed. A buying opportunity maybe?
Safestyle Uk (LON:SFE) - (from y'day) - excellent interim results from this double glazing company. Not a sector I would consider, but for people who do, then this share could be worth a closer look.
In Style (LON:ITS) - Trading update that starts well, and gradually turns into a profit warning! Supply chain problems (not a surprise) and much higher customer returns are given as reasons. Underlying demand looks strong though. Impossible to value, given the absence of proper guidance.
Roland's Section:
Judges Scientific (LON:JDG) - Excellent results from this scientific instrument firm, showing a decent recovery. But the shares are trading at a historically strong valuation, suggesting to me that the shares may be up with events.
Mission (LON:TMG) - This marketing group has delivered a solid set of half-year results, suggesting the business is getting back on track. Although profits are normally weighted to the second half of the year, I think this stock could offer value at current levels.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
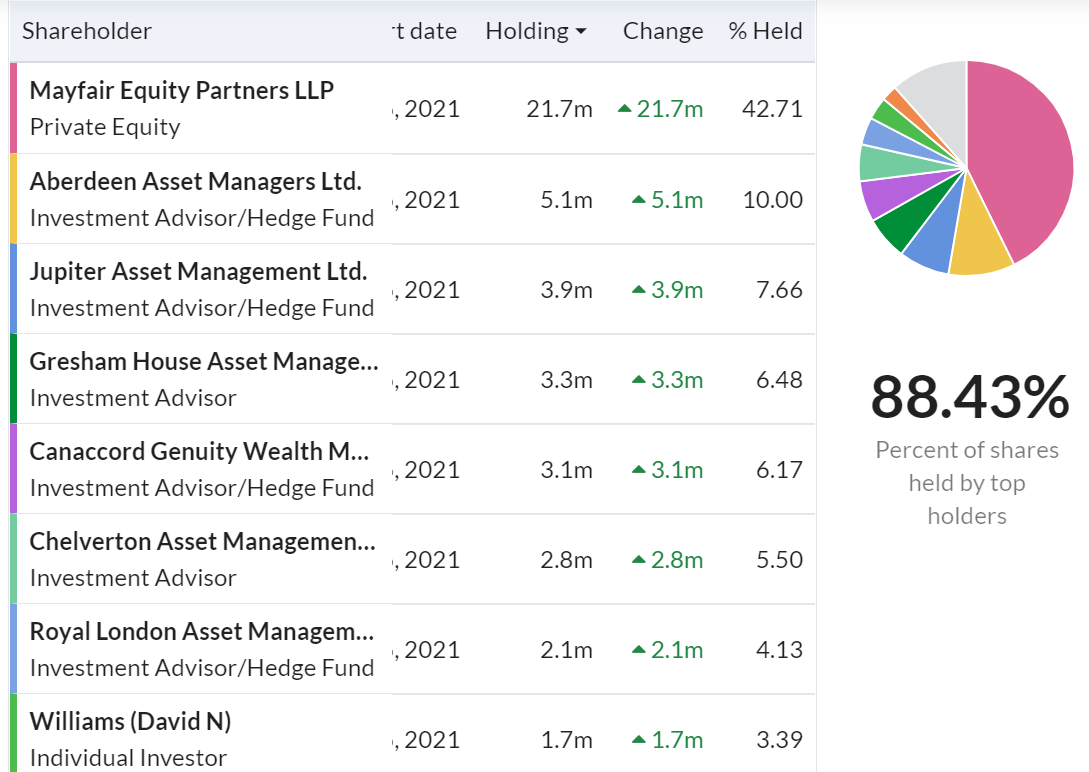
Seraphine (LON:BUMP)
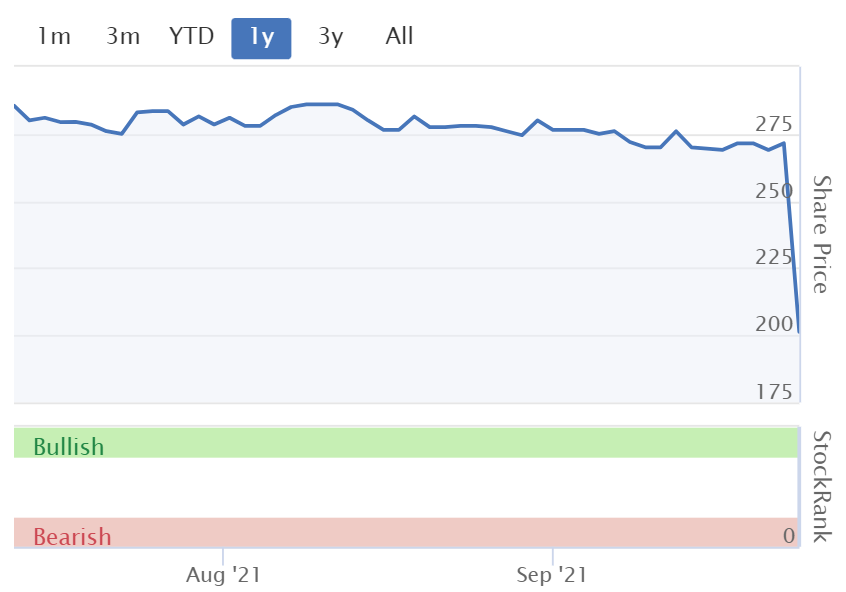
Share price: 204p (down c.25% y’day)
No. shares: 50.9m
Market cap: £103.8m
Well this is awkward. This digitally-led vendor of maternity & nursery products floated on the main market on 16 July 2021. It’s issued a profits warning today, just over 2 months later.
The Group experienced a strong Q1 (13 weeks to 4th July 2021) with better than expected demand for higher priced categories and delivered year on year Group revenue growth of greater than 50%. However, trading in the second quarter has been more challenging than the Board anticipated…
Supply chain problems led to a shortage of stock in July & August, hence lower than expected sales. It says the supply problems (delayed shipping from China) have now been “fully resolved”.
Digital partnerships (e.g. Zalando) are doing well.
Retail stores (BUMP has 8 shops) are “challenging”
Guidance - I don’t know how this compares to previous expectations, as this is a recent float, and I’ve not looked at it before -
As a result the Group now expects H1 year on year revenue growth to be circa 35% on a constant currency basis (circa 30% on variable currency) and Adjusted EBITDA pre-IFRS16 to be circa £2.5m (circa 15% below previous year).
Looking ahead to the full year, should the recent trends continue, the Group would expect revenue growth to be at least in line with H1 and profit to be at least in line with FY21 (on an Adjusted EBITDA pre-IFRS16 basis).
Actions are being taken to improve performance.
My opinion - obviously an incredibly embarrassing, and infuriating (for institutions who bought into the recent float) profit warning, coming so soon after a new listing.
My view is that supply chain problems are temporary, and fixable, so really shouldn’t impact the long-term valuation of companies very much at all. However, that’s not how the market is actually behaving - shares are routinely slammed 20-30% on supply chain problems. That is creating, and no doubt will create many more buying opportunities. Hence why I think this is a really good time to build up a cash pile, to pounce on panic sell-offs when some companies inevitably report supply chain problems that we all know are coming. That’s an opportunity staring us in the face, and is my main investing theme for the rest of this year.
I don’t have an overall opinion on BUMP, and don’t feel inclined to plough through its prospectus, because most floats are over-priced, and I only tend to become interested if they drop in price by about half.
When the company reports its next results statement, then I’ll take a closer look.
How does it make sense to float something with such a small free float?
.
Prospectus - OK, curiosity got the better of me, and I’ve just skimmed through some of the prospectus and this business does look quite appealing. It has a track record of decent growth, delivers high gross margins, and is profitable.
My opinion - this looks like the sort of niche online retail business that I tend to gravitate towards.
At some point in the future, I’ll have a proper dig through the numbers. For the moment a £104m (after today’s profit warning) doesn’t strike me as a bargain, so I’m not motivated to dig any deeper, but will keep it on my watch list, and report back to you when it publishes maiden results as a listed company.
.
.
Safestyle Uk (LON:SFE)
55.8p (up c.8% y’day) - mkt cap £77m
Safestyle UK plc (AIM: SFE), the leading UK-focused retailer and manufacturer of PVCu replacement windows and doors for the homeowner market, today announces its interim results for the six months ended 4 July 2021.
Strong first half driven by improved gross margins and continued progress made against our strategic priorities
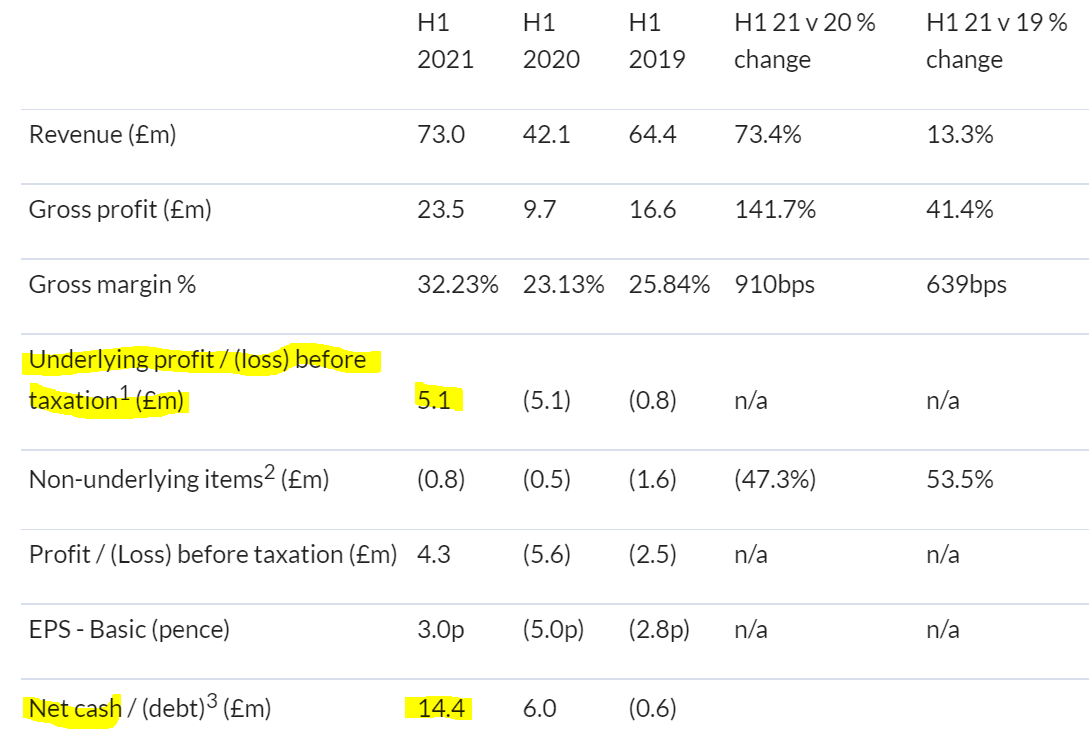
The financial highlights look excellent - this is a decisive return to profitability, and is only for H1 remember -
.
Order book - is strong -
Order book at the end of H1 was 9.6% ahead of H1 2020's position and 65.7% ahead of the closing position at the end of H1 2019.
Operational challenges -
Customer service provision has remained a challenge due to the broad range of disruption experienced, most notably labour availability…
Continued operational challenges are anticipated for the remainder of the year, particularly potential supply chain disruption and resource shortages in critical skilled labour pools.
Full year trading is anticipated to be in line with expectations.
Balance sheet - is OK, with tangible NTAV c.£10m.
As with DFS above, double glazing companies benefit from favourable working capital - customers paying at least some up-front.
My opinion - these numbers look excellent. It’s not a sector that interests me, because the big flaw in the business model for double glazing companies, is that so much of the profit comes from a small group of star salespeople. Who can up sticks and join/create a competitor. We saw SFE’s profits wiped out a few years ago, when exactly that happened.
.
.
In Style (LON:ITS)
196p (last night’s close) - market cap £103m
In The Style, the fast-growing digital womenswear fashion brand with an innovative influencer collaboration model, announces a trading update for the period from April to August 2021 (the "Period")...
This update starts strongly, then steadily deteriorates, such that by the end I think it’s become a profit warning!
The financial year ends 31 March 2022, so today we’re being told about trading in the first 5 months - most of H1.
This is not the easiest trading update to interpret, because ITS floated this year, on 15 March 2021, hence there are no interim results from last year to use as comparatives.
I’ve looked through the Admission Document, and that gives historic years results, plus 9 months to 31 Dec 2020 unaudited figures.
Summarising the figures in the admission document -
FY 03/2020 - revenues of £19.3m, Adj loss before tax £(2.16)m - this year and all previous years are when the business was sub-scale, and loss-making.
FY 03/2021 - the breakthrough year, with revenue shooting up 132% to £44.7m, and a move into adj profit of £2.47m.
It was on the back of this performance that ITS floated on AIM in March 2021 (the prospectus contained 9 month figures to 31 Dec 2020, which showed the very strong growth underway in calendar 2021). My concern was that maybe ITS was benefiting from both a boost to sales from lockdown (as physical competition was closed for much of 2020 and early 2021), and also that a fly-on-the-wall TV documentary gave the company a lot of free publicity. We’ve seen before how a virtually identical series for larger competitor Missguided helped to turn around its fortunes, when it had a period of disastrous performance, narrowly avoiding insolvency.
So there’s no doubt the exposure from documentaries, even though it shows the chaos which is normal for the fast fashion sector, does give them a significant boost.
In the ITS documentary, the team came across as personable underdogs, trying (and often failing) to compete with giants Boohoo (LON:BOO) (I hold) and Asos (LON:ASC) (I hold), and of course we Brits love to support the underdog! So I reckon that documentary probably did ITS much good.
FY 03/2022 - moving on to the current financial year, this is what we’re told today -
5 month (April-Aug 2021) revenues up a startling +45% against strong comparators (although no figures are given other than the % increase). Taking out wholesale revenues, eCommerce Gross Order Value (NB not the same as revenues!) were up an even more impressive +50%.
Keep reading though, and it turns out that there’s been a large increase in the returns rate, due to a shift in demand from casualwear last year, to occasionwear this year. Women customers don’t tend to return much product that is loose, and made in stretchy fabrics (casualwear). But they do return a much higher proportion of say dresses, which are a more complex fit. We’ve heard this from Sosandar (LON:SOS) (I hold), which is why SOS has broadened its product range into other categories with lower returns rates, such as stretch fabric jeans.
It turns out that the +50% Gross Order Value drops to only +25% net revenue growth for eCommerce, which means that customer returns (with the associated cost of postage, handling, and re-sale) have put a massive dent in the sales growth.
I imagine there’s likely to be some read-across to other eCommerce fashion businesses too, and indeed this issue has already been alluded to in commentary from Boohoo (LON:BOO) - the unusually low returns rate of last year was not expected to continue, so it’s a known factor.
ITS customers are buying from their mobile devices through the app - this has now reached 62% (prior year 53%) of total sales.
Wholesaling is up 200%+ due to the launch in 100 ASDA stores, but again no actual figures given.
New hires have been made, which means more central costs, again no figures provided.
Supply chain - the big issue for everyone who imports physical goods from the Far East - i.e. pretty much all companies that sell physical goods of any kind, whether retail, or B-2-B.
Supply chain difficulties should not be coming as a surprise to any investor. I think a lot of this has already been priced-in, with many shares selling off in recent months. The trouble is, the market often punishes shares twice - once in anticipation, then another sell-off on the actual news of supply chain difficulties. These could be our buying opportunities, as mentioned above, so I see this as more opportunity than threat.
The best managed, and larger companies should be able to navigate through these problems, and see strong demand offsetting the extra costs.
Unsurprisingly, ITS today says that it is seeing shipping delays, and extra costs. This is expected to continue until at least March 2022, and will impact profits. Again, no figures given. So this is a profit warning I think.
My opinion - I find trading updates like this very unsettling. We’re not given any specific guidance on profitability, just told that higher costs & customer returns will impact profitability. That’s not good enough, investors need numbers.
More detailed guidance is often slipped out by companies, via brokers research analysts, whose research notes are sometimes (depending on the broker) only accessible by a select few institutional & high net worth clients of the broker. This is so wrong. Everyone should be given proper guidance at the same time, as the Companies Act requires.
Liberum is generally very helpful, publishing excellent quality research notes via Research Tree. ITS is one of their stocks, so let's hope they promptly update us through that channel. Nothing has come through so far, but sometimes there's a short delay.
Supply chain problems are par for the course at the moment, and really shouldn’t be surprising any investors. The trouble is, that shares of this size (particularly recent floats) are largely owned by major holders, with a small free float. So the price moves a lot, on very little volume, because market makers want a neutral book. This means price movements can be greatly exaggerated.
I’m impressed with the sales growth at ITS, because it’s on top of what I suspected was a one-off good year in FY 03/2021. To be lapping those numbers, and seeing +50% higher eCommerce orders is very impressive.
Although the increase in customer returns seems huge, to take that growth down to +25%.
Supply problems don’t bother me, as that’s one-off for now, and I’m not buying this year’s earnings, I’m buying all the company’s earnings for the rest of time. So for long-term investors, a one-off bad year from factors outside the company’s control, should not logically be punished too much. The trouble is, illiquid markets dominated by short term traders, are not logical! Hence why I think it’s a good time to keep a cash pile on the sidelines, ready to pick up some bargains as supply chain problems cause a wave of profit warnings.
In the first hour of trading, ITS is down about 10% to 175p, valuing it at about £93m. That’s not an outrageous over-valuation.
This is a very competitive sector, and it’s difficult to make a profit at all, especially now there is such a focus on ESG. Chinese competitor Shein seems to be rapidly carving out a large market share in the USA, and I think fears about it doing the same in UK/Europe is behind the sector de-rating of online fashion businesses such as Boohoo (LON:BOO) (I hold) and Asos (LON:ASC) (I hold).
I’ll keep an eye on ITS, but am not ready to take the plunge at the current price. If it were to get down to say 100p, then I think it might be worth a punt. It’s incredibly difficult to scale up in this sector, due to the massive marketing spend of the larger companies.
Today’s update hasn’t helped, by warning on profits, but giving no actual numerical guidance. For that reason, it’s impossible to value this share, given incomplete information provided.
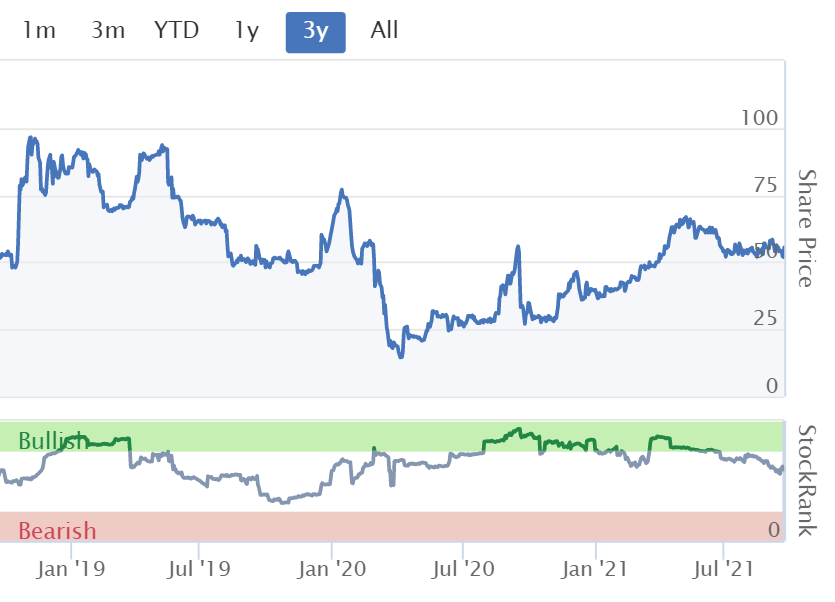
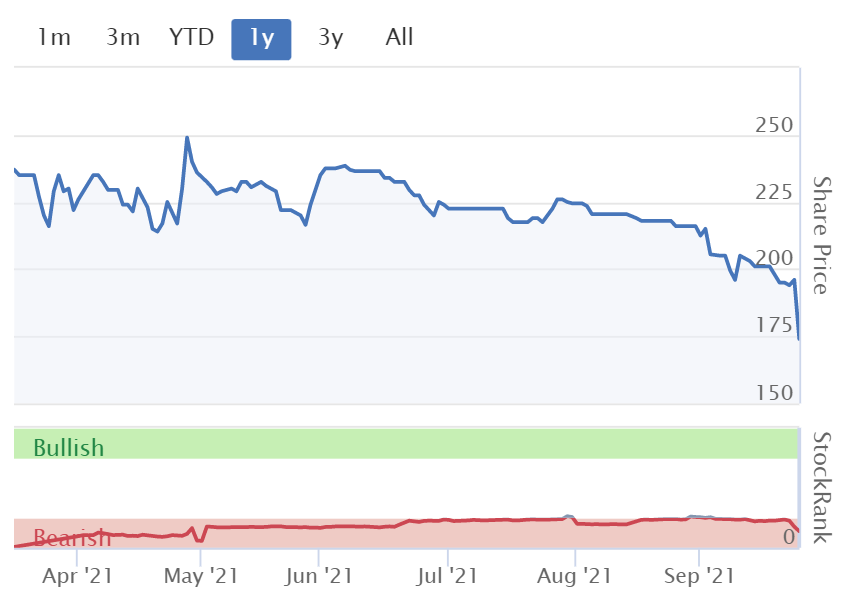
In my experience it's usually a mistake to buy a share with a chart like the one below! Usually better to watch from the sidelines, and see where it settles. Or to only take the plunge when the valuation is so compellingly cheap that further falls don't really matter, because the longer term upside is so great. ITS doesn't tick either of those boxes at the moment for me, so I'll sit on the sidelines for now.
.
Roland’s section
Judges Scientific (LON:JDG)
Share price: 7,000p (pre-open)
Shares in issue: 6.3m
Market cap: £442m
This highly-regarded manufacturer of scientific instruments is popular with investors - and for good reason.
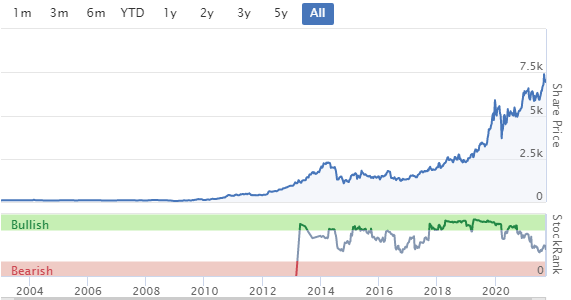
Today’s half-year results for the period to 30 June 2021 suggest to me that this show is still on the road.
“The Board is confident that the Group will exceed existing market expectations for the current year.”
When Judge’s profits slumped last year, the company said it believed that orders had been deferred, not cancelled. I think today’s results support this claim. Let’s start with a look at the key points.
Financial highlights
- Revenue +14.7% to £43.0m
- Adjusted pre-tax profit +31.5% to £8.5m
- Cash generated from operations +56.5% to £8.0m
- Adjusted eps +31.8% to 111p
- Interim dividend +15.2% to 19p
- Net debt £1.7m (H1 2020: £5.7m)
These numbers are broadly comparable to Judge’s half-year results in 2019. I’ve not compared them explicitly above because the company’s regular acquisitions mean that a comparison of this kind would not be like-for-like.
Fortunately, the company has provided some metrics which show a like-for-like progression against 2020 and 2019.
- Organic revenue +5% against H1 2020
- Organic order intake +25% against H1 2020 and +3% against H1 2019
- Organic order book at 16.1 weeks (H1 2020: 10.8 weeks, H1 2019: 13.2 weeks)
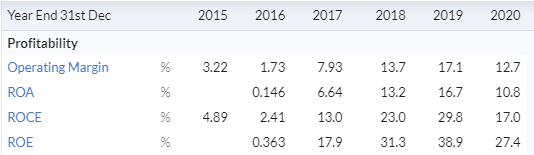
Profitability: According to my sums, today’s numbers give Judges a trailing 12-month operating margin of 14.8% and a TTM return on capital employed of 21.0%.
These are both excellent figures, in my view, and are consistent with the company’s historic performance:
Balance sheet & cash flow: There’s not much to say here. Judges’ cash conversion is strong and fairly consistent, and the group’s balance sheet looks fine to me.
The group did not need to dilute shareholders last year and recently secured a new £60m bank facility (previously £35m) to support increased acquisition activity.
Naturally there’s a lot of goodwill on the balance sheet, reflecting past acquisitions. Today’s accounts show £18.7m of goodwill, out of a total equity (book) value of £38.2m. However, given the company’s consistent growth and profitability over many years, I don’t see this as a concern.
Outlook
Today’s commentary is short but fairly reassuring, in my view.
The business is still recovering from the impact of Covid-19 and some scientific markets are recovering more quickly than others. Supply chain issues are having a growing impact, but the company’s recovery is continuing.
The group’s total order book now stands at 20.1 weeks and organic orders (i.e. like-for-like) are 23% higher than at the end of August last year.
Judges’ board is confident that full-year results should be ahead of current market forecasts. No explicit guidance is provided, but broker WH Ireland has put out an updated note this morning upgrading its 2021 earnings forecast by 10% to 208.2p per share.
That puts Judges stock on 35 times 2021 forecast earnings, after this morning’s gain.
My view
Judges’ chief executive David Cicurel is popular with investors and is an entertaining speaker. But he’s also the company’s largest shareholder, with a 10% stake, and the main driver of its disciplined and consistent acquisition-led growth strategy.

I expect Judges to continue to make good progress while Mr Cicurel remains invested and in charge. But at the age of 71, I wonder if succession planning could soon become an issue.
My only real concern today is the stock’s valuation. While I subscribe to the idea of paying a premium for a high-quality company, Judges’ shares are looking a lot more expensive than they have done in the past.
Using Stockopedia’s own WaybackMachine (click on the arrowhead next to the print button at the top of the StockReport), I’ve compared today’s valuation of 35 times forecast earnings with the ratings seen over the last few years:
- September 2021: 35
- September 2020: 29.9
- September 2019: 18.9
- September 2018: 17.4
Judges Scientific has become more expensive, but I’m not sure it’s become a better or faster-growing business.
For me personally, the share price is up with events. Judges’ dividend yield has dropped below 1% and I estimate the trailing free cash flow yield at 2.9%, excluding acquisitions.
These metrics don’t suggest much value to me, given that consensus forecasts ahead of today were suggesting single-digit percentage growth this year and in 2023.
I wouldn’t sell Judges Scientific shares if I held them, but I would want to wait for a better buying opportunity.
.
Mission (LON:TMG)
Share price: 76.3p (+1% at 9am)
Shares in issue: 91.0m
Market cap: £68.7m
Half-year results (announced 22/9)
As usual on Friday, it’s a relatively quiet day for news. So I’m going to scroll back to Wednesday and cover half-year results from Mission (LON:TMG)
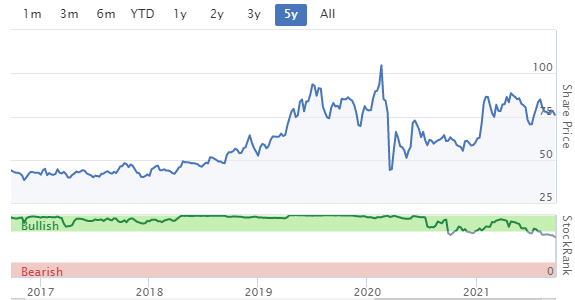
Mission is a group of marketing agencies that’s appeared in my screening results from time to time and often looks attractively valued. Progress has been somewhat mixed in recent years though, and the company’s revenue was hit hard last year. Timing has been important for buyers:
Financial highlights
Profits are seasonal at Mission - in 2019, around 65% of profit was generated in the second half of the year. So we have to bear that in mind when looking at numbers for the first half of the year.
- Revenue +17% to £34.1m
- Pre-tax profit: £1.4m (H1 2020: -£2.3m)
- Earnings per share: 1.7p (H1 2020: -1.92p)
- Net bank debt £3.9m after settling £4.5m of deferred tax/dividend liabilities
Mission’s business has returned to profitability during the first half of the year and appears to have maintained a healthy liquidity position.
I should point out that the company’s use of revenue (as above) is an adjusted measure. It excludes pass-through costs, such as television advertising, to which Mission does not apply a margin.
Stockopedia’s data provider naturally reports statutory revenue. This is why forecast revenues are much lower than historic revenues:
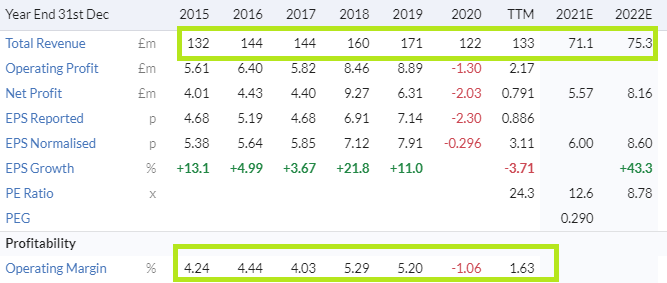
Mission’s adjusted measure of revenue also impacts operating profit margins, which I’ve highlighted above. For example, the 2019 statutory operating margin of 5.2% shown above is considerably lower than the c.13% margin I calculate for 2019, using TMG’s adjusted revenue.
Excluding pass-through costs is not unusual in this sector. For example, FTSE 100 rival WPP does a similar thing. I think it’s probably fair to say that this adjustment does provide a more accurate view of underlying profitability, as long as it is done correctly and consistently.
Trading update: Eleven of the group’s 13 eligible agencies are said to have delivered year-on-year growth. New business wins included FTSE 250 housebuilder Redrow, Porsche GB, Mecca (bingo, I assume) and online used car retailer Cazoo.
Balance sheet: I’m comfortable with Mission’s debt and cash positions. But it’s worth noting that the balance sheet has negative tangible equity and carries £7.3m of acquisition obligations, which I would view as a form of hidden debt.
Most of these payments are due in cash. If I include these, then the group’s net financial debt rises from £3.9m to £10.9m.
That still looks manageable to me against forecast profits of £5.6m, but I think it’s worth remembering that these acquisition obligations are expected to result in a cash outflow of £6.4m over the coming 12 months. Arguably, the company’s liquidity position isn’t quite as strong as it appears at first glance.
Outlook
Fortunately, the outlook appears to be improving. Assuming that no further Covid-19 restrictions are put in place in the UK, Mission’s board expects
“the Group’s sequential recovery to continue in line with expectations” (my bold).
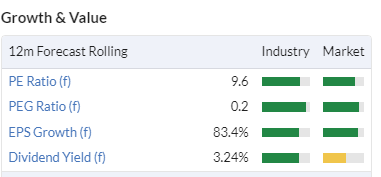
There’s an updated broker note this morning from commissioned research broker Edison which leaves forecasts for 2021 unchanged. Edison is forecasting earnings of 6p per share in 2021, rising to 8.6p in 2022. These numbers are in line with the consensus numbers shown in Stockopedia.
This gives Mission Group some potentially attractive valuation metrics:
My view
I’ve got mixed feelings about this business. On the face of it, Mission has similar underlying profit margins to larger rivals, but its shares trade at a lower valuation.
The group is also returning to growth and appears to have a positive outlook.
On the other hand, Mission’s practice of regular acquisitions isn’t without risk.
This is also a cyclical business that is dependent on client marketing spend. Last year was an extreme example of how this spending can be cut, but even in a more normal downturn, Mission could see a dip in client spend and a corresponding drop in profits..
Profitability has been somewhat inconsistent over the years, although pre-Covid, the trend was positive:

On balance, I can see potential value here. I could be interested in taking a closer look at Mission at current levels.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

37 comments
If I'd told you 5-8 years ago, that French Connection (LON:FCCN) (I hold) would still be going in 2021, whilst Arcadia would have gone bust, you'd have carted me off to the nearest funny farm.
It seems unusually quiet on here today.
Maybe everyone is out queueing for Petrol or Diesel .
News on former FTSE 250 “golden boy” Petrofac (LON:PFC) since fallen on hard times (and into the SCVR market cap remit) due to a long running SFO fraud enquiry (do they ever have any other duration?!) into alleged bribery by now departed senior management to secure contracts in the Middle East. (Do bears really s**t in the woods?). Basically the company has agreed a resolution with the SFO with a financial penalty yet to be determined over the next few weeks. The statement suggests the SFO acknowledges the company has changed substantially (better compliance, guilty parties all gone, serious helpings of mea culpa humble pie etc.) so hopefully the penalty will take this favourably into account.
https://www.investegate.co.uk/....
Historically this was a quality company (or at least had good earnings from high value long term contracts with leading players in the sector albeit secured on questionable terms) so it could be an interesting special situation recovery play. For my sins I hold (and have held for a while). Shares at about 106p when the news broke.
Gus.
I flagged on this original report that Petrofac (LON:PFC) had reached an in principle settlement with the SFO about historic bribery actions. Terms of the settlement were announced yesterday, including an aggregate fine of about £77m. This should be seen in the context of a market cap of about £600m so not peanuts but substantially less of a sanction than was once feared.
https://www.investegate.co.uk/....
In addition there will have been considerable associated costs and a huge amount of management time devoted to dealing with the enquiry as well as damage to reputation and turnover of senior management. All told the shares are now about 1/5 of where they were before news of the scandal first broke (above £9) but at today’s 182p considerably more (about 70%) than the 106p mentioned above in my original post a couple of weeks ago*. Possibly more to come from what historically was a well connected (hopefully for the right reasons!) quality service provider to the O&G sector now that this enquiry/ restitution is behind them.
Gus.
(Bear in mind, there’s been no new share issuance during the period so the total share count is more or less as it was five years ago).
Not small cap shares related, but I'd advise to keep an eye out on 10 year gilt prices.
Yields were only 0.5% a month ago but now approaching 1% after a huge rise yesterday and today.
This, of course, will put pressure on shares on a high PE rating where expectations are big profits in medium/long term horizon like tech stocks...
Very good advice indeed. I have large holdings of US growth stocks and the first macro datapoint I look at every morning and whenever the market lurches is the US 10yr Treasury yield. I recently trimmed every single one of my >100 growth stocks by 10% across the board for exactly the reason you've given. I'm not trying to time the market - I'm still >85% in equities - and I have a discipline of buying back into any top-sliced name that has dropped by a pre-determined level.
There is a thread on Oxford Nanopore in the context of the possible impact of the IPO on Ip (LON:IPO) and Schroder Uk Public Private Trust (LON:SUPP) which are both substantial holders and which might be one of the few ways for ON bulls to stag the game ahead of the launch in the next week or so.
https://www.stockopedia.com/co...
Gus.
I need to come around to this sort of thinking "I wouldn’t sell Judges Scientific (LON:JDG) shares if I held them, but I would want to wait for a better buying opportunity." Having sold at £45 (repurchased at £60 for family portfolio mind you).
The problem I have is with this thinking is that if as a holder I'm not buying more who is to drive the price further? New buyers will say it's too expensive...
You could say that about most high flyers, yet the prices often go up further. Value stocks often stay value stocks. If you compare momentum v value, momentum will win. Quality will usually also beat value. Value there is often a reason for, such as high debt. I have made the mistake in the past of not buying shares because they look too expensive. A few PIs will not affect the share price anyway. Institutions may want to buy.
If the company keeps beating the forecasts then the share price should continue to rise but not always as we have seen lately in this market, but if they miss a forecast then the shares will plummet.
Plummet indeed. That’s pretty much exactly what happened with Avon Protection (LON:AVON) which was the other former high growth/high momentum star in my original post with news out today that warned on a delay in orders at the back end of last year and saw its share price halve.
Gus.
Paul , sorry enjoy the sun of course .
I agree with Yiannos1 on NSCI , reminds me a bit of ELTA situation where sun of the parts is clearly currently way in excess of market cap .
Unless PDSB price collapses totally then NSCI looks significantly under priced , and if PDSB continues / holds looks a very low risk opportunity with very good medium term upside , plus the added bonus of significant upside should any of the other investments hit a home run .
Great to see coverage of Judges Scientific (LON:JDG) (I hold) on a “value” forum. While not cheap, it’s important to see the company’s valuation in the context of recent multiple expansion for other laboratory and medical equipment suppliers.
According to my Refinitiv feed, Judge’s is on an FY21 EV/EBITDA of 25x while lab equipment manufacturers like JEOL ( Japan - I hold), Tecan (Switzerland - I hold) and Agilent (US - I hold) are on ratios of 33x, 33x and 31x. And if you want to see what expensive looks like, try Sartorius Stedim Biotech (France-Germany - I hold) on 55x.
By this most levelling of metrics Judges represents decent value and would, if listed in Switzerland perhaps, be on a considerably higher multiple. I’m sure other holders are happy and the market reaction this morning is positive. My experience as a long term owner is that new buyers might get a better price next week but shouldn’t worry too much about entry price if their horizons are lengthy.
Fair comment BnB about the relative value of Judges Scientific (LON:JDG) against some of its peers. With an initial holding from September 2016 at 1280p a share, however, the current 7000p+ looks vertiginous and the temptation to top slice is there but the company does keep growing into progressively higher valuations so I should probably just stick it in the coffee can and leave well alone.
Gus.
Hi BnB,
Thanks for your comment. I agree that Judges Scientific (LON:JDG) is a high quality business that might turn out to be a profitable long-term hold from the current valuation.
But while it's true that some comparable businesses are more expensive than Judges, I don't agree that a stock is good value simply because another stock is more expensive.
Similarly, just because the whole sector has seen multiple expansion does not necessarily mean that it's safe to ignore this.
If Judges Scientific was re-rated onto a P/E of 25, the shares would fall by 30% (£75 -> £52) based on the latest earnings forecasts.
This is why I think it's important to consider absolute valuation (e.g. FCF yield) as well. My question is would I be happy with the returns implied by the current valuation. In this case, I'm not sure I would.
A fund manager holding stocks might have to keep buying at any price to deploy client inflows. But fortunately as private investors we can be more choosy and wait for opportune moments to buy.
Regards,
Roland
I completely agree, Roland. Shares have to make sense as a proposition in isolation of their peers and with reference to the investors own benchmarks. For example, Judges FCF yield is unlikely ever to rival that of another of my quality UK mid caps , K3 Capital, in a different sector, so would be off the menu for many.
My point was that for those seeking exposure to a picks and shovels play on life sciences growth, Judges is relatively cheap amongst the higher quality names globally.
I think this discussion ably highlights how different investors have very different approaches. Many here (at least judging by the thread name) are looking for value as a guiding principle and that very often means identifying a company in some stage or other of recovery, where a mis-pricing of risk and reward has potentially developed. My approach is to invest in companies exclusively within secular growth sectors (the usual themes: digital transformation, cybersecurity, genomics, life science, e-commerce, energy transition etc) and I'm more interested in excluding candidates on the basis of low quality than including them on the basis of low valuation. To many, high valuation is a risk, when, to my perspective, the risk is in going down the quality scale.
Of course there is a goldilocks zone where we can all meet and hopefully find quality businesses on reasonable valuations, Kainos, Games Workshop, Strix and Somero would be good recent examples. But with the bubble of everything that's not getting any easier!
Note that In Style (LON:ITS) commented today:
As anticipated, over the Period the Company has seen a shift in demand towards occasionwear, which typically carries a higher rate of returns than the leisurewear categories that dominated the sales mix during the prior year...
This confirmed my thoughts (which were pretty obvious really), hence why I bought into Quiz (LON:QUIZ) (I hold) last year, anticipating a recovery in its niche of occasionwear. Given that's what QUIZ has always done, then it would probably be used to the higher returns rate.
QUIZ shares have re-rated a lot recently, but the market cap is still very small, at £31m, despite it being bigger than some of the newer online fashion businesses like Sosandar (LON:SOS) (I hold) and In Style (LON:ITS) . The store portfolio is no longer a problem, but an asset, having moved to short leases on low turnover rents.
I'm hoping for a positive update from QUIZ next week, it's due to report on Weds, 29 Sept, but we'll have to wait and see what they say.
The improvement in occasionwear sales from opening up must be what's driven the interest in QUIZ shares of late, and they're very tightly held, so buyers have no other option than to force up the price, if they want to get hold of any. I spent about a year buying stock, it was fiendishly difficult, because there were rarely any sellers, and I refused to pay a stupidly wide spread.
Fingers crossed! Due to price appreciation, QUIZ is now my 3rd largest position. Obviously DYOR. I would say this is high risk, but if you crunch the numbers properly, actually it isn't as high risk as people imagine. Net cash on a strong balance sheet, 50% family ownership (owner's eye), very experienced rag traders running it, and costs stripped out during pandemic.
If it continues to do really well, I'll give another grand or two to ZANE :-)
Regards, Paul.
Quiz (LON:QUIZ) also noticed that the online presence appears to have been enhanced with cleaner/better website.
Note that Saga (LON:SAGA) (I hold) is doing a presentation on InvestorMeetCompany at 11:30 today. I know a lot of subscribers here hold SAGA, hence thought a reminder might be useful.
A couple of my longer term holdings out with news on an otherwise typically quiet Friday. Judges Scientific (LON:JDG) continues to churn out ahead of expectations earnings upgrades with another this morning. Share price continues to defy gravity and its on a very high valuation multiple but a very solid performer.
https://www.investegate.co.uk/...
Meanwhile defence stock Avon Protection (LON:AVON) has come out with another big order extension from the US military. Share price has been in the doldrums of late after a stellar run last year but to my mind seems oversold against the backdrop of a solid business with an established relationship with the US army (and others) in a sector that has seen a lot of takeover activity of late.
https://www.investegate.co.uk/...
Gus.
Hi Gus, I also hold those 2 stocks. I agree about Avon Protection (LON:AVON), seems just delays in contracts, if they do come through next year, this could be a good recovery stock. I'm tempted to top up but will probably wait until next week.
That’s PDSB not PFSB .
Bump indeed! Interestingly, Hargreaves Lansdown, my main market news feed isn't showing this RNS when I look up BUMP at the moment but it is there on Investegate.
An immediate thought: they have a smaller chance of attracting repeat business than many clothing brands. These are not casual purchases and each punter will have 1,2 or 3 buying seasons at best.
Most purchases will get handed down to relatives or resold via charity shops or online outlets. "digitally led" means online sales, hence lots of returns, so they are also competing against their own returns stock.
Thus, they are going to continually struggle to attract new buyers and have to compete with 2nd hand outlets against their own range. Their marketing costs will be immense.
I have no position in Seraphine (LON:BUMP) but I don't quite agree with that assessment.
Firstly the average household is 2 children and usually 2-3 years in-between so an average customer may frequent a baby/toddler outlet (digitally or otherwise) for the best part of 5 to 6 years in all if they have a good experience. Granted they may not be all big ticket items but parents propensity for "new" is high. If incomes get squeezed (and that may happen in the not too distant future) then I do agree this type of retailer could suffer worse than average, so geographic diversification is probably important.
In the baby universe word of mouth and reputation is probably more important than the marketing itself. So clever marketing will get Mums to talk to each other and build brand that way rather than direct advertising to each individual. Thus marketing costs do not need to be immense at all but they do need to be well executed.
Presumably they are a direct replica of Mothercare (LON:MTC) new strategy (small number of retail outlets, franchises and digital sales). Be interesting at some point to compare the two. I wouldn't want to own both, and actually, I probably want to own neither given the chequered history of this segment but I might do a bit more analysis.
Any chance of commenting on NCSI ? Looks a potential special situation with its market cap almost entirely covered by cash plus its equity in PFSB . Leaves all the rest of its portfolio effectively in for free .
Looks an anomaly of a rating and with news due out soon very likely to rerate significantly especially if PDSB keeps rising so strongly .
I don't want to delve into a new share to research, because I'm on holiday & want to enjoy some sun today! (hence why I did 2 sections last night, to clear the decks a bit for today). Sorry about that. By all means tell us more about £PDSB though, as your introduction does make it sound quite interesting.
Thanks, Paul.
NSCI has 1,338.833 shares in PDSB ( closed at $17.08 ).
PDSB is collaborating with MERCK and speculation is that they will be bought by MERCK eventually.
What strikes me here is that one of the major shareholders of NSCI ( Melvin Anthony Lawson ) has recently invested around €12m in PDSB.
NSCI has approximately £7m in cash.
These added up make roughly all the market cap of NSCI.
However , in addition , NSCI has in its portfolio ( amongst others ) the following:
1. EMV Capital ( investment services company with interests in the industrial high tech , energy , smart city , transportation and healthcare sectors ).
2. ProAxsis Ltd ( medical diagnostics- early stage commercial ).
3. Glycotest ( live cancer diagnostics-late stage clinical ).
CEO is Dr. Illian Iliev who was the CEO of CambridgeIP Ltd and holds a PhD from Cambridge University.
This share should already been £2+ ( at least ).
Interims out on Wednesday the 29th of September.
Sorry I forgot to mention that I hold!!
Netscientific (LON:NSCI) does look interesting but what I would say is that investments held are never marked to market by investors, even if they are listed. There is generally quite a high liquidity discount applied so you should factor that in.
The question for me would be what EMV, ProAxsis and Glycotest are valued at and where/when a crystallisation event for any of these might occur. Plus of course and share price movement in PDSB.
Thanks for flagging - I will add to the watchlist and be interested to get more colour in the interims hopefully.
We've just published the PIWORLD interview with Christopher Mills: Spotting value and doing something about. A superb insight into how he invests, his razor sharp mind, and why he's such a successful investor. Mentions of Circassia (LON:CIR), Polar Capital Holdings (LON:POLR) Assetco (LON:ASTO) £FEN. Video & podcast.
Join us today, 24.9.21 at 2pm, for the interim results webinar with Personal Group (LON:PGH). They had a fairly rough time with CV19 but offer an employee benefits platform to improve employee engagement & wellbeing are they now in the sweet spot? Deborah Frost, CEO & Sarah Mace, CFO will present interim results followed by Q&A. Register here.
Finally, we have the next Stockopedia/PIWORLD StockSlam on Wednesday 27th October, 6pm. Another fun remote event where you'll hear 10 private investors each share their best investment idea in a quick 3-minute pitch. With Q&A to follow, you'll pick up valuable stock ideas. Register here. And, how do you fancy slamming a stock? (It's fun and rewarding).
From personal experience, it is rewarding. To volunteer to 'Slam', please contact me here.
Positive update from £TLY. Operating in an area that is going to need more help (NHS). Growth forecast is good but with thin margins. Directors buying significantly at 41p is very positive but share price falling as money flows out of the market (as for mdd as my small caps). Buy or wait?
that should say “as for many small caps”
what are your thoughts on upcoming ipo Oxford nanopor
Hi Everton24,
I've had a quick look at Oxford Nanopore Technologies, and (as a I suspected from the name) it's not something we'll be covering here. Reasons? Too big, and it's a growth company, loss-making, where the value of the share is going to be all about trying to assess the future value of whatever it does. That's outside our remit here, and definitely outside my skill set! Sorry about that.
If it interest you, then by all means set up a new discussion thread on Stockopedia if there isn't one already.
Regards, Paul.
There is an article in the October edition of Which? magazine on 'Best place to buy your next sofa'. Scs (LON:SCS) (I hold), much favoured in the SCVR, was in bottom place out of 9 with a rating of 64%. Top with 83% was John Lewis, closely followed by IKEA (79%). SCS 'was the only store to get just three stars for value.
The survey was conducted amongst 2932 Which members. The readership (subscribers to the magazine) is 573000.
DFS, out of interest, was in 7th place with 68%
I wonder what the correlation of John Lewis shoppers and Which members is. Much higher than with the ScS demographic I suspect. Could be wrong
I doubt that Carrie Symonds subscribes to Which.
Re: SCS (LON:SCS) I understand the demographic argument but I wonder how long a company that, even its supporters agree, sells sofas etc. which quality wise are inferior to those sold by rivals, can prosper.