Small Cap Value Report (Fri 26 June 2020) - TND, W7L, CWD, CNKS, BWNG

Good morning! Especially to the Liverpool fans out there.
The RNS is a little quiet for small-caps today, which is good, because I want to catch up on your suggestions in yesterday's comments section.
In today's news, I note that the FD of Sosandar (LON:SOS) has decided to step down and is swiftly replaced.
More to follow!
Graham
This report covers:
- Tandem (LON:TND)
- Warpaint London (W7L)
- Countrywide (LON:CWD)
- Cenkos Securities (LON:CNKS)
- N Brown (LON:BWNG)
Finished at 13:40.
Tandem (LON:TND) post-script
(Please note I have a long position in TND)
I realise that this stock won't appeal to most of you, but I just want to quickly mention the outcome of yesterday's AGM. What happened yesterday was very unusual.
The Non-Executive Chairman, Mervyn Keene, saw only 57% of votes go in his favour, with 43% against.
And the new Director, MA Taylor, was elected with just 59% of votes in favour.
You won't need me to tell you that this is an extraordinary level of dissent to see from the shareholders of a publicly listed company.
And it looks like these two Directors were only saved by last-ditch efforts to persuade the company's biggest shareholder to back them.
What exactly did they promise him? Impossible to know for sure. But the "Investor Day" and the production of results presentations might be important factors.
Warpaint London (W7L)
- Share price: 66.3p (+1%)
- No. of shares: 76.7 million
- Market cap: £51 million
A brief statement from this cosmetics group. The main point is that H1 sales have been "higher than anticipated, albeit significantly below the first half of 2019".
Does anyone else get the impression that companies might have been too pessimistic since lockdown? Many of them seem surprised by how much trade they've done over the past month.
Forecasting has been more or less impossible, though, and I don't blame them for being conservative with their forecasts.
As far as the economy goes, forecasts are about as useless as they've ever been.
The only strong conviction I have, when it comes to the economy, is that there will be a rebound, and that we will be "back to normal".
But I have no real idea how long it will take. It could be U-shaped, V-shaped, in the shape of a Nike swoosh, or in the shape of some other letter or symbol.
When it comes to investments, I simply try to avoid companies which need a quick recovery. I want time to be on my side - and I want the companies I own to be relaxed about the pace of economic growth.
As for Warpaint, its shares have looked inexpensive since last year (e.g. see the comments by Paul in August).
When I looked into its core brand, W7, I found that it was known primarily for being very cheap, relative to other cosmetics brands.
Its margins aren't too bad (gross margin 33%-35%) and it has generated some useful profits over the years, so maybe the cheap pricing is sustainable? But I have no idea if this is enough to create any sort of competitive moat.
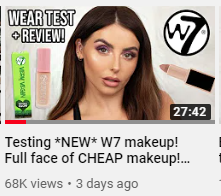
Here's a video from a big YouTube account reviewing W7 products. It was released 3 days ago and has nearly 70k views already. Note how CHEAP is emphasised in the title:
Countrywide (LON:CWD)
- Share price: 100.86p (-0.1%)
- No. of shares: 33 million
- Market cap: £33 million
More evidence of the property market coming back and estate agents getting back to work. I don't invest in estate agents, but I do hold Rightmove (LON:RMV).
Performance
Countrywide reports income of £142.5 million for the first five months of the year (2019: £200 million).
All branches were closed from March 23rd, with branches in England re-opening from May 18th.
Adjusted EBITDA margin was flat at 5% and this is after taking a hit from the tenant fee ban. So without that ban, margins would have improved.
Trends in Sales and Lettings since the easing of lockdown
- Most existing instructions now have virtual viewings on Rightmove and Zoopla. All new instructions have this.
- Most branches (70%) have been risk-assessed and are certified safe. I guess the other 30% will be, soon.
- New instructions are now running at c. 90% of normal levels (depends on what you define "normal" to be).
- Exchanges are at 71% of last year's levels.
The other divisions are less interesting to me, so I'll skip them.
Balance sheet
As at the end of May our net bank debt was £55 million and our liquidity headroom was £64 million, benefitting from the deferral of VAT, PAYE and NI.
When the VAT/PAYE/NI bills are paid, liquidity will go down and net bank debt will go up.
I wonder to what extent the tax deferrals are responsible for the reduction in net debt since December?
Outlook
The company expects a similar bounce in Scotland and Wales. However, it does not provide formal guidance for the rest of the year.
My view
I don't see any attractions here, I'm afraid.
If you time your purchase right, you could do well, but this is emphatically not the type of business that I think is capable of compounding wealth for its shareholders.
LSL Property Services (LON:LSL) recently walked away from buying Countrywide, whose balance sheet still might require some surgery to get it back onto a stable footing.
Suggested by timarr yesterday:
Cenkos Securities (LON:CNKS)
- Share price: 52.4p (+2%)
- No. of shares: 56.7 million
- Market cap: £30 million
This well-known City broker is now trading at a small premium to book value. You could buy it at discount last year.
It has a great track record of paying out large dividends to shareholders in the good times. But we are currently in the bad times, with a lack of major deals, and the final dividend for 2019 was only 1p.
Things might be turning up again:
- revenue from Jan-May is up, compared to last year.
- fixed cost base is now "significantly lower" (CNKS also has a great track record of aligning its cost base with the revenue performance)
It's normal for the company to reduce its variable costs - staff bonuses - when deals are lower.
Reducing its fixed costs is perhaps a little more worrying. Does that mean it expects revenue to stay lower for longer?
The immediate outlook does at least sound good:
...we are currently working on several transactions for our clients, and with our potential pipeline, together with a lower cost base in place we are well placed to meet the challenges ahead and are cautiously optimistic for the rest of the year.
My view
There were soothing and encouraging words in the statement but it must be said that nothing was quantified.
Checking the company website, I see that the transactions this year are of a pretty decent aggregate size, so far. It does look like 2020 can beat 2019. We are still a long way from the mega success of several years ago.
If you are able to accept its lumpy, cyclical and unpredictable revenues, I think there are plenty of other reasons to like this company.
N Brown (LON:BWNG)
- Share price: 39.05p (-1.6%)
- No. of shares: 285 million
- Market cap: £111 million
This retailer is nearly 100% online now - 85% of product sales were online in the most recent financial year.
That will be of little consolation to shareholders, who have seen the value of their investment plummet.
Last year, I was surprised by how cheap the shares had already become, and thought it could have potential. But things went on to get a whole lot worse, not helped by Covid-19. So my optimism was misplaced.
FY Feb 2020 results weren't so bad: adjusted PBT of £59.5 million (down 29%) and actual PBT of £35.7 million. Revenues declined 6%.
Net debt at the end of February was £77.5 million (excluding the customer loan book). This was flat year-on-year.
Q1 FY 2021 (March - May)
Revenue down 22%, mostly due to lower product sales (down 29%).
Revenue from loans to customers, by contrast, was only down 8%. Cash collections are said to be "in line with prior year".
Trading improved towards the end of the quarter.
Operating costs fell 42.6% - a big achievement by management. Costs were cut in many different areas.
Liquidity headroom is huge at £148 million. Covenants for the £125 million RCF have been relaxed.
FY 2020 Guidance
There are a lot of moving parts:
Product gross margin pressure is expected to continue due to mix and the highly promotional retail market. Financial Services gross margin will decline as a result of previously guided regulatory pressures and an increase in bad debt provisioning due to the impact of Covid-19.
The Group is confident of offsetting at least 75% of the Group gross margin decline through operational cost savings with bad debt provision movements being the primary driver negatively affecting EBITDA.
My view
This doesn't tick my checklist in terms of quality but I'm still curious and open-minded as to whether it can pull through. It appears to be in a good position with its lenders, for now.
One thing I would highlight is the "highly promotional retail market" - there is so much excess inventory being dumped on the market, from retailers who couldn't sell their summer collections, that it is having an effect on the CPI.
And yet one or two companies (I thinking of £BOO) report strong and increasing margins. Is that brilliance, or is it too good to be true? I honestly don't know.
Anyway, good luck to everyone holding BWNG shares.
I have to call it a day there, but thanks very much for dropping by - Paul will be with you again next week.
Cheers
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

59 comments
Graham
Some possibly interesting points re Re N Brown for you or other readers:
Net Assets per share are 111p v market price of 37p . Lord Alliance and his brother control 44% of the company. Both are very shrewd and have decades of experience in the textile industry but neither are in the first flush of youth and are non-execs.
Management reactions to covid 19 are impressive.
While it looks superficially very attractive what bothers me is that their mail order market is to the lower market echelons and bad debts are likely to be massively higher than usual given furloughing and the likely downsizing of many employers. They seem to sell on a credit basis as opposed to a fashion basis (of course fashion has a role but it is not like Boohoo and I suspect their target market is older than Boohoo .)
I got in on considering the first points and then got out after considering the later points - fortunately at a profit. Was this right ??
They are good points and I considered that too but I fell on the view that credit lines for clothes are extremely unlikely to be defaulted on - not like a mortgage or a car - and I expect it more to impact margins due to the low rate environment and regs but I can live with that at the current price and the price I bought in.
I can see why others might take it the other way though.
Howard Marks take on the rally:
I liked the comment, the only casino that was open was the stock mkt.
https://www.oaktreecapital.com...
#W7L Warpaint
Thx , as always, Graham. If any investor wants to hear the proposition 'from the horses mouth' then in 20 mins (2pm UK time, Friday) the Management of Warpaint are doing a webinar with Q&A - just register here :
https://tinyurl.com/ybgt673o
If you miss it, Equity Development will circulate a recording later
Morning all - hope someone can help me out here regarding Boohoo (LON:BOO) and the new incentive plan announced today.
https://www.londonstockexchang...
Firstly they say that:
The Plan will be share price focussed (my bold) to align interests of management with existing and potential shareholders and will be a 3-year scheme measured on 17 June 2023. The single share price growth measure is well aligned to the Group's strategy of delivering substantial and sustained returns to shareholders.
So, as an existing shareholder, that sounds OK to me. But then they say:
The Plan will pay out in full and to its maximum level of £150 million (across all participants) if the market capitalisation rises by 66 per cent (my bold). to £7.55 billion over the 3 year-performance scheme period, which equates to a compound average growth rate ("CAGR") of at least 18 per cent.
So, excuse me for potentially being stupid, but that's not necessarily the same thing, is it? If they decide to issue more shares at a discount (they have history here), whether for asset purchases or other reasons then that would boost the market capitalisation but not necessarily the share price. So, potentially, management could get £150M for making the company worth 66% more but my shares might not be worth 66% more??
Or am I just being over cynical?
Why say the Plan is share price focussed and then say so much about market cap? It's the share price that I'm interested in.
Boohoo (LON:BOO)
So, excuse me for potentially being stupid, but that's not necessarily the same thing, is it? If they decide to issue more shares at a discount (they have history here), whether for asset purchases or other reasons then that would boost the market capitalisation but not necessarily the share price.
I would be surprised (but not shocked) if that is the case - i think most companies would make an adjustment for additional shares issued.
If you read on a few more lines they say
"Provisions will be made to the Plan to make the adjustments for increases in market capitalisation arising from corporate events such as issuing shares for acquisitions so that the benefits derived from the Plan only arise from organic growth."
Boohoo (LON:BOO)
That's a very strange way to word an LTIP RNS. Firstly the targets are clearly based on market cap targets, but then they say there will be provisions made for increases in market cap from issuing shares, so that the benefits derived are only from organic growth.
So if they really intend to only pay out based on organic share price growth, would it not be clear & simple to set a target based on share price instead ? I really have doubts about this.
Secondly, I think the targets are not exactly stretching. Stockopedia shows a historic CAGR of 54% in sales & looking at the trailing PE of 77.8, it seems the market anticipates further strong growth.
Thirdly, the co-founders and the son of one of the co-founders clearly require a very large incentive plan to motivate them, but the CEO, who I though was supposed to be the most important person in any business isn't named as a significant beneficiary. His existing options are worth just over £1m (@ current prices), whilst this package for the founding families is ~£150m.
They already put a similar plan in place for the CEO when they recruited him from Primark.
He gets a maximum of £50m if the market value hits £6bn by March 2024.
This is ringing alarm bells with me! This is setting a target share price and could mean desperate management massaging figures to push the price up. Surely it would be better to set targets for profitability, earnings and cash flow etc?
Interesting - no mention of total shareholder returns. So no dividends will be paid, all spare cash will goto acquisitions to bump up market cap. Still, if acquisitions are sensible it will add value. I don't have anything against mgt sharing the rewards, just need to understand it can create pump incentives.
Good morning Graham, will you be having a look at one of your favourites which has had preliminary results today Thalassa Holdings (LON:THAL) ? Mkt cap of £9m and cash of $16m.
Cheers, Graham
any thoughts on the Countrywide (LON:CWD) trading update if time. seems the housing market is coming back surprisingly strongly although might just be a backlog after a couple of months with little activity
U And I (LON:UAI) unwanted and unloved, the share price would suggest that it is going the same way as Intu Properties (LON:INTU), notwithstanding that here have been a number of positive announcements recently. This morning's announcement confirming the granting of planning permission for the Kensington Church Street development being the most recent. I doubt the stock has been cheaper in over a decade. Admittedly business is difficult and NAV will be heavily impacted but from my view this is more than reflected in the share price.
Also good to see senior management sharing the pain with a 25% to 50% reduction in salaries and bonus payments and entitlements rightly waived or cancelled.
We will have a better indication of the damage inflicted by economic conditions with the release of the prelims on 8 July. The best that can be expected in the short term is perhaps that trading conditions have stabilised, but longer term there is significant upside, albeit requiring a large dollop of patience. Needles to say I hold.
Good to see your concern, jonno. I too am a confused U And I (LON:UAI) holder. I recognise the 'calling in' on the 8 Albert Embankment permission to be a setback, but some of their schemes are progressing, I believe they have cut costs sufficiently, and Richard Upton must be sick as dog to be 50% down on the £400k+ he spent on steadily buying shares from Nov to Jan. (as am I, albeit, thankfully, on a lesser amount). I will hold for the prelims but will look at them carefully and may exchange views then. I do think mixed use will survive, small retail spaces, London pads and serviced small offices (which is why I have not sold Rdi Reit (LON:RDI) yet, which I feel should emerge at 110p next year, fingers crossed!).
Probably the most significant announcement today is Intu Properties (LON:INTU) - who are about to go into administration. Quite how that will pan out is beyond my capacity to analyse, but it'll be interesting to see what the ramification are. It's one thing for retailers who haven't got the means to pay to withhold rents but it's entirely another when they do so to protect shareholder returns.
But, as ever, unintended consequences abound when governments intervene.
timarr
The administrators will be duty bound to pursue the unpaid rent by all legal means won't they?Up to and including seeking winding-up orders?
But yes if the government gets involved I have no idea either.
Winding-up orders are disallowed under Part 1 of schedule 10 of the Corporate Insolvency & Governance Bill, the next stage of which is a debate on the HL amendments on 25 June. The effect of schedule 10 will be back-dated to 27 April 2020 and will expire on 30 June 2020 but I anticipate that this latter date will be extended. Do not count on administrators having the ability to act as they might have done before the virus disaster. By the way, under clause 10 wrongful trading will no longer be an offence, and I wonder if this will alter directors' behaviour.
https://publications.parliamen...
I think we can pretty much guarantee that this will alter behaviour. If the incentives change then behaviour changes. There will be some interesting test cases and opportunities for the likes of Manolete Partners (LON:MANO) resulting from this.
I think we can pretty much guarantee that this will alter behaviour.
Clearly. However, I don't think the new Act allows withholding of payments just because the company feels like it. Genuinely cash strapped companies are protected but those that aren't paying because they don't want to aren't. Plenty of room for legal action there.
Anyway it'll be an interesting three way standoff between the administrators, the bondholders and the tenants. If the bondholders refuse to play ball and the administrators are forced to shut the doors what happens?
Very happy to watch this from afar.
timarr
One angry Intu shareholder took direct action a few days ago:
A man smashed up a computer in the Trafford Centre as he was angry that the company's share price had dropped.
The customer, who had invested shares in the company, was frustrated that he had lost money, police said.
https://www.manchestereveningnews.co.uk/news/greater-manchester-news/angry-man-goes-rampage-trafford-18466150
I like his style.. Right, I'm off to my nearest Aston Martin dealership!
Brilliant 4.5 bil in debt and lost 1.5 bil last year in a sector on its knee's what could go wrong he should be beating himself up.
Intu....yes the Government tells businesses they cannot be evicted and the usual rules are suspended. So what do they do? "UK retailers stumped up just 14% of the rent bill due this week, as the high street crisis triggered by the lockdown reverberated through the property industry". So the result? Commercial landlords are in trouble all over the place. Intu is a "reit" after all....a supposed safe property investment vehicle where a lot of pension money has been invested. Other reits (do I dare mention NRR?) are falling like a stone as the implications are so unknown.
Meanwhile, the administrators have said all of the 17 Intu shopping centres will close and stay closed unless the bond holders stump up an initial £12 million upfront. Will they pay when the rents are not being paid? Tens of thousands of jobs are at risk. It seems the Government is going to end up with exactly what it say it did not want.
Graham, Any thoughts on Immotion (LON:IMMO) would be welcome. Covid more or less stopped their business in the tracks (they provide VR headsets to theme parks, etc) but do they have the money to survive the hopefully temporary downturn?
Also second the request for comments on Elecosoft (LON:ELCO) .
this industry is still frozen - the second lockdown in china putting all development in china on hold, they are the canary in this industry's mine - will be very very slow for 18 months . They have to pivot or have a lot of cash
888 Holdings (LON:888)
slightly odd significantly ahead of prior expectations update from 888 today, the tone of the news sort of suggests this good streak may/will not last - headwinds ahead doh. Hopefully they are just being suitably cautious about the future and/or they have a regulator they do not want to upset - its kinda like the news was drafted by lawyers in the knowledge the ceo would be put infront of a treasury select committee next week.
Marlowe (LON:MRL) please Graham. A strong trading update plus another acquisition and a bookbuild at 480p.
I hold happily.
Seconded. Marlowe (LON:MRL), like many buy and build firms, gets short thrift here but is carving out an interesting position in the health and safety space which will only get better in a post COVID world. Today it has thousands of workers conducting mandated checks on water, air and fire safety; its has consultants advising property owners on risk management and has legal and HR consultants helping property owners. Today's results show great progress with organic revenues now at 7%. Margins still look sub10% but these will improve as the more recent, higher margin acquisitions, come on stream. I hold.
cheers
Francis
Thanks for bringing Marlowe to my attention. In terms of the sectors in which it operates it seems at first sight to have similarities with Halma with has been a long term hold for me, and done very well. I guess Halma is more the equipment and Marlowe provide services. But I think it is a good area to be in. I need to get in to the detail now!
I'd appreciate comment on Warpaint. And merely for entertainment, DP Poland "broadly inline" (ie disappointing yet again) - still can't figure out why it has done so badly versus the other Domino's Pizza's in US and UK.
My morning smallcap tweet: AML taps shareholders again
Redcentric (LON:RCN) Ten Entertainment (LON:TEG) John Menzies (LON:MNZS) Instem (LON:INS) Intu Properties (LON:INTU) Supermarket Income REIT (LON:SUPR) Iofina (LON:IOF) Aston Martin Lagonda Global Holdings (LON:AML) Powerhouse Energy (LON:PHE) Countrywide (LON:CWD) Live (LON:LVCG) U and I (LON:UAI) Sportech (LON:SPO) £W7L DP Poland (LON:DPP) Inspiration Healthcare (LON:IHC) Windar Photonics (LON:WPHO)
Redcentric (RCN) FCA orders it to pay £11.4m compensation to buyers from Nov 15 to Nov 16 when co misstated accounts! Great but why has it taken 4 years? £5.775m placing at 110p, a 7% premium, to help pay for it. Guides Q1 recurring revenue orders slightly up and significantly ahead of the Board's expectations. Also customer installations significantly up and ahead of expectations. Passes div.
Ten Entertainment (TEG) CEO leaves at YE for to better job. He is thanked.
John Menzies (MNZS) CEO leavesin Aug. He is thanked.
Instem (INS) £15.75m placing at 435p, a 4.4% discount, for acquisitions.
Intu (INTU) creditors not playing ball. Co likely to go into administration.
Supermarket Income REIT (SUPR) gets 100% of June rents due. Auditors will therefore not require a material uncertainty clause in forthcoming portfolio valuation.
Iofina (IOF) plant 8 restarts production. Co's senior secured lender agreesin principle to extend repayment deadline by two months to allow new lender talks to conclude.
Aston Martin Lagonda (AML) desperate measures ('strategy to realise its full potential and operate as a true luxury company') increase under new CEO. Yet another placing of up to 20% of cap via ABB and PrimaryBid, more loans.
PowerHouse Energy (PHE) buys Waste2Tricity in all paper deal.
Countrywide (CWD) rev down 29% in 5 months to May. Adj EBITDA £7.4m (£10m) 'after absorbing £8.1 million gross impact of the tenant fee ban'. May seek covid loan.
Live Company Group (LVCG) £0.4m placing at 10p, a 20% discount, to keep the lights on.
U and I (UAI) gets planning for Kensington Church Street development.
Sportech (SPO) guides net cash £8.9m end June, better than £7.5m prev guided.
Warpaint (W7L) AGM stmt: H1 rev higher level than anticipated, albeit significantly down. Margin improves, positive EBITDA.
DP Poland (DPP) AGM stmt: first 5 months broadly in line with management's expectations. LFL up 3% in April and May.
Inspiration Healthcare (IHC) AGM stmt upbeat.
Windar Photonics (WPHO) guides FY19 rev €1.2m (€3.5m). EBITDA -€1.9m. Orders won in FY20 €1.7m."The current order backlog and sales pipeline for the rest of 2020 and 2021 are stronger that as at Dec." Finals delayed 3 months. Last trading stmt was Nov. Disgraceful.
Inspiration Healthcare (LON:IHC) - upbeat statement on continued growth and acquisition. TO of ILS doubles IHC revenue so is pretty significant. ILS business is neo-natal ventilators. IHC recently licensed a patented neo-natal respiratory product from the US, and has also recently received a grant for respiratory work of its own. It may have had ILS over a barrel. Not much financial info on the deal, but is £18m for £16m sales cash and debt free (and '£1.5m EBITDA') an apparently good price?
Graham, please try to avoid football commentary. Apart from improving my financial knowledge, I visit this page every day for some football escapism......it helps me to forget that I am a season ticket holder at Bolton Wanderers ;-) I hold Sosandar too, I hope its path over the next few years will be a better one than my football teams current direction of travel.
Morning Graham do you have any thoughts on ELCO. It fell yesterday afternoon approx 15% while there seems to be no news.
many thanks
Belluci, it was a short attack by ciphersense-research
Thanks for the "heads up", 4351anf
ciphersense does not have a position:
https://twitter.com/Ciphersens...
apols - maybe it would have been better to have said short report
Ciphersense does not have a functioning website, does not have any employee details / profiles and does not have a Companies house registration either...
ciphersense-research: the use of the term 'research' in the name of outfit seems somewhat of a misnomer.
posted by ansc on advfn this morning
I hope genuine shareholders were not panicked into selling yesterday following the release of that obnoxious report. I spoke at length to the company yesterday and, as I suspected, it looks as though the mysterious publishing company is associated with the guy who posted a while ago as MBcontrarian; not surprisingly, throwing accusations around then about ELCO too. The company have a thick dossier on this individual apparently as he's been actively attempting to dig up dirt about the company for some considerable time, stooping pretty low in his numerous attempts.
I didn't sell a single share from my not inconsiderable pot yesterday and intend to ride out the Covid pandemic with them come what may.
FD jumping ship at £SOS. Never a good sign!
FD jumping ship at Sosandar (LON:SOS). Never a good sign!
I would say if a company is replacing the FD immediately with a suitably qualified (upgraded?) replacement and there are no current reasons to query any of the current financials i would say the adverse news is not so much a bad sign as it might have been if they went under a cloud with no immediate replacement. In some respects as i have not been particularly impressed with the bitty nature of the numbers/outlook statements sos have released there is potential that the new bod could be a nice upgrade - certainly seems the cv is a massive upgrade compared to that of the person leaving - someone with larger company experience and more experience in this field.
I wander if this was more a mutually convenient switch rather than the FD simply jumping ship - at a minimum the replacement . I can certainly imagine the cut and thrust that comes with fashion finances probably isn't that attractive for all FD's out there.
I thought that as well about the Sosandar (LON:SOS) change, until I checked my facts. What has happened to Mark Collingbourne, who is listed as Finance Director on the website but does not get a mention in this announcement at all?
He is also still listed as Finance Director on his LinkedIn account.
https://www.sosandar-ir.com/content/investors/board
https://www.linkedin.com/in/ma...
https://www.investegate.co.uk/...
The new FD is replacing a Head of Finance and not being appointed to the board yet.
So I would expect him to be appointed to the board in a few months and for Mark Collingbourne to move on then.
So Sosandar (LON:SOS) is functioning with two Finance Directors in the meantime? And a decision has been made (by him or by the Board) that Collingbourne will be leaving and this has not been announced?
At best, today's announcement is extremely ill-drafted, at worst, it is "economic with the truth".
The new man isn't joining until Sept 7th.
The RNS says "The Board expects that Stephen will be appointed to the Board once he has settled into his new role, subject to the satisfactory completion of the necessary regulatory requirements."
The assumption that Collingbourne will then leave is mine as two FD's would seem excessive.
re Sosandar (LON:SOS), it must surely take some time to recruit a new FD. If the board knew some time ago of Collingbourne's intention to resign should this not have been announced then?
Compare and contrast with Card Factory (LON:CARD), where today it is announced the CEO is being put on garden leave for six months, with the search for a sucessor starting immediately. Also interesting timing with the strategy day next month. I think Paul had mentioned here previously that he thought a change of CEO may be needed.
Personally I think that's excellent news for Card Factory and about time.
TBH I think they've regressed over her reign. Very poor online traction, negligible organic growth.
Something like £320m has been paid out in dividends, which in retrospect seems absurd considering debt levels. By now they could have taken over one of the more established online card companies.... I can't understand how their own online offering has been so poor considering the immense amount of footfall in their stores.
Quite tempted to purchase.
Agree about Card Factory (LON:CARD) CEO. Didn't get a good feeling the performance drift from quite early on in her tenure. Card Factory (LON:CARD) also had at one point one of those Chairmen who had multiple high paying directorships. He's gone thank heavens. The whole business felt more like an institution taking its strong cash flow for granted.
Finding a replacement will not be easy, as it needs a mixture of entrepreneur and solid planner, to deal with a difficult environment
Thank you Paul, yes a great morning for Liverpool fans!
Instem (LON:INS)
Announced raising gross £15.75m (net £15m) at 435p - yesterday's closing was 455p. Insiders paying another £3m through options excise and shares.
"The net proceeds of the Placing receivable by the Company will be used to accelerate the Group's acquisition strategy with a number of potential compelling opportunities for bolt on acquisitions and more substantial targets having been identified"
I used to hold INS but sold recently when share price failed to break through previous high of 540p
I might buy back in as good timing now for companies to make accretive acquisitions, for a change.
I also sold and have bought back in. I found last year's video on PIWorld was very informative. The CEO explained the business very well and he discussed their acquisition strategy.
#INS.
I spoke with Phil Reason two weeks ago after the delayed results. I also met him and chatted with him about a year ago. He is the kind of CEO who I like running companies I own a share in.
Instem operate in an area of pharma where they are not reliant on drugs being approved, but assist in this process. All the large pharma are clients and they claim to have been involved at some stage in 50% of the drugs on the market.
Instem is highly scaleable and well run. After the results Phil talked about a strong pipeline of acquisition options and Instem have a very good record in this regard and it is their strategy.
The placing of £15million is large for a company of £75m MCap and only at a small discount and gives them substantially more fire-power.
I watched the APAX video session with shareholders yesterday, and both asked and got answered a message relating to APAX.
I thought that the mechanism was brilliant; really shareholder friendly. Not sure what the technology underlying it was. Zoom or the like.
I noted that APAX were pretty sanguine about the effect of COVID on tech investing, which is basically what they do. I'm a strong Hold(er) of the shares.
I live in the Thames Valley. Riverside activity was similar to Bournemouth. Expect an uptick in COVID shortly. I volunteer to pick up litter; there was so much that I had to give up. Some Brits......why do they never take rubbish home, then expect better people than them to pick it up and risk catching the virus (I'm 65) ?
It’s exactly the same in Richmond on most summer weekends and on any hot day. All the parks in the area are littered with rubbish,as are the river banks. Absolutely appalling behaviour
It’s exactly the same in Richmond on most summer weekends and on any hot day. All the parks in the area are littered with rubbish,as are the river banks. Absolutely appalling behaviour